
 Hydrocolloid Carrier Market | 2026-2036
Hydrocolloid Carrier Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrocolloid Carrier Market Analytics
The gap between premium medical-grade hydrocolloids and commodity food-industrial grades is broadening as clinical applications demand stricter purity thresholds and validated supply chains. DuPont leverages its polymer science heritage to anchor high-performance wound care formulations. Cargill competes through agricultural feedstock security that sustains cost advantages in guar and cellulose derivatives. CP Kelco specializes in fermentation-based gellan gum production that dominates niche pharmaceutical coating segments.
Hydrocolloid carriers are cross-linked polysaccharide or protein matrices that absorb exudate while maintaining moist wound interfaces, typically formulated with gelatin, pectin, or sodium carboxymethylcellulose at gel strengths between 50 and 500 Bloom. These materials enable controlled moisture vapor transmission rates essential for granulation tissue formation in chronic wound management. Wound dressings and adhesive bandages occupy mature volume positions with stable hospital procurement contracts, while drug delivery systems capture expanding margin pools as transdermal patch formulations multiply. Hydrogel and film forms lead innovation pipelines due to their tunable release kinetics and conformability to irregular anatomical surfaces.
FDA biocompatibility testing under ISO 10993 and EMA medical device regulations govern material qualification timelines for hydrocolloid carriers entering clinical applications. EPA industrial chemical reporting requirements and REACH substance registration in Europe add compliance layers that favor suppliers with established regulatory dossiers. Stakeholders must monitor evolving pharmacopeial monograph revisions and polymer sourcing transparency mandates that will reshape supplier qualification criteria and contract manufacturing organization selection.
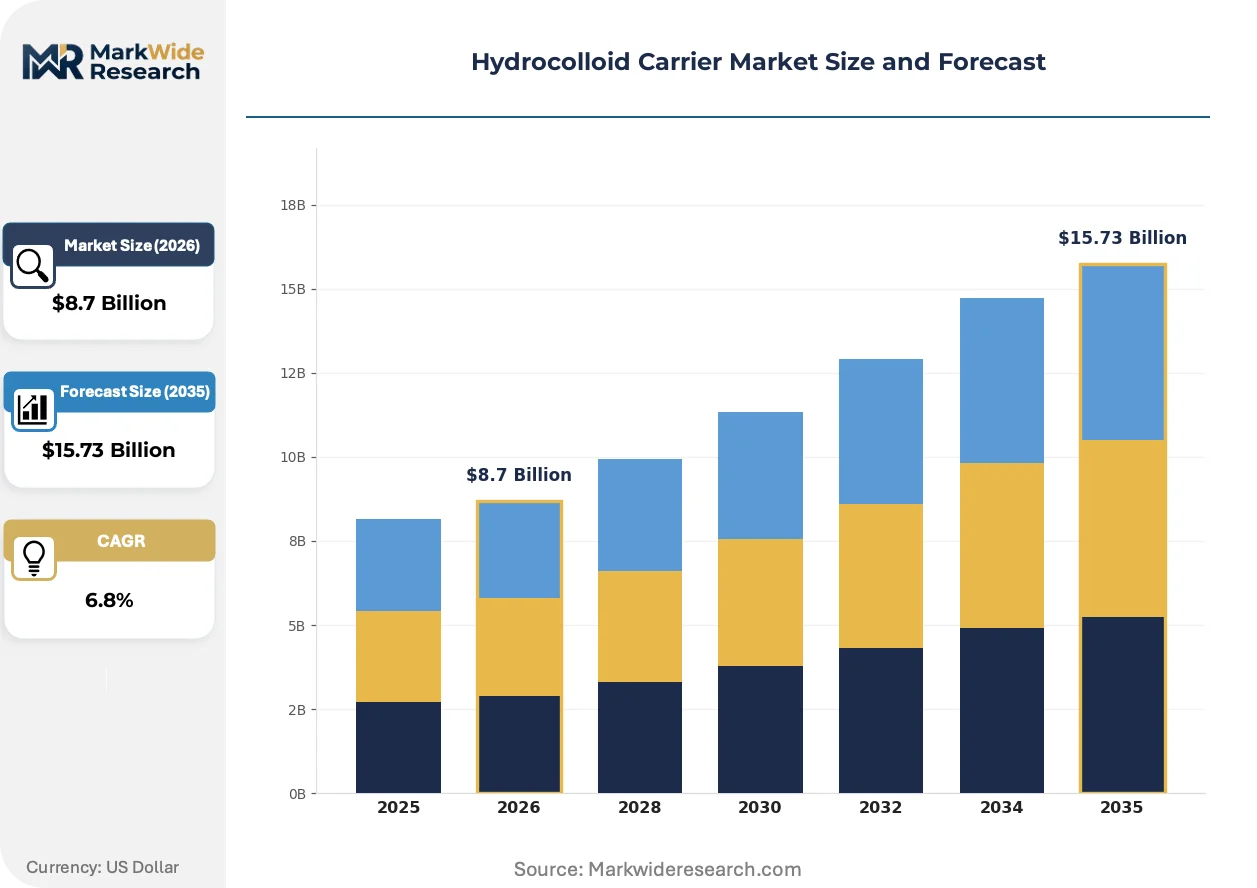
Market Dynamics
FDA and EMA biocompatibility mandates are compressing supplier qualification timelines while pharmaceutical manufacturers accelerate transdermal drug delivery adoption. This regulatory tightening concentrates procurement power among carriers with pre-validated ISO 10993 dossiers.
Growth Catalysts
- Transdermal patch expansion:Chronic disease management protocols favor controlled-release platforms over oral dosing. Pharmaceutical formulators prioritize hydrocolloid matrices with tunable permeation kinetics.
- REACH substance registration:European chemical transparency rules favor established suppliers with complete polymer traceability documentation. Medical-grade certification becomes a competitive differentiator.
- Chronic wound prevalence:Aging demographics in Germany and Japan drive hospital procurement of advanced moisture-retentive dressings. Reimbursement codes increasingly cover bioactive carrier formulations.
Market Restraints
- Guar gum price volatility:Indian monsoon variability disrupts agricultural feedstock supply for cellulose derivative production. Cargill's agricultural security buffers margin compression for integrated players.
- Fermentation capacity concentration:Gellan gum production clusters in single-site fermentation facilities. CP Kelco's Danish manufacturing base creates geographic supply risk for pharmaceutical coating segments.
- ISO 10993 testing duration:Cytotoxicity and sensitization studies extend material qualification to 18-24 months. Early-stage carriers face cash flow strain during regulatory hold periods.
Strategic Opportunities
- Brazilian ANVISA pathway:Latin America's largest pharmaceutical market lacks domestic hydrocolloid carrier production. First-movers establishing local technical dossiers capture hospital tender preferences.
- Hydrogel-film convergence:Combination products merging absorbent cores with transparent silicone interfaces address post-surgical monitoring needs. Device manufacturers seek co-development partnerships with polymer specialists.
- EU MDR Article 10 compliance:Stricter clinical evidence requirements for wound care devices create demand for carriers with pre-established biocompatibility data. Suppliers with technical files gain procurement preference.
Industry Challenges
- Polymer characterization expertise:Cross-link density analysis and rheological profiling require specialized analytical chemists. Contract manufacturers struggle to staff qualified release testing personnel.
- Cleanroom retrofit costs:Medical-grade production demands ISO 7 or better environments. Mid-scale processors face capital allocation decisions between facility upgrades and raw material inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrocolloid Carrier Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wound Dressings, Adhesive Bandages, Drug Delivery Systems, Medical Sealants End User: Hospitals, Clinics, Home Care, Ambulatory Surgical Centers Form: Hydrogels, Films, Sheets, Coatings Application: Chronic Wounds, Burn Treatment, Surgical Procedures, Skin Care |
| Companies Covered | DuPont, Cargill, CP Kelco, Ashland, Lubrizol Corporation, Alland & Robert Company, Rousselot S.A.S., Koninklijke DSM N.V., Ingredion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrocolloid Carrier Market Evolving Landscape
Formulation science is converging with digital manufacturing controls to enable lot-to-lot consistency that batch records alone cannot guarantee. This precision shift redefines supplier technical service expectations.
Electrospun nanofiber hydrocolloid composites are consolidating manufacturing complexity by integrating drug loading directly into fiber formation rather than post-processing impregnation. Transdermal patch producers adopt these structures for their surface-area-to-volume advantages. The technology is consolidating formulation steps that previously required separate coating and drying lines.
EMA's Medical Device Regulation (MDR) transition deadlines are forcing wound care manufacturers to revalidate legacy carrier formulations under stricter clinical evidence standards. Technical documentation gaps trigger notified body non-conformities for suppliers without established biological safety assessments. German hospital purchasing groups now require MDR-compliant certificates of conformity for all new hydrocolloid dressing introductions.
Hospital procurement consortia in the Benelux region are consolidating vendor lists to carriers offering validated sterilization assurance and supply continuity guarantees. Group purchasing organizations negotiate multi-year frameworks that exclude smaller processors lacking redundant manufacturing sites. This concentration shifts margin pressure upstream to raw material suppliers while rewarding integrated polymer producers with captive quality control systems.
Hydrocolloid Carrier Market Segmentation
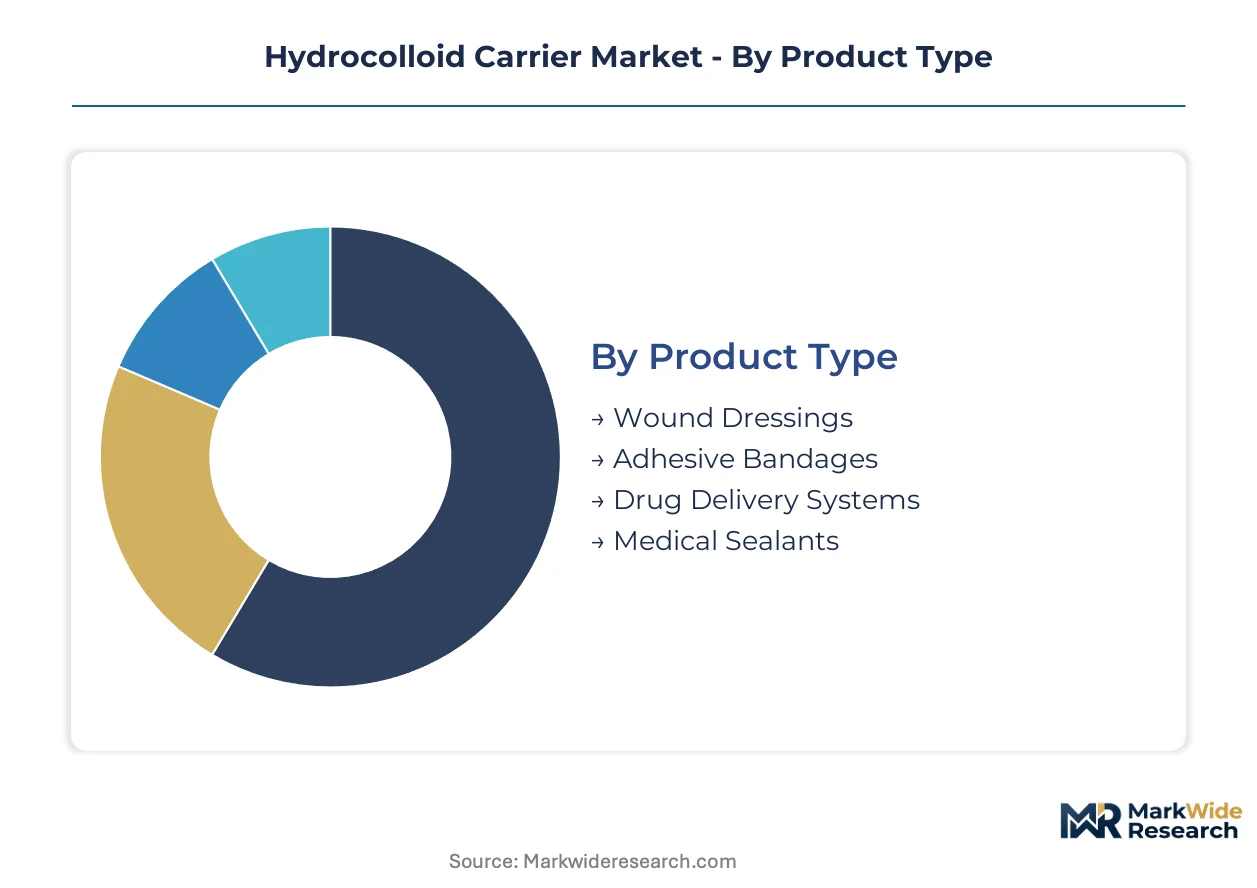
Hydrocolloid carrier segmentation reveals how formulation complexity, clinical setting requirements, and physical form factors create distinct commercial battlegrounds. Each dimension carries unique margin structures and regulatory qualification burdens that reshape supplier positioning.
Product Type:
Customization intensity spans from commoditized wound care consumables to precision-engineered drug delivery matrices requiring validated release kinetics.
- Wound Dressings:Absorbent polysaccharide matrices—typically gelatin-pectin-CMC blends at 100-300 Bloom gel strength—maintain moist healing environments for diabetic foot ulcers and pressure injuries. Hospital procurement consortia in Germany's Rhineland cluster negotiate multi-year supply agreements for these high-volume consumables, with reimbursement codes increasingly favoring bioactive formulations over basic moisture-retentive versions.
- Drug Delivery Systems:Tunable permeation hydrocolloids enable zero-order release kinetics for transdermal patches treating chronic pain and motion sickness. Pharmaceutical formulators in Denmark's Medicon Valley prioritize carriers with pre-validated ISO 10993 biocompatibility dossiers to compress 18-24 month qualification timelines.
- Adhesive Bandages:Standardized hydrocolloid strips for minor wound management compete on manufacturing scale and retail distribution reach.
- Medical Sealants:Surgical adhesion barriers and tissue-bonding formulations require specialized cross-linking chemistry for controlled degradation rates.
Leading the category by volume: Wound Dressings. Expanding most quickly: Drug Delivery Systems.
End User:
Clinical acuity and reimbursement sophistication create tiered demand patterns from intensive care settings to decentralized home administration.
- Hospitals:Advanced wound care centers and surgical departments drive specification authority for medical-grade hydrocolloids. German hospital purchasing groups now mandate MDR-compliant certificates of conformity for all new dressing introductions, concentrating procurement among carriers with established technical files.
- Home Care:Self-administered chronic wound management and transdermal therapy delivery are climbing the fastest as aging demographics in Japan and Germany shift treatment locus from acute facilities. Reimbursement frameworks in the Netherlands explicitly cover home-based bioactive dressing applications.
- Clinics:Outpatient wound care centers balance clinical efficacy with cost containment in government tender processes.
- Ambulatory Surgical Centers:Same-day procedure volumes concentrate demand for rapid-application sealants and post-operative dressings with minimal nursing intervention.
Dominant by procurement value: Hospitals. Steepest expansion trajectory: Home Care.
Form:
Manufacturing complexity and conformability requirements differentiate physical presentations from pourable gels to precision-coated substrates.
- Hydrogels:Three-dimensional water-swollen polymer networks—typically 70-90% aqueous content—provide cooling sensation and exudate absorption for burn treatment. Electrospun nanofiber variants integrate drug loading directly into fiber formation, consolidating manufacturing steps for transdermal patch producers seeking surface-area advantages.
- Films:Thin, transparent polyurethane-hydrocolloid laminates enable continuous wound visualization without dressing removal. Post-surgical monitoring applications in Belgian university hospitals favor these conformable structures for irregular anatomical surfaces.
- Sheets:Pre-formed hydrocolloid wafers offer standardized thickness and absorption capacity for routine wound care protocols.
- Coatings:Sub-micron hydrocolloid layers functionalize medical device surfaces with lubricious or bioactive properties.
Highest volume production: Hydrogels. Gaining share fastest: Films.
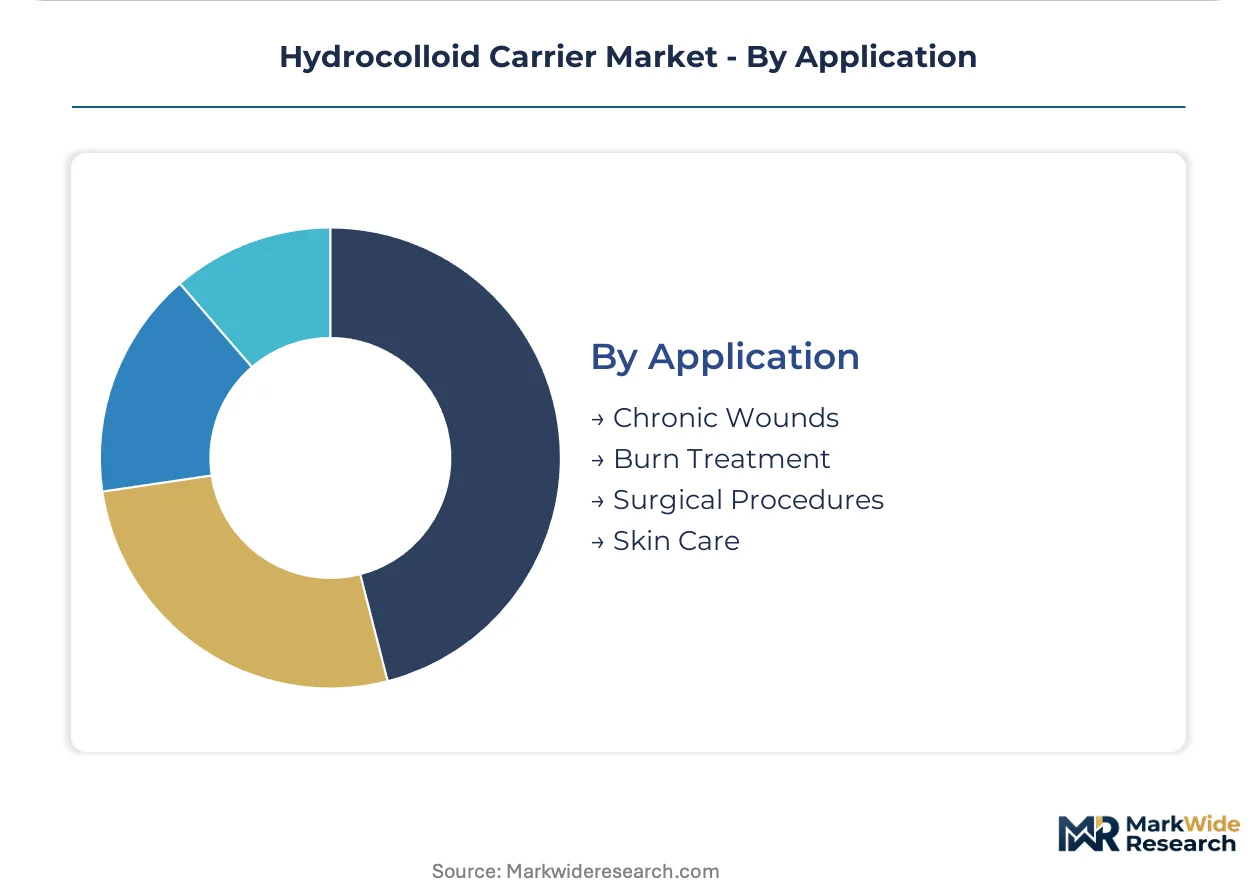
Application:
Therapeutic indication determines regulatory pathway complexity and pricing power across acute intervention versus chronic management scenarios.
- Chronic Wounds:Diabetic foot ulcers, venous leg ulcers, and pressure injuries sustain recurring demand for moisture-retentive dressings with extended wear times. Japan's aging population and Germany's diabetes prevalence concentrate hospital procurement of advanced formulations with antimicrobial silver integration.
- Surgical Procedures:Incision management and adhesion prevention require hydrocolloid carriers with precisely tuned absorption and degradation profiles. EMA MDR Article 10 compliance demands are forcing manufacturers to revalidate legacy formulations under stricter clinical evidence standards.
- Burn Treatment:Partial-thickness thermal injuries utilize hydrogel cooling and eschar management properties.
- Skin Care:Cosmetic dermatology applications leverage hydrocolloid occlusion for acne treatment and post-procedure recovery.
Largest addressable patient population: Chronic Wounds. Accelerating most rapidly: Surgical Procedures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhineland medical polymer cluster anchors hydrocolloid carrier demand through integrated pharmaceutical and wound care manufacturing corridors.
Germany
Hospital purchasing groups in North Rhine-Westphalia drive specification authority for advanced wound dressings. EMA's MDR Article 10 compliance deadlines force manufacturers to revalidate legacy formulations under stricter clinical evidence standards. The Rhineland cluster concentrates polymer compounding and coating operations serving Benelux procurement consortia.
United States
FDA biocompatibility testing under ISO 10993 governs material qualification timelines for transdermal drug delivery platforms. Pharmaceutical formulators prioritize carriers with pre-validated dossiers to compress 18-24 month regulatory cycles. Boston's Route 128 corridor hosts contract research organizations specializing in cytotoxicity and sensitization studies for hydrocolloid entrants.
Japan
Aging demographics concentrate hospital procurement of moisture-retentive dressings for diabetic foot and pressure injury management. PMDA medical device regulations align with international standards while maintaining supplementary pharmacopeial requirements. The Kansai region around Osaka anchors domestic wound care manufacturing with specialized hydrogel production facilities.
Denmark
Medicon Valley pharmaceutical clusters demand fermentation-based gellan gum for precision coating applications in transdermal patches. REACH substance registration requirements favor suppliers with complete polymer traceability documentation. CP Kelco's Danish manufacturing base serves Nordic and Northern European pharmaceutical formulators despite geographic concentration risk.
Brazil
Latin America's largest pharmaceutical market lacks domestic hydrocolloid carrier production, creating tender opportunities for dossier-ready suppliers. ANVISA regulatory pathways remain underdeveloped compared to FDA or EMA frameworks. São Paulo's hospital procurement networks increasingly specify imported medical-grade carriers for chronic wound protocols.
Hydrocolloid Carrier Market Competitive Landscape
Capital-heavy producers compete with asset-light formulators across hydrocolloid carrier supply chains. Integrated agricultural processors control feedstock security for cellulose and guar derivatives, while specialized fermentation operators dominate niche gellan gum segments. Three archetypes define competitive positioning: diversified polymer science conglomerates, agricultural commodity integrators, and focused bioprocess specialists. Consolidation pressures favor M&A activity among mid-scale processors seeking ISO 10993 dossiers, while capacity expansion concentrates in medical-grade cleanroom facilities.
Within the diversified polymer science tier, DuPont exemplifies integrated material qualification capabilities spanning pharmaceutical and wound care applications. Cargill occupies a position anchored to agricultural feedstock security that sustains cost advantages in guar and cellulose derivative supply. CP Kelco represents the focused bioprocess specialist archetype through fermentation-based production systems. These three entities collectively illustrate how competitive positioning stratifies across feedstock control, regulatory dossier depth, and manufacturing technology specialization.
| Leading Market Players |
|---|
| DuPont |
| Cargill |
| CP Kelco |
| Ashland |
| Lubrizol Corporation |
| Alland & Robert Company |
| Rousselot S.A.S. |
| Koninklijke DSM N.V. |
| Ingredion |
| Others |
Value Network & Pricing Analysis
Electrospun nanofiber manufacturing integration is compressing formulation steps from separate coating and drying lines into single-process fiber formation, simultaneously reducing unit production costs and concentrating supply among processors with capital-intensive electrospinning capabilities. This technological shift tightens procurement options for pharmaceutical formulators seeking tunable permeation kinetics while amplifying price premiums for carriers with validated nanofiber dossiers.
Pricing Analysis
Outcome-based pricing anchors medical-grade hydrocolloid contracts to granulation tissue formation rates and zero-order drug release consistency. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10993-validated carriers from basic moisture-retentive grades and commodity food-industrial derivatives. Pricing pressure stems from hospital procurement consortia consolidating vendor lists to multi-year frameworks. Home care segments exhibit highest price sensitivity due to out-of-pocket reimbursement gaps, while pharmaceutical formulators absorb premiums for pre-validated biocompatibility dossiers.
Supply Chain Analysis
Freight cost escalation from Indian guar gum cultivation regions to European compounding facilities is amplifying geographic sourcing advantages for integrated agricultural processors with Benelux distribution hubs. Raw material supply draws from Indian guar cultivation, Danish fermentation facilities for gellan gum, and North American wood pulp for cellulose derivatives. Single-source vulnerability concentrates in CP Kelco's Danish fermentation base for pharmaceutical-grade gellan gum. Distribution runs through hospital purchasing group frameworks in Germany's Rhineland cluster and pharmaceutical formulator networks in Denmark's Medicon Valley.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrospun nanofiber hydrocolloid composites are displacing legacy coating-impregnation processes, compressing manufacturing timelines while demanding fresh capital deployment from established processors and opening white-space for specialized entrants.
For Market Incumbents: Extend regulatory dossier depth beyond ISO 10993 baseline to capture EMA MDR Article 10 compliance premiums before revalidation deadlines force competitor exits. Anchor capacity expansion in Germany's Rhineland cluster to defend procurement relationships with Benelux hospital consortia. Vertical integration into agricultural feedstock security buffers guar gum price volatility that threatens margin compression for non-integrated formulators. For New Entrants and Emerging Players: Brazilian hospital procurement managers represent the most penetrable buyer archetype given ANVISA's underdeveloped domestic carrier production and São Paulo tender networks specifying imported medical-grade formulations. Target hydrogel-film combination products for post-surgical monitoring applications where Belgian university hospitals seek co-development partnerships. Accelerate technical dossier preparation to capture first-mover preferences in Latin America's largest pharmaceutical market. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified polymer science conglomerates seeking ISO 10993 dossiers to compress 18-24 month qualification timelines. Mid-scale processors with established cleanroom facilities and pre-validated biocompatibility data represent priority targets over raw material suppliers facing commodity margin pressure. Watch EMA MDR transition completion rates as inflection indicator for carrier revalidation demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Biocompatibility Dossier Expansion | Pre-validated ISO 10993 testing compresses pharmaceutical formulator qualification timelines to secure multi-year contracts. |
| EMA MDR Article 10 Compliance Investment | Technical file depth captures procurement preference from German hospital purchasing groups enforcing certificate mandates. |
| Electrospun Nanofiber Capacity Buildout | Single-process fiber formation consolidates coating and drying steps for transdermal patch surface-area advantages. |
| Backward Integration into Guar Cultivation | Agricultural feedstock security buffers Indian monsoon variability disrupting cellulose derivative supply chains. |
| Benelux Distribution Hub Establishment | Proximity to Rhineland medical polymer cluster reduces freight costs and secures group purchasing organization access. |
Research Methodology
Independent corroboration across primary interviews with wound care procurement managers, pharmaceutical formulation scientists, and biomedical regulatory affairs directors, combined with secondary validation through FDA 510(k) filings, EMA medical device database entries, and ISO 10993 testing laboratory records, underwrites the qualitative findings. Bottom-up demand modeling from hospital procurement database analysis and top-down supply verification through customs trade data triangulate volume estimates. Conversations with contract manufacturing organization executives and GPO contracts managers anchored regional demand assessments.
Rate-of-change decomposition across the analysis window segments expansion by wound dressing, drug delivery system, and adhesive bandage product categories, further disaggregated by hydrogel, film, sheet, and coating form factors. End-user splits across hospital, home care, clinic, and ambulatory surgical center settings incorporate reimbursement code evolution and chronic wound prevalence demographics. CAGRs derive from historical volume trajectories adjusted for regulatory qualification timeline compression and electrospun nanofiber adoption curves. Raw material feedstock cost indices and cleanroom capacity expansion pipelines inform supply-side constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EMA MDR enforcement consistency, Indian monsoon patterns affecting guar gum cultivation, and fermentation facility geographic concentration risk. Forecasts reflect documented assumptions regarding regulatory pathway stability and pharmaceutical outsourcing trends. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Grade Calcium Lactate Market
Food Additives and Ingredients
Africa Food Acidulants Market
Food Additives and Ingredients
Australia Food Emulsifiers Market
Food Additives and Ingredients
Caramel Food Colors Market
Food Additives and Ingredients
Germany Anticaking Market
Food Additives and Ingredients
North America Food Enzymes Market
Food Additives and Ingredients
Sucroglycerides Market
Food Additives and Ingredients
Trans Fatty Acids Market
Food Additives and Ingredients
Spain Food Acidulants Market
Food Additives and Ingredients
Egg Wash Substitute Market
Food Additives and Ingredients
France Food Additives Market
Food Additives and Ingredients
Food and Beverages Color Fixing Agents Market
Food Additives and Ingredients
Argentina Food Enzymes Market
Food Additives and Ingredients
Argentina Food Acidulants Market
Food Additives and Ingredients
Global Fatty Acids Market
Food Additives and Ingredients
North America Feed Additives Market