
 Asia-Pacific Food Emulsifier Market | 2026-2036
Asia-Pacific Food Emulsifier Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Food Emulsifier Market Outlook
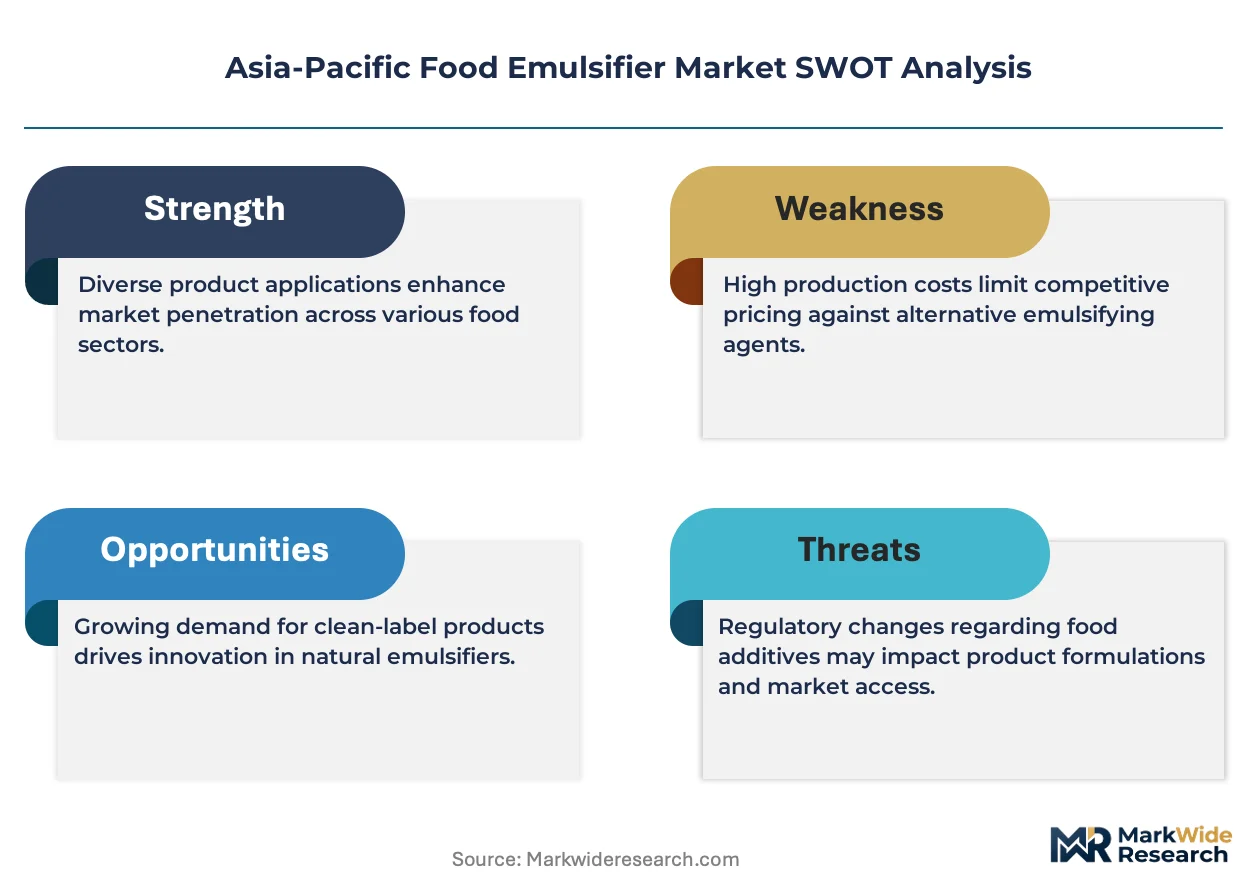
Clean-label enzyme modification is narrowing the performance gap between synthetic and plant-derived emulsifiers across Asia-Pacific processing lines. Cargill Incorporated leverages its integrated oilseed processing network to secure consistent lecithin supply chains. BASF SE anchors its position through specialized polyglycerol ester portfolios tailored to tropical climate stability. Kerry Group PLC differentiates via fermentation-derived solutions that bypass allergen labeling triggers.
Asia-Pacific food emulsifiers comprise surface-active compounds—typically esterified fatty acids, phospholipids, or polyol derivatives—that reduce interfacial tension between immiscible phases such as oil and water, with hydrophilic-lipophilic balance values generally ranging from 2 to 16 depending on intended functionality. Mono- and di-glycerides retain dominant volume share due to cost efficiency and broad regulatory acceptance across ASEAN formulations. Lecithin segments accelerate fastest as plant-based sourcing claims displace animal-derived alternatives in premium applications. Polyglycerol esters capture concentrated margin pools where heat stability and extended shelf life justify formulation premiums.
Japan's Ministry of Health, Labour and Welfare positive list system and China's SAMR food additive safety standards collectively elevate compliance burdens for imported emulsifier formulations. Australia's FSANZ code and South Korea's MFDS notification requirements add further layer variations that fragment market access protocols. India's FSSAI emulsifier purity specifications are tightening ahead of broader packaged food sector reforms. Stakeholders must monitor divergence between national positive lists and harmonized Codex frameworks to anticipate reformulation costs and registration timelines.
Market Dynamics
Japan's positive list system for food additives is forcing rapid reformulation across Asia-Pacific emulsifier supply chains, compressing registration timelines and elevating purity specifications beyond Codex baselines. Manufacturers must now maintain parallel formulation portfolios to satisfy divergent national safety standards.
Growth Catalysts
- Processed dairy expansion:Southeast Asian dairy processors are scaling emulsifier volumes to support extended shelf-life UHT milk and recombined cream applications.
- SAMR food additive safety standards:China's tightened purity specifications are accelerating domestic substitution for imported emulsifier grades, creating captive demand for local producers.
- Enzyme modification advances:Clean-label enzymatic processes are narrowing performance gaps between synthetic and plant-derived emulsifiers across ASEAN processing lines.
Market Restraints
- Palm oil feedstock volatility:Malaysian and Indonesian palm kernel oil price swings directly compress margins on mono- and di-glyceride production.
- MFDS notification complexity:South Korea's layered additive approval protocols extend market access timelines for new emulsifier entrants by 12-18 months.
- Soy lecithin allergen labeling:FSSAI tightening on soy-derived ingredient declarations is constraining formulation flexibility in India's packaged food sector.
Strategic Opportunities
- Vietnam's underpenetrated bakery sector:Western-style bread and pastry processing is creating first-mover advantage for emulsifier suppliers establishing technical service presence.
- Fermentation-derived emulsifiers:Microbial production platforms bypass allergen triggers and unlock premium positioning in Japan's functional food applications.
- E-commerce ingredient channels:Direct procurement platforms are disintermediating traditional distributor networks for mid-tier food manufacturers across China.
Industry Challenges
- Positive list synchronization:Divergence between Japan's MHLW positive list and China's SAMR approved additives database forces redundant safety dossier preparation.
- Heat stability engineering:Tropical climate distribution requirements demand extended shelf-life validation that stretches R&D timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Food Emulsifier Market |
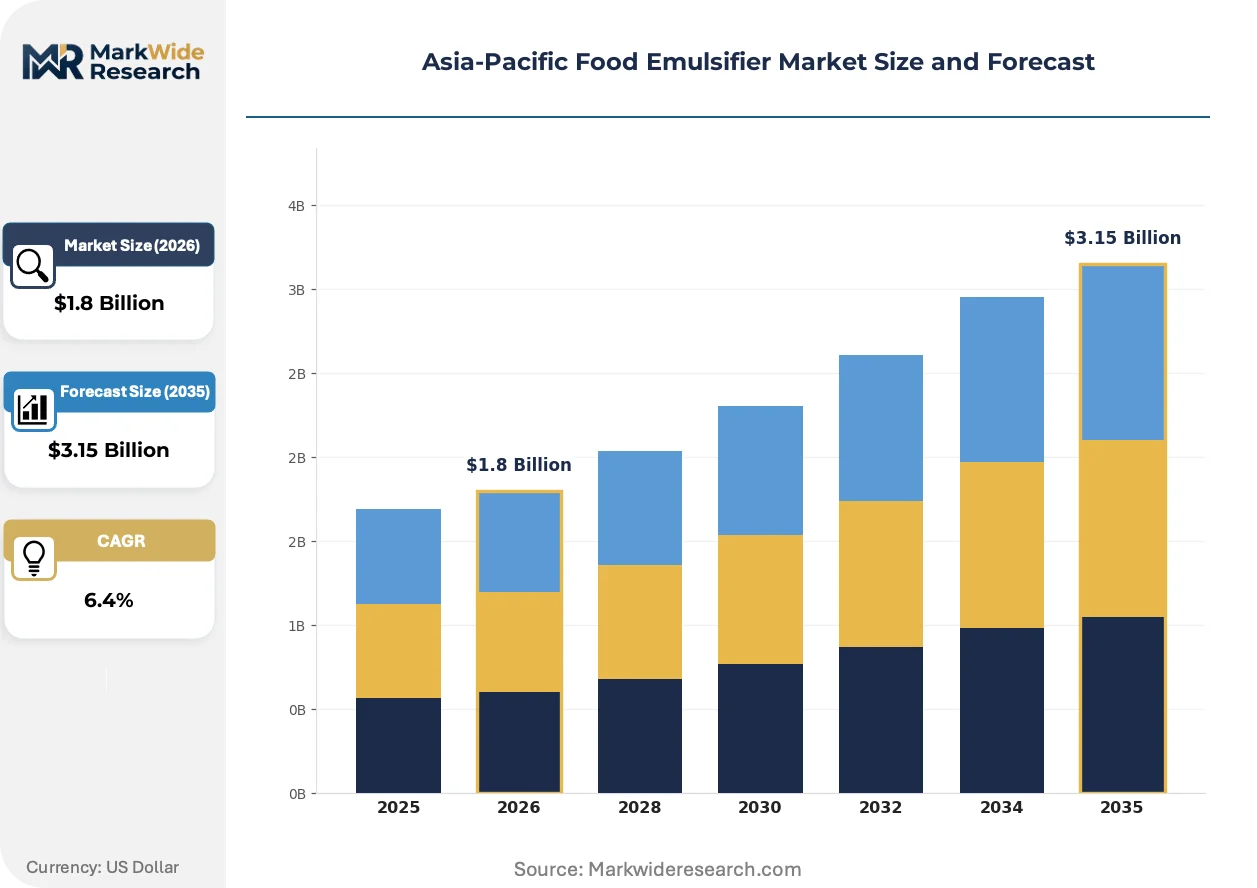
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mono- and Di-Glycerides, Lecithin, Sorbitan Esters, Polyglycerol Esters Application: Baked Goods, Dairy Products, Dressings, Sauces Source: Plant-Based, Animal-Based, Synthetic, Fermented Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, DuPont de Nemours Inc., Kerry Group PLC, BASF SE, Corbion N.V., Tate & Lyle PLC, Palsgaard A/S, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Food Emulsifier Market Strategic Shifts
Clean-label enzyme technology is compressing the traditional synthetic-versus-natural emulsifier trade-off, while regulatory divergence between national positive lists is fragmenting formulation standardization across the region.
Phospholipid fractionation technology is hybridizing crude lecithin into high-purity phosphatidylcholine and phosphatidylethanolamine fractions with tailored HLB values. Japanese functional food manufacturers are adopting these refined grades at accelerated pace for cognitive health positioning. The technology is hybridizing commodity lecithin supply chains into performance-tiered ingredient portfolios that command formulation premiums.
China's SAMR food additive safety standards are tightening purity specifications ahead of broader packaged food sector reforms. Domestic emulsifier producers are capturing share from import-dependent processors by pre-certifying to these elevated baselines. Premium bakery and infant nutrition applications in Shanghai and Jiangsu province are most affected, with local suppliers accelerating technical service investments.
Direct procurement through B2B ingredient platforms is consolidating purchasing power among mid-tier ASEAN food manufacturers. Traditional distributor networks with technical advisory capabilities are losing share to algorithmic pricing and transparent specification comparison. This channel shift is most visible in Thailand's expanding processed dairy sector, where plant managers now specify emulsifiers through digital catalogs rather than legacy supplier relationships.
Asia-Pacific Food Emulsifier Market Segmentation
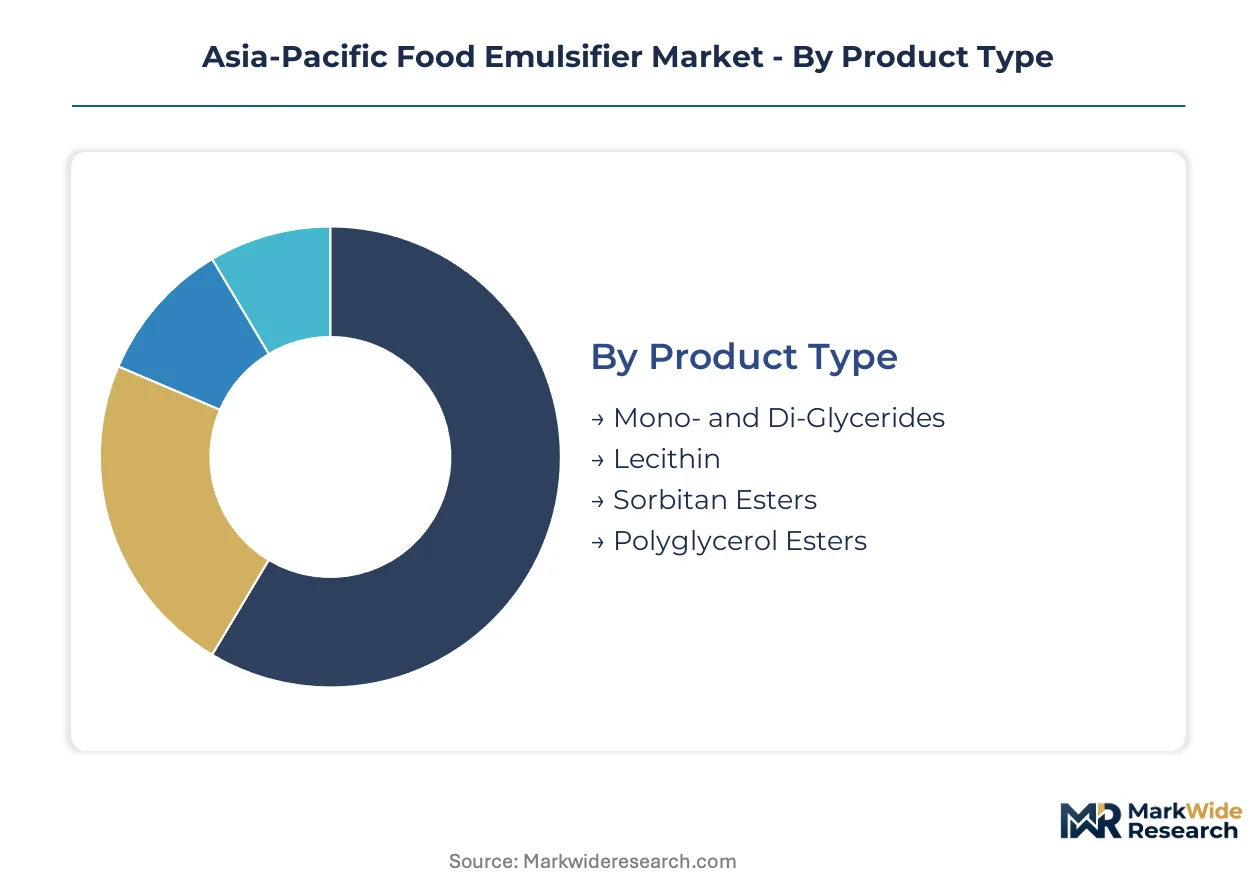
Emulsifier selection across Asia-Pacific processing lines hinges on precise matching of hydrophilic-lipophilic balance values to specific food matrix requirements. Technical service intensity varies sharply by segment, with reformulation support demands highest where regulatory divergence between Japan's MHLW positive list and China's SAMR standards forces parallel qualification protocols.
Product Type:
After-sales technical service intensity peaks with polyglycerol esters and fermented grades, where heat stability validation and regulatory dossier preparation consume disproportionate supplier resources.
- Mono- and Di-Glycerides:Esterified fatty acid derivatives produced from glycerol and triglyceride feedstocks, typically exhibiting HLB values between 3 and 6 for water-in-oil applications. Southeast Asian dairy processors in Thailand and Vietnam concentrate procurement here for cost-sensitive UHT milk and recombined cream formulations where extended shelf-life specifications must balance against margin pressure. Mono- and di-glycerides hold the largest share; momentum sits with lecithin as plant-based claims displace synthetic alternatives.
- Lecithin:Phospholipid mixtures extracted from soybean, sunflower, or rapeseed sources, with crude grades refined through fractionation into phosphatidylcholine-enriched fractions for premium positioning. Japanese functional food manufacturers in Tokyo and Osaka corridors are adopting high-purity grades at accelerated pace for cognitive health applications, bypassing allergen labeling triggers that constrain soy-derived alternatives in infant nutrition.
- Sorbitan Esters:Fatty acid esters of sorbitol with HLB ranges spanning 4.7 to 8.6, serving niche stability requirements in tropical climate distribution.
- Polyglycerol Esters:Condensed glycerol polymers esterified with C8-C18 fatty acids, commanding formulation premiums where thermal processing demands exceed 120°C.
Cost tier stratification separates commodity mono- and di-glycerides from performance-priced polyglycerol esters, with lecithin fractionation technology bridging mid-market positioning.
Application:
Application-driven segmentation reveals divergent technical support requirements, with dairy processors demanding intensive shelf-life validation versus bakery formulators prioritizing dough conditioning consistency.
- Baked Goods:Bread, pastry, and cake applications requiring emulsifiers for crumb softening, volume enhancement, and anti-staling functionality. Vietnam's western-style bakery sector expansion is creating first-mover advantage for suppliers establishing localized technical service presence, particularly around Ho Chi Minh City processing clusters where European-style laminated dough techniques are displacing traditional methods.
- Dairy Products:UHT milk, recombined cream, and processed cheese applications where emulsifiers stabilize fat globule distribution and prevent creaming. China's eastern manufacturing corridor spanning Shanghai and Jiangsu province concentrates demand as domestic processors scale capacity to serve premium infant nutrition and extended shelf-life milk segments.
- Dressings:Mayonnaise and salad dressing emulsions requiring oil-in-water stability across variable cold-chain conditions.
- Sauces:Processed savory applications where heat stability and freeze-thaw tolerance determine formulation selection.
Dairy applications command the deepest technical engagement; baked goods are climbing the fastest as Vietnam's processing base matures.
Source:
Source-based segmentation tracks the accelerating shift from synthetic and animal-derived origins toward plant-based and fermentation platforms that satisfy clean-label positioning and allergen avoidance requirements.
- Plant-Based:Soy, sunflower, and rapeseed lecithin derivatives alongside palm-derived mono- and di-glycerides. Malaysian and Indonesian palm kernel oil price volatility directly compresses margins on plant-derived mono- and di-glyceride production, forcing processors to maintain dual sourcing strategies across Southeast Asian supply chains.
- Animal-Based:Tallow-derived and other animal-origin emulsifiers facing declining acceptance across ASEAN markets as halal certification requirements tighten and consumer preference shifts accelerate.
- Synthetic:Petrochemical-derived emulsifiers retaining cost advantage in commodity applications but losing share to enzymatically modified plant alternatives as clean-label enzyme technology narrows performance gaps.
- Fermented:Microbial production platforms generating glycolipid and phospholipid emulsifiers that bypass allergen labeling triggers entirely. Japan's functional food sector is adopting fermentation-derived solutions at premium positioning for cognitive health and gut microbiome applications where synthetic alternatives face formulation barriers.
Plant-based sourcing retains volume dominance; fermented platforms are expanding most quickly on allergen-free positioning.
Distribution Channel:
Channel segmentation captures the disintermediation pressure from B2B ingredient platforms that consolidate mid-tier manufacturer purchasing power across Thailand's processed dairy expansion and China's eastern corridor.
- Wholesale:Traditional distributor networks with technical advisory capabilities serving established processors through relationship-based procurement. Legacy networks are losing share to algorithmic pricing platforms in Thailand's expanding processed dairy sector, where plant managers increasingly specify emulsifiers through digital catalogs.
- Retail:Packaged ingredient sales to small-scale food manufacturers and artisanal processors, concentrated in India's fragmented bakery sector ahead of FSSAI emulsifier purity specification tightening.
- Online:B2B ingredient platforms enabling direct procurement with transparent specification comparison and consolidated purchasing power. China's mid-tier food manufacturers are shifting procurement to these channels most visibly, disintermediating traditional technical service relationships in Shanghai and Jiangsu province.
- Direct Sales:Supplier-manufacturer relationships for large-volume accounts requiring customized formulation support and regulatory dossier preparation. Direct channels retain dominance for polyglycerol ester and fermented grades where Japan's MHLW positive list compliance demands intensive technical collaboration.
Wholesale channels retain the largest transaction volume; online platforms are gaining share fastest among mid-tier processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asia-Pacific's food emulsifier trade flows reveal divergent national strategies: China and Japan drive import substitution while Southeast Asian markets deepen reliance on regional supply corridors. Export-oriented processors in Thailand and Vietnam capture downstream value through processed dairy and bakery applications.
China
Shanghai and Jiangsu province concentrate emulsifier demand from infant nutrition and premium bakery processors scaling domestic capacity. SAMR food additive safety standards are tightening purity specifications ahead of broader packaged food sector reforms, accelerating substitution for imported grades. Local producers are pre-certifying to elevated baselines to capture share from import-dependent processors in the eastern manufacturing corridor.
Japan
Tokyo and Osaka corridors drive adoption of high-purity phospholipid fractions for cognitive health positioning in functional foods. The Ministry of Health, Labour and Welfare positive list system forces rapid reformulation across supply chains, compressing registration timelines and elevating purity specifications beyond Codex baselines. Fermentation-derived emulsifiers are gaining premium positioning for gut microbiome applications where synthetic alternatives face formulation barriers.
Thailand
Processed dairy expansion across Bangkok-centered processing clusters is scaling emulsifier volumes for extended shelf-life UHT milk and recombined cream. Plant managers are shifting procurement to B2B ingredient platforms with algorithmic pricing, disintermediating traditional distributor networks with technical advisory capabilities. Western-style bakery processing is creating first-mover advantage for suppliers establishing localized technical service presence.
Vietnam
Ho Chi Minh City processing clusters are displacing traditional methods with European-style laminated dough techniques, driving emulsifier uptake in the underpenetrated bakery sector. Cost-sensitive formulations favor mono- and di-glycerides for margin-constrained processors scaling western-style bread and pastry output. First-mover suppliers are investing in technical service infrastructure to capture emerging demand.
India
Maharashtra and Gujarat industrial corridors face tightening FSSAI emulsifier purity specifications ahead of broader packaged food sector reforms. Soy lecithin allergen labeling requirements are constraining formulation flexibility in the fragmented bakery sector. Domestic producers are capturing share from import-dependent processors by aligning with tightening purity baselines.
Asia-Pacific Food Emulsifier Market Competitive Environment
On the supply side, the industry is consolidating around integrated oilseed processors and specialized fermentation platforms that control critical feedstock pathways. Three archetypes dominate: multinational agribusiness conglomerates with captive oilseed crushing capacity, European chemical specialists with polyol ester technology portfolios, and Asia-Pacific fermentation platforms leveraging microbial production for allergen-free positioning. Competitive moves center on backward integration into palm and soy feedstocks and geographic expansion through technical service localization in Vietnam and Indonesia.
Within the integrated agribusiness tier, Cargill Incorporated and Archer Daniels Midland Company exemplify scale-driven supply chain control, anchoring positions through oilseed processing networks that secure consistent lecithin availability. BASF SE and Kerry Group PLC occupy the specialty formulation segment, with the former representing European chemical expertise in heat-stable polyol esters and the latter exemplifying fermentation-derived solutions that bypass allergen labeling triggers. Corbion N.V. and Palsgaard A/S represent mid-cap specialists with concentrated technical service capabilities in tropical climate stability validation.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| DuPont de Nemours Inc. |
| Kerry Group PLC |
| BASF SE |
| Corbion N.V. |
| Tate & Lyle PLC |
| Palsgaard A/S |
| Others |
Value Chain & Pricing Dynamics
Malacca Strait shipping corridors transmit palm kernel oil cost volatility directly into mono- and di-glyceride pricing tiers across Southeast Asian dairy processors. This logistics chokepoint concentrates supply-side leverage among integrated crushers in Malaysia and Indonesia while forcing downstream formulators into dual-sourcing strategies that fragment procurement efficiency.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume-scale discounts dominating commodity-grade mono- and di-glycerides. Price differentiation rests on certification grade—SAMR pre-certified suppliers command premiums over import-dependent competitors—and vertical integration into palm crushing assets. Cost compression in standard-grade lecithin is intensifying because Malaysian feedstock volatility outpaces formulation pass-through capabilities. Mid-tier bakery processors in Vietnam exhibit highest price sensitivity, while Japanese functional food manufacturers demonstrate lowest sensitivity for phospholipid fractions with cognitive health positioning.
Supply Chain Analysis
Crude lecithin feedstocks concentrate in Malaysian and Indonesian palm oil complexes, with soy-derived alternatives anchored in Chinese and Indian oilseed crushing corridors. Raw material dependencies span palm kernel oil, crude soybean lecithin, and glycerol from biodiesel co-production streams. Single-source vulnerability runs through Malacca Strait logistics channels where congestion events disrupt just-in-time delivery to Thai and Vietnamese processors. Distribution runs through B2B ingredient platforms consolidating mid-tier manufacturer purchasing power alongside direct sales channels for fermentation-derived grades requiring regulatory dossier support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Thailand's processed dairy processors and China's eastern corridor infant nutrition formulators as procurement shifts to algorithmic B2B platforms that disintermediate traditional distributor relationships.
For Market Incumbents: Harden technical service localization in Vietnam's Ho Chi Minh City processing clusters to defend against first-mover entrants capturing western-style bakery expansion. Deepen backward integration into Indonesian palm kernel oil assets to insulate margin structures from feedstock volatility that synthetic competitors cannot replicate. Certification investment in SAMR pre-approved additive grades creates switching costs for Chinese processors accelerating domestic substitution. For New Entrants and Emerging Players: Vietnam's underpenetrated bakery sector offers white-space capture through localized dough-conditioning technical support that European-style laminated processing techniques now require. Fermentation-derived emulsifier platforms bypass soy allergen labeling triggers constraining incumbents in India's FSSAI-tightening market. Go-to-market through direct e-commerce ingredient channels disintermediates legacy distributor networks in Thailand's expanding processed dairy base. For Investors and Strategic Acquirers: Japan's MHLW positive list synchronization with China's SAMR database reshapes the acquisition landscape toward fermentation-platform specialists with dual-market regulatory dossiers already filed. Long-term viability favors microbial production assets over palm-dependent crushing infrastructure as clean-label positioning hardens across ASEAN. Watch for MFDS notification backlog clearance velocity as the signal indicating when South Korean market access timelines compress for new technology entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palm Kernel Oil Assets | Captive feedstock supply insulates margin compression from Malaysian price volatility. |
| SAMR Pre-Certification Investment | Accelerated domestic substitution in China's eastern manufacturing corridor displaces import-dependent competitors. |
| Fermentation Platform Scale-Up | Microbial production bypasses soy allergen triggers tightening under India's FSSAI reforms. |
| Technical Service Localization in Vietnam | Western-style bakery expansion in Ho Chi Minh City clusters demands dough-conditioning expertise. |
| B2B E-Commerce Channel Development | Algorithmic pricing platforms consolidate mid-tier processor purchasing power across Thailand's dairy sector. |
Study Parameters
Two parallel data streams informed the analysis: structured interviews with emulsifier procurement managers at Thai and Vietnamese dairy processors, technical R&D directors at Japanese functional food manufacturers, and regulatory affairs leads navigating MHLW positive list compliance; alongside secondary validation through SAMR food additive safety standards filings, ASEAN customs trade data, and SEC 10-K disclosures from integrated oilseed processors. Bottom-up volume triangulation across product-grade segments was cross-checked against top-down market sizing from industry association reports.
Forecast inputs across the projection horizon modeled hydrophilic-lipophilic balance grade tier, application segment intensity, source-origin platform type, and regional regulatory cluster divergence. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic indicators for processed food consumption. Industry-specific inputs included palm kernel oil price elasticity coefficients and enzyme modification technology adoption curves across ASEAN processing lines.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by Chinese state-linked oilseed processors would shift outcomes through accelerated domestic substitution. Cross-checking against SAMR food additive registration velocity data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Global Fatty Acids Market
Food Additives and Ingredients
Nanoencapsulated Food Additives Market
Food Additives and Ingredients
Middle East and Africa Clean Label Ingredients Market
Food Additives and Ingredients
Europe Food Micronized Salt Market
Food Additives and Ingredients
Global Canthaxanthin Market
Food Additives and Ingredients
Cake Enzyme Market
Food Additives and Ingredients
Food Grade Potassium Sorbate Market
Food Additives and Ingredients
Food Binders Market
Food Additives and Ingredients
Ammonium Chloride Food Grade Market
Food Additives and Ingredients
Germany Feed Additives Market
Food Additives and Ingredients
South America Food Stabilizers Market
Food Additives and Ingredients
Australia Food Emulsifiers Market
Food Additives and Ingredients
Global Organic Food Preservatives Market
Food Additives and Ingredients
Organic Food Additives Market
Food Additives and Ingredients
Chymosine Market
Food Additives and Ingredients
Sunset Yellow FCF Market