
 Food Colorants Market | 2026-2036
Food Colorants Market Size, Share, and Industry Trends Forecast 2026-2036
Food Colorants Market Analysis
Specialty ingredient distribution is fragmenting as regional distributors lose ground to direct procurement platforms and co-manufacturer networks. Sensient Technologies Corporation leverages its integrated extraction capabilities to supply beverage giants with stable anthocyanin formulations. Archer-Daniels-Midland anchors North American supply through its botanical sourcing infrastructure and fermentation-derived color platforms. Chr. Hansen Holding A/S differentiates via microbial pigment expertise, particularly in dairy applications where heat stability determines contract viability.
Food colorants comprise pigments, dyes, and lakes dissolved or dispersed into edible matrices to confer visual identity, with natural variants extracted from fruits, vegetables, insects, or microorganisms and synthetic variants synthesized from petroleum-derived aromatic hydrocarbons using azo or triarylmethane chemistries. These additives must achieve specified tinctorial strength, pH stability between 2.5 and 8.0, and lightfastness exceeding 80 hours under accelerated testing to maintain shelf appeal across processed food systems. Natural colorants now lead type-based value pools as beverage and confectionery manufacturers reformulate around consumer preference for plant-derived ingredients, while synthetic variants retain volume dominance in bakery items where cost thresholds override clean-label positioning. Liquid forms command premium placement in automated dosing systems at large-scale food manufacturers, though powder formats sustain margin resilience among regional processors seeking transport efficiency.
EFSA maintains stringent toxicological evaluation protocols for synthetic colorants under EU Regulation 1333/2008, while the FDA's Color Additive Status List governs permissible daily exposure limits and batch certification requirements for lakes and dyes in the United States. India's FSSAI has progressively tightened additive approvals, aligning with Codex Alimentarius frameworks while imposing additional indigenous testing mandates that extend market access timelines for imported synthetic portfolios. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and secure dual-territory product registrations before competitor lock-in accelerates.
Market Dynamics
EFSA's 2021 ban on titanium dioxide as a food additive and escalating scrutiny of azo dyes under EU Regulation 1333/2008 are forcing multinational reformulation programs that favor natural colorant portfolios over synthetic alternatives.
Growth Catalysts
- Beverage Industry Reformulation:Major soft drink and juice manufacturers are converting production lines to anthocyanin and carotenoid-based color systems to meet clean-label commitments and preempt regulatory restrictions on synthetic alternatives.
- FSSAI Clean-Label Mandates:India's food safety regulator has tightened additive approval protocols and mandated front-of-pack labeling disclosures, accelerating procurement of plant-derived colorants among export-oriented processors in Gujarat and Maharashtra.
- Microbial Pigment Platforms:Fermentation-derived colorants from fungal and bacterial sources are achieving commercial scale, offering batch consistency and year-round supply security that agricultural extraction cannot match.
Market Restraints
- Raw Material Volatility:Beetroot and grape skin concentrate prices fluctuate with agricultural yield cycles and climate disruption in major growing regions, compressing margins for natural colorant suppliers.
- Heat Stability Limitations:Anthocyanin formulations degrade above 85°C, restricting their deployment in ultra-high-temperature processed dairy and baked goods where synthetic alternatives maintain performance.
- Extended Certification Timelines:India's FSSAI imposes indigenous toxicological testing mandates that add 18-24 months to market access for imported synthetic color portfolios, locking out foreign suppliers.
Strategic Opportunities
- Encapsulation Technology Convergence:Microencapsulation of natural pigments with lipid and protein matrices is extending pH and thermal stability ranges, opening reformulation pathways into confectionery and extruded snacks.
- Direct Procurement Platforms:Food manufacturers are bypassing traditional distributors to source colorants through digital B2B marketplaces and co-manufacturer networks, collapsing margin layers for intermediaries.
- Plant-Based Meat Analogues:Myoglobin-mimicking heme and beet-derived color systems are capturing new volume as meat substitute manufacturers seek authentic browning and bleeding visual cues.
Industry Challenges
- Formulation Chemistry Expertise Gap:Natural colorant stabilization requires specialized knowledge of antioxidant synergists and chelating agents that legacy synthetic colorant technical teams rarely possess.
- Legacy Equipment Retrofit Costs:Automated dosing systems designed for liquid synthetic dyes require capital-intensive recalibration to handle viscous natural extracts with variable solids content and particulate loading.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Colorants Market |
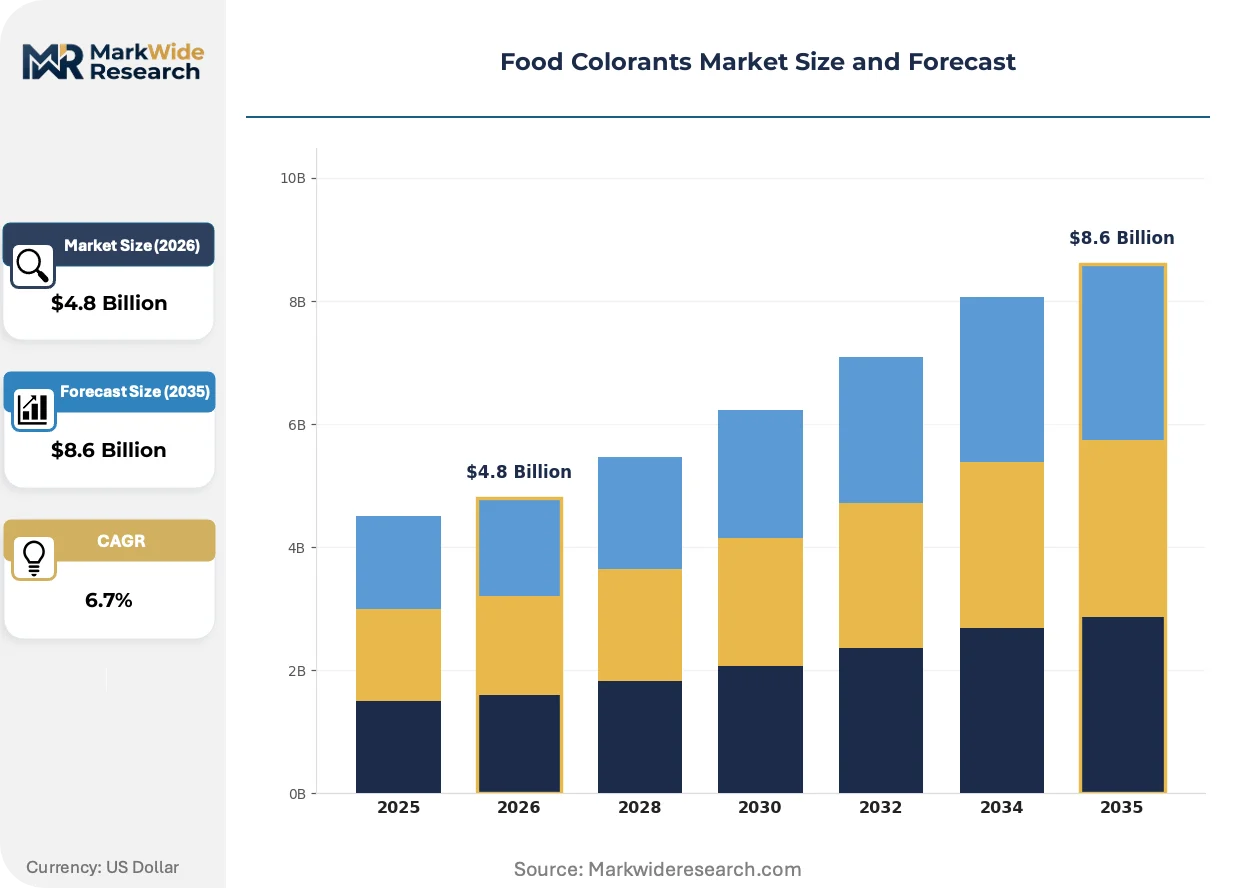
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
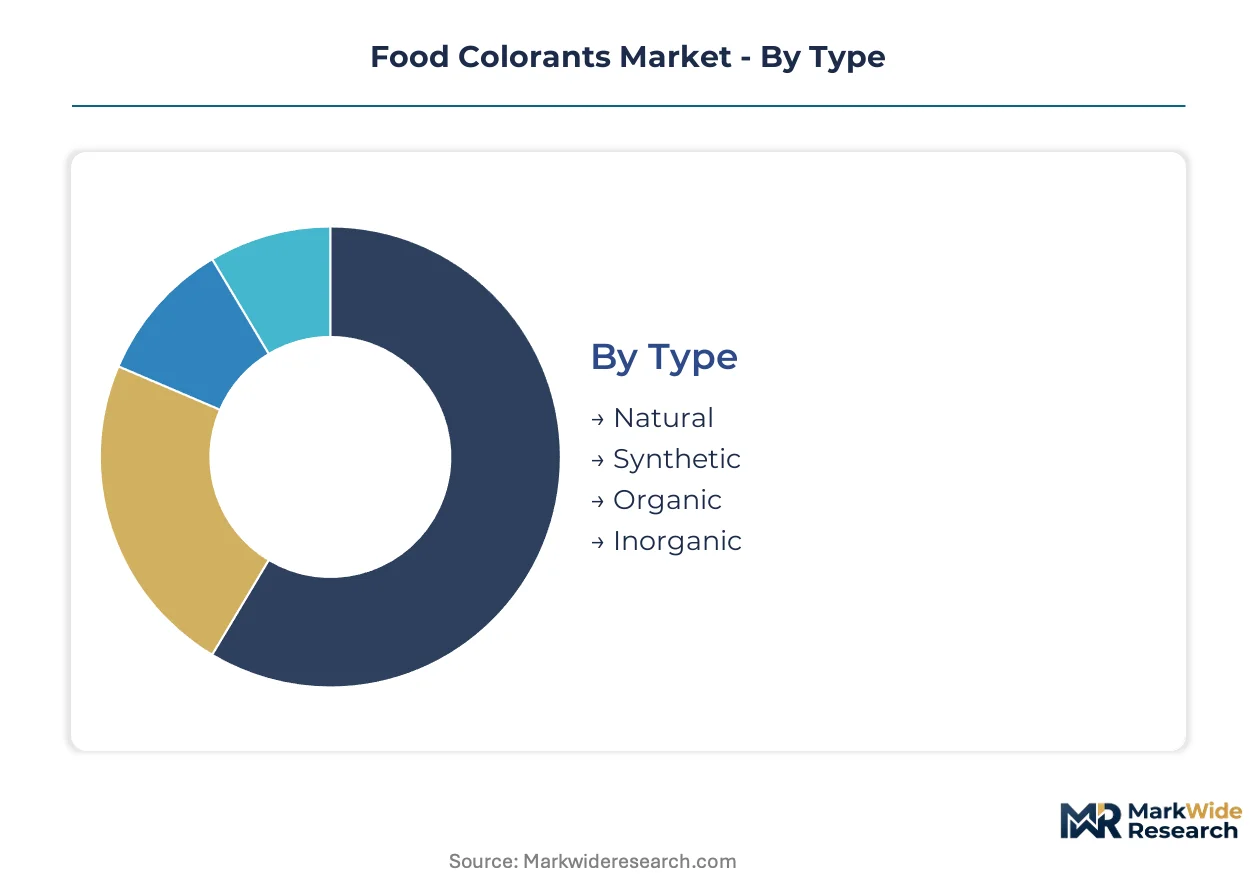
| Segmentation | Type: Natural, Synthetic, Organic, Inorganic Application: Beverages, Dairy Products, Confectionery, Bakery Items Form: Liquid, Powder, Gel, Paste End User: Food Manufacturers, Beverage Companies, Retailers, Restaurants |
| Companies Covered | Sensient Technologies Corporation, Archer-Daniels-Midland, Koninklijke DSM N.V., Dohler Group, Symrise AG, Chr. Hansen Holding A/S, Givaudan S.A., Kalsec Inc., GNT Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Colorants Market Emerging Trajectories
Clean-label positioning has shifted from marketing differentiation to regulatory survival, with extraction technologies and stabilization chemistries now determining which suppliers retain shelf space at major food manufacturers.
Encapsulation systems combining modified starch and gum arabic matrices are collapsing the performance gap between natural and synthetic colorants in high-heat applications. Confectionery multinationals in Western Europe and North America are adopting these systems at pilot scale, with full production line conversions accelerating as heat-stable anthocyanin formulations achieve 12-month shelf life targets previously reserved for azo dyes.
REACH authorization requirements for aromatic amine-derived pigments are compelling EU-based manufacturers to eliminate legacy synthetic portfolios ahead of 2026 sunset dates. The industrial consequence is a supply squeeze for compliant alternatives, with dairy processors most affected as they scramble to secure heat-stable carotenoid supplies for cheese and butter applications before competitor lock-in accelerates.
Buyer concentration among multinational food manufacturers is compressing supplier negotiation cycles and unbundling technical service from base ingredient contracts. Regional colorant distributors are losing ground to direct platform procurement, with this disintermediation most visible in India where FSSAI-registered domestic extractors are securing long-term supply agreements with beverage and dairy processors in Mumbai and Delhi-NCR industrial corridors.
Food Colorants Market Segmentation
Colorant procurement cycles vary dramatically across the food colorants market, with beverage reformulation programs turning over in 12-18 months while bakery ingredient specifications persist for 5-7 years. Understanding these velocity differentials helps suppliers align inventory positions and technical service investments with segment-specific renewal patterns.
Type:
Natural colorants command the shortest procurement cycles as beverage and confectionery manufacturers accelerate reformulation timelines, while synthetic portfolios face extended recertification delays in regulated markets.
- Natural:Anthocyanin, carotenoid, and betalain extracts from fruits, vegetables, and microorganisms now dominate new product development. Beverage manufacturers in India and Western Europe are converting production lines to these plant-derived systems ahead of regulatory sunset dates for titanium dioxide and azo dyes.
- Synthetic:Petroleum-derived azo and triarylmethane chemistries retain volume dominance in cost-sensitive bakery applications where heat stability requirements exceed natural pigment performance thresholds. Extended FSSAI certification timelines for imported synthetic portfolios are locking foreign suppliers out of Indian procurement channels.
- Organic:Certified organic colorants carry premium positioning in baby food and premium confectionery segments where dual organic-clean-label claims command shelf price multiples.
- Inorganic:Mineral-based pigments including iron oxides and titanium dioxide face contracting food-grade applications following EFSA's titanium dioxide ban, with residual demand concentrating in non-EU markets with less stringent toxicological evaluation protocols.
Natural dominates installed base growth. Synthetic is where margin compression concentrates most severely.
Application:
Cost tier stratification separates premium-positioned applications willing to absorb natural colorant premiums from commodity segments where synthetic alternatives retain economic viability.
- Beverages:Anthocyanin-based reds and carotenoid oranges are displacing synthetic alternatives in soft drinks and juices. EFSA scrutiny of azo dyes and consumer clean-label preferences are accelerating procurement of stable, pH-tolerant natural formulations with 12-month shelf life targets.
- Dairy Products:Heat-stable carotenoids for cheese and butter applications face supply squeezes as EU manufacturers eliminate legacy synthetic portfolios ahead of REACH authorization deadlines. Microbial-derived beta-carotene from fermentation platforms is capturing share in yogurt and ice cream segments.
- Confectionery:Microencapsulated natural pigments are achieving commercial scale in high-heat extruded and panned candy applications where thermal degradation previously restricted natural colorant deployment.
- Bakery Items:Cost thresholds override clean-label positioning in mass-market bread and cake segments, preserving synthetic dye volumes despite regulatory pressure in premium European markets.
Beverages command the steepest expansion trajectory. Bakery represents the most entrenched synthetic stronghold.
Form:
Volume scale separates automated dosing applications requiring liquid consistency from regional processors prioritizing transport efficiency and shelf stability.
- Liquid:Standardized dispersions with controlled viscosity and solids content integrate with automated metering systems at large-scale food manufacturers. Premium placement reflects dosing precision and reduced handling labor.
- Powder:Spray-dried and freeze-dried concentrates sustain margin resilience among regional processors and export-oriented suppliers seeking reduced shipping weights and extended ambient storage stability.
- Gel:High-viscosity suspensions target artisanal and small-batch food manufacturers with manual mixing processes and intermittent production schedules.
- Paste:Concentrated semi-solid formats serve specialty confectionery and decoration applications requiring precise color matching and minimal moisture addition.
Liquid dominates capital-intensive manufacturing installations. Powder is where regional supplier differentiation concentrates.
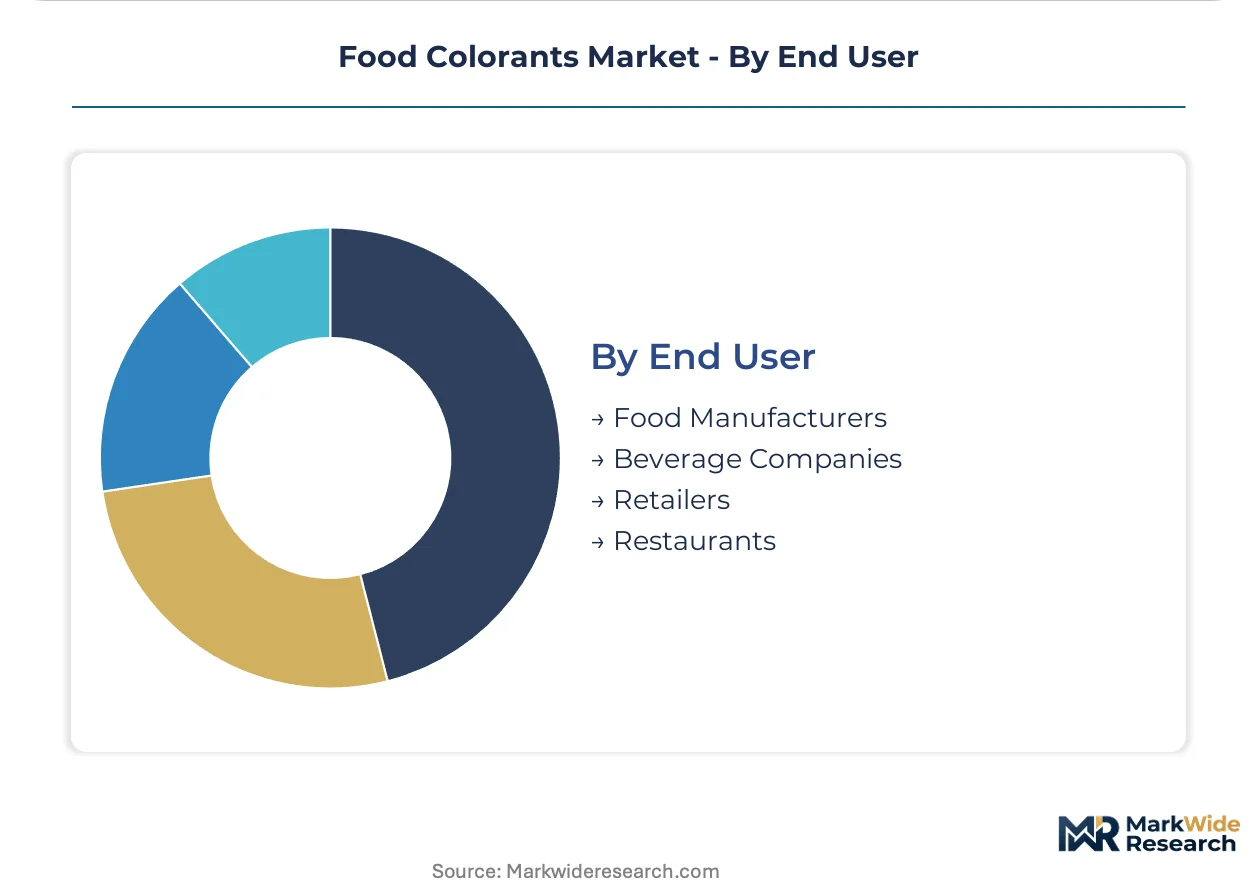
End User:
Customer type determines technical service intensity, with multinational food manufacturers demanding formulation partnership while retailers and restaurants prioritize procurement simplicity.
- Food Manufacturers:Integrated procurement teams are bypassing distributors for direct platform sourcing of colorants, collapsing margin layers and unbundling technical consultation from base ingredient contracts.
- Beverage Companies:Reformulation programs at major soft drink and juice multinationals are driving anthocyanin and carotenoid volume growth, with heat stability and pH tolerance specifications determining supplier selection.
- Retailers:Private-label food producers are consolidating colorant specifications across product categories to simplify procurement and reduce SKU complexity in ingredient inventories.
- Restaurants:Food service distributors supply standardized colorant formats to commercial kitchens with limited technical staff and minimal formulation customization requirements.
Food manufacturers anchor volume concentration. Beverage companies are where specification innovation accelerates fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Western Europe where EFSA regulatory barriers protect premium natural colorant suppliers, while cost-sensitive procurement in South Asia compresses margins for commodity-grade formulations.
United States
Beverage manufacturers in California and Texas are accelerating anthocyanin adoption as FDA batch certification requirements for synthetic lakes tighten compliance costs. The FDA's Color Additive Status List governs permissible exposure limits for azo dyes in confectionery applications. Chicago and Minneapolis industrial corridors host reformulation laboratories where dairy processors test heat-stable carotenoid alternatives to synthetic portfolios.
Germany
REACH authorization deadlines for aromatic amine-derived pigments are forcing dairy and bakery manufacturers to eliminate legacy synthetic colorants by 2026. ECHA substance evaluation protocols now classify several azo dye metabolites as substances of very high concern. Bavarian and North Rhine-Westphalia food clusters are securing fermentation-derived beta-carotene supplies through direct contracts with microbial pigment platforms.
India
FSSAI-mandated front-of-pack labeling disclosures and clean-label additive approvals are redirecting procurement toward plant-derived colorants in beverage and dairy segments. The regulator's indigenous toxicological testing mandates extend market access timelines for imported synthetic portfolios by 18-24 months. Gujarat and Maharashtra export-processing zones are consolidating supply agreements with domestic extractors of turmeric, annatto, and beetroot concentrates.
Brazil
ANVISA alignment with Codex Alimentarius frameworks is accelerating natural colorant adoption in juice and soft drink manufacturing while preserving synthetic dye volumes in mass-market bakery. The regulator's updated additive monographs impose stricter purity specifications on imported azo dyes. São Paulo and Minas Gerais industrial corridors are expanding extraction capacity for annatto and paprika oleoresins to serve Mercosur export markets.
China
SAMR implementation of GB standards for natural food colorants is standardizing quality specifications for carotenoid and anthocyanin extracts in domestic and export-oriented manufacturing. The regulator's 2023 updates to food additive usage standards expanded permitted applications for fermentation-derived pigments. Shandong and Jiangsu provinces are scaling microbial pigment fermentation facilities to reduce dependency on agricultural extraction vulnerable to climate disruption.
Food Colorants Market Vendor Landscape
Integrated extraction specialists and fermentation-platform operators split the market into technology-driven tiers, with botanical sourcing capabilities and microbial pigment expertise determining contract viability at multinational food manufacturers. Three archetypes dominate: agricultural extractors with vertical control over raw material supply, biotechnology firms deploying fungal and bacterial fermentation systems, and hybrid operators combining both production modes. Competitive positioning hinges on securing long-term supply agreements with beverage multinationals and achieving FSSAI or EFSA regulatory pre-approval for novel colorant formulations.
Within the integrated-extraction tier, Sensient Technologies Corporation and Archer-Daniels-Midland exemplify archetypes built on captive agricultural sourcing and global distribution infrastructure. Chr. Hansen Holding A/S occupies a distinct position as a fermentation-platform specialist, representing the biotechnology-driven segment where batch consistency and year-round supply security override seasonal agricultural constraints. These three entities anchor the competitive structure, with their strategic orientations shaping procurement patterns across beverage, dairy, and confectionery applications.
| Leading Market Players |
|---|
| Sensient Technologies Corporation |
| Archer-Daniels-Midland |
| Koninklijke DSM N.V. |
| Dohler Group |
| Symrise AG |
| Chr. Hansen Holding A/S |
| Givaudan S.A. |
| Kalsec Inc. |
| GNT Group |
| Others |
Supply Flow & Price Mechanics
India's turmeric and annatto extraction clusters concentrate upstream supply, directing margin capture toward fermentation-platform operators who bypass agricultural yield cycles entirely. Natural colorant procurement cycles compress where FSSAI mandates accelerate reformulation, while synthetic portfolios face extended recertification timelines that lock foreign suppliers out of price-sensitive segments.
Pricing Analysis
Configured-to-order pricing for stabilized anthocyanin formulations commands 40-60% premiums over standard beetroot concentrates, with heat-stable microencapsulated variants capturing the widest spreads. Price differentiation hinges on certification tier (FSSAI-registered vs. EU organic) and volume scale, with multinational beverage contracts anchoring long-term offtake structures. Cost compression in commodity-grade synthetic dyes intensifies as REACH deadlines force distressed inventory liquidation. Regional processors in Gujarat exhibit highest price sensitivity; dairy multinationals in Germany show least.
Supply Chain Analysis
Tariff exposure between India and EU markets dominates supply chain risk calculus for natural colorant distributors. Geographic supply concentrates in India, China, and Brazil, with extraction capacity for carotenoids and betalains drawing from agricultural feedstocks vulnerable to monsoon disruption. Raw material dependencies center on grape skin concentrate, paprika oleoresin, and fermentation-derived beta-carotene. Single-source vulnerability persists for heat-stable microbial pigments where Chr. Hansen and select biotechnology firms control proprietary strains. Distribution runs through co-manufacturer networks and direct procurement platforms that disintermediate traditional regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation-derived colorants pose the central substitution threat to agricultural extraction incumbents, with batch consistency and year-round supply security eroding the traditional botanical sourcing moat. Incumbents must navigate this technology transition while defending margin positions in regulated markets.
For Market Incumbents: Insulate core beverage supply relationships through backward integration into fermentation platforms or exclusive microbial pigment licensing agreements. Anchor capacity in FSSAI-preapproved Indian extraction facilities to preempt domestic competitor lock-in. Defend against biotechnology entrants by securing long-term annatto and turmeric supply contracts with Gujarat and Maharashtra agricultural cooperatives before climate volatility disrupts harvest cycles. For New Entrants and Emerging Players: Pursue white-space opportunities in heat-stable natural formulations for ultra-high-temperature dairy applications, where synthetic alternatives face REACH-mandated elimination. Target Brazil's juice manufacturing corridor through ANVISA-registered annatto extraction partnerships with São Paulo industrial clusters. Establish go-to-market presence via direct B2B procurement platforms that bypass legacy distributor networks and capture technical service premiums. For Investors and Strategic Acquirers: Capital is best deployed toward fermentation-platform specialists with proprietary microbial strain libraries and existing EFSA safety dossiers, positioned for 5-10 year regulatory tailwinds as EU synthetic colorant bans cascade through global formulation standards. Watch for inflection signals in FSSAI organic certification timelines, where accelerated approval pathways for domestic biotechnology firms would signal structural advantage capture.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Platform Scale-Up | Chr. Hansen-style microbial pigment expertise achieves batch consistency that agricultural extraction cannot match. |
| Backward Integration into Extraction | Sensient Technologies' captive botanical sourcing insulates supply from climate-driven raw material volatility. |
| FSSAI Pre-Approval Investment | Domestic Indian registration accelerates market access ahead of 18-24 month foreign synthetic certification timelines. |
| Microencapsulation R&D Partnership | Heat-stable anthocyanin formulations open reformulation pathways into confectionery and extruded snack segments. |
| Direct Procurement Platform Launch | Digital B2B marketplaces collapse distributor margin layers and capture technical service premiums from multinational manufacturers. |
Methodological Framework
Desk research of FDA Color Additive Status List filings, EFSA scientific opinions, FSSAI additive approval registers, and customs trade data preceded structured interviews with beverage formulation directors, dairy procurement leads, natural colorant extraction plant managers, and microbial fermentation R&D heads. Primary intelligence combined with secondary validation across regulatory databases and industry association disclosures. Bottom-up volume modeling triangulated against top-down value estimates from ingredient supplier revenue disclosures.
Forecast assumptions held EFSA enforcement timelines and FSSAI certification protocols fixed while varying beverage reformulation velocity and microbial pigment adoption curves across the analysis window. Segmentation dimensions modeled include colorant type, application category, form factor, and end-user procurement sophistication. CAGRs derived from weighted average of historical volume trajectories and forward-looking procurement cycle analysis, with inputs from agricultural yield projections and fermentation capacity expansion announcements.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices, EU regulatory enforcement intensity, or India monsoon patterns would shift the trajectory. Forecasts reflect documented assumptions regarding synthetic colorant sunset dates and natural alternative technical performance thresholds. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Food Grade Menthol Crystal Market
Flavorings and Food Additives
Lecithin Oleoresin Market
Flavorings and Food Additives
Sour Flavor Ingredient Market
Flavorings and Food Additives
Orange Extract Market
Flavorings and Food Additives
Poria Cocos Extract Market
Flavorings and Food Additives
Synthetic Food Colors Market
Flavorings and Food Additives
Water-Soluble Flavors Market
Flavorings and Food Additives
Soy Sauce Powder Market
Flavorings and Food Additives
Edible Food Paints Market
Flavorings and Food Additives
Flavor Ingredients Market
Flavorings and Food Additives
Lemon Oil Market
Flavorings and Food Additives
Betanin Food Color Market
Flavorings and Food Additives
De Oiled Lecithin Market
Flavorings and Food Additives
Browning Solutions Market
Flavorings and Food Additives
South America Food Flavor and Enhancer Market
Flavorings and Food Additives
Keto Friendly Flavors Market