
 Oxygen Absorbers Market | 2026-2036
Oxygen Absorbers Market Size, Share, and Industry Trends Forecast 2026-2036
Oxygen Absorbers Market Analytics
Asset-light leasing models for oxygen scavenging equipment is reconfiguring how mid-sized food processors enter barrier packaging without heavy capital outlays. Mitsubishi Gas Chemical Company leverages its integrated iron powder supply chain to sustain cost leadership across Asia-Pacific pouch production. Clariant Inc. differentiates through zeolite-based formulations that navigate stringent pharmaceutical stability requirements in Europe. Multisorb Technologies Inc. specializes in canister formats for high-volume electronics shipments, anchoring its position in moisture-sensitive component logistics.
Oxygen absorbers are reactive materials—typically iron powder, activated carbon, or zeolite composites—engineered to remove dissolved or headspace oxygen through oxidation or adsorption, maintaining internal atmospheres below 0.1% residual O₂ to prevent spoilage, corrosion, or degradation. Iron powder formulations dominate food packaging applications due to their rapid reaction kinetics and low unit cost, while zeolite and activated carbon blends command premium positioning in pharmaceutical and electronics sectors where outgassing purity and non-magnetic properties matter. Pouch and sachet formats lead volume shipments given their compatibility with automated insertion equipment, though canister designs are capturing faster growth in electronics and diagnostic kit packaging where rigid geometry prevents compression damage. Material segmentation reveals margin concentration in clay-enhanced composites, where regional mineral sourcing creates supply moats for integrated producers.
FDA food contact substance notifications and EU REACH compliance obligations shape formulation chemistry and migration testing burdens for suppliers targeting transatlantic distribution. Japan's METI enforces JIS packaging standards that mandate oxygen transmission rate disclosures, creating a technical barrier that favors certified absorber manufacturers. China's SAMR implements GB standards for pre-packaged food labeling that indirectly drive absorber adoption by extending permissible shelf-life claims. Stakeholders must monitor evolving extended producer responsibility frameworks in Europe and North America, as packaging recyclability mandates will force material redesigns that preserve scavenger performance while eliminating multi-layer incompatibility with mechanical recycling streams.
Market Dynamics
The EU F-Gas Regulation and EU Green Deal are forcing oxygen absorber manufacturers to eliminate perfluorinated compounds from packaging laminates while maintaining sub-0.1% residual oxygen performance, compressing reformulation timelines and testing budgets across European supply chains.
Growth Catalysts
- Extended Producer Responsibility mandates:The EU Green Deal's packaging recyclability requirements are compelling food processors to adopt mono-material compatible absorbers, expanding addressable demand for clay-enhanced iron formulations that survive mechanical recycling streams without performance degradation.
- Pharmaceutical stability protocols:Zeolite-based oxygen scavengers are capturing share in diagnostic kit packaging where METI's JIS oxygen transmission rate disclosures create certification barriers that filter out commodity suppliers.
- Electronics logistics expansion:Canister-format absorbers are penetrating moisture-sensitive component shipments as semiconductor fabs in Taiwan and South Korea mandate vacuum-sealed barrier packaging for wafer transport.
Market Restraints
- Iron powder supply concentration:Captive production of reduced iron feedstock by integrated chemical conglomerates in Japan and China limits independent absorber manufacturers' negotiating leverage on input costs.
- Multi-layer incompatibility:Oxygen scavenger pouches embedded in metallized films create sorting contamination that violates EU mechanical recycling standards, forcing costly material redesigns.
- Zeolite mineral sourcing moats:Regional clay deposit control by producers in the United States and Turkey creates supply bottlenecks for pharmaceutical-grade formulations requiring specific cation exchange capacities.
Strategic Opportunities
- Asset-light equipment leasing:Mid-sized food processors in Germany are accessing barrier packaging capabilities through rental models for oxygen scavenging machinery, lowering capital barriers to premium shelf-life extension.
- Diagnostic kit convergence:Combination absorber-desiccant canisters are capturing share in point-of-care testing kits where humidity and oxygen control must coexist in rigid geometries preventing pouch compression.
- China's GB labeling standards:SAMR's pre-packaged food shelf-life disclosure rules are indirectly accelerating absorber adoption by legitimating extended freshness claims that require verified oxygen exclusion.
Industry Challenges
- Migration testing timelines:FDA food contact substance notifications and EU REACH compliance obligations impose 18-24 month certification cycles that delay product launches for reformulated scavenger chemistries.
- Legacy insertion equipment retrofitting:Automated packaging lines designed for standard pouch formats require mechanical modifications to handle rigid canister geometries, complicating electronics sector penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxygen Absorbers Market |
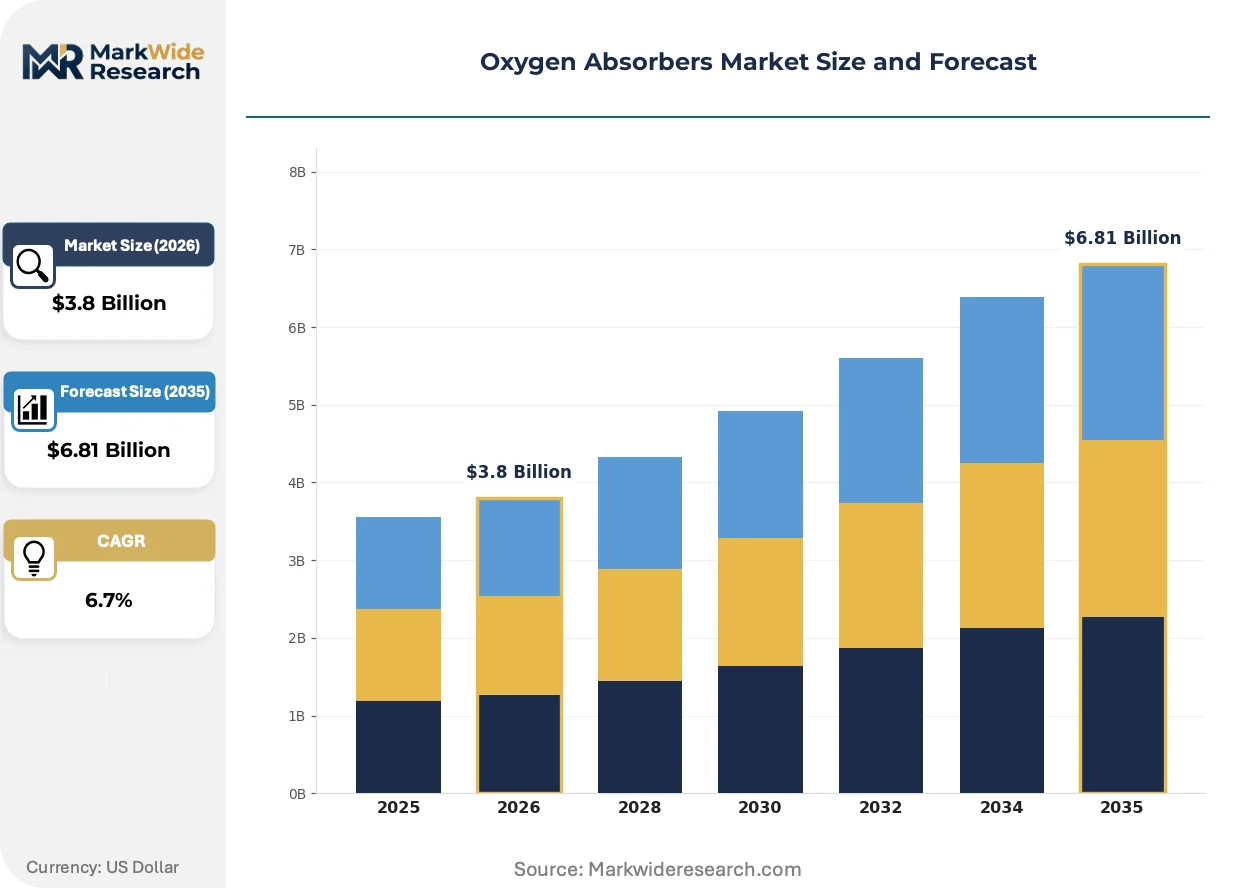
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pouches, sachets, bags, canisters Material: Iron powder, activated carbon, zeolites, clay Application: Food packaging, pharmaceuticals, electronics, textiles End User: Food manufacturers, pharmaceutical companies, electronics firms, retailers |
| Companies Covered | Clariant Inc., Eastman Chemical Company, Multisorb Technologies Inc., Kemira, Arkema, Mitsubishi Gas Chemical Company Inc., Ecolab Inc., Sealed Air Corporation, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxygen Absorbers Market Evolving Landscape
Active packaging chemistry is undergoing forced convergence with circular economy mandates, as scavenger performance requirements collide with mechanical recycling compatibility. Three developments are compressing traditional formulation approaches.
Non-magnetic zeolite composites are collapsing the historical trade-off between oxygen scavenging efficiency and electromagnetic compatibility in electronics packaging. Semiconductor logistics operators in South Korea and Taiwan are specifying these formulations for wafer cassette shipments where ferrous contamination risks device yield. The technology is collapsing price premiums previously commanded by activated carbon alternatives in high-value component transport.
REACH substance restriction proposals targeting intentionally added microplastics are forcing absorber manufacturers to eliminate synthetic polymer binders from iron powder formulations. European compounders are responding with starch-based and cellulose-derived matrix materials that maintain reaction kinetics while satisfying ECHA biodegradability screening criteria. Food contact applications in Germany and France face the steepest retesting burdens as existing notifications expire under the revised regulatory interpretation.
Leasing structures for oxygen scavenging equipment are displacing capital purchase models among mid-tier European food processors. Third-party service providers in Bavaria and Lombardy are bundling absorber supply with machine maintenance, converting fixed costs to variable per-unit charges. The model is compressing customer switching costs and concentrating procurement influence with equipment lessors who specify approved scavenger suppliers.
Oxygen Absorbers Market Segmentation
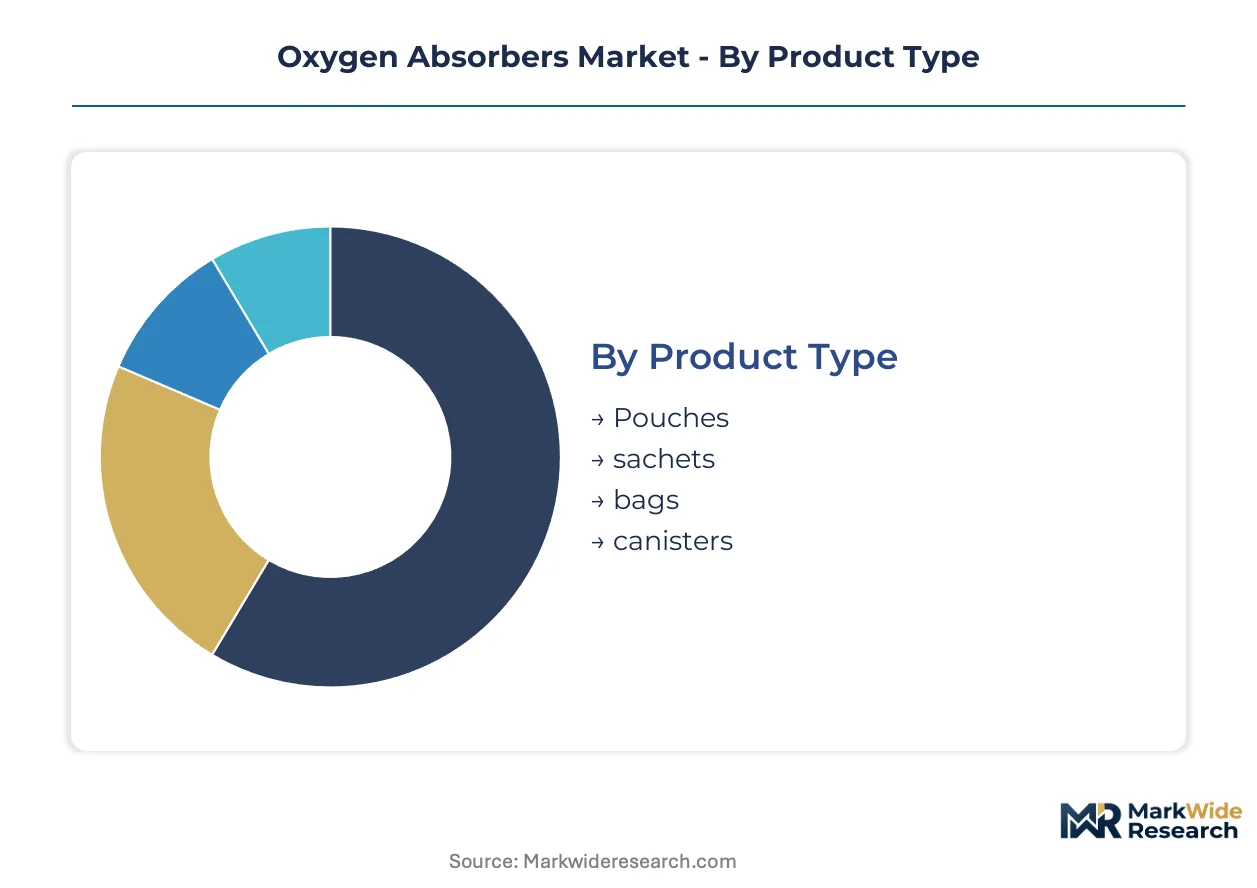
Oxygen absorber segmentation reveals how format chemistry and end-use requirements fragment procurement patterns across distinct performance tiers. Material composition and packaging geometry determine regulatory compliance pathways and insertion equipment compatibility.
Product Type:
Flexible and rigid formats serve divergent automation requirements and damage-sensitivity thresholds across end-use applications.
- Pouches:Laminated polymer constructions with iron powder cores dominate high-speed food packaging lines. German meat processors and Japanese snack manufacturers specify these for automated insertion at throughput rates exceeding 300 units per minute.
- Canisters:Rigid plastic or metal housings protect fragile electronics components from compression damage during vacuum-sealed shipment. Taiwan semiconductor fabs and South Korean display panel manufacturers mandate these for wafer cassette transport where pouch deformation risks yield loss.
- Sachets:Smaller flexible formats target single-serve pharmaceutical and diagnostic applications where precise unit dosing matters.
- Bags:Large-capacity formats serve bulk grain storage and industrial equipment preservation where extended protection duration exceeds standard pouch specifications.
Established volume favors pouches; emerging adoption favors canisters.
Material:
Cost structures and purity requirements stratify sourcing strategies across commodity and specialty feedstocks.
- Iron powder:Reduced iron formulations deliver rapid oxygen scavenging kinetics at lowest unit cost. Captive production by Japanese and Chinese chemical conglomerates constrains independent manufacturer margins through feedstock supply concentration.
- Zeolites:Synthetic aluminosilicate frameworks enable non-magnetic oxygen adsorption for electronics packaging where ferrous contamination threatens device performance. German pharmaceutical packagers specify these for diagnostic kit stability protocols under EMA guidelines.
- Activated carbon:Porous carbon structures combine moisture and oxygen control in dual-function applications.
- Clay:Regional mineral deposits in Turkey and the United States create supply moats for pharmaceutical-grade formulations requiring specific cation exchange capacities.
Iron powder commands current volume leadership; zeolite formulations are climbing the fastest on electronics sector specification.
Application:
Shelf-life extension mandates and component protection standards drive divergent performance specifications across consumer and industrial segments.
- Food packaging:Oxygen exclusion below 0.1% residual concentration prevents lipid oxidation and microbial spoilage in processed meats, baked goods, and coffee. EU Green Deal recyclability requirements are forcing mono-material compatible absorber redesigns.
- Pharmaceuticals:Stability protocols for diagnostic reagents and active pharmaceutical ingredients demand verified oxygen transmission rate performance. Japan's METI JIS standards create certification barriers filtering commodity suppliers.
- Electronics:Moisture-sensitive semiconductor components require vacuum-sealed barrier packaging with non-outgassing scavenger chemistry.
- Textiles:Preservation of natural fiber shipments and archival storage applications represent niche demand with specialized duration requirements.
Food packaging anchors current procurement volume; electronics logistics is gaining share fastest on semiconductor supply chain expansion.
End User:
Scale and integration level determine whether procurement favors spot purchasing or captive formulation development.
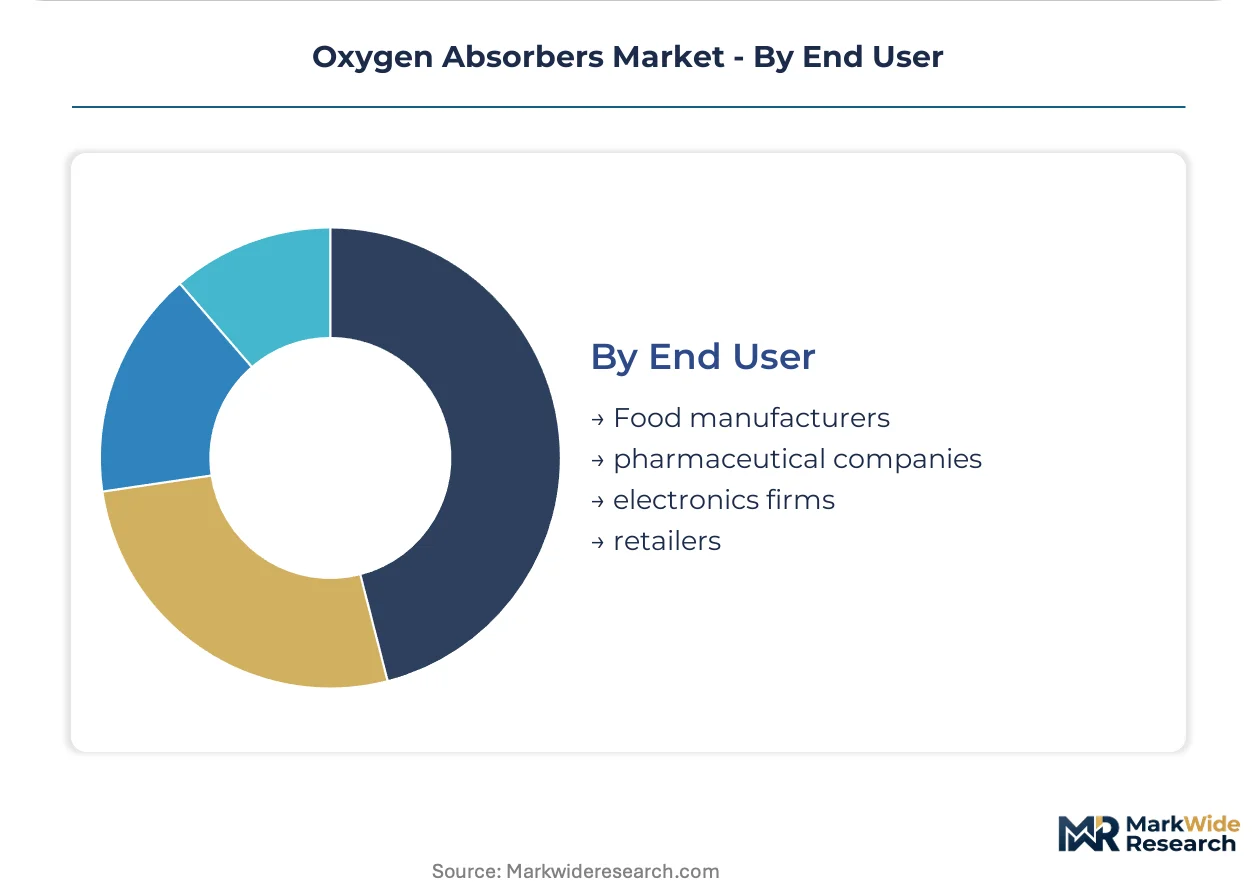
- Food manufacturers:Mid-sized European processors are accessing barrier packaging through asset-light equipment leasing models that bundle absorber supply with machine maintenance.
- Pharmaceutical companies:Stability testing burdens and FDA food contact substance notification timelines concentrate procurement with certified suppliers capable of 18-24 month compliance documentation.
- Electronics firms:Semiconductor fabs in Taiwan and South Korea specify canister formats with electromagnetic compatibility verification.
- Retailers:Private-label shelf-life claims under China's SAMR GB labeling standards indirectly accelerate absorber adoption for extended freshness positioning.
Food manufacturers represent the largest addressable base; pharmaceutical companies command premium pricing through compliance complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in oxygen absorbers track the geographic concentration of precision manufacturing and processed food exports. Import dependency characterizes markets lacking integrated iron powder or zeolite feedstock capacity.
United States
Pharmaceutical packaging demand from diagnostic kit manufacturers drives premium zeolite absorber imports. EPA and FDA food contact substance notifications govern formulation chemistry for domestic distribution. Clay mineral deposits in the southeastern states supply regional pharmaceutical-grade formulation producers with cation exchange capacity requirements.
Germany
Precision meat processing and pharmaceutical packaging standards sustain demand for certified mono-material compatible absorbers. EU F-Gas Regulation and Green Deal recyclability mandates force reformulation of embedded scavenger laminates. Bavarian food processors access barrier packaging through equipment leasing models that bundle absorber supply with machine maintenance.
China
SAMR GB labeling standards for pre-packaged food shelf-life claims indirectly accelerate absorber adoption for extended freshness positioning. Captive iron powder production by integrated chemical conglomerates constrains independent manufacturer feedstock access. Yangtze River Delta electronics fabs specify canister formats for semiconductor wafer cassette transport.
Japan
METI JIS packaging standards mandate oxygen transmission rate disclosures that filter commodity suppliers from pharmaceutical and diagnostic applications. Mitsubishi Gas Chemical Company leverages integrated iron powder supply chains for cost leadership across Asia-Pacific pouch production. Kanto region precision food manufacturers specify rapid-kinetics iron formulations for automated insertion lines.
South Korea
Semiconductor logistics operators mandate vacuum-sealed barrier packaging with non-magnetic zeolite composites for wafer shipments. National industrial policy supports domestic absorber formulation capacity for electronics sector self-sufficiency. Busan-Ulsan cluster display panel manufacturers drive canister-format specification for moisture-sensitive component protection.
Oxygen Absorbers Market Competitive Landscape
On the supply side, the industry is consolidating around integrated chemical conglomerates with captive iron powder capacity and specialized compounders serving pharmaceutical and electronics niches. Three archetypes dominate: integrated feedstock producers controlling reduced iron supply chains, formulation specialists navigating FDA and EMA compliance burdens, and equipment-integrated service providers converting fixed costs to variable per-unit charges. Competitive moves concentrate on backward integration into mineral sourcing and strategic partnerships with automated packaging equipment manufacturers.
Among diversified chemical conglomerates, BASF SE and Eastman Chemical Company occupy positions spanning multiple active packaging chemistries beyond oxygen scavenging. Mitsubishi Gas Chemical Company exemplifies the integrated feedstock archetype through its captive iron powder production. Clariant Inc. and Multisorb Technologies Inc. represent formulation specialists targeting pharmaceutical stability protocols and electronics logistics respectively, with geographic footprints anchored in European and North American regulatory jurisdictions.
| Leading Market Players |
|---|
| Clariant Inc. |
| Eastman Chemical Company |
| Multisorb Technologies Inc. |
| Kemira |
| Arkema |
| Mitsubishi Gas Chemical Company Inc. |
| Ecolab Inc. |
| Sealed Air Corporation |
| BASF SE |
| Others |
Value Network & Pricing Analysis
Overcapacity in Asia-Pacific iron powder production is compressing feedstock margins and forcing integrated suppliers toward longer-term offtake contracts with European and North American compounders, reshaping how pricing power distributes across the value chain.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure that stratifies across pharmaceutical-grade certification tiers, food-contact FDA notification status, and electronics-sector electromagnetic compatibility verification. Price differentiation hinges on REACH compliance documentation burden and volume scale, with mid-sized German food processors capturing softer terms through bundled equipment leasing. Cost compression in standard iron powder formulations is intensifying because Japanese and Chinese conglomerates leverage captive feedstock supply; pharmaceutical and electronics buyers show least price sensitivity due to stability protocol mandates.
Supply Chain Analysis
Extended payment terms from Japanese chemical conglomerates to independent compounders are tightening working capital constraints across European formulation specialists. Captive iron powder production concentrates in Japan and China, while pharmaceutical-grade zeolite sourcing draws from Turkish and United States clay deposits. The chain rests on reduced iron feedstock, synthetic aluminosilicate frameworks, and starch-based polymer binders. Single-source vulnerability from METI JIS certification concentration creates procurement bottlenecks for diagnostic kit manufacturers. Distribution runs through automated packaging equipment lessors who specify approved scavenger suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward mid-sized food processors in Germany and Lombardy as equipment leasing models consolidate procurement influence with third-party service providers, fragmenting direct supplier relationships.
For Market Incumbents: Harden backward integration into regional clay deposits to secure cation exchange capacity for pharmaceutical-grade zeolite formulations against Turkish mineral sourcing moats. Deepen channel control through strategic partnerships with automated packaging equipment manufacturers in Bavaria, converting leasing relationships into captive supply agreements that lock out commodity competitors. For New Entrants and Emerging Players: Establish a beachhead in mono-material compatible absorber formulations for EU Green Deal compliance, where incumbent redesign timelines create temporary supply gaps. Target South Korean semiconductor logistics operators specifying non-magnetic zeolite composites for wafer cassette transport, using electromagnetic compatibility certification as the go-to-market wedge against iron powder incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because FDA and EMA stability documentation burdens concentrate procurement with certified compounders capable of 18-24 month notification cycles. Acquisition candidates include formulation specialists with existing pharmaceutical client relationships and in-house migration testing infrastructure. Watch for REACH substance restriction proposals targeting intentionally added microplastics as the signal forcing binder chemistry redesigns and creating replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Sourcing | Captive clay deposit control in Turkey neutralizes pharmaceutical-grade zeolite supply bottlenecks. |
| Green Manufacturing Transition | Starch-based binder formulations satisfy ECHA biodegradability screening while maintaining iron powder reaction kinetics. |
| Long-term Supply Agreement | Offtake contracts with Yangtze River Delta electronics fabs secure canister-format volume commitments. |
| Joint Venture | Partnerships with Bavarian equipment lessors convert fixed scavenger costs to variable per-unit charges. |
| Regulatory Certification Investment | FDA food contact substance notifications and METI JIS compliance create 18-24 month barriers filtering commodity entrants. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers at iron powder production facilities, procurement leads at German meat processing OEMs, pharmaceutical packaging engineers, and electronics logistics operators; alongside secondary validation through customs and trade data, SEC 10-K filings of diversified chemical conglomerates, and ECHA REACH substance restriction proposals. Bottom-up triangulation across material composition, format geometry, and end-use application segments was cross-checked against top-down market sizing from regional production hub analysis.
Forecast inputs considered iron powder kinetics degradation curves, zeolite cation exchange capacity specifications, and regulatory compliance timeline distributions across the projection horizon. Segmentation dimensions modeled include material chemistry tier, packaging format rigidity, end-use industry stability protocol, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity utilization trends, with specific weighting for EU F-Gas Regulation reformulation deadlines and SAMR GB labeling standard enforcement trajectories.
Stress conditions across iron powder feedstock pricing volatility, REACH substance restriction implementation speed, and semiconductor fab capacity expansion rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory interpretation stability and substitution elasticity between scavenger chemistries. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Global Lutein and Lutein Esters Market
Food Additives and Ingredients
Olestra Market
Food Additives and Ingredients
Global Edible Films and Coatings for Fruits and Vegetables Market
Food Additives and Ingredients
Spain Food Enzymes Market
Food Additives and Ingredients
Food Grade Phosphates Market
Food Additives and Ingredients
Australia Food Emulsifiers Market
Food Additives and Ingredients
Carob Gum Market
Food Additives and Ingredients
Antimicrobial Packaging Ingredients for Food Packaging Market
Food Additives and Ingredients
Cream Emulsifier Market
Food Additives and Ingredients
Japan Food Preservatives Market
Food Additives and Ingredients
France Food Additives Market
Food Additives and Ingredients
Casamino Acids Market
Food Additives and Ingredients
Western Europe Food Phosphate Market
Food Additives and Ingredients
Beverage Acidulants Market
Food Additives and Ingredients
United Kingdom Food Colorants Market
Food Additives and Ingredients
Bakery Release Agents Market