
 Natural Food Color Ingredients Market | 2026-2036
Natural Food Color Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Food Color Ingredients Market Foresight
Beverage and confectionery procurement is shifting toward anthocyanin and carotenoid-based systems as CPG brands purge synthetic azo dyes from ingredient decks. Sensient Technologies Corporation leverages captive extraction capabilities across multiple botanical supply chains. Archer Daniels Midland Company anchors North American grain and legume-derived colorant production through integrated agricultural sourcing. Givaudan S.A. competes on flavor-color synergy platforms that bundle taste modulation with visual performance.
Natural food color ingredients comprise pigments extracted from fruits, vegetables, herbs, and microalgae through aqueous, solvent, or supercritical CO2 processes, standardized for light stability, pH tolerance, and thermal degradation thresholds to replace certified synthetic dyes in packaged foods. Spirulina-derived phycocyanin dominates liquid applications in dairy alternatives and sports beverages where blue hue claims support protein positioning. Beetroot and annatto powders command premium placement in clean-label meat analogues and plant-based cheese, while turmeric oleoresin faces margin compression from volatile Indian rhizome pricing and competing curcumin nutraceutical offtake.
Regulators in the United States enforce FDA color additive petitions and GRAS self-affirmation pathways that delay novel botanical approvals by months. The European Food Safety Authority applies EFSA-led re-evaluations of existing colorants and enforces EU Green Deal-linked Farm to Fork pesticide residue limits that constrain extract purity. Stakeholders must monitor how microbiome and allergen labeling expansions in Germany and France reshape acceptable source declarations and extraction method transparency before committing to multi-year supply agreements.
Market Dynamics
EU Green Deal mandates and REACH synthetic dye restrictions are forcing CPG brands to redirect formulation budgets toward botanical extraction, compressing approval timelines and reshaping supplier qualification criteria across beverage and confectionery supply chains.
Growth Catalysts
- EU Farm to Fork pesticide residue limits:These EFSA-enforced thresholds accelerate botanical colorant R&D as manufacturers seek compliant extract sources. Dairy alternative brands in Germany and France now prioritize spirulina-derived phycocyanin for blue hue positioning.
- Clean-label confectionery procurement:Beetroot and anthocyanin systems displace azo dyes in premium chocolate and gummy segments. Brazilian and Indian regional manufacturers are reformulating portfolios to capture export eligibility.
- Supercritical CO2 extraction:This solvent-free process improves carotenoid stability in thermal applications. Meat analogue producers leverage the technology for annatto and turmeric oleoresin standardization.
Market Restraints
- Indian rhizome price volatility:Turmeric oleoresin faces margin compression from competing curcumin nutraceutical offtake and monsoon-dependent harvest yields. Extractors struggle to lock annual supply contracts.
- FDA GRAS self-affirmation delays:Novel botanical approvals stretch across months as petition documentation requirements expand. Startups lack capital to navigate parallel FDA and state-level compliance.
- Light stability limitations:Anthocyanin degradation in transparent beverage packaging constrains shelf-life claims. Brands must invest in secondary barrier films or accept shortened distribution windows.
Strategic Opportunities
- Brazilian Amazon fruit extraction:Açaí and camu camu pigment streams remain underdeveloped for food-grade applications. Local cooperatives seek technical partnerships to scale aqueous extraction capacity.
- Flavor-color synergy platforms:Bundled taste modulation with visual performance creates premium positioning. Givaudan and similar integrators capture reformulation budgets from standalone colorant suppliers.
- Microbiome labeling expansions:German and French regulators now mandate extraction method transparency. Early adopters of enzymatic versus solvent processes gain retail placement advantages.
Industry Challenges
- Phycocyanin purification talent scarcity:Microalgae processing requires specialized bioprocess engineers. Universities in producing regions lack dedicated food-grade extraction curricula.
- Multi-jurisdiction certification timelines:Simultaneous EU organic, USDA organic, and FSSAI natural claims demand redundant documentation. Brands delay launch schedules to accumulate stacked certifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Food Color Ingredients Market |
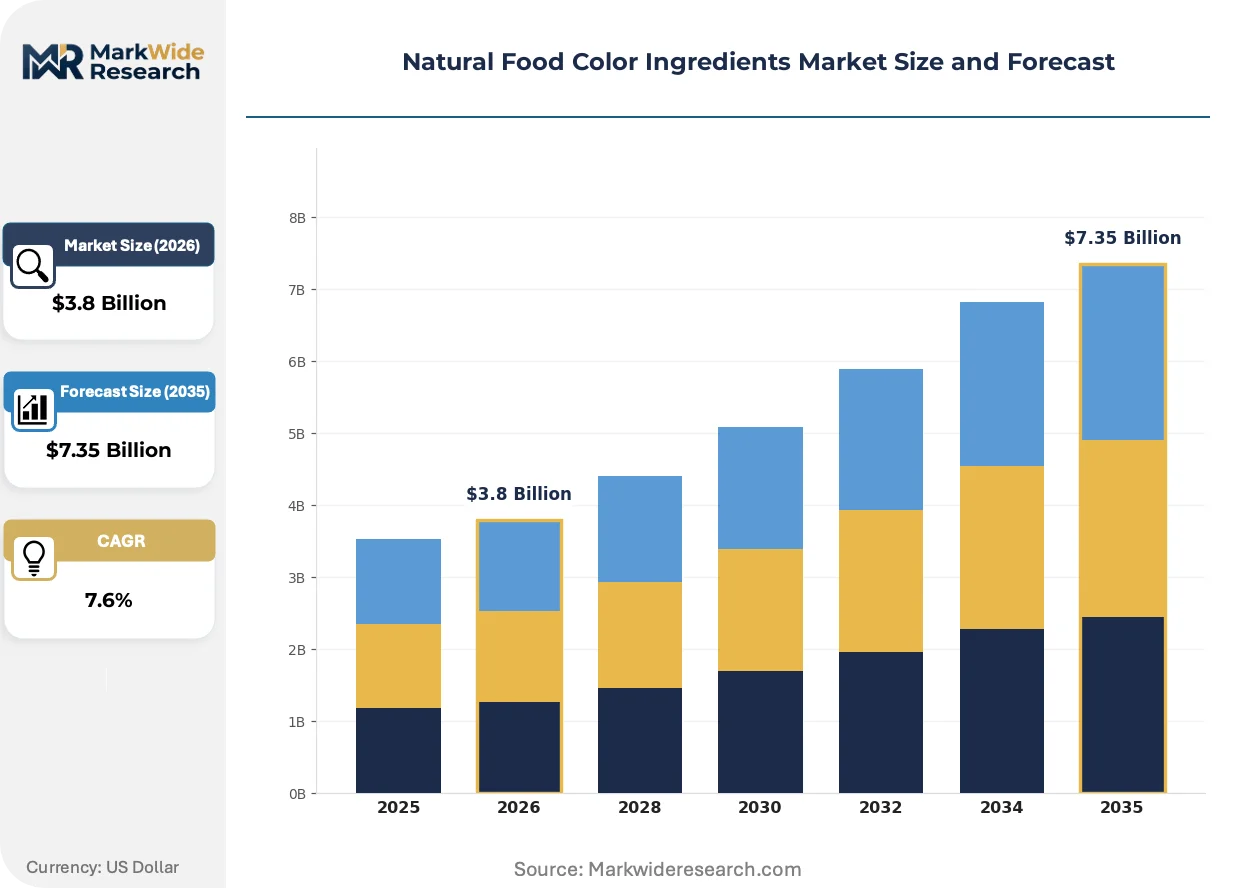
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Annatto, Beetroot, Turmeric, Spirulina Application: Confectionery, Beverages, Dairy, Meat Products Form: Liquid, Powder, Granules, Paste Source: Fruits, Vegetables, Herbs, Others |
| Companies Covered | Sensient Technologies Corporation, Archer Daniels Midland Company, Givaudan S.A., Döhler GmbH, GNT Group B.V., Oterra A/S, International Flavors & Fragrances Inc., Kalsec Inc., DDW The Color House, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Food Color Ingredients Market Shifts & Advancements
Extraction technology convergence and regulatory disclosure mandates are compressing traditional supply relationships while opening novel partnership models between agricultural cooperatives and finished goods manufacturers.
Supercritical CO2 extraction is overtaking solvent-based methods for heat-sensitive carotenoid recovery. Premium beverage manufacturers in Germany and California now specify CO2-derived lycopene and beta-carotene in procurement tenders. The technology enables cleaner label declarations while reducing thermal degradation losses that previously limited natural colorant adoption in UHT dairy applications.
REACH authorization requirements for synthetic azo dyes are tightening batch-by-batch disclosure obligations. ECHA enforcement actions against non-compliant imports redirect European formulation budgets toward EFSA-positively-listed botanical sources. Confectionery exporters to the EU now pre-qualify Indian and Brazilian extract suppliers against evolving substance restriction candidate lists.
Direct agricultural contracting is replacing spot-market pigment purchasing among mid-scale CPG brands. Sourcing managers now embed sustainability auditors within cooperative operations in Karnataka and Minas Gerais. This behavioral shift concentrates procurement volume with vertically integrated extractors who control cultivation through captive agricultural partnerships rather than merchant trading relationships.
Natural Food Color Ingredients Market Segmentation
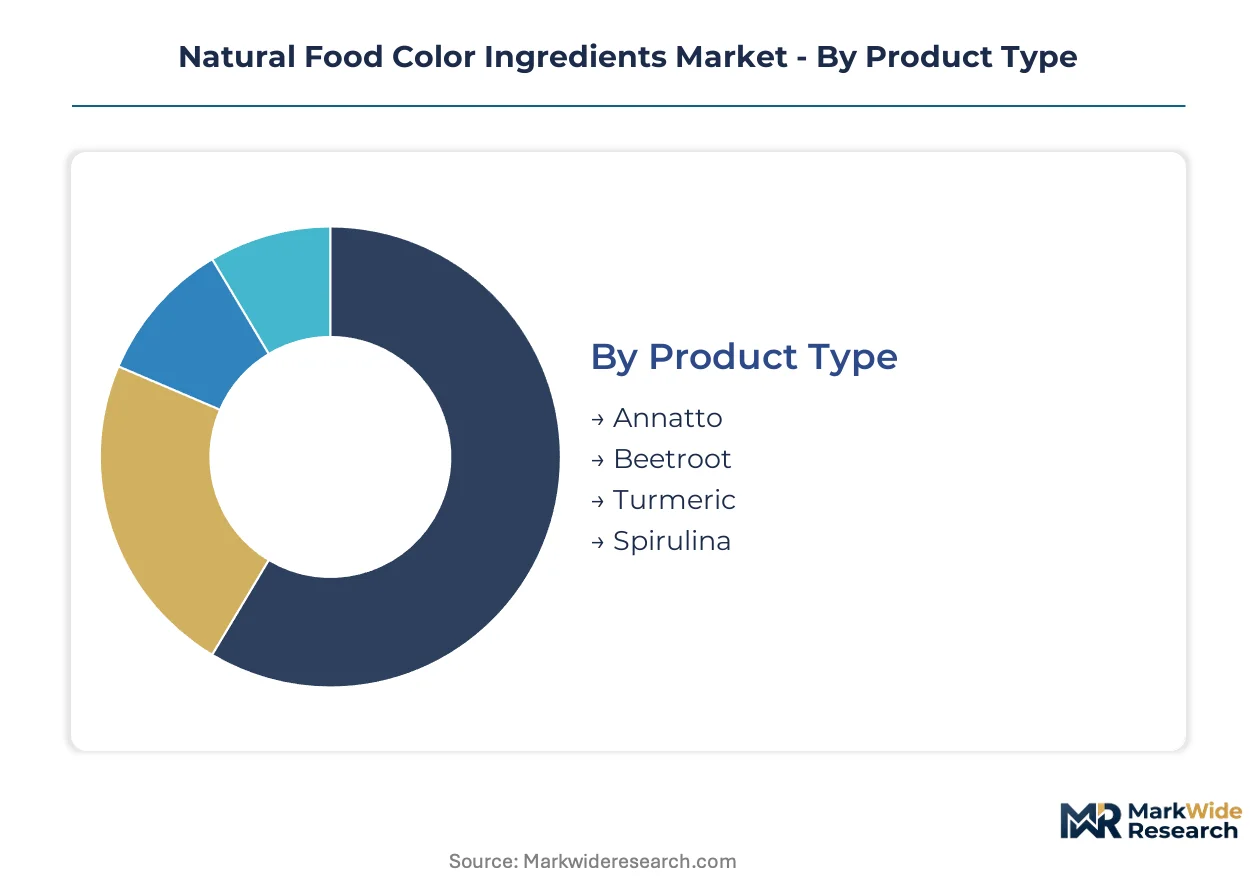
Natural food color procurement splits along stability requirements and clean-label positioning. Buyers prioritize light-fastness in transparent packaging or pH tolerance in thermal processing depending on end-use specifications.
Product Type:
Cost tier separates commodity botanicals from microalgae-derived premium streams requiring bioprocess expertise.
- Annatto:Carotenoid-rich seed extracts deliver yellow-orange hues with superior heat stability. Meat analogue producers in Germany and Brazil specify annatto oleoresin for plant-based burger coloration amid clean-label reformulation mandates.
- Spirulina:Phycocyanin protein-pigment complexes provide rare blue coloration without synthetic alternatives. Sports beverage brands in California and dairy alternative manufacturers capture protein-positioning claims through spirulina-derived liquid systems.
- Beetroot:Betalain pigments from red beet offer pH-sensitive pink-to-red coloration for confectionery applications.
- Turmeric:Curcumin oleoresin from Indian rhizomes faces supply competition from nutraceutical offtake and monsoon-dependent harvest variability.
Volume sits with annatto; growth tilts toward spirulina.
Application:
Application maturity determines whether brands accept shortened shelf-life or invest in barrier packaging for natural colorant migration.
- Confectionery:Gummy and chocolate segments displace synthetic azo dyes with beetroot and anthocyanin systems. Premium brands in France and Germany now mandate EFSA-compliant botanical extracts to maintain EU export eligibility under REACH restrictions.
- Beverages:Transparent bottled drinks concentrate demand for light-stable carotenoid and anthocyanin formulations. German and California procurement teams specify supercritical CO2-derived lycopene to reduce thermal degradation in UHT processing.
- Dairy:Yogurt and cheese applications leverage annatto and turmeric for yellow hue standardization across fat-content variations.
- Meat Products:Plant-based analogue producers require color stability through freeze-thaw cycles and cooking temperatures.
Confectionery commands procurement volume; beverages expand most quickly on clean-label positioning.
Form:
Customer type separates industrial-scale manufacturers seeking handling efficiency from artisanal producers prioritizing dissolution control.
- Liquid:Standardized aqueous or oil-dispersed formats enable automated dosing in high-speed bottling lines. Beverage manufacturers in Germany and California specify liquid spirulina and beta-carotene for batch consistency.
- Powder:Spray-dried or freeze-dried formats offer extended shelf-life and reduced shipping costs for regional distribution.
- Granules:Agglomerated particles improve flowability in confectionery dry-mix applications.
- Paste:High-concentration semi-solid formats suit artisanal meat processing and small-batch dairy operations.
Liquid dominates industrial procurement; powder gains share fastest in emerging market regional manufacturing.
Source:
Supply concentration shapes extraction method transparency requirements under expanding microbiome labeling mandates.
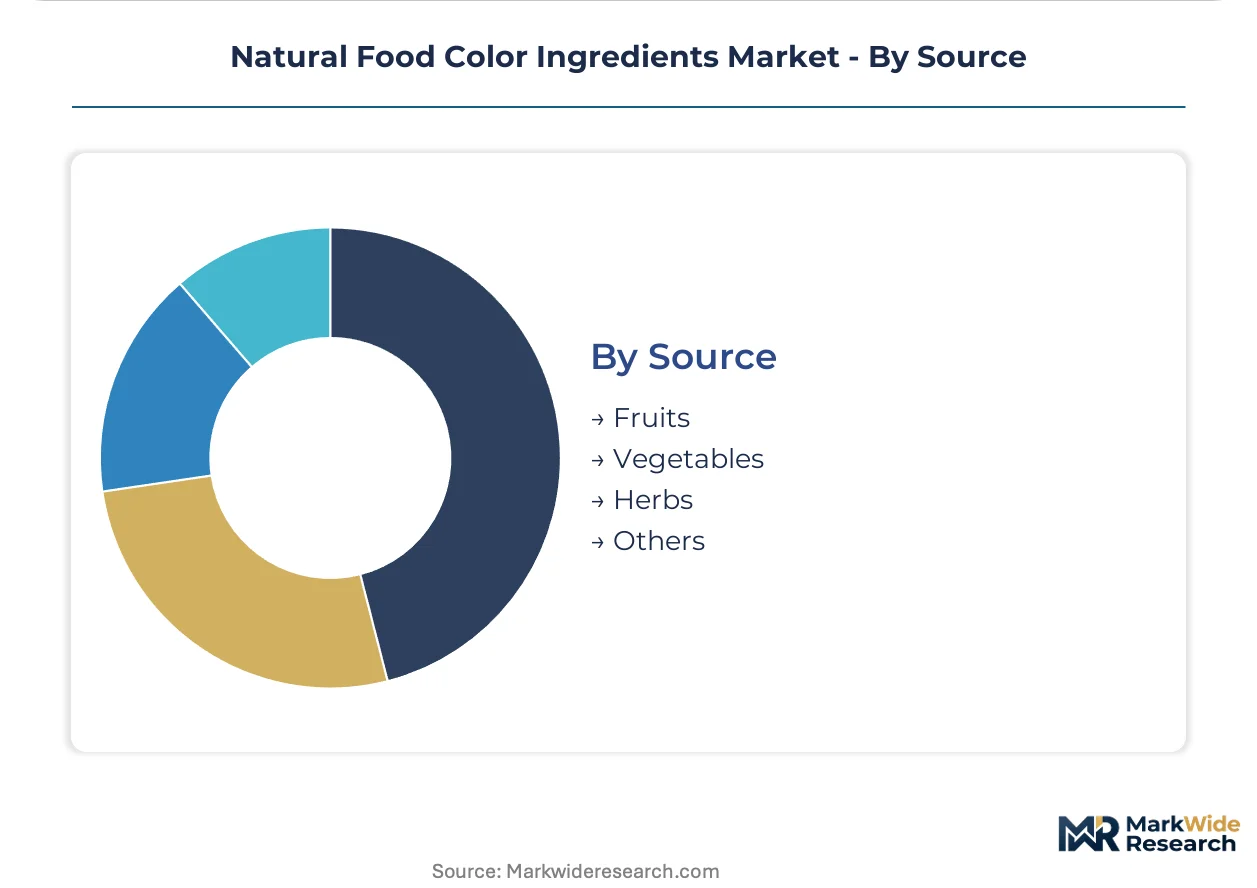
- Fruits:Anthocyanin streams from grape, elderberry, and blackcurrant provide pH-dependent red-to-purple coloration. German and French regulators now mandate extraction method disclosure for fruit-derived colorants entering retail distribution.
- Vegetables:Beetroot and red cabbage concentrates serve as the backbone of clean-label red coloration in meat analogues and confectionery.
- Herbs:Turmeric, paprika, and saffron deliver oleoresin-based yellow-orange systems with flavor-color synergy potential.
- Others:Microalgae and insect-derived pigments occupy niche positions pending regulatory approval expansion.
Vegetables anchor supply volume; fruits climb the fastest on beverage clean-label conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Karnataka and Minas Gerais are driving extraction facility concentration. Tax incentives for agro-processing operations redirect investment toward captive botanical supply chains. Regional procurement patterns now favor vertically integrated extractors over merchant traders.
Germany
Clean-label confectionery brands in Bavaria and Baden-Württemberg accelerate spirulina procurement for protein-positioned dairy alternatives. EFSA-enforced EU Green Deal pesticide residue limits constrain extract purity standards. The ECHA REACH framework tightens synthetic azo dye batch disclosure, redirecting formulation budgets toward EFSA-positively-listed botanical sources in Cologne and Hamburg industrial clusters.
United States
California beverage manufacturers specify supercritical CO2-derived carotenoids for UHT thermal stability. FDA GRAS self-affirmation pathways delay novel botanical approvals by months, compressing startup launch timelines. Procurement teams in Greater Los Angeles and San Francisco Bay Area now embed sustainability auditors within cooperative operations to secure multi-year supply agreements.
India
Turmeric oleoresin extractors in Karnataka and Andhra Pradesh face margin compression from competing curcumin nutraceutical offtake. FSSAI natural claims and organic certification requirements demand redundant documentation for export eligibility. The PLI scheme for food processing incentivizes aqueous extraction capacity expansion in Maharashtra and Gujarat industrial corridors.
Brazil
Regional manufacturers in São Paulo and Minas Gerais reformulate portfolios to capture EU export eligibility under REACH restrictions. ANVISA alignment with EFSA substance restriction candidate lists pre-qualifies extract suppliers. Açaí and camu camu pigment streams in Amazonas cooperatives seek technical partnerships to scale food-grade aqueous extraction for annatto and beetroot applications.
France
Microbiome labeling mandates from ANSM and DGCCRF now require extraction method transparency for fruit-derived colorants entering retail distribution. Premium chocolate brands in Île-de-France mandate EFSA-compliant anthocyanin systems to maintain clean-label positioning. The Farm to Fork pesticide residue limits accelerate botanical R&D investment in Lyon and Strasbourg formulation centers.
Natural Food Color Ingredients Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with captive extraction capabilities commanding premium placement in beverage and confectionery supply chains. Market structure tilts toward integrated agricultural sourcing rather than merchant trading relationships. Three archetypes dominate: multi-national flavor houses bundling taste-color synergy, regional extractors with captive cultivation partnerships, and technology licensors specializing in supercritical CO2 purification. Competitive moves concentrate on backward integration into botanical supply chains and strategic partnerships with Amazon basin cooperatives.
Within the integrated extraction tier, Sensient Technologies Corporation, Archer Daniels Midland Company, and Givaudan S.A. exemplify divergent positioning strategies. Sensient anchors North American procurement through captive supply chain control across multiple botanical sources. Archer Daniels Midland occupies a position centered on grain and legume-derived colorant production through upstream agricultural partnerships. Givaudan sits within the flavor-color convergence space, representing bundled taste modulation with visual performance to capture reformulation budgets from standalone colorant suppliers.
| Leading Market Players |
|---|
| Sensient Technologies Corporation |
| Archer Daniels Midland Company |
| Givaudan S.A. |
| Döhler GmbH |
| GNT Group B.V. |
| Oterra A/S |
| International Flavors & Fragrances Inc. |
| Kalsec Inc. |
| DDW The Color House |
| Others |
Supply & Pricing Matrix
Clean-label confectionery procurement in Germany and France now mandates EFSA-compliant botanical extracts, forcing extractors to absorb certification costs and pass through premiums for compliant spirulina and beetroot streams.
Pricing Analysis
Short lead-time premiums now apply to spirulina-derived phycocyanin as dairy alternative brands in California and Germany compress procurement cycles. Three-tier pricing structure across premium, standard, and economy levels separates CO2-extracted carotenoids from solvent-based alternatives and commodity annatto powders. Pricing pressure stems from Indian turmeric oleoresin volatility as nutraceutical offtake competes for rhizome supply. Regional manufacturers in Brazil and India exhibit highest price sensitivity, while premium beverage brands in Germany accept stability-tested premiums.
Supply Chain Analysis
Single-source vulnerability sits with Indian turmeric oleoresin as monsoon-dependent harvests and competing curcumin demand constrain supply security. Raw material flows draw from Karnataka rhizome cooperatives, Minas Gerais annatto cultivation, and California spirulina bioreactors. Distribution runs through vertically integrated extractors with captive agricultural partnerships rather than merchant traders. Tariff exposure looms as EFSA pesticide residue enforcement tightens on Indian and Brazilian imports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where EU Green Deal and REACH synthetic dye restrictions erect regulatory moats favoring extractors with stacked organic certifications and documented supply chain transparency.
For Market Incumbents: Cement backward integration into Amazon basin açaí and camu camu cooperatives before technical partnerships lock in competitor access. Expand supercritical CO2 capacity in Germany and California to capture premium beverage procurement tenders. Defensive priority rests on pre-empting flavor-color synergy bundling by integrated houses through standalone stability-testing capabilities. For New Entrants and Emerging Players: Artisanal meat processors in France and artisanal dairy operations in California present the most penetrable entry points given their tolerance for paste formats and smaller batch scales. White-space targets include enzymatic extraction method transparency claims for microbiome labeling compliance and underdeveloped Brazilian Amazon fruit pigment streams. Go-to-market positioning should emphasize extraction method disclosure advantages over incumbent solvent-based suppliers. For Investors and Strategic Acquirers: Re-rating potential sits with regional extractors holding captive cultivation partnerships in Karnataka and Minas Gerais given accelerating direct agricultural contracting trends. Long-term viability over the coming decade hinges on EFSA-positively-listed botanical portfolios rather than novel ingredient pipelines. Signal to monitor: ANVISA alignment velocity with EFSA substance restriction candidate lists as a predictor of Brazilian supplier pre-qualification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation Partnerships | Captive supply of Karnataka turmeric and Minas Gerais annatto secures margin control against spot volatility. |
| Supercritical CO2 Capacity Expansion | German and California beverage tenders now specify solvent-free carotenoid extraction for clean-label claims. |
| Flavor-Color Synergy Platform Development | Bundled taste modulation captures reformulation budgets from standalone colorant suppliers in confectionery. |
| EFSA Compliance Documentation Investment | Stacked organic and residue-limit certifications open EU export eligibility under REACH restrictions. |
| Amazon Cooperative Technical Partnership | Açaí and camu camu pigment streams remain underdeveloped for food-grade aqueous extraction scale-up. |
Research Methodology
Multi-period observation of EFSA re-evaluation timelines, REACH authorization batch disclosures, and FSSAI certification backlogs anchored the trend analysis, supplemented by interviews with extraction facility operators in Karnataka and Minas Gerais, procurement managers at German confectionery brands, California beverage formulators, and regulatory affairs specialists navigating GRAS self-affirmation pathways. Secondary validation drew from ECHA enforcement action records, EU Farm to Fork pesticide residue databases, FDA color additive petition filings, and Indian PLI scheme disbursement reports. Bottom-up volume estimates from individual extractor capacity and top-down demand calibration from CPG reformulation announcements were triangulated.
Segment-weighting across product type, application, form, and source dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from slope-consistency checks against historical price-volume elasticities in turmeric oleoresin and spirulina phycocyanin markets. Industry-specific inputs included monsoon yield correlation models for Indian rhizome supply and supercritical CO2 adoption curves in German beverage manufacturing.
Caveats apply where FDA GRAS petition delays, EFSA substance re-evaluation outcomes, or Indian harvest variability could materially shift the outlook. Forecasts assume sustained EU Green Deal enforcement trajectory and stable ANVISA-EFSA alignment pace. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Argentina Food Preservatives Market
Food Additives and Ingredients
North America Anti-Caking Market
Food Additives and Ingredients
Food Emulsifiers Market
Food Additives and Ingredients
Beverage Acidulants Market
Food Additives and Ingredients
Japan Food Acidulants Market
Food Additives and Ingredients
Food and Beverage Sterilizing Agent Market
Food Additives and Ingredients
Canada Food Additives Market
Food Additives and Ingredients
Europe Feed Anti-Caking Agents Market
Food Additives and Ingredients
China Food Additives Market
Food Additives and Ingredients
Agar Agar Gum Market
Food Additives and Ingredients
Sri Lanka Starch and Starch Derivative Market
Food Additives and Ingredients
Casamino Acids Market
Food Additives and Ingredients
Food Texturing Agents Market
Food Additives and Ingredients
Argentina Gellan Gum Market
Food Additives and Ingredients
Global Yeast and Yeast Ingredients Market
Food Additives and Ingredients
India Food Additives Market