
 Australia Digital Twin Market | 2026-2036
Australia Digital Twin Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Digital Twin Market Insights
Australian industrial software providers is pivoting toward cloud-native twin architectures for resource-heavy sectors. Siemens leverages deep energy sector expertise to anchor utility-scale digital twin deployments across the National Electricity Market. ANSYS sustains competitive intensity through physics-based simulation engines that dominate aerospace and defense validation workflows. Bosch competes on sensor-to-cloud integration, extending its IoT hardware footprint into predictive maintenance contracts for Queensland mining infrastructure.
A digital twin constitutes a dynamic virtual representation of a physical asset, system, or process, sustained through real-time data feeds from IoT sensors, SCADA networks, and enterprise systems to mirror operational states, stress distributions, and performance degradation. The construct enables scenario modeling, predictive intervention, and lifecycle optimization across capital-intensive industries. Manufacturing applications command the deepest deployment maturity, with automotive and smart cities segments representing the fastest expansion vectors as precinct-scale simulation gains traction in urban planning mandates. Healthcare twins remain nascent in Australia, though margin pools concentrate in implementation and consulting services where systems integrators bridge legacy hospital infrastructure with modern AI inference layers.
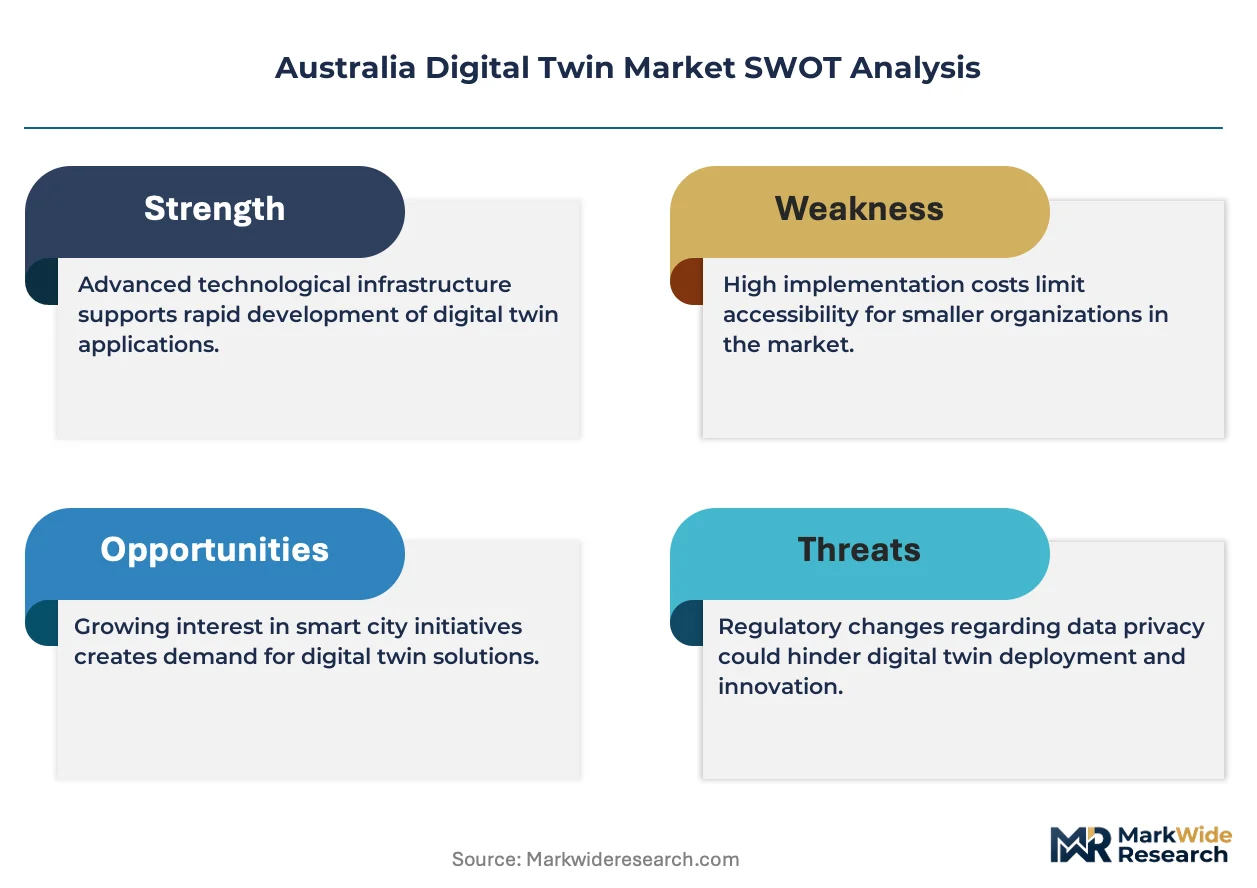
TGA standards for software-as-medical-device and the Australian Cyber Security Centre's Essential Eight framework shape product certification pathways and data governance requirements for twin platforms handling critical infrastructure. The Australian Energy Market Operator's integrated system plan and CSIRO's digital twin research programs further steer technical specifications for grid and environmental simulation tools. Stakeholders must monitor how sovereign capability policies reshape procurement preferences for federally funded infrastructure projects.
Market Dynamics
Sovereign capability mandates from Canberra are redirecting procurement flows toward domestic systems integrators, compressing foreign vendor margins while elevating implementation and consulting fee pools for local platforms serving critical infrastructure.
Growth Catalysts
- Critical Technologies Fund allocations:Federal capital injections accelerate domestic industrial simulation platform development, with priority lanes for mining and energy asset twins.
- Western Australia mining automation:Remote equipment fleets generate sustained demand for predictive maintenance architectures across iron ore and lithium extraction corridors.
- Cloud-native twin architectures:Resource-heavy sectors pivot from on-premise legacy stacks to elastic compute models that reduce total cost of ownership for asset-intensive operators.
Market Restraints
- SCADA integration complexity:Brownfield industrial sites require expensive middleware layers to bridge legacy operational technology with modern inference engines.
- Specialized talent scarcity:Systems integrators face acute shortages of industrial data engineers capable of fusing physics-based simulation with real-time sensor telemetry.
- Cybersecurity compliance burden:The Australian Cyber Security Centre's Essential Eight framework imposes mandatory controls that extend deployment timelines for critical infrastructure twins.
Strategic Opportunities
- Queensland mining infrastructure:Sensor-to-cloud predictive maintenance contracts remain underpenetrated across coal and metallurgical operations in the Bowen Basin.
- Healthcare twin emergence:TGA software-as-medical-device pathways create first-mover advantages for platforms validating clinical workflow optimization in tertiary hospitals.
- Smart precinct mandates:Sydney's urban planning authorities now require precinct-scale simulation for major developments, opening municipal procurement channels.
Industry Challenges
- Physics-to-AI model reconciliation:Engineering teams struggle to align finite element analysis outputs with machine learning inference layers without domain-specific retraining pipelines.
- Hospital legacy system bridging:Healthcare implementations demand expensive custom integration to connect modern twin platforms with decades-old patient administration systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Digital Twin Market |
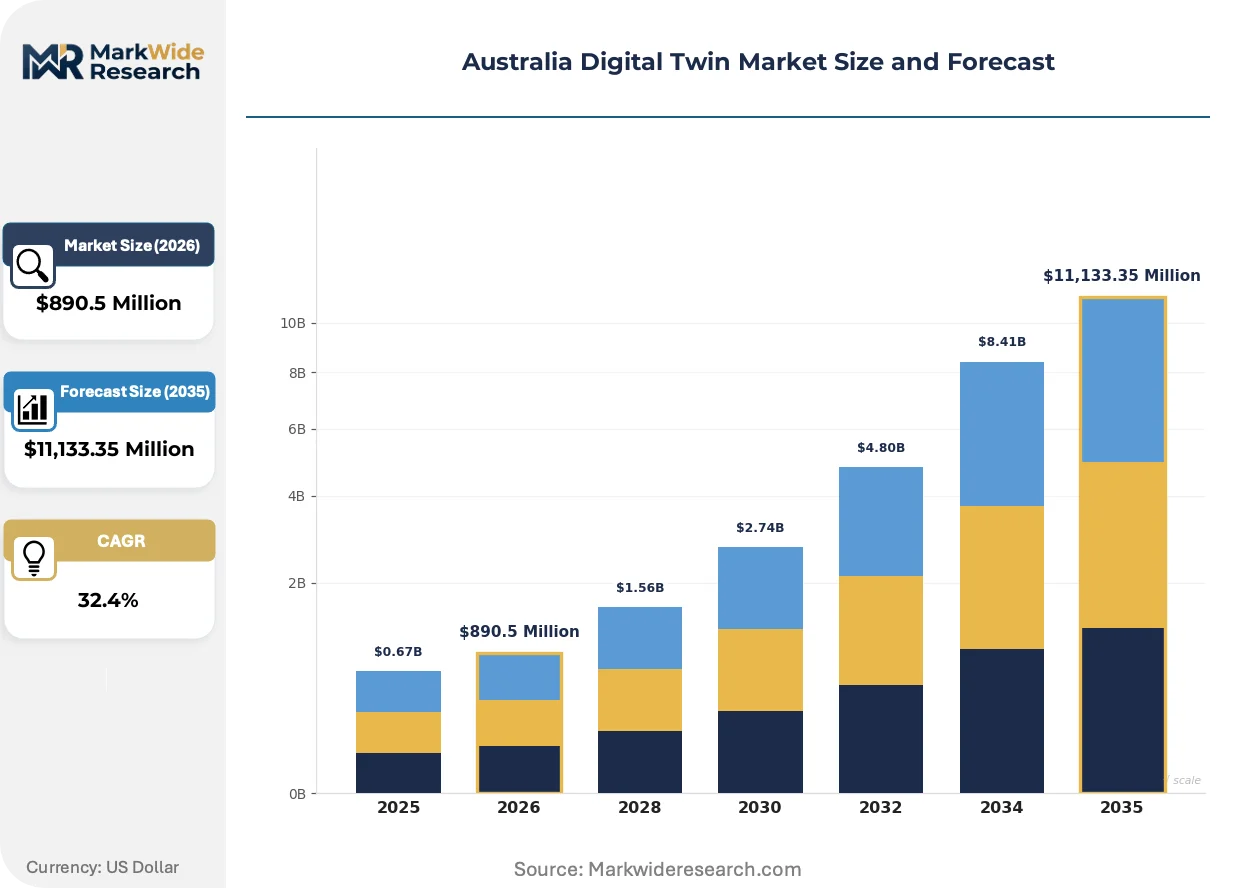
| Market Size in 2026 | $890.5 Million |
| Market Size in 2035 | $11,133.35 Million |
| CAGR (2026 – 2036) | 32.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Smart Cities, Manufacturing, Healthcare, Automotive Technology: IoT, AI, AR, VR End User: Government, Enterprises, Real Estate, Logistics Service Type: Consulting, Implementation, Maintenance, Support |
| Companies Covered | GE Vernova, AIOTEL, Siemens, ANSYS, Bosch, Dassault Systèmes, Geminum, Factory AI, PTC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Digital Twin Market Trends and Innovations
Technical specifications across the Australian market are hardening around sovereign data residency requirements and real-time interoperability standards, compressing vendor differentiation toward implementation velocity and sector-specific domain depth.
Edge-to-cloud streaming architectures are consolidating control system data flows for remote mining fleets. Operators in the Pilbara region now mandate sub-100 millisecond latency for equipment health telemetry, forcing infrastructure providers to deploy regional compute nodes. This compression is eliminating pure-cloud vendors from bidding pools for autonomous haulage contracts.
The Australian Energy Market Operator's integrated system plan now requires generator and network operators to submit digital twin models for grid stability assessments. This regulatory mandate forces asset owners to maintain synchronized virtual representations of rotating machinery and transmission topology. Compliance deadlines are compressing procurement cycles for utility-scale simulation platforms.
Asset-as-a-service contracting is displacing traditional capital purchase models for mining equipment. Rio Tinto and BHP now specify predictive maintenance guarantees in operating lease agreements, transferring performance risk to OEMs. This shift concentrates demand in Western Australia for outcome-linked twin deployments where sensor density directly determines contract pricing.
Australia Digital Twin Market Segmentation
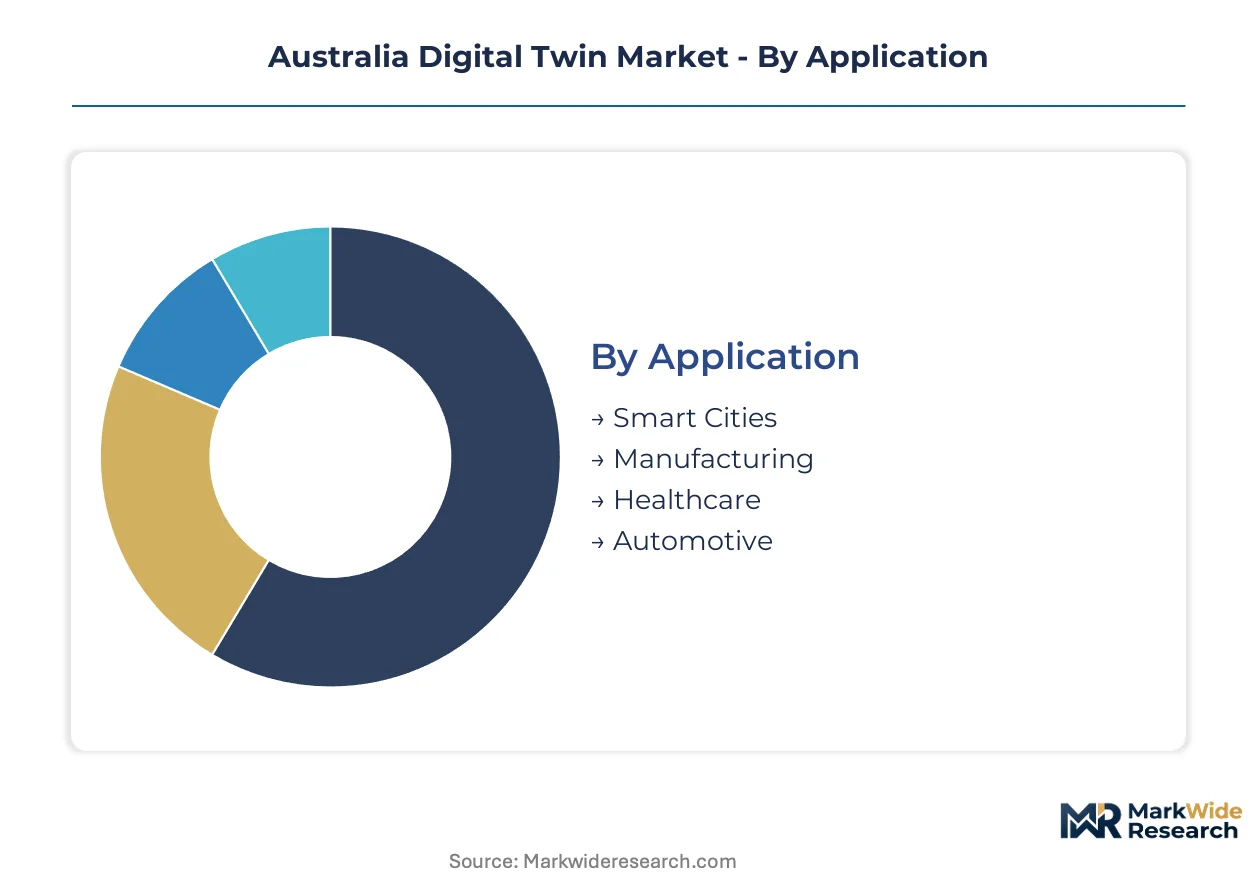
Digital twin procurement in Australia diverges sharply across application maturity and technical complexity. Mining and energy operators prioritize predictive maintenance architectures, while municipal authorities mandate precinct-scale simulation for urban planning compliance.
Application:
Capital allocation intensity determines buyer priorities across sectors with divergent regulatory timelines and asset replacement cycles.
- Smart Cities:Precinct-scale simulation platforms integrate building information modeling with real-time traffic and utility data streams. Sydney's urban planning mandates now require digital twin submissions for developments exceeding 50,000 square meters, compressing vendor selection cycles.
- Manufacturing:Physics-based asset twins dominate automotive and advanced manufacturing corridors in Melbourne, where finite element analysis fusion with sensor telemetry enables predictive quality control. The sector commands the deepest deployment maturity and highest service attach rates.
- Healthcare:Clinical workflow optimization twins remain nascent, constrained by TGA software-as-medical-device certification pathways and expensive legacy system bridging requirements in tertiary hospitals.
- Automotive:Connected vehicle simulation and autonomous system validation drive demand, though Australian OEM presence limits domestic deployment scale relative to manufacturing applications.
Manufacturing leads on scale; Smart Cities leads on momentum.
Technology:
Integration architecture choices hinge on latency requirements for remote asset monitoring and sovereign data residency constraints.
- IoT:Sensor-to-cloud pipelines form the data foundation for mining equipment twins, with Pilbara operators mandating sub-100 millisecond telemetry latency that forces regional edge compute deployment.
- AI:Machine learning inference layers enable predictive intervention, though engineering teams struggle to reconcile physics-based simulation outputs with neural network predictions without domain-specific retraining.
- AR:Field technician guidance applications gain traction in Queensland mining maintenance contracts, overlaying equipment schematics onto physical assets for remote expert assistance.
- VR:Immersive training and design review applications concentrate in defense and aerospace validation workflows, where ANSYS physics engines power high-fidelity simulation environments.
IoT anchors current deployment value; AI commands future capability premiums.
End User:
Procurement authority and compliance burden shape vendor engagement models across public and private sector buyers.
- Government:Federal infrastructure projects under sovereign capability mandates redirect procurement toward domestic systems integrators, elevating consulting fee pools for local platforms.
- Enterprises:Mining majors Rio Tinto and BHP now specify predictive maintenance guarantees in operating lease agreements, transferring performance risk to OEMs and concentrating demand for outcome-linked twin deployments.
- Real Estate:Commercial property developers adopt building twins for energy optimization and tenant experience management, though scale remains fragmented outside Sydney and Melbourne premium assets.
- Logistics:Supply chain visibility applications remain underpenetrated, constrained by fragmented fleet data standards and limited port authority integration mandates.
Enterprises dominate current revenue; Government procurement is expanding most quickly.
Service Type:
Margin capture shifts toward implementation complexity as product differentiation compresses around interoperability standards.
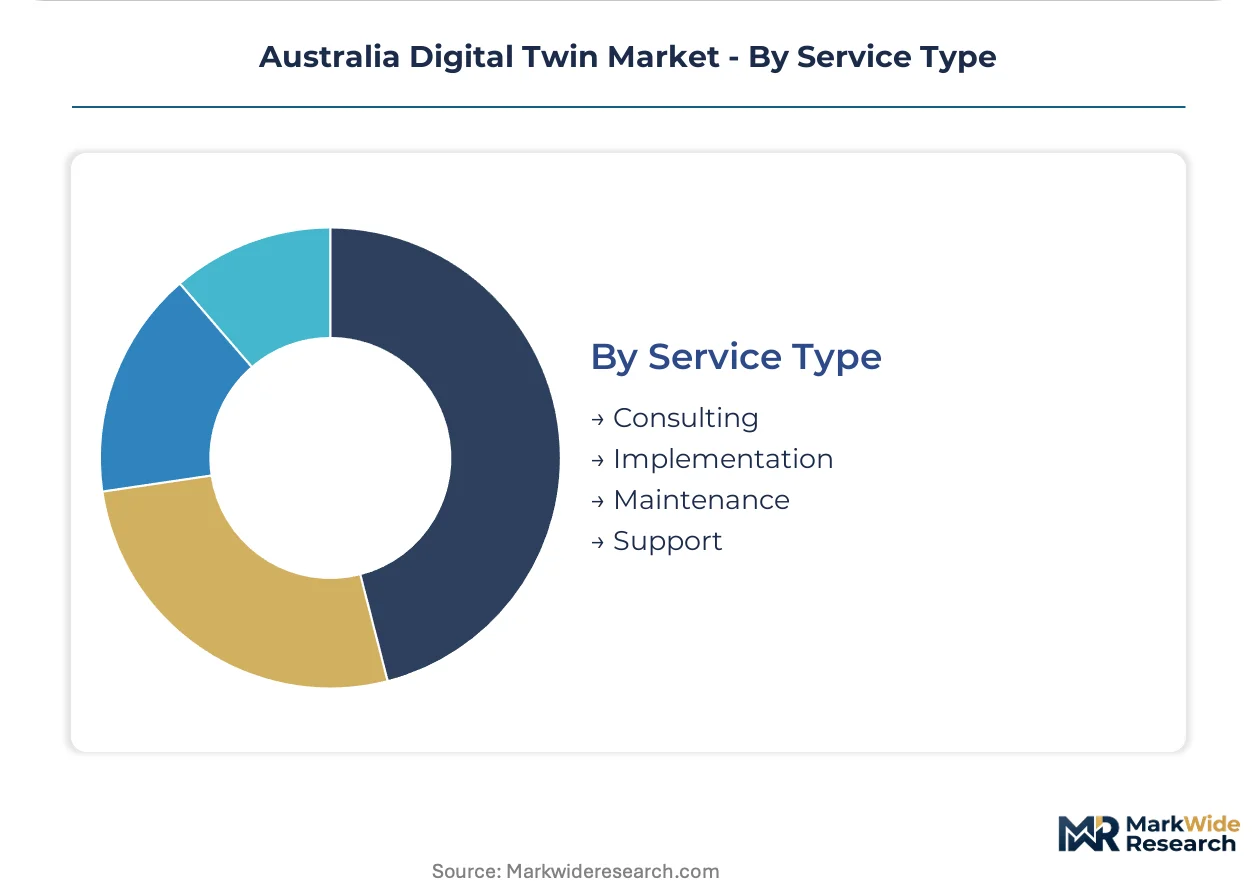
- Consulting:Systems integrators bridge legacy SCADA infrastructure with modern inference engines, commanding premium fees for brownfield industrial sites with complex middleware requirements.
- Implementation:Cloud-native architecture deployment for resource-heavy sectors drives sustained demand, as operators pivot from on-premise legacy stacks to elastic compute models.
- Maintenance:Continuous model calibration and sensor network optimization contracts extend customer lifetime value, particularly for autonomous haulage fleets in Western Australia.
- Support:Cybersecurity compliance services around the Australian Cyber Security Centre's Essential Eight framework extend deployment timelines but create recurring revenue anchors.
Consulting captures the highest margins; Implementation represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's digital twin deployment outpaces New Zealand's nascent adoption by a significant margin, with federal infrastructure mandates creating distinct procurement patterns across state boundaries. The national market fragments across five economic zones with divergent asset bases and regulatory environments.
New South Wales
Sydney's smart precinct mandates drive precinct-scale simulation demand for developments exceeding 50,000 square meters. The state's planning authorities compress vendor selection cycles through mandatory digital twin submissions. Parramatta's urban renewal corridor anchors municipal procurement for integrated building and transport modeling.
Victoria
Melbourne's advanced manufacturing corridors command the deepest deployment maturity in automotive and aerospace validation workflows. The state's industrial zones prioritize physics-based asset twins for predictive quality control. Fishermans Bend and the Latrobe Valley concentrate finite element analysis fusion with sensor telemetry implementations.
Western Australia
Pilbara mining operators mandate sub-100 millisecond latency for autonomous haulage fleet telemetry, forcing regional edge compute deployment. The state's Critical Technologies Fund allocations accelerate domestic industrial simulation platform development. Karratha and Port Hedland anchor predictive maintenance architectures for iron ore and lithium extraction corridors.
Queensland
Bowen Basin coal and metallurgical operations generate underpenetrated demand for sensor-to-cloud predictive maintenance contracts. The state's mining infrastructure presents first-mover opportunities for equipment health monitoring platforms. Brisbane's technology precincts house emerging systems integrators bridging legacy SCADA with modern inference engines.
South Australia
Defense and aerospace validation workflows concentrate around physics-based simulation requirements for sovereign capability projects. The state's manufacturing base supports ANSYS-dominated high-fidelity environments for component testing. Adelaide's technology park anchors specialized consulting services for brownfield industrial integration.
Australia Digital Twin Market Competitive Landscape
European industrial software giants anchor the premium tier; Australian domestic specialists hold implementation and consulting fee pools through sovereign capability mandates. The vendor base compresses around interoperability standards, with differentiation shifting toward sector-specific domain depth and deployment velocity. Three archetypes dominate: cloud-native platform providers, physics-based simulation engine vendors, and systems integrators bridging legacy infrastructure. Competitive moves concentrate on strategic partnerships with mining majors and technology licensing for edge-to-cloud streaming architectures.
Within the industrial software tier, Siemens and ANSYS exemplify divergent technical approaches—Siemens leveraging energy sector expertise for utility-scale deployments, ANSYS sustaining intensity through physics-based engines. Bosch occupies a position in sensor-to-cloud integration, extending IoT hardware footprints into predictive maintenance contracts. These three anchors represent distinct competitive vectors: sector depth, simulation fidelity, and hardware-to-software verticality.
| Leading Market Players |
|---|
| GE Vernova |
| AIOTEL |
| Siemens |
| ANSYS |
| Bosch |
| Dassault Systèmes |
| Geminum |
| Factory AI |
| PTC |
| Others |
Pricing and Supply Chain Analysis
Sovereign capability mandates from Canberra are compressing foreign vendor margins while elevating implementation fee pools for domestic systems integrators serving critical infrastructure projects. This procurement redirection forces supply chain reconfiguration toward Australian-based engineering talent and cloud residency-certified platforms.
Pricing Analysis
Direct-to-OEM discount structures dominate outcome-linked predictive maintenance contracts where Rio Tinto and BHP transfer performance risk to equipment suppliers. Three-tier pricing structure across premium physics-based simulation, standard IoT sensor integration, and economy cloud-native deployment separates ANSYS-level fidelity from Bosch sensor-to-cloud bundles. Cost compression in mid-tier implementation services is intensifying because systems integrators compete on deployment velocity for brownfield SCADA bridging. Government procurement under sovereign mandates shows lowest price sensitivity; Queensland mining contractors exhibit highest.
Supply Chain Analysis
Domestic-content requirements under Australia's Critical Technologies Fund are reshaping sourcing toward local systems integrators and sovereign cloud providers. Hardware components draw from Germany for industrial sensors, USA for GPU compute infrastructure, and Taiwan for edge processing units. Software licensing rests on US-based physics engines and European IoT platforms. Single-source vulnerability concentrates in specialized industrial data engineering talent pools. Distribution runs through federal procurement channels for infrastructure projects and direct OEM engagements for mining automation contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia's digital twin market functions as a geographic-arbitrage play where regulatory divergence between Canberra's sovereign capability mandates and New Zealand's lighter procurement frameworks concentrates margin capture in Australian-resident platforms.
For Market Incumbents: Cement market position through exclusive partnerships with Western Australia mining majors for autonomous haulage fleet telemetry architectures. Lock in multi-year sensor-to-cloud maintenance contracts that embed switching costs. Deepen vertical integration into edge compute infrastructure deployment across Pilbara regional nodes to preempt pure-cloud vendor re-entry. For New Entrants and Emerging Players: Cloud-native platform marketplaces offer lowest-friction entry vectors for healthcare twin applications constrained by TGA software-as-medical-device certification complexity. Queensland's Bowen Basin coal operations present the most penetrable mining segment with undercontracted predictive maintenance coverage. Lead with outcome-based pricing tied to equipment uptime guarantees rather than capital deployment models. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap systems integrators possessing existing federal infrastructure project credentials and cleared engineering teams. Long-term viability hinges on recurring maintenance revenue from calibrated sensor networks rather than one-time implementation fees. Monitor AEMO integrated system plan compliance deadlines as inflection indicators for utility-scale simulation platform procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | ANSYS physics engine licensing to Australian mining OEMs anchors high-fidelity simulation workflows. |
| Strategic Partnership | Siemens utility-scale deployments across the National Electricity Market lock in decade-long service contracts. |
| Acquisition of Specialist Firm | Domestic systems integrators with Essential Eight compliance expertise command premium valuation multiples. |
| Geographic Expansion | Edge compute node deployment in Karratha and Port Hedland captures Pilbara latency requirements. |
| Product Launch | TGA-validated clinical workflow twins for Sydney tertiary hospitals open first-mover certification pathways. |
Research Methodology
Direct dialogue with mining automation engineers, federal procurement officers, systems integration specialists, and cloud platform architects combined with secondary validation from AEMO integrated system plan documentation, CSIRO digital twin research publications, and Australian Cyber Security Centre Essential Eight compliance frameworks. Bottom-up project pipeline analysis triangulated against top-down federal budget allocation tracking for Critical Technologies Fund disbursements.
Segmented outputs across application type, technology stack, end-user category, and service delivery model populate the analytical framework over the projection horizon. CAGRs derive from deployment velocity curves calibrated against historical mining automation adoption patterns and utility regulatory compliance deadlines. Cloud-native architecture migration rates and sovereign data residency certification timelines serve as primary forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for edge-to-cloud streaming architectures would alter the outlook if latency requirements soften or pure-cloud vendors achieve sub-100 millisecond performance guarantees. Forecasts reflect documented assumptions around federal procurement policy continuity and mining capital expenditure cycles. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Enterprise Mobility in Manufacturing Market
Digital Solutions
IPTV Market
Digital Solutions
Mobile Campaign Management Platform Market
Digital Solutions
Digital Manufacturing Market
Digital Solutions
Mobile Command and Control Solutions Market
Digital Solutions
Boat Navigation Software Market
Digital Solutions
Desktop Virtualization Market
Digital Solutions
India ICT Market
Digital Solutions
Global B2B Services Review Platforms Market
Digital Solutions
Global Drilling Data Management Systems Market
Digital Solutions
Global Commerce Cloud Solution Market
Digital Solutions
NFT Creation Software Market
Digital Solutions
Smart Signage Market
Digital Solutions
OTA Transmission Platform Market
Digital Solutions
New Zealand ICT Market
Digital Solutions
Smart Process Application (SPA) Market