
 New Zealand ICT Market | 2026-2036
New Zealand ICT Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand ICT Market Foresight
Cloud architecture skills is rotating from scarce to strategically critical as enterprises migrate core systems off legacy infrastructure. Datacom leverages its nationwide delivery footprint to anchor public sector digital transformation contracts. Spark New Zealand competes through vertically integrated network-to-cloud service stacks. Xero dominates small-business financial software with API-first platform architecture.
Information and communications technology encompasses digital infrastructure, software applications, telecommunications networks, and data management systems operating at speeds from gigabit fiber to 5G millimeter-wave spectrum. Primary commercial purpose centers on enabling real-time transaction processing, remote collaboration, and automated decision pipelines across distributed organizations. Software and cloud solutions command the deepest margin pools as recurring revenue models displace perpetual licensing. Services integration grows fastest where legacy modernization intersects cybersecurity hardening. Hardware retains structural importance in data center expansion and edge computing deployments.
New Zealand's Privacy Act 2020 and Commerce Commission telecommunications regulations shape market access through data sovereignty mandates and infrastructure sharing obligations. The country's national cyber security centre and ISO 27001 certification requirements further constrain vendor qualification pathways. Stakeholders must weigh the trade-off between offshore SaaS scalability and onshore compliance residency as procurement criteria tighten.
Market Dynamics
Cloud migration is compressing procurement cycles across New Zealand enterprises as legacy infrastructure retirement accelerates and data sovereignty requirements harden under the Privacy Act 2020.
Growth Catalysts
- Privacy Act 2020 compliance mandates:Data localization requirements are forcing enterprises to repatriate workloads to domestic cloud regions, expanding addressable market for local infrastructure providers.
- Hyperscale data center investment:Auckland's technology corridor is absorbing concentrated enterprise software spending as fintech clusters demand low-latency compute infrastructure.
- SME cloud adoption acceleration:Small and medium enterprises are bypassing on-premise hardware procurement entirely, collapsing traditional IT refresh cycles into subscription-based consumption models.
Market Restraints
- Specialized cloud architecture talent scarcity:Skills rotation from legacy infrastructure management to container orchestration and FinOps is outpacing domestic training pipeline capacity.
- Subsea cable concentration risk:International connectivity depends on limited transpacific fiber routes, exposing latency-sensitive applications to geopolitical or physical disruption.
- ISO 27001 certification friction:Vendor qualification pathways through the national cyber security centre are extending sales cycles for offshore SaaS providers seeking public sector access.
Strategic Opportunities
- Canterbury agritech corridor:Precision agriculture platforms remain underpenetrated relative to Auckland's financial services density, creating whitespace for vertical-specific IoT and edge deployments.
- API-first platform convergence:Integration between financial software and supply chain management tools is opening embedded finance opportunities for developers building on open banking infrastructure.
- Telecommunications infrastructure sharing:Commerce Commission regulations are lowering barriers to wholesale network access, enabling virtual mobile network operators to compete without spectrum ownership.
Industry Challenges
- Multi-cloud integration complexity:Enterprises managing workloads across domestic and Australian cloud regions face operational overhead from divergent compliance frameworks and data residency rules.
- Legacy system interdependency mapping:Core banking and government systems built on 1990s architectures resist modular decomposition, extending transformation timelines and budget uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand ICT Market |
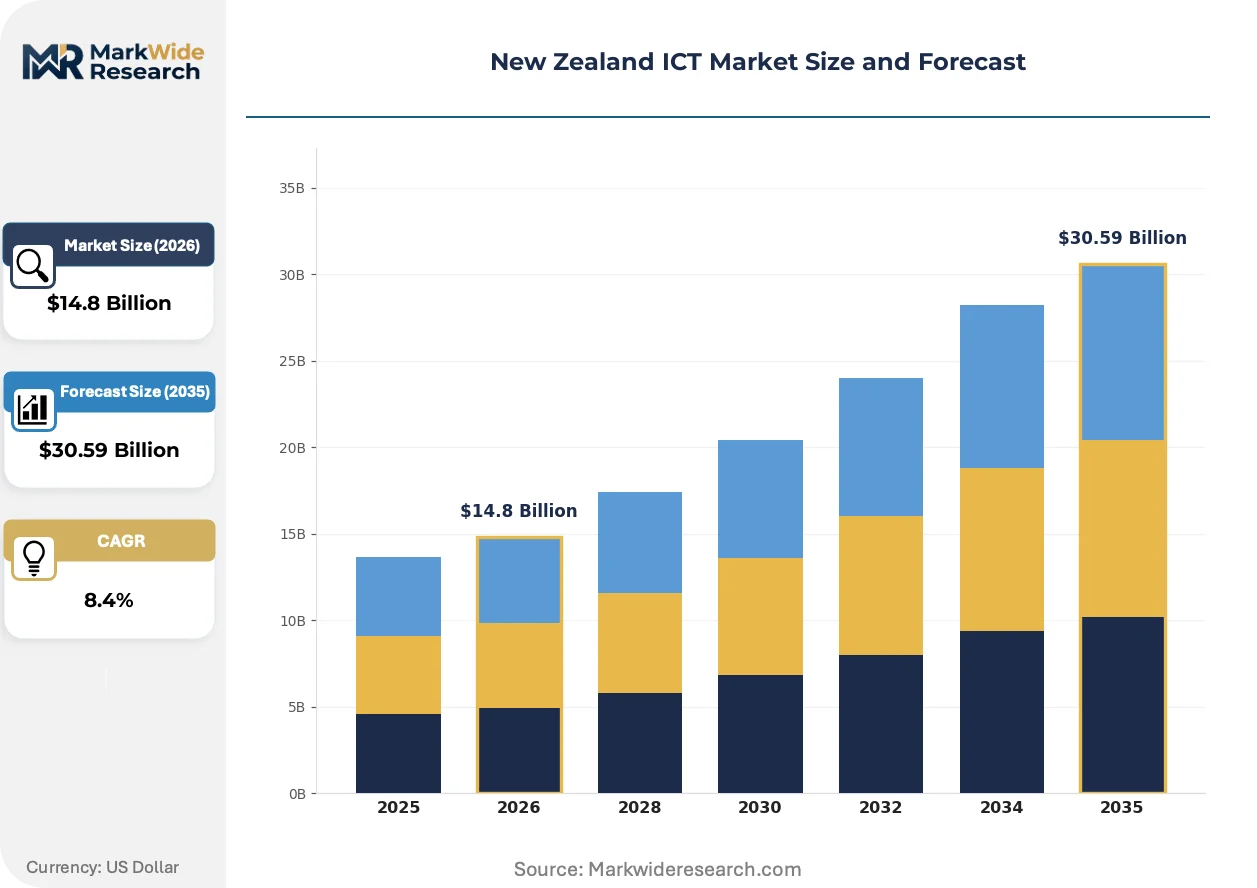
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $30.59 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Cloud Solutions End User: Government, Education, Healthcare, SMEs Technology: AI, IoT, Cybersecurity, Blockchain Service Type: Consulting, Support, Integration, Development |
| Companies Covered | Xero, Microsoft New Zealand, Datacom, Umbrellar Technology Group, IBM New Zealand, Spark New Zealand, Orion Health, Lexel, One NZ, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand ICT Market Shifts & Advancements
Containerized application deployment is reshaping how New Zealand enterprises consume infrastructure, with implications for vendor lock-in, cost visibility, and operational control that extend beyond technology selection into procurement governance.
Microservices architecture is decomposing monolithic enterprise applications into independently deployable components. Financial services institutions in Auckland are adopting Kubernetes-orchestrated workloads at pace, collapsing three-year hardware refresh cycles into continuous integration pipelines. This decomposition is compressing vendor consolidation strategies and forcing incumbents to expose granular pricing for compute, storage, and network resources rather than bundled enterprise agreements.
The Privacy Act 2020's information privacy principles are tightening data handling obligations for offshore SaaS providers. Multinational cloud operators must now designate local representatives and demonstrate compliance with New Zealand's notification regime for privacy breaches. Public sector procurement panels are revising qualification criteria to prioritize vendors with domestic data residency certifications, disadvantaging pure offshore delivery models.
Subscription consumption patterns are displacing capital-intensive IT ownership models across Wellington's government and professional services clusters. Buyers are unbundling hardware procurement from managed service relationships, preferring outcome-aligned contracts with explicit service-level commitments over traditional break-fix arrangements. This shift is most visible in healthcare and education verticals where operational expenditure budgets are replacing depreciated asset lines.
New Zealand ICT Market Segmentation
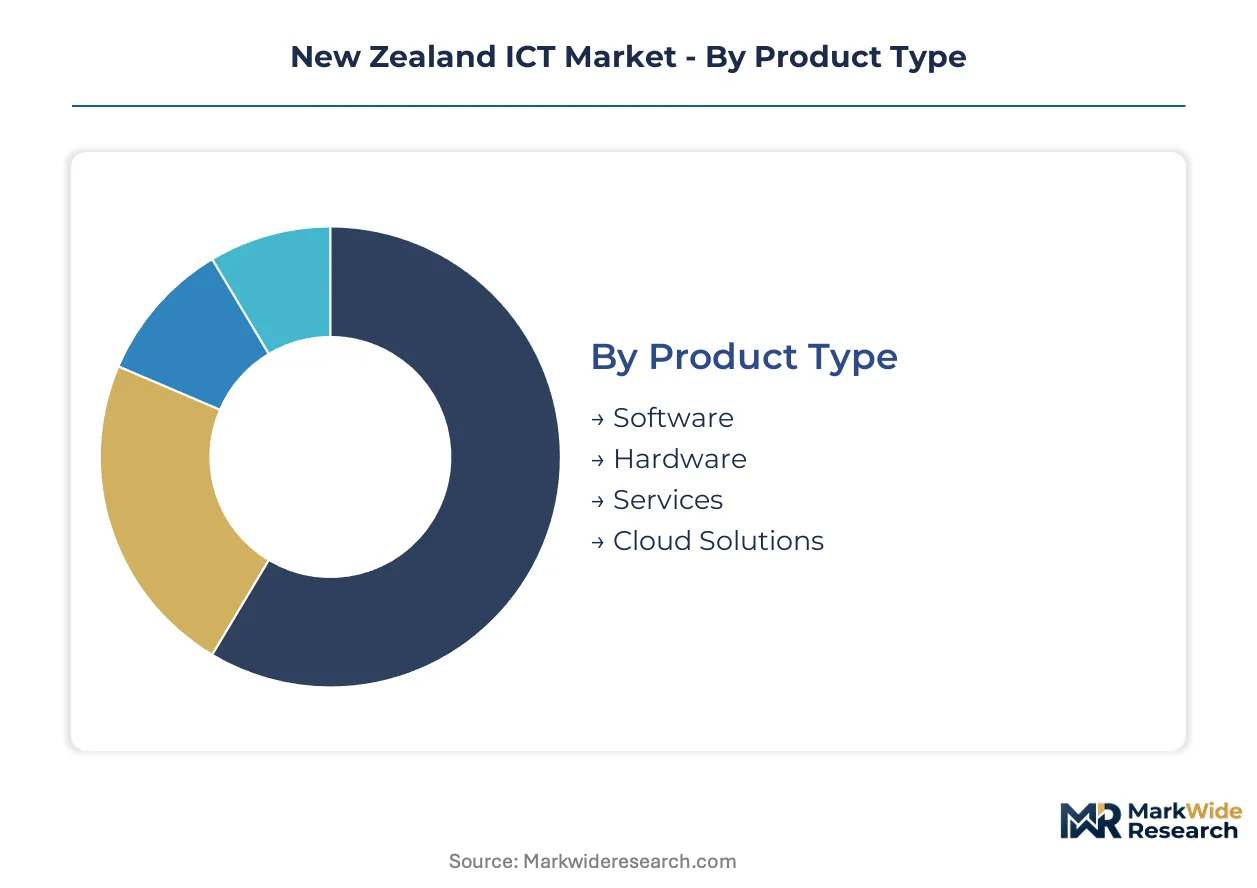
Segmentation reveals how procurement authority is fragmenting across New Zealand's ICT landscape. Government buyers prioritize data sovereignty certifications while SMEs optimize for subscription flexibility, creating divergent vendor qualification pathways.
Product Type:
Substitution pressure is most acute where cloud consumption models displace capital-intensive hardware ownership, forcing legacy vendors to reprice perpetual licenses against recurring SaaS alternatives.
- Software:Enterprise applications and productivity suites dominate procurement panels across Wellington government clusters. Auckland fintechs drive demand for API-first financial platforms that integrate with open banking infrastructure.
- Cloud Solutions:Hyperscale infrastructure services and domestic data center regions absorb the majority of enterprise migration budgets. Privacy Act 2020 compliance mandates are repatriating workloads from offshore regions to Auckland-based facilities.
- Services:Managed service providers bundle legacy modernization with cybersecurity hardening for mid-market buyers.
- Hardware:Server and storage equipment retains relevance in edge computing deployments across Canterbury agritech corridors.
Software retains volume leadership; Cloud Solutions holds the steepest expansion curve.
End User:
Cost tier stratification separates sovereign-funded buyers with multi-year transformation budgets from SMEs purchasing through operational expenditure lines.
- Government:Central agencies and departmental CIOs procure through consolidated panels with mandatory ISO 27001 certification. The national cyber security centre extends vendor qualification timelines for offshore SaaS providers seeking public sector access.
- SMEs:Small and medium enterprises bypass on-premise infrastructure entirely, collapsing traditional refresh cycles into consumption-based subscriptions. Cloud adoption acceleration compresses procurement decision timelines from quarters to weeks.
- Healthcare:District health boards replace depreciated asset lines with outcome-aligned managed service contracts.
- Education:Tertiary institutions and K-12 clusters unbundle hardware from break-fix arrangements in favor of explicit service-level commitments.
Government retains volume leadership; SMEs hold the steepest expansion curve.
Technology:
Application maturity separates production-grade deployments from pilot-stage evaluations across New Zealand enterprise buyers.
- Cybersecurity:Zero-trust architecture and identity management solutions anchor post-Privacy Act compliance investments. Financial services institutions in Auckland prioritize threat detection platforms that satisfy both domestic regulators and Australian parent-bank standards.
- AI:Machine learning pipelines and natural language processing tools concentrate in government automation and fintech credit decisioning. Skills scarcity in MLOps and model governance constrains deployment velocity outside well-capitalized enterprises.
- IoT:Precision agriculture sensors and supply chain tracking devices penetrate Canterbury agritech corridors.
- Blockchain:Distributed ledger pilots remain confined to trade finance and identity verification proofs-of-concept.
Cybersecurity retains volume leadership; AI holds the steepest expansion curve.
Service Type:
Margin concentration favors integration and development engagements where legacy system interdependencies extend project timelines and budget uncertainty.
- Integration:Multi-cloud orchestration and legacy-to-cloud migration services command premium pricing as enterprises navigate divergent data residency rules across domestic and Australian regions. Project complexity escalates where 1990s core banking architectures resist modular decomposition.
- Development:Custom application builds on containerized infrastructure accelerate as Kubernetes adoption matures in Auckland financial services clusters. API-first platform convergence creates embedded finance opportunities for developers building on open banking rails.
- Consulting:Strategy and architecture advisory supports C-suite cloud migration business cases.
- Support:Break-fix and maintenance contracts lose share to outcome-aligned managed service relationships.
Integration retains volume leadership; Development holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Auckland commands premium pricing power over Canterbury due to hyperscale data center density and fintech concentration, while Wellington's government procurement panels enforce strict compliance premiums that reshape vendor margins across both markets.
Auckland
Hyperscale data center investments and fintech clusters drive concentrated enterprise software spending. The Privacy Act 2020 mandates data localization for public sector contracts. Auckland's technology corridor absorbs the majority of cloud migration budgets as financial services institutions demand low-latency compute infrastructure.
Wellington
Central government agencies and departmental CIOs anchor demand through consolidated procurement panels. ISO 27001 certification requirements and national cyber security centre vetting extend vendor qualification timelines. The capital's professional services clusters accelerate subscription consumption patterns across healthcare and education verticals.
Canterbury
Precision agriculture platforms and agritech IoT deployments create whitespace outside Auckland's financial services density. Rural connectivity investments and regional development funding support edge computing infrastructure. The Canterbury agritech corridor remains underpenetrated relative to northern markets, attracting vertical-specific solution providers.
Waikato
Manufacturing and logistics enterprises drive industrial automation demand alongside agricultural technology adoption. Regional broadband initiatives and fiber network extensions enable cloud migration for mid-market manufacturers. Hamilton's emerging technology precinct concentrates supply chain software and IoT integration services.
New Zealand ICT Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the New Zealand ICT market, creating a tiered competitive structure where specialized capability providers coexist with scale-driven infrastructure operators. The vendor base clusters around three strategic archetypes: vertically integrated telecommunications-to-cloud stacks, API-first software platforms, and public sector-focused managed service integrators. M&A activity concentrates on cybersecurity capability acquisition, while strategic partnerships dominate multi-cloud orchestration service development.
Within the vertically integrated tier, Spark New Zealand and One NZ occupy positions spanning network infrastructure through managed cloud services, exemplifying the telecommunications-origin archetype that leverages captive fiber and mobile spectrum assets. Xero anchors the API-first platform segment, representing the SaaS-native model that has displaced traditional on-premise financial software through subscription economics and open banking integration. Datacom sits within the public sector specialist tier, anchoring government digital transformation contracts through nationwide delivery footprints and compliance-certified service operations.
| Leading Market Players |
|---|
| Xero |
| Microsoft New Zealand |
| Datacom |
| Umbrellar Technology Group |
| IBM New Zealand |
| Spark New Zealand |
| Orion Health |
| Lexel |
| One NZ |
| Others |
Supply & Pricing Matrix
Hyperscale data center utilization rates in Auckland's technology corridor anchor both supply concentration and price floors for domestic cloud infrastructure. Scale efficiencies at these facilities compress marginal delivery costs while Privacy Act 2020 compliance premiums sustain elevated pricing tiers for sovereign-certified workloads.
Pricing Analysis
The customization-premium spread separates standard SaaS subscriptions from configured-to-order enterprise implementations across New Zealand's ICT procurement landscape. Subscription-based consumption models dominate software and cloud solutions, with price differentiation driven by ISO 27001 certification tier and data residency guarantees. Pricing pressure stems from SME procurement acceleration collapsing traditional evaluation timelines. Government buyers exhibit lowest price sensitivity due to mandatory compliance requirements, while mid-market manufacturers in Waikato demonstrate highest sensitivity to per-seat licensing costs.
Supply Chain Analysis
Inbound logistics costs for server hardware and networking equipment hinge on Trans-Tasman shipping lane reliability and Port of Auckland container throughput. Supply concentrates in China, Taiwan, and the United States for semiconductor components, hyperscale server assemblies, and enterprise networking gear. Raw material dependencies span silicon wafers, rare earth elements for magnetic storage, and copper for fiber optic cabling. Single-source vulnerability persists where specialized ASICs source exclusively from TSMC fabrication facilities. Distribution runs through distributor-led channel partnerships serving Wellington government clusters and direct hyperscaler relationships for Auckland enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
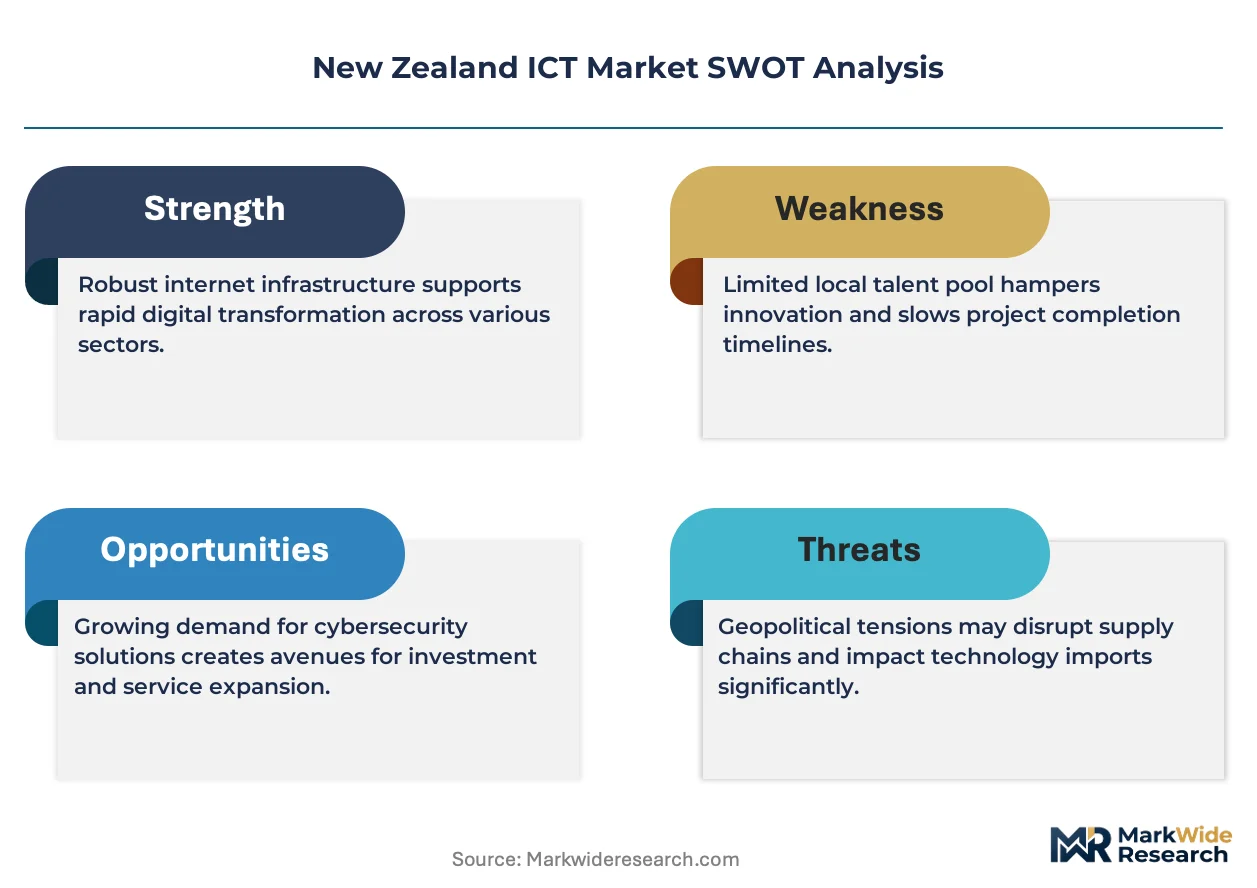
New Zealand's ICT market constitutes a defensive-moat story anchored in regulatory entrenchment. Privacy Act 2020 data sovereignty mandates and ISO 27001 certification requirements create structural switching costs that protect incumbent positions.
For Market Incumbents: Fortify compliance-certified service operations against emerging cybersecurity specialists targeting public sector panels. Invest in domestic data center capacity expansion within Auckland's technology corridor to capture repatriating workloads. Deepen API-first platform architectures to embed financial services customers through open banking integration, raising substitution barriers. For New Entrants and Emerging Players: Differentiate on vertical-specific IoT deployments across Canterbury's underpenetrated agritech corridor. Target precision agriculture platforms where legacy vendors lack domain expertise. Pursue embedded finance opportunities through supply chain software integration, leveraging Commerce Commission infrastructure-sharing regulations to bypass spectrum ownership requirements. For Investors and Strategic Acquirers: Public sector-focused managed service integrators with nationwide delivery footprints represent the most defensible acquisition archetype. Long-term viability hinges on sustained government digital transformation budgets and tightening procurement qualification pathways. Watch hyperscaler domestic region announcements as inflection indicators for local infrastructure provider valuation compression.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Data Center Region Expansion | Captures Privacy Act 2020-driven workload repatriation from Australian hyperscale regions. |
| ISO 27001 Certification Investment | Unlocks Wellington government procurement panel access and extends vendor qualification timelines. |
| API-First Platform Integration | Embeds financial services customers through open banking infrastructure convergence. |
| Canterbury Agritech Corridor Entry | Addresses whitespace in precision agriculture IoT outside Auckland's fintech density. |
| Cybersecurity Capability Acquisition | Consolidates post-Privacy Act compliance investments across zero-trust architecture demand. |
Research Methodology
Operator-level perspectives from cloud infrastructure architects, government procurement officers, cybersecurity compliance leads, and managed service delivery heads anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation across SEC filings from multinational hyperscalers, New Zealand Commerce Commission telecommunications determinations, and Privacy Commissioner breach notification databases. Bottom-up segment sizing triangulated against top-down ICT expenditure estimates from central government budget disclosures.
Sensitivity analysis tested forecast outputs against alternative adoption curves for container orchestration and AI/ML pipeline deployment. The analytical framework modeled segmentation across deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern throughout the forecast period. CAGRs derived from fitted growth curves applied to baseline expenditure data, with inputs from hyperscaler domestic capex announcements and subsea cable capacity expansion timelines.
Material uncertainties — regulatory enforcement intensity for data localization, subsea cable geopolitical disruption, and domestic cloud architecture talent pipeline capacity — sit outside the modeled envelope. Forecasts reflect documented assumptions about Privacy Act 2020 compliance cost trajectories and SME subscription conversion rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Data Monetization Market
Digital Solutions
Data Labeling Solution and Services Market
Digital Solutions
Digital Dispenser Systems Market
Digital Solutions
Digital String Encoder Market
Digital Solutions
Lecture Capture Solutions Market
Digital Solutions
Global Correspondence Management System Market
Digital Solutions
Global Cloud Monitoring Tools Market
Digital Solutions
Australia Digital Marketing Software Market
Digital Solutions
Australia Cloud OSS BSS Market
Digital Solutions
Asia-Pacific Digital Twin Market
Digital Solutions
Global Mesh App and Service Architecture Market
Digital Solutions
Commodity Supply Chain Management Solution Market
Digital Solutions
Control Room Solutions Market
Digital Solutions
Social Networking App Market
Digital Solutions
Data Fusion Solutions Market
Digital Solutions
Microservices Architecture Market