
 Smart Process Application (SPA) Market | 2026-2036
Smart Process Application (SPA) Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Process Application (SPA) Market Analytics
North American cloud infrastructure expansion is reshaping competitive dynamics in SPA delivery. Microsoft Corporation leverages its Azure ecosystem to anchor enterprise workflow automation across hybrid deployments. IBM Corporation sustains R&D intensity in AI-infused decision management, competing with specialized pure-plays. Salesforce.com, Inc. dominates CRM-integrated process automation, extending its platform into industry-specific verticals.
Smart Process Application denotes software that orchestrates, automates, and optimizes business workflows through embedded analytics, business rules engines, and adaptive case management capabilities. These platforms integrate with enterprise systems via APIs and microservices architectures to execute end-to-end processes spanning document routing, approval chains, and exception handling. Workflow Automation occupies the largest revenue pool as enterprises eliminate manual handoffs, while Cloud-Based deployment represents the fastest expansion trajectory as organizations retire on-premise legacy stacks. Decision Management captures concentrated margin pools in regulated verticals requiring auditable, explainable automation logic.
The EU AI Act, GDPR, and HIPAA impose algorithmic transparency and data residency requirements that directly shape SPA procurement criteria and vendor qualification. FDA guidance on software as a medical device and SEC rules on electronic recordkeeping further segment compliance obligations across healthcare and financial services deployments. Stakeholders must monitor evolving cross-border data governance frameworks to align platform architectures with jurisdiction-specific audit and explainability mandates.
Market Dynamics
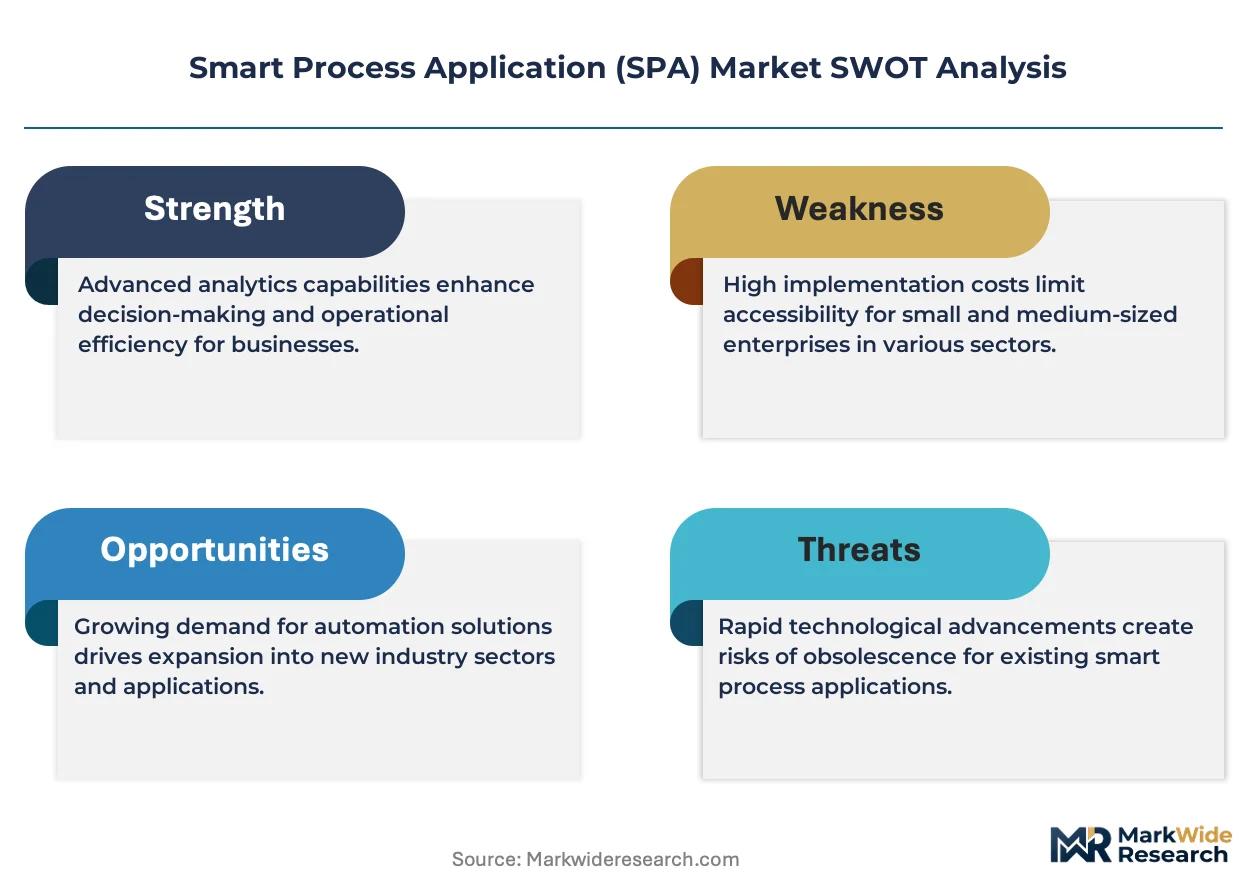
Cloud migration mandates under the EU AI Act and GDPR are forcing European enterprises to replace on-premise legacy stacks with compliant SaaS architectures, compressing deployment cycles and reshaping vendor qualification criteria.
Growth Catalysts
- EU AI Act compliance deadlines:Enterprises across Germany, France, and the Netherlands are accelerating procurement of auditable SPA platforms to meet algorithmic transparency requirements.
- Healthcare digitization:HIPAA-covered entities in the United States are deploying decision management tools to automate prior authorization and claims adjudication workflows.
- Microservices architecture adoption:Financial services firms are integrating API-first SPA platforms to enable real-time risk scoring and customer onboarding orchestration.
Market Restraints
- Data residency infrastructure costs:GDPR-mandated sovereign cloud deployments require redundant compute capacity in each member state, elevating total cost of ownership.
- Legacy system technical debt:Mainframe-based core banking and insurance policy administration systems resist API integration without expensive middleware layers.
- Specialized talent scarcity:Shortage of process engineers fluent in both business rules engine configuration and regulatory audit trail design constrains implementation velocity.
Strategic Opportunities
- CSRD reporting automation:The EU Corporate Sustainability Reporting Directive creates demand for SPA platforms that embed ESG data collection and validation into operational workflows.
- India BIS certification pipelines:Manufacturing exporters are adopting quality management SPAs to automate documentation for Bureau of Indian Standards compliance.
- Adaptive case management convergence:Integration of low-code process modeling with AI-powered exception handling opens new verticals in legal services and public sector case processing.
Industry Challenges
- Multi-jurisdiction audit trail reconciliation:Enterprises operating across GDPR, HIPAA, and SEC jurisdictions struggle to maintain unified logging standards that satisfy divergent evidentiary requirements.
- Explainability engineering bottlenecks:Shortage of professionals capable of translating black-box machine learning outputs into human-interpretable decision rationales delays AI-infused SPA deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Process Application (SPA) Market |
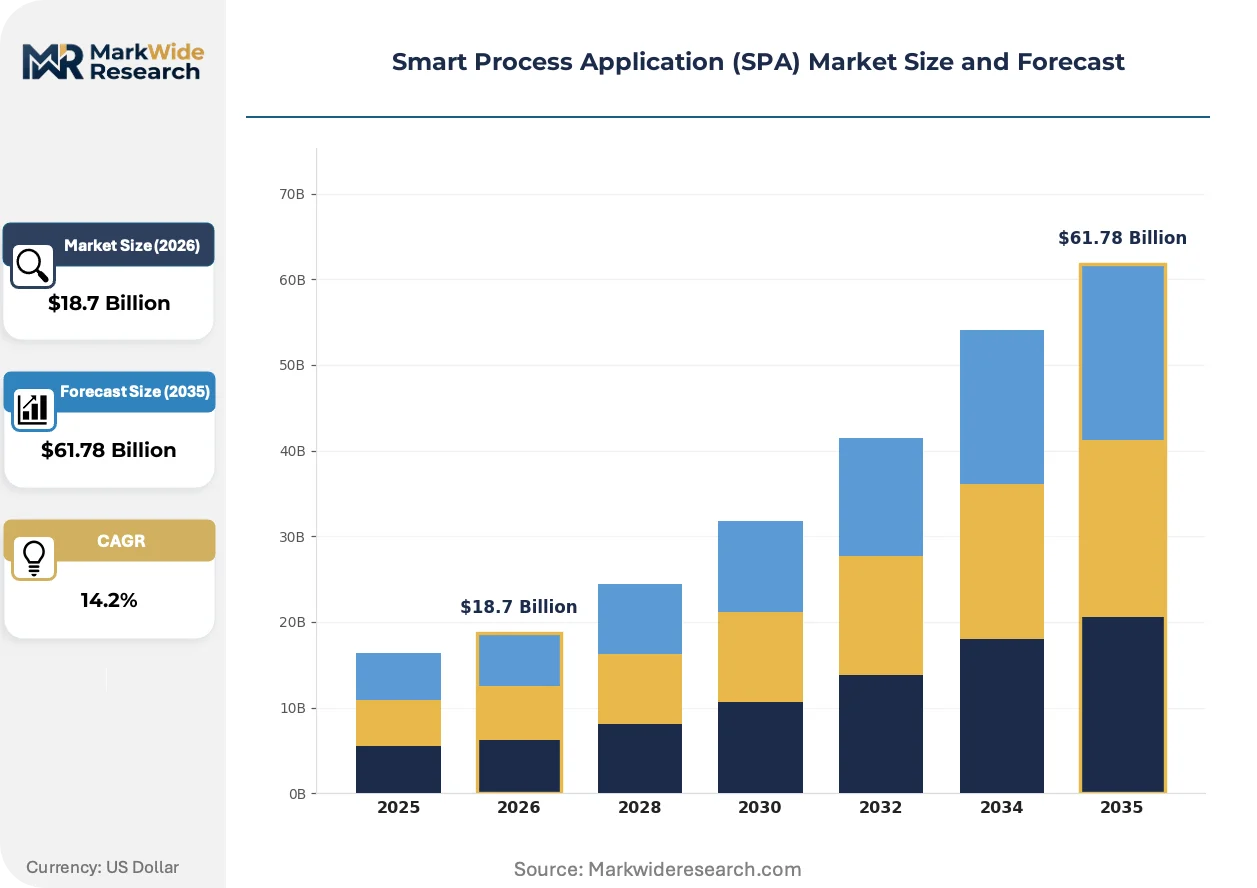
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Workflow Automation, Business Process Management, Document Management, Decision Management Industry Vertical: Manufacturing, Healthcare, Retail, Financial Services Deployment Model: On-Premise, Cloud-Based, Hybrid, SaaS End User: SMEs, Large Enterprises, Government Agencies, Non-Profits |
| Companies Covered | Pegasystems Inc, Microsoft Corporation, IBM Corporation, OpenText Corporation, Oracle Corporation, SAP SE, Salesforce.com, Inc., Dell Technologies, Appian Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Process Application (SPA) Market Evolving Landscape
Generative AI capabilities are embedding into process orchestration layers, enabling natural language interface design and automated workflow documentation that compresses implementation timelines.
Low-code business rules engines with embedded explainability logging are rendering obsolete traditional hard-coded workflow systems that require developer intervention for policy changes. Insurance carriers and commercial banks are adopting these platforms at accelerated cadences to compress product launch cycles. The shift is rendering obsolete centralized IT backlog queues that previously gated business-led process modifications.
The EU AI Act's risk-based classification system mandates human oversight interfaces for high-risk automated decision systems. Healthcare providers deploying diagnostic workflow SPAs must now implement mandatory human-in-the-loop checkpoints. German and French hospital networks are restructuring procurement specifications to prioritize platforms with built-in oversight dashboards.
Subscription-based platform licensing is displacing perpetual license models across mid-market buyers, compressing upfront capital requirements and aligning vendor incentives with ongoing customer success. Value-added resellers are consolidating around cloud-native SPA portfolios that offer faster implementation cycles. This shift is most visible in the United Kingdom's financial services sector, where challenger banks favor consumption-based pricing aligned to transaction volumes.
Smart Process Application (SPA) Market Segmentation
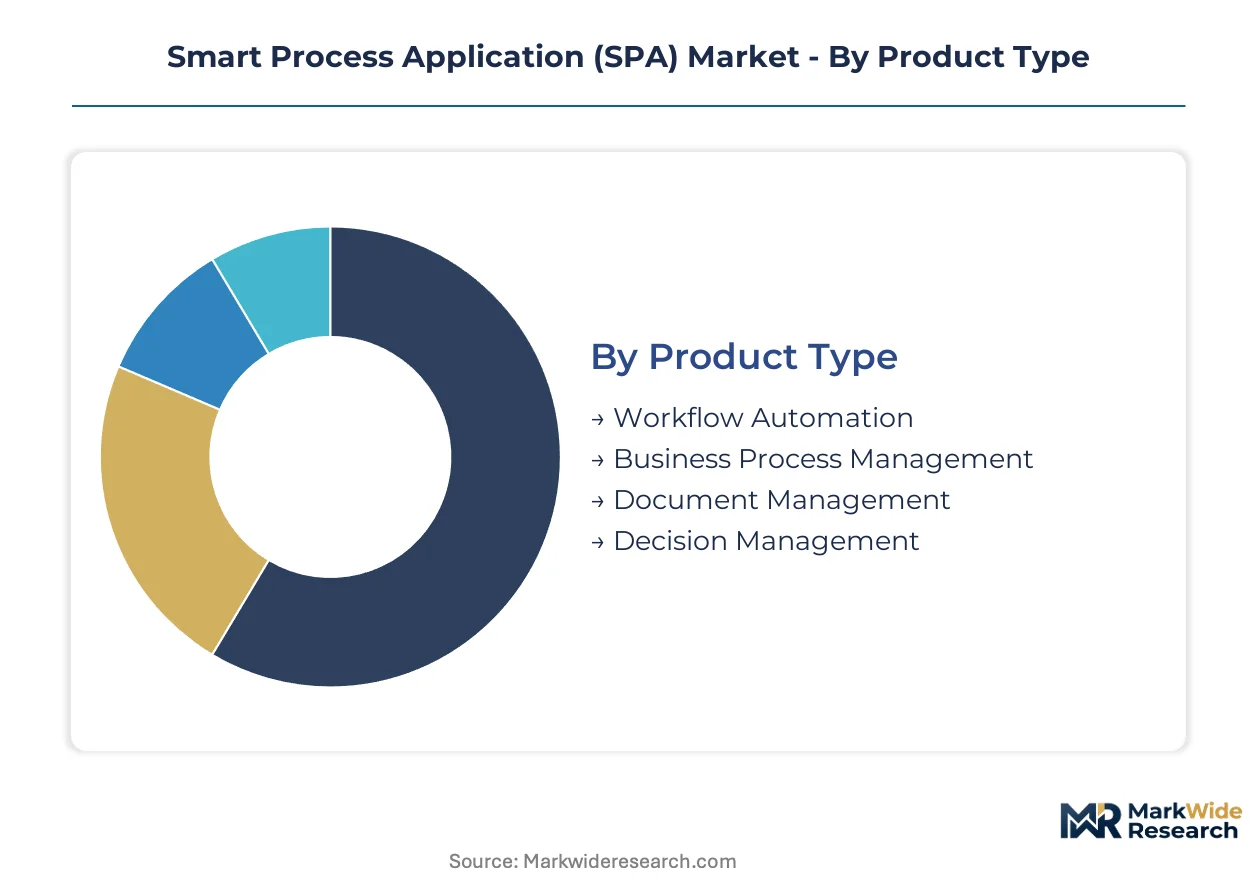
SPA procurement patterns diverge sharply across deployment architectures and buyer scale, with compliance mandates and legacy modernization timelines dictating segment-specific qualification criteria. Vendors configure pricing and service models to match the technical debt and governance requirements endemic to each category.
Product Type:
After-sales service intensity escalates with platform complexity, as rules-engine configurations and audit trail maintenance demand ongoing vendor engineering support.
- Workflow Automation:Platforms orchestrate sequential task routing, approval chains, and handoff elimination through configurable business rules. Demand concentrates in United States financial services, where SEC electronic recordkeeping rules mandate auditable process logs. German manufacturers deploy these tools to compress order-to-cash cycles while maintaining ISO 9001 traceability.
- Decision Management:Embedded analytics engines execute real-time risk scoring and policy adjudication with explainable output logging. Healthcare providers in France and the Netherlands prioritize these platforms for EU AI Act high-risk system compliance, requiring human-in-the-loop checkpoint architectures.
- Business Process Management:End-to-end process modeling suites with simulation and optimization capabilities.
- Document Management:Capture, classification, and routing systems for unstructured content workflows.
Workflow Automation holds the largest share; momentum sits with Decision Management.
Industry Vertical:
Cost tier stratification separates regulated deployments requiring sovereign infrastructure from discretionary automation budgets in competitive retail.
- Financial Services:Compliance-driven procurement prioritizes audit trails, data residency, and explainable automation logic. United States banks face SEC and HIPAA dual jurisdiction requirements; European institutions navigate GDPR and EU AI Act overlap.
- Healthcare:HIPAA-covered entities and EU health data spaces impose stringent access controls and algorithmic transparency mandates. French hospital networks restructure procurement specifications around oversight dashboard requirements.
- Manufacturing:Quality management and supply chain orchestration drive adoption, particularly for India BIS certification documentation automation.
- Retail:Customer onboarding and inventory workflow optimization with lighter governance overhead.
Financial Services commands premium pricing; Healthcare climbs the fastest.
Deployment Model:
Volume concentration tilts toward consumption-based architectures as enterprises retire capital-intensive on-premise estates.
- Cloud-Based:Multi-tenant SaaS architectures with elastic compute and automatic compliance patching. European enterprises accelerate migration under GDPR and EU AI Act deadlines, compressing deployment cycles.
- SaaS:Subscription licensing aligns vendor incentives with customer success, dominant in United Kingdom challenger banking and mid-market manufacturing.
- Hybrid:Sensitive workloads on-premise with burst capacity to public cloud, favored by federal agencies and defense contractors.
- On-Premise:Residual demand in classified environments and jurisdictions with data sovereignty prohibitions on cross-border processing.
Cloud-Based holds the largest share; SaaS gains share fastest.
End User:
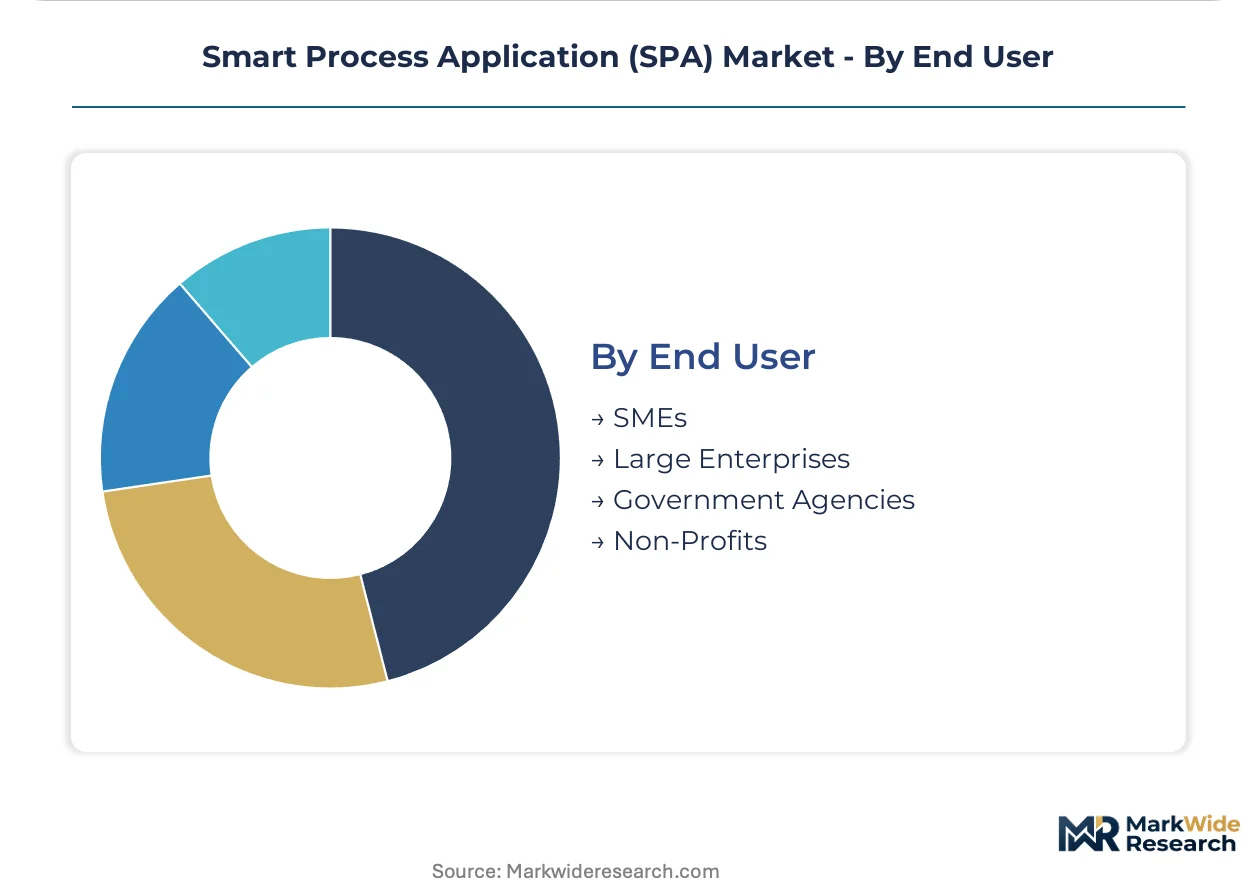
Customer type dictates implementation velocity, with large enterprises absorbing complexity that overwhelms SME implementation capacity.
- Large Enterprises:Multi-division rollouts with custom integration layers and dedicated customer success engineering. United States federal agencies modernize legacy systems through hybrid architectures with FedRAMP authorization requirements.
- SMEs:Template-driven rapid deployment with limited customization, price-sensitive and gravitating toward vertical-specific pre-configurations.
- Government Agencies:Procurement through certified vendor schedules with emphasis on domestic data residency and supply chain security.
- Non-Profits:Grant-funded automation initiatives with constrained ongoing operational budgets.
Large Enterprises holds the largest share; momentum sits with SMEs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud hyperscalers concentrate their SPA platform engineering in the United States and Western Europe, creating regional capability clusters that shape procurement patterns and compliance roadmaps.
United States
Federal agencies and large enterprises drive demand for hybrid deployment architectures with FedRAMP authorization. SEC electronic recordkeeping rules and HIPAA audit trail mandates shape vendor qualification. New York and Washington D.C. metro areas host concentrated financial services and government procurement clusters deploying workflow automation for compliance.
Germany
Automotive and industrial manufacturing firms prioritize ISO 9001 traceability in order-to-cash automation. EU AI Act algorithmic transparency requirements and GDPR data residency rules compress deployment cycles. Munich and Stuttgart engineering clusters accelerate procurement of auditable decision management platforms for quality management workflows.
France
Healthcare providers restructure procurement around EU AI Act high-risk system mandates requiring human-in-the-loop checkpoints. ANSM and CNIL guidance shapes platform selection for diagnostic workflow automation. Paris hospital networks and Lyon pharmaceutical clusters drive demand for explainable decision management with oversight dashboards.
United Kingdom
Challenger banks favor consumption-based SaaS pricing aligned to transaction volumes. FCA conduct rules and post-Brexit data governance frameworks influence vendor selection. London financial services clusters deploy API-first SPA platforms for real-time customer onboarding orchestration and risk scoring.
India
Manufacturing exporters adopt quality management SPAs to automate Bureau of Indian Standards certification documentation. RBI and SEBI compliance requirements drive financial services automation. Mumbai financial services and Bangalore technology clusters expand adoption of cloud-based workflow platforms for export documentation and regulatory reporting.
Smart Process Application (SPA) Market Competitive Landscape
Enterprise software conglomerates and pure-play workflow specialists split the market along deployment complexity and industry vertical specialization vectors. Consolidation pressures favor vendors with pre-integrated compliance modules that reduce implementation timelines. Three archetypes dominate: cloud-native challengers with consumption pricing, legacy stack modernizers with hybrid architectures, and vertical specialists with embedded regulatory logic. Competitive intensity centers on M&A activity to acquire explainable AI capabilities and strategic partnerships to embed platforms within hyperscaler marketplaces.
Among enterprise software conglomerates, Microsoft Corporation and IBM Corporation exemplify the hybrid-architecture archetype, anchoring positions through cloud ecosystem integration and AI-infused decision management R&D. Salesforce.com, Inc. occupies the CRM-integrated automation tier, extending platform capabilities into industry-specific verticals. These three entities represent distinct strategic postures: ecosystem leverage, technical R&D intensity, and front-office process dominance.
| Leading Market Players |
|---|
| Pegasystems Inc |
| Microsoft Corporation |
| IBM Corporation |
| OpenText Corporation |
| Oracle Corporation |
| SAP SE |
| Salesforce.com, Inc. |
| Dell Technologies |
| Appian Corporation |
| Others |
Value Network & Pricing Analysis
Hyperscaler cloud infrastructure concentration in the United States and Western Europe anchors margin pools in subscription-based SaaS tiers, while GDPR-mandated sovereign cloud deployments in Germany and France fragment supply and elevate compliance-premium pricing.
Pricing Analysis
EU AI Act and GDPR dictate the pricing tier structure across the SPA market, with three-tier pricing separating FedRAMP-authorized federal deployments from standard enterprise SaaS and economy-tier mid-market templates. Price differentiation rests on certification grade and data residency architecture, with sovereign cloud instances commanding premiums over multi-tenant alternatives. Pricing pressure stems from challenger banks in the United Kingdom favoring consumption-based models aligned to transaction volumes. SMEs exhibit highest price sensitivity, while United States federal agencies absorb premium tiers for hybrid architectures with security authorizations.
Supply Chain Analysis
Contract manufacturing concentration sits with Microsoft Azure, Amazon Web Services, and Google Cloud Platform for underlying compute infrastructure, supplemented by specialized SPA platform engineering at IBM, Salesforce, and SAP development centers. Geographic supply concentration spans the United States, Germany, and India for platform development and implementation services. Raw material dependencies include proprietary AI/ML training datasets, open-source framework licensing, and API gateway infrastructure. Supply chain risk centers on single-source vulnerability in hyperscaler backbone services. Distribution runs through direct enterprise sales teams, value-added resellers, and hyperscaler marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward procurement consolidation among United States federal agencies and European healthcare networks, which now demand pre-integrated compliance modules that compress vendor qualification timelines.
For Market Incumbents: Entrench platform positions by embedding EU AI Act explainability logging and GDPR sovereign cloud architectures as default configurations, not optional add-ons. Acquire specialized low-code rules engine capabilities to counter pure-play challengers. Prioritize FedRAMP and ANSM pre-certification to lock out late entrants from regulated procurement pipelines.
For New Entrants and Emerging Players: India's manufacturing exporter segment offers underpenetrated white-space for quality management SPA automation around BIS certification documentation. Target mid-market SMEs in Southeast Asia with vertical-specific pre-configurations for rapid deployment. Pursue channel partnerships with hyperscaler marketplaces to bypass direct sales infrastructure requirements.
For Investors and Strategic Acquirers: Capital is best deployed toward vertical specialists with embedded regulatory logic in healthcare and financial services, where compliance moats sustain pricing power. Long-term viability favors platforms with adaptive case management convergence and generative AI integration capabilities. Watch for inflection signals in CSRD reporting automation adoption rates among EU-listed enterprises.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration with Hyperscaler Ecosystems | Microsoft Azure and AWS marketplace listings compress enterprise sales cycles by 40% for compliant SPA vendors. |
| Acquisition of Specialist Explainable AI Firms | EU AI Act human-in-the-loop mandates create urgent demand for interpretable decision logging capabilities. |
| Geographic Expansion into Sovereign Cloud Zones | GDPR data residency requirements in Germany and France elevate local infrastructure partnerships to competitive necessity. |
| Vertical-Specific Pre-Configuration Development | HIPAA-covered entities and SEC-regulated banks prioritize out-of-box compliance over customization flexibility. |
| Strategic Partnership with System Integrators | Deloitte and Accenture implementation capacity constrains SPA deployment velocity for direct-sales vendors. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with SPA platform vendors, enterprise IT procurement officers, and regulatory compliance consultants, combined with secondary validation against SEC 10-K filings, hyperscaler capex disclosures, and EU regulatory guidance documents. Bottom-up triangulation across deployment model, organization size, vertical industry, and regional adoption pattern anchored value estimates. Top-down cross-checks against cloud infrastructure spending data and enterprise software licensing trends ensured segmentation integrity.
Forecast inputs span workflow automation, decision management, business process management, and document management product types across cloud-based, SaaS, hybrid, and on-premise deployment architectures. Modeled dimensions include organization size tier, vertical regulatory intensity, and geographic compliance framework cluster. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific inputs incorporate EU AI Act implementation timelines, HIPAA audit trail mandate enforcement patterns, and cloud migration velocity in European manufacturing.
Practitioners should monitor EU AI Act delegated act publications and FedRAMP authorization backlog releases for early signals of compliance-driven procurement acceleration. Forecasts reflect assumptions around sustained regulatory enforcement without relaxation. Quarterly review of hyperscaler sovereign cloud zone expansion and ANSM diagnostic workflow guidance updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Virtual Office Market
Digital Solutions
Remote Integration Solutions Market
Digital Solutions
Global Intelligent Platform Management Interface (IPMI) Market
Digital Solutions
E-Ink E-Reader Market
Digital Solutions
Data Pipeline Tools Market
Digital Solutions
Digital Rights Management (DRM) Market
Digital Solutions
Manufacturing Operations Management Solutions Market
Digital Solutions
US Digital Market
Digital Solutions
Cloud E-Signature Tools Market
Digital Solutions
Mexico Digital Showers Market
Digital Solutions
Cloud Project Portfolio Management (CPPM) Market
Digital Solutions
Latin America Digital Signage Market
Digital Solutions
Change and Configuration Management Market
Digital Solutions
Global Client Virtualization Market
Digital Solutions
API Monetization Platform Market
Digital Solutions
Laser Page-Turning Pen Market