
 Smart Signage Market | 2026-2036
Smart Signage Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Signage Market Analysis
Market Context
ISO 9241-307 ergonomic display certification is rotating the competitive field by filtering out suppliers unable to meet luminance uniformity and color consistency thresholds. Samsung Electronics leverages its semiconductor foundry capacity to captive-supply display driver ICs for its signage panels. LG Electronics anchors its position through dominant share in OLED commercial panels for high-end retail installations.
Technical Definition and Structural Segments
Smart signage denotes networked electronic display systems that integrate media players, content management software, and environmental sensors to deliver dynamically updatable visual communication in commercial and public spaces, typically operating at brightness levels exceeding 500 nits for daylight visibility. The technology segment shows cloud-based solutions pulling ahead as retailers abandon on-premise servers for centralized content orchestration, while LED signs command premium positioning in outdoor installations where durability and energy efficiency determine total cost of ownership. Interactive displays within the product type category are gaining traction in transportation hubs where wayfinding and real-time service updates require passenger input.
Regulatory Frame and Outlook
The Federal Communications Commission governs electromagnetic emissions from networked signage hardware in the United States, while the EU's RoHS and REACH frameworks restrict hazardous substances in display manufacturing and mandate recyclability disclosures. China's Ministry of Industry and Information Technology enforces GB energy efficiency standards that dictate maximum power draw for commercial screens deployed in government buildings and transit infrastructure. Stakeholders must monitor evolving e-waste regulations across multiple jurisdictions as display replacement cycles compress and panel disposal volumes escalate.
Market Dynamics
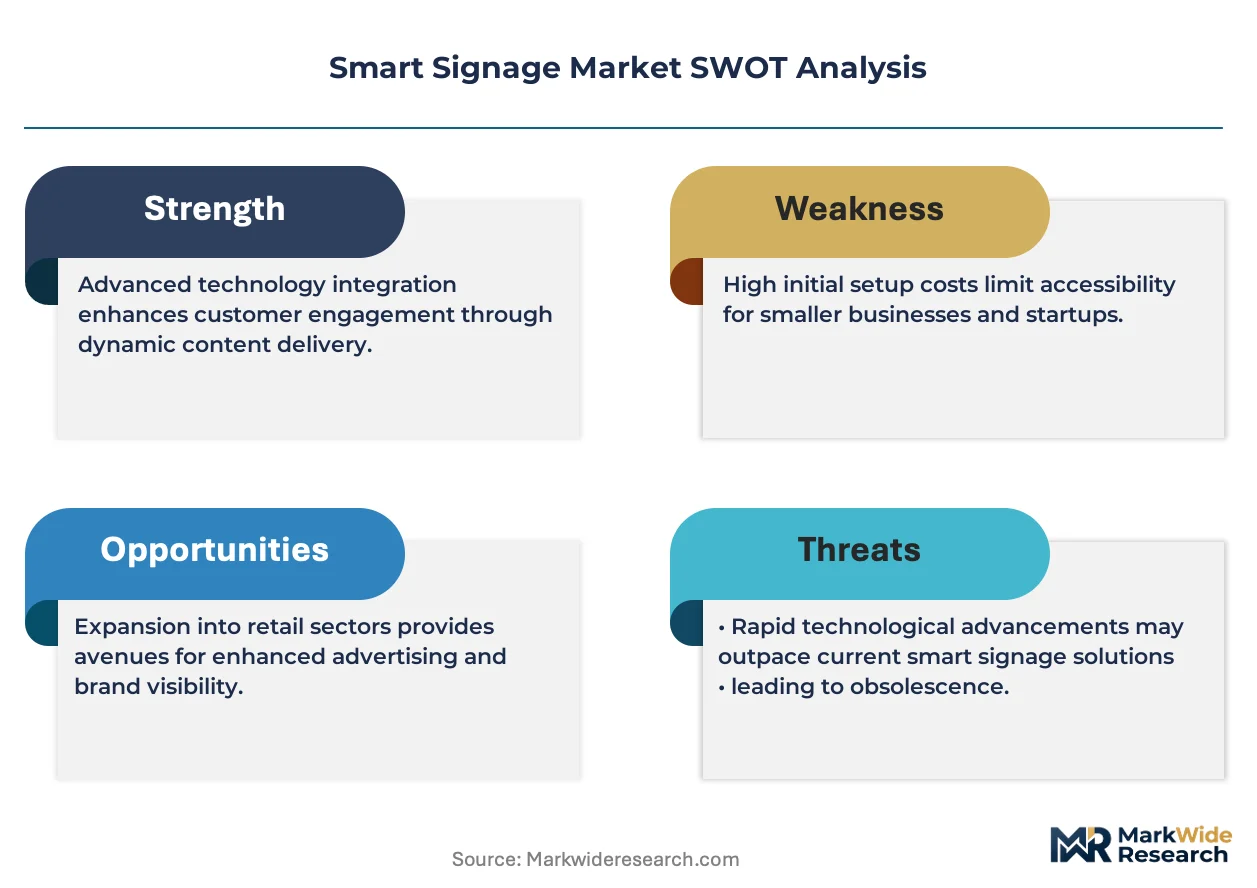
Cloud-based content management architectures are collapsing the traditional on-premise server infrastructure, forcing hardware suppliers to pivot toward software-recurring revenue models and sensor-integrated edge computing platforms.
Growth Catalysts
- EU Ecodesign Directive:Mandates for lower-power display technologies are accelerating LED and OLED adoption in commercial installations across member states, compressing payback periods for energy-efficient retrofits.
- Transportation infrastructure digitization:Subway systems in Shanghai, Beijing, and Guangzhou are deploying interactive wayfinding networks that integrate real-time service data with passenger input capabilities.
- Edge AI processing:On-chip inference engines enable localized audience analytics without cloud latency, unlocking dynamic content triggering based on demographic detection.
Market Restraints
- Display driver IC supply concentration:Foundry capacity constraints in Taiwan and South Korea create bottlenecks for high-brightness panel production, extending lead times for outdoor-rated installations.
- GB energy efficiency ceilings:China's MIIT power-draw limits for government-deployed screens restrict brightness levels in transit applications, forcing performance trade-offs in sunlit environments.
- Direct-view LED cost structure:MicroLED pixel pitch scaling requires precision transfer equipment that inflates capital intensity for fine-pitch indoor applications.
Strategic Opportunities
- India's smart city mandates:Municipal digital infrastructure programs in tier-two urban centers remain underpenetrated for networked display deployment, creating first-mover positioning for integrated solution providers.
- Healthcare wayfinding convergence:Hospital systems are merging digital signage with patient flow management and appointment synchronization, opening vertical-specific software stacks.
- Solar-powered off-grid installations:Photovoltaic-integrated displays with battery storage enable deployment in remote retail and outdoor advertising locations lacking grid connectivity.
Industry Challenges
- ISO 9241-307 certification timelines:Luminance uniformity testing protocols extend product validation cycles, compressing launch windows for seasonal retail deployment schedules.
- Legacy CMS integration friction:Retail chains with entrenched on-premise content systems face data migration complexity when transitioning to cloud-orchestrated architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Signage Market |
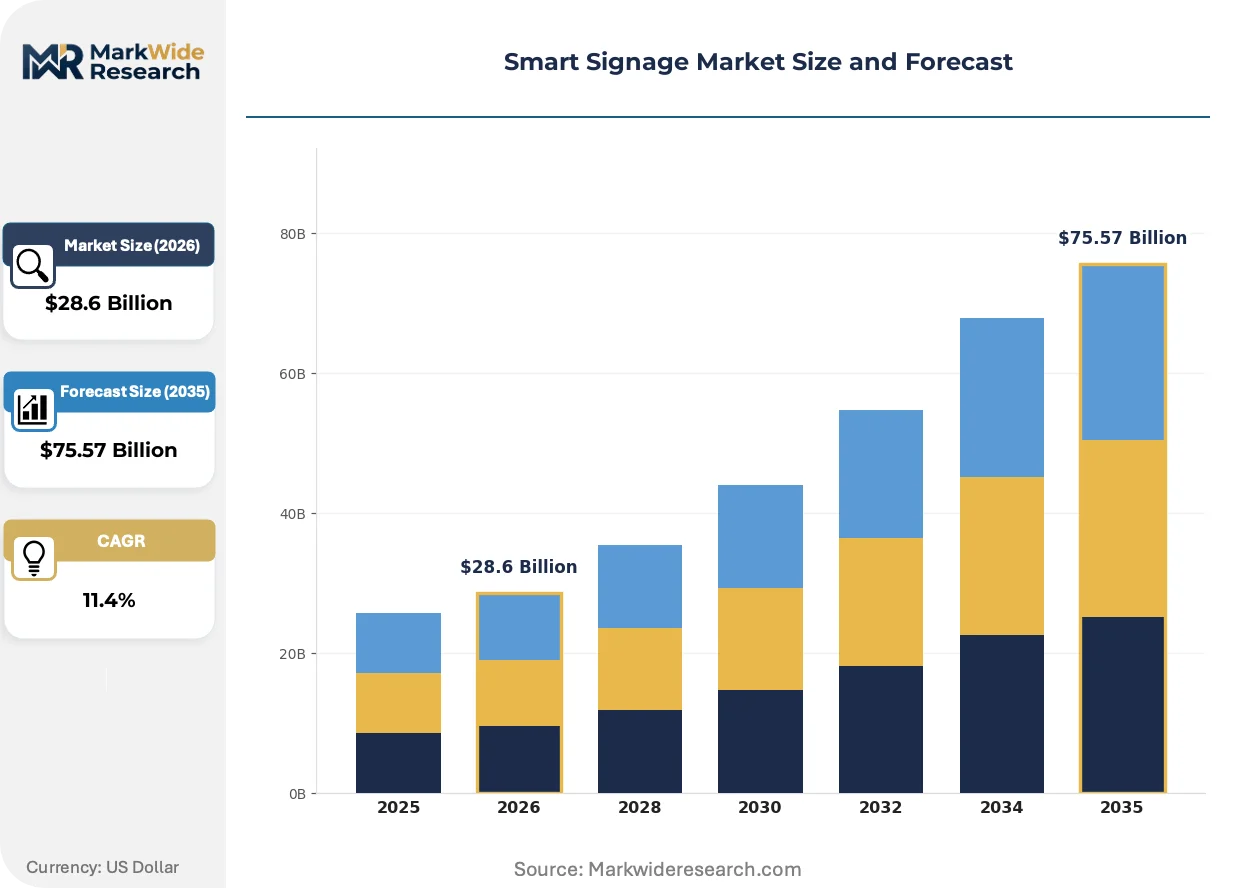
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Displays, LED Signs, LCD Screens, Projection Systems Technology: Interactive Displays, Touchscreen Technology, Cloud-based Solutions, Internet of Things End User: Retail Stores, Transportation Hubs, Educational Institutions, Corporate Offices Installation: Wall-mounted, Freestanding, Integrated, Outdoor |
| Companies Covered | Sony Corporation, BrightSign, Samsung Electronics, Scala, SpinetiX, LG Electronics, NEC Corporation, Xibo Signage, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Signage Market Emerging Trajectories
Hardware-software decoupling is fragmenting the vendor landscape as specialized software platforms capture margin previously retained by integrated equipment manufacturers.
MicroLED display technology is decomposing the traditional LCD backlight assembly into self-emitting pixel arrays that eliminate optical stack thickness and viewing angle degradation. Luxury retail brands in Dubai and Singapore are piloting transparent microLED storefront installations that maintain glass transparency while displaying dynamic content. This architecture is decomposing the distinction between architectural glass and display surface, enabling new spatial design vocabularies in flagship environments.
REACH substance restrictions are compelling manufacturers to reformulate solder alloys and eliminate cadmium-based quantum dot phosphors from production lines. The industrial consequence cascades through component sourcing, requiring qualification of alternative rare-earth dopants for color gamut maintenance. Outdoor LED module suppliers serving European stadium and transit markets are accelerating RoHS-compliant supply chain audits to preempt enforcement actions.
Retailers are unbundling content creation from hardware procurement, contracting specialized agencies for dynamic creative production while treating displays as commoditized infrastructure. This pattern concentrates buying power among procurement functions that prioritize total cost of ownership over brand loyalty to legacy suppliers. The shift is most visible in North American quick-service restaurant chains, where franchisee cooperatives negotiate centralized content subscriptions independent of screen vendor selection.
Smart Signage Market Segmentation
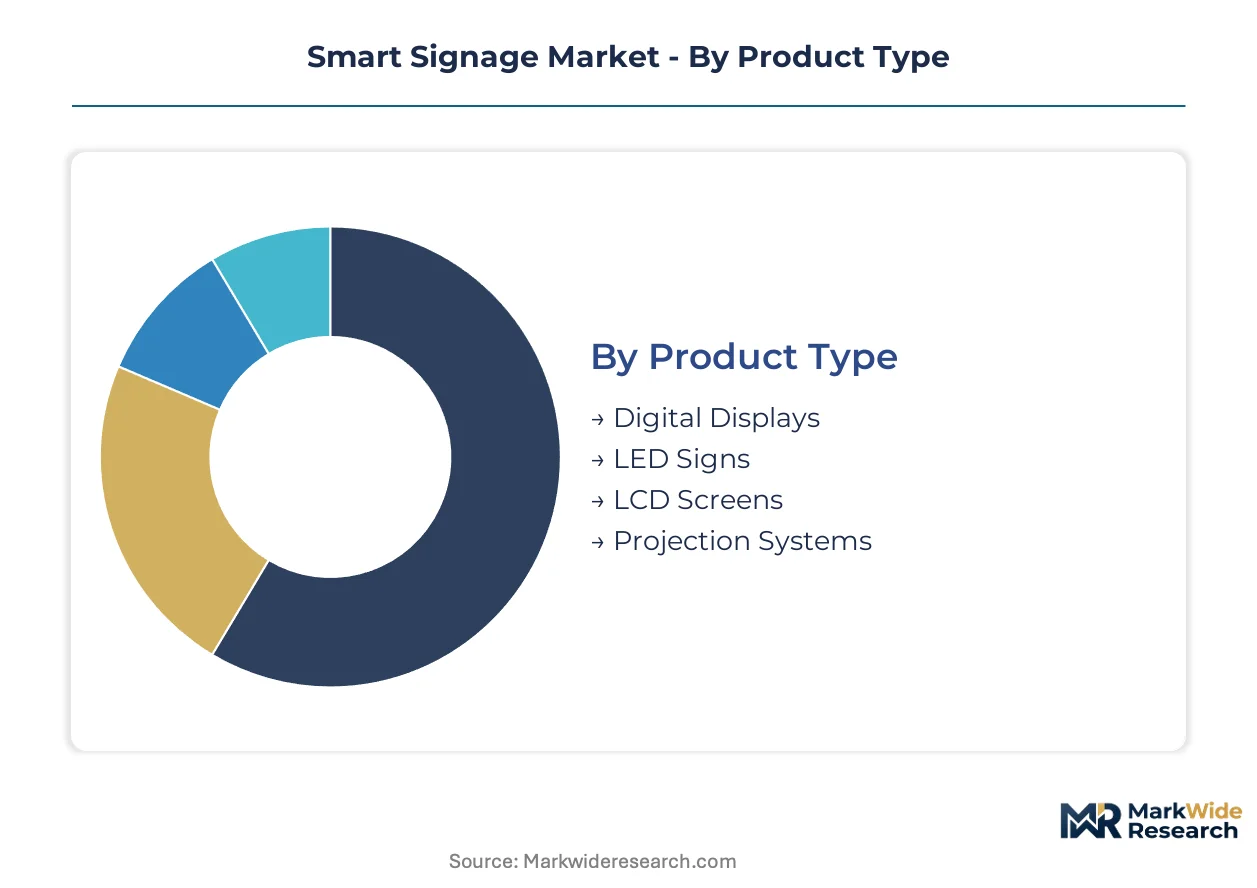
Smart signage procurement patterns diverge sharply across deployment contexts, with regulatory compliance thresholds and environmental durability requirements filtering supplier eligibility before price negotiations begin. Understanding these segment boundaries clarifies where technology substitution accelerates versus where legacy architectures persist.
Product Type:
REACH substance restrictions and EU Ecodesign Directive power ceilings are segmenting supplier capabilities, with RoHS-compliant manufacturers capturing European transit and retail contracts while non-compliant vendors retreat to less regulated geographies.
- Digital Displays:Network-connected flat-panel systems integrating media players and content management software for centralized update control. Demand concentrates in China's tier-one cities where subway systems and shopping districts are undergoing massive screen installation programs, with MIIT GB energy efficiency standards dictating maximum power draw for government building deployments.
- LED Signs:Direct-view LED arrays operating without backlight assemblies, achieving brightness levels exceeding 5000 nits for daylight visibility. North American retail chains are expanding digital screen networks for personalized promotions, drawn by durability and energy efficiency advantages that compress total cost of ownership payback periods.
- LCD Screens:Liquid crystal panels with edge-lit or full-array LED backlighting, dominating indoor commercial applications where cost sensitivity outweighs brightness requirements. ISO 9241-307 ergonomic certification filters out suppliers unable to meet luminance uniformity thresholds.
- Projection Systems:Laser or lamp-based image projection onto dedicated surfaces, retaining niche positioning in temporary installations and large-venue applications where display surface scale exceeds economical panel dimensions.
Established volume favors LCD Screens; emerging adoption favors LED Signs.
Technology:
Customer procurement is shifting toward recurring software revenue models as cloud architectures displace on-premise server infrastructure, collapsing traditional hardware margin capture.
- Interactive Displays:Sensor-integrated panels enabling passenger or shopper input for wayfinding, ordering, and information retrieval. Transportation infrastructure digitization in Shanghai, Beijing, and Guangzhou subway systems is deploying interactive wayfinding networks that integrate real-time service data with passenger input capabilities.
- Touchscreen Technology:Capacitive or infrared touch overlay systems supporting multi-point gesture recognition. Edge AI processing with on-chip inference engines enables localized audience analytics without cloud latency, unlocking dynamic content triggering based on demographic detection.
- Cloud-based Solutions:Centralized content orchestration platforms eliminating on-premise server dependencies. Cloud-based content management architectures are forcing hardware suppliers to pivot toward software-recurring revenue models.
- Internet of Things:Sensor-networked displays integrating environmental monitoring, occupancy detection, and predictive maintenance signaling. FCC electromagnetic emissions governance applies to networked signage hardware in the United States.
Hardware-centric procurement favors Touchscreen Technology; service-revenue expansion favors Cloud-based Solutions.
End User:
Vertical-specific compliance requirements and replacement cycle timing are concentrating supplier specialization, with healthcare and transit applications demanding distinct certification portfolios.
- Retail Stores:In-store digital promotion networks and interactive product discovery installations. Retailers are unbundling content creation from hardware procurement, contracting specialized agencies for dynamic creative production.
- Transportation Hubs:Wayfinding, service update, and advertising displays in airports, rail stations, and bus terminals. Interactive displays are gaining traction where wayfinding and real-time service updates require passenger input.
- Educational Institutions:Campus-wide communication networks and classroom collaboration displays. Procurement prioritizes total cost of ownership over brand loyalty to legacy suppliers.
- Corporate Offices:Meeting room scheduling, lobby messaging, and internal communication systems. Cloud-based solutions are pulling ahead as organizations abandon on-premise servers.
Replacement cycle compression favors Retail Stores; infrastructure digitization mandates favor Transportation Hubs.
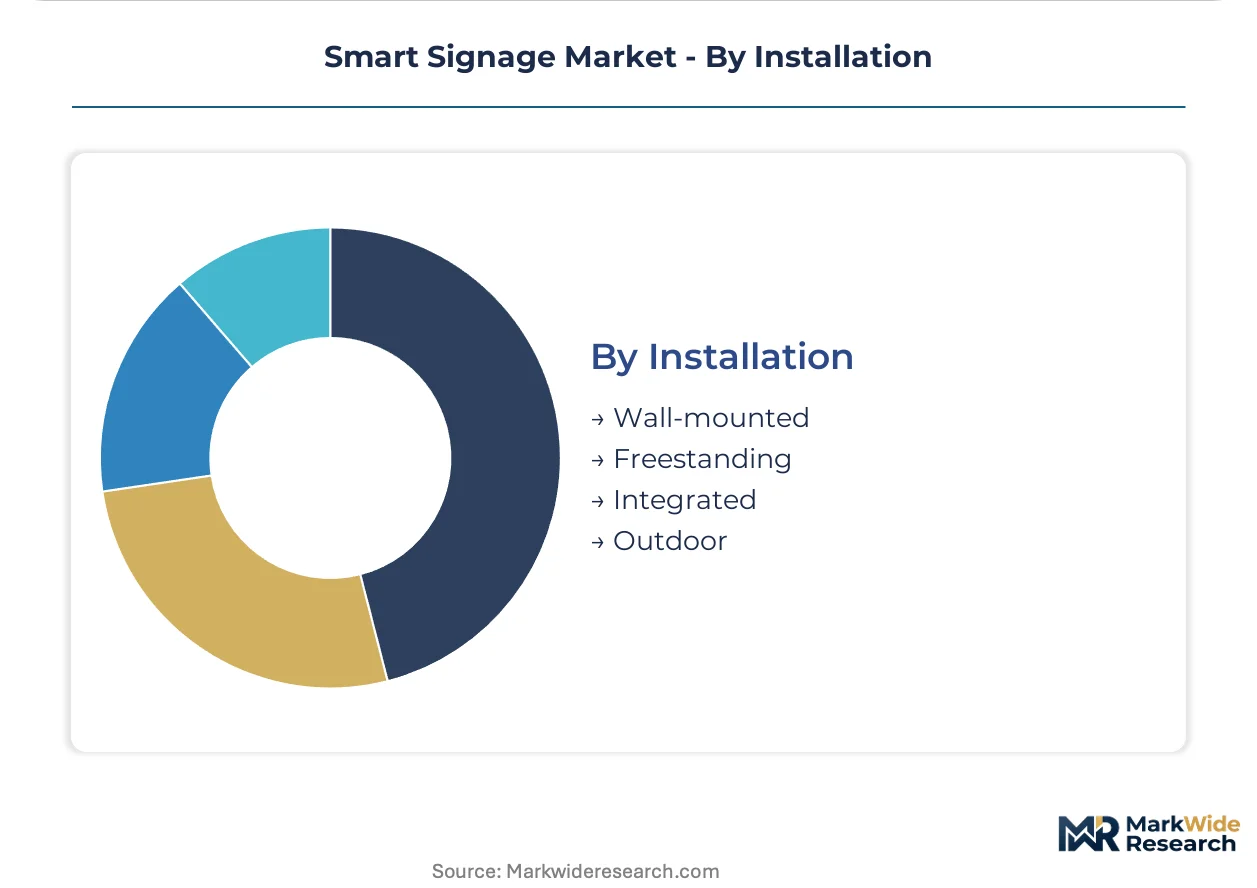
Installation:
Environmental exposure ratings and structural mounting requirements are bifurcating supplier capabilities between climate-controlled indoor and weather-hardened outdoor specializations.
- Wall-mounted:Fixed bracket installations optimizing floor space in retail and corporate environments. Indoor applications where climate control eliminates weatherproofing premiums.
- Freestanding:Kiosk and totem structures enabling repositioning and floor-plan flexibility. Quick-service restaurant chains deploy centralized content subscriptions independent of screen vendor selection.
- Integrated:Architectural embedding within walls, furniture, or fixtures for seamless spatial design. Luxury retail brands pilot transparent microLED storefront installations that maintain glass transparency.
- Outdoor:Weather-sealed enclosures with thermal management and vandal resistance for street-facing and transit applications. LED signs command premium positioning where durability and energy efficiency determine total cost of ownership.
Volume concentration favors Wall-mounted; margin expansion favors Outdoor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Ecodesign Directive's power consumption mandates are accelerating LED and OLED retrofits across member states, while China's MIIT enforces GB energy efficiency standards that dictate maximum power draw for government and transit deployments.
United States
Retail chains are expanding digital screen networks for personalized promotions across quick-service restaurants and big-box formats. The FCC governs electromagnetic emissions from networked signage hardware, creating compliance thresholds for media player integration. Deployment concentrates in New York Metro and Los Angeles, where subway systems and shopping districts are undergoing massive screen installation programs.
China
Subway systems in Shanghai, Beijing, and Guangzhou are deploying interactive wayfinding networks that integrate real-time service data with passenger input capabilities. MIIT enforces GB energy efficiency standards that restrict brightness levels in sunlit transit applications. Tier-one cities are driving demand concentration as shopping districts undergo massive screen installation programs.
Germany
Industrial machinery suppliers and automotive showrooms are digitizing customer-facing communication infrastructure. REACH and RoHS frameworks restrict hazardous substances in display manufacturing and mandate recyclability disclosures. The Ruhr industrial corridor and Bavaria host concentrated deployment of energy-efficient commercial panels in manufacturing facilities and exhibition centers.
Japan
Transportation hubs and corporate offices are migrating toward cloud-orchestrated content management architectures. METI oversees industrial standards that influence procurement specifications for networked display systems. Tokyo and Osaka anchor demand for high-brightness panels in rail stations and flagship retail environments.
India
Municipal digital infrastructure programs in tier-two urban centers remain underpenetrated for networked display deployment. The country's national electronics regulator enforces import certification requirements for commercial screen hardware. Maharashtra and Karnataka are emerging as early deployment zones for smart city mandates in transit and public information systems.
Smart Signage Market Vendor Landscape
Player mix skews toward diversified electronics conglomerates with captive semiconductor and display panel capabilities. Market structure concentrates around vertically integrated manufacturers that control upstream component supply and downstream system integration. Three archetypes dominate: semiconductor-foundry-linked display makers, specialized commercial AV integrators, and software-centric platform providers. Competitive moves center on backward integration into display driver IC supply and geographic expansion into underpenetrated municipal infrastructure markets.
Within the diversified electronics tier, Samsung Electronics and LG Electronics exemplify the vertically integrated model with captive display panel and semiconductor capabilities. Sony Corporation and Panasonic Corporation occupy positions as precision electronics specialists with heritage in broadcast and professional imaging equipment. NEC Corporation represents the commercial infrastructure archetype with entrenched positioning in transportation and public sector deployments. These anchors illustrate how competitive positioning depends on upstream control over critical components versus downstream software and service integration.
| Leading Market Players |
|---|
| Sony Corporation |
| BrightSign |
| Samsung Electronics |
| Scala |
| SpinetiX |
| LG Electronics |
| NEC Corporation |
| Xibo Signage |
| Panasonic Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts with Taiwan-based foundries lock in display driver IC supply visibility while capping price volatility for high-brightness panel procurement. These arrangements bind North American retail chains and European transit authorities to fixed-volume commitments that trade flexibility for cost predictability across multi-year deployment cycles.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ISO 9241-307-compliant panels commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects luminance uniformity testing investment and after-sales service bundling. Cost compression in economy LCD segments is intensifying because Chinese manufacturers are flooding tier-one city transit markets with GB-standard-compliant but non-ISO-certified alternatives. Quick-service restaurant franchisee cooperatives exhibit highest price sensitivity, while luxury retail flagship installations remain least sensitive due to architectural integration requirements.
Supply Chain Analysis
Strategic stockpiling of display driver ICs dominates inventory strategy as foundry capacity constraints in Taiwan and South Korea extend lead time uncertainty for outdoor-rated installations. Panel assembly concentrates in China, South Korea, and Taiwan, with Mexico emerging as a near-shore final integration hub for North American retail deployments. Supply chains draw from gallium nitride substrates, rare-earth phosphors, and precision transfer equipment for MicroLED scaling. Single-source vulnerability around Taiwan Semiconductor Manufacturing capacity creates structural risk for high-brightness outdoor LED module procurement. Distribution runs through commercial AV integrators and direct OEM relationships with large-format retail and transit authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around procurement functions at North American quick-service restaurant cooperatives and Chinese municipal transit authorities, fragmenting vendor pricing leverage across standardized hardware categories.
For Market Incumbents: Shield software-recurring revenue streams by accelerating cloud-based content management platform development before hardware margins collapse further. Prioritize backward integration into display driver IC supply through foundry partnerships or captive semiconductor capacity to mitigate Taiwan supply concentration. Defend against emerging software-centric platform providers by bundling sensor-integrated edge computing capabilities with legacy hardware installations. For New Entrants and Emerging Players: Anchor in India's tier-two smart city mandates where municipal digital infrastructure programs remain underpenetrated for integrated solution deployment. Target healthcare wayfinding convergence as the most penetrable vertical, where hospital systems seek patient flow management synchronization without entrenched incumbent relationships. Pursue solar-powered off-grid installation segments through photovoltaic-integrated display development for remote retail and outdoor advertising locations lacking grid connectivity. For Investors and Strategic Acquirers: The market sits at a hardware-software decoupling phase that favors software-centric platform providers with recurring revenue visibility over capital-intensive panel manufacturers. Long-term viability across the projection horizon rests on cloud-orchestrated content management architectures rather than commoditized display hardware production. Acquisition target archetype: specialized commercial AV integrators with entrenched transportation and public sector relationships. Monitor cloud-based solution adoption rates in North American retail chains as the primary inflection indicator for margin structure transformation.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Integration | Enables recurring SaaS revenue capture as retailers abandon on-premise server infrastructure. |
| Display Driver IC Backward Integration | Secures captive semiconductor supply against Taiwan foundry capacity constraints. |
| ISO 9241-307 Certification Investment | Filters out non-compliant competitors from European transit and healthcare procurement. |
| Healthcare Wayfinding Partnership | Opens vertical-specific software stacks merging patient flow with appointment synchronization. |
| India Smart City Geographic Expansion | Captures first-mover positioning in tier-two municipal digital infrastructure programs. |
Methodological Framework
Initial hypotheses were tested against primary input from display hardware procurement managers, cloud content management platform engineers, transit authority technology directors, and commercial AV integration specialists and refined through secondary validation. Analysis combined structured interviews with secondary sources including FCC electromagnetic emissions filings, EU Ecodesign Directive implementation reports, MIIT GB standard documentation, and SEC disclosures from diversified electronics conglomerates. Bottom-up unit deployment estimates triangulated against top-down market sizing from foundry capacity and panel shipment data.
Variance decomposition across product type, technology architecture, end-user vertical, and installation environment shaped the analytical framework. Segmentation dimensions modeled include hardware category, deployment model, organizational scale, regulatory compliance tier, and regional adoption pattern. CAGRs were derived from installed base growth rates and replacement cycle compression dynamics. Forecast inputs incorporated cloud migration velocity in retail and edge AI processing adoption in transportation infrastructure.
Decision-makers should treat outputs as directional under assumptions of continued cloud architecture displacement and stable foundry capacity expansion; material deviation would warrant model refresh. Specific risk factors include abrupt Taiwan semiconductor supply disruption, accelerated EU e-waste regulation enforcement, and Chinese municipal budget contraction affecting tier-one transit deployment schedules. Revision becomes warranted when cloud-based solution penetration in North American retail crosses threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
South Korea Cloud OSS BSS Market
Digital Solutions
Singapore System Integration Market
Digital Solutions
Healthcare Video Conferencing Solutions Market
Digital Solutions
Product As a Service Market
Digital Solutions
Cloud MFT Services Market
Digital Solutions
Weather Information Technologies Market
Digital Solutions
Route Optimization Software Market
Digital Solutions
Europe Digital Twin Market
Digital Solutions
End User Experience Monitoring (EUEM) Market
Digital Solutions
India Loyalty Program Market
Digital Solutions
Europe Smart Card Market
Digital Solutions
Consent Management Market
Digital Solutions
Hyperlocal Services Market
Digital Solutions
Incidence Management Software Market
Digital Solutions
Contact Tracing Application Market
Digital Solutions
Global Sharing Economy Market