
 Enterprise Mobility in Manufacturing Market | 2026-2036
Enterprise Mobility in Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Mobility in Manufacturing Market Foresight
Asset-light leasing models for rugged mobile hardware and managed mobility services is tilting competitive dynamics toward platform providers with financing flexibility. Microsoft Corporation leverages its Azure cloud backbone to bundle device management with predictive analytics subscriptions. SAP SE anchors its position through deep ERP integration that locks manufacturing clients into mobility workflows. VMware competes by extending virtualization security protocols to edge devices across distributed shop floors.
Enterprise mobility in manufacturing encompasses the deployment of connected devices, applications, and backend systems that enable real-time data capture, workforce coordination, and equipment monitoring across production environments, typically operating over 4G/5G private networks with sub-50ms latency requirements for mission-critical control loops. Its primary industrial purpose is to collapse information delays between factory-floor operations and enterprise planning systems. Mobile Device Management currently dominates technology spending as manufacturers grapple with fleet security for thousands of heterogeneous endpoints. Cloud Computing deployment models are capturing the fastest expansion as Tier-1 suppliers abandon capital-intensive on-premise infrastructure. Workforce Management applications concentrate margin pools where biometric authentication and geofenced compliance command premium pricing.
OSHA lockout/tagout digitization mandates and FCC Part 90 private spectrum allocations for industrial 5G are reshaping how mobility vendors certify devices for hazardous environments. NIST SP 800-207 zero-trust architecture requirements are forcing segmentation between operational technology and enterprise mobility backbones. Stakeholders must weigh sovereign data residency rules against cloud-native platform agility when architecting cross-border manufacturing networks.
Market Dynamics
Private 5G spectrum allocations and zero-trust security mandates are compressing deployment timelines for connected factory-floor mobility platforms. Manufacturers must now integrate operational technology segmentation with enterprise mobility backbones under tightened cybersecurity frameworks.
Growth Catalysts
- OSHA lockout/tagout digitization:US manufacturing facilities face mandates to replace paper-based safety protocols with mobile-enabled digital verification, forcing fleet-wide rugged device rollouts.
- Industrie 4.0 smart manufacturing corridors:Germany's federal manufacturing digitization incentives concentrate demand for integrated workforce mobility platforms in automotive and precision engineering clusters.
- Edge-native AI inference:On-device machine learning for predictive maintenance is pulling GPU-enabled mobile hardware onto assembly lines previously served by cloud-tethered tablets.
Market Restraints
- Semiconductor supply concentration:Rugged mobile device production depends on specialized industrial-grade chipsets sourced primarily from Taiwanese foundries, exposing procurement to geopolitical disruption.
- NIST SP 800-207 compliance costs:Zero-trust architecture mandates impose segmentation infrastructure investments that Tier-2 and Tier-3 manufacturers struggle to absorb without managed service intermediation.
- Private 5G spectrum scarcity:FCC Part 90 industrial spectrum allocations remain limited in key US manufacturing belts, constraining latency-sensitive control-loop applications.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Contract manufacturers establishing mobile device assembly capacity under production-linked incentives create localized rugged hardware supply for regional industrial mobility deployments.
- Convergence of digital twin and AR-assisted maintenance:Overlaying real-time equipment telemetry with spatial computing on mobile headsets opens premium service tiers in aerospace and semiconductor fabrication.
- EU CSRD sustainability reporting mandates:Scope 3 emissions tracking requirements are driving demand for mobile-enabled supply chain visibility tools across European automotive OEM networks.
Industry Challenges
- OT-IT convergence skill scarcity:Manufacturing mobility deployments require personnel fluent in both operational technology protocols and enterprise security frameworks, a combination rarely found in existing workforce pools.
- Legacy MES integration complexity:Decades-old manufacturing execution systems with proprietary data formats resist API-based connectivity to modern mobile platforms, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Mobility in Manufacturing Market |
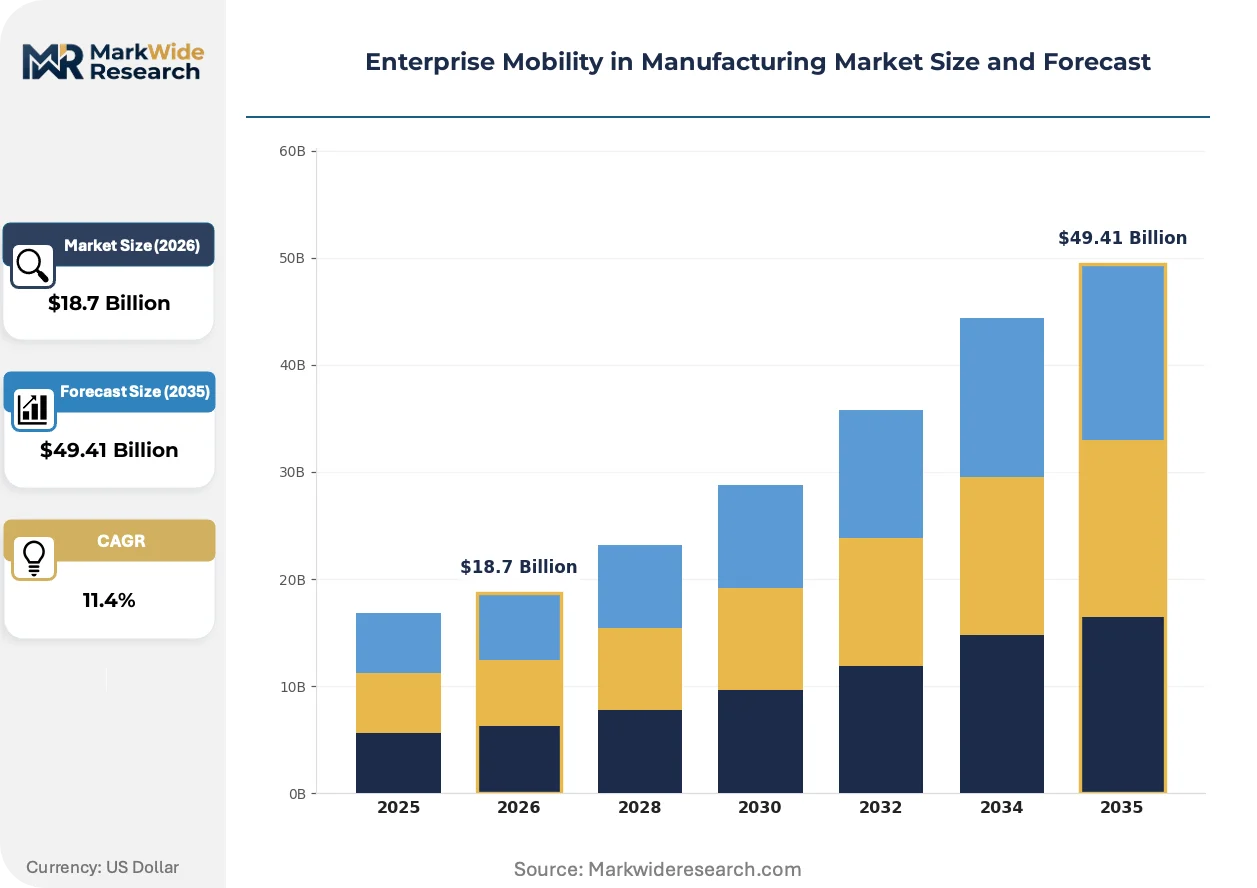
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Mobile Device Management, IoT Solutions, Cloud Computing, Augmented Reality Application: Inventory Management, Production Tracking, Quality Control, Workforce Management End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Equipment Manufacturers Deployment: On-Premise, Cloud-Based, Hybrid, Mobile-First Strategy |
| Companies Covered | IBM Corporation, Microsoft Corporation, SAP SE, Cisco, Citrix Systems, Oracle, VMware, Blackberry, Dell Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Mobility in Manufacturing Market Shifts & Advancements
Containerized application delivery and sovereign cloud architectures are fragmenting how mobility platforms get deployed across multinational manufacturing footprints. Vendors now compete on edge orchestration capabilities rather than device hardware specifications alone.
Cloud-native mobile device management platforms are rendering obsolete on-premise MDM appliances that required dedicated infrastructure teams and multi-week patch cycles. Automotive OEMs in Stuttgart and Wolfsburg have shifted to Azure-based fleet orchestration, collapsing provisioning time from days to minutes. This compression is eliminating regional systems integrators who previously monetized deployment complexity.
EU AI Act risk classification requirements are forcing mobility vendors to document algorithmic decision-making in workforce management applications. Manufacturers deploying biometric authentication or predictive scheduling now face conformity assessment obligations for high-risk AI systems. German automotive suppliers are front-loading compliance investments ahead of enforcement timelines, creating first-mover certification advantages.
Subscription-based hardware-as-a-service models are displacing capital purchase cycles for rugged mobility fleets. Industrial buyers in Japan's Kanto manufacturing belt now prioritize per-device monthly rates that bundle insurance, refresh guarantees, and predictive analytics. This preference shift favors platform providers with captive financing arms over pure hardware OEMs.
Enterprise Mobility in Manufacturing Market Segmentation
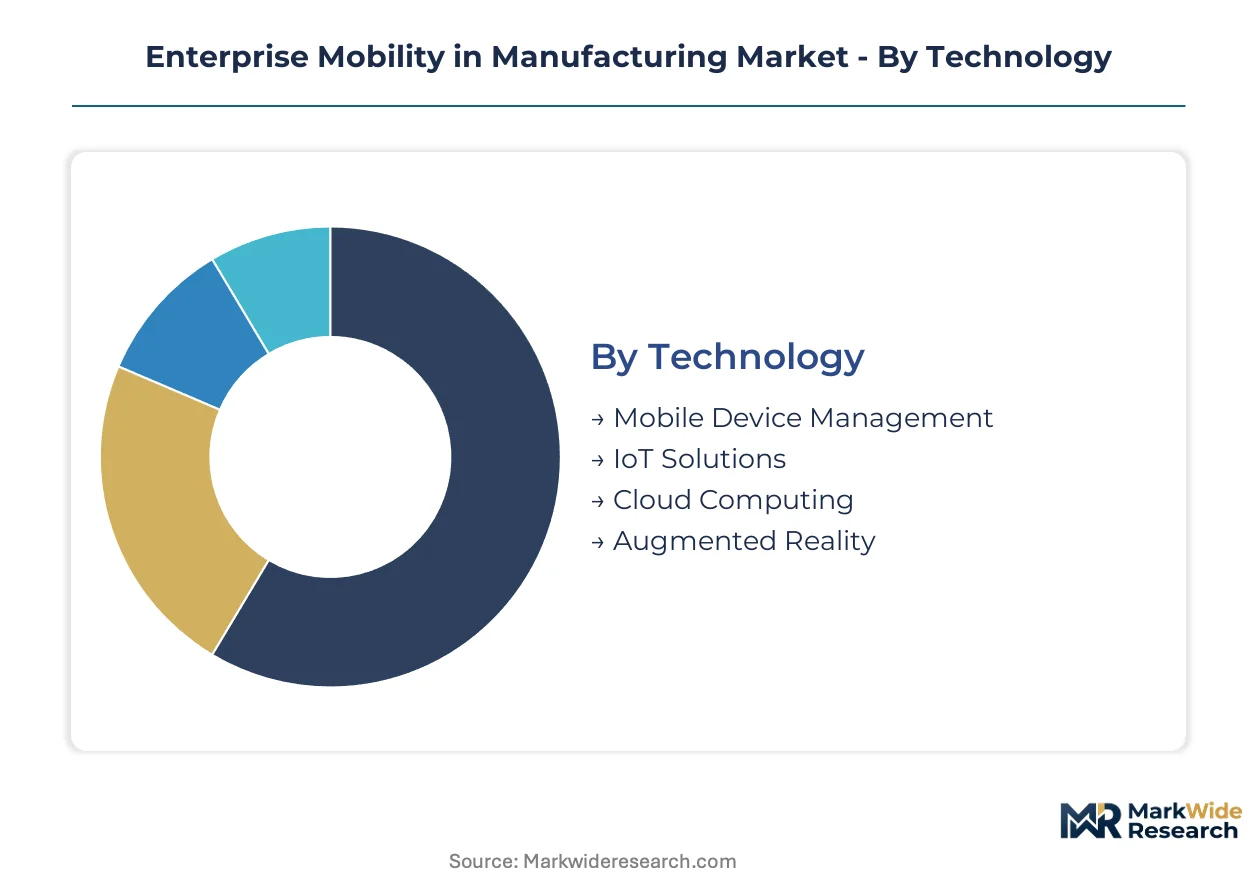
Enterprise mobility in manufacturing fragments across technology layers, operational use cases, and customer archetypes with sharply diverging service requirements. Each segment demands distinct integration depth, security postures, and financing structures that reshape vendor economics.
Technology:
After-sales service intensity varies dramatically across technology segments, with ongoing security patching and compliance updates determining lifetime value capture.
- Mobile Device Management:Centralized endpoint orchestration platforms enforce policy compliance across heterogeneous rugged device fleets. German automotive OEMs in Stuttgart and Wolfsburg currently concentrate procurement here, driven by NIST SP 800-207 zero-trust mandates requiring continuous posture verification.
- Cloud Computing:Scalable backend infrastructure delivers predictive analytics and cross-facility data synchronization without capital-intensive server deployments. Tier-1 suppliers in Japan's Kanto manufacturing belt are migrating fastest, abandoning on-premise appliances for Azure-based subscription models that collapse provisioning cycles.
- IoT Solutions:Sensor-to-cloud pipelines enabling real-time equipment telemetry and condition monitoring across distributed assets.
- Augmented Reality:Spatial computing overlays for assembly guidance and remote expert assistance on industrial headsets.
By volume, Mobile Device Management leads. By growth pace, Cloud Computing is expanding most quickly.
Application:
Application segments stratify by integration complexity with legacy manufacturing execution systems, determining implementation timelines and professional services attach rates.
- Workforce Management:Biometric authentication, geofenced compliance tracking, and predictive scheduling optimize labor allocation across shift patterns. Aerospace and semiconductor fabrication facilities in the US and Germany command premium pricing here, compelled by OSHA digitization mandates and EU AI Act conformity assessments for algorithmic decision systems.
- Production Tracking:Real-time work-in-progress visibility and bottleneck identification through mobile-enabled shop-floor data capture. India's electronics contract manufacturers under PLI scheme incentives are deploying fastest, seeking to demonstrate operational efficiency to anchor OEM partnerships.
- Inventory Management:Barcode and RFID-enabled stock visibility across warehouse and production line locations.
- Quality Control:Mobile inspection workflows with photographic documentation and statistical process control integration.
Workforce Management captures the highest margin pools. Production Tracking shows the steepest expansion trajectory as Asian manufacturing scales.
End User:
End user archetypes differ in procurement sophistication, with fleet scale and internal IT capability shaping platform selection criteria.
- OEMs:Original equipment manufacturers with multi-facility footprints requiring standardized mobility architectures across global operations. German automotive OEMs anchor demand concentration, leveraging Industrie 4.0 federal incentives to integrate mobility platforms with existing Siemens and Bosch smart manufacturing ecosystems.
- Tier-1 Suppliers:Direct component providers to OEMs facing stringent traceability and compliance requirements. These customers in the US Midwest manufacturing belt are accelerating adoption, pressed by FDA 21 CFR Part 11 digitization mandates for pharmaceutical and medical device supply chains.
- Equipment Manufacturers:Capital goods producers embedding mobility capabilities into machinery offerings as differentiated service layers.
- Aftermarket Providers:Spare parts and service networks requiring mobile-enabled field technician dispatch and inventory access.
OEMs dominate absolute spending. Tier-1 Suppliers are gaining share fastest as compliance pressure cascades downstream.
Deployment:
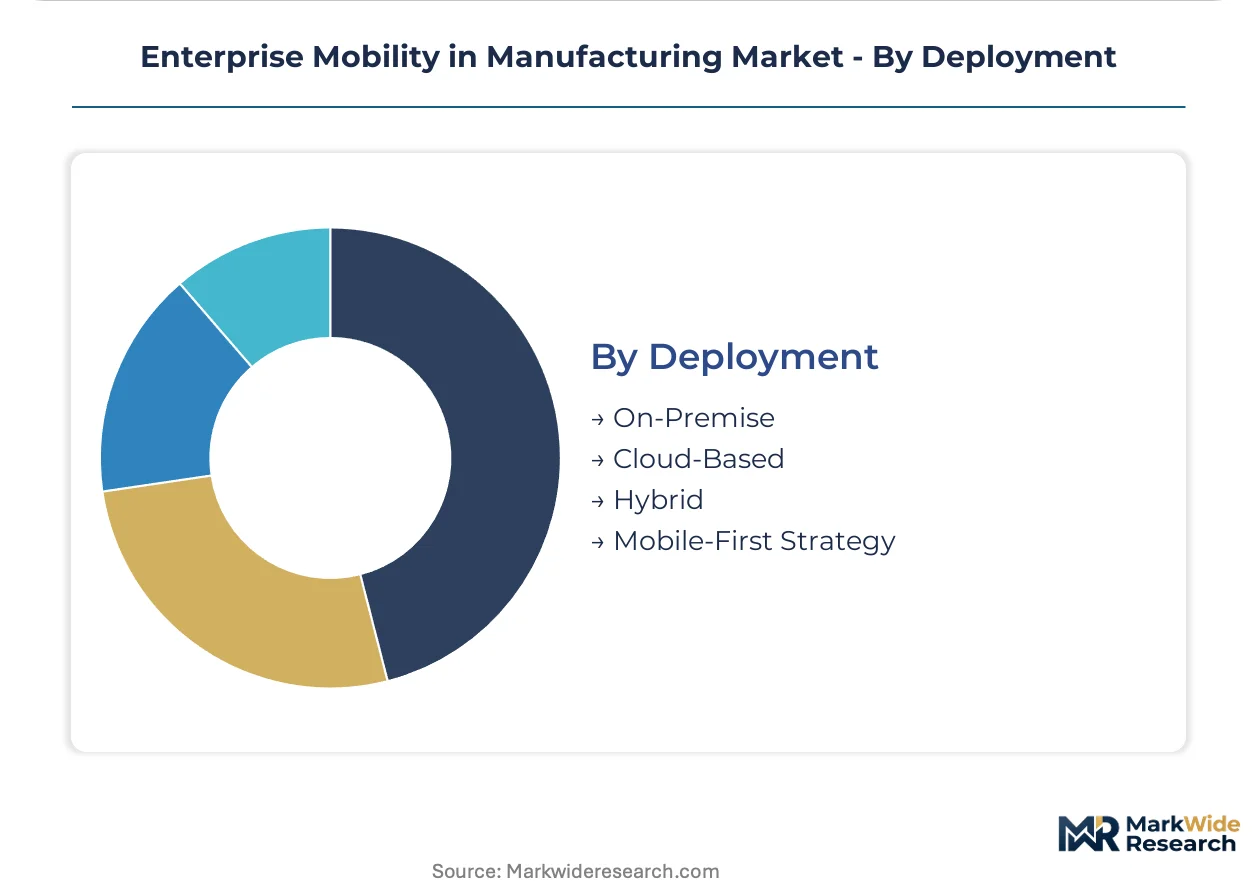
Deployment models segment by capital structure preference, with financing flexibility becoming the primary competitive differentiator.
- Cloud-Based:Fully managed SaaS delivery eliminating infrastructure ownership and enabling rapid geographic expansion. Japanese industrial buyers increasingly specify per-device monthly rates bundling hardware, insurance, and analytics, favoring providers with captive financing arms over pure hardware vendors.
- Hybrid:Split architectures retaining sensitive operational technology data on-premise while leveraging cloud elasticity for enterprise analytics. German precision engineering clusters prefer this model, balancing sovereign data residency requirements against platform agility.
- On-Premise:Self-managed infrastructure deployment for facilities with strict air-gapping or latency requirements.
- Mobile-First Strategy:Native mobile application architectures designed for intermittent connectivity and edge-native processing.
Cloud-Based deployments lead by new project volume. Hybrid architectures are climbing the fastest as sovereignty concerns persist.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal digitization incentives and industrial spectrum allocations are redrawing geographic demand patterns for factory-floor mobility platforms. Germany's Industrie 4.0 corridor anchors European investment intensity. OSHA mandates and FCC private 5G licensing compress US deployment timelines. Asian contract manufacturers leverage production-linked incentives to scale mobile-enabled operational visibility.
Germany
Automotive OEMs in Stuttgart and Wolfsburg drive procurement concentration for integrated workforce mobility platforms. The country's federal manufacturing digitization incentives under Industrie 4.0 accelerate compliant platform investments. Siemens and Bosch anchor smart manufacturing mobility ecosystems across Baden-Württemberg and Bavaria, pulling through Azure-based fleet orchestration subscriptions.
United States
OSHA lockout/tagout digitization mandates force fleet-wide rugged device rollouts across automotive and aerospace facilities. FCC Part 90 private spectrum allocations for industrial 5G reshape how vendors certify devices for hazardous environments. Midwest manufacturing belt Tier-1 suppliers accelerate adoption, pressed by FDA 21 CFR Part 11 requirements for pharmaceutical supply chains.
Japan
Industrial buyers in the Kanto manufacturing belt prioritize per-device monthly rates bundling hardware, insurance, and predictive analytics. METI industrial productivity initiatives subsidize cloud migration for precision engineering clusters. Toyota City and Nagoya manufacturing corridors lead edge-native AI inference deployments for predictive maintenance on GPU-enabled mobile hardware.
India
Electronics contract manufacturers under the PLI scheme establish mobile device assembly capacity for regional industrial mobility deployments. CDSCO digitization requirements cascade compliance pressure downstream to medical device suppliers. Karnataka and Tamil Nadu electronics manufacturing clusters deploy production tracking applications fastest to demonstrate operational efficiency for OEM partnerships.
China
MIIT smart manufacturing guidelines and dual carbon goals drive demand for mobile-enabled supply chain visibility tools. Yangtze River Delta automotive OEMs integrate mobility platforms with existing industrial automation ecosystems. Shenzhen and Shanghai manufacturing hubs concentrate cloud computing deployment models as Tier-1 suppliers abandon capital-intensive on-premise infrastructure.
Enterprise Mobility in Manufacturing Market Competitive Landscape
On the supply side, the industry is consolidating around platform providers with financing flexibility and deep ERP integration capabilities. Cloud-native mobile device management vendors are displacing regional systems integrators who previously monetized deployment complexity. Two strategic archetypes dominate: hyperscale cloud providers bundling device management with predictive analytics, and enterprise software incumbents anchoring position through workflow lock-in. Competitive dynamics center on M&A activity targeting edge orchestration capabilities and strategic partnerships for sovereign cloud architectures.
Within the enterprise software tier, Microsoft Corporation exemplifies the hyperscale platform archetype through Azure-based fleet orchestration, while SAP SE occupies a position representing deep ERP integration specialists. VMware sits within the virtualization security segment, extending protocols to edge devices. These three anchors demonstrate how competitive positioning tilts toward providers with captive financing arms and multi-cloud orchestration capabilities rather than pure hardware OEMs.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| SAP SE |
| Cisco |
| Citrix Systems |
| Oracle |
| VMware |
| Blackberry |
| Dell Technologies |
| Others |
Supply & Pricing Matrix
Semiconductor supply concentration in Taiwanese foundries exposes rugged mobile device procurement to tariff escalation and geopolitical disruption, compressing margin structures across premium certification tiers while forcing buyers toward asset-light leasing models that externalize inventory risk.
Pricing Analysis
Certification level creates the primary spread across NIST SP 800-207 zero-trust compliant, FDA 21 CFR Part 11 validated, and baseline CE-marked mobility platforms. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and predictive analytics inclusion. Cost compression in the standard tier is intensifying because Japanese industrial buyers prioritize per-device monthly rates over capital purchase cycles. Tier-2 suppliers in India's PLI electronics corridors exhibit highest price sensitivity, while German automotive OEMs in Stuttgart anchor premium tier demand.
Supply Chain Analysis
Industrial-grade chipsets feed from Taiwan, South Korea, and Japan, with specialized rugged displays and thermal management components drawing from Shenzhen and Nagoya manufacturing clusters. GPU-enabled mobile hardware for edge-native AI inference rests on concentrated foundry capacity. Single-source vulnerability around FCC Part 90 private spectrum modules constrains US deployment timelines. Distribution runs through hyperscale cloud providers with captive financing arms rather than regional systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise mobility in manufacturing sits at a cyclical recovery phase driven by Industrie 4.0 federal digitization incentives cascading through European automotive supply chains.
For Market Incumbents: Build ecosystem lock-in moats through deep ERP integration that embeds mobility workflows into manufacturing execution systems. Incumbent platform providers should anchor position via Azure-based fleet orchestration subscriptions that collapse provisioning cycles, while defending against cloud-native MDM vendors by acquiring edge orchestration specialists. Certification pre-loading for EU AI Act conformity assessments creates switching costs ahead of enforcement timelines. For New Entrants and Emerging Players: Establish a beachhead in India's PLI electronics manufacturing clusters where production tracking applications demonstrate operational efficiency to anchor OEM partnerships. New entrants should target Tier-3 contract manufacturers underserved by zero-trust compliance costs, deploying hardware-as-a-service models with localized assembly partnerships. Go-to-market leverage rests on CDSCO digitization requirements cascading downstream to medical device suppliers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform providers with captive financing arms and multi-cloud orchestration capabilities. Acquisition targets should exhibit sovereign cloud architecture partnerships and containerized application delivery expertise. The signal to watch is FCC Part 90 spectrum allocation velocity as inflection indicator for latency-sensitive control-loop application scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Orchestration Acquisition | Captures GPU-enabled mobile hardware deployment for predictive maintenance in Toyota City corridors. |
| Sovereign Cloud Partnership | Addresses German precision engineering data residency requirements against platform agility tradeoffs. |
| Hardware-as-a-Service Launch | Aligns with Kanto manufacturing belt preference for per-device monthly rates bundling insurance. |
| Zero-Trust Certification Pre-Loading | Front-loads EU AI Act conformity investments for biometric authentication systems. |
| PLI Scheme Localization | Establishes Karnataka and Tamil Nadu assembly capacity for regional industrial mobility supply. |
Research Methodology
Desk research of hyperscaler capex disclosures, SEC filings, and FCC spectrum allocation records preceded structured interviews with CTOs, plant engineers, IT procurement officers, and aftermarket service heads. Primary fieldwork with manufacturing execution system vendors and rugged device OEMs combined with secondary validation through NIST framework documentation and Industrie 4.0 federal incentive databases. Bottom-up segment sizing across technology layers triangulated against top-down macroeconomic indicators.
Assumptions held private 5G spectrum availability and zero-trust compliance timelines fixed while varying semiconductor supply scenarios and geopolitical tariff exposure across the projection horizon. Segmentation dimensions modeled include deployment model, organization size, integration complexity with legacy MES, and regional regulatory cluster. CAGRs derived from unit economics analysis of subscription versus capital purchase adoption curves, with edge-native AI inference penetration and OSHA digitization mandate compliance as industry-specific inputs.
Sensitivities concentrate around Taiwanese foundry capacity constraints and FCC Part 90 allocation velocity. Forecasts reflect assumptions on Industrie 4.0 incentive continuity and PLI scheme extension. Quarterly review of private spectrum licensing timelines and EU AI Act enforcement preparedness is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Cloud MFT Services Market
Digital Solutions
Global Product Design and Development Market
Digital Solutions
Global E-Signature Platform Market
Digital Solutions
Data Fusion Solutions Market
Digital Solutions
Global Remote Monitoring and Management (RMM) Tools Market
Digital Solutions
Global DDI Market
Digital Solutions
South Korea Digital Twin Market
Digital Solutions
Digital Signage Systems Market
Digital Solutions
Global E-Visa Market
Digital Solutions
Global Enterprise Information Archiving Market
Digital Solutions
Decision Support System Market
Digital Solutions
Parking Management Systems Market
Digital Solutions
Europe Digital Marketing Software Market
Digital Solutions
China Digital Twin Market
Digital Solutions
Digital Project Delivery Solutions Market
Digital Solutions
Global Web Push Notification Software Market