
 India ICT Market | 2026-2036
India ICT Market Size, Share, and Industry Trends Forecast 2026-2036
India ICT Market Foresight
Platform licensing revenue is reconfiguring margin pools away from perpetual software sales toward recurring subscription models across enterprise accounts. Tata Consultancy Services anchors this transition through its cloud-native platform investments, while Infosys differentiates via AI-integrated service layers for banking clients. HCL Technologies extends its position through in-house supercomputing infrastructure that reduces third-party dependency for government contracts.
Information and communications technology encompasses electronic systems for data processing, transmission, and storage, operating across silicon-based semiconductor architectures, fiber-optic transmission protocols, and virtualized compute environments with latency thresholds below five milliseconds for real-time applications. Software and cloud services capture expanding margin pools as enterprises shift capital expenditure to operational expenditure models, while hardware segments face compression from import duty structures on semiconductor components. Managed services within the service-type dimension sustains pricing power through long-term government outsourcing contracts, whereas SME end users drive volume growth in standardized SaaS offerings.
BIS certification requirements for telecom equipment and TRAI's net neutrality frameworks shape product standards and market access conditions for domestic and foreign vendors alike. The RBI's data localization directives for financial services further constrain cloud deployment architectures, pushing hybrid models across banking infrastructure. PLI scheme disbursements for semiconductor assembly and testing are redirecting capital flows toward Gujarat and Assam greenfield sites. Stakeholders must weigh the trade-off between cloud scalability and regulatory compliance costs as state-level data center policies diverge in subsidy intensity and land allocation speed.
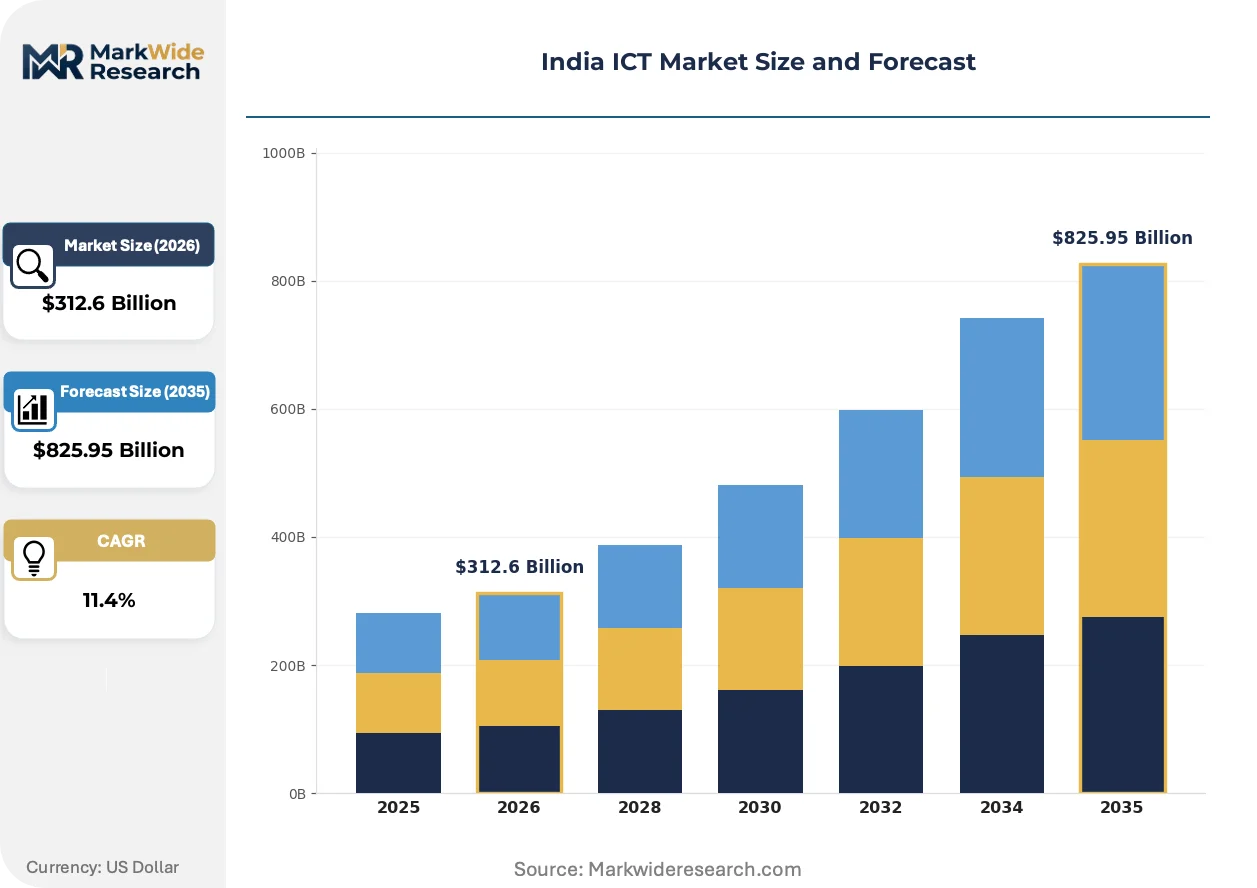
Market Dynamics
Digital India infrastructure mandates are compressing enterprise procurement cycles while RBI data localization rules force hybrid cloud architectures across banking infrastructure, creating simultaneous pull for scale and compliance-heavy deployment models.
Growth Catalysts
- PLI scheme disbursements:Semiconductor assembly and testing incentives redirect capital toward Gujarat and Assam greenfield sites, expanding domestic manufacturing capacity.
- Maharashtra's Mumbai-Pune corridor:Data center investments and 5G rollouts concentrate enterprise demand and reshape procurement patterns for cloud services.
- AI-integrated service layers:Banking clients drive subscription revenue migration as financial services hubs demand real-time analytics capabilities.
Market Restraints
- Import duty compression:Semiconductor component tariffs squeeze hardware segment margins and elevate server and networking equipment costs.
- BIS certification timelines:Telecom equipment testing protocols extend product launch windows and create inventory holding costs for vendors.
- Optical fiber supply concentration:Dependence on imported preform materials exposes infrastructure rollout schedules to shipping volatility.
Strategic Opportunities
- Telangana's Hyderabad tech triangle:State-level data center subsidies and land allocation speed attract hyperscaler investments underserved by Mumbai-Bengaluru saturation.
- Edge computing convergence with 5G:Manufacturing hubs deploy sub-five-millisecond latency applications for predictive maintenance and quality control.
- SME SaaS standardization:Volume growth in operational expenditure models outpaces enterprise customization complexity for domestic software vendors.
Industry Challenges
- Supercomputing talent scarcity:Government contract fulfillment requires specialized workforce pools concentrated at HCL Technologies and limited national institutes.
- Legacy mainframe integration:Public sector banks face multi-year migration complexity as RBI deadlines compress parallel system operation periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India ICT Market |
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $825.95 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Networking Equipment, Cloud Services End User: Enterprises, SMEs, Government, Educational Institutions Service Type: Consulting, Managed Services, Technical Support, Outsourcing Deployment: On-Premises, Cloud-Based, Hybrid, Virtual |
| Companies Covered | HCL Technologies, LTIMindtree, Tata Consultancy Services, Mphasis, Coforge, Infosys, Tech Mahindra, Hexaware Technologies, Wipro, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India ICT Market Shifts & Advancements
Enterprise technology stacks across India are fragmenting into modular, API-driven architectures that separate compute, storage, and application layers, enabling vendor substitution and compressing long-term contract lock-in.
Serverless computing architectures are rendering obsolete traditional provisioned infrastructure models in financial services deployments. Kotak Mahindra Bank and Axis Bank pilot consumption-based billing for core banking workloads. This shift is rendering obsolete capital-intensive data center buildouts previously required for peak-load provisioning.
RBI's data localization directives for financial services mandate in-country storage for payment system data and customer records. Cloud providers reconfigure service delivery through Mumbai, Chennai, and Hyderabad availability zones to satisfy audit requirements. Banking infrastructure teams prioritize hybrid models that segment sensitive workloads from elastic compute.
Enterprise buyers unbundle hardware procurement from managed service contracts that previously bundled five-year refresh cycles. State government IT departments now separate infrastructure purchase from operational support, enabling multi-vendor competition. Karnataka and Tamil Nadu e-governance projects exemplify this disaggregation trend.
India ICT Market Segmentation
Segmentation in the India ICT Market reveals distinct procurement rhythms and margin profiles across product, service, and deployment dimensions. Understanding these structural divisions helps vendors align R&D cycles, pricing frameworks, and partnership strategies with the specific velocity of each segment cluster.
Product Type:
Software refreshes operate on 12-18 month release cycles while networking equipment extends to 5-7 year replacement horizons, creating fundamentally different working capital requirements across vendor portfolios.
- Software:Platform licensing models dominate enterprise accounts as perpetual sales give way to recurring subscriptions. Banking and financial services hubs in Mumbai and Bengaluru drive demand for AI-integrated application layers with real-time analytics capabilities.
- Hardware:Server and storage systems face margin compression from semiconductor import duty structures. Manufacturing corridors in Maharashtra and Tamil Nadu anchor procurement volume for edge computing infrastructure supporting sub-five-millisecond latency applications.
- Networking Equipment:5G rollout schedules and fiber-optic backbone expansions concentrate demand in Telangana's Hyderabad triangle and Karnataka's Bengaluru cluster.
- Cloud Services:RBI data localization directives force hybrid architectures across banking infrastructure, expanding domestic availability zone requirements in Mumbai, Chennai, and Hyderabad.
Hardware anchors the volume base while cloud services gain share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive government contracts from operational expenditure models prevalent among smaller commercial accounts.
- Enterprises:Manufacturing and financial services hubs demand modular, API-driven architectures that separate compute, storage, and application layers. Procurement cycles compress under Digital India infrastructure mandates while compliance requirements multiply.
- SMEs:Standardized SaaS offerings drive volume growth in operational expenditure models. Domestic software vendors capture share through simplified deployment and consumption-based billing structures.
- Government:Long-term outsourcing contracts sustain pricing power for managed service providers. PLI scheme disbursements redirect capital toward Gujarat and Assam greenfield semiconductor assembly sites.
- Educational Institutions:E-governance projects in Karnataka and Tamil Nadu exemplify unbundled procurement separating infrastructure purchase from operational support.
Enterprises dominate current revenue pools while SMEs are expanding most quickly as SaaS standardization penetrates tier-2 and tier-3 commercial centers.
Service Type:
Margin concentration varies sharply between commoditized technical support and high-retention managed services locked into multi-year government frameworks.
- Consulting:Cloud migration advisory and legacy mainframe integration projects concentrate among public sector banks facing RBI deadline pressure. Multi-year migration complexity creates sustained engagement windows.
- Managed Services:State government IT departments separate infrastructure purchase from operational support, enabling multi-vendor competition. Long-term contracts anchor revenue predictability.
- Technical Support:Standardized delivery models face pricing pressure as remote diagnostic tools and automated remediation reduce labor intensity.
- Outsourcing:Supercomputing talent scarcity limits fulfillment capacity for specialized government contracts, concentrating capability at select national institutes and established infrastructure operators.
Managed services anchor the volume base while consulting climbs the fastest as digital transformation mandates accelerate across banking and public sector verticals.
Deployment:
Application criticality determines architecture selection, with latency-sensitive workloads demanding physical proximity while elastic compute favors distributed cloud topologies.
- On-Premises:Core banking systems and payment infrastructure maintain captive data center footprints to satisfy RBI audit requirements. Legacy mainframe integration projects prolong parallel system operation periods.
- Cloud-Based:Kotak Mahindra Bank and Axis Bank pilot consumption-based billing for core banking workloads, rendering obsolete capital-intensive data center buildouts previously required for peak-load provisioning.
- Hybrid:Banking infrastructure teams segment sensitive workloads from elastic compute, configuring service delivery across Mumbai, Chennai, and Hyderabad availability zones to satisfy data localization directives.
- Virtual:Serverless computing architectures displace traditional provisioned infrastructure models in financial services deployments, enabling precise resource matching to transaction volume fluctuations.
On-premises deployments anchor the volume base while hybrid architectures gain share at the steepest rate as regulatory compliance and cloud scalability requirements converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers in tier-2 cities exhibit acute price sensitivity to SaaS subscription tiers, while financial services hubs in Mumbai and Bengaluru absorb premium pricing for compliance-heavy hybrid cloud deployments.
Maharashtra
Manufacturing corridors in the Mumbai-Pune belt drive edge computing procurement for sub-five-millisecond latency applications. The state's data center subsidy framework accelerates hyperscaler availability zone construction. Mumbai's financial district anchors hybrid cloud spending as RBI audit requirements force workload segmentation across captive and distributed infrastructure.
Karnataka
Bengaluru's technology cluster concentrates AI-integrated service layer demand from banking clients migrating to recurring subscription models. The state's e-governance procurement reforms separate infrastructure purchase from operational support, enabling multi-vendor competition. Tamil Nadu border regions capture spillover data center investment as land allocation saturation intensifies in the core metro.
Telangana
Hyderabad's tech triangle attracts hyperscaler investments underserved by Mumbai-Bengaluru corridor saturation, leveraging state-level land allocation speed. TRAI's 5G spectrum frameworks accelerate fiber-optic backbone expansion across the metro periphery. Government outsourcing contracts sustain managed services pricing power through long-term frameworks.
Gujarat
PLI scheme disbursements for semiconductor assembly and testing redirect capital flows toward greenfield sites in the western corridor. DGFT import duty structures on networking equipment elevate total cost of ownership for enterprise hardware procurement. GIFT City's financial services concentration drives demand for RBI-compliant data localization architectures.
Tamil Nadu
Manufacturing hubs deploy predictive maintenance applications requiring edge computing infrastructure with strict latency thresholds. State IT department unbundling of hardware procurement from managed service contracts mirrors Karnataka's e-governance reform trajectory. Chennai's availability zone expansion supports banking sector hybrid cloud segmentation mandates.
India ICT Market Competitive Landscape
Systems integrators and platform-native specialists split the market between compliance-heavy government contracts and standardized SaaS volume plays. The vendor base concentrates around three strategic archetypes: scale-driven diversified IT services houses, domain-specialized banking technology providers, and infrastructure-centric supercomputing operators. Competitive intensity manifests through cloud-native platform investments and in-house supercomputing capacity builds that reduce third-party dependency.
Within the diversified systems integrator tier, Tata Consultancy Services, Infosys, and Wipro occupy positions defined by cloud migration advisory scale and enterprise account penetration. HCL Technologies sits within the infrastructure-centric archetype, anchoring government contract fulfillment through captive supercomputing assets. These named entities exemplify the strategic segmentation between platform licensing revenue capture and recurring managed services frameworks.
| Leading Market Players |
|---|
| HCL Technologies |
| LTIMindtree |
| Tata Consultancy Services |
| Mphasis |
| Coforge |
| Infosys |
| Tech Mahindra |
| Hexaware Technologies |
| Wipro |
| Others |
Supply & Pricing Matrix
The Mumbai-JNPT maritime corridor carries semiconductor components and networking equipment from East Asian fabrication hubs, with freight cost volatility transmitting directly into hardware margin compression and downstream subscription pricing tiers for cloud services.
Pricing Analysis
Managed service contracts and extended warranty tiers generate lifetime value that exceeds initial platform licensing fees across enterprise accounts. Three-tier pricing structure across premium, standard, and economy levels separates RBI-compliant banking infrastructure from volume SaaS offerings for SME segments. Pricing pressure stems from import duty structures on semiconductor components that elevate server costs. Government buyers exhibit lowest price sensitivity due to long-term outsourcing frameworks, while tier-2 city SMEs drive hardest negotiation on per-seat SaaS rates.
Supply Chain Analysis
Export control restrictions on advanced GPU and AI accelerator chips limit flows from the United States and Taiwan into domestic cloud infrastructure buildouts. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States, while optical fiber preform materials source primarily from Japan and China. Single-source vulnerability in advanced node chip access threatens hyperscaler expansion timelines. Distribution runs through Mumbai, Chennai, and Hyderabad availability zones with last-mile fiber deployment handled by state-level telecom infrastructure partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India ICT Market sits at a platform-economics inflection where API-driven interoperability between cloud-native services and legacy banking infrastructure determines competitive survival.
For Market Incumbents: Pre-empt margin erosion in hardware resale by accelerating captive semiconductor assembly investments under PLI scheme frameworks. Deepen backward integration into domestic testing facilities to reduce DGFT tariff exposure on imported networking equipment. Anchor government contract renewal through supercomputing talent retention programs that address fulfillment scarcity. For New Entrants and Emerging Players: Establish a beachhead in Telangana's Hyderabad tech triangle where state subsidies and land allocation speed attract underserved hyperscaler demand. Target standardized SME SaaS offerings in tier-2 manufacturing corridors where operational expenditure models outpace enterprise customization complexity. Lead with consumption-based billing structures that displace capital-intensive data center provisioning. For Investors and Strategic Acquirers: Domain-specialized banking technology providers with RBI-compliant hybrid cloud architectures represent the highest-conviction acquisition archetype. Long-term viability hinges on navigating the tension between cloud scalability mandates and data localization enforcement. Monitor PLI scheme disbursement velocity as the signal for domestic manufacturing capacity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-driven separation of compute and storage layers enables vendor substitution across Mumbai banking infrastructure. |
| Geographic Expansion | Hyderabad availability zone construction captures hyperscaler investment fleeing Bengaluru land saturation. |
| Backward Integration | In-house semiconductor testing reduces DGFT import duty exposure for government server procurement. |
| Strategic Partnership | State government IT outsourcing contracts anchor multi-year managed services revenue predictability. |
| Product Launch | Serverless computing pilots at Kotak Mahindra Bank and Axis Bank displace provisioned infrastructure models. |
Research Methodology
Desk research of TRAI spectrum allocation records, RBI circulars on data localization, and PLI scheme disbursement filings preceded structured interviews with CTOs at financial services institutions, procurement officers at state government IT departments, platform engineers at hyperscaler availability zones, and integration specialists at domestic software vendors. Secondary validation drew from SEBI filings, BIS certification databases, and customs import records for semiconductor components. Bottom-up segment sizing triangulated against top-down macroeconomic indicators for ICT expenditure.
Assumptions held fixed across the analysis window include Digital India infrastructure mandate continuity, TRAI net neutrality framework stability, and RBI data localization enforcement intensity. Segmentation dimensions modeled encompass deployment architecture, organization size tier, vertical industry, and regional adoption cluster. CAGRs derived from historical expenditure patterns projected forward with regulatory scenario weighting. Forecast inputs incorporated 5G rollout schedules and semiconductor PLI capacity buildout timelines.
Sensitivities concentrate around BIS certification timeline extensions, PLI scheme disbursement delays, and export control tightening on advanced chips. Forecasts reflect these documented assumptions without forward-year precision. Material shifts in RBI data localization scope or TRAI spectrum policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Australia Cloud OSS BSS Market
Digital Solutions
Europe IT Asset Disposition Market
Digital Solutions
Europe Online Dating Services Market
Digital Solutions
Webrtc Market
Digital Solutions
North America Product Design and Development Services Market
Digital Solutions
Electronic Document Management System (EDMS) Market
Digital Solutions
Product Lifecycle Management Consumer Packaged Goods and Retail (PLM Cpandr) Market
Digital Solutions
United States Contract Manufacturing Services Market
Digital Solutions
Global Cloud Monitoring Tools Market
Digital Solutions
Global Asset Reliability Software Market
Digital Solutions
IT Monitoring Tools Market
Digital Solutions
Master Data Management Market
Digital Solutions
NFT Creation Software Market
Digital Solutions
Canada ICT Market
Digital Solutions
Product Engineering Services Market
Digital Solutions
Australia System Integration Market