
 Mobile Command and Control Solutions Market | 2026-2036
Mobile Command and Control Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Command and Control Solutions Market Foresight
The capability gap between software-centric and hardware-heavy suppliers is rotating competitive investment toward modular, open-architecture platforms. Thales Group leverages its European defense footprint to sustain integrated naval command contracts across multiple NATO navies. Motorola Solutions anchors its position through backward integration into dedicated public-safety LTE infrastructure. L3Harris Technologies differentiates via specialized signals-intelligence modules that slot into broader C2 networks.
Mobile command and control solutions encompass portable hardware, secure software, and communication layers that enable real-time situational awareness and decision authority for distributed operators, typically requiring MIL-STD-810G environmental ruggedization and NSA Suite B cryptographic compliance. These systems serve military, emergency services, and transportation coordinators who must maintain operational continuity across degraded or contested networks. Software and integrated systems segments command the deepest margin pools because recurring update cycles and interoperability certification create vendor stickiness. Cloud-based and edge computing deployments represent the fastest-expanding deployment models as latency-sensitive applications push processing closer to tactical users.
FCC FirstNet standards, NSA cryptographic certification requirements, and NATO STANAG interoperability protocols collectively shape product roadmaps and procurement eligibility for vendors serving North American and European buyers. The Federal Aviation Administration's evolving unmanned aircraft system traffic management rules are extending C2 requirements into commercial drone coordination, opening adjacent demand channels. Stakeholders must weigh the trade-off between proprietary ecosystem lock-in and the modular interoperability that defense customers increasingly mandate in future procurement cycles.
Market Dynamics
The Pentagon's Joint All-Domain Command and Control mandate is compressing procurement cycles and forcing vendors toward modular, open-architecture platforms that interoperate across air, land, sea, space, and cyber domains.
Growth Catalysts
- FCC FirstNet mandate:The Federal Communications Commission's broadband public safety network standard creates guaranteed demand for interoperable first responder command systems across United States emergency services agencies.
- NATO STANAG protocols:Standardization agreements for battlefield management systems drive cross-border procurement alignment among European defense ministries seeking interoperable naval and ground force networks.
- Edge computing architectures:Latency-sensitive tactical applications are pushing processing power toward forward-deployed operators, expanding hardware refresh cycles and software licensing revenue pools.
Market Restraints
- NSA Suite B cryptographic compliance:National Security Agency certification timelines extend product development cycles by 18-24 months and restrict vendor eligibility for classified network integration.
- Gallium nitride component concentration:Specialized semiconductor supply chains concentrate in East Asian foundries, creating single-source vulnerability for high-frequency radio modules.
- Proprietary ecosystem lock-in:Established vendors' closed command protocols create switching costs that delay modular interoperability adoption among legacy platform operators.
Strategic Opportunities
- FAA unmanned aircraft system traffic management:Evolving commercial drone coordination rules extend command and control requirements into civilian logistics, agriculture, and infrastructure inspection verticals.
- Cloud-native deployment models:Containerized software architectures enable subscription-based recurring revenue and reduce hardware-dependent margin compression for systems integrators.
- 5G private network integration:Dedicated cellular infrastructure for military bases and emergency response hubs creates adjacent equipment and spectrum management service demand.
Industry Challenges
- MIL-STD-810G environmental testing capacity:Limited certified laboratory throughput for thermal, shock, and electromagnetic interference validation creates bottlenecks for new product introductions.
- Cross-domain security clearance pipelines:Personnel vetting backlogs restrict engineering talent availability for classified program development, compressing vendor delivery schedules.
- Legacy analog radio integration:Backward compatibility requirements with existing tactical voice networks complicate software-defined radio transition roadmaps and increase firmware complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Command and Control Solutions Market |
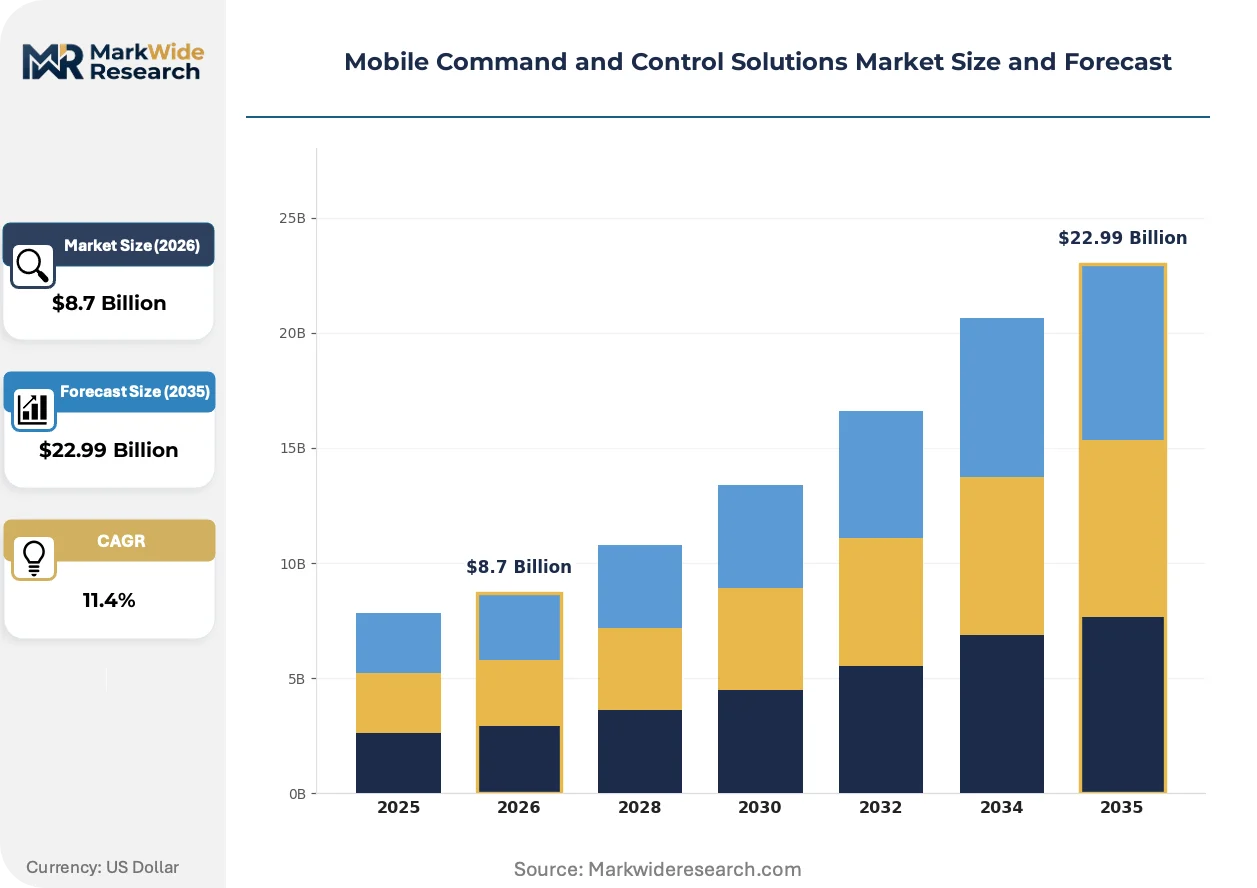
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Software, Hardware, Service, Integrated Systems Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Military, Emergency Services, Transportation, Public Safety Technology: IoT, AI, Big Data, GIS |
| Companies Covered | Thales Group, Honeywell International Inc., Lockheed Martin Corporation, Northrop Grumman Corporation, BAE Systems, Collins Aerospace, Motorola Solutions, Saab AB, L3Harris Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Command and Control Solutions Market Shifts & Advancements
Software-defined architectures are actively restructuring competitive advantage away from hardware durability toward rapid feature deployment and cross-platform interoperability certification.
Containerized mission applications running on standardized tactical edge hardware are supplanting monolithic, vendor-locked command systems. United States Special Operations Command units are piloting modular software payloads that reconfigure within hours rather than months. This flexibility is compressing traditional prime contractor maintenance revenue streams while opening subscription-based update opportunities for specialized software houses.
Europe's Cyber Resilience Act and Network and Information Security Directive impose mandatory security update obligations and incident reporting timelines on command system vendors. These frameworks accelerate product lifecycle management costs but create compliance service revenue streams for systems integrators with established European security certification pathways. Defense procurement offices in Germany, France, and Poland are prioritizing vendors with pre-certified supply chain documentation.
Buying committees are consolidating vendor relationships around integrated platform providers rather than assembling best-of-breed components. United States Army program offices now favor single-source responsibility for command suites spanning vehicle, dismounted, and headquarters nodes. This concentration rewards vendors with breadth across hardware, software, and cryptographic layers while marginalizing specialized component suppliers lacking integration certification.
Mobile Command and Control Solutions Market Segmentation
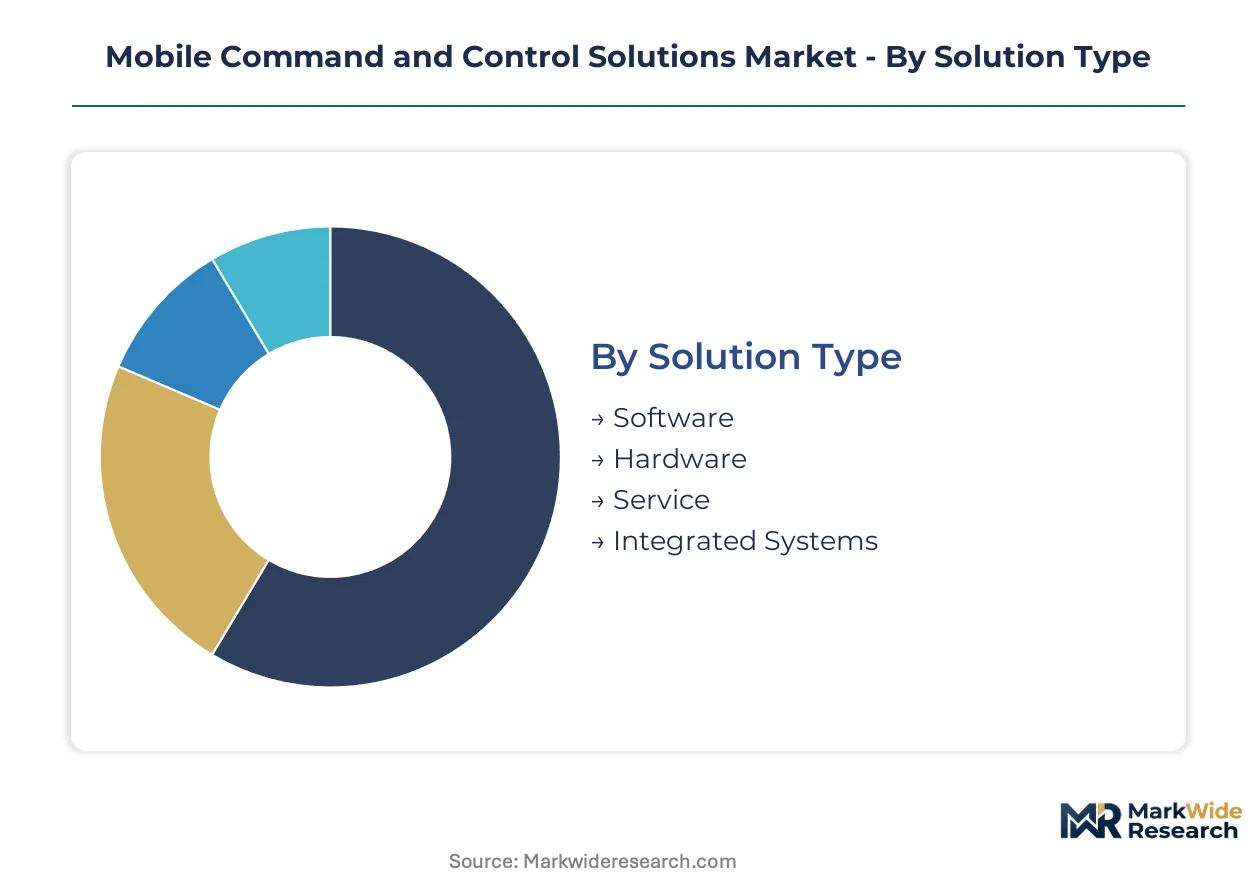
Mobile command and control solutions fragment across four critical dimensions that determine procurement pathways, margin profiles, and vendor competitive positioning. Each segmentation layer reflects distinct technical requirements, regulatory compliance burdens, and customer acquisition economics that shape go-to-market strategy.
Solution Type:
Software solutions concentrate demand in NATO member states and Five Eyes intelligence-sharing nations with mature cryptographic infrastructure. Hardware procurement patterns diverge sharply between domestic defense industrial base requirements and export-licensed foreign military sales.
- Software:Modular applications running on standardized tactical operating systems enable rapid feature deployment through over-the-air updates. Pentagon Joint All-Domain Command and Control architectures and FCC FirstNet broadband mandates are compressing procurement cycles toward software-centric acquisition models.
- Hardware:Ruggedized terminals, vehicle-mounted command consoles, and dismounted soldier systems require MIL-STD-810G environmental certification and NSA Suite B cryptographic validation. European defense ministries prioritize hardware with pre-certified NATO STANAG interoperability documentation.
- Service:Integration, training, and sustainment contracts spanning system lifecycle management.
- Integrated Systems:End-to-end platform responsibility combining hardware, software, and cryptographic layers under single-source contracting.
Integrated systems command the established base. The steepest expansion runs through software.
Deployment Model:
Cost-tier stratification separates capital-intensive on-premises installations from recurring-revenue cloud and edge architectures. Volume concentration favors hybrid models that bridge legacy infrastructure with modern software-defined networks.
- On-Premises:Dedicated server infrastructure within classified facilities or hardened command posts. Military customers in Germany, France, and Poland maintain preference for sovereign data control despite higher total cost of ownership.
- Cloud-Based:Containerized mission applications hosted on government-approved commercial cloud environments. United States Special Operations Command units pilot subscription-based software payloads that reconfigure within hours.
- Hybrid:Sensitive data processing on-premises with non-classified analytics in commercial cloud.
- Edge Computing:Latency-sensitive tactical processing pushed toward forward-deployed operators. FAA unmanned aircraft system traffic management rules and battlefield drone coordination requirements are accelerating hardware refresh cycles.
Hybrid deployments anchor current procurement volumes. Edge computing climbs the fastest.
End User:
Application-specific requirements drive divergence in ruggedization standards, cryptographic certification levels, and interoperability protocol compliance across customer categories.
- Military:Joint force command networks spanning air, land, sea, space, and cyber domains with NSA Suite B encryption. Pentagon spending on cross-domain architectures concentrates vendor investment toward modular, open-standards platforms.
- Emergency Services:First responder command systems interoperable across jurisdictional boundaries. FCC FirstNet broadband mandate creates guaranteed demand for interoperable LTE infrastructure among United States fire, police, and emergency medical agencies.
- Transportation:Coordination platforms for rail, port, and highway operations requiring integration with civilian communication networks.
- Public Safety:Municipal and regional command centers managing multi-agency incident response with backward compatibility to legacy analog radio systems.
Military end users command the established base. Emergency services gain share fastest.
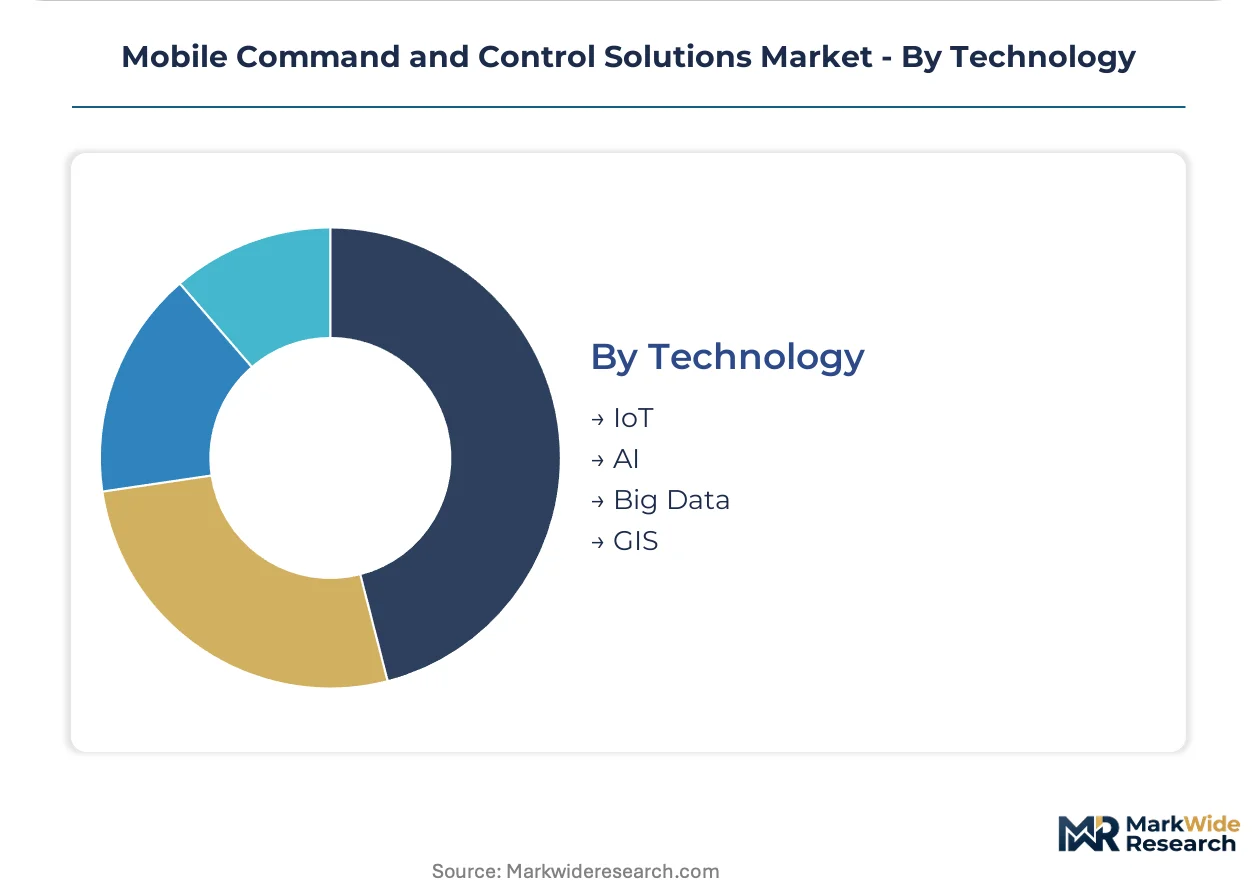
Technology:
Maturity curves separate proven sensor integration and mapping capabilities from emerging artificial intelligence and predictive analytics layers that remain in pilot deployment.
- IoT:Distributed sensor networks feeding situational awareness dashboards. NATO naval command contracts and battlefield management systems rely on maritime and ground sensor fusion architectures.
- AI:Machine learning models for threat prediction, resource allocation, and decision support. European Cyber Resilience Act and Network and Information Security Directive compliance requirements accelerate product lifecycle management costs.
- Big Data:Historical pattern analysis and real-time stream processing for operational intelligence.
- GIS:Geospatial mapping and terrain analysis integrated with command visualization layers.
GIS commands the established base. AI shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement elasticity varies sharply across geographies. Pentagon budgets absorb premium pricing for cross-domain architectures, while European ministries negotiate harder on unit costs amid fragmented national requirements.
United States
Pentagon Joint All-Domain Command and Control spending concentrates vendor investment toward modular platforms. FCC FirstNet mandates reshape interoperability requirements for first responder systems. Defense contractors cluster around Washington DC metropolitan area and Huntsville, Alabama, where Army program offices consolidate command suite procurement.
Germany
Bundeswehr modernization programs drive demand for NATO STANAG-compliant battlefield management systems. Cyber Resilience Act and Network and Information Security Directive impose mandatory security update obligations on vendors. Industrial concentration spans Munich aerospace corridor and Stuttgart defense electronics cluster, where systems integrators maintain pre-certified supply chain documentation.
United Kingdom
Integrated Review defense spending priorities accelerate procurement of interoperable naval and ground force networks. Ministry of Defence digital transformation mandates favor vendors with established security clearance pathways. London and Bristol host prime contractor headquarters, while Farnborough maintains systems integration and testing infrastructure.
France
Direction Générale de l'Armement procurement emphasizes sovereign data control and backward compatibility with legacy tactical networks. EU AI Act and Cyber Resilience Act compliance requirements accelerate product lifecycle management costs. Paris-Saclay defense technology cluster and Toulouse aerospace hub concentrate systems engineering talent for command platform development.
Israel
Israel Defense Forces operational requirements drive rapid iteration cycles for signals intelligence and electronic warfare modules. National cryptographic authority certification restricts vendor eligibility for classified network integration. Tel Aviv metropolitan area and Haifa technology corridor host specialized software houses developing containerized mission applications.
Mobile Command and Control Solutions Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-tier competitive structure. Prime contractors with breadth across hardware, software, and cryptographic layers capture single-source program awards. Component suppliers lacking integration certification face margin compression as buying committees consolidate vendor relationships. Dominant competitive moves include portfolio diversification into adjacent 5G private network infrastructure and strategic partnerships for cloud-native deployment models.
Within the integrated systems tier, Thales Group and L3Harris Technologies exemplify vendors with established NATO interoperability credentials. Motorola Solutions anchors the public-safety segment through dedicated LTE infrastructure positions. These three companies represent contrasting geographic footprints—European defense industrial base, transatlantic defense electronics, and North American first responder markets—illustrating how regulatory alignment shapes competitive boundaries.
| Leading Market Players |
|---|
| Thales Group |
| Honeywell International Inc. |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| BAE Systems |
| Collins Aerospace |
| Motorola Solutions |
| Saab AB |
| L3Harris Technologies |
| Others |
Supply & Pricing Matrix
NSA Suite B cryptographic certification gates both vendor eligibility and price stratification in mobile command and control markets, compressing margins for uncertified suppliers while enabling premium capture for accredited integrators. Pentagon Joint All-Domain Command and Control procurement and FCC FirstNet mandates concentrate buying power among defense ministries and emergency services agencies that bundle hardware, software, and sustainment into multi-year contracts.
Pricing Analysis
After-sales service and extended sustainment contracts drive lifetime value capture for integrated systems vendors. Three-tier pricing structure across premium, standard, and economy levels separates NSA-certified battlefield management suites from commercial-grade public safety terminals and uncertified component offerings. Price differentiation rests on cryptographic validation tier and interoperability certification depth. Cost compression in hardware modules is intensifying because gallium nitride component supply concentrates in East Asian foundries. Military end users show lowest price sensitivity due to mission-critical requirements, while municipal public safety agencies face the tightest budget constraints.
Supply Chain Analysis
Inbound logistics costs for gallium nitride semiconductors and ruggedized display modules fluctuate with transpacific container availability and port congestion at Long Beach and Rotterdam. Supply concentration spans Taiwan for high-frequency radio components, South Korea for advanced displays, and the United States for cryptographic processing modules. Raw material dependencies include rare earth elements for magnetics, specialized aluminum alloys for thermal management, and military-grade conformal coatings. Single-source vulnerability in East Asian foundries creates structural risk for radio frequency module procurement. Distribution runs through prime contractor integration facilities and direct defense procurement channels with minimal aftermarket intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile command and control market is approaching a platform-economics inflection as Pentagon Joint All-Domain Command and Control architectures and NATO STANAG interoperability protocols consolidate procurement around integrated ecosystem providers rather than component assemblers.
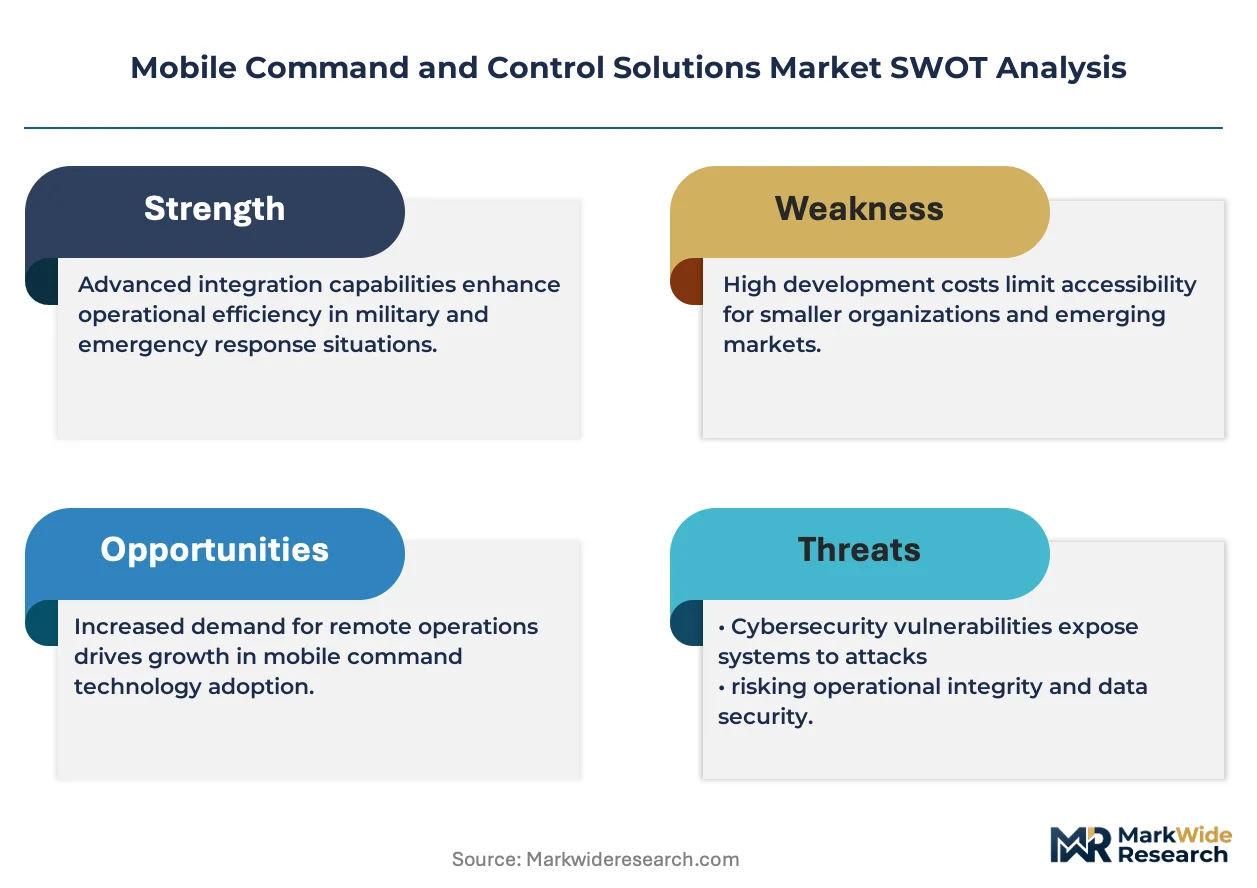
For Market Incumbents: Compound platform stickiness through backward integration into 5G private network infrastructure and captive cryptographic certification pipelines. Lockheed Martin and Northrop Grumman face emerging pressure from modular software houses that compress traditional prime contractor maintenance revenue through containerized mission applications. Priority lever rests on single-source responsibility contracts spanning vehicle, dismounted, and headquarters command nodes. For New Entrants and Emerging Players: Cloud-native deployment and edge computing integration services represent the most penetrable white space where incumbents under-serve latency-sensitive tactical applications. FAA unmanned aircraft system traffic management rules extend command requirements into commercial drone coordination, opening civilian logistics and infrastructure inspection verticals with lighter certification burdens. Go-to-market angle should emphasize subscription-based software payloads that reconfigure within hours rather than months. For Investors and Strategic Acquirers: Europe's Cyber Resilience Act and Network and Information Security Directive reshape the acquisition landscape by accelerating compliance service revenue opportunities for systems integrators with pre-certified European supply chain documentation. Long-term viability favors vendors with breadth across hardware, software, and cryptographic layers capable of capturing consolidated single-source awards. Signal to watch is German, French, and Polish defense procurement office preference shifts toward integrated platform providers.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Containerized mission applications enable rapid reconfiguration for Pentagon Joint All-Domain Command and Control architectures. |
| Strategic Partnership | Cloud-native deployment alliances with hyperscalers unlock subscription revenue and reduce hardware-dependent margin compression. |
| Acquisition of Specialist Firm | Signals intelligence and electronic warfare module specialists deepen cryptographic layer capabilities for NATO interoperability. |
| Geographic Expansion | European Cyber Resilience Act compliance investments open Bundeswehr and French Direction Générale de l'Armement procurement pathways. |
| Product Launch | 5G private network infrastructure positions capture dedicated cellular demand for military bases and emergency response hubs. |
Research Methodology
A standing panel of Pentagon program office directors, NATO procurement officials, FCC FirstNet implementation leads, and systems integration engineers provided ongoing calibration across primary interview cycles. Defense contractor business development executives and public safety agency CIOs supplied operational deployment perspectives. Secondary validation drew from Pentagon budget justification documents, NATO STANAG publication archives, FCC regulatory filings, and ETSI technical specifications. Bottom-up unit economics and top-down defense spending allocations were cross-referenced for triangulation.
Consistency checks validated volume and value outputs against external benchmarks including defense procurement databases and emergency services technology expenditure surveys. The analytical framework modeled deployment model, solution type, end user category, and technology layer across the projection horizon. CAGRs were derived from segment-level growth trajectories weighted by procurement pipeline visibility. Industry-specific inputs included Joint All-Domain Command and Control program milestone schedules and FirstNet network deployment phases.
Forecasts assume regulatory continuity in NSA cryptographic certification timelines and NATO STANAG interoperability protocols; material policy shifts would require re-modeling. Cross-domain security clearance pipeline constraints and gallium nitride supply concentration represent specific risk factors that could compress vendor delivery schedules. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Digital User Experience Solutions Market
Digital Solutions
Switzerland ICT Market
Digital Solutions
Crop Management Software Market
Digital Solutions
Asia-Pacific API Management Market
Digital Solutions
Mobile Collaboration Market
Digital Solutions
AI Powered Home Solution Market
Digital Solutions
United States ICT Market
Digital Solutions
Revops Platform Market
Digital Solutions
Change Management Software Market
Digital Solutions
Digital Pen Market
Digital Solutions
United States Contract Manufacturing Services Market
Digital Solutions
Global Online Reputation Management Software Market
Digital Solutions
Load Balancer Market
Digital Solutions
Enterprise Application Integration (EAI) Market
Digital Solutions
Global E-Passport and E-Visa Market
Digital Solutions
Container Orchestration Market