
 Potassium Polymetaphosphate Food Additives Market | 2026-2036
Potassium Polymetaphosphate Food Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Potassium Polymetaphosphate Food Additives Market Analytics
Phosphate chemistry expertise is unwinding across Eastern European and Chinese manufacturing bases, tightening the specialist labor pool available for food-grade polymetaphosphate production. ICL Group leverages captive phosphate rock access in the Negev to sustain integrated supply security. Innophos anchors North American demand through its Caldwell, New Jersey technical center. Prayon competes from its Engis, Belgium hub with deep European regulatory navigation.
Potassium polymetaphosphate, a cyclic condensed phosphate with variable chain length typically expressed as (KPO₃)ₙ, functions primarily as a sequestrant, moisture binder, and texture modifier in protein-rich food matrices. Its manufacturing involves thermal dehydration of monopotassium phosphate at controlled temperatures between 400°C and 600°C to achieve the desired polymeric structure. Powder formulations dominate current volume owing to dosing precision and stability in industrial blending operations, while liquid grades capture expanding beverage system demand where rapid dispersion matters. Food grade specifications command premium positioning over technical and pharmaceutical variants due to batch certification costs and FSSC 22000 compliance overhead.
FDA food additive regulations under 21 CFR govern US market access, while EFSA evaluates phosphate additive safety through its ANS panel with cumulative dietary exposure thresholds. China's SAMR enforces GB 1886.181 for food-grade potassium polymetaphosphate purity and heavy metal limits. Stakeholders must monitor evolving maximum permitted levels in processed meat across multiple jurisdictions, as regulatory tightening in one geography typically cascades into supplier reformulation mandates elsewhere.

Market Dynamics
Regulatory tightening on phosphate cumulative dietary exposure is forcing simultaneous reformulation across Brazil, Indonesia, and EU member states, compressing supplier response windows and reshaping procurement qualification protocols.
Growth Catalysts
- EFSA ANS Panel Thresholds:Tighter cumulative exposure limits for processed meat are accelerating phosphate additive substitution toward potassium polymetaphosphate in EU protein processing facilities.
- Brazilian Poultry Belt Expansion:Shelf-life mandates under ANVISA food safety codes are driving phosphate additive procurement volumes in São Paulo and Paraná processing clusters.
- Instant Noodle Processing:Indonesia's surging noodle sector demands moisture-binding phosphates for texture stability in high-temperature frying operations.
Market Restraints
- Phosphate Rock Concentration:Captive ore access concentrates with ICL Group in the Negev and Moroccan state-linked suppliers, constraining independent processor feedstock security.
- GB 1886.181 Compliance Costs:China's heavy metal purity benchmarks impose batch certification overhead that technical-grade producers cannot absorb for food-grade pivot.
- Plant-Based Protein Substitution:Pea and soy protein isolates with native emulsification properties are displacing phosphate additives in clean-label meat analog formulations.
Strategic Opportunities
- Vietnam Processing Investment:Underpenetrated poultry and seafood processing infrastructure creates first-mover positioning for phosphate additive technical service partnerships.
- Beverage System Dispersion:Liquid-grade potassium polymetaphosphate formats are capturing functional water and isotonic drink applications where rapid dissolution matters.
- FSSC 22000 Certification Arbitrage:Mid-tier Chinese producers achieving food safety certification gain qualified supplier status with multinational protein processors seeking dual-source security.
Industry Challenges
- Thermal Dehydration Expertise Scarcity:Phosphate polymerization chemistry specialists are exiting Eastern European and Chinese manufacturing bases, constraining qualified production scale-up.
- Multi-Jurisdiction Reformulation Coordination:Simultaneous compliance with FDA 21 CFR, EFSA ANS thresholds, and SAMR GB standards fragments R&D resource allocation across regulatory silos.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potassium Polymetaphosphate Food Additives Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Liquid, Tablets Application: Meat Processing, Bakery Products, Dairy Items, Beverages Grade: Food Grade, Technical Grade, Pharmaceutical Grade, Industrial Grade Customer Type: Food Manufacturers, Beverage Companies, Retailers, Food Service Providers |
| Companies Covered | ICL Group, Innophos, Prayon, Aditya Birla Chemicals, Nutrien Ltd, Fosfa, Budenheim, TKI Hrastnik, Haifa Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potassium Polymetaphosphate Food Additives Market Evolving Landscape
Process intensification and regulatory harmonization pressures are compressing traditional manufacturing timelines while opening technical service differentiation pathways for qualified suppliers.
Controlled-atmosphere thermal dehydration is supplanting conventional rotary kiln processing for potassium polymetaphosphate polymerization. Brazilian poultry processors and Indonesian noodle manufacturers are adopting this technology to achieve tighter molecular weight distribution and reduced heavy metal carryover. The shift is supplanting commodity-grade suppliers unable to justify capital retrofitting, concentrating qualified supply among integrated phosphate chemistry specialists.
REACH authorization timelines for phosphate process intermediates are extending chemical registration obligations for EU-located production facilities. This regulatory friction is diverting incremental capacity investment toward Middle Eastern and North African manufacturing zones with streamlined chemical notification pathways. Food-grade specifications are absorbing disproportionate compliance cost allocation, widening the premium spread over technical grades.
Direct technical center engagement is displacing distributor-mediated phosphate additive procurement in North American protein processing. Large meatpackers in the US Midwest are contracting formulation support directly from supplier technical centers in New Jersey, compressing traditional ingredient distribution margins. This channel compression is most visible in sodium-reduced processed meat development, where potassium polymetaphosphate substitution requires application-specific hydration protocol customization.
Potassium Polymetaphosphate Food Additives Market Segmentation
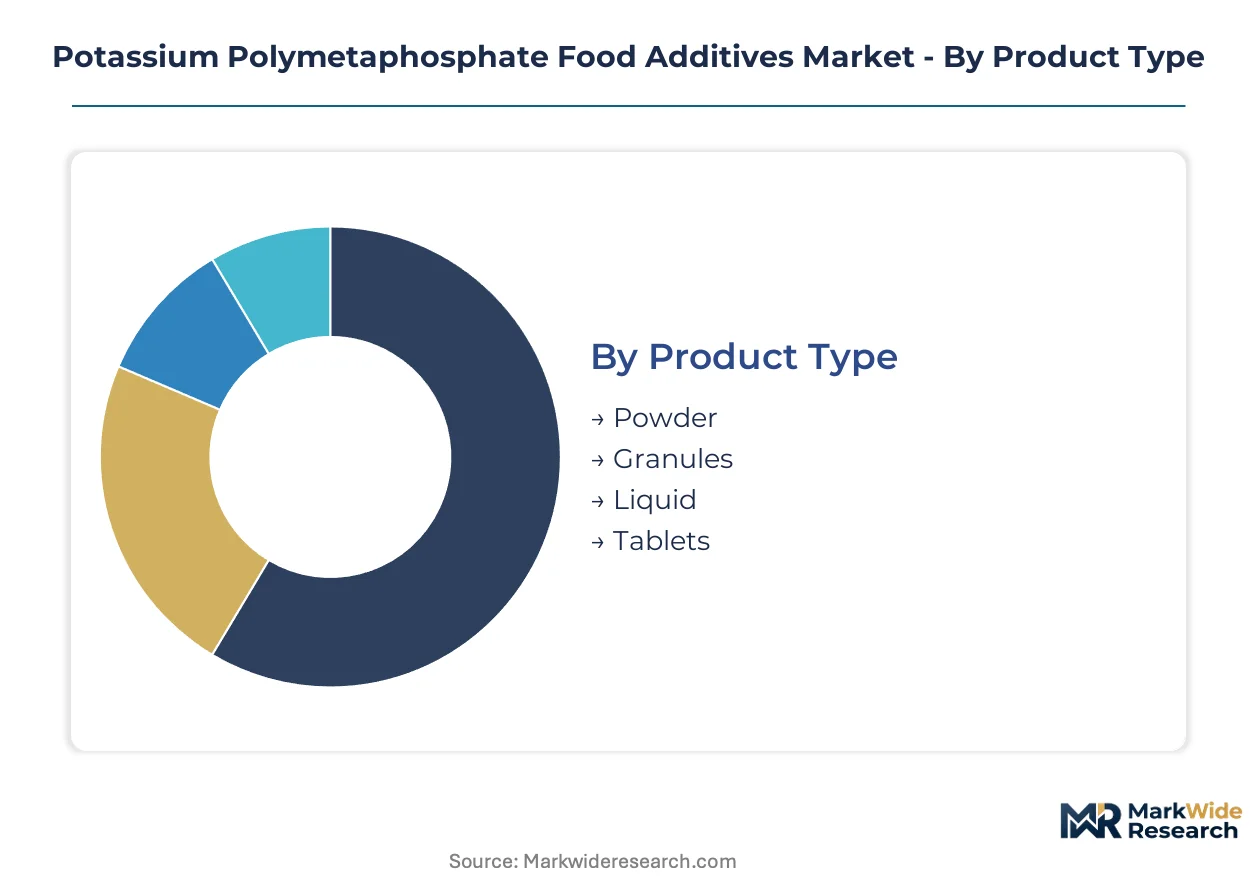
Segmentation in potassium polymetaphosphate reveals how formulation requirements diverge across protein matrices, regulatory jurisdictions, and customer technical capabilities. Understanding these splits illuminates where substitution pressures concentrate and where premium positioning holds.
Product Type:
Powder and liquid formats face divergent substitution threats from native protein emulsifiers and clean-label hydrocolloids.
- Powder:Dominant format with precise dosing control in industrial blending operations. São Paulo poultry processors and Indonesian noodle manufacturers specify powder grades for moisture-binding consistency under ANVISA and BPOM food safety codes.
- Liquid:Rapid dispersion characteristics capture functional water and isotonic beverage applications. US Midwest meatpackers specify liquid grades for sodium-reduced processed meat hydration protocols requiring application-specific customization.
- Granules:Intermediate flow properties suit intermediate-scale bakery operations without pneumatic conveying infrastructure.
- Tablets:Compressed formats serve laboratory and quality control calibration needs in food-grade certification workflows.
Powder retains volume leadership; liquid holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity protein processing from premium beverage formulation opportunities.
- Meat Processing:Primary demand concentration in Brazil's Paraná processing belt and US Midwest packing facilities. EFSA ANS cumulative exposure thresholds and FDA 21 CFR compliance reshape phosphate additive selection toward potassium polymetaphosphate substitution.
- Beverages:Functional water and isotonic drink manufacturers specify liquid-grade formats for rapid dissolution. Chinese SAMR GB 1886.181 heavy metal limits constrain supplier qualification for this premium segment.
- Bakery Products:Moisture retention applications in Southeast Asian commercial baking operations drive steady powder-grade procurement.
- Dairy Items:Texture stabilization in processed cheese systems faces displacement from native milk protein restructuring technologies.
Meat Processing commands the largest revenue pool; Beverages is expanding most quickly.
Grade:
Customer type concentration determines margin capture across certification tiers.
- Food Grade:FSSC 22000 compliance overhead and batch certification costs command premium positioning over technical variants. Mid-tier Chinese producers achieving certification gain qualified supplier status with multinational protein processors seeking dual-source security.
- Technical Grade:Industrial sequestrant applications in water treatment and metal finishing absorb commodity pricing pressure without food-safety compliance burden.
- Pharmaceutical Grade:USP-NF and EP monograph compliance for excipient applications in tablet binding commands the highest purity premiums.
- Industrial Grade:Ceramic and detergent applications tolerate broader specification tolerances and heavier metal content.
Food Grade dominates value capture; Pharmaceutical Grade holds the highest margin expansion potential.
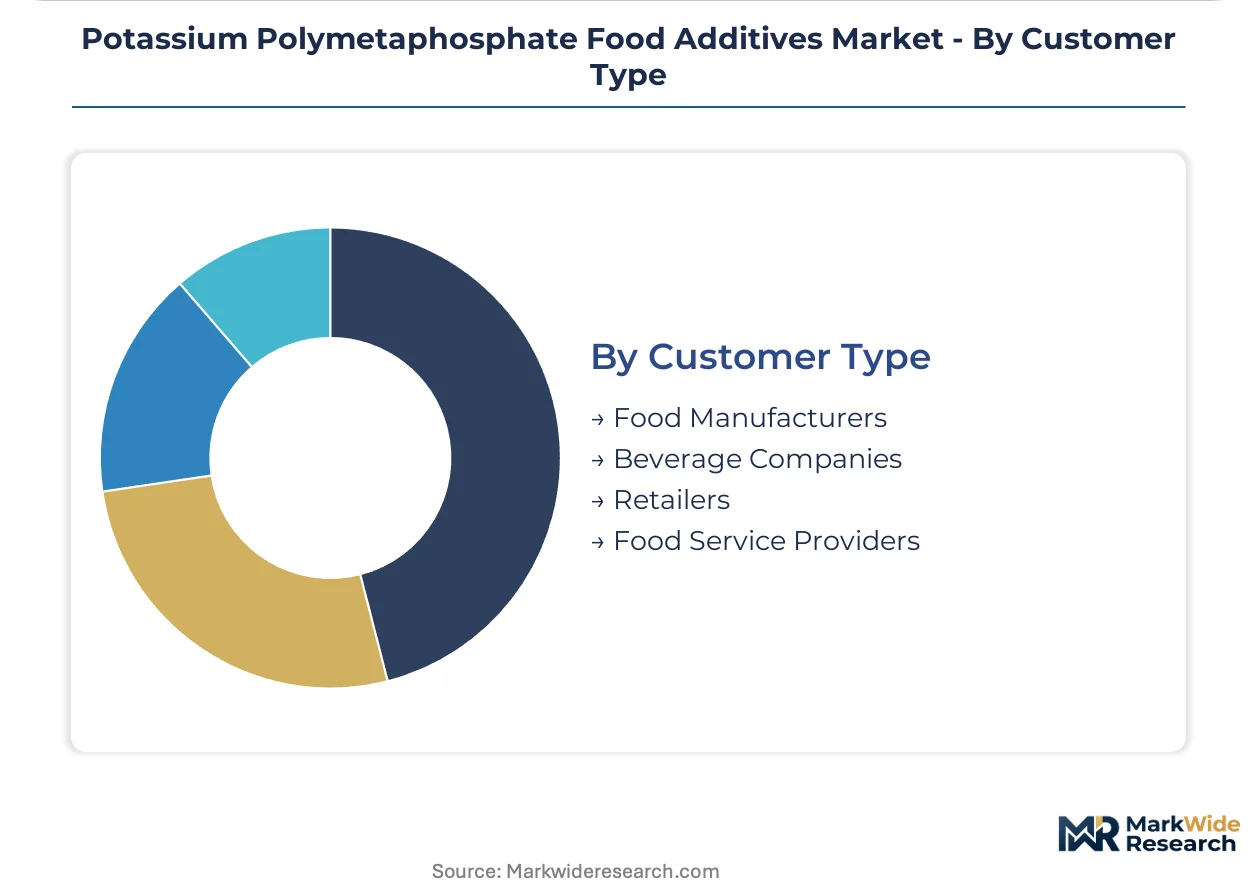
Customer Type:
Supply concentration favors direct technical center engagement over distributor-mediated procurement.
- Food Manufacturers:Large meatpackers contract formulation support directly from supplier technical centers, compressing traditional ingredient distribution margins in sodium-reduced product development.
- Beverage Companies:Functional drink formulators specify liquid-grade potassium polymetaphosphate for rapid dispersion in high-speed bottling operations.
- Food Service Providers:Institutional procurement specifications lag retail-facing manufacturers in phosphate additive transparency requirements.
- Retailers:Private-label processed meat programs drive consolidated phosphate additive procurement through approved supplier lists.
Food Manufacturers retain procurement volume leadership; Beverage Companies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA food safety codes anchor Brazil's processed meat sector, the dominant geography for phosphate additive procurement. SAMR GB standards and EFSA ANS thresholds reshape supplier qualification across Asia and Europe.
Brazil
Poultry belt expansion in São Paulo and Paraná drives phosphate additive volumes for shelf-life compliance. ANVISA mandates under national food safety codes force processors toward certified potassium polymetaphosphate suppliers. São Paulo processing clusters absorb the majority of procurement as exporters target EU and Middle Eastern markets.
China
Instant noodle manufacturers and protein processors scale food-grade phosphate adoption under tightening purity benchmarks. SAMR enforces GB 1886.181 heavy metal limits that disqualify technical-grade producers from food applications. Yangtze River Delta chemical clusters pivot capacity toward FSSC 22000-certified food-grade output for multinational buyers.
Indonesia
Surging instant noodle production demands moisture-binding phosphates for high-temperature frying stability. BPOM food safety regulations align with ASEAN harmonization initiatives for additive purity. Java-based processing corridors concentrate procurement as domestic brands expand export capacity.
United States
Midwest meatpackers contract directly with supplier technical centers for sodium-reduced formulation support. FDA 21 CFR governs additive approval while USDA inspection protocols shape in-plant usage standards. Chicago and Omaha processing hubs drive liquid-grade demand for hydration protocol customization.
Germany
EFSA ANS cumulative exposure thresholds accelerate potassium polymetaphosphate substitution in processed meat formulations. REACH authorization timelines for phosphate intermediates extend chemical registration burdens for domestic producers. Bavarian protein processors lead reformulation efforts as EU-wide regulatory tightening cascades through supply chains.
Potassium Polymetaphosphate Food Additives Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive phosphate rock access separating the two. ICL Group anchors the upper tier through Negev-based ore control, while Prayon and Innophos occupy specialist positions anchored by regional technical centers. Budenheim and TKI Hrastnik represent mid-scale European fabricators with regulatory navigation depth. Competitive moves concentrate on backward integration into phosphate rock and FSSC 22000 certification arbitrage for Asian market access.
Among Israel-based integrated producers, ICL Group exemplifies the captive-resource archetype. Innophos and Prayon occupy the technical-service tier, with the former anchoring North American demand through New Jersey-based formulation support and the latter navigating European regulatory complexity from Belgian operations. Haifa Group and Nutrien Ltd represent diversified agricultural-chemical players with phosphate additive exposure.
| Leading Market Players |
|---|
| ICL Group |
| Innophos |
| Prayon |
| Aditya Birla Chemicals |
| Nutrien Ltd |
| Fosfa |
| Budenheim |
| TKI Hrastnik |
| Haifa Group |
| Others |
Value Network & Pricing Analysis
Capacity utilization differentials between integrated Negev-based producers and independent Chinese fabricators compress price floors for food-grade certification tiers. Scale advantages at ICL Group's captive rock operations sustain margin buffers that technical-grade competitors cannot match under SAMR GB 1886.181 compliance burdens.
Pricing Analysis
Geographic price spreads separate EU-located supply under REACH authorization timelines from Middle Eastern and North African manufacturing zones with streamlined chemical notification pathways. Three-tier pricing structure across food-grade, technical-grade, and pharmaceutical-grade certification levels reflects batch certification overhead and FSSC 22000 compliance costs. Cost compression in technical-grade segments is intensifying as Yangtze River Delta chemical clusters pivot capacity toward certified food-grade output. Beverage manufacturers specifying liquid-grade formats for rapid dispersion exhibit the lowest price sensitivity; industrial-grade ceramic applications demonstrate the highest.
Supply Chain Analysis
Israel and Morocco anchor phosphate rock supply through ICL Group's Negev operations and state-linked ore access, constraining independent processor feedstock security. Thermal dehydration equipment and monopotassium phosphate precursors draw from German and Japanese specialty chemical suppliers. Single-source vulnerability concentrates in captive ore access controlled by integrated producers. Distribution runs through direct technical center engagement with large meatpackers, compressing traditional ingredient distribution margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation support services and application-specific hydration protocol customization expand faster than commodity powder-grade volume, creating service-attach revenue pools for qualified suppliers.
For Market Incumbents: Shield food-grade positioning through FSSC 22000 certification arbitrage at mid-tier Chinese production assets, securing dual-source supplier status with multinational protein processors. Deepen backward integration into phosphate rock where geologically feasible, or lock long-term offtake agreements with Moroccan state-linked suppliers to offset captive ore concentration. Counter plant-based protein substitution threats by embedding technical service teams directly into sodium-reduced processed meat development workflows at US Midwest meatpackers. For New Entrants and Emerging Players: Anchor in Vietnam's underpenetrated poultry and seafood processing infrastructure, where technical service partnerships face limited incumbent saturation. Target liquid-grade beverage system dispersion as the most penetrable application segment, where rapid dissolution requirements favor rapid-delivery supply models over established powder-grade relationships. Pursue direct engagement with functional water and isotonic drink formulators seeking hydration protocol customization without legacy distributor markups. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated phosphate chemistry specialists with captive rock access and thermal dehydration expertise scarcity. Long-term viability rests on regulatory navigation depth across FDA, EFSA, and SAMR jurisdictions rather than commodity scale alone. Watch for inflection signals in EFSA ANS cumulative exposure threshold revisions that would accelerate potassium polymetaphosphate substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Rock | Captive ore access at ICL Group's Negev deposits insulates supply security from Moroccan state-linked concentration. |
| FSSC 22000 Certification Arbitrage | Mid-tier Chinese producers achieving certification gain qualified supplier status with multinational protein processors. |
| Technical Center Direct Engagement | Innophos's Caldwell, New Jersey facility anchors North American formulation support, compressing distributor margins. |
| Liquid-Grade Capacity Expansion | Rapid dispersion formats capture functional water and isotonic drink applications where bottling speed matters. |
| Controlled-Atmosphere Thermal Dehydration Retrofit | Brazilian poultry processors adopt tighter molecular weight distribution technology to meet ANVISA shelf-life mandates. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with phosphate additive procurement managers at Brazilian poultry processors, Indonesian noodle manufacturers, and US Midwest meatpackers; and secondary validation through customs trade data, SEC filings from listed chemical producers, and SAMR GB standard documentation. Plant managers at Yangtze River Delta chemical clusters, technical R&D directors at European phosphate fabricators, and distribution channel partners in Southeast Asian food ingredient supply provided operational perspective. Bottom-up volume triangulation across grade tiers and applications converged with top-down market sizing from producer capacity disclosures.
Across the projection horizon, the analytical framework modeled segmentation dimensions including product format, application matrix, certification grade, and customer procurement channel. CAGRs were derived from elasticity-adjusted demand projections tied to protein processing capacity expansion in named geographies. Forecast inputs incorporated regulatory threshold revision probabilities from EFSA ANS panel deliberations and thermal dehydration expertise scarcity constraints on qualified production scale-up.
Underlying assumptions cover sustained ANVISA and BPOM enforcement of phosphate additive shelf-life mandates, with deviation risk concentrated in abrupt EFSA cumulative exposure limit tightening or accelerated plant-based protein displacement in clean-label meat analogs. Recalibration cycles align with material shifts in regulatory threshold announcements and major capacity investment completions at integrated producers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Australia Food Colorants Market
Food Additives and Ingredients
Africa Food Enzymes Market
Food Additives and Ingredients
Chymosine Market
Food Additives and Ingredients
Oleic Acid Market
Food Additives and Ingredients
Sucroglycerides Market
Food Additives and Ingredients
Italy Food Emulsifier Market
Food Additives and Ingredients
Monosodium Glutamate Market
Food Additives and Ingredients
Sodium Propionate Market
Food Additives and Ingredients
Italy Food Enzymes Market
Food Additives and Ingredients
Food Grade Potassium Sorbate Market
Food Additives and Ingredients
Asia-Pacific Anti-Caking Market
Food Additives and Ingredients
Salt Substitutes Market
Food Additives and Ingredients
Plant-Based Emulsifiers Market
Food Additives and Ingredients
Flour Treatment Agent Market
Food Additives and Ingredients
Europe Food Colorants Market
Food Additives and Ingredients
Methyl Oleate Market