
 Solanesol Market | 2026-2036
Solanesol Market Size, Share, and Industry Trends Forecast 2026-2036
Solanesol Market Analysis
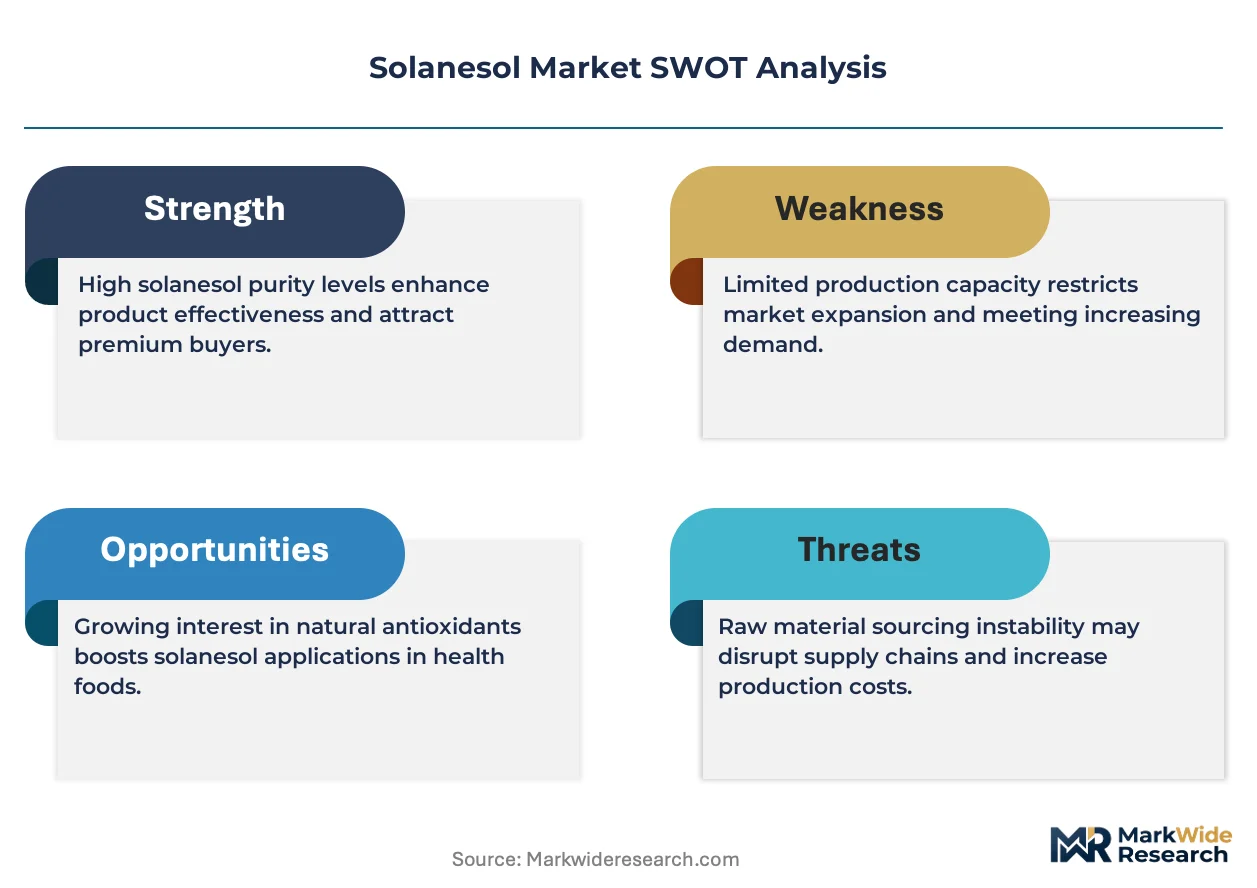
Pharmaceutical manufacturing is repositioning solanesol as a critical precursor for cardiovascular and metabolic therapeutics. Yunnan Lilian Biotechnology leverages its proximity to Yunnan's tobacco-growing regions to secure raw material streams. Zhejiang Yixin Pharmaceutical sustains competitive positioning through synthetic process optimization that reduces batch-to-batch variability. ExtRx anchors North American supply relationships through distributor networks serving contract research organizations.
Solanesol is a linear isoprenoid alcohol (C45H74O) extracted primarily from tobacco leaves or produced via synthetic routes, serving as a key building block for ubiquinone and vitamin K analog synthesis. Natural Solanesol commands premium positioning in nutraceutical applications where traceability certifications support margin pools, while Synthetic Solanesol occupies volume-driven pharmaceutical contracts requiring consistent stereochemistry. Solanesol Derivatives represent the fastest-expanding category as functionalized intermediates enable next-generation drug conjugates.
China's NMPA enforces GB standards for pharmaceutical-grade solanesol purity, while India's CDSCO mandates import testing protocols that shape cross-border trade flows. REACH compliance in Europe restricts certain solvent residues from natural extraction processes, redirecting investment toward green chemistry alternatives. Stakeholders must monitor regulatory divergence between biosynthetic and petrochemical-derived pathways as classification frameworks evolve across major jurisdictions.
Market Dynamics
Pharmaceutical procurement of solanesol is accelerating as cardiovascular therapeutic pipelines expand, tightening feedstock competition between natural extraction clusters and synthetic production facilities.
Growth Catalysts
- Coenzyme Q10 synthesis expansion:Cardiovascular drug manufacturers are scaling solanesol procurement for ubiquinone production, creating sustained pull from pharmaceutical contract manufacturers.
- REACH green chemistry mandates:European ECHA restrictions on petrochemical-derived solvents are redirecting investment toward biosynthetic extraction pathways that reduce environmental liability.
- Tobacco-leaf processing consolidation:Zhejiang and Yunnan province clusters in China are integrating backward into solanesol recovery, securing captive feedstock streams for derivative production.
Market Restraints
- Feedstock concentration risk:Natural solanesol extraction depends on tobacco-leaf supply chains concentrated in specific Chinese provincial clusters, creating geographic single-point vulnerability.
- Synthetic route cost structure:Petrochemical-derived solanesol production faces input cost volatility from C5 isoprene feedstock prices tied to naphtha cracking economics.
- Solvent residue compliance:REACH and EPA regulations on extraction solvent traces create batch rejection risk for natural product shipments entering regulated markets.
Strategic Opportunities
- Biosynthetic pathway development:Microbial fermentation of solanesol precursors using engineered yeast strains offers route diversification beyond tobacco dependence.
- CDSCO import testing alignment:Indian pharmaceutical manufacturers are qualifying solanesol suppliers against CDSCO protocols, opening procurement relationships for compliant exporters.
- Functionalized derivative expansion:Drug conjugate applications requiring site-specific solanesol modifications represent unpenetrated demand from oncology and immunology pipelines.
Industry Challenges
- Chiral purity certification timelines:Pharmaceutical-grade solanesol requires stereochemical verification protocols that extend batch release cycles by 4-6 weeks.
- Extraction technician scarcity:Natural product isolation expertise in supercritical CO2 and chromatographic purification is concentrating at specialized contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solanesol Market |
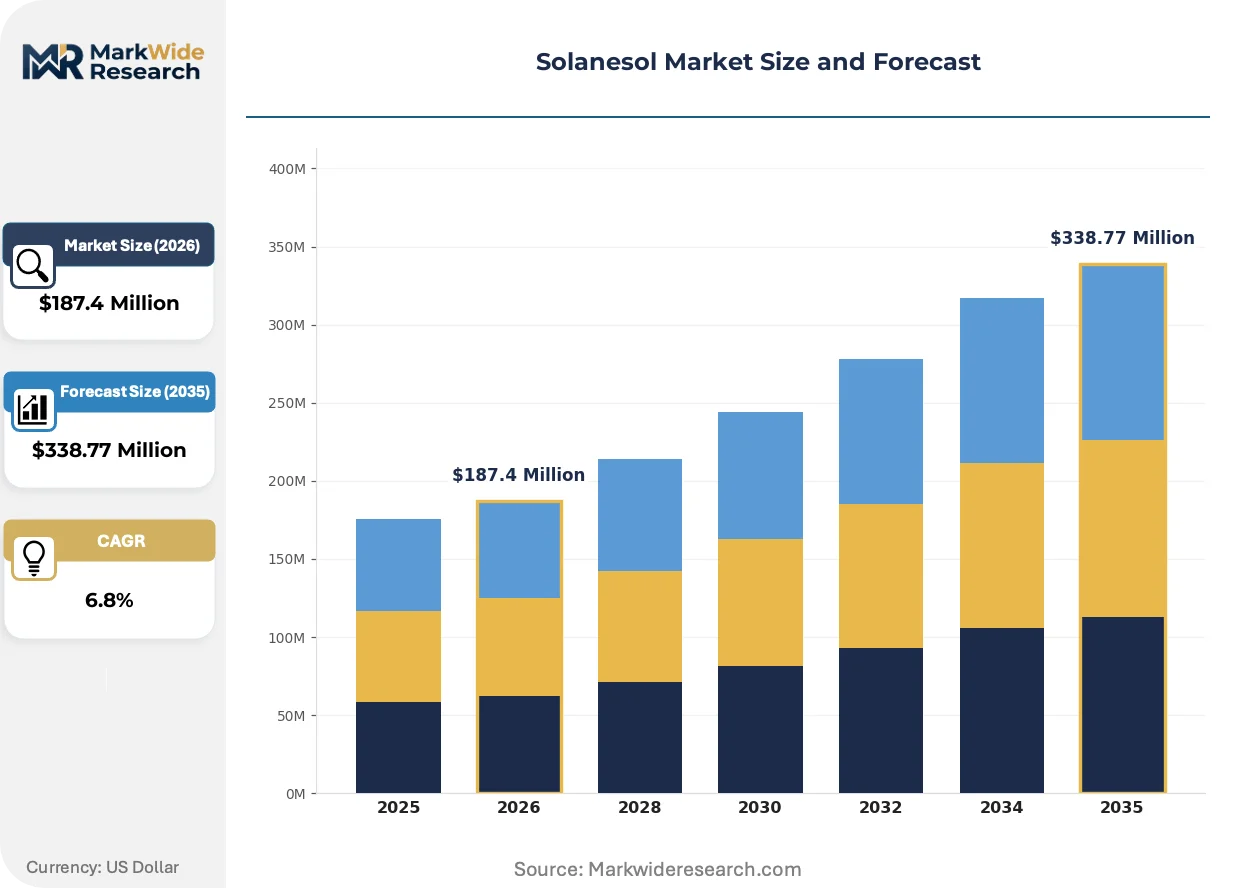
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Solanesol, Synthetic Solanesol, Solanesol Derivatives, Solanesol Compounds Application: Pharmaceuticals, Nutraceuticals, Cosmetics, Agrochemicals End User: Healthcare Providers, Food Manufacturers, Cosmetic Brands, Agricultural Enterprises Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Yunnan Lilian Biotechnology, Wuhan Xinyangruihe Chemical Technology, ExtRx, Xi'an TonKing, TCI Chemicals (India), Zhejiang Yixin Pharmaceutical, JSN Chemicals, Zhongshan Belling Biotechnology, Capot Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solanesol Market Emerging Trajectories
Process intensification and regulatory chemistry shifts are compressing the viable pathway set for solanesol production, favoring operators with integrated quality systems over commodity traders.
Supercritical CO2 extraction technology is absorbing market share from conventional solvent-based methods in natural solanesol recovery. Nutraceutical manufacturers in Germany and Switzerland are adopting CO2 systems to satisfy EFSA traceability requirements. This shift is absorbing capital that previously flowed into hexane extraction infrastructure, consolidating equipment vendor relationships around specialized system integrators.
China's NMPA is tightening GB pharmaceutical purity benchmarks for natural extraction methods. The industrial consequence is disqualification of smaller tobacco processors lacking chromatographic finishing capability. Synthetic solanesol producers with certified stereochemistry are capturing displaced pharmaceutical contracts previously served by natural suppliers.
Contract research organizations are consolidating solanesol procurement through qualified distributor networks rather than direct manufacturer relationships. North American CROs are channeling volume through specialty chemical distributors with documented chain-of-custody protocols. This behavioral shift is most visible in Massachusetts and California biotech clusters where audit requirements exceed standard commercial documentation.
Solanesol Market Segmentation
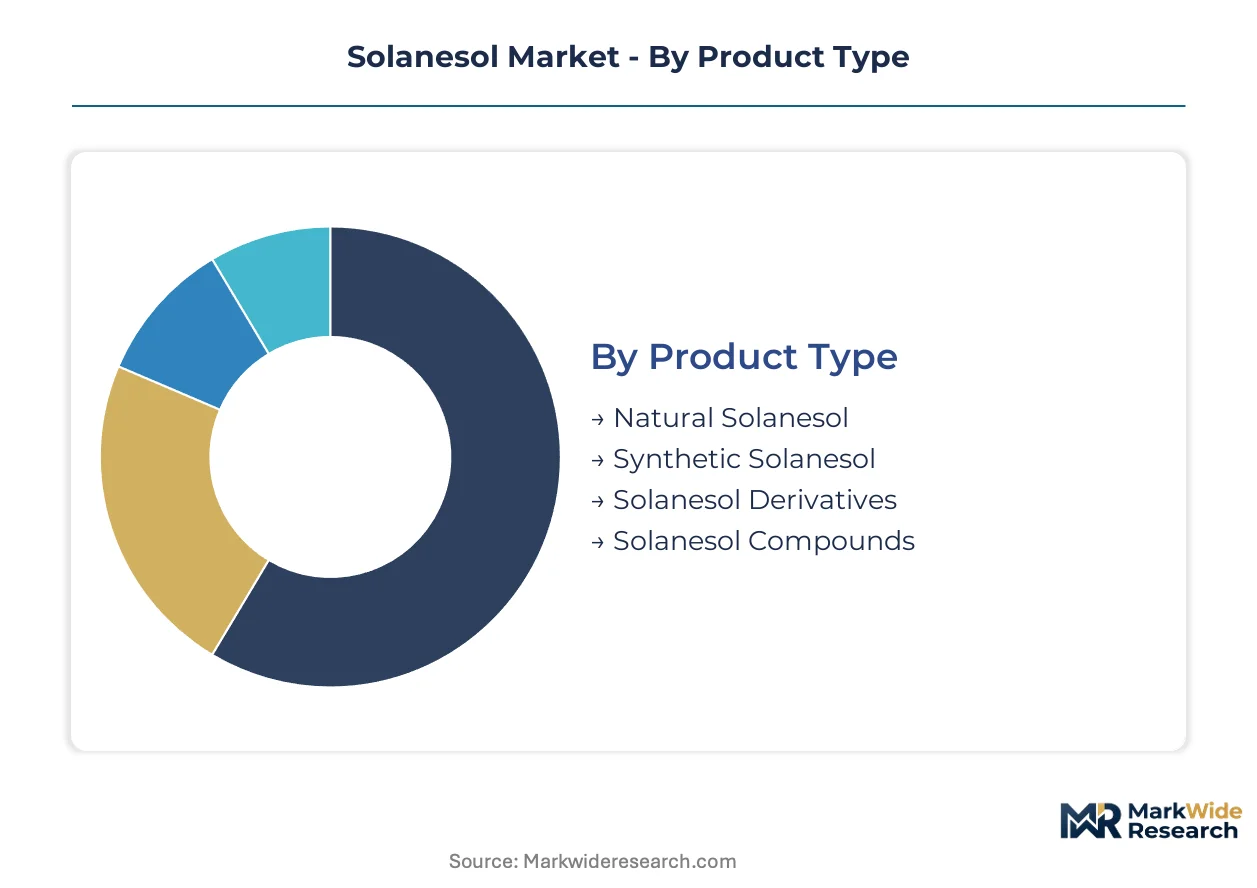
Solanesol procurement patterns split sharply between premium natural grades and volume synthetic contracts. Pharmaceutical manufacturers select segments based on stereochemistry requirements and regulatory filing status, while nutraceutical buyers prioritize traceability certifications that command margin premiums.
Product Type:
Volume concentrates in synthetic routes, yet premium positioning belongs to certified natural extraction with full agricultural traceability.
- Natural Solanesol:Extracted from tobacco leaf waste streams through supercritical CO2 or solvent-based methods, this grade carries C45H74O isoprenoid alcohol with batch-specific stereochemical profiles. Demand clusters in German and Swiss nutraceutical facilities where EFSA traceability mandates require documented agricultural sourcing from Yunnan or Zhejiang province processors.
- Synthetic Solanesol:Petrochemical-derived via C5 isoprene oligomerization delivers consistent stereochemistry critical for FDA pharmaceutical filings. Contract manufacturers in Massachusetts and California biotech corridors specify synthetic grades for ubiquinone synthesis where batch-to-batch variability would invalidate regulatory submissions.
- Solanesol Derivatives:Functionalized intermediates for drug conjugate applications represent the category gaining share fastest, driven by oncology pipeline expansion requiring site-specific molecular modifications.
- Solanesol Compounds:Pre-formulated blends with co-solvents or stabilizers serve agrochemical and cosmetic compounders seeking processing efficiency over raw material handling.
Today's leader: Synthetic Solanesol. Tomorrow's challenger: Solanesol Derivatives.
Application:
Pharmaceutical ubiquinone synthesis absorbs the largest procurement volumes, though nutraceutical CoQ10 supplements sustain higher per-kilogram pricing.
- Pharmaceuticals:Cardiovascular therapeutic manufacturers specify pharmaceutical-grade solanesol for coenzyme Q10 synthesis, with CDSCO import testing in India and NMPA GB standards in China governing acceptable purity thresholds. Synthetic routes dominate this segment due to stereochemistry certification requirements.
- Nutraceuticals:Dietary supplement producers in Germany and Switzerland pay premiums for natural solanesol with EFSA-compliant traceability documentation, sourcing through specialized distributors with chain-of-custody protocols.
- Cosmetics:Anti-aging formulations incorporate solanesol for its antioxidant properties, with formulators in South Korea and Japan specifying cosmetic-grade purity tiers.
- Agrochemicals:Plant growth regulator applications consume lower-purity grades, with agricultural enterprises in Brazil and India sourcing through bulk chemical distributors.
Pharmaceutical contracts anchor current revenue; nutraceutical premiums offer the steepest expansion trajectory for compliant natural suppliers.
End User:
Procurement sophistication varies dramatically across buyer types, from CRO audit requirements to agricultural commodity purchasing.
- Healthcare Providers:Hospital systems and specialty clinics rarely source directly; instead they rely on pharmaceutical manufacturers who integrate solanesol into finished cardiovascular therapeutics with full regulatory documentation.
- Food Manufacturers:Functional food producers in Japan and South Korea specify solanesol for fortified beverages and nutritional bars, requiring FSSAI or MFDS compliance for regional market access.
- Cosmetic Brands:Premium skincare houses in France and Switzerland contract for solanesol derivatives with documented supercritical CO2 extraction to support clean-label marketing claims.
- Agricultural Enterprises:Large-scale farming operations in Brazil and India purchase solanesol compounds through agrochemical distributors for plant growth applications with less stringent purity requirements.
Cosmetic brands currently pay the highest purity premiums; food manufacturers represent the most price-sensitive volume opportunity.
Distribution Channel:
Channel selection tracks directly with buyer sophistication and audit burden, fragmenting the supply base between commodity traders and qualified specialists.
- Direct Sales:Pharmaceutical manufacturers with annual volume commitments negotiate directly with synthetic solanesol producers in Zhejiang province, bypassing intermediaries to secure batch-specific stereochemistry documentation.
- Online Retail:Small-scale nutraceutical formulators and research laboratories source gram-to-kilogram quantities through specialized chemical marketplaces with documented CAS registry and SDS compliance.
- Distributors:North American CROs in Massachusetts and California consolidate procurement through specialty distributors with qualified vendor programs, chain-of-custody protocols, and audit-ready documentation packages.
- Wholesalers:Agricultural and industrial buyers in Brazil and India access solanesol compounds through regional chemical wholesalers offering volume pricing with limited technical support.
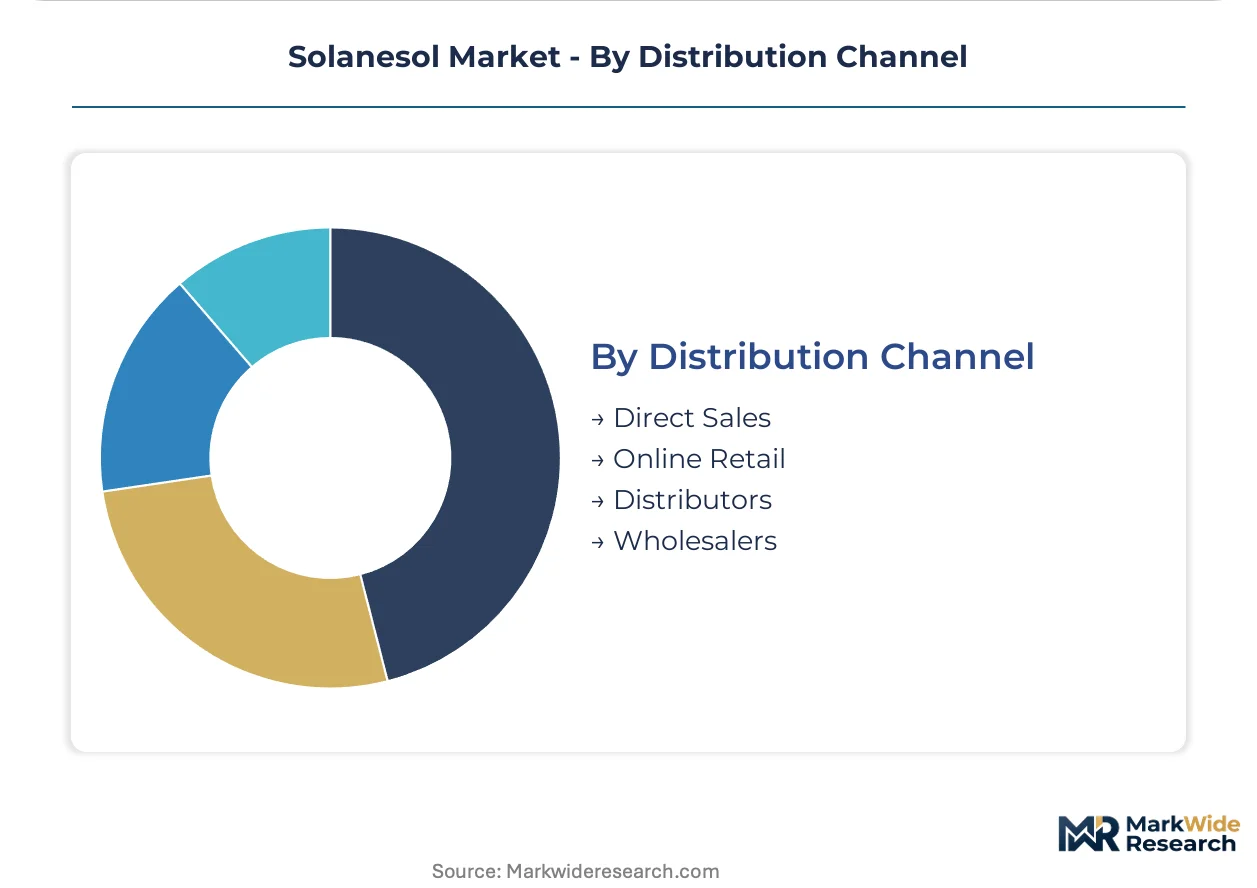
Distributors capture the most sophisticated pharmaceutical demand; direct sales retain the largest synthetic volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting solanesol production toward jurisdictions with lower compliance burdens for natural extraction methods, while synthetic capacity concentrates in regions with established petrochemical infrastructure and stereochemistry certification capabilities.
China
Pharmaceutical-grade solanesol procurement from Zhejiang and Yunnan province clusters is tightening under NMPA GB purity benchmarks. The country's dual carbon goals are pressuring tobacco-leaf processors to adopt supercritical CO2 extraction systems that reduce solvent residue liabilities. Hangzhou and Kunming industrial zones are consolidating backward into captive feedstock recovery to secure supply chains for derivative production.
United States
Massachusetts and California biotech corridors are driving synthetic solanesol demand for FDA-tracked ubiquinone synthesis. EPA restrictions on residual extraction solvents are disqualifying certain natural grades from pharmaceutical contracts. Greater Boston CROs are channeling procurement through qualified distributors with documented chain-of-custody protocols rather than direct manufacturer relationships.
India
CDSCO import testing protocols are reshaping cross-border supplier qualification for pharmaceutical-grade material. Mumbai and Hyderabad pharmaceutical manufacturers are expanding CoQ10 synthesis capacity, creating pull for compliant solanesol feedstock. Gujarat chemical processors are investing in stereochemistry verification capabilities to meet domestic regulatory filing requirements.
Germany
EFSA traceability mandates are sustaining premium pricing for natural solanesol with documented agricultural sourcing. REACH green chemistry restrictions on petrochemical-derived solvents are redirecting investment toward biosynthetic extraction pathways. Bavarian and Baden-Württemberg nutraceutical facilities are adopting supercritical CO2 systems to satisfy environmental liability standards.
Switzerland
Swissmedic pharmaceutical purity requirements are reinforcing demand for synthetic grades with certified stereochemistry. Basel-area contract manufacturers are specifying solanesol for cardiovascular therapeutic pipelines with full regulatory documentation. Geneva-based distributors are consolidating procurement relationships with Chinese processors capable of EFSA-compliant traceability certification.
Solanesol Market Vendor Landscape
Capacity expansion dominates the current landscape as processors invest in supercritical CO2 infrastructure to satisfy tightening solvent residue regulations. The vendor base organizes around three archetypes: tobacco-proximate natural extractors with captive feedstock, petrochemical-derived synthetic producers with stereochemistry certification, and specialized distributors with qualified vendor programs. Strategic differentiation flows from backward integration into tobacco-leaf processing and technology licensing for biosynthetic pathway development.
Within the natural extraction tier, Yunnan Lilian Biotechnology and Zhejiang Yixin Pharmaceutical occupy positions anchored to provincial tobacco-growing regions. Wuhan Xinyangruihe Chemical Technology represents the synthetic production archetype with petrochemical route capabilities. ExtRx sits within the specialized distribution tier serving North American CRO networks with audit-ready documentation packages.
| Leading Market Players |
|---|
| Yunnan Lilian Biotechnology |
| Wuhan Xinyangruihe Chemical Technology |
| ExtRx |
| Xi'an TonKing |
| TCI Chemicals (India) |
| Zhejiang Yixin Pharmaceutical |
| JSN Chemicals |
| Zhongshan Belling Biotechnology |
| Capot Chemical |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical procurement mandates for stereochemistry certification are forcing natural extractors to invest in chromatographic finishing capacity, compressing margins for smaller tobacco processors while synthetic producers capture displaced volume at premium contract rates.
Pricing Analysis
Distributor margins absorb 15-25% of final pharmaceutical pricing as North American CROs consolidate procurement through qualified vendor programs with chain-of-custody documentation. Three-tier pricing structure across pharmaceutical-grade, nutraceutical-grade, and industrial-grade solanesol separates FDA-tracked synthetic contracts from EFSA-traceable natural premiums and agrochemical commodity volumes. Cost compression in natural extraction is intensifying because REACH solvent residue restrictions disqualify hexane-based batches from regulated markets. Agricultural buyers in Brazil and India exhibit highest price sensitivity, while Swiss and German nutraceutical manufacturers accept 40-60% premiums for supercritical CO2 extraction with full agricultural traceability.
Supply Chain Analysis
Refurbishment flows for supercritical CO2 extraction equipment are extending asset lifecycles among Yunnan and Zhejiang processors, reducing capital requirements for natural solanesol recovery. Raw material sourcing draws from tobacco-leaf waste streams in China, C5 isoprene feedstock from South Korean and Japanese petrochemical complexes, and engineered yeast strains from German biosynthetic development facilities. Single-source vulnerability concentrates in Yunnan province clusters where tobacco-growing regions anchor captive feedstock supply. Distribution runs through specialty chemical distributors serving Massachusetts and California biotech corridors, direct manufacturer relationships for volume pharmaceutical contracts, and regional wholesalers for Brazilian and Indian agrochemical applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solanesol demand functions as a stable compounder anchored to cardiovascular therapeutic pipelines where coenzyme Q10 synthesis creates non-discretionary procurement pull from contract manufacturers.
For Market Incumbents: To counter displacement by synthetic producers with certified stereochemistry, natural extractors should deepen backward integration into tobacco-leaf processing clusters in Yunnan and Zhejiang provinces, securing captive feedstock streams while investing in supercritical CO2 systems that satisfy REACH green chemistry mandates. For New Entrants and Emerging Players: Specialty distributors with qualified vendor programs represent the most accessible entry vector for penetrating North American CRO networks in Massachusetts and California, where audit requirements exceed standard commercial documentation and incumbent relationships remain underconsolidated. For Investors and Strategic Acquirers: Asymmetric upside sits with biosynthetic pathway developers using engineered yeast strains, given their route diversification beyond tobacco dependence and alignment with European ECHA restrictions on petrochemical-derived solvents. Long-term viability hinges on microbial fermentation scale-up capabilities; practitioners should monitor CDSCO import testing protocol expansions and NMPA GB purity benchmark tightening as regulatory inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tobacco Processing | Yunnan and Zhejiang province clusters secure captive feedstock streams for derivative production. |
| Supercritical CO2 Extraction Adoption | German and Swiss nutraceutical facilities satisfy EFSA traceability and REACH green chemistry requirements. |
| Biosynthetic Pathway Development | Engineered yeast strains offer route diversification beyond geographic concentration in Chinese tobacco regions. |
| CDSCO Import Testing Alignment | Mumbai and Hyderabad pharmaceutical manufacturers qualify compliant suppliers for expanding CoQ10 synthesis capacity. |
| Functionalized Derivative Expansion | Site-specific molecular modifications serve oncology and immunology pipelines requiring drug conjugate intermediates. |
Methodological Framework
Direct dialogue with pharmaceutical procurement managers, tobacco-processing plant operators, supercritical CO2 equipment vendors, regulatory affairs specialists at CDSCO and NMPA, and specialty chemical distributors anchored qualitative findings. Secondary validation drew from customs trade databases, SEC filings of contract research organizations, EMA and FDA submission records for coenzyme Q10 therapeutics, and GB standard documentation from China's Standardization Administration. Bottom-up and top-down triangulation reconciled volume estimates across extraction technology types and application segments.
Bottom-up modeling aggregated capacity utilization rates at Zhejiang and Yunnan province processing facilities, synthetic production yields from C5 isoprene oligomerization, and derivative formulation throughput across pharmaceutical contract manufacturers. Segmentation dimensions spanned product grade tier, end-use application, extraction technology, and regional regulatory cluster. CAGRs were derived from trend extrapolation of procurement volumes against cardiovascular therapeutic pipeline expansion and nutraceutical CoQ10 supplement penetration. Industry-specific forecast inputs included NMPA GB purity benchmark implementation timelines and REACH solvent residue restriction enforcement patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to biosynthetic pathway commercialization rates and tobacco-leaf supply chain disruptions from agricultural policy shifts. Practitioners should monitor CDSCO import testing protocol expansions, NMPA enforcement actions against non-compliant natural extractors, and supercritical CO2 equipment vendor order backlogs for early signals of supply-side restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
India Prussian Blue Market
Specialty Chemicals
Encapsulated Lactic Acid Market
Specialty Chemicals
Cholesteryl Isostearate Market
Specialty Chemicals
Fragrance-Release Control Agents for Long-Lasting Home Care Scents Market
Specialty Chemicals
Global Flame Retardants Market
Specialty Chemicals
Protein Purification Resin Market
Specialty Chemicals
Precast Gels Market
Specialty Chemicals
Global Bio Based Esters Market
Specialty Chemicals
Europe Malic Acid Market
Specialty Chemicals
Ethyl Ascorbic Acid Market
Specialty Chemicals
Octocrylene Market
Specialty Chemicals
Perfluoropolyether (PFPE) Market
Specialty Chemicals
Synthetic and Bio-Based Adipic Acid Market
Specialty Chemicals
Enzyme Inhibitors Market
Specialty Chemicals
Titanium Fluoride Phosphate Market
Specialty Chemicals
Undecylenic Acid Market