
 Bio Polyol and Green Polyol Market | 2026-2036
Bio Polyol and Green Polyol Market Size, Share, and Industry Trends Forecast 2026-2036
Bio Polyol and Green Polyol Market Outlook
Multi-source procurement of bio-based feedstocks is recalibrating supply security for polyurethane producers. BASF SE leverages its integrated petrochemical-biotech complexes to secure non-food crop supply chains across European manufacturing hubs. Cargill Inc. anchors North American bio-polyol output through its captive soybean oil processing infrastructure. Dow Inc. competes on formulation flexibility, blending petroleum and renewable polyethers to meet intermediate sustainability thresholds.
Bio polyols and green polyols are polyether or polyester macromolecules synthesized from renewable feedstocks such as soybean oil, castor oil, or recycled polyethylene terephthalate, designed to replace petroleum-derived polyols in polyurethane synthesis with equivalent hydroxyl values between 28 and 800 mg KOH/g. Their primary industrial purpose centers on reducing cradle-to-gate carbon emissions in flexible foam cushioning, rigid foam insulation, and protective coating systems without sacrificing mechanical performance. Flexible foam formulations currently occupy the largest demand share among product types due to entrenched upholstery and bedding supply chains, while rigid foam applications in construction insulation generate the fastest demand acceleration as energy retrofit mandates tighten across residential and commercial building codes. Polyester polyol formulations sustain premium pricing positions where hydrolytic stability and flame retardance justify material substitution in automotive seating and refrigeration panels.
EPA renewable fuel standards and the EU F-Gas Regulation collectively redirect polyurethane demand toward low-global-warming-potential blowing agents paired with bio-derived polyol matrices, tightening product specifications for imported foam systems. REACH registration requirements for novel bio-based intermediates extend compliance timelines and elevate testing costs for non-European suppliers seeking market access. China's MEE enforces provincial carbon intensity audits that favor domestic producers with verified bio-content certifications. Stakeholders must monitor evolving feedstock competition from food and biofuel sectors as castor and soybean oil prices become structurally linked to agricultural commodity volatility rather than crude oil benchmarks.
Market Dynamics
The EU Green Deal's tightening carbon intensity benchmarks for chemical imports are forcing polyurethane foam manufacturers to requalify entire supply chains around plant-based feedstock polyols with verified bio-content certifications.
Growth Catalysts
- EU F-Gas Regulation:Mandates for low-global-warming-potential blowing agents in insulation systems pair naturally with bio-derived polyol matrices, accelerating formulation switches in construction applications across Germany, France, and Italy.
- China's provincial dual carbon targets:Domestic soy-castor polyol capacity buildouts receive preferential permitting and subsidized utility rates, concentrating new production in Shandong and Jiangsu provinces.
- Castor oil epoxidation:Advances in catalytic ring-opening chemistry now yield hydroxyl-functionalized polyols with equivalent reactivity to petroleum-based polyethers, eliminating performance penalties in flexible foam cushioning.
Market Restraints
- Agricultural commodity volatility:Soybean and castor oil prices decouple from crude oil benchmarks and track food and biofuel demand, creating margin compression for polyol producers without captive crushing infrastructure.
- REACH registration timelines:Novel bio-based intermediates face extended compliance pathways and elevated testing costs for non-European suppliers seeking EU market access, advantaging incumbent registrants.
- Technical hydrolytic stability gaps:Polyester polyol formulations outperform plant-based polyethers in humid environments, limiting substitution rates in marine and tropical climate applications.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Domestic castor seed crushing and downstream polyol production qualify for production-linked incentives, creating a low-cost export hub targeting Middle East and Southeast Asian foam converters.
- Recycled PET-derived aromatic polyols:Chemical glycolysis of post-consumer polyethylene terephthalate yields rigid foam intermediates with superior compressive strength and flame retardance for construction insulation panels.
- Direct-to-mattress-brand distribution:Bypassing traditional chemical distributors, bio-polyol producers establish formulation partnerships with sleep product OEMs seeking certified sustainable supply chains for ESG reporting.
Industry Challenges
- Cross-functional talent scarcity:Formulation chemists with simultaneous expertise in polyurethane catalysis, agricultural supply chains, and carbon accounting command premium compensation, constraining R&D expansion at mid-scale producers.
- Multi-standard certification complexity:Reconciling USDA BioPreferred, EU Ecolabel, and China's GB/T bio-based content methodologies requires redundant testing protocols and extends product qualification cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio Polyol and Green Polyol Market |
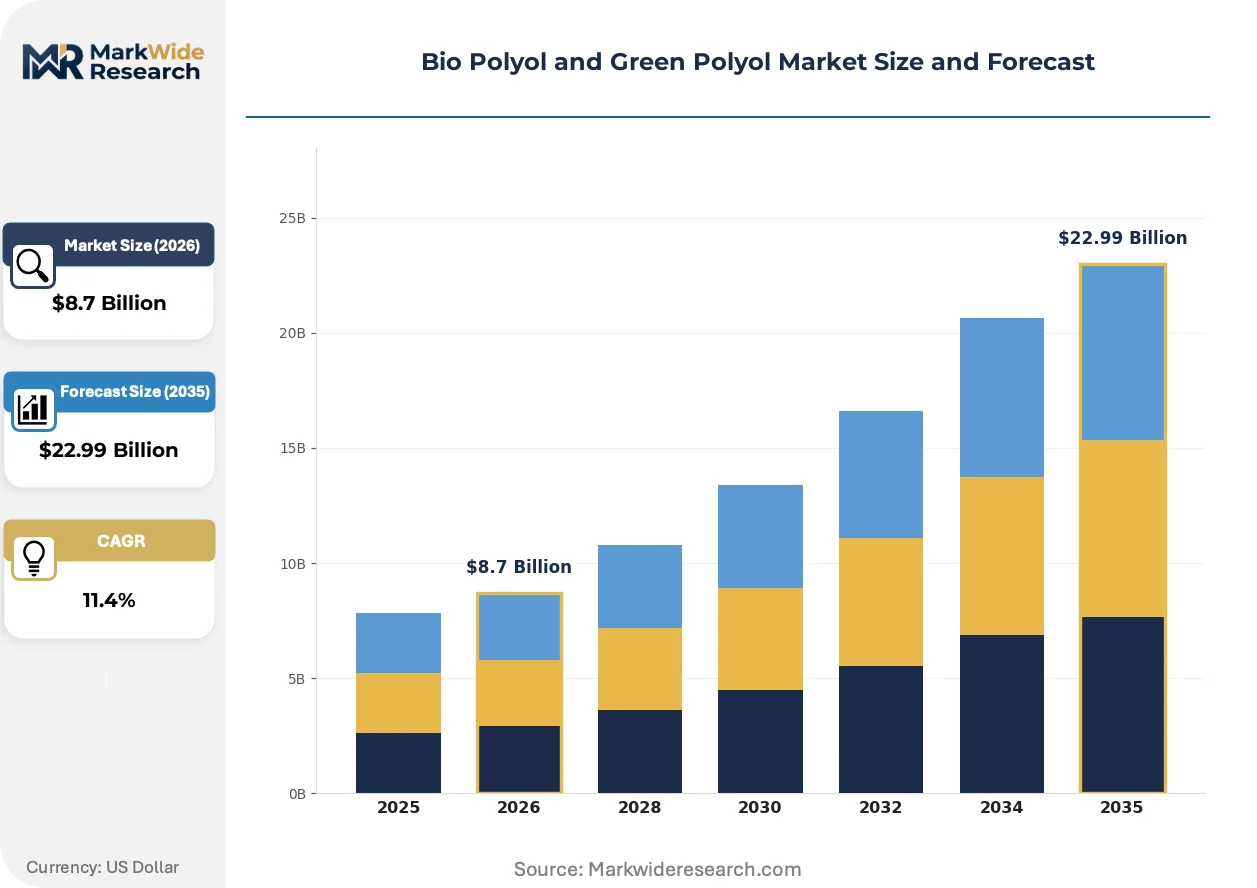
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Foam, Rigid Foam, Coatings, Adhesives Application: Furniture, Automotive, Construction, Footwear End User: Manufacturers, Retailers, Contractors, Designers Formulation: Polyester, Polyether, Blended, Others |
| Companies Covered | Stepan Company, Dow Inc., BASF SE, Emery Oleochemicals, Arkema S.A., Covestro AG, Mitsui Chemicals, Inc, Evonik Industries AG, Cargill Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio Polyol and Green Polyol Market Strategic Shifts
Formulation science and carbon accounting protocols are converging to redefine how polyurethane producers source, certify, and price renewable polyol content across flexible foam, rigid insulation, and coating applications.
Second-generation bio-polyols synthesized from non-food lignocellulosic feedstocks such as wheat straw and corn stover are electrifying research priorities at European and North American chemical institutes. Automotive seating suppliers in Germany and Tier 1 mattress manufacturers in the US Midwest are piloting these materials at 500-2,000 metric ton annual volumes. The technology is electrifying competitive positioning by enabling producers to bypass food-versus-fuel debates and secure supply chains decoupled from agricultural commodity markets.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon blowing agents is tightening product specifications for imported foam systems across all member states. Rigid insulation panel producers must now demonstrate compatibility between bio-polyol matrices and hydrocarbon or hydrofluoroolefin blowing agents through third-party thermal conductivity testing. Construction retrofit mandates in Germany, the Netherlands, and France are driving the fastest demand acceleration for certified low-carbon insulation systems.
Buyers are consolidating procurement authority at the parent-company level and demanding mass-balance certificates traceable to specific crushing facilities. Mattress OEMs and automotive Tier 1s are displacing regional chemical distributors with direct partnerships holding bio-polyol producers accountable for scope 3 emissions data. This pattern is most visible in Germany's industrial corridor, where BASF and Covestro operate integrated petrochemical-biotech complexes with verified supply chain documentation.
Bio Polyol and Green Polyol Market Segmentation
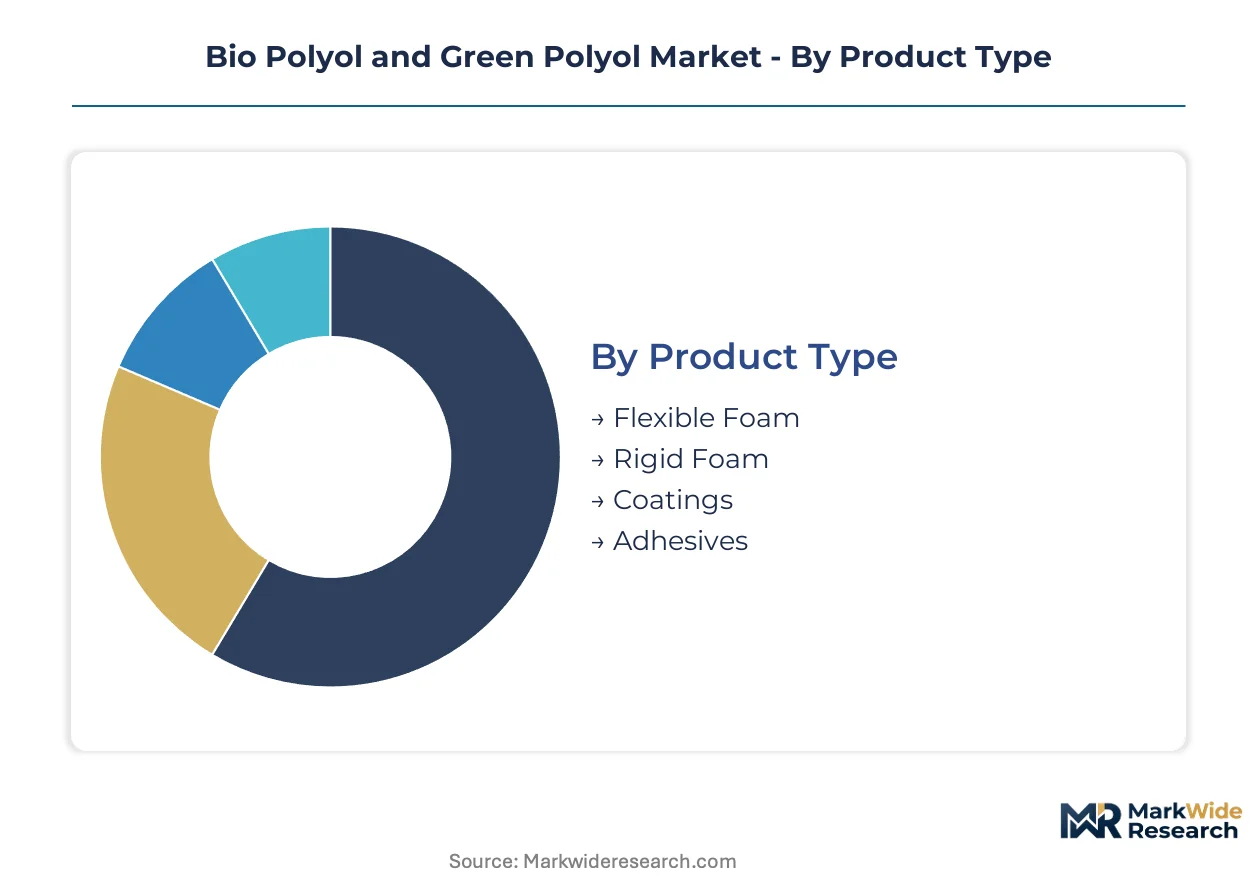
Polyurethane producers configure procurement strategies around performance specifications, carbon accounting requirements, and end-use certification demands. Segmentation reveals where formulation flexibility commands premium pricing versus where commodity substitution drives volume.
Product Type:
Buyers differentiate by thermal performance needs, mechanical durability requirements, and blowing agent compatibility mandates.
- Flexible Foam:Open-cell structures derived from soy-based polyethers dominate cushioning applications with hydroxyl values between 28 and 60 mg KOH/g. Mattress and upholstered furniture manufacturers in Germany and the US Midwest concentrate procurement here, driven by ESG reporting requirements for scope 3 emissions reduction.
- Rigid Foam:Closed-cell insulation systems require higher functionality polyols with hydroxyl values exceeding 400 mg KOH/g to achieve compressive strength above 150 kPa. Construction retrofit mandates across German residential building codes accelerate specification switches toward bio-derived matrices compatible with hydrocarbon blowing agents.
- Coatings:Protective film-forming applications utilize lower-molecular-weight bio-polyols for abrasion resistance in industrial flooring.
- Adhesives:Bonding formulations leverage polyester polyols for hydrolytic stability in moisture-exposed assembly operations.
Volume sits with Flexible Foam; growth tilts toward Rigid Foam.
Application:
End-use sectors impose distinct certification burdens, thermal performance thresholds, and supply chain traceability requirements.
- Furniture:Bedding and seating manufacturers demand mass-balance certificates tied to specific crushing facilities, displacing regional chemical distributors with direct producer partnerships.
- Automotive:Tier 1 seating suppliers in Germany pilot second-generation lignocellulosic polyols at pilot volumes to bypass food-versus-fuel debates and secure supply chains decoupled from agricultural commodity volatility.
- Construction:Rigid insulation panel producers face EU F-Gas Regulation compliance deadlines requiring demonstrated compatibility between bio-polyol matrices and low-global-warming-potential blowing agents through third-party thermal conductivity testing.
- Footwear:Midsole cushioning applications prioritize rebound resilience and density specifications over bio-content percentages.
Procurement concentrates in Furniture; specification evolution runs fastest in Construction.
End User:
Organizational scale and vertical integration depth determine pricing power and formulation co-development access.
- Manufacturers:Integrated polyurethane foam producers with captive slabstock operations negotiate long-term offtake agreements for verified bio-content polyols, securing preferential pricing through volume commitments.
- Retailers:Mattress and furniture brands with direct-to-consumer distribution channels increasingly specify certified sustainable supply chains for ESG disclosure, bypassing traditional chemical distributors.
- Contractors:Construction installation firms face fragmented procurement with limited leverage over formulation specifications.
- Designers:Architectural and industrial design studios influence material selection through sustainability scoring rubrics without direct purchasing authority.
Volume aggregates with Manufacturers; influence migrates toward Retailers.
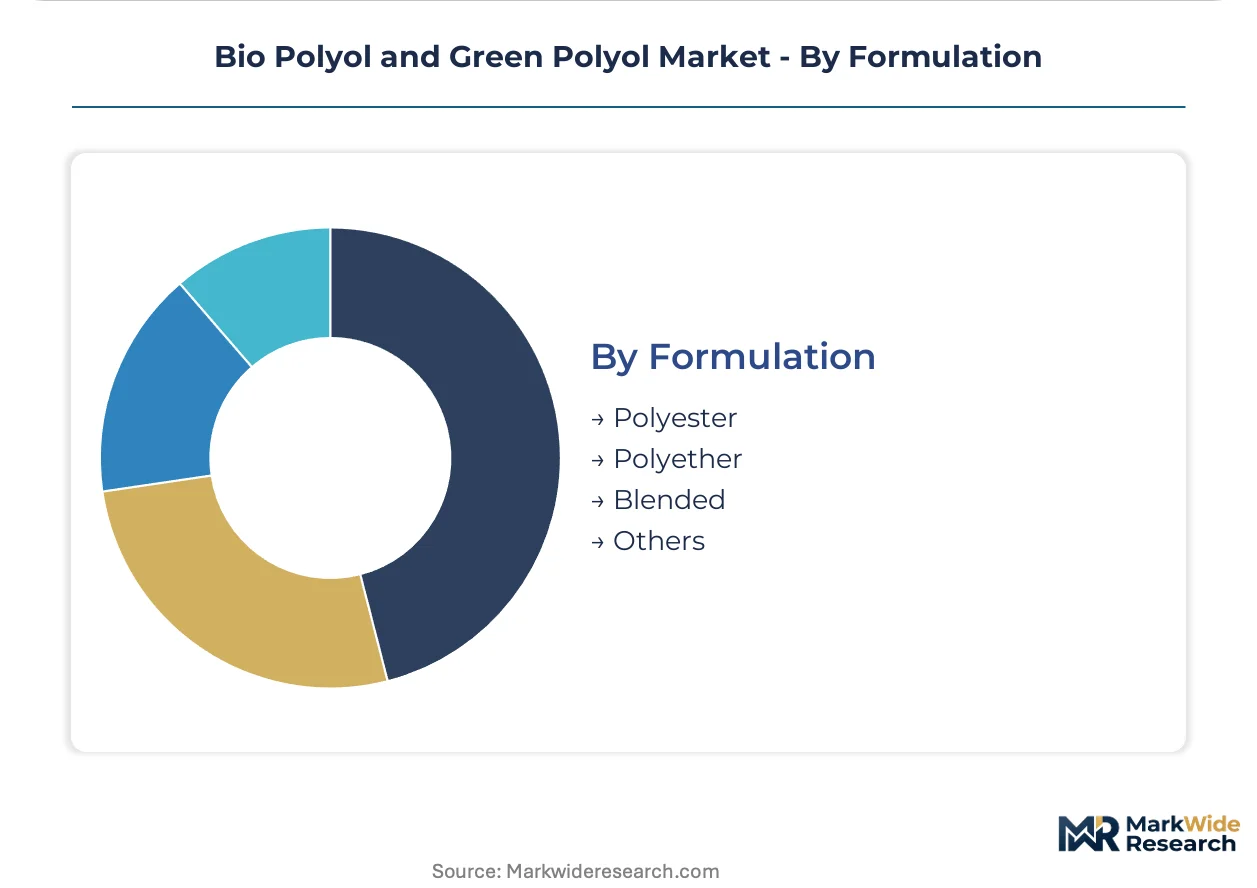
Formulation:
Chemical architecture determines hydrolytic stability, flame retardance compatibility, and feedstock flexibility.
- Polyester:Aromatic and aliphatic structures deliver superior hydrolytic stability and flame retardance in automotive seating and refrigeration panels, sustaining premium pricing positions where performance justifies material substitution.
- Polyether:Flexible foam formulations dominate by volume, with soy-castor feedstocks achieving cost parity in Chinese provincial manufacturing clusters benefiting from subsidized utility rates under dual carbon targets.
- Blended:Intermediate sustainability thresholds combine petroleum and renewable polyethers to meet customer specifications without full bio-content certification costs.
- Others:Emerging recycled PET-derived aromatic polyols from chemical glycolysis of post-consumer polyethylene terephthalate offer rigid foam intermediates with compressive strength advantages for construction insulation panels.
Polyether commands current volume; Polyester and recycled feedstock alternatives gain specification share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Soybean crushing infrastructure in the US Midwest and castor seed processing clusters in India Gujarat anchor raw material flows for bio-polyol production. Regional demand patterns diverge sharply between mature insulation retrofit markets and rapidly scaling flexible foam manufacturing hubs.
United States
Midwest mattress manufacturers and automotive seating suppliers in Michigan and Ohio drive flexible foam procurement. EPA renewable fuel standards redirect agricultural oil flows toward chemical applications. Iowa and Illinois soybean crushing facilities now supply dedicated polyol-grade oil streams separate from biodiesel channels.
Germany
Rigid insulation panel producers in the industrial corridor face EU F-Gas Regulation compliance deadlines for low-global-warming-potential blowing agent compatibility. The EU Green Deal's carbon intensity benchmarks force requalification of entire polyurethane supply chains. BASF and Covestro operate integrated petrochemical-biotech complexes in Ludwigshafen and Leverkusen with verified bio-content documentation.
China
Provincial dual carbon targets accelerate domestic soy-castor polyol capacity buildouts in Shandong and Jiangsu provinces. MEE carbon intensity audits favor producers with verified bio-content certifications. Qingdao and Nanjing manufacturing clusters receive preferential permitting and subsidized utility rates for renewable polyol output.
India
Domestic castor seed crushing and downstream polyol production qualify under the PLI scheme for specialty chemicals. Gujarat's castor processing belt supplies epoxy-hardened polyol intermediates for export markets. Mumbai-Pune industrial corridor foam converters target Middle East and Southeast Asian construction insulation demand.
Japan
Automotive interior specifications from Toyota and Honda Tier 1 suppliers pilot second-generation lignocellulosic polyols at limited volumes. METI carbon neutrality roadmaps pressure chemical producers to demonstrate feedstock traceability. Osaka-Kobe manufacturing hub concentrates formulation R&D for premium seating applications.
Bio Polyol and Green Polyol Market Competitive Environment
Capacity expansion dominates the current landscape as producers race to secure crushing infrastructure and downstream polyol manufacturing positions. The vendor base stratifies between integrated petrochemical-biotech conglomerates and agricultural processors with captive oilseed supply. Three archetypes define competitive positioning: seed-crushing specialists with downstream chemical conversion, diversified chemical majors blending petroleum and renewable feedstocks, and regional foam converters backward-integrating into polyol synthesis. M&A activity concentrates on oilseed processing assets, while strategic partnerships between chemical producers and mattress OEMs displace traditional distributor channels.
Among diversified chemical majors, BASF SE and Covestro AG exemplify integrated European producers with verified supply chain documentation spanning petrochemical and biotech manufacturing hubs. Cargill Inc. represents the agricultural processor archetype, anchoring North American output through captive soybean oil infrastructure. Dow Inc. occupies a formulation-flexibility position, blending petroleum and renewable polyethers to meet intermediate sustainability thresholds without full bio-content certification investment.
| Leading Market Players |
|---|
| Stepan Company |
| Dow Inc. |
| BASF SE |
| Emery Oleochemicals |
| Arkema S.A. |
| Covestro AG |
| Mitsui Chemicals, Inc |
| Evonik Industries AG |
| Cargill Inc. |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal carbon intensity benchmarks gate qualified supply access and premium-tier pricing power for polyurethane foam manufacturers seeking verified bio-content certifications. Producers without crushing infrastructure face margin compression as agricultural commodity volatility decouples feedstock costs from petroleum benchmarks.
Pricing Analysis
Carbon accounting documentation bundled with mass-balance certificates commands premium positioning, while unbundled commodity polyols compete on spot-market terms. Three-tier pricing structure across certified sustainable, intermediate blend, and conventional petroleum tiers reflects bio-content percentage and traceability depth. Pricing pressure stems from castor and soybean oil price spikes linked to biofuel demand competition. Mattress OEMs with ESG disclosure mandates show lowest price sensitivity; regional foam converters exhibit highest.
Supply Chain Analysis
Specialized catalysis and formulation chemist shortages in Ludwigshafen, Leverkusen, and Shandong manufacturing clusters constrain capacity scaling. Supply concentrates in Germany, China, and India, with raw material flows drawing from Iowa soybean crushing facilities and Gujarat castor seed processing belts. Single-source vulnerability runs through EU F-Gas Regulation-compliant blowing agent suppliers. Distribution runs through direct partnerships with sleep product OEMs displacing traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Castor seed crushing capacity shortages prop pricing premiums for verified bio-content polyols, creating supply-constrained conditions favoring incumbent producers with captive agricultural infrastructure.
For Market Incumbents: Acquire oilseed crushing assets in Iowa, Illinois, or Gujarat to secure feedstock supply chains decoupled from biodiesel channel competition. Expand downstream polyol synthesis capacity in Shandong and Jiangsu provinces to capture China's subsidized utility rates under dual carbon targets. Defend against second-generation lignocellulosic polyol substitutes through accelerated R&D in catalytic ring-opening chemistry. For New Entrants and Emerging Players: Recycled PET-derived aromatic polyol technology offers a technology-first wedge into rigid foam insulation specifications demanding superior compressive strength and flame retardance. Target construction retrofit mandates in Germany, the Netherlands, and France where EU F-Gas Regulation compliance deadlines drive fastest specification evolution. Pursue direct-to-mattress-brand distribution partnerships bypassing entrenched chemical distributor relationships. For Investors and Strategic Acquirers: India's PLI scheme disbursement acceleration is the leading indicator that domestic castor-based polyol production will emerge as a low-cost export hub. Long-term viability centers on producers with integrated seed-crushing-to-polyol synthesis capabilities spanning 5-10 year investment horizons. Acquisition target archetype: regional foam converters with backward integration potential and verified supply chain documentation. Watch for MEE carbon intensity audit enforcement patterns as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Captive supply of soybean and castor oil feedstocks insulates margins from agricultural commodity volatility. |
| Green Manufacturing Transition | EU Green Deal compliance enables premium pricing access for certified low-carbon polyurethane systems. |
| Long-term Supply Agreement | Mattress OEM partnerships displace distributors and lock in volume commitments with scope 3 data sharing. |
| Joint Venture | Automotive Tier 1 co-development accelerates second-generation lignocellulosic polyol qualification cycles. |
| Capacity Expansion | Shandong and Jiangsu manufacturing clusters capture China's preferential permitting under dual carbon targets. |
Study Parameters
Multi-period observation of provincial carbon intensity audits, bio-content certification trajectories, and crushing capacity buildouts anchored the trend analysis, supplemented by interviews with polyurethane plant managers, procurement leads at mattress OEMs, automotive Tier 1 seating suppliers, distribution channel partners, and technical R&D directors at integrated chemical complexes. Secondary validation drew from EU ECHA REACH registration databases, US EPA renewable fuel standard filings, China MEE provincial audit disclosures, India PLI scheme beneficiary lists, and customs trade flow data. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators.
Input-output matrices mapped feedstock crushing volumes through downstream polyol synthesis capacity to end-use demand across flexible foam, rigid insulation, and coating applications over the projection horizon. Segmentation dimensions included product type, formulation chemistry, end-use industry, and regional production hub. CAGRs derived from regression analysis against carbon pricing trajectories and regulatory compliance deadlines. Industry-specific forecast inputs incorporated EU F-Gas Regulation phasedown schedules and China's dual carbon target enforcement intensity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under agricultural commodity price spikes or REACH registration timeline extensions for novel bio-based intermediates. Forecasts reflect documented assumptions regarding provincial policy enforcement and crushing infrastructure commissioning schedules. Material deviation in MEE audit stringency or PLI scheme disbursement velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Lanolin Market
Specialty Chemicals
Rosin Press Market
Specialty Chemicals
Demethylase Inhibitor Market
Specialty Chemicals
Global Non-Halogenated Flame Retardants Market
Specialty Chemicals
Organometallics Market
Specialty Chemicals
4-Propyl-1,3,2-Dioxathiolane 2,2-Dioxid Market
Specialty Chemicals
Ascorbic Acid Market
Specialty Chemicals
Phosphonate Market
Specialty Chemicals
Phosphatidylcholine Market
Specialty Chemicals
Global Specialty Fuel Additives Market
Specialty Chemicals
Perfluoropolyether (PFPE) Market
Specialty Chemicals
Global Benzoyl Peroxide Market
Specialty Chemicals
Fatty Acid Methyl Ester Market
Specialty Chemicals
Iron Phosphate Market
Specialty Chemicals
GLDA Market
Specialty Chemicals
Plastic Stabilizer Market