
 Organometallics Market | 2026-2036
Organometallics Market Size, Share, and Industry Trends Forecast 2026-2036
Organometallics Market Intelligence
Buyer consolidation among pharmaceutical contract manufacturers is recalibrating procurement volumes and specification rigor across the organometallics supply base. Albemarle Corporation leverages its bromine and lithium derivative networks to sustain captive feedstock access for organometallic precursors. BASF SE anchors its position through integrated catalyst production spanning homogeneous and heterogeneous systems. Umicore competes via closed-loop metal recovery capabilities that reduce virgin material dependence for specialty organometallic compounds.
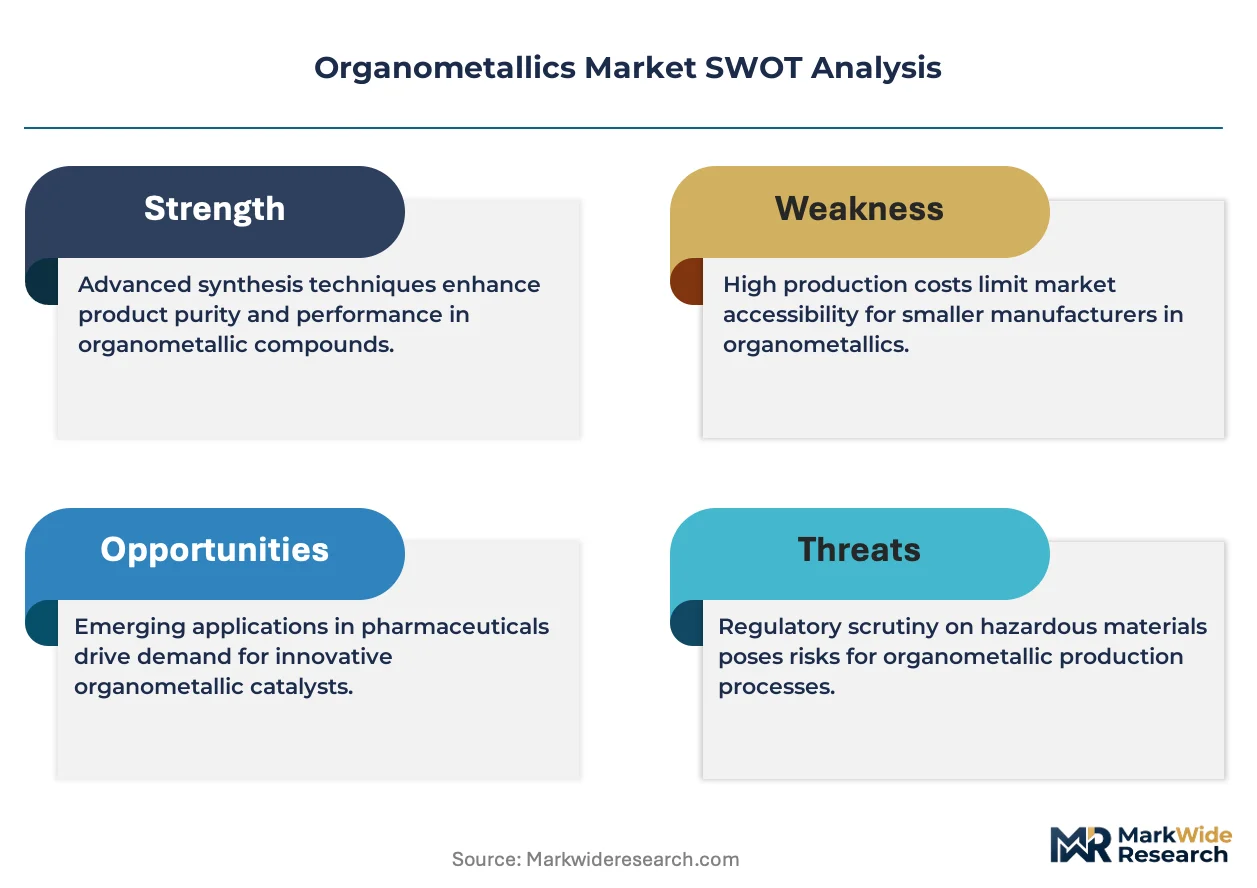
Organometallics are compounds containing direct carbon-metal bonds, typically synthesized through transmetallation or oxidative addition routes, and serve as essential intermediates in stereoselective synthesis and polymerization catalysis. The organometallic catalysts category leads value contribution due to iridium, palladium, and rhodium complexes commanding premium pricing in fine chemical applications. The pharmaceuticals application segment exhibits the fastest structural expansion as metal-catalyzed cross-coupling reactions displace traditional synthetic pathways in drug manufacturing. The alkyl product type maintains mature volume positions in agricultural chemical production, though margin compression from commodity titanium and aluminum derivatives limits profitability.
The EPA regulates metal waste discharge under the Resource Conservation and Recovery Act, while REACH mandates registration and hazard communication for organometallic substances imported or manufactured in Europe. China's MEE enforces emission standards for volatile organometallic compounds in chemical manufacturing zones, shaping plant location decisions and technology upgrade timelines. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate compliance cost fragmentation and supply chain reconfiguration requirements.
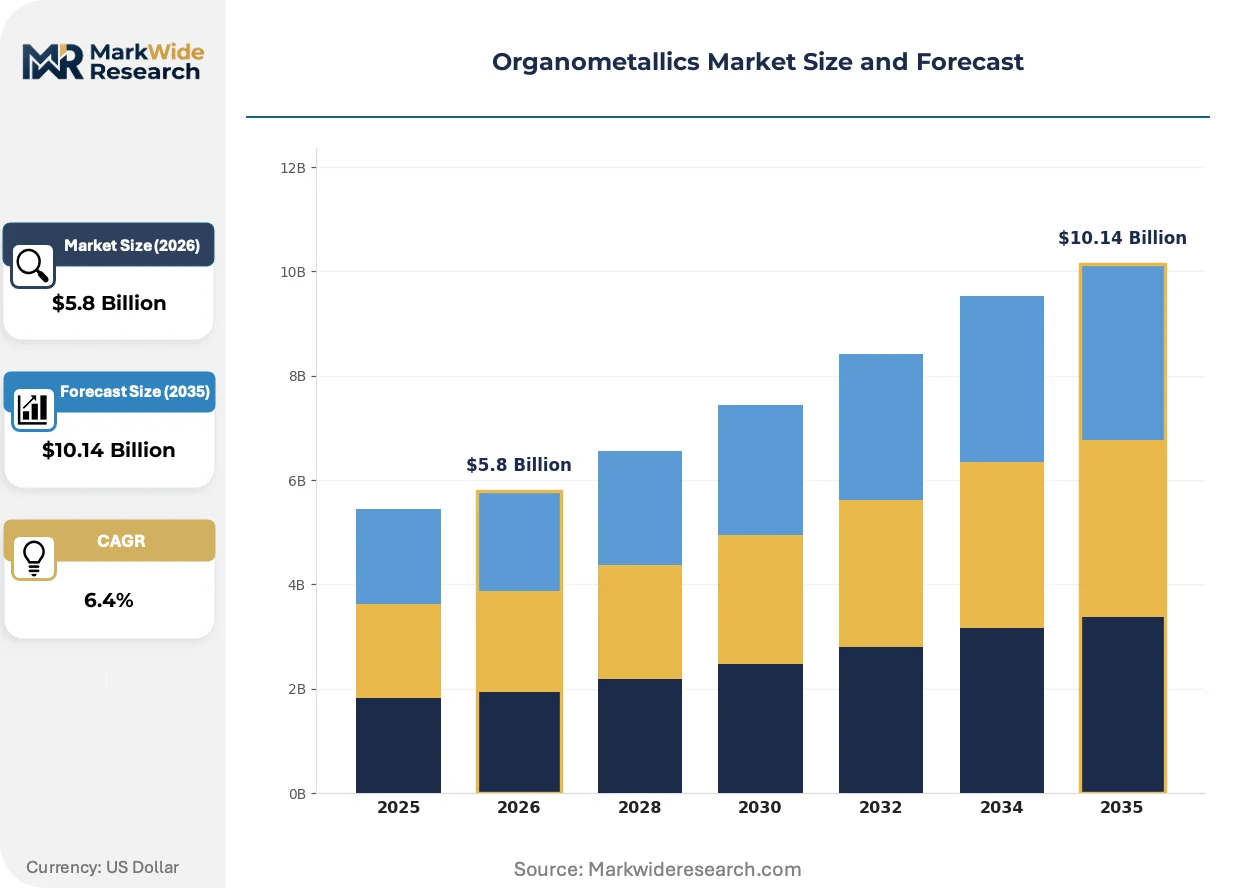
Market Dynamics
Pharmaceutical contract manufacturers are consolidating procurement specifications, forcing organometallic suppliers to recalibrate batch sizes and purity documentation. REACH registration deadlines and EPA metal discharge limits are compressing supplier qualification timelines while elevating analytical chemistry requirements.
Growth Catalysts
- Metal-catalyzed cross-coupling:Pharmaceutical synthesis protocols now specify Suzuki and Negishi couplings for complex stereocenters, displacing traditional stoichiometric routes in active ingredient manufacturing.
- China's MEE emission standards:Domestic chemical producers are retrofitting plants with closed-loop recovery systems, expanding captive catalyst output for polymerization applications.
- Iridium complex demand:OLED material producers in East Asia are scaling phosphorescent emitter procurement, pulling high-purity organometallic volumes into electronics supply chains.
Market Restraints
- Precious metal volatility:Palladium and rhodium price swings compress margin predictability for homogeneous catalyst formulators serving fine chemical applications.
- China supply concentration:Over half of global alkylaluminum and titanium derivative capacity sits in Shandong and Jiangsu provinces, creating geographic risk for agricultural chemical manufacturers.
- Substitution by biocatalysis:Engineered enzymes for carbon-carbon bond formation are displacing organometallic reagents in early-stage pharmaceutical route scouting.
Strategic Opportunities
- India fine chemical expansion:CDSCO manufacturing incentives and PLI scheme benefits are drawing organometallic catalyst investments toward Ahmedabad and Hyderabad clusters.
- Battery electrolyte additives:Organolithium reagents for solid-state electrolyte synthesis represent emerging pull from electric vehicle material suppliers.
- Closed-loop metal recovery:EU Critical Raw Materials Act mandates are creating service-contract opportunities for spent catalyst refining and virgin metal displacement.
Industry Challenges
- Organometallic chemist scarcity:Academic pipeline contraction in synthetic inorganic chemistry limits talent availability for process development roles at catalyst manufacturers.
- Multi-jurisdiction registration:Divergent hazard classification between REACH, EPA TSCA, and China's MEE notification requirements extends product launch timelines for new metal complexes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organometallics Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkyl, Aryl, Complexes, Organometallic Catalysts Application: Agriculture, Pharmaceuticals, Electronics, Catalysis End User: Chemical Manufacturers, Research Institutions, Automotive, Energy Distribution Channel: Direct Sales, Online Retail, Third-Party Distributors, Others |
| Companies Covered | Albemarle Corporation, LANXESS, BASF SE, Bayer AG, Solvay, Merck KGaA, Sumitomo Chemical, Umicore, Nouryon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organometallics Market Strategic Shifts & Innovations
Continuous flow synthesis protocols are reshaping how organometallic intermediates are manufactured, displacing batch reactor dominance in hazardous chemistry. Process intensification and real-time analytical integration are compressing development cycles while elevating safety benchmarks.
Photoredox catalysis is expanding into pharmaceutical route design, enabling single-electron transfer mechanisms previously inaccessible through thermal activation. Merck and Pfizer process chemistry groups have adopted iridium photocatalyst libraries for late-stage functionalization, compressing synthetic step counts in complex molecule assembly. This modality is expanding into contract research organization screening services, creating pull for standardized photocatalyst kits.
REACH authorization requirements for cobalt and nickel compounds are tightening downstream documentation obligations. ECHA substance evaluation deadlines are forcing formulators to substitute restricted metal centers with iron or manganese alternatives in polymerization catalysts. European catalyst producers are accelerating bio-based ligand development to preempt regulatory exclusion of conventional organometallic systems.
Specification-driven procurement now dominates pharmaceutical buyer behavior, with quality agreements replacing transactional spot purchasing. Contract manufacturers are consolidating supplier panels to three qualified sources per metal center, compressing vendor counts while elevating analytical capability requirements. This consolidation is most visible in Swiss and German pharmaceutical clusters, where CDMO qualification timelines now stretch eighteen to twenty-four months for new organometallic inputs.
Organometallics Market Segmentation
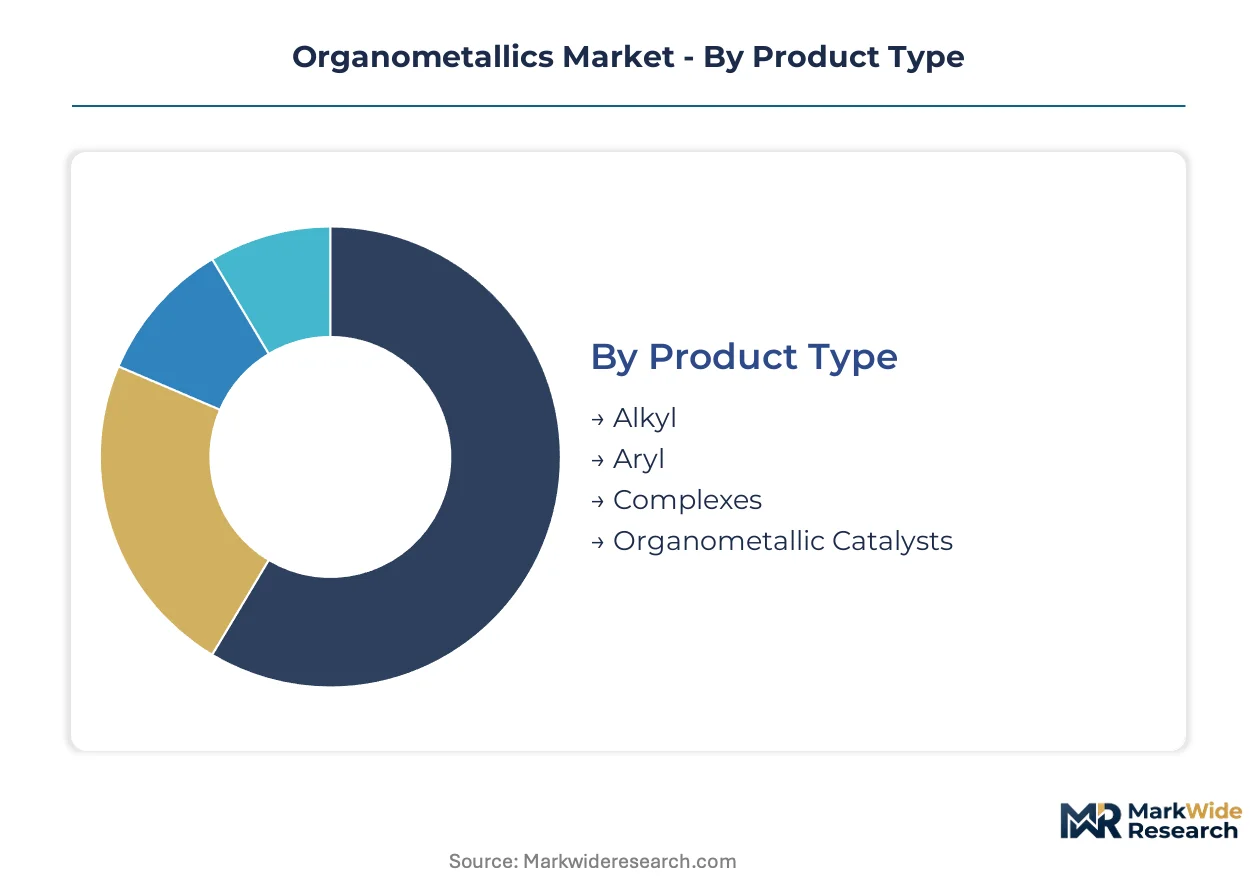
Organometallics procurement varies sharply by buyer sophistication and volume scale. Specification rigor, metal center selection, and regulatory documentation requirements differ fundamentally across product categories and end-use applications.
Product Type:
Purchasing decisions pivot on metal center scarcity and synthetic complexity rather than commodity chemistry logic.
- Organometallic Catalysts:Iridium, palladium, and rhodium complexes command premium positioning in stereoselective synthesis protocols. Pharmaceutical contract manufacturers in Switzerland and Germany now require eighteen-to-twenty-four-month qualification timelines for new catalyst sources, compressing vendor panels to three qualified suppliers per metal center.
- Alkyl:Titanium and aluminum derivatives dominate agricultural chemical production with mature volume positions. Margin compression from commodity pricing limits profitability despite steady offtake from crop protection formulators.
- Aryl:Phenyl and benzyl metal compounds serve specialized electronics and fine chemical applications with moderate batch scale requirements.
- Complexes:Multi-ligand systems enable tailored reactivity profiles for custom synthesis houses and contract research organizations.
Volume sits with Alkyl; growth tilts toward Organometallic Catalysts.
Application:
End-use specifications determine purity thresholds, analytical documentation, and metal recovery obligations.
- Pharmaceuticals:Metal-catalyzed cross-coupling reactions now displace traditional stoichiometric routes in active ingredient manufacturing. Suzuki and Negishi protocols specify organometallic intermediates for complex stereocenter construction, with REACH and EPA registration requirements elevating supplier qualification barriers.
- Catalysis:Polymerization and fine chemical production consume homogeneous and heterogeneous organometallic systems. China's MEE emission standards are driving domestic chemical producers toward closed-loop recovery retrofits, expanding captive catalyst output.
- Electronics:OLED material producers in East Asia scale phosphorescent emitter procurement, pulling high-purity iridium complexes into display supply chains.
- Agriculture:Alkylaluminum and titanium derivatives feed herbicide and insecticide synthesis with established volume contracts.
Revenue concentration favors Pharmaceuticals; Electronics shows the steepest expansion trajectory.
End User:
Customer scale and technical capability shape procurement modality and service expectations.
- Chemical Manufacturers:Integrated producers with captive organometallic synthesis capability dominate bulk alkyl and aryl consumption. Albemarle Corporation leverages bromine and lithium derivative networks for captive feedstock access.
- Research Institutions:Academic and government laboratories drive exploratory demand for novel metal complexes with small-batch, high-specification requirements.
- Automotive:Battery electrolyte additive producers represent emerging pull for organolithium reagents in solid-state electrolyte synthesis.
- Energy:Fuel cell and hydrogen storage research programs consume specialized metal hydride complexes at pilot scale.
Tonnage concentrates with Chemical Manufacturers; Automotive is gaining share fastest.
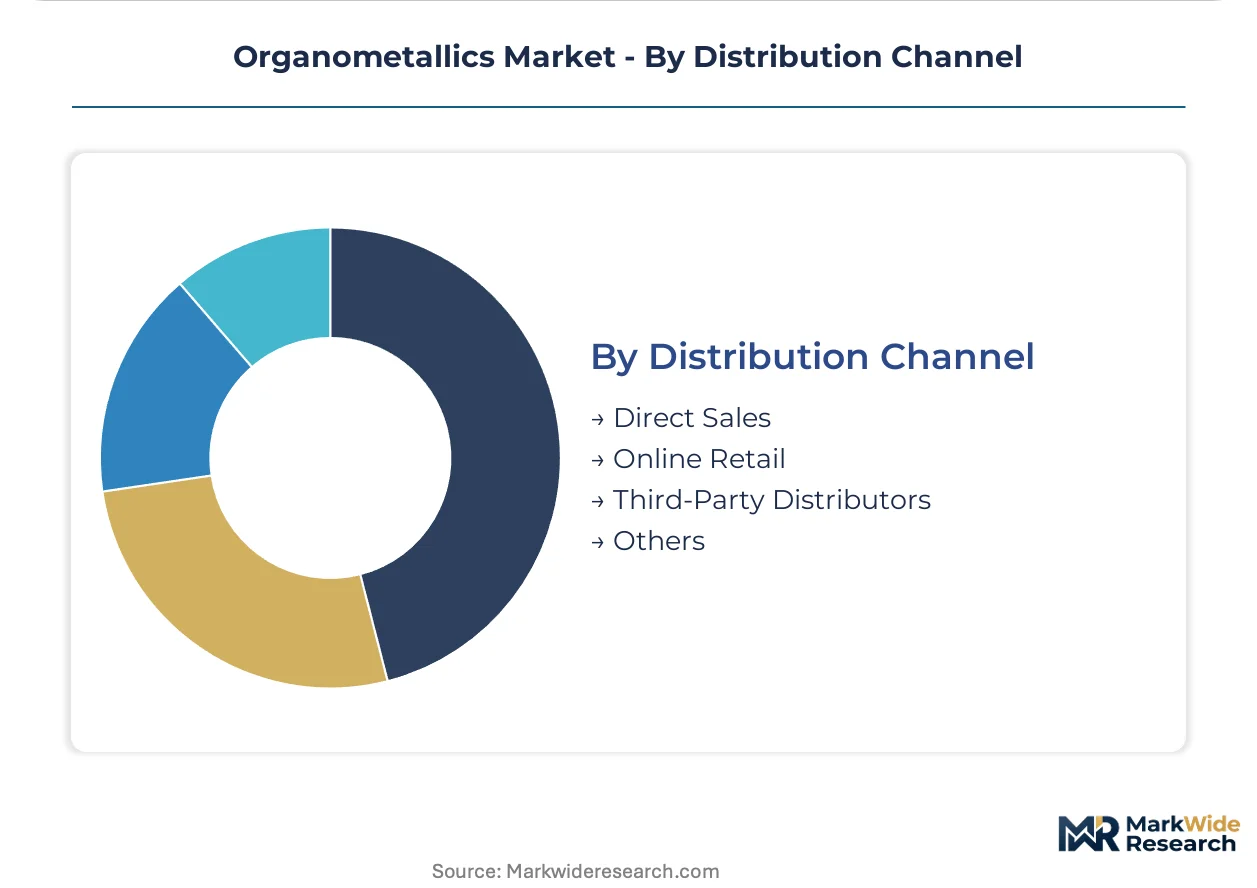
Distribution Channel:
Channel selection reflects shipment hazard classification and customer technical support needs.
- Direct Sales:Large-volume pharmaceutical and chemical manufacturers negotiate frame contracts with producers for scheduled deliveries of pyrophoric and air-sensitive materials. BASF SE anchors position through integrated catalyst production with direct technical service.
- Third-Party Distributors:Regional chemical distributors handle smaller lot sizes for mid-tier manufacturers with limited cold chain and inert atmosphere logistics capability.
- Online Retail:Catalog suppliers serve research institutions and pilot-scale operations with standard-grade alkyl and aryl reagents.
- Others:Consortium purchasing arrangements and government procurement frameworks cover specialized defense and aerospace applications.
Direct Sales captures the largest transaction value; Third-Party Distributors are expanding most quickly into India and Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium brine deposits in Chile's Atacama Desert and bromine extraction networks in the US Gulf Coast anchor feedstock security for organometallic precursor manufacturing. Regional demand patterns diverge sharply between pharmaceutical-driven consumption in Western Europe and polymerization catalyst expansion across East Asian chemical corridors.
United States
Pharmaceutical contract manufacturers in Massachusetts and New Jersey drive iridium and palladium complex consumption for metal-catalyzed cross-coupling protocols. EPA metal discharge limits under the Resource Conservation and Recovery Act tighten wastewater treatment obligations for New Jersey-based catalyst formulators. The Gulf Coast petrochemical corridor sustains captive alkylaluminum output for agricultural chemical synthesis.
Germany
Specialty chemical producers in North Rhine-Westphalia scale homogeneous catalyst output for European pharmaceutical CDMOs. REACH authorization requirements for cobalt and nickel compounds accelerate substitution research at Ludwigshafen and Leverkusen industrial clusters. ECHA substance evaluation deadlines compress reformulation timelines for polymerization catalyst suppliers serving BASF SE integrated production networks.
China
Domestic chemical producers in Shandong and Jiangsu provinces retrofit plants with closed-loop recovery systems under MEE emission standards for volatile organometallic compounds. The Yangtze River Delta concentrates over half of global alkylaluminum and titanium derivative capacity for agricultural chemical export markets. State-backed catalyst research programs in Shanghai target iridium complex localization for OLED material supply chains.
India
CDSCO manufacturing incentives and PLI scheme benefits draw organometallic catalyst investments toward Ahmedabad and Hyderabad fine chemical clusters. Domestic pharmaceutical API producers expand Suzuki coupling capacity for export-oriented generic active ingredient synthesis. Gujarat's specialty chemical corridor attracts toll manufacturing partnerships for European agrochemical formulators seeking non-China alkyl sourcing.
Japan
OLED material producers in Kyushu and Kansai regions scale phosphorescent emitter procurement, pulling high-purity iridium complexes into display supply chains. METI industrial technology roadmaps prioritize organometallic catalyst efficiency improvements for fine chemical export competitiveness. The Chubu region's chemical engineering base sustains process development partnerships with pharmaceutical multinationals.
Organometallics Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue closed-loop metal recovery and bio-based ligand development as differentiation vectors. The vendor base stratifies across integrated chemical conglomerates with captive feedstock access, specialized catalyst formulators serving pharmaceutical qualification protocols, and regional alkyl producers competing on agricultural chemical volume contracts. Three archetypes dominate: upstream-integrated miners with bromine-lithium derivative networks, homogeneous catalyst specialists with pharmaceutical CDMO relationships, and metal recovery service providers addressing EU Critical Raw Materials Act mandates. Competitive intensity centers on supplier panel consolidation by contract manufacturers and accelerated REACH registration timelines compressing new entrant qualification windows.
Among diversified chemical conglomerates, Albemarle Corporation, BASF SE, and Umicore occupy positions reflecting distinct strategic anchoring. Albemarle represents upstream-integrated supply security through bromine and lithium derivative networks. BASF SE exemplifies catalyst production integration spanning homogeneous and heterogeneous systems with direct technical service capabilities. Umicore sits within the metal recovery tier, addressing circular economy mandates through closed-loop refining capabilities that reduce virgin material dependence for specialty organometallic compounds.
| Leading Market Players |
|---|
| Albemarle Corporation |
| LANXESS |
| BASF SE |
| Bayer AG |
| Solvay |
| Merck KGaA |
| Sumitomo Chemical |
| Umicore |
| Nouryon |
| Others |
Cost & Logistics Intelligence
Pharmaceutical contract manufacturers in Switzerland and Germany now demand eighteen-to-twenty-four-month qualification timelines for new organometallic catalyst sources, forcing suppliers to absorb extended working capital cycles and elevate analytical chemistry capabilities. This specification rigor compresses vendor panels to three qualified suppliers per metal center, concentrating pricing power among incumbents with established pharmaceutical CDMO relationships.
Pricing Analysis
Service bundling separates qualified suppliers from commodity traders, with REACH documentation, stability testing, and metal recovery guarantees now standard in pharmaceutical-grade contracts. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and agricultural-grade levels reflects certification burden and analytical intensity. Cost compression in titanium and aluminum alkyl derivatives is intensifying because Chinese producers are expanding Shandong and Jiangsu capacity for crop protection export markets. Agricultural chemical manufacturers exhibit highest price sensitivity, while OLED material producers in East Asia show lowest sensitivity for high-purity iridium complexes.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme and China's MEE emission standards are reshaping sourcing patterns, drawing catalyst investments toward Ahmedabad and Hyderabad while forcing Jiangsu retrofitting. Supply concentrates in China, Germany, and the United States for homogeneous catalysts, with Chile and Australia anchoring lithium and bromine feedstock security. Production draws from palladium and rhodium concentrates, lithium brine, and bromine extraction networks. Single-source vulnerability runs through South African platinum group metal refining. Distribution runs through direct frame contracts for pharmaceutical manufacturers and regional distributors for mid-tier agricultural chemical formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supplier panel consolidation by pharmaceutical contract manufacturers is eliminating sub-scale catalyst formulators, creating acquisition opportunities for integrated chemical conglomerates with captive feedstock access and REACH registration capabilities.
For Market Incumbents: Deploy closed-loop metal recovery infrastructure to preempt EU Critical Raw Materials Act service-contract mandates and reduce virgin palladium dependence. BASF SE and Umicore demonstrate how integrated refining capabilities defend margin position against precious metal volatility. Backward integration into lithium brine or bromine extraction networks secures feedstock autonomy for organometallic precursor manufacturing. For New Entrants and Emerging Players: Photoredox catalyst standardization for contract research organization screening services offers a technology-first wedge into pharmaceutical supply chains with lower qualification barriers than custom homogeneous catalysts. India's CDSCO manufacturing incentives and PLI scheme benefits present the most penetrable geography for toll manufacturing partnerships. A catalog-based go-to-market model with standardized iridium photocatalyst kits bypasses eighteen-month pharmaceutical qualification timelines. For Investors and Strategic Acquirers: The window for entry favors metal recovery service providers with hydrometallurgical refining capabilities and existing pharmaceutical customer relationships. Long-term viability hinges on positioning for circular economy mandates and virgin metal displacement across the analysis window. Watch ECHA substance evaluation deadlines for cobalt and nickel compounds as the inflection signal for substitution-driven acquisition activity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Feedstock | Albemarle's Atacama brine access secures captive organolithium precursor supply for battery electrolyte additives. |
| Closed-Loop Metal Recovery Infrastructure | Umicore's hydrometallurgical refining addresses EU Critical Raw Materials Act mandates while reducing virgin palladium dependence. |
| Photoredox Catalyst Standardization | Standardized iridium photocatalyst kits for CRO screening services compress synthetic step counts in pharmaceutical route design. |
| India Toll Manufacturing Partnerships | Ahmedabad and Hyderabad clusters attract European agrochemical formulators seeking non-China alkyl sourcing under CDSCO incentives. |
| REACH Registration Acceleration | Early cobalt and nickel compound substitution research at Ludwigshafen preempts ECHA authorization requirements for polymerization catalysts. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across catalyst formulators, pharmaceutical CDMO procurement leads, and metal recovery service operators. ECHA substance evaluation databases, EPA RCRA discharge records, and China MEE emission compliance filings provided regulatory trajectory validation. Cefic and ACC chemical production statistics, SEC 10-K supply chain disclosures, and customs import-export data for lithium and platinum group metals furnished volume calibration. Bottom-up catalyst consumption modeling and top-down fine chemical production estimates were triangulated for cross-validation.
Segment-level granularity modeled organometallic catalysts, alkyl, aryl, and complexes by product type; pharmaceuticals, catalysis, electronics, and agriculture by application; and chemical manufacturers, research institutions, automotive, and energy by end user across the analysis window. CAGRs were derived from regression analysis against pharmaceutical API production indices, OLED display shipment forecasts, and agricultural chemical formulation trends. Metal price volatility scenarios and REACH registration timeline assumptions informed sensitivity boundaries.
Several conditions sit outside the modeled scope, including unannounced regulatory reclassifications, abrupt platinum group metal supply disruptions, and biocatalysis substitution breakthroughs in carbon-carbon bond formation. Forecasts reflect documented assumptions about qualification timeline stability and emission standard enforcement continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Salt Hydrate Market
Specialty Chemicals
Fabric Antibacterial Spray Market
Specialty Chemicals
Bio-Ketones Market
Specialty Chemicals
Europe Malic Acid Market
Specialty Chemicals
Fluorotelomers Market
Specialty Chemicals
Dimethylolpropionic Acid (DMPA) Market
Specialty Chemicals
Bio-Based Phenol Market
Specialty Chemicals
Methyltrimethoxysilane Market
Specialty Chemicals
Erucic Acid Market
Specialty Chemicals
Immunochemistry Products Market
Specialty Chemicals
Ethyl Ascorbic Acid Market
Specialty Chemicals
Non-Commercial Acrylic Paints Market
Specialty Chemicals
Coconut Derived Emollients Market
Specialty Chemicals
Superdisintegrants Market
Specialty Chemicals
Silver Iodide Market
Specialty Chemicals
Myrcene Market