
 Augmented Reality Software Development Kit Market | 2026-2036
Augmented Reality Software Development Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Augmented Reality Software Development Kit Market Insights
GDPR's extraterritorial data-processing rules are decoupling European AR SDK procurement from legacy cloud architectures. Apple leverages its vertically integrated hardware-software stack to sustain premium developer retention. Google anchors its position through open-source ARC distribution and cross-platform compatibility. Qualcomm differentiates by dominating mobile chipset-optimized spatial computing libraries.
An augmented reality software development kit comprises a programmable framework enabling real-time overlay of digital content onto physical environments through camera feeds, inertial measurement units, and depth sensors, typically exposing APIs for SLAM tracking, plane detection, and occlusion rendering at sub-50ms latency. Mobile SDK occupies the largest deployment base due to smartphone ubiquity, while Cloud SDK registers the fastest expansion as latency-sensitive rendering migrates to edge infrastructure. Markerless technology leads R&D allocation because environmental understanding without fiducial markers unlocks industrial field-service applications.
FCC spectrum allocations for mmWave and mid-band 5G directly shape AR SDK throughput capabilities in the United States, while EU AI Act conformity requirements are forcing algorithmic auditability into European platform releases. China's MIIT issues mandatory GB standards for data localization in spatial computing services. Stakeholders must weigh regulatory fragmentation against the cost of maintaining jurisdiction-specific compliance layers.
Market Dynamics
Edge computing infrastructure is compressing latency thresholds for real-time spatial rendering, forcing SDK vendors to rearchitect their pipeline distribution between device-local and cloud-offloaded processing. This technical inflection is redrawing competitive moats around inference optimization and 5G network integration.
Growth Catalysts
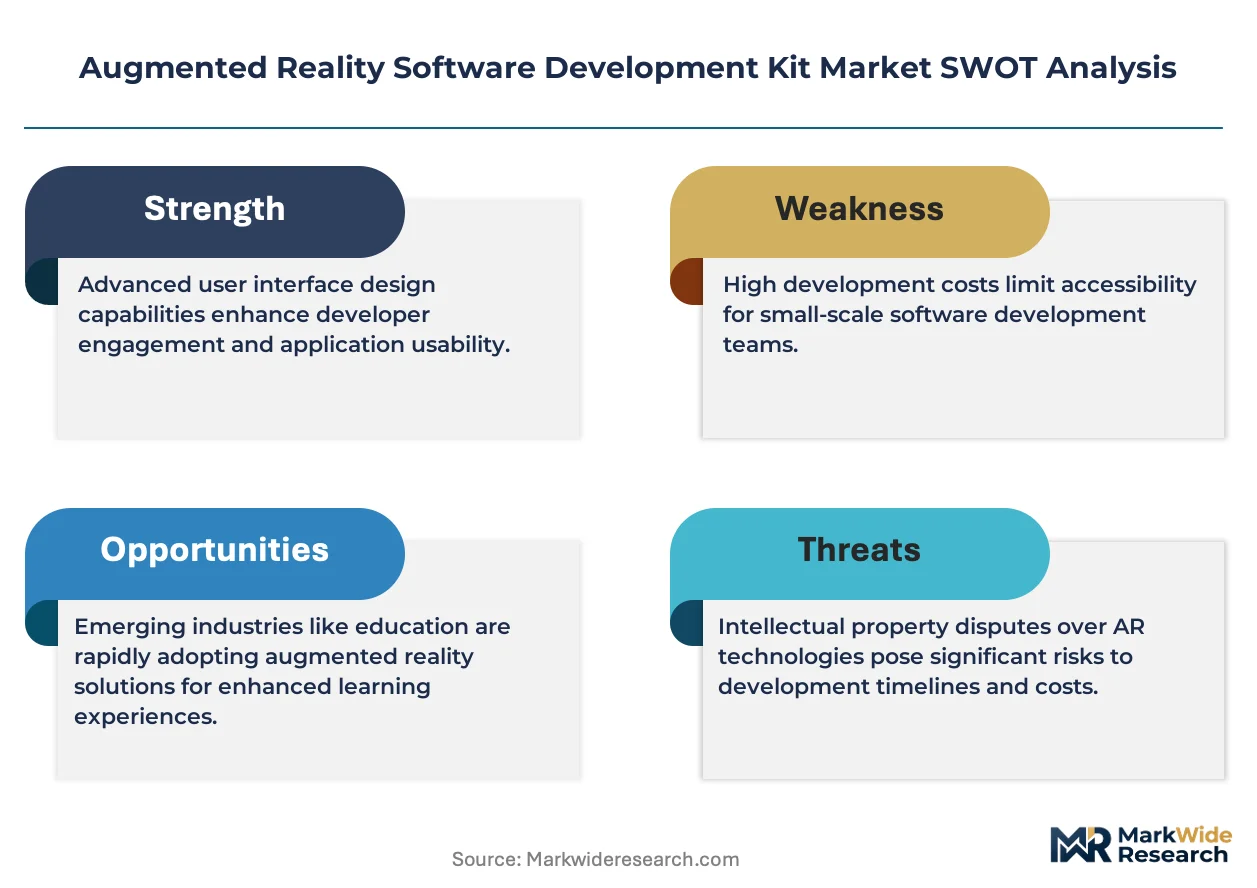
- EU AI Act algorithmic auditability mandates:European healthcare providers are accelerating procurement of conformant AR SDK platforms for surgical training applications, creating certified-vendor preference cascades.
- mmWave spectrum deployment:FCC allocations in dense urban corridors are unlocking throughput for uncompressed point-cloud streaming in industrial field-service scenarios.
- Markerless SLAM maturation:Environmental understanding without fiducial dependencies is electrifying warehouse logistics and remote equipment maintenance workflows.
Market Restraints
- GPU silicon concentration:Foundry capacity constraints in Taiwan and South Korea are throttling availability of neural-optimized chipsets for spatial computing workloads.
- GDPR extraterritorial data routing:European procurement is decoupling from legacy cloud architectures, forcing redundant compliance-layer investments.
- Depth sensor cost volatility:Time-of-flight module pricing fluctuation is compressing margins for mid-tier mobile SDK bundles.
Strategic Opportunities
- Defense IT budget expansion:United States military maintenance and training contracts are creating high-security, air-gapped deployment specifications.
- Convergence of AR SDK with digital twin platforms:Industrial manufacturers are demanding unified spatial-data pipelines for asset lifecycle management.
- Underpenetrated surgical simulation:Japanese academic medical centers are piloting haptic-integrated AR training modules with regulatory pre-clearance pathways.
Industry Challenges
- SLAM engineer scarcity:Specialized computer-vision talent for real-time tracking algorithms commands premium compensation, constraining R&D velocity.
- Multi-jurisdiction certification timelines:FDA, PMDA, and CE marking concurrency requirements are extending product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Augmented Reality Software Development Kit Market |
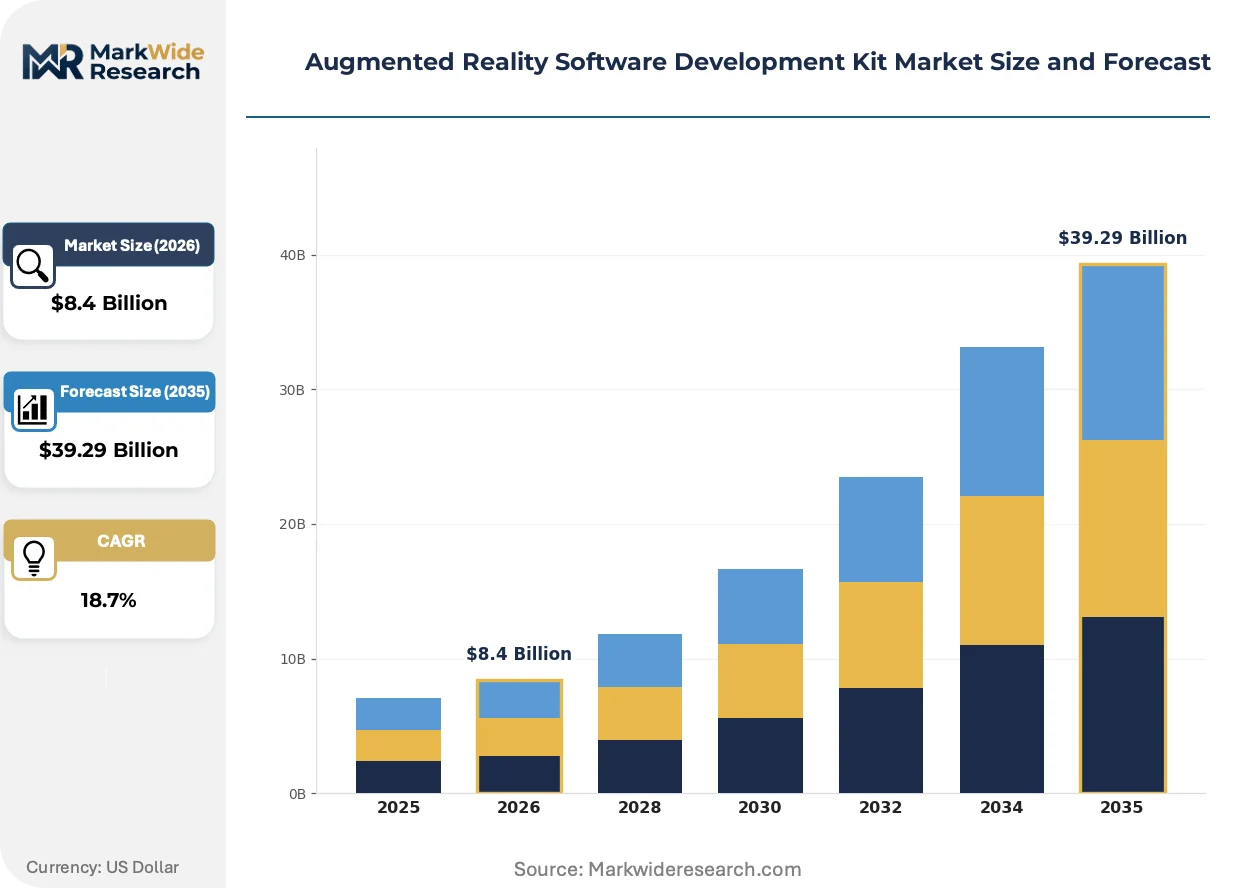
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile SDK, Web SDK, Desktop SDK, Cloud SDK End User: Gaming, Education, Healthcare, Retail Technology: Marker-Based, Markerless, Projection-Based, Superimposition Deployment: On-Premise, Cloud-Based, Hybrid, Others |
| Companies Covered | Apple, Google, PTC, Unity Technologies, Niantic, MAXST, Microsoft, ARToolKit, Qualcomm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Augmented Reality Software Development Kit Market Trends and Innovations
Neural rendering pipelines are compressing the boundary between precomputed assets and real-time synthesis, enabling photorealistic occlusion without dedicated depth hardware. This technical trajectory is redefining minimum viable device specifications across consumer and enterprise tiers.
Cloud-native AR SDK architectures are electrifying the separation of tracking compute from rendering output, allowing low-end smartphones to access high-fidelity spatial experiences through edge-offloaded inference. Industrial field-service teams in Germany and the United States are piloting these configurations for remote expert guidance. The structural consequence is a bifurcation between premium on-device stacks and commodity thin-client implementations.
The EU AI Act's conformity assessment procedures for algorithmic transparency are mandating explainability documentation for spatial computing tools deployed in healthcare and public infrastructure. European platform releases now require audit trails for plane detection and object recognition decision paths. Medical device manufacturers are responding by embedding logging subsystems that trace inference outputs to training dataset provenance.
Enterprise procurement of AR SDK licenses is consolidating around multi-year platform commitments with embedded professional-services hours, displacing per-seat transactional models. Automotive and aerospace OEMs in Japan and the United States are negotiating master service agreements that bundle SDK access with custom pipeline engineering. This shift concentrates vendor selection authority within central IT procurement functions rather than distributed developer teams.
Augmented Reality Software Development Kit Market Segmentation
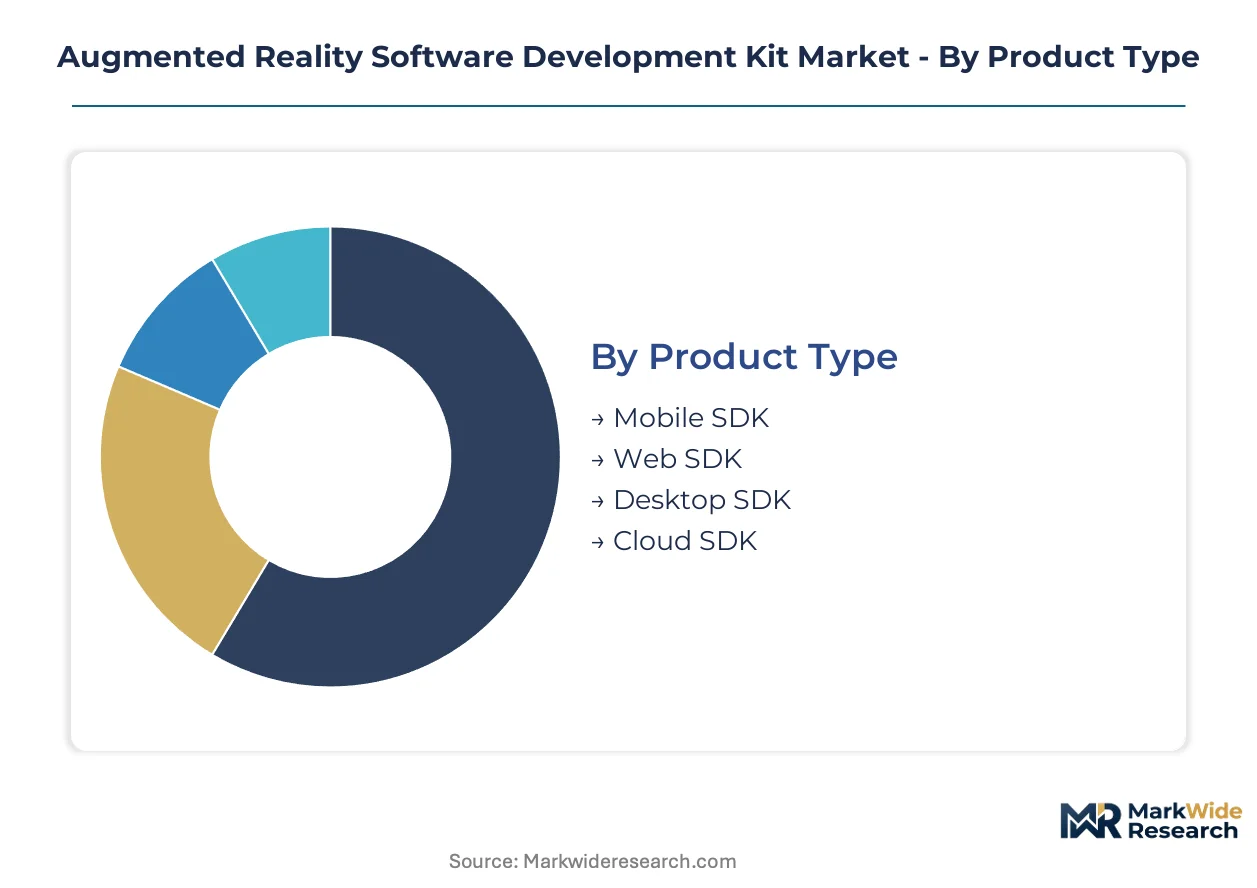
AR SDK segmentation reveals how procurement priorities diverge across compute environments, end-use applications, and tracking methodologies. Understanding these fault lines exposes where platform vendors must architect differentiated compliance and performance layers.
Product Type:
Buyers in this category separate by infrastructure ownership and latency tolerance, with smartphone OEMs prioritizing bundled integration while industrial operators demand elastic compute scaling.
- Mobile SDK:Optimized for ARM-based chipsets with tight camera-IMU fusion pipelines. Smartphone OEMs in the United States and South Korea bundle these into flagship device releases, driving volume through consumer app store distribution. GPU silicon constraints from Taiwan foundries are throttling neural-optimized variants.
- Cloud SDK:Offloads SLAM inference and occlusion rendering to edge nodes via 5G streaming. German automotive suppliers and Japanese logistics operators pilot these for warehouse guidance systems where device hardware costs must compress. FCC mmWave allocations in dense urban corridors unlock throughput for uncompressed point-cloud streaming.
- Web SDK:Browser-executable frameworks using WebXR standards with degraded tracking fidelity. Retailers deploy for rapid prototyping of virtual try-on experiences without native app installation friction.
- Desktop SDK:Workstation-grade libraries targeting tethered headsets with high-fidelity depth sensing. Architectural visualization studios in France leverage these for building information modeling integration.
Mobile SDK leads volumes today; Cloud SDK is gaining share fastest.
End User:
Application context dictates regulatory exposure and certification burden, with healthcare procurement requiring algorithmic audit trails that gaming publishers ignore.
- Healthcare:Surgical training and remote diagnostic platforms demand FDA, PMDA, and CE marking concurrency. EU AI Act conformity requirements force logging subsystems that trace plane detection outputs to training dataset provenance. European providers accelerate procurement of certified-vendor platforms.
- Gaming:Consumer entertainment prioritizes markerless environmental understanding for immersive occlusion without fiducial setup. Mobile game publishers in South Korea and the United States drive integration into multiplayer location-based experiences.
- Education:Institutional procurement cycles favor multi-year platform commitments with embedded professional services. Japanese academic medical centers pilot haptic-integrated modules with regulatory pre-clearance pathways.
- Retail:Virtual try-on and spatial commerce deployments emphasize rapid deployment over tracking precision. GDPR extraterritorial rules force redundant compliance-layer investments for European customer data processing.
Healthcare commands premium pricing tiers; Gaming delivers volume scale.
Technology:
Tracking methodology selection hinges on environmental control and setup tolerance, with uncontrolled industrial spaces demanding environmental independence.
- Markerless:SLAM-based environmental understanding without fiducial dependencies. Warehouse logistics operators in Germany and the United States deploy for remote equipment maintenance where marker placement proves impractical. R&D allocation concentrates here for field-service electrification.
- Marker-Based:Image-target recognition with sub-pixel registration accuracy. Museum installations and controlled training environments retain preference for deterministic tracking stability.
- Projection-Based:Spatial light modulation onto physical surfaces for shared experiences without head-mounted hardware. Retail showrooms pilot for collaborative product configuration.
- Superimposition:Object replacement rendering with precise geometric alignment. Automotive design studios employ for clay model digitization workflows.
Markerless dominates R&D spend; Marker-Based retains installed base.
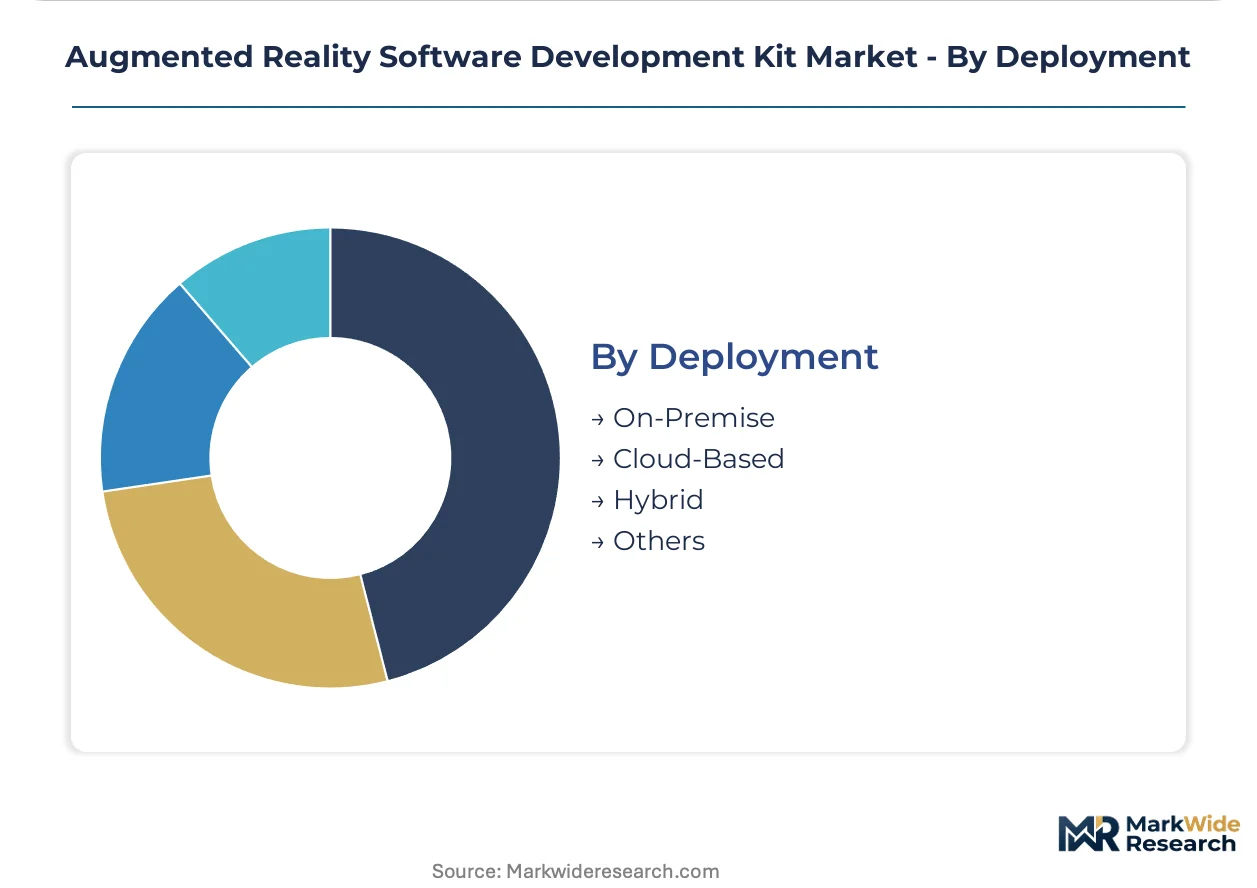
Deployment:
Infrastructure posture reflects data sovereignty requirements and air-gap security mandates, with defense contractors refusing external network dependencies.
- On-Premise:Fully air-gapped installations with local inference execution. United States military maintenance contracts specify these configurations for classified facility training. High-security deployments demand custom pipeline engineering.
- Cloud-Based:Elastic compute with centralized model updates and telemetry aggregation. GDPR extraterritorial rules decouple European procurement from legacy cloud architectures, forcing jurisdiction-specific compliance layers.
- Hybrid:Device-local tracking with cloud-offloaded rendering for quality-tier adaptation. Industrial field-service teams pilot these configurations for remote expert guidance across connectivity gradients.
- Others:Peer-to-peer mesh architectures and federated learning deployments for privacy-preserving collaboration.
Hybrid architectures expand most quickly; On-Premise captures defense premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SLAM engineers and computer-vision specialists concentrate in the United States, Germany, China, Japan, and South Korea, anchoring regional R&D capacity and platform development velocity.
United States
Defense IT budgets and enterprise procurement cycles drive platform adoption. FCC mmWave spectrum allocations unlock throughput for uncompressed point-cloud streaming in dense urban corridors. Seattle and San Francisco Bay Area clusters host major SDK vendors optimizing neural rendering pipelines for industrial field-service deployment.
Germany
Automotive suppliers and logistics operators pilot cloud-native configurations for warehouse guidance systems. EU AI Act conformity requirements force algorithmic auditability into platform releases. Munich and Stuttgart engineering centers concentrate development of markerless SLAM for remote equipment maintenance workflows.
China
MIIT mandatory GB standards for data localization reshape cloud architecture decisions for spatial computing services. Smartphone OEMs bundle mobile SDKs into flagship device releases at massive volume. Shenzhen and Beijing clusters dominate chipset-optimized library development despite GPU silicon constraints from Taiwan foundries.
Japan
PMDA regulatory pre-clearance pathways accelerate pilot programs for haptic-integrated surgical training modules. Academic medical centers demand multi-year platform commitments with embedded professional services. Tokyo and Osaka metropolitan areas concentrate enterprise procurement authority for industrial digital-twin integration.
South Korea
Mobile game publishers drive consumer-facing markerless environmental understanding into multiplayer location-based experiences. MFDS and national standards bodies shape certification timelines for healthcare-adjacent deployments. Seoul Capital Area clusters anchor neural-optimized spatial computing library development for ARM-based chipsets.
Augmented Reality Software Development Kit Market Competitive Landscape
The competitive structure tilts toward vertically integrated technology conglomerates with captive hardware-software stacks. Apple and Google anchor opposing poles of this architecture, with closed-system premium positioning confronting open-source cross-platform distribution. Three archetypes dominate: hardware-captive platform owners, pure-play spatial computing specialists, and chipset-optimized library vendors. Competitive moves concentrate on strategic partnerships with automotive and aerospace OEMs, plus M&A activity targeting SLAM engineering talent pools.
Within the hardware-captive tier, Apple exemplifies premium developer retention through vertical control over silicon, optics, and distribution. Google occupies the open-architecture position, anchoring cross-platform compatibility through ARC distribution. Qualcomm represents the chipset-optimized vector, dominating mobile spatial computing libraries through neural engine integration with its Snapdragon platforms.
| Leading Market Players |
|---|
| Apple |
| PTC |
| Unity Technologies |
| Niantic |
| MAXST |
| Microsoft |
| ARToolKit |
| Qualcomm |
| Others |
Pricing and Supply Chain Analysis
Premium-mid-economy pricing differentiation across SDK tiers manifests in bundled professional services for healthcare and defense contracts versus stripped-down API access for retail prototyping, with supply chain configurations mirroring this split through captive engineering teams for high-security deployments versus commodity cloud infrastructure for mass-market segments.
Pricing Analysis
Bundled service contracts dominate enterprise procurement while unbundled per-seat licensing persists in developer-tooling segments. Pricing stratifies across premium, standard, and economy tiers based on certification grade (FDA/CE/PMDA concurrency) and volume scale, with cost compression in mid-tier mobile SDK bundles intensifying due to time-of-flight module pricing fluctuation. Healthcare providers exhibit lowest price sensitivity given regulatory compliance mandates; retail virtual-try-on deployments show highest elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from smartphone manufacturers in South Korea and the United States, while value-added resellers serve fragmented industrial field-service accounts. Taiwan and South Korea foundries anchor GPU silicon supply for neural-optimized chipsets; German automotive suppliers and Japanese logistics operators draw from these nodes for edge-compute deployments. Single-source vulnerability in advanced node semiconductor fabrication concentrates risk. Distribution runs through SDK vendor direct sales for defense contracts and cloud marketplaces for enterprise self-service procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities crystallize around EU AI Act compliance costs in Europe versus streamlined procurement pathways in the United States, where defense IT budgets absorb premium pricing for air-gapped configurations.
For Market Incumbents: Cement platform stickiness through multi-year master service agreements bundling SDK access with custom pipeline engineering for automotive and aerospace OEMs. Deepen backward integration into neural-optimized silicon design to offset Taiwan foundry capacity constraints. Prioritize FDA/PMDA/CE marking concurrency investments to extend certified-vendor preference cascades in healthcare procurement. For New Entrants and Emerging Players: Enter via haptic-integrated surgical training modules in Japanese academic medical centers, where regulatory pre-clearance pathways accelerate pilot programs. Target warehouse logistics operators in Germany and the United States with markerless SLAM solutions for remote equipment maintenance. Pursue channel partnerships with industrial digital-twin platform vendors to bypass direct enterprise sales friction. For Investors and Strategic Acquirers: Consolidation pressure builds where SLAM engineering talent scarcity constrains R&D velocity across mid-tier specialists. Frame long-term viability around 5-10 year platform consolidation toward vertically integrated hardware-software stacks. Target acquisition profiles emphasizing computer-vision engineering teams with real-time tracking algorithm expertise. Monitor FCC mmWave deployment velocity as inflection indicator for cloud-native SDK throughput expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies spatial-data pipelines for automotive digital-twin asset lifecycle management. |
| Acquisition of Specialist Firm | Addresses SLAM engineer scarcity constraining real-time tracking R&D velocity. |
| Strategic Partnership | Unlocks defense IT budgets through air-gapped deployment specifications with systems integrators. |
| Product Launch | Captures EU AI Act certified-vendor preference cascades in European healthcare procurement. |
| Geographic Expansion | Exploits FCC mmWave allocations for uncompressed point-cloud streaming in dense urban corridors. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core. Primary interviews with SDK platform engineers, enterprise IT procurement officers, healthcare biomedical engineers, and defense systems integrators combine with secondary validation from SEC filings, hyperscaler capex disclosures, App Annie mobile SDK adoption data, and EU AI Act conformity assessment documentation. Triangulation across these sources yields volume and value estimates.
Historical trendline analysis of mobile SDK bundling patterns and cloud-native architecture deployment rates informs projection construction across the analysis window. Segmentation dimensions modeled include product type (mobile/cloud/web/desktop), end-use vertical (healthcare/gaming/education/retail), technology methodology (markerless/marker-based/projection/superimposition), and deployment posture (on-premise/cloud/hybrid). CAGRs derive from regression-adjusted growth rate convergence with industry-specific inputs including 5G spectrum allocation timelines and regulatory certification backlog data.
The model holds under stable geopolitical conditions for semiconductor supply chains; deviation in Taiwan strait tensions or EU AI Act enforcement intensity would shift trajectory assumptions. Forecasts reflect documented base-case conditions with acknowledged sensitivity to GPU silicon availability and multi-jurisdiction certification concurrency delays. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Board Management Software Market
Software & Services
Banking Team Collaboration Software Market
Software & Services
DevOps Market
Software & Services
Embedded Software and Tools Market
Software & Services
Parametric Design Software Market
Software & Services
Managed Information Services Market
Software & Services
Global Gym Software Market
Software & Services
Global Online OCR Software Market
Software & Services
Automotive Customization Software Market
Software & Services
Generative Design Software Market
Software & Services
Mining Software Market
Software & Services
Estate Management Software Market
Software & Services
Illustration Software Market
Software & Services
Computational Medicine and Drug Discovery Software Market
Software & Services
Software Release Management Tools Market
Software & Services
Consignment Software Market