
 Illustration Software Market | 2026-2036
Illustration Software Market Size, Share, and Industry Trends Forecast 2026-2036
Illustration Software Market Outlook
ISO/IEC 25010 software quality certification is collapsing the barrier between professional-grade and consumer illustration tools, forcing incumbents to recertify or lose enterprise procurement eligibility. Adobe Illustrator leverages its Creative Cloud integration to sustain subscription renewal rates among design agencies. Affinity Designer anchors its position through perpetual-license pricing that competes directly with Adobe's subscription model. CorelDRAW dominates manufacturing and sign-making verticals where vector-to-CAM workflows remain essential.
Illustration software encompasses digital tools for creating, editing, and manipulating visual imagery through vector mathematics or raster pixel arrays, typically supporting color spaces such as CMYK and RGB with resolution outputs ranging from 72 ppi for web to 2400 ppi for print reproduction. These applications serve commercial art production, industrial design communication, and multimedia content creation across print, digital, and motion media. Vector graphics commands premium positioning among packaging and branding agencies where infinite scalability eliminates resolution loss across billboard-to-business-card workflows. Cloud-based deployment is accelerating fastest among distributed marketing teams requiring real-time collaboration tools with version control and asset libraries. Perpetual license models retain stronghold status in government and educational institutions with multi-year capital budgeting cycles that resist recurring operational expenditures.
FCC guidelines on digital accessibility shape interface design requirements for software distributed in the United States, while EU GDPR and the EU AI Act impose data governance and algorithmic transparency obligations on cloud-based platforms offering generative features. The California Consumer Privacy Act extends these compliance burdens to vendors serving the largest US state economy regardless of headquarters location. Stakeholders must monitor how generative AI disclosure mandates will reshape feature roadmaps and user consent architectures before committing to multi-year licensing structures.
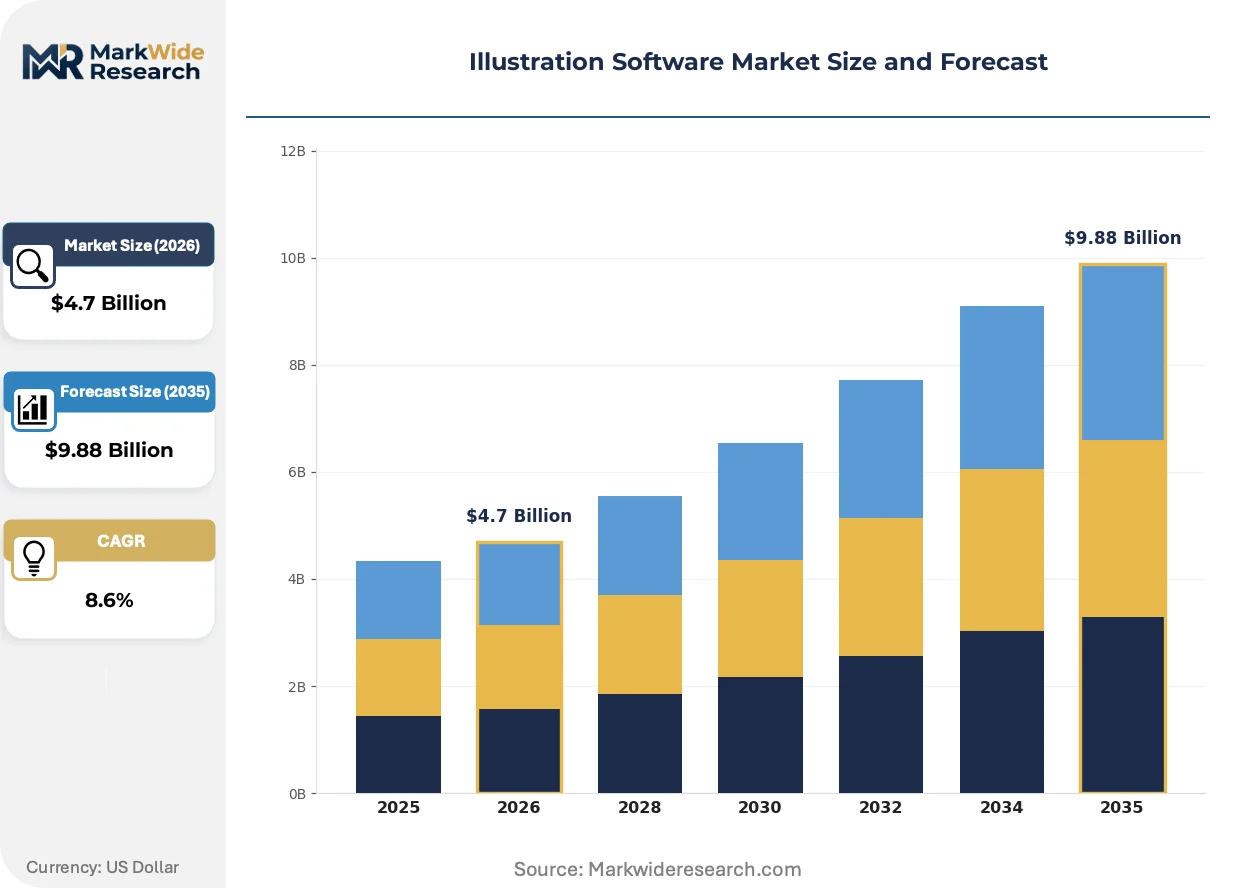
Market Dynamics
Generative AI disclosure mandates are compressing vendor compliance timelines while vector-to-CAM workflow integration locks manufacturing buyers into specialized toolchains. Cloud-native collaboration features are becoming procurement prerequisites for distributed creative teams.
Growth Catalysts
- EU AI Act transparency requirements:Disclosure mandates for generative tools are accelerating ISO/IEC 25010 certification adoption among enterprise vendors seeking procurement eligibility.
- Vector-based packaging workflows:Branding agencies demand infinite scalability from billboard to business card, driving premium positioning for mathematical illustration engines.
- Cloud deployment:Real-time version control and shared asset libraries are displacing file-based collaboration for marketing teams with distributed personnel.
Market Restraints
- Perpetual-license budget cycles:Government and educational institutions resist recurring SaaS expenditures, fragmenting revenue predictability.
- GDPR data residency:Cloud-based generative features face storage location restrictions that complicate multi-tenant architecture.
- Raster substitution in web workflows:Browser-native canvas rendering and CSS-based graphics reduce dependency on dedicated illustration applications for screen-only outputs.
Strategic Opportunities
- Sign-making vertical expansion:Vector-to-CAM integration for CNC routing and laser cutting remains underpenetrated outside North American and Western European manufacturing clusters.
- Accessibility compliance:FCC Section 508 and WCAG interface requirements create procurement wedges for vendors with certified accessible design toolkits.
- AI-human hybrid workflows:Convergence of generative fill capabilities with precision vector editing opens white space between automated production and craft-oriented refinement.
Industry Challenges
- Cross-functional certification timelines:ISO/IEC 25010 quality validation requires 12-18 month engineering cycles that delay feature releases.
- Legacy file format entrenchment:Decades of .AI and .CDR archives create switching friction for enterprise accounts with deep asset libraries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Illustration Software Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Software, 3D Software, Vector Graphics, Raster Graphics End User: Graphic Designers, Illustrators, Animators, Marketing Teams Deployment: Cloud-Based, On-Premises, Subscription-Based, Perpetual License Feature: Collaboration Tools, Export Options, Custom Brushes, Layer Management |
| Companies Covered | Procreate, Affinity Designer, Adobe Illustrator, Vectornator, Sketch, Canva, CorelDRAW, Clip Studio Paint, Figma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Illustration Software Market Strategic Shifts
Computational illustration is bifurcating between browser-native immediacy and desktop-grade precision, with regulatory pressure on algorithmic transparency forcing architectural rewrites.
Generative vector assistance is miniaturizing the gap between concept and production-ready artwork. Marketing teams at mid-size e-commerce operations are adopting AI-assisted path generation for rapid social asset iteration. This compression is miniaturizing the traditional agency retainer model by enabling in-house production at comparable output quality.
GDPR Article 22 and the EU AI Act's algorithmic transparency provisions are mandating disclosure of training data provenance for generative fill features. Vendors must now maintain auditable consent chains for source imagery, increasing compliance overhead. Cloud platforms serving European creative agencies are responding by segregating generative compute stacks to EU-only data centers.
Subscription fatigue among freelance illustrators is reviving perpetual-license demand, particularly in capital-budget-dependent sectors. Educational institutions and municipal government design departments are consolidating purchasing around multi-year license commitments that avoid operational expenditure classification. This pattern is most visible in United States state university systems and Canadian provincial education authorities.
Illustration Software Market Segmentation
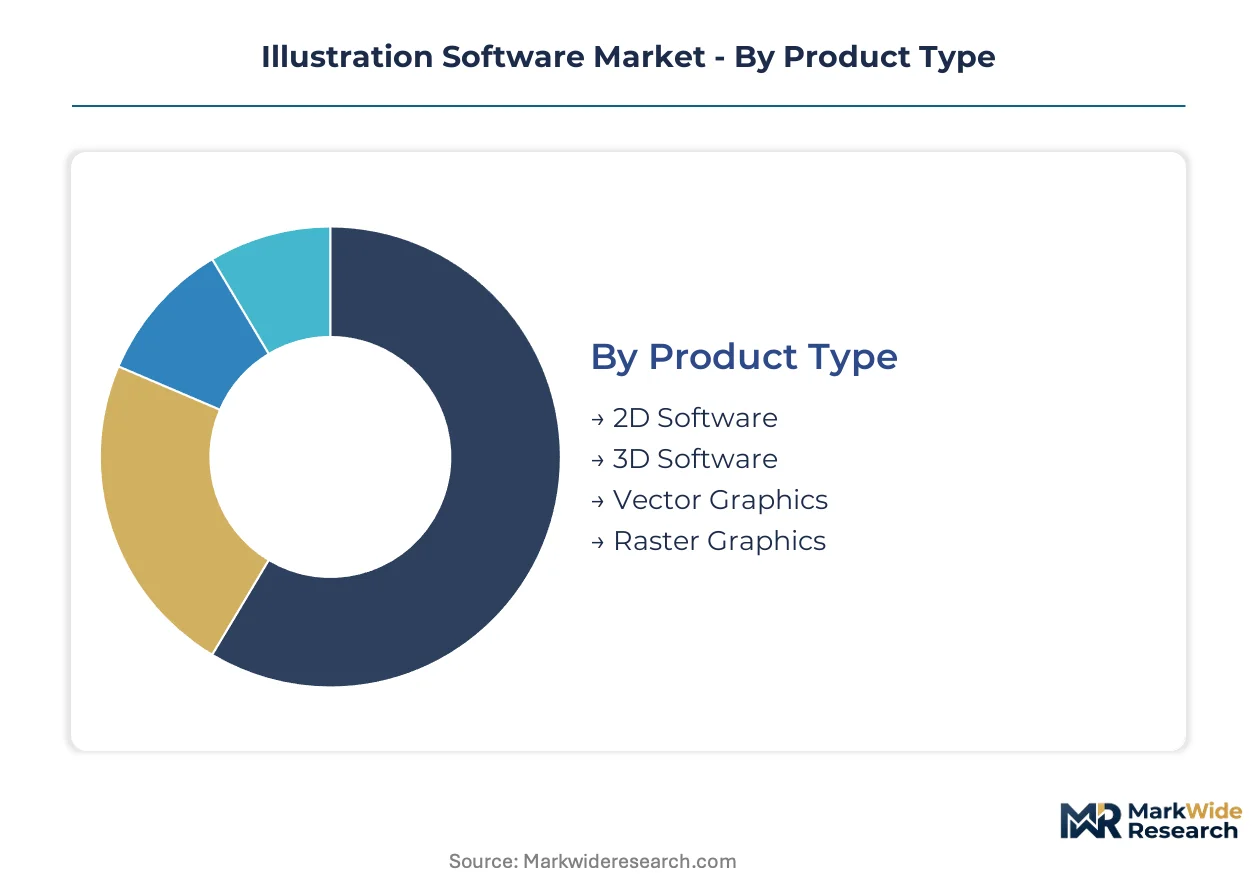
Illustration software procurement patterns diverge sharply across creative workflows, with vector-based tools dominating export-oriented packaging studios while raster solutions serve localized web production. Deployment preferences split along institutional budgeting cycles rather than technical requirements alone.
Product Type:
Vector graphics command premium positioning in cross-border branding workflows, while raster tools anchor domestic digital publishing operations.
- 2D Software:Flat illustration engines power editorial workflows, UI asset libraries, and social media content pipelines. Demand concentrates in United States marketing agencies where rapid turnaround timelines favor streamlined toolsets over dimensional complexity.
- 3D Software:Dimensional illustration tools support product visualization, architectural rendering, and motion graphics pre-visualization. German industrial design studios and Japanese gaming publishers drive specialized adoption where depth-accurate prototyping reduces physical sampling costs.
- Vector Graphics:Mathematical path engines enable infinite scalability from postage stamps to building wraps.
- Raster Graphics:Pixel-based editing dominates photography retouching and textured illustration styles.
Vector graphics holds the largest share; momentum sits with 3D software.
End User:
Marketing teams operate as the volume anchor, while animators represent the highest per-seat expenditure tier.
- Graphic Designers:Visual communication specialists bridge brand identity systems across print and digital touchpoints. United Kingdom packaging agencies and Dutch studio collectives drive ISO/IEC 25010 certification requirements for enterprise procurement eligibility.
- Illustrators:Individual practitioners and boutique studios prioritize brush responsiveness and tablet integration. Freelance communities in France and Canada sustain perpetual-license demand against subscription consolidation.
- Animators:Motion designers require timeline integration and frame-accurate export pipelines.
- Marketing Teams:In-house creative departments favor template libraries and brand-locked asset systems.
Marketing teams generate the highest seat volume; animators command the steepest expansion trajectory.
Deployment:
Cloud architectures concentrate in distributed creative operations, while perpetual licenses retain institutional strongholds.
- Cloud-Based:Browser-accessible platforms enable real-time collaboration across time zones. Australian and Singaporean agencies with remote-first policies drive adoption where version control replaces file-naming conventions.
- On-Premises:Local installation meets data sovereignty requirements and offline production needs. Defense contractors and financial services firms in Switzerland and the United States mandate air-gapped workflows for sensitive brand assets.
- Subscription-Based:Recurring revenue models dominate individual practitioners and mid-size studios.
- Perpetual License:One-time purchase structures align with capital budgeting cycles in education and government sectors.
Subscription-based deployment captures the broadest user base; perpetual licenses are gaining share fastest in public-sector procurement.
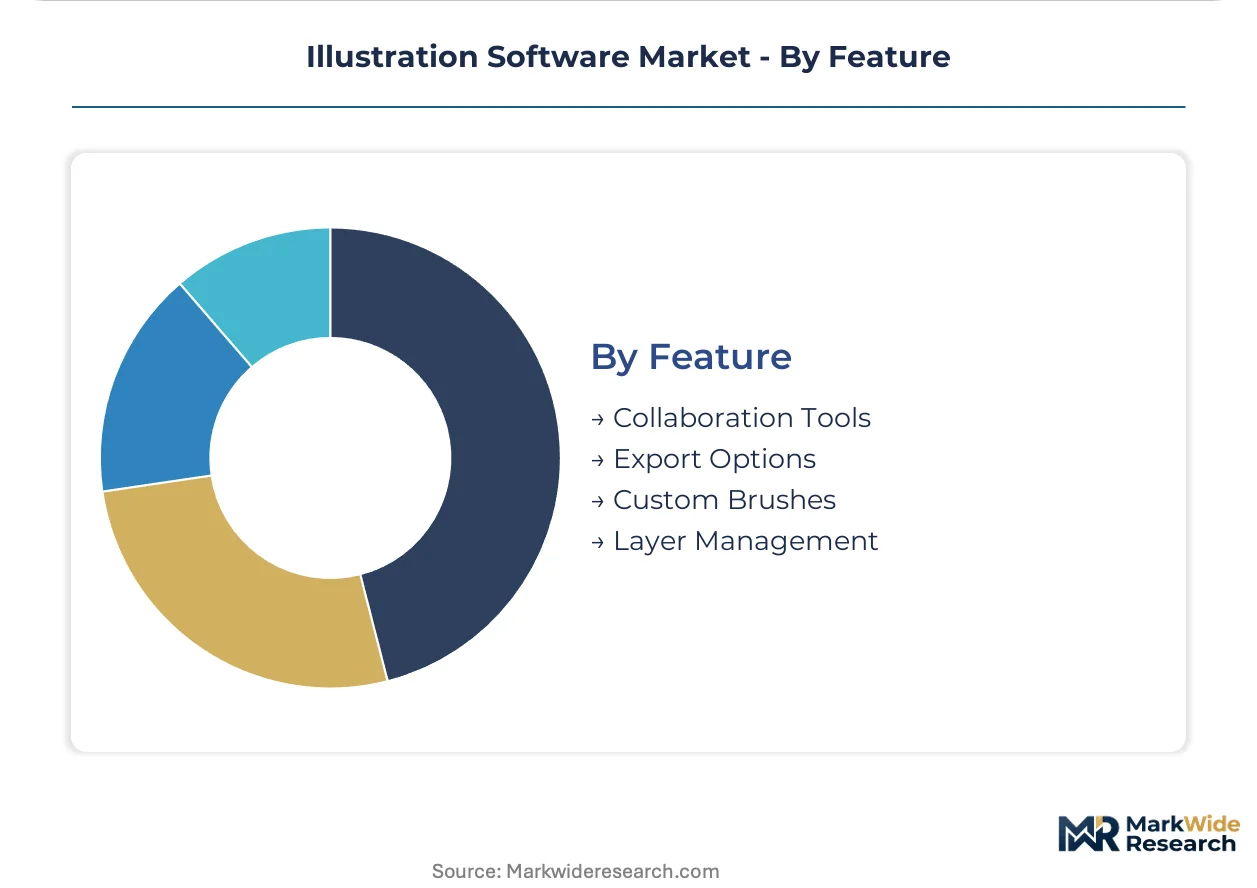
Feature:
Collaboration tools differentiate enterprise platforms, while custom brush engines defend professional-grade positioning.
- Collaboration Tools:Real-time co-editing, comment threading, and approval workflows compress production cycles. Brazilian and Mexican agency networks with distributed talent pools prioritize these capabilities over localized performance optimization.
- Export Options:Format breadth determines interoperability with manufacturing and web pipelines. Italian and Spanish packaging converters require CMYK-separated PDF/X compliance for press-ready output.
- Custom Brushes:Programmable stroke engines enable proprietary illustration styles.
- Layer Management:Non-destructive editing hierarchies support complex compositing workflows.
Export options holds functional priority across all tiers; collaboration tools are climbing the fastest as remote production normalizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transatlantic fiber optic cables and Pacific submarine networks underpin the geographic distribution of creative software demand, with latency-sensitive collaboration tools clustering near these digital arteries.
United States
Creative industry employment density in California and New York drives the highest per-capita SaaS procurement rates worldwide. FCC Section 508 accessibility mandates shape interface design requirements for vendors serving federal contracts. Austin and Seattle studio clusters are expanding vector-to-CAM workflows for regional manufacturing clients.
Germany
Industrial design studios in Bavaria and Baden-Württemberg anchor European demand for precision vector engines with manufacturing export pipelines. EU AI Act transparency requirements are compressing vendor compliance timelines for generative features. Berlin's motion graphics collectives are driving adoption of real-time cloud collaboration among distributed creative teams.
United Kingdom
London packaging agencies and Manchester e-commerce operations sustain premium positioning for scalable illustration tools across cross-border branding workflows. GDPR data residency rules are forcing cloud platform segregation for generative compute stacks. Bristol's independent game studios are expanding 3D illustration adoption for pre-visualization pipelines.
Japan
Tokyo-based gaming publishers and Osaka animation houses command the steepest per-seat expenditure for dimensional illustration tools. METI guidelines on software quality assurance intersect with ISO/IEC 25010 certification requirements for enterprise procurement. Kyoto's traditional craft industries are digitizing heritage designs through vector-based archival workflows.
Australia
Sydney and Melbourne agencies with remote-first policies are accelerating cloud-native adoption where version control replaces file-based collaboration. The country's national privacy regulator enforces data sovereignty requirements that complicate multi-tenant generative architectures. Brisbane's sign-making manufacturers are expanding vector-to-CAM integration for regional construction supply chains.
Illustration Software Market Competitive Environment
Listed leaders compete with private specialists across deployment models and licensing structures, creating a tiered competitive field where subscription scale battles perpetual-license loyalty. The market structure concentrates around three strategic archetypes: integrated creative suites, specialized vector engines, and browser-native collaboration platforms. Dominant competitive moves include ISO/IEC 25010 certification campaigns for enterprise eligibility and cloud infrastructure expansion to satisfy data residency mandates.
Within the integrated suite tier, Adobe Inc. exemplifies the subscription-scale archetype through Creative Cloud ecosystem lock-in, while Corel Corporation anchors the perpetual-license stronghold in manufacturing verticals. Among specialized vector specialists, Serif (Europe) Ltd. occupies a position competing directly on pricing model differentiation against recurring revenue incumbents.
| Leading Market Players |
|---|
| Procreate |
| Affinity Designer |
| Adobe Illustrator |
| Vectornator |
| Sketch |
| Canva |
| CorelDRAW |
| Clip Studio Paint |
| Figma |
| Others |
Value Chain & Pricing Dynamics
Twelve-month ISO/IEC 25010 certification cycles compress vendor pricing power by delaying feature releases that justify premium tiers, while cloud infrastructure concentration in United States and Irish data centers concentrates cost leverage among hyperscaler-dependent platforms. This lead-time rigidity forces subscription vendors to absorb compliance overhead or sacrifice enterprise procurement eligibility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and collaboration feature depth. Premium tiers command position through ISO/IEC 25010 validation and real-time co-editing capabilities, while economy tiers serve individual practitioners with offline-only toolsets. Cost compression in mid-market subscriptions intensifies because perpetual-license competitors capture public-sector volume. Government and educational procurement committees exhibit highest price sensitivity; animation studios with frame-accurate export requirements show lowest.
Supply Chain Analysis
Strait of Malacca submarine cable transit underpins cloud delivery latency for Southeast Asian creative agencies, creating infrastructure chokepoints that advantage vendors with Singapore and Sydney edge presence. Software development concentrates in United States, Germany, and Japan, with generative compute stacks drawing from Irish and Dutch data centers for EU compliance. Single-source vulnerability sits with hyperscaler GPU provisioning for AI-assisted features. Distribution runs through direct-to-customer SaaS portals and value-added resellers serving manufacturing verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of ISO/IEC 25010-certified engineering talent concentrates competitive advantage among vendors with completed validation cycles, locking out late entrants from enterprise procurement shortlists.
For Market Incumbents: Compound ecosystem lock-in through deeper Creative Cloud-style integration with manufacturing CAM pipelines and brand asset management platforms. Defend against Serif's perpetual-license threat by accelerating certification completion to maintain public-sector eligibility. Prioritize vertical integration into vector-to-CAM workflow toolchains for sign-making and packaging converters. For New Entrants and Emerging Players: Anchor in browser-native collaboration platforms for distributed marketing teams underserved by desktop-heavy incumbents. Target Australian and Brazilian agency networks with remote-first policies where version control gaps persist. Pursue white-label partnerships with e-commerce platform providers seeking embedded design tools. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified software conglomerates with undermonetized illustration assets lacking ISO/IEC 25010 certification. Long-term viability hinges on generative AI disclosure architecture compliance under EU AI Act transparency mandates. Monitor FCC Section 508 accessibility enforcement as signal for procurement wedge expansion.| Strategic Initiative | Industry Significance |
|---|---|
| ISO/IEC 25010 Certification Campaign | Unlocks enterprise procurement eligibility against unvalidated competitors in government verticals. |
| Vector-to-CAM Integration | Captures manufacturing loyalty through direct CNC and laser cutting pipeline connectivity. |
| EU Data Center Segregation | Satisfies GDPR Article 22 and EU AI Act residency requirements for generative compute. |
| Perpetual-License Product Line | Penetrates education and municipal sectors resisting recurring operational expenditures. |
| Accessibility Toolkit Development | Creates procurement advantage under FCC Section 508 and WCAG federal contract requirements. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with creative directors, IT procurement officers, platform engineers, and CAM workflow specialists; and secondary validation through SEC SaaS vendor filings, hyperscaler capex disclosures, App Annie productivity software rankings, and EU regulatory transparency databases. Bottom-up seat-count estimates triangulated against top-down addressable market calculations.
Across the analysis window, forecasts model deployment mode, organization size, creative vertical, and regional regulatory cluster. CAGRs derive from segment-level growth rate blending with technology adoption S-curves. Inputs include cloud infrastructure expansion timelines, ISO/IEC 25010 certification completion rates, and EU AI Act implementation phase transitions.
Underlying assumptions cover sustained remote-work normalization and stable hyperscaler pricing, with deviation risk concentrated in generative AI regulatory acceleration and perpetual-license demand revival. Practitioners should keep alternative scenarios live as compliance timeline compression and budget cycle shifts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Thermal Analysis Software Market
Software & Services
Pure Play Software Testing Market
Software & Services
Service Scheduling Software Market
Software & Services
Problem Management Software Market
Software & Services
Europe CMMS Software Market
Software & Services
Weather Forecast Software Market
Software & Services
API Testing Market
Software & Services
Global Recreation Management Software Market
Software & Services
LTFS Copy Software Market
Software & Services
Global Board Management Software Market
Software & Services
Global Dance Studio Software Market
Software & Services
Global Localization Software Market
Software & Services
Global Testing Software Market
Software & Services
Global Managed File Transfer Software Market
Software & Services
Global Big Data Software Market
Software & Services
Sales Gamification Software Market