
 Global Board Management Software Market | 2026-2036
Global Board Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Board Management Software Market Foresight
Cloud-native architecture is reshaping how board management platforms are built and delivered, shifting vendor investment from monolithic codebases toward API-first microservices. Diligent Corporation leverages extensive R&D intensity to sustain product leadership across enterprise governance workflows. Nasdaq Incorporation anchors its competitive position through deep integration with capital markets compliance infrastructure. Azeus Convene differentiates by specializing in Asia-Pacific localization and multilingual boardroom support.
Board management software comprises digital platforms that centralize document distribution, meeting orchestration, voting workflows, and compliance reporting for governing bodies, typically delivered through web and mobile interfaces with AES-256 encryption and role-based access controls. The primary commercial purpose is to replace paper-based board packets with auditable, real-time collaboration environments that reduce administrative overhead and strengthen regulatory defensibility. Cloud-based deployment leads the solution type landscape due to lower total cost of ownership and faster implementation cycles, while compliance tracking commands premium pricing as organizations face escalating disclosure obligations. Meeting scheduling and voting systems represent adjacent growth pockets where automation reduces friction in distributed board decision-making.
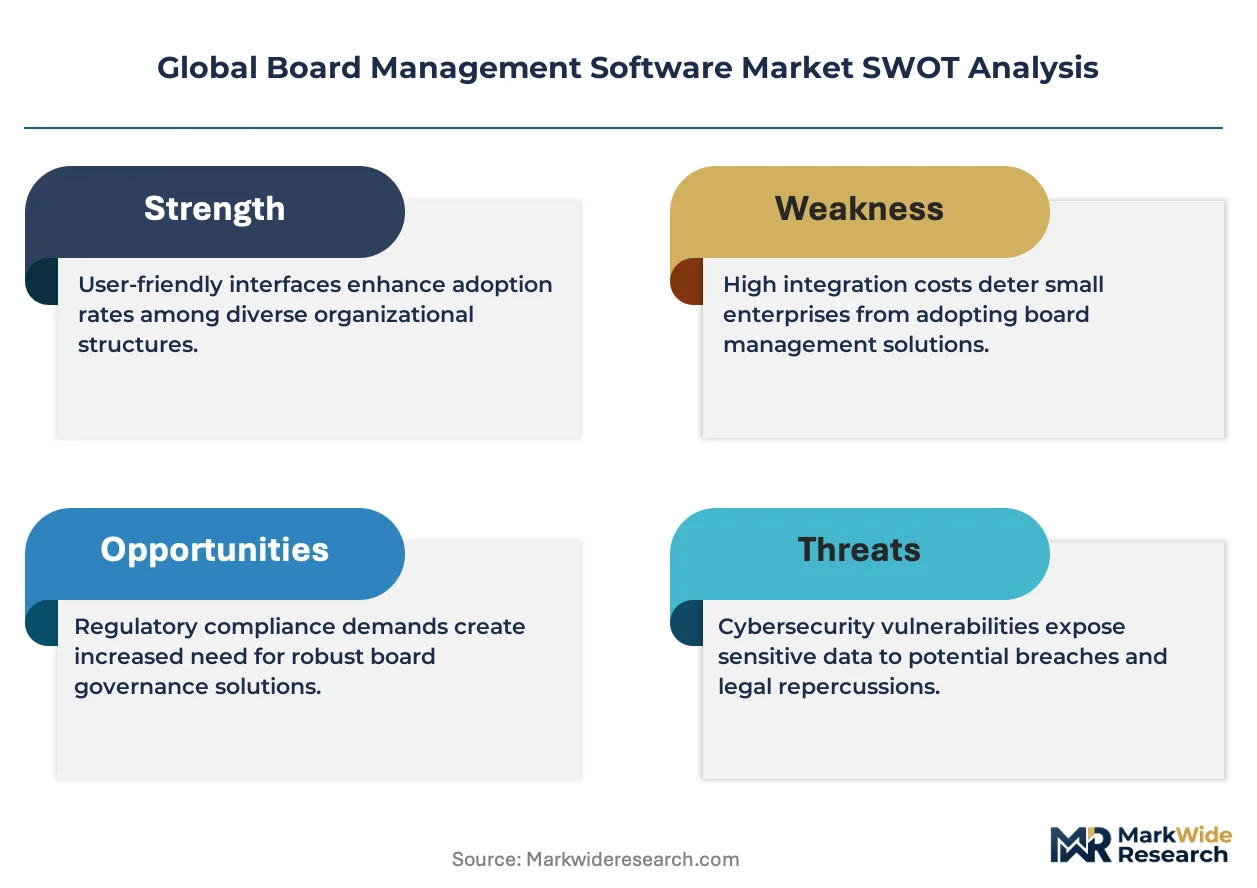
The EU CSRD and GDPR frameworks impose strict data residency and audit trail requirements on European board software procurement, directly shaping vendor product roadmaps and hosting architecture decisions. The US SEC and HIPAA regulations create parallel compliance burdens for healthcare and publicly traded entities selecting governance technology. Stakeholders must monitor how diverging jurisdictional standards for encryption, retention, and cross-border data flow influence platform design and vendor qualification criteria across their operating geographies.
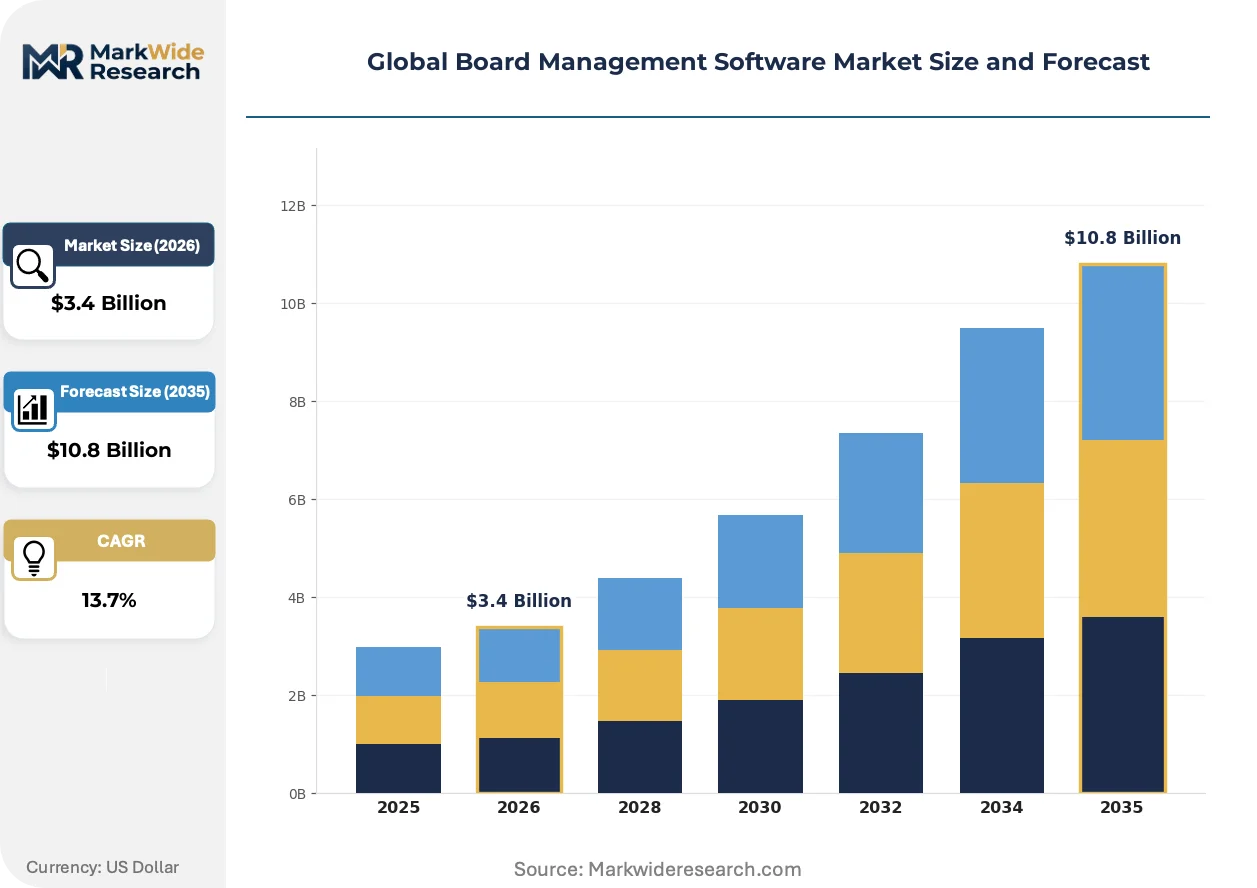
Market Dynamics
Cloud-native architecture is compressing deployment cycles and forcing incumbent vendors to rearchitect legacy platforms around API-first microservices, fundamentally altering competitive moats in enterprise governance technology.
Growth Catalysts
- EU CSRD Mandates:Corporate sustainability reporting directives in Europe are compelling boards to adopt audit-ready digital infrastructure with immutable document trails and granular access logging.
- Healthcare Digitization:US hospital systems facing HIPAA enforcement actions are replacing paper-based governance workflows with encrypted, role-controlled platforms to demonstrate compliance defensibility.
- Zero-Trust Security:AES-256 encryption with multi-factor authentication is becoming baseline procurement criteria, expanding addressable market for vendors with FedRAMP or ISO 27001 certifications.
Market Restraints
- Data Residency Costs:GDPR and emerging national data localization laws are fragmenting hosting architectures, forcing vendors to maintain redundant infrastructure across jurisdictions.
- Enterprise Sales Cycles:Procurement of board software by Fortune 500 companies typically spans 12-18 months with extensive security audits and pilot programs.
- Legacy System Entrenchment:Decades of Microsoft SharePoint and email-based board workflows create switching friction that slows platform consolidation.
Strategic Opportunities
- German Mittelstand:Mid-sized German corporations undergoing governance professionalization represent an underpenetrated segment with specific requirements for German-language support and local hosting.
- AI-Powered Analytics:Natural language processing for automated meeting transcription and sentiment analysis is creating premium pricing tiers for predictive governance intelligence.
- Mobile-First Design:Board members in Asia-Pacific markets are demanding full-featured native applications, opening differentiation paths beyond responsive web interfaces.
Industry Challenges
- Cybersecurity Talent Scarcity:Vendors struggle to hire sufficient security engineers to maintain SOC 2 Type II and ISO 27001 certifications across expanding product portfolios.
- Cross-Border Integration Complexity:Multinational clients require seamless data synchronization between instances hosted in different regulatory zones without violating residency requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Board Management Software Market |
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $10.8 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Hosted, Private Cloud Solution Type: Document Management, Meeting Scheduling, Voting Systems, Compliance Tracking, Collaboration Tools Application: Corporate Governance, Investor Relations, Risk Management, Strategic Planning, Audit Committees End User: Public Companies, Private Firms, Nonprofit Organizations, Educational Institutions, Government Agencies |
| Companies Covered | BoardEffect, Boardable, Diligent Corporation, Passageways, BoardPro, Nasdaq Incorporation, OnBoard, Admincontrol AS (Visma), Azeus Convene, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Board Management Software Market Shifts & Advancements
Artificial intelligence and zero-trust security architectures are converging to transform how sensitive board materials are created, distributed, and consumed across geographically dispersed leadership teams.
Blockchain-based document verification is virtualizing the notarization and chain-of-custody functions historically performed by physical document management services. Financial services boards in Switzerland and Singapore are piloting distributed ledger attestations for shareholder resolutions and audit committee reports. This shift is virtualizing third-party trust intermediaries and compressing the timeline for regulatory evidence production from weeks to minutes.
The EU AI Act is imposing risk-classification requirements on automated decision-support tools embedded in board analytics platforms. Vendors must now document algorithmic transparency and human oversight protocols for AI-generated meeting summaries or director performance assessments. German and French corporate governance advisors are demanding explicit contractual indemnification for algorithmic outputs, reshaping vendor liability frameworks.
Subscription fatigue among mid-market buyers is fragmenting procurement authority away from centralized IT departments toward individual board administrators. Chief governance officers in US healthcare systems and UK professional services firms are negotiating direct SaaS contracts with specialized vendors, bypassing enterprise software procurement committees. This disintermediation is compressing sales cycles but eroding volume-based pricing leverage for traditional enterprise license agreements.
Global Board Management Software Market Segmentation
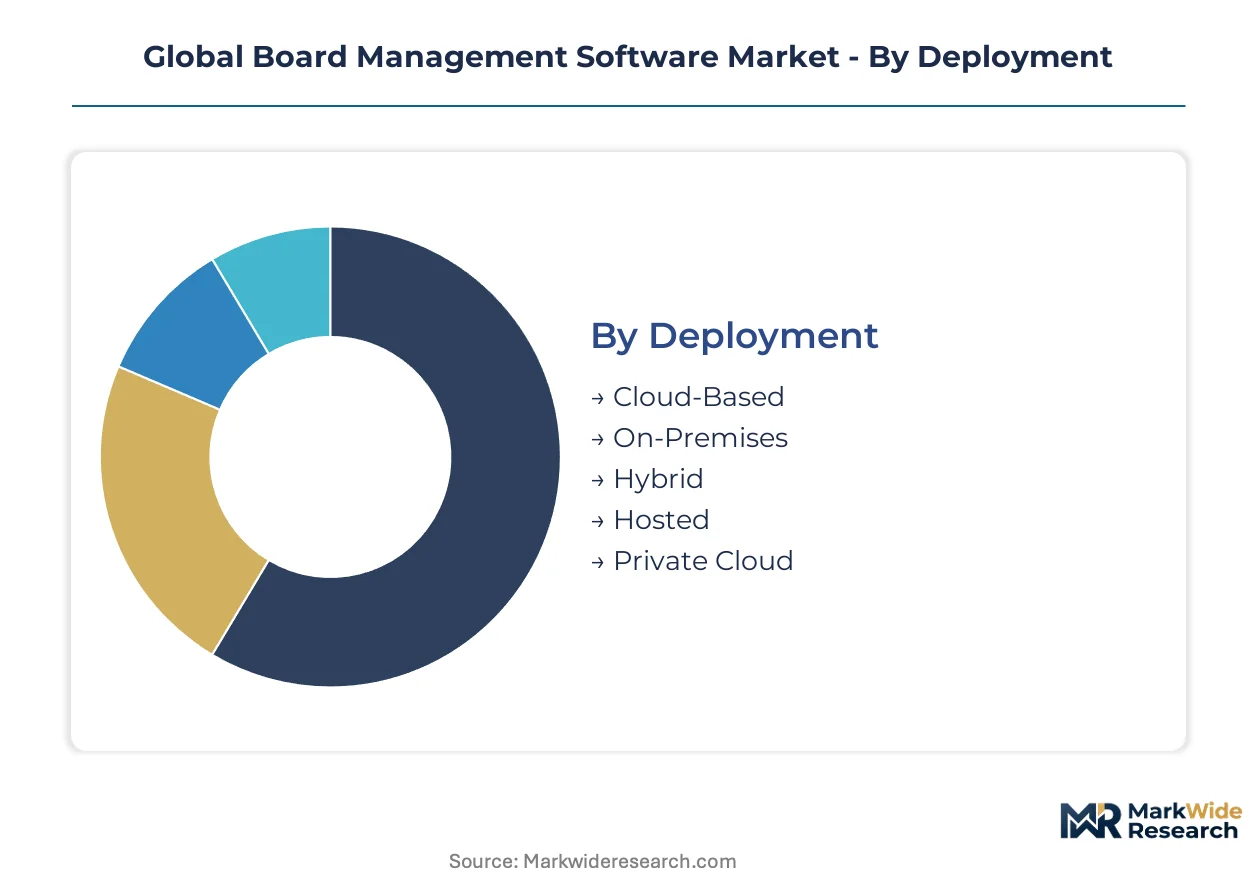
Board management software segments reflect divergent compliance burdens, security postures, and workflow complexity across governing bodies. Procurement patterns vary sharply between regulated public corporations and resource-constrained nonprofits, while deployment choices increasingly hinge on data residency mandates rather than pure cost optimization.
Deployment:
Use-case spectrum spans from lightly regulated nonprofits seeking minimal IT overhead to financial institutions demanding sovereign data control.
- Cloud-Based:Multi-tenant SaaS architecture with automatic updates and elastic scaling dominates mid-market procurement. US hospital systems facing HIPAA enforcement prioritize FedRAMP-authorized cloud instances to demonstrate compliance defensibility without capital expenditure.
- On-Premises:Dedicated hardware installations within client data centers serve organizations with strict air-gapping requirements. Swiss private banks and German automotive suppliers maintain on-premises governance infrastructure to satisfy national data localization statutes.
- Hybrid:Split architectures segregate sensitive board materials on-premises while routing collaboration tools through cloud gateways.
- Hosted:Single-tenant managed services in vendor-operated facilities bridge compliance and convenience for mid-tier public companies.
- Private Cloud:Dedicated virtualized environments within hyperscaler infrastructure deliver isolation without physical server ownership.
By volume, Cloud-Based leads. By growth pace, Hybrid is gaining share fastest as multinationals navigate conflicting jurisdictional requirements.
Solution Type:
Cost tier differentiation separates commodity workflow automation from premium compliance infrastructure commanding annual per-seat premiums.
- Document Management:Centralized repository systems with version control, watermarking, and granular access logging form the functional core of every platform. EU CSRD audit trail mandates are accelerating replacement of email-based document distribution in French and German boardrooms.
- Compliance Tracking:Automated disclosure calendars, regulatory deadline alerts, and attestation workflows carry the highest pricing multiples. US SEC reporting requirements and GDPR documentation obligations drive enterprise willingness to pay for integrated compliance modules.
- Meeting Scheduling:Calendar synchronization and room booking automation reduce administrative friction for distributed boards.
- Voting Systems:Secure digital ballot casting with cryptographic verification supports confidential director deliberations.
- Collaboration Tools:Real-time annotation, threaded discussions, and task assignment extend platforms beyond passive document consumption.
By volume, Document Management leads. By margin contribution, Compliance Tracking is expanding most quickly.
Application:
Customer type maturity shapes feature requirements, with audit committees demanding forensic-grade evidence chains that strategic planning users rarely invoke.
- Corporate Governance:Board portal functionality encompassing director onboarding, committee structure management, and governance policy distribution. UK-listed companies and Dutch multinational headquarters anchor demand for integrated entity management capabilities.
- Audit Committees:Specialized workflows for whistleblower intake, external auditor collaboration, and internal control documentation. Post-Enron regulatory frameworks in the US and post-Wirecard reforms in Germany elevate audit committee technology budgets.
- Investor Relations:Earnings preparation, shareholder communication tracking, and proxy statement management.
- Risk Management:Enterprise risk register integration and control self-assessment documentation.
- Strategic Planning:Long-range plan collaboration and scenario modeling support for board retreats.
By volume, Corporate Governance leads. By contract value expansion, Audit Committees are climbing the fastest.
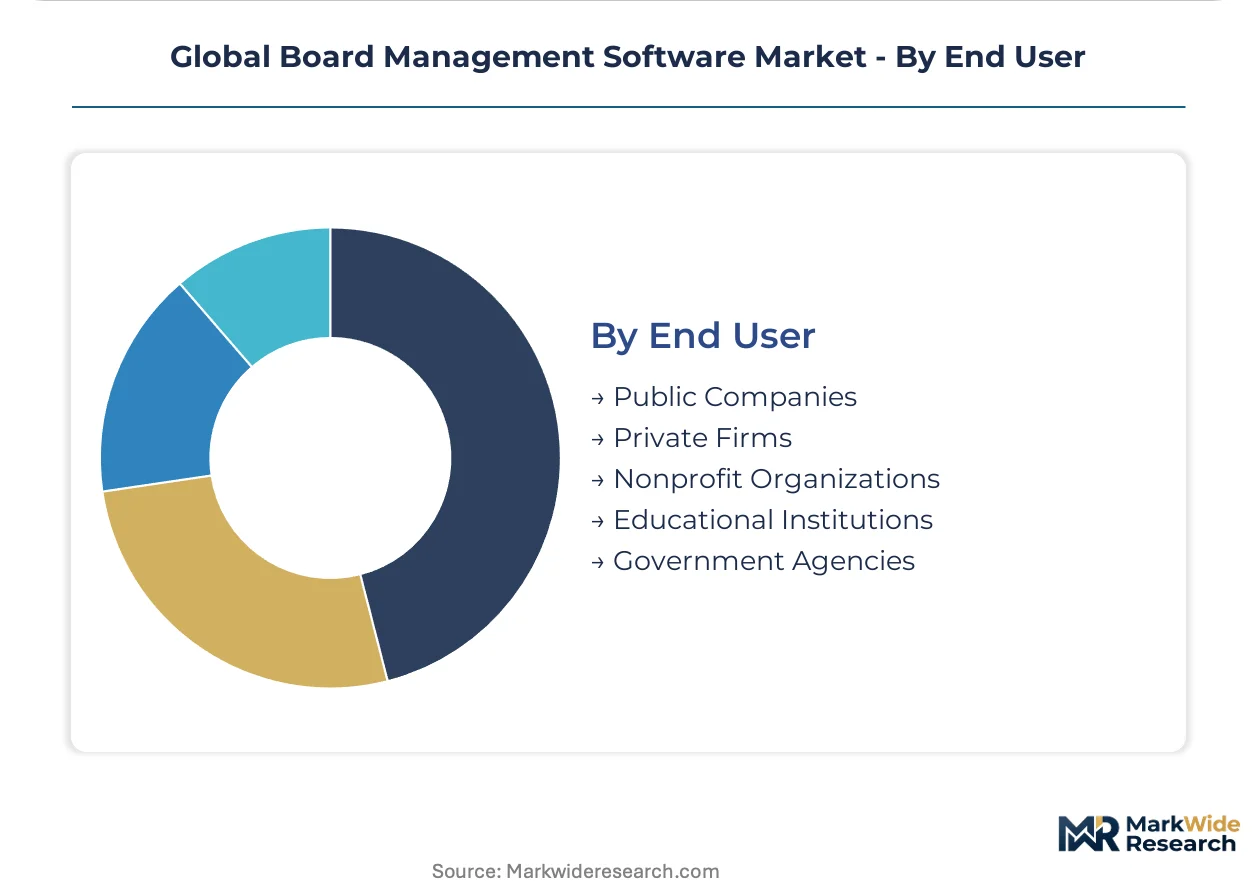
End User:
Volume concentration sits with regulated entities where governance technology spending is non-discretionary, while nonprofit and educational segments exhibit price elasticity.
- Public Companies:Mandatory disclosure regimes and shareholder litigation exposure make board software procurement defensive necessity. US SEC registrants and EU-listed entities under CSRD scope represent the revenue foundation for established vendors.
- Private Firms:Family-owned enterprises and private equity portfolio companies adopt streamlined governance platforms as professionalization signals. German Mittelstand corporations undergoing generational succession drive regional growth.
- Nonprofit Organizations:Foundation boards and association governing bodies prioritize cost minimization over feature depth.
- Educational Institutions:University trustees and school district boards adopt lightweight solutions for volunteer-led governance.
- Government Agencies:Public sector procurement compliance and open records requirements create specialized specification demands.
By volume, Public Companies leads. By new customer acquisition velocity, Private Firms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fortune 500 headquarters clusters in the United States and Germany concentrate procurement authority for board management platforms, while regulatory divergence between SEC disclosure mandates and EU CSRD requirements fragments vendor go-to-market strategies.
United States
Healthcare systems and publicly traded corporations drive demand through defensive compliance spending. SEC enforcement actions and HIPAA audit pressures push hospital networks toward FedRAMP-authorized cloud deployments. The New York-Washington corridor anchors procurement volume for audit-committee-grade platforms with forensic document trails.
Germany
Corporate governance reforms under EU CSRD and post-Wirecard regulatory tightening accelerate Mittelstand professionalization. The country's national data regulator enforces strict data localization requirements that favor hybrid deployment architectures. Frankfurt and Munich host concentrated demand from automotive suppliers and private banks requiring sovereign hosting.
United Kingdom
Listed companies and professional services firms sustain demand for integrated entity management capabilities. The Financial Conduct Authority's disclosure expectations align with premium compliance-tracking module adoption. London's governance advisory cluster shapes procurement specifications across Commonwealth markets.
Japan
Corporate governance code revisions and board independence mandates expand addressable market beyond traditional paper-based workflows. METI guidance on digital transformation encourages adoption among keiretsu-affiliated manufacturers. Tokyo and Osaka headquarters concentrate demand for multilingual support and mobile-first interfaces.
Singapore
Regional headquarters for multinational corporations generate demand for cross-border data synchronization without violating residency requirements. The Monetary Authority of Singapore's technology risk management guidelines elevate security certification requirements. The city-state's financial district pilots blockchain-based document verification for shareholder resolutions.
Global Board Management Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered pricing bands that separate enterprise governance suites from mid-market workflow tools. Market structure concentrates around three strategic archetypes: capital markets infrastructure incumbents leveraging compliance integration, pure-play SaaS vendors emphasizing user experience, and regional specialists optimizing for local regulatory nuance. Dominant competitive moves include strategic partnerships with audit firms and geographic expansion through localization investments.
Within the capital markets infrastructure tier, Nasdaq Incorporation and Diligent Corporation exemplify archetypes that anchor competitive positioning through regulatory integration depth. Azeus Convene occupies a specialist position emphasizing Asia-Pacific localization. These three represent the spectrum from global-scale compliance platforms to regionally optimized deployment expertise.
| Leading Market Players |
|---|
| BoardEffect |
| Boardable |
| Diligent Corporation |
| Passageways |
| BoardPro |
| Nasdaq Incorporation |
| OnBoard |
| Admincontrol AS (Visma) |
| Azeus Convene |
| Others |
Supply & Pricing Matrix
Single-source dependency on hyperscaler infrastructure in the United States determines both pricing tier spreads and supply chain shape for board management software vendors navigating data residency mandates.
Pricing Analysis
Cost-plus contracts with hyperscaler indexation anchor vendor cost structures, forcing SaaS pricing stratification across FedRAMP-authorized premium tiers, standard commercial tiers, and economy self-serve tiers. Price differentiation separates healthcare systems requiring HIPAA-compliant hosting from nonprofit boards accepting standard encryption. Pricing pressure stems from subscription fatigue among mid-market buyers bypassing enterprise procurement committees. Nonprofit organizations exhibit highest price sensitivity, while publicly traded entities under SEC enforcement show lowest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for hardware-dependent on-premises deployments, though pure SaaS vendors face minimal direct exposure. Software development concentrates in the United States, India, and Ireland, with cloud infrastructure drawing from hyperscaler facilities in Frankfurt, Singapore, and Virginia. Raw material dependencies include semiconductor components for secure hardware modules, cryptographic processors, and specialized storage arrays. Single-source vulnerability sits with AWS, Azure, and GCP for elastic compute. Distribution runs through direct enterprise sales teams and channel partners serving regional mid-markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward individual board administrators and chief governance officers, fragmenting procurement authority away from centralized IT committees and compressing enterprise sales cycles.
For Market Incumbents: Insulate recurring revenue streams by embedding workflow automation deeper into audit committee processes, creating switching costs that offset subscription fatigue. Defend against emerging low-code governance platforms by accelerating FedRAMP and ISO 27001 certification investments that mid-market buyers cannot replicate. Prioritize API-first microservices architecture to maintain integration leverage against point solutions. For New Entrants and Emerging Players: Establish a beachhead in German Mittelstand corporations undergoing CSRD-mandated governance professionalization, where local hosting requirements and German-language support create barriers for global incumbents. Target private equity portfolio companies seeking lightweight governance signals for limited partner reporting. Pursue mobile-first native applications for Asia-Pacific board members as the primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized compliance infrastructure over generalist workflow tools, rewarding vendors with audit-firm partnerships and regulatory integration depth. Long-term viability hinges on AI governance capabilities that survive EU AI Act risk-classification scrutiny. Acquisition target archetype: regional specialists with sovereign hosting certifications and established channel relationships. Signal to watch: CSRD enforcement actions accelerating replacement cycles in European boardrooms.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deepens vendor lock-in by embedding board workflows within existing Microsoft 365 and Salesforce environments. |
| Strategic Partnership | Big Four audit firm alliances accelerate CSRD-ready sales cycles through trusted advisor channels. |
| Acquisition of Specialist Firm | Blockchain verification capabilities from Swiss and Singapore pilots address forensic document attestation demand. |
| Geographic Expansion | Frankfurt and Munich data centers satisfy German national regulator localization mandates for automotive suppliers. |
| Product Launch | AI-powered meeting transcription with human oversight protocols meets EU AI Act transparency requirements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, EU regulatory guidance documents, and hyperscaler infrastructure disclosures to validate market sizing assumptions. Primary interviews encompassed chief governance officers at US hospital systems, corporate secretaries at UK-listed companies, compliance leads at German automotive suppliers, and channel partners serving Asia-Pacific mid-markets. Secondary sources included FDA enforcement action databases, EBA supervisory guidance, and cloud certification registries. Bottom-up triangulation across deployment models and top-down validation against enterprise software spending benchmarks anchored volume estimates.
Forecast inputs include adoption velocity across cloud-native and hybrid architectures, CSRD implementation timelines in EU member states, and HIPAA enforcement intensity in US healthcare systems. Segmentation modeling spans deployment type, solution tier, end-user organization size, and regional regulatory cluster. CAGRs derive from elasticity-adjusted penetration curves and replacement cycle compression in regulated industries. Industry-specific inputs incorporate FedRAMP authorization backlogs and German data localization statute enforcement patterns.
Sensitivities concentrate around EU AI Act risk-classification rulings affecting automated governance tools and potential hyperscaler price indexation shocks. Forecasts reflect assumptions about regulatory enforcement continuity and enterprise procurement centralization trends. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Attendance Tracking Software Market
Software & Services
School Timetable Software Market
Software & Services
Patent Management Software Market
Software & Services
3D Animation Production Software Market
Software & Services
Point Cloud Processing Software Market
Software & Services
Freight Management Software Market
Software & Services
Electronic Data Interchange (EDI) Software Market
Software & Services
APAC Workforce Management Software Market
Software & Services
On-Demand Wellness Software Market
Software & Services
Global Desktop As a Service Market
Software & Services
Global Absence Management Software Market
Software & Services
Load Balancing Software Market
Software & Services
Home Fitness App Market
Software & Services
LTFS Copy Software Market
Software & Services
Global Architecture Software Market
Software & Services
Dental Practice Management Software Market