
 Estate Management Software Market | 2026-2036
Estate Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Estate Management Software Market Analysis
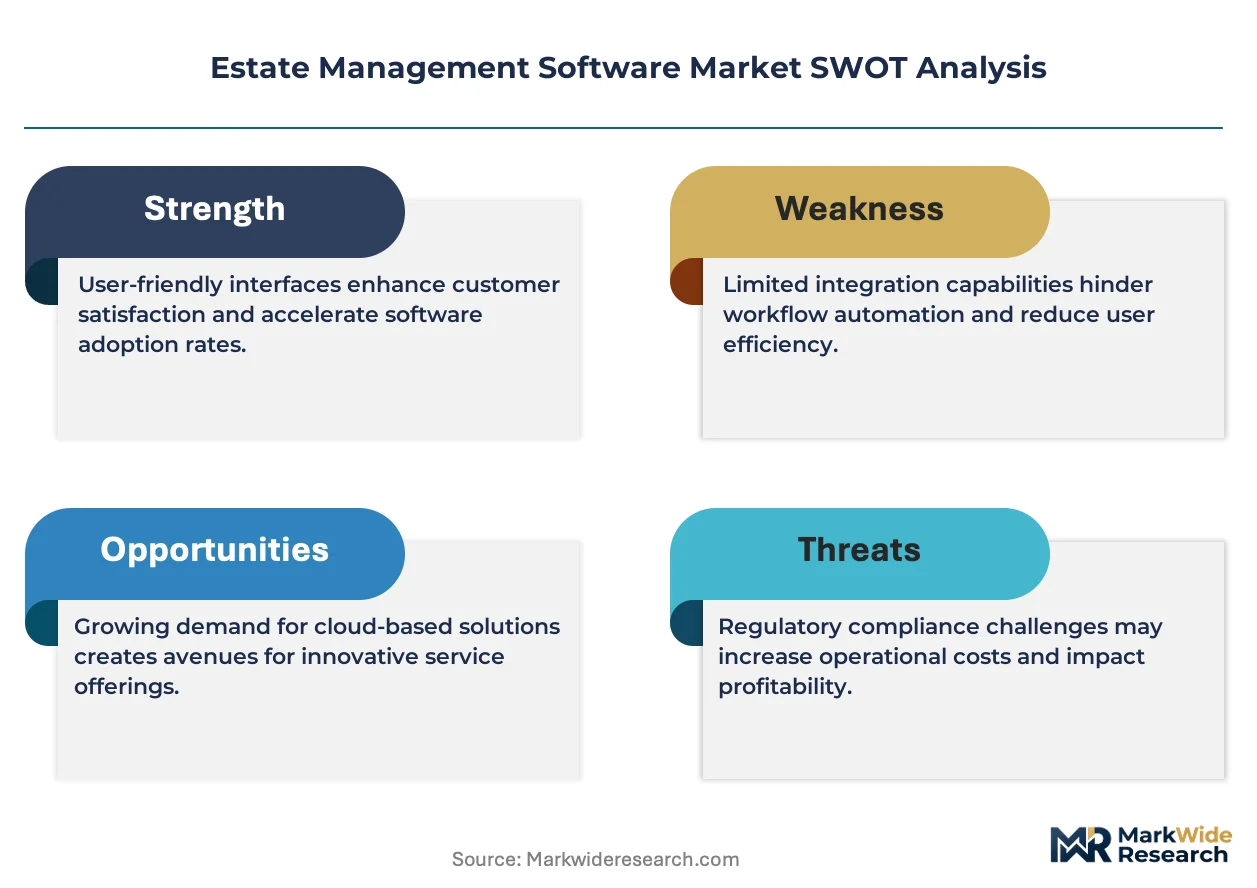
The divide between premium enterprise suites and commodity point solutions is hardening in the estate management software space. Yardi Systems anchors the high end through deep vertical integration across property management and lease administration modules. RealPage competes on scale, sustaining dominance in multifamily revenue management through channel control with major REITs.
Estate management software encompasses integrated digital platforms that automate property operations, financial reporting, tenant communications, and maintenance workflows through configurable dashboards and API-connected data layers. These systems serve commercial and residential asset operators by centralizing lease lifecycles, rent collection, and regulatory compliance documentation into unified command structures. Cloud-based deployment leads expansion as asset managers prioritize remote accessibility and reduced IT overhead, while on-premises installations retain traction among regulatory bodies with stringent data sovereignty requirements. Property Management as a product category captures the largest margin pool due to recurring subscription attach rates, whereas Maintenance Management represents the fastest-growing segment as Internet of Things sensor integration drives predictive service models.
FDA guidelines on software validation for financial reporting, EU GDPR data residency mandates, and SEC disclosure requirements for real estate investment trusts collectively elevate compliance functionality from feature to procurement prerequisite. HIPAA-adjacent privacy frameworks in medical office building management further complicate vendor qualification, filtering out undercapitalized entrants. Stakeholders must weigh the trade-off between platform consolidation and specialized best-of-breed tools as regulatory complexity intensifies.
Market Dynamics
The estate management software sector is experiencing a structural compression as cloud-native architectures displace legacy on-premises deployments, forcing vendors to rebuild core modules for API-first interoperability while institutional buyers demand unified data layers across mixed-use portfolios.
Growth Catalysts
- GDPR data residency mandates:European asset managers are replacing fragmented point solutions with integrated platforms that embed encryption and localized server infrastructure, accelerating procurement cycles for compliant vendors.
- Internet of Things sensor networks:Predictive maintenance modules are capturing subscription attach rates as commercial property operators deploy connected HVAC and elevator systems to reduce unplanned downtime.
- Institutional multifamily REITs:These investors are consolidating vendor relationships to achieve portfolio-wide visibility across lease administration, rent collection, and capital planning functions.
Market Restraints
- Technical debt in legacy systems:On-premises installations at regulatory bodies and sovereign wealth funds resist migration due to stringent data sovereignty requirements and multi-year amortization schedules.
- Specialized compliance fragmentation:HIPAA-adjacent privacy frameworks for medical office buildings and SEC disclosure requirements for real estate investment trusts create qualification barriers that filter undercapitalized entrants.
- Integration complexity costs:Best-of-breed toolchains require expensive middleware development to synchronize lease lifecycle data with financial reporting systems, eroding total cost of ownership advantages.
Strategic Opportunities
- United States institutional asset managers:Mixed-use portfolio operators represent concentrated demand for unified command structures spanning residential, retail, and office assets.
- Outcome-based service contracts:Vendors are repositioning maintenance management modules as performance-guaranteed subscriptions tied to uptime metrics rather than seat-based licensing.
- API marketplace ecosystems:Third-party developers are building vertical extensions for specialized asset classes, creating network effects that reinforce platform stickiness without internal R&D burden.
Industry Challenges
- Cloud architecture talent scarcity:Vendors struggle to recruit engineers with expertise in multi-tenant SaaS infrastructure and real-time data pipeline engineering.
- Certification timeline compression:SOC 2 Type II and ISO 27001 audits now require 12-18 month lead times, delaying market entry for new platform entrants serving financial services end-uses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Estate Management Software Market |
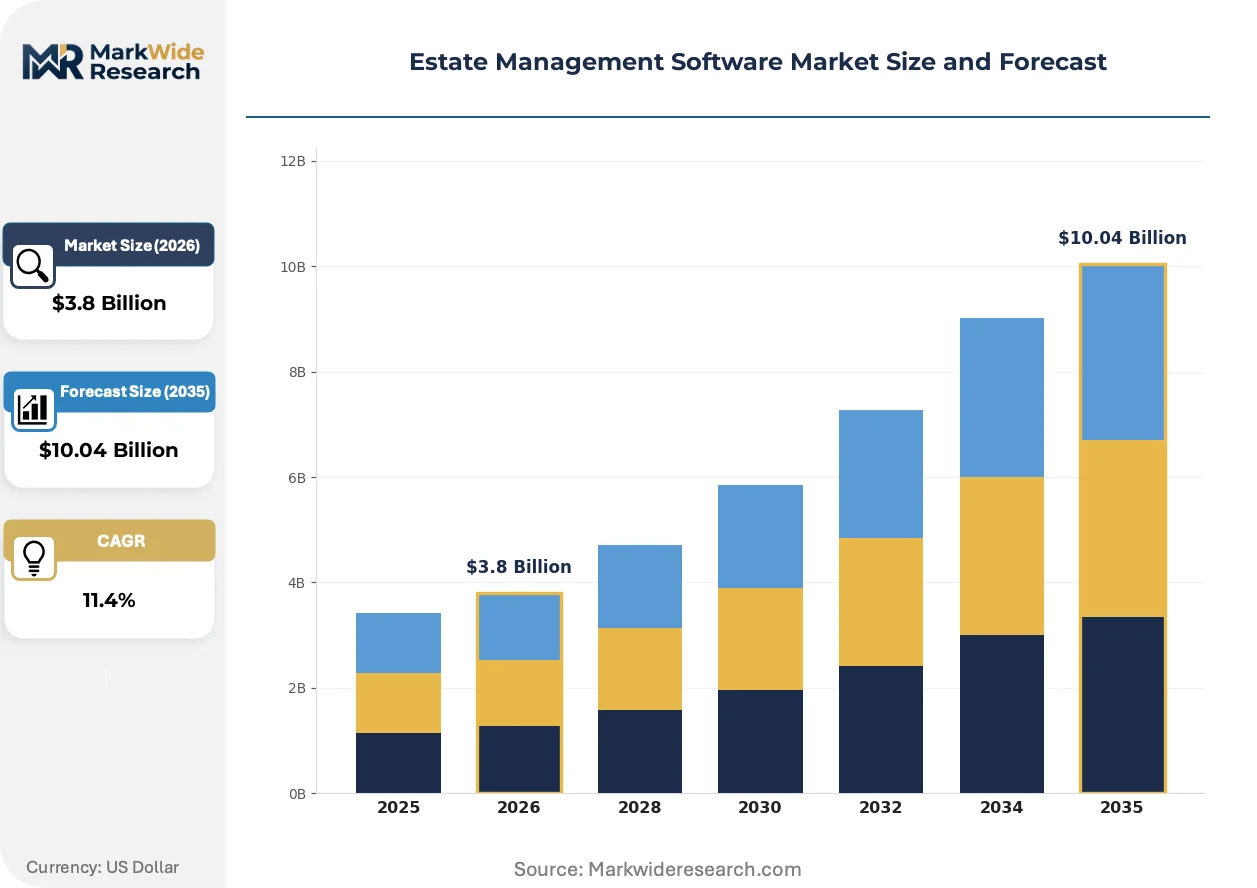
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Property Management, Lease Administration, Trust Management, Maintenance Management Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Solutions End User: Real Estate Firms, Asset Managers, Property Owners, Regulatory Bodies Application: Commercial Estates, Residential Properties, Mixed-Use Developments, Retail Spaces |
| Companies Covered | Yardi Systems, Inc., RealPage, Inc., AppFolio, Inc., MRI Software, Entrata, Inc., Buildium, ResMan, CoStar Group, Propertyware, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Estate Management Software Market Emerging Trajectories
Artificial intelligence and machine learning capabilities are absorbing operational workflows across property management, compressing the competitive window for vendors that lack native predictive analytics while buyers recalibrate procurement criteria around automation depth.
Machine learning algorithms trained on historical lease patterns and maintenance logs are absorbing routine decision-making previously executed by property managers. Mid-market multifamily operators are deploying these tools to optimize rent pricing and vendor dispatch schedules. The technology is absorbing margin from traditional consulting relationships as asset managers bring predictive capabilities in-house.
EU GDPR data residency mandates are forcing vendors to establish regional cloud infrastructure and appoint data protection officers for European deployments. Asset managers operating cross-border portfolios must now maintain segregated data environments with distinct encryption keys. Medical office building operators face the steepest compliance burden as they navigate overlapping HIPAA-adjacent frameworks and EU privacy requirements.
Subscription pricing for maintenance management modules is displacing perpetual licenses as Internet of Things sensor integration creates recurring value through predictive service models. Institutional buyers are consolidating vendor relationships to reduce contract administration overhead. This shift is most visible in the United States, where REITs with diversified portfolios are demanding unified dashboards across asset classes rather than specialized tools for each property type.
Estate Management Software Market Segmentation
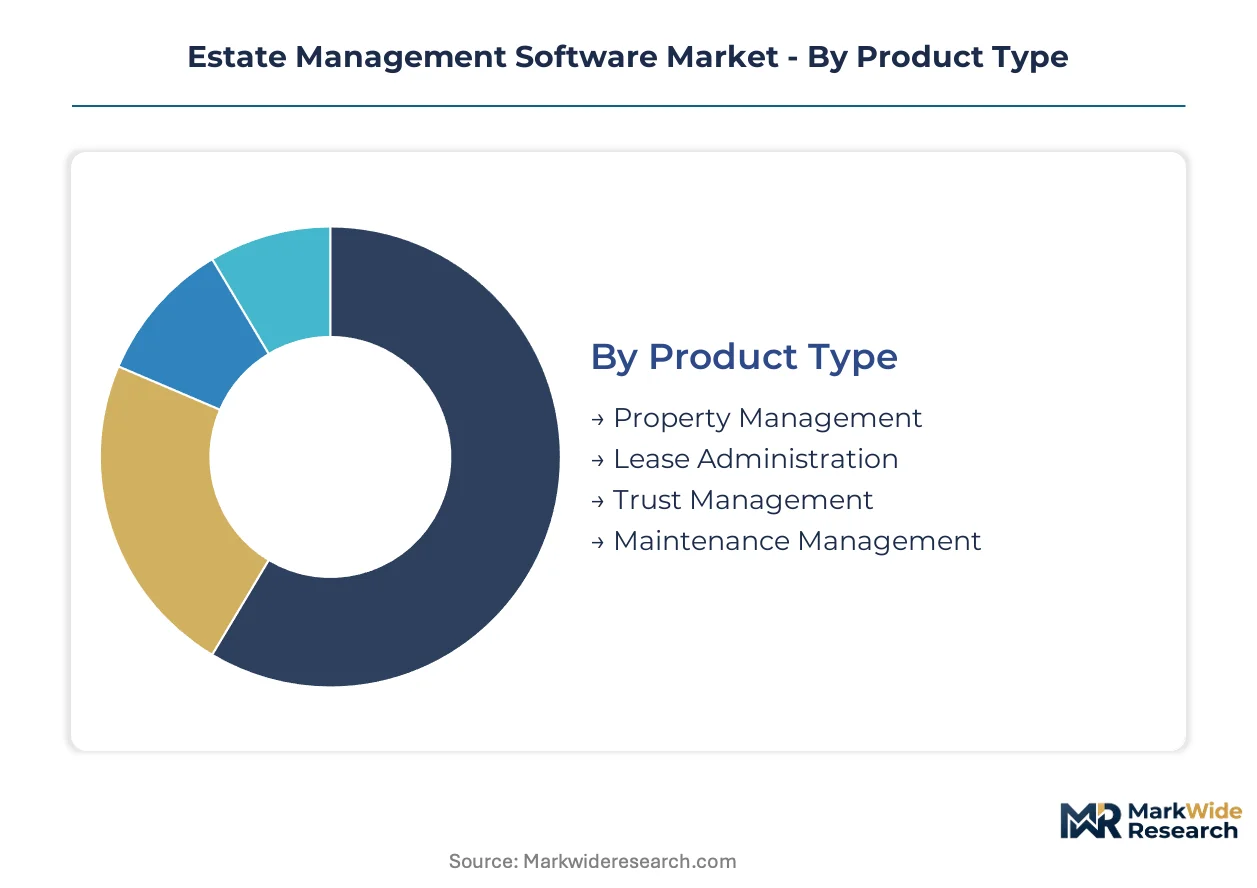
Estate management software segments diverge sharply by integration depth, with standalone modules serving specialized compliance needs while unified platforms capture institutional consolidation mandates. Procurement criteria now prioritize API connectivity over feature breadth alone.
Product Type:
Standalone modules dominate regulatory-heavy deployments, whereas integrated suites command premium pricing through unified data layers.
- Property Management:Core modules automate rent collection, tenant screening, and lease lifecycle tracking through configurable workflow engines. Asset managers in the United States favor these systems for multifamily portfolio visibility, driven by SEC disclosure requirements for REITs.
- Maintenance Management:Predictive service platforms integrate IoT sensor feeds from HVAC and elevator systems to dispatch vendors before failure events. Commercial property operators in Germany deploy these tools to satisfy GDPR-mandated data residency while reducing unplanned downtime.
- Lease Administration:Document-centric platforms centralize abstracting, critical date tracking, and ASC 842 compliance reporting.
- Trust Management:Fiduciary accounting modules serve family offices and estate trustees with segregated fund tracking and beneficiary distribution workflows.
Property Management leads volumes today; Maintenance Management is gaining share fastest.
Deployment:
Cost tier stratification separates enterprise-grade infrastructure from mid-market accessibility, with hybrid architectures bridging compliance and agility demands.
- Cloud-Based:Multi-tenant SaaS architectures deliver remote accessibility and reduced IT overhead through browser-native dashboards. Institutional asset managers prioritize these deployments for mixed-use portfolio command structures, though GDPR compliance requires localized server infrastructure in Europe.
- On-Premises:Single-tenant installations maintain data sovereignty for sovereign wealth funds and regulatory bodies with multi-year amortization schedules. French medical office building operators retain these systems to satisfy CNIL oversight alongside HIPAA-adjacent frameworks.
- Hybrid:Split architectures isolate sensitive financial data on-premises while pushing operational workflows to cloud edge nodes.
- Mobile Solutions:Native iOS and Android applications extend field staff capabilities for inspection capture and work order execution.
Cloud-Based deployments anchor current procurement; Hybrid architectures show steepest expansion trajectory.
End User:
Customer type determines feature prioritization, with institutional buyers demanding portfolio-wide analytics and regulatory bodies insisting on audit trails.
- Asset Managers:Institutional investors oversee diversified holdings across residential, retail, and office assets through unified command structures. United States-based REITs consolidate vendor relationships to achieve cross-asset visibility, compressing procurement cycles for integrated platforms.
- Real Estate Firms:Brokerage-owned property management divisions balance client service mandates with operational efficiency targets.
- Property Owners:Individual and family-held portfolios prioritize cost containment over advanced analytics capabilities.
- Regulatory Bodies:Government housing authorities and pension fund auditors require immutable record-keeping and granular permission architectures.
Asset Managers concentrate revenue today; Regulatory Bodies are expanding procurement most quickly.
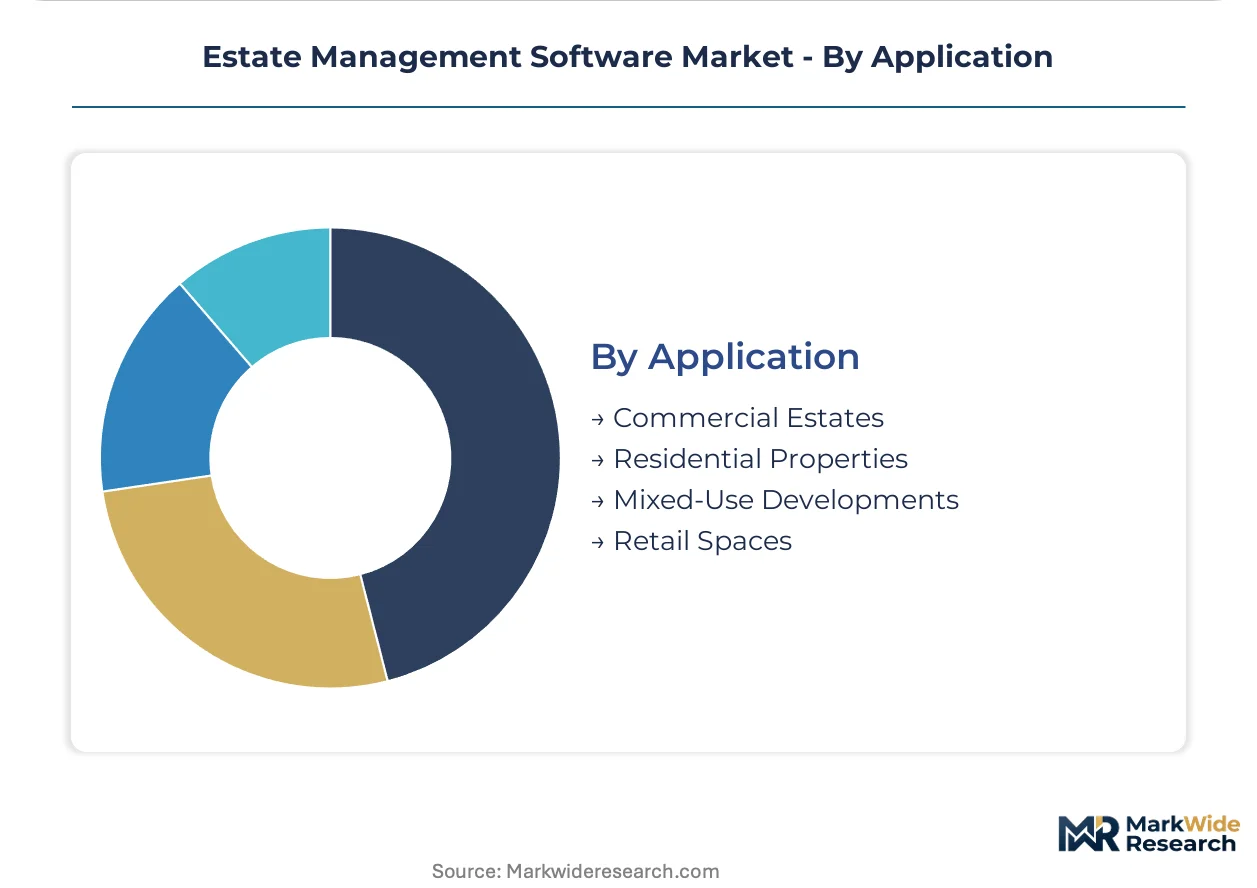
Application:
Maturity gradients separate established commercial deployments from emerging mixed-use complexity, with retail spaces presenting unique tenant-mix optimization challenges.
- Commercial Estates:Office and industrial property platforms emphasize lease abstraction, CAM reconciliation, and tenant improvement tracking. German institutional investors deploy these systems to satisfy ESG disclosure requirements under CSRD while managing cross-border portfolios.
- Mixed-Use Developments:Integrated residential-retail-office assets demand unified dashboards spanning disparate operational workflows. Developers in the United States prioritize these platforms for new construction financing and stabilized asset management.
- Residential Properties:Multifamily operators optimize rent pricing and resident retention through algorithmic lease renewal tools.
- Retail Spaces:Shopping center management modules incorporate percentage rent calculations and co-tenancy clause monitoring.
Commercial Estates dominate installed base today; Mixed-Use Developments are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software engineering talent clusters in metropolitan technology corridors anchor regional competitive positioning, with regulatory frameworks and institutional capital availability determining deployment velocity across national markets.
United States
Institutional asset managers in New York and Chicago drive demand for unified portfolio command structures spanning mixed-use developments. SEC disclosure requirements for REITs mandate granular lease lifecycle documentation, compressing procurement cycles for compliant vendors. Silicon Valley and Austin technology clusters supply cloud-native engineering talent to platform developers serving cross-asset operators.
Germany
Commercial property operators in Frankfurt and Munich prioritize predictive maintenance platforms integrating IoT sensor networks from HVAC and elevator systems. GDPR data residency mandates force vendors to establish localized server infrastructure with distinct encryption keys. Berlin's startup ecosystem produces specialized compliance modules for ESG disclosure under CSRD requirements.
United Kingdom
London-based family offices and real estate investment trusts demand fiduciary accounting modules with segregated fund tracking capabilities. The Information Commissioner's Office enforces strict data localization protocols for cross-border portfolio management. Manchester and Birmingham regional hubs concentrate mid-market property management software deployments for residential portfolio operators.
France
Medical office building operators in Paris and Lyon navigate overlapping CNIL oversight and HIPAA-adjacent privacy frameworks, creating qualification barriers for undercapitalized entrants. The country's national data protection authority mandates immutable audit trails for government housing authority deployments. Toulouse and Nice regional markets retain on-premises installations to satisfy multi-year amortization schedules at sovereign wealth funds.
Canada
Toronto and Vancouver institutional investors consolidate vendor relationships to achieve visibility across diversified holdings in residential, retail, and office assets. Health Canada and provincial privacy commissioners enforce data sovereignty requirements for pension fund auditors. Calgary's energy sector asset managers deploy hybrid architectures isolating sensitive financial data on-premises while pushing operational workflows to cloud edge nodes.
Estate Management Software Market Vendor Landscape
Top-tier vendors anchor the premium enterprise segment through deep module integration, while mid-market specialists compete on deployment speed and vertical customization. The vendor base stratifies across three functional tiers: full-suite platform providers, best-of-breed point solution developers, and API marketplace ecosystem orchestrators. Dominant competitive moves include strategic acquisitions to fill capability gaps and geographic expansion through localized cloud infrastructure partnerships.
Within the full-suite platform tier, Yardi Systems and RealPage exemplify contrasting scale strategies, with the former representing vertical integration archetypes and the latter embodying channel-controlled revenue management dominance. AppFolio occupies a position among cloud-native mid-market specialists targeting rapid-deployment segments. These three anchors illustrate how vendor archetypes map to buyer procurement criteria ranging from compliance depth to implementation velocity.
| Leading Market Players |
|---|
| Yardi Systems, Inc. |
| RealPage, Inc. |
| AppFolio, Inc. |
| MRI Software |
| Entrata, Inc. |
| Buildium |
| ResMan |
| CoStar Group |
| Propertyware |
| Others |
Supply Flow & Price Mechanics
Cloud-native engineering talent concentration in Silicon Valley and Austin creates labor-cost differentials that widen pricing-tier spreads between enterprise suites and mid-market deployments. GDPR-compliant infrastructure requirements in Europe add regional cost premiums that vendors pass through as localized server surcharges.
Pricing Analysis
Bundled platform subscriptions compete against unbundled point solutions across procurement cycles. Three-tier pricing structure across premium, standard, and economy levels separates Yardi Systems' enterprise depth from AppFolio's mid-market accessibility and Buildium's small-portfolio economy tier. Price differentiation rests on API integration depth and SOC 2 certification status. Cost compression in the mid-market tier intensifies as cloud-native entrants absorb margin from legacy on-premises vendors. Small property owners exhibit highest price sensitivity; institutional REITs prioritize compliance depth over license cost.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and United Kingdom anchor hub-and-spoke patterns for cloud infrastructure provisioning. Software development draws from Indian engineering hubs, Eastern European QA clusters, and domestic US product management. Raw material dependencies include hyperscaler compute capacity from AWS, Azure, and Google Cloud; IoT sensor hardware from Chinese manufacturers; and encryption modules from Israeli security firms. Single-source vulnerability concentrates in hyperscaler concentration for cloud-native deployments. Distribution runs through direct enterprise sales teams, value-added resellers, and API marketplace ecosystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Estate management software functions as a stable compounder, with recurring SaaS attach rates and regulatory compliance mandates creating durable revenue visibility across economic cycles.
For Market Incumbents: Anchor platform stickiness through deeper API marketplace ecosystems that externalize R&D burden to third-party developers. Fortify GDPR-compliant localized infrastructure in Frankfurt and London to defend against emerging European cloud-native entrants. Channel control with major REITs remains the critical defensive lever.
For New Entrants and Emerging Players: Regional system integrators represent the most viable path to market penetration. White-space concentrates in predictive maintenance modules for medical office buildings navigating HIPAA-adjacent frameworks. Target French and Canadian sovereign wealth funds retaining on-premises installations with hybrid architecture offerings. Go-to-market should emphasize rapid deployment velocity against legacy vendor implementation timelines.
For Investors and Strategic Acquirers: Private equity firms with real estate technology portfolios are the most active acquirer in this space, consolidating mid-market specialists into platform roll-ups. Long-term viability frames around 5-10 year regulatory compliance tailwinds and IoT sensor network expansion. Acquisition target archetype: cloud-native maintenance management specialists with proven API integration layers. Watch for inflection in REIT vendor consolidation announcements as signal of platform consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies lease administration with IoT predictive maintenance for mixed-use REIT portfolios. |
| Acquisition of Specialist Firm | Fills compliance module gaps for HIPAA-adjacent medical office building requirements. |
| Geographic Expansion | Establishes GDPR-compliant server infrastructure in Frankfurt to serve German institutional investors. |
| Strategic Partnership | Links with hyperscaler edge computing to reduce latency for real-time maintenance dispatch. |
| Product Launch | Introduces outcome-based maintenance contracts tied to HVAC uptime metrics rather than seat licenses. |
Methodological Framework
Bottom-up asset manager modeling reconciled against top-down vendor revenue tracking forms the analytical core of this study. Primary interviews with CTOs at institutional REITs, IT procurement officers at property management firms, platform engineers at cloud-native vendors, and integration specialists at regional system integrators supplied demand-side validation. Secondary sources include SEC filings from publicly traded REITs, GDPR compliance certification databases, hyperscaler capex disclosures, and IoT sensor deployment statistics from commercial real estate trade associations.
Historical trendline analysis of cloud migration patterns and subscription pricing trajectories informed projection frameworks. Segmentation dimensions span deployment model, organization size by unit count, vertical asset class, integration complexity tier, and regional regulatory cluster. CAGRs derive from fitted growth curves across the analysis window, with cross-validation against vendor booking data and end-user procurement cycle surveys. Forecast inputs incorporate GDPR enforcement intensity indices and IoT sensor cost decline curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to hyperscaler pricing volatility and regulatory timeline shifts. Outputs reflect documented assumptions around cloud adoption saturation levels and REIT consolidation velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Combat Management Systems Software Market
Software & Services
Commercial Drone Software Market
Software & Services
Global Data Integration and Integrity Software Market
Software & Services
Digital Onboarding Platform Market
Software & Services
Global Time and Attendance Management Software Market
Software & Services
Europe CMMS Software Market
Software & Services
App Building Software Market
Software & Services
Lead Scoring Software Market
Software & Services
Camera Tracking Software Market
Software & Services
Global Note Taking App Market
Software & Services
Intelligent Enterprise Data Capture Software Market
Software & Services
Subscription Management Software Market
Software & Services
Enterprise Capture Software Market
Software & Services
Pet Tracking Software Market
Software & Services
Global Mobile User Interface Services Market
Software & Services
Workstation Software Market