
 Managed Information Services Market | 2026-2036
Managed Information Services Market Size, Share, and Industry Trends Forecast 2026-2036
Managed Information Services Market Foresight
Mid-market enterprises is unwinding long-standing reliance on fully in-house IT departments as cloud-native alternatives mature. IBM Corporation leverages its Red Hat integration to anchor hybrid cloud infrastructure contracts across regulated industries. Tata Consultancy Services Limited sustains delivery scale through its India-centric global delivery network. Microsoft Corporation dominates enterprise productivity-to-platform bundling that locks in recurring managed service commitments.
Managed Information Services encompass the outsourced oversight, maintenance, and optimization of enterprise data, applications, network, and security infrastructure, typically governed by service-level agreements specifying uptime thresholds, response times, and data residency requirements. These services eliminate capital-intensive internal IT buildouts while ensuring continuous system availability and regulatory-compliant data handling. Cloud Services within the Service Type dimension captures the fastest-expanding margin pool as multi-tenant architectures reduce per-customer delivery costs. Hybrid Cloud deployment models concentrate investment from finance and healthcare verticals requiring partitioned workloads between compliant private nodes and scalable public resources.
FCC guidelines on telecommunications infrastructure reliability, HIPAA security rule enforcement for healthcare data handlers, and EU GDPR cross-border transfer mechanisms collectively elevate compliance costs for providers serving regulated verticals. The SEC's cybersecurity disclosure rules for publicly traded clients further tighten audit and incident-response obligations across the vendor chain. Stakeholders must weigh sovereign data localization mandates against the operational efficiency of centralized global delivery centers when structuring service architectures.
Market Dynamics
Healthcare providers migrating legacy infrastructure to hybrid cloud architectures are compressing procurement cycles and forcing vendors to embed compliance automation directly into service delivery stacks.
Growth Catalysts
- EU AI Act enforcement:Mandated algorithmic transparency requirements are creating captive demand for managed governance services among European financial institutions deploying machine learning models.
- Multi-tenant cloud architectures:Shared infrastructure platforms are collapsing per-customer delivery costs and unlocking margin expansion for providers serving mid-market healthcare and manufacturing segments.
- United States:SEC cybersecurity disclosure rules for publicly traded enterprises are extending audit and incident-response obligations down the entire vendor chain, institutionalizing recurring managed security contracts.
Market Restraints
- Specialized talent scarcity:Shortage of certified cloud security architects and compliance specialists is inflating wage costs and constraining delivery scale for providers.
- Input cost volatility:Proprietary security software licensing fees and hyperscaler compute pricing are compressing gross margins for fixed-fee managed service arrangements.
- Regulatory fragmentation:Conflicting data residency requirements across Germany, France, and United Kingdom jurisdictions are fragmenting service architectures and duplicating infrastructure investments.
Strategic Opportunities
- India:Underpenetrated mid-market manufacturing and pharmaceutical sectors present whitespace for standardized managed security and compliance packages.
- Edge-to-cloud convergence:Integration of distributed IoT endpoints with centralized cloud governance is creating new service tiers for industrial automation and logistics verticals.
- Outcome-based pricing models:Contracts tied to measurable uptime, threat mitigation, or compliance audit outcomes are displacing traditional seat-based or device-based billing in United States enterprise accounts.
Industry Challenges
- Legacy system integration:Decades-old mainframe and proprietary healthcare IT systems require custom middleware development, extending deployment timelines and inflating professional services costs.
- Certification pipeline delays:Backlogs in ISO 27001 and SOC 2 Type II audit scheduling are stretching vendor onboarding cycles and delaying revenue recognition for new contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Managed Information Services Market |
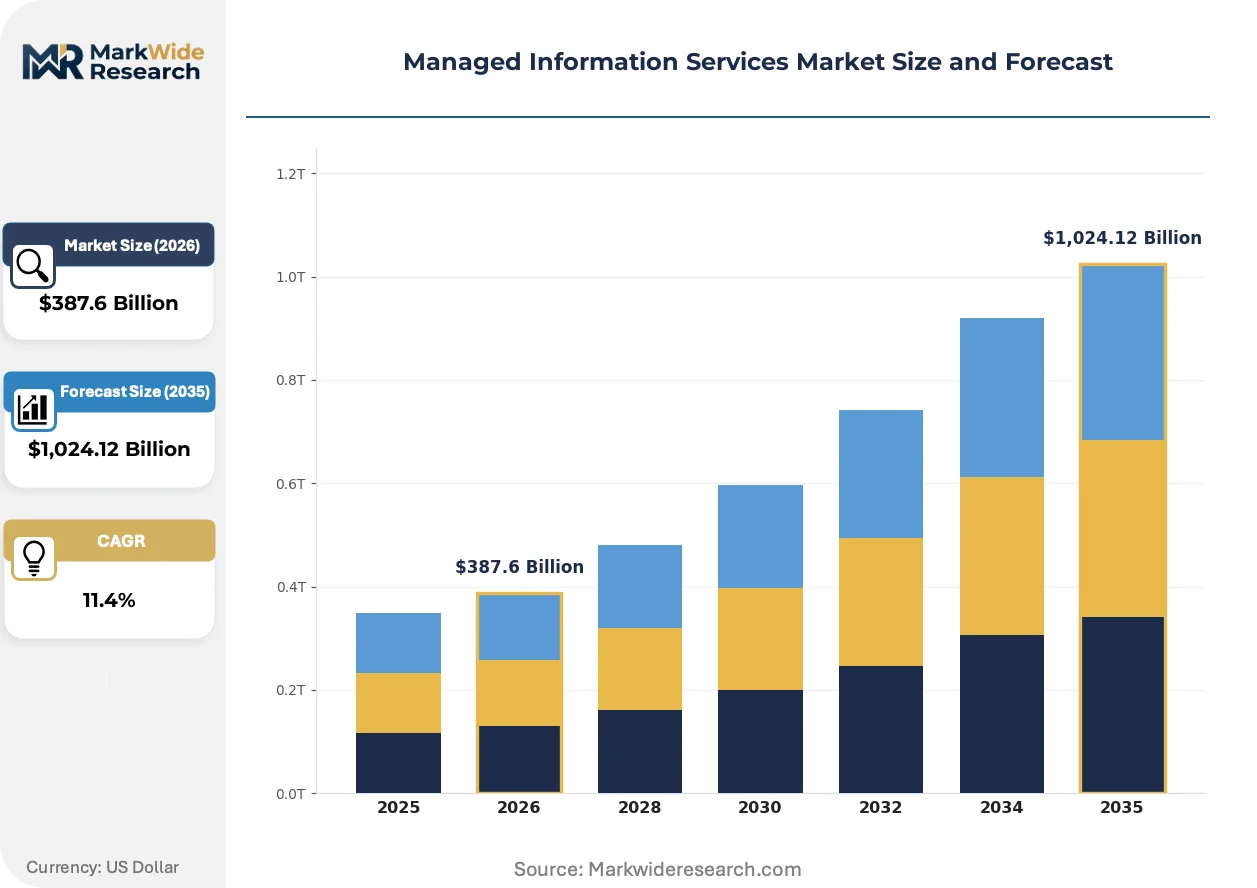
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,024.12 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Management, IT Support, Cloud Services, Security Management Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Industry Vertical: Healthcare, Finance, Education, Retail Customer Type: SMEs, Large Enterprises, Government Agencies, Non-Profits |
| Companies Covered | IBM Corporation, Accenture plc, Fujitsu Ltd, Cisco Systems Inc, Microsoft Corporation, Tata Consultancy Services Limited, Hewlett-Packard Enterprise, DXC Technology Company, AT&T Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Managed Information Services Market Shifts & Advancements
Service delivery architectures are fragmenting into modular, API-orchestrated components that enable rapid reconfiguration without wholesale platform replacement.
Containerized microservices is decomposing monolithic managed security platforms into discrete, interoperable functions. Healthcare providers in the United States are deploying these components incrementally to isolate patient data workflows from administrative systems. This modularization is compressing vendor lock-in and accelerating switching between best-of-breed providers.
EU NIS2 Directive implementation is mandating cross-border incident reporting and supply-chain security attestations for critical infrastructure operators. Managed service providers serving energy, transport, and digital infrastructure sectors must now embed continuous monitoring and 24-hour breach notification capabilities. German and French utilities are consolidating vendor relationships to reduce audit complexity.
Enterprise buying committees are unbundling security operations from broader infrastructure management contracts. Financial services buyers in the United Kingdom and United States are procuring managed detection and response as standalone services rather than bundled suites. This disaggregation is fragmenting incumbent provider relationships and creating entry points for specialized cybersecurity-native vendors.
Managed Information Services Market Segmentation
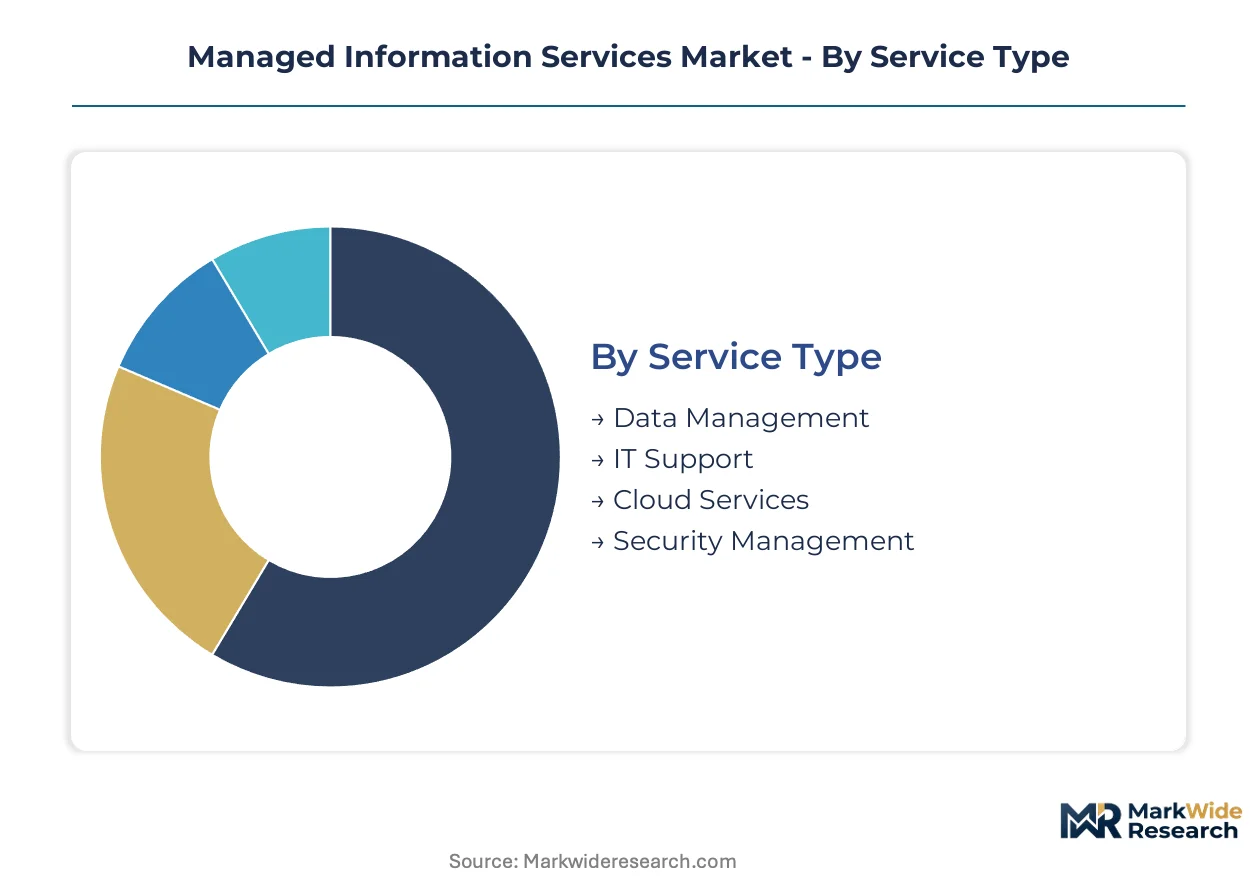
Segmentation in managed information services determines contract structure, margin profiles, and compliance obligations. Service type dictates delivery architecture, deployment model governs data residency requirements, and vertical specialization shapes regulatory exposure.
Service Type:
Channel mix varies sharply across service categories: Cloud Services and Security Management flow predominantly through direct enterprise sales with embedded professional services, while Data Management and IT Support retain higher indirect channel penetration via systems integrators and value-added resellers.
- Cloud Services:Multi-tenant infrastructure provisioning with automated orchestration layers and consumption-based metering. Demand concentrates among United States healthcare providers modernizing electronic health record systems under HIPAA security rule pressure. The EU AI Act is forcing European financial institutions toward managed governance wrappers around machine learning deployments.
- Security Management:Continuous threat monitoring, incident response orchestration, and compliance attestation services delivered through security operations centers. United States SEC cybersecurity disclosure rules are institutionalizing recurring contracts among publicly traded enterprises requiring vendor-chain audit coverage. Talent scarcity for certified cloud security architects is inflating delivery costs.
- Data Management:Lifecycle governance, quality assurance, and analytics enablement across structured and unstructured repositories.
- IT Support:Service desk operations, endpoint management, and legacy system maintenance typically bundled with broader infrastructure contracts.
By volume, IT Support leads through sheer contract ubiquity. By growth pace, Cloud Services is expanding most quickly.
Deployment Model:
Cost tier stratification separates these segments: Hybrid Cloud and Private Cloud command premium pricing for compliance-bound workloads, while Public Cloud and On-Premises compete on operational efficiency and capital avoidance respectively.
- Hybrid Cloud:Partitioned architectures linking compliant private nodes with scalable public resources via encrypted interconnects. Finance and healthcare verticals in the United States and Germany dominate procurement, driven by GDPR and HIPAA data residency requirements that prohibit pure public deployment. FCC guidelines on telecommunications infrastructure reliability further constrain architecture choices for carriers.
- Public Cloud:Shared hyperscaler infrastructure with standardized service level agreements and geographic redundancy. Mid-market manufacturing and pharmaceutical segments in India represent whitespace for standardized packages.
- Private Cloud:Single-tenant dedicated infrastructure with customizable security controls and guaranteed resource isolation.
- On-Premises:Legacy retained ownership models persisting in government agencies and regulated utilities with sovereign data mandates.
Hybrid Cloud captures the steepest expansion trajectory as compliance complexity rises. On-Premises retains the largest installed base by revenue.
Industry Vertical:
Application intensity differentiates these segments: Healthcare and Finance drive complexity through layered regulation, while Education and Retail prioritize cost efficiency and scalability.
- Healthcare:HIPAA security rule enforcement and FDA software validation requirements for clinical systems. United States providers are compressing procurement cycles and forcing vendors to embed compliance automation directly into delivery stacks. Legacy mainframe integration extends deployment timelines and inflates professional services costs.
- Finance:SEC cybersecurity disclosure rules, EU AI Act algorithmic transparency mandates, and NIS2 Directive cross-border incident reporting. United Kingdom and United States buyers are unbundling security operations from broader infrastructure contracts, fragmenting incumbent relationships.
- Education:Federated identity management and remote learning infrastructure with constrained capital budgets.
- Retail:Seasonal elasticity requirements and point-of-sale system integration with supply chain platforms.
Healthcare dominates contract value per seat. Finance is gaining share fastest through regulatory-driven security spending.
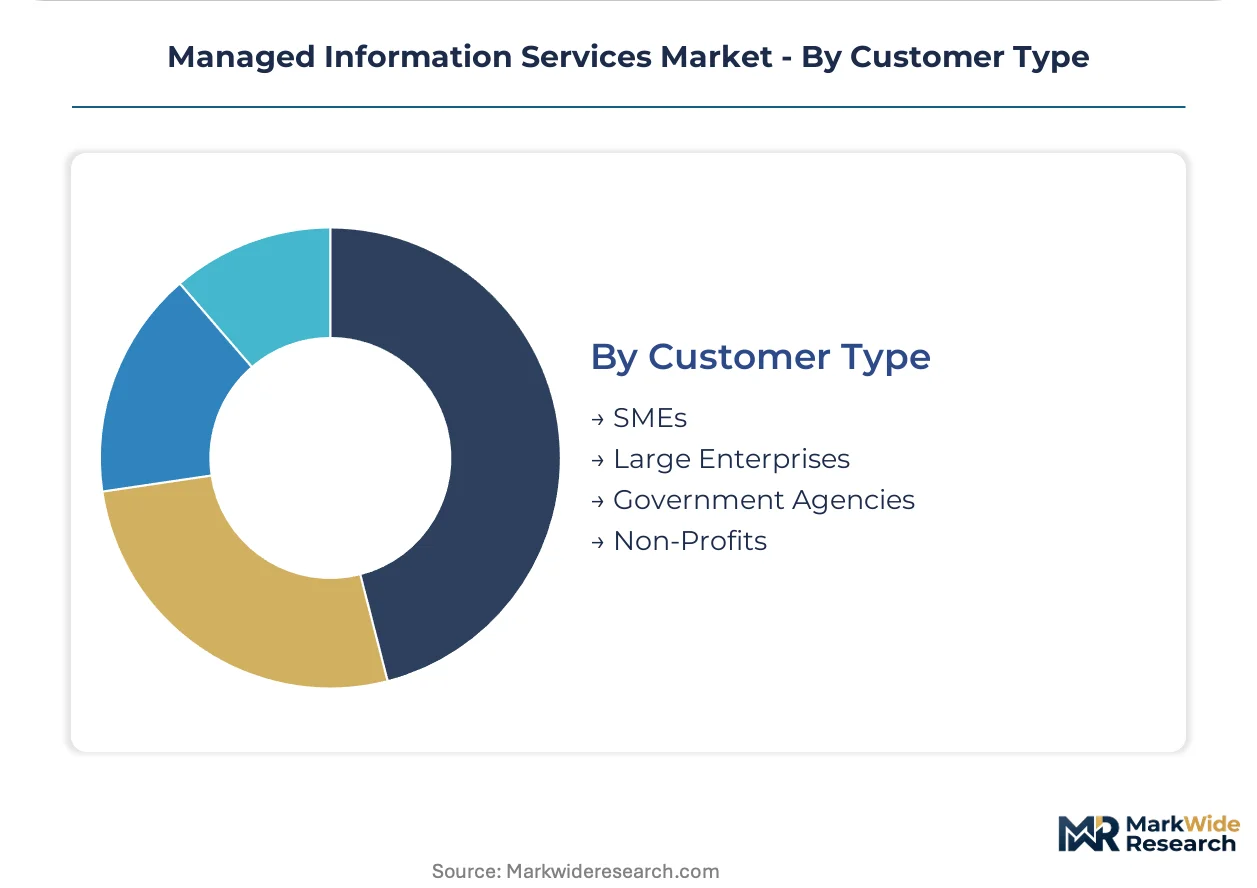
Customer Type:
Customer maturity separates these segments: Large Enterprises and Government Agencies demand outcome-based contracting with embedded compliance, while SMEs and Non-Profits prioritize standardized packages with predictable pricing.
- Large Enterprises:Complex multi-year agreements with service level agreements specifying uptime thresholds, response times, and data residency requirements. United States enterprises migrating legacy systems are driving hybrid cloud concentration. Procurement committees are displacing traditional seat-based billing with contracts tied to measurable uptime and threat mitigation outcomes.
- SMEs:Mid-market enterprises unwinding in-house IT departments as cloud-native alternatives mature. Standardized managed security and compliance packages present whitespace in underpenetrated Indian manufacturing and pharmaceutical sectors.
- Government Agencies:Sovereign data localization mandates and certification requirements constraining vendor selection.
- Non-Profits:Grant-funded technology refresh cycles with donor-imposed transparency and audit requirements.
Large Enterprises anchor aggregate revenue. SMEs are climbing the fastest as cloud delivery collapses per-customer costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian service providers export managed infrastructure capacity to United States healthcare and financial institutions, while German compliance specialists supply governance frameworks across EU member states. Cross-border data flows concentrate in these bilateral corridors.
United States
Large enterprises migrating legacy systems to hybrid cloud architectures are compressing procurement cycles. SEC cybersecurity disclosure rules extend audit obligations through vendor chains, institutionalizing recurring managed security contracts. Healthcare clusters in Boston and North Carolina force vendors to embed HIPAA compliance automation directly into delivery stacks.
Germany
Finance and healthcare verticals require partitioned workloads between compliant private nodes and scalable public resources. NIS2 Directive mandates cross-border incident reporting and supply-chain security attestations for critical infrastructure operators. Frankfurt and Munich utilities consolidate vendor relationships to reduce audit complexity under BSI oversight.
India
Mid-market manufacturing and pharmaceutical sectors present whitespace for standardized managed security packages. RBI guidelines on data localization and cyber resilience reshape contract structures for financial services outsourcing. Bengaluru and Hyderabad delivery centers sustain global scale through India-centric network architecture.
United Kingdom
Financial services buyers unbundle security operations from broader infrastructure contracts, fragmenting incumbent provider relationships. FCA operational resilience requirements tighten third-party risk management standards. London-based procurement committees displace seat-based billing with outcome-based contracts tied to measurable uptime.
France
EU AI Act enforcement creates captive demand for managed governance services among financial institutions deploying machine learning models. CNIL guidance on automated decision-making systems elevates algorithmic transparency obligations. Paris banking clusters consolidate vendor selections to streamline compliance attestation.
Managed Information Services Market Competitive Landscape
Listed leaders compete with private specialists across contract scale and compliance depth. The market structure concentrates around tier-one technology conglomerates with platform bundling power, mid-scale systems integrators with vertical expertise, and specialized security-native vendors with detection capabilities. Strategic moves center on hybrid cloud infrastructure anchoring and outcome-based pricing model displacement.
Within the platform-anchoring tier, IBM Corporation and Microsoft Corporation exemplify divergent bundling strategies, while Tata Consultancy Services Limited occupies a position as a scale-driven delivery specialist. These three entities represent the dominant competitive archetypes: infrastructure platform owners, productivity-to-service bundlers, and global delivery network operators. Their collective positioning shapes contract terms and margin pressure across mid-market and enterprise segments.
| Leading Market Players |
|---|
| IBM Corporation |
| Accenture plc |
| Fujitsu Ltd |
| Cisco Systems Inc |
| Microsoft Corporation |
| Tata Consultancy Services Limited |
| Hewlett-Packard Enterprise |
| DXC Technology Company |
| AT&T Inc |
| Others |
Supply & Pricing Matrix
Hyperscaler compute pricing replacing fixed infrastructure licensing as the primary cost anchor simultaneously concentrates supply geography around India-centric delivery networks and compresses margin structures for fixed-fee managed service arrangements.
Pricing Analysis
Legacy on-premises infrastructure maintenance commands premium pricing against collapsing public cloud consumption rates and emerging edge-to-cloud bundled tiers. Three-tier pricing structure across premium compliance-bound, standard multi-tenant, and economy self-service levels differentiates by certification depth and data residency guarantees. Pricing pressure stems from hyperscaler compute pricing volatility and proprietary security software licensing fees. Mid-market healthcare and manufacturing segments exhibit highest price sensitivity, while United States financial institutions under SEC cybersecurity disclosure obligations accept premium positioning for vendor-chain audit coverage.
Supply Chain Analysis
Inventory lead times for certified cloud security architects and ISO 27001 audit slots stretch vendor onboarding cycles and delay revenue recognition. Supply concentrates in India for global delivery scale, the United States for healthcare and financial services domain expertise, and Germany for EU NIS2 Directive compliance frameworks. The talent pipeline draws from computer science graduates, legacy mainframe specialists transitioning to cloud architectures, and compliance-certified project managers. Single-source vulnerability in India-centric delivery networks creates concentration risk. Distribution runs through direct enterprise sales with embedded professional services for cloud and security segments, and systems integrator channels for data management and IT support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed information services have reached a platform-economics inflection where Red Hat OpenShift and Azure Arc ecosystems are displacing standalone infrastructure contracts through interoperability mandates.
For Market Incumbents: Shield recurring revenue streams by embedding compliance automation into hybrid cloud delivery stacks before specialized security-native vendors capture governance wrappers. Anchor contracts through outcome-based pricing tied to measurable uptime and threat mitigation metrics. Prioritize certification investment in ISO 27001 and SOC 2 Type II to compress audit scheduling backlogs that delay competitor onboarding.
For New Entrants and Emerging Players: Differentiate on modular API-orchestrated components that enable rapid reconfiguration without wholesale platform replacement. Target India's underpenetrated mid-market manufacturing and pharmaceutical sectors with standardized managed security packages. Pursue edge-to-cloud convergence service tiers for industrial automation verticals as the most penetrable whitespace.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors compliance-specialist acquisitions over scale-driven generalists. Long-term viability hinges on regulatory complexity deepening rather than simplifying across EU AI Act and NIS2 Directive enforcement. Watch German and French utility vendor consolidation patterns as the signal for critical infrastructure operator buying behavior inflection.
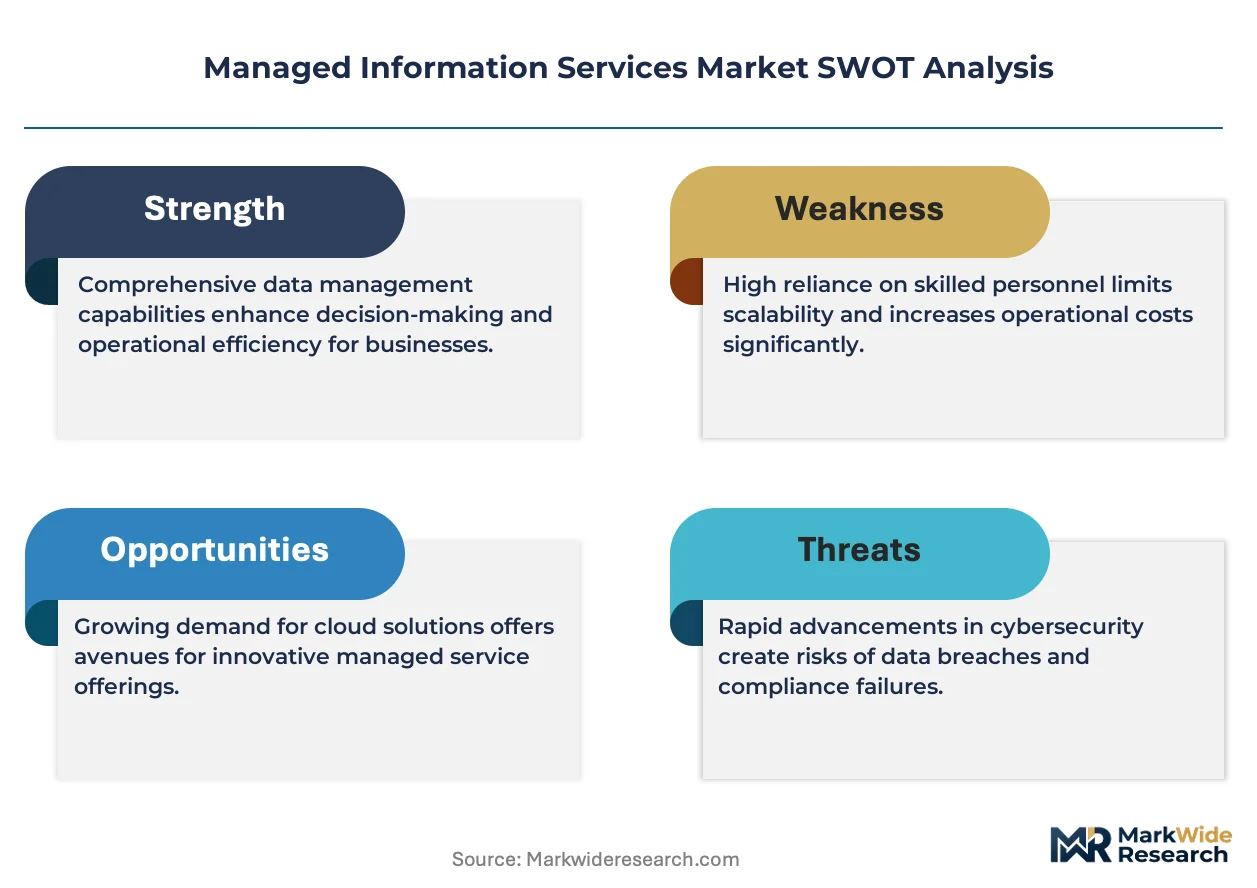
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Cloud Infrastructure Anchoring | IBM Corporation leverages Red Hat integration to lock regulated industries into multi-year platform contracts. |
| Compliance Automation Embedding | United States healthcare providers force HIPAA security rule automation directly into service delivery stacks. |
| Outcome-Based Pricing Displacement | London and New York financial services procurement committees abandon seat-based billing for uptime-guaranteed contracts. |
| Modular Microservices Decomposition | Containerized security functions accelerate switching between best-of-breed providers and fragment incumbent relationships. |
| India-Centric Delivery Scale | Tata Consultancy Services sustains global capacity through Bengaluru and Hyderabad network architecture concentration. |
Research Methodology
Cross-validation between primary interviews with CIOs, CISOs, cloud procurement officers, and compliance directors and secondary validation through SEC cybersecurity disclosure filings, EU AI Act implementation guidance, and hyperscaler capex disclosures anchors the qualitative findings. Bottom-up contract analysis triangulates against top-down market sizing across service type, deployment model, industry vertical, and customer type segmentation dimensions.
Sensitivity analysis around regulatory enforcement timing and hyperscaler pricing volatility shapes the analytical framework across the projection horizon. Modeled segmentation spans cloud services, security management, data management, and IT support by service type; hybrid, public, private, and on-premises by deployment model; healthcare, finance, education, and retail by vertical; and large enterprise, SME, government, and non-profit by customer type. CAGRs derive from penetration rate trajectories in underpenetrated Indian mid-markets and compliance-driven replacement cycles in United States and EU regulated verticals.
The analysis sits within stated boundaries; outcomes outside sustained EU AI Act enforcement intensity or abrupt hyperscaler pricing recalibration would require recalibration. Forecasts reflect documented assumptions around talent pipeline expansion and certification audit capacity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Low Code Development Platform Market
Software & Services
Global Software Quality Assurance Market
Software & Services
Global Employee Recognition Software Market
Software & Services
Global Driving School Software Market
Software & Services
Global Meeting Room Booking System Software Market
Software & Services
Global Kiosk Software Market
Software & Services
Global SAP S-4HANA Application Market
Software & Services
3D Modeling Software Market
Software & Services
Remote Sensing Software Market
Software & Services
Global Mobile Application Testing Solution Market
Software & Services
US Enterprise Legal Management Software Market
Software & Services
Global API Management Software Market
Software & Services
Middleware Market
Software & Services
Global OEE Software Market
Software & Services
Push Notifications Software Market
Software & Services
Telecom Billing Software Market