
 Consignment Software Market | 2026-2036
Consignment Software Market Size, Share, and Industry Trends Forecast 2026-2036
Consignment Software Market Outlook
API-first architecture is pivoting legacy consignment software economics away from monolithic on-premises installations toward modular cloud stacks. Shopify leverages its commerce ecosystem to anchor consignment workflows within broader retail operations. ConsignCloud specializes in resale-specific inventory tracking, while Lightspeed Retail competes through point-of-sale integration that extends into consignment commission calculations.
Consignment software comprises inventory management, commission tracking, vendor settlement, and resale analytics modules delivered through web or mobile interfaces, typically integrating with payment processors and accounting systems via REST APIs. Cloud-Based deployment leads current uptake among small and mid-sized resale operators seeking lower upfront infrastructure costs. Mobile App functionality represents the fastest-expanding segment as curbside consignment and pop-up resale events proliferate. On-Premises solutions retain margin concentration among enterprise thrift chains with strict data sovereignty requirements.
The Federal Trade Commission guides consignment advertising and commission disclosure practices in the United States, while the EU General Data Protection Regulation imposes cross-border data handling standards on vendors serving European resale marketplaces. State-level biometric privacy laws in Illinois and Texas are reshaping identity verification features for consignor onboarding. Stakeholders must monitor how fragmented privacy compliance costs redistribute competitive advantage between integrated platforms and point solutions.
Market Dynamics
API-first architecture is dismantling monolithic on-premise installations across consignment operations, forcing vendors to modularize core inventory and commission engines or lose integration contracts with multi-location resale chains.
Growth Catalysts
- Biometric Privacy Mandates:Illinois BIPA and Texas CUBI are compelling consignment platforms to embed compliant identity verification for consignor onboarding, creating upgrade cycles among legacy operators.
- Curbside Consignment Proliferation:Mobile-first inventory intake workflows are accelerating among pop-up resale events and temporary retail activations in urban California clusters.
- GDPR Cross-Border Enforcement:European resale marketplaces are demanding data residency guarantees from software vendors, pulling cloud architecture investments toward EU sovereign hosting.
Market Restraints
- Payment Processor Concentration:Dependency on Stripe and Square for commission settlement creates single-point-of-failure risk for mid-sized consignment operators.
- Biometric Compliance Cost Burden:Illinois BIPA private right of action exposes software vendors to statutory damages per violation, elevating liability insurance premiums.
- Legacy System Entrenchment:Enterprise thrift chains with 15+ year on-premise deployments face prohibitive data migration costs to cloud-native stacks.
Strategic Opportunities
- AI-Powered Pricing Engines:Machine learning models analyzing historical resale velocity are converging with automated commission adjustment tools for high-value consignment categories.
- Texas Multi-Location Expansion:Austin and Dallas-Fort Worth resale chains remain underpenetrated by specialized consignment software relative to California saturation.
- CSRD Reporting Integration:EU corporate sustainability disclosure requirements are creating demand for carbon-tracking modules within consignment inventory systems.
Industry Challenges
- API Talent Scarcity:Consignment software vendors struggle to hire engineers with both retail payment integration experience and GDPR compliance expertise.
- Legacy Database Migration Complexity:Decades of consignor transaction history in proprietary on-premise formats resist clean extraction to cloud SQL architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consignment Software Market |
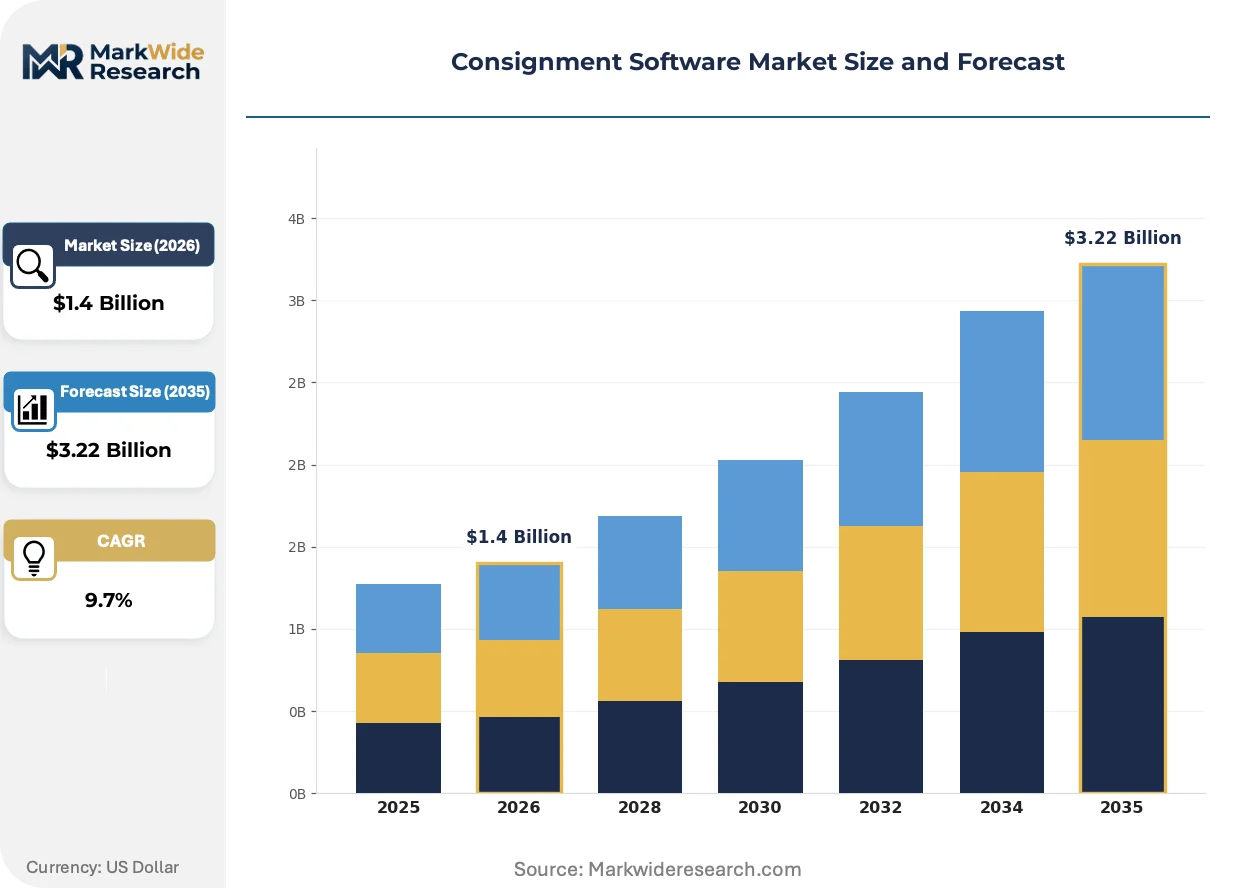
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.22 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Mobile App, Hybrid Solution End User: Retail Stores, Wholesalers, Online Marketplaces, Freight Forwarders Deployment Model: Public Cloud, Private Cloud, Community Cloud, Hybrid Cloud Service Type: Software Development, Consulting, Maintenance, Support Services |
| Companies Covered | Aravenda Consignment Software, ConsignR, Ricochet POS, Epos Now, Shopify, ConsignCloud, Lightspeed Retail, Liberty REACT, SimpleConsign, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consignment Software Market Strategic Shifts
Mobile-native inventory intake is compressing deployment timelines for consignment operators while regulatory pressure on data handling is forcing architectural redesigns across vendor roadmaps.
Headless commerce APIs are overtaking traditional point-of-sale integrations as the dominant connection layer between consignment software and retail operations. Resale boutiques in California and Texas are adopting these modular interfaces within six-month procurement cycles. This shift is compressing vendor switching costs and enabling best-of-breed stacking across payment, accounting, and inventory modules.
GDPR Article 44 transfer mechanism enforcement is requiring consignment software vendors serving EU resale marketplaces to implement Standard Contractual Clauses with audit rights. Vendors without EU-based data processing infrastructure face procurement disqualification from Dutch and German consignment chains. The regulatory friction is accelerating consolidation toward platforms with pre-built EU sovereign hosting.
Consignor settlement expectations are compressing payment cycles from monthly to bi-weekly or on-demand disbursement. Multi-location thrift chains in Texas are unbundling commission calculations from batch processing to real-time APIs. This behavioral shift is most visible among Gen Z-targeted resale boutiques where cash-flow transparency functions as a competitive recruitment tool for high-volume consignors.
Consignment Software Market Segmentation
Segmentation in consignment software reveals how deployment economics, end-user workflows, and service delivery models create divergent vendor strategies. Understanding these splits helps identify where modular API architectures displace legacy installations versus where on-premise entrenchment persists.
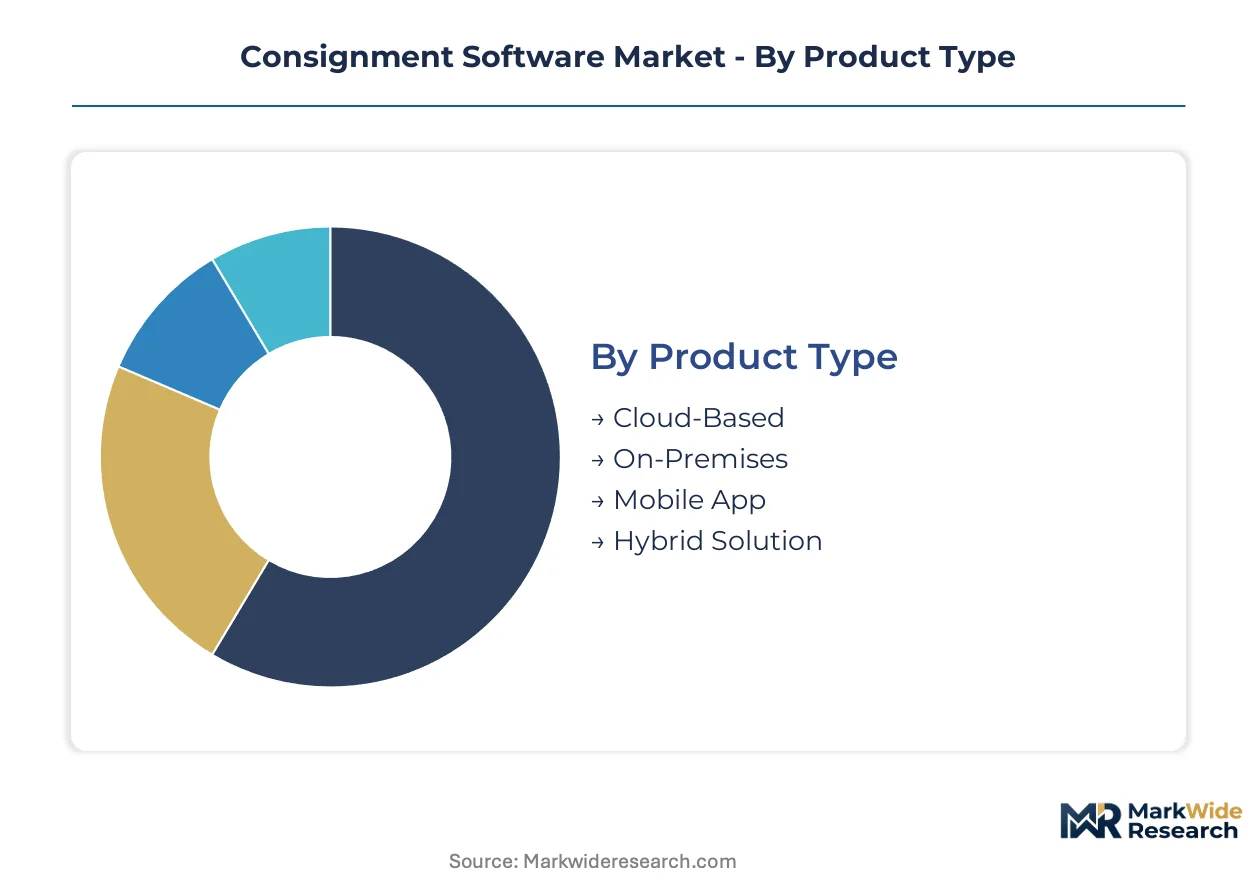
Product Type:
Volume deployment concentrates in subscription-based cloud offerings, while premium functionality commands higher per-seat pricing in specialized mobile and hybrid configurations.
- Cloud-Based:Multi-tenant SaaS architectures with REST API connectivity to payment processors and accounting systems. Demand clusters among Texas and California multi-location thrift chains seeking centralized inventory visibility across distributed storefronts. GDPR compliance features are becoming table stakes for vendors serving EU-connected consignors.
- Mobile App:Native iOS and Android interfaces enabling curbside intake, photo-based condition logging, and real-time consignor notifications. California pop-up resale events and urban curbside operations in Los Angeles and San Francisco are driving procurement cycles here. Biometric privacy compliance for consignor identity verification adds development overhead.
- On-Premises:Single-tenant installations on client-owned servers with full data sovereignty. Enterprise thrift chains with 15+ year legacy deployments and strict internal audit requirements maintain this stack despite migration friction.
- Hybrid Solution:Split architectures retaining sensitive commission data on-premise while pushing customer-facing inventory to cloud edge nodes. Mid-sized resale boutiques in regulated states use this to balance compliance with mobile accessibility.
Mature deployment sits with On-Premises. Newer deployment is concentrated in Mobile App.
End User:
Application intensity varies sharply—physical retail demands POS integration depth, while online marketplaces prioritize API throughput for multi-channel listing synchronization.
- Retail Stores:Brick-and-mortar consignment and thrift operations requiring barcode scanning, physical inventory counts, and in-person consignor settlement workflows. Texas multi-location chains represent concentrated procurement activity.
- Online Marketplaces:Digital-first resale platforms integrating with Shopify, eBay, and Poshmark via headless commerce APIs. These users demand real-time inventory synchronization across distributed sales channels.
- Wholesalers:Bulk consignment aggregators moving inventory between secondary markets. Commission calculations here emphasize volume-tiered pricing rather than individual item tracking.
- Freight Forwarders:Logistics intermediaries requiring consignment status visibility for cross-border resale shipments. GDPR Article 44 transfer compliance is reshaping vendor selection criteria for EU-connected freight operators.
Procurement volume clusters with Retail Stores. Technical sophistication requirements peak with Online Marketplaces.
Deployment Model:
Cost tiering follows infrastructure control—public cloud minimizes capital outlay while private and community variants extract premiums for data residency guarantees.
- Public Cloud:Shared infrastructure with vendor-managed security patches and automatic feature updates. Small resale operators in California and Texas dominate this segment due to minimal upfront investment requirements.
- Private Cloud:Dedicated single-tenant environments with custom security configurations. EU resale marketplaces in Germany and the Netherlands are mandating this model to satisfy GDPR data residency requirements.
- Community Cloud:Shared infrastructure among consignment operators with similar compliance profiles. Illinois BIPA-covered entities are exploring this model to distribute biometric compliance audit costs.
- Hybrid Cloud:Workload-splitting between public edge nodes and private core databases. Multi-state operators use this to keep commission records in-state while enabling mobile inventory access.
Adoption velocity is steepest in Public Cloud. Compliance-driven procurement is concentrating in Private Cloud.
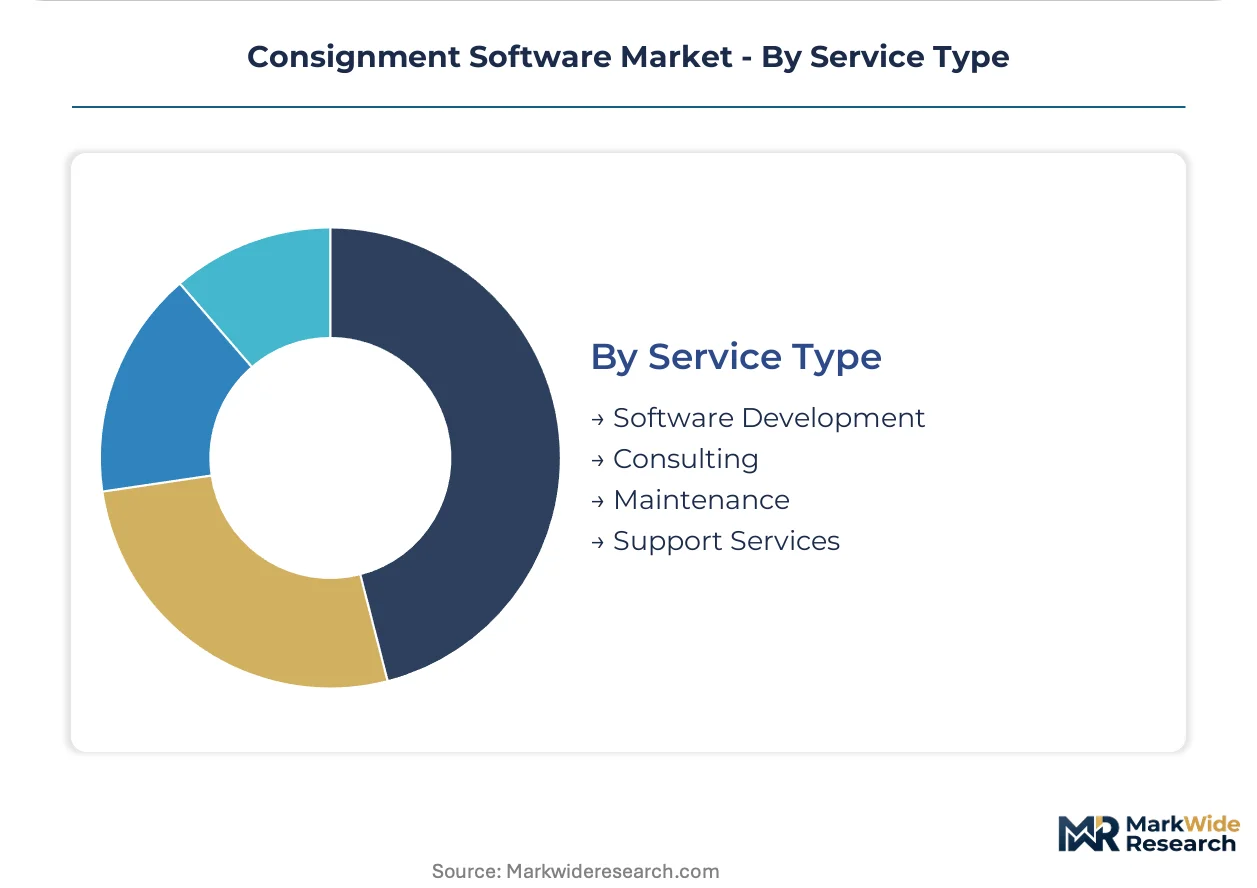
Service Type:
Margin concentration shifts upstream—custom development and consulting command premium pricing, while support services face commoditization pressure from self-service documentation and community forums.
- Software Development:Custom module creation for specialized consignment categories—art, luxury goods, automotive—with non-standard commission structures. High-value consignors in California luxury resale drive bespoke development contracts.
- Consulting:Workflow optimization, data migration planning, and compliance architecture design. Illinois BIPA and Texas CUBI implementation projects are expanding this service line.
- Maintenance:Scheduled updates, security patching, and performance monitoring. Cloud-native vendors bundle this into subscription pricing, compressing standalone maintenance markets.
- Support Services:Help desk access, training delivery, and troubleshooting documentation. Tiered SLAs differentiate premium from standard offerings based on response time guarantees.
Revenue per engagement peaks with Software Development. Volume concentration sits with Support Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for consignment software concentrates in the United States, where multi-location thrift chains and resale boutiques drive procurement cycles. Texas and California anchor this concentration through distinct regulatory and operational environments.
United States
Texas multi-location resale chains and California urban boutiques generate concentrated procurement activity for cloud-based inventory tools. The Federal Trade Commission guides consignment advertising and commission disclosure practices nationwide. Austin and Dallas-Fort Worth operators are accelerating mobile-first intake workflows for curbside consignment events.
Germany
Dutch and German consignment chains are mandating EU sovereign hosting for data residency compliance. GDPR Article 44 transfer mechanisms require Standard Contractual Clauses with audit rights from software vendors. Berlin and Hamburg resale marketplaces are disqualifying vendors without EU-based data processing infrastructure from procurement cycles.
United Kingdom
London-based resale platforms prioritize headless commerce API integrations for multi-channel inventory synchronization. The UK Information Commissioner's Office enforces GDPR-aligned data handling standards for cross-border consignor transactions. Southeast England boutique operators are compressing vendor switching costs through modular best-of-breed stacking.
Canada
Toronto and Vancouver consignment operators seek centralized inventory visibility across distributed storefronts. Health Canada and provincial privacy commissioners impose data handling standards on resale software serving cross-border consignors. Ontario multi-location thrift chains are exploring hybrid cloud deployments to balance compliance with mobile accessibility.
France
Paris luxury resale boutiques drive bespoke software development for non-standard commission structures in high-value consignment categories. The CNIL enforces biometric data handling restrictions that reshape identity verification features for consignor onboarding. Île-de-France operators are demanding real-time commission calculations unbundled from batch processing.
Consignment Software Market Competitive Environment
API-first modularization dominates the current landscape as vendors dismantle monolithic architectures to retain integration contracts with multi-location chains. The vendor base clusters around three strategic archetypes: commerce ecosystem anchors, resale-specialized point solutions, and legacy point-of-sale extenders. Consolidation pressure favors platforms with pre-built GDPR compliance and EU sovereign hosting capabilities. M&A activity and strategic API partnership formation represent the dominant competitive vectors reshaping vendor positioning.
Within the commerce ecosystem tier, Shopify anchors broader retail operations that subsume consignment workflows. ConsignCloud and Lightspeed Retail occupy distinct specialization positions—ConsignCloud exemplifies resale-native inventory tracking architecture, while Lightspeed Retail represents POS-integrated commission calculation extension. These three companies illustrate how vendor selection increasingly hinges on pre-existing retail technology commitments rather than standalone consignment functionality.
| Leading Market Players |
|---|
| Aravenda Consignment Software |
| ConsignR |
| Ricochet POS |
| Epos Now |
| Shopify |
| ConsignCloud |
| Lightspeed Retail |
| Liberty REACT |
| SimpleConsign |
| Others |
Value Chain & Pricing Dynamics
API-first modularization is compressing development costs for cloud-native consignment vendors while concentrating supply-side talent in California and Texas engineering clusters. This architectural shift simultaneously erodes legacy on-premise pricing premiums and redistributes margin capture toward integration specialists with pre-built GDPR compliance.
Pricing Analysis
Volume deployment concentrates in subscription-based SaaS tiers while premium functionality commands per-seat premiums in specialized mobile configurations. Three-tier pricing structure across premium, standard, and economy levels differentiates by compliance certification depth and API throughput capacity. Pricing pressure stems from open-source inventory frameworks lowering entry barriers for mid-market resale operators. Small California pop-up boutiques exhibit highest price sensitivity, while enterprise thrift chains with 15+ year data histories accept premium migration consulting fees.
Supply Chain Analysis
Workforce availability for API engineering with retail payment integration expertise concentrates in Austin, San Francisco, and Berlin metropolitan clusters. Cloud infrastructure provisioning draws from AWS, Google Cloud, and Microsoft Azure data centers, with EU sovereign hosting increasingly mandatory for Dutch and German marketplace connectivity. Single-source vulnerability sits with Stripe and Square dominance in commission settlement rails. Distribution runs through direct vendor sales teams for enterprise accounts and self-service onboarding portals for sub-50-seat operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The consignment software market functions as a cost-of-compliance story where Illinois BIPA and Texas CUBI biometric mandates erect barrier-to-entry moats favoring vendors with pre-built legal engineering.
For Market Incumbents: Extend API modularization roadmaps to capture integration contracts from multi-location Texas chains before cloud-native entrants achieve feature parity. Consolidate around EU sovereign hosting capabilities as GDPR Article 44 enforcement disqualifies vendors without Standard Contractual Clause infrastructure. Biometric compliance cost burden represents the primary margin defense lever against point-solution competitors. For New Entrants and Emerging Players: Headless commerce API specialization offers a technology-first wedge into California resale boutiques already running Shopify stacks. Target Austin and Dallas-Fort Worth multi-location chains where specialized consignment penetration lags California saturation. Go-to-market execution should lead with real-time commission calculation APIs that unbundle from legacy batch processing workflows. For Investors and Strategic Acquirers: Re-rating potential sits with platforms combining pre-built GDPR compliance and EU sovereign hosting capabilities given cross-border enforcement acceleration. Long-term viability favors vendors with architectural optionality across cloud, hybrid, and on-premise deployment modes. Watch Illinois BIPA private right of action litigation volume as inflection indicator for compliance cost redistribution toward integrated platforms.| Strategic Initiative | Industry Significance |
|---|---|
| EU Sovereign Hosting Buildout | GDPR Article 44 enforcement disqualifies vendors lacking Standard Contractual Clause infrastructure from Dutch and German procurement cycles. |
| Biometric Compliance Module Development | Illinois BIPA and Texas CUBI mandates create upgrade revenue streams among legacy operators facing statutory damage exposure. |
| Headless Commerce API Integration | Modular connection layers compress vendor switching costs for California resale boutiques running Shopify operations. |
| AI-Powered Pricing Engine Launch | Machine learning models analyzing resale velocity converge with automated commission tools for high-value consignment categories. |
| Strategic Partnership with Payment Processors | Stripe and Square dependency concentration creates co-development opportunities for real-time settlement infrastructure. |
Study Parameters
Multi-period observation of API adoption rates, biometric compliance implementation timelines, and cloud migration patterns anchored the trend analysis, supplemented by interviews with resale software CTOs, thrift chain operations directors, consignor settlement specialists, and EU data protection officers. Secondary validation incorporated SEC filings from publicly traded retail technology vendors, hyperscaler capex disclosures, Illinois BIPA litigation dockets, and GDPR enforcement actions from European data protection authorities. Bottom-up segment sizing triangulated against top-down market aggregation across deployment models and end-user categories.
Segment-weighting approaches distributed value estimates across cloud-based, mobile app, on-premise, and hybrid product types, further disaggregated by retail store, online marketplace, wholesaler, and freight forwarder end users. CAGRs were derived from fitted growth curves incorporating vendor pricing disclosures, procurement cycle interviews, and technology adoption S-curve analysis. Forecast inputs included API talent availability indices, biometric regulatory expansion trajectories, and headless commerce penetration rates in California and Texas resale clusters.
Several conditions sit outside the modeled scope, including unforeseen FTC advertising guideline revisions, abrupt payment processor policy changes, and biometric privacy law preemption by federal legislation. Forecasts reflect assumptions about continued GDPR enforcement intensity and cloud infrastructure cost trajectories. Material deviation in Illinois BIPA litigation volume, EU data residency mandate timing, or Stripe API pricing structure warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Continuous Testing Market
Software & Services
Software Containers Market
Software & Services
Airline Route Profitability Software Market
Software & Services
Digital Onboarding Platform Market
Software & Services
Global Policy Management Software Market
Software & Services
Global Idea Management Software Market
Software & Services
Indonesia Big Data Analytics Software Market
Software & Services
Audio Editing Software Market
Software & Services
Account-Based Data Software Market
Software & Services
Global Managed Application Services Market
Software & Services
Observability Platform Market
Software & Services
Global Appointment Reminder Software Market
Software & Services
Enterprise Resource Planning Market
Software & Services
Business Email Market
Software & Services
Account-Based Direct Mail Software Market
Software & Services
Global Mobile Application Testing Solution Market