
 Global Gym Software Market | 2026-2036
Global Gym Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gym Software Market Foresight
Direct-to-gym SaaS distribution is reconfiguring how vendors reach independent fitness operators. Virtuagym leverages its European headquarters to sustain strong channel partnerships with boutique studios across Germany and the Netherlands. ABC Fitness Solutions, LLC anchors its position through deep integration with legacy club management systems, while MINDBODY, Inc. competes aggressively in the wellness retreat and yoga studio verticals where brand recognition drives purchasing decisions.
Gym software encompasses cloud-based and on-premise platforms that automate membership lifecycle management, payment processing, class scheduling, and biometric performance tracking through API-connected wearable devices and access control hardware. Its primary commercial purpose centers on reducing administrative overhead while increasing member retention through personalized engagement workflows. Cloud-based deployment leads absolute revenue contribution as franchise operators prioritize remote accessibility and automatic security patching over capital-intensive server installations. Performance tracking modules represent the fastest-expanding solution category, driven by trainer demand for VO2 max integration and recovery metrics that justify premium personal training rates.
FDA oversight applies indirectly where gym software interfaces with medical-grade body composition analyzers or cardiac monitoring equipment, while GDPR and the EU AI Act impose strict boundaries on automated member profiling and predictive churn algorithms in European jurisdictions. The California Consumer Privacy Act creates additional compliance layers for US vendors serving California-based chains. Stakeholders must monitor evolving biometric data classifications, as regulators in multiple countries reassess whether fitness-derived health metrics warrant enhanced protection beyond standard commercial data rules.
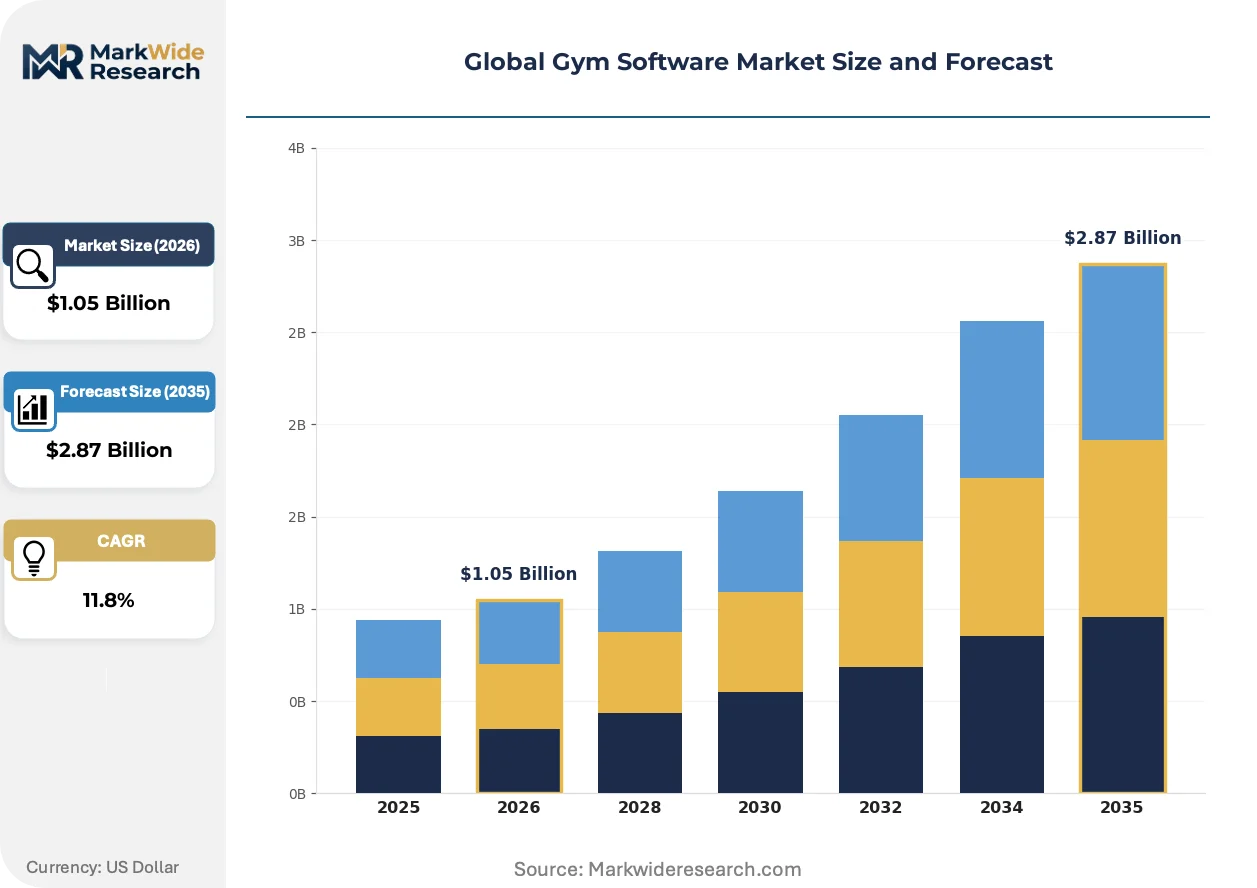
Market Dynamics
Franchise operators are consolidating vendor relationships around unified platforms that collapse billing, scheduling, and performance analytics into single-dashboard environments, compressing procurement cycles and elevating switching costs for incumbent providers.
Growth Catalysts
- GDPR and EU AI Act compliance mandates:European gym chains face binding requirements for automated member profiling and biometric data governance, forcing upgrades to auditable cloud infrastructure and creating replacement demand for legacy on-premise systems.
- API-connected wearable ecosystems:Trainer demand for VO2 max and recovery metric integration is pulling software vendors into deeper hardware partnerships, expanding addressable revenue per member through premium personal training tier justification.
- Multi-location franchise standardization:United States-based operators with 10+ clubs are mandating centralized data lakes across states, eliminating patchwork local solutions and concentrating purchasing authority with corporate procurement teams.
Market Restraints
- California Consumer Privacy Act layering:Vendors serving California-based chains must architect dual compliance frameworks alongside federal standards, inflating development overhead and delaying feature rollouts for national product roadmaps.
- Cloud infrastructure concentration:Dependence on hyperscale providers for automatic security patching creates single-point vulnerability for franchise operators requiring 99.99% uptime guarantees during peak January enrollment periods.
- Biometric data reclassification risk:Regulators in multiple jurisdictions are reassessing whether fitness-derived health metrics warrant medical-grade protection, threatening retroactive compliance obligations for historical member datasets.
Strategic Opportunities
- Underpenetrated German boutique studio segment:Independent Pilates and barre operators in Berlin and Munich remain on spreadsheet-based management, presenting first-mover SaaS conversion potential for vendors with localized payment gateway integrations.
- Wellness retreat vertical expansion:Yoga and meditation centers with multi-day programming requirements represent adjacent demand for scheduling modules with accommodation and meal-planning extensions beyond standard gym workflows.
- India PLI scheme for software exports:Domestic vendors capturing incentives for registered IT exports can price aggressively into Southeast Asian franchise markets while maintaining margin structures unavailable to US and European competitors.
Industry Challenges
- Legacy club management system integration:Decades-old member databases with non-standard schema require expensive middleware development, consuming engineering resources that could otherwise advance AI-driven churn prediction capabilities.
- Biometric hardware certification timelines:FDA-adjacent oversight for medical-grade body composition analyzers extends vendor qualification periods by 12-18 months, delaying revenue recognition for integrated platform deals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gym Software Market |
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.87 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS Solution Offering: Membership Management, Billing & Payments, Scheduling, Performance Tracking, Marketing Automation Application: Fitness Centers, Personal Training, Yoga Studios, Martial Arts Schools, Dance Centers End User: Gym Owners, Fitness Trainers, Wellness Coaches, Franchise Operators |
| Companies Covered | Virtuagym, Wodify Technologies, LLC, ABC Fitness Solutions, LLC, Exercise.com, Inc., Zen Planner, LLC, MINDBODY, Inc., Xplor Technologies, PushPress, LLC, Daxko, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gym Software Market Shifts & Advancements
Software architectures are fragmenting between all-in-one suites and specialized best-of-breed stacks, with buyer preferences oscillating based on franchise scale and in-house technical capacity. This tension is accelerating API standardization efforts and reshaping vendor competitive moats.
Edge computing nodes embedded within club access control hardware are hybridizing traditional cloud-dependent architectures. Boutique fitness operators in the Netherlands are deploying these systems to process biometric entry locally, reducing latency for member check-ins while maintaining centralized oversight. This architecture is hybridizing vendor cost structures, compressing pure-SaaS margins while enabling premium pricing for hybrid deployment models.
The EU AI Act's risk classification framework for automated decision-making systems is compelling European vendors to reengineer member retention algorithms. Systems scoring above "limited risk" thresholds now require human-in-the-loop overrides and audit trail documentation, extending development cycles. German and French operators are responding by demanding contractual indemnification from software providers against regulatory penalties.
Corporate wellness procurement teams are consolidating vendor relationships under master service agreements that bundle gym software with broader employee benefit platforms. This behavior is disintermediating direct-to-gym sales channels and elevating the importance of HRIS integration capabilities. The United States exhibits the most pronounced concentration, with Fortune 500 benefits administrators driving standardization across regional club networks.
Global Gym Software Market Segmentation
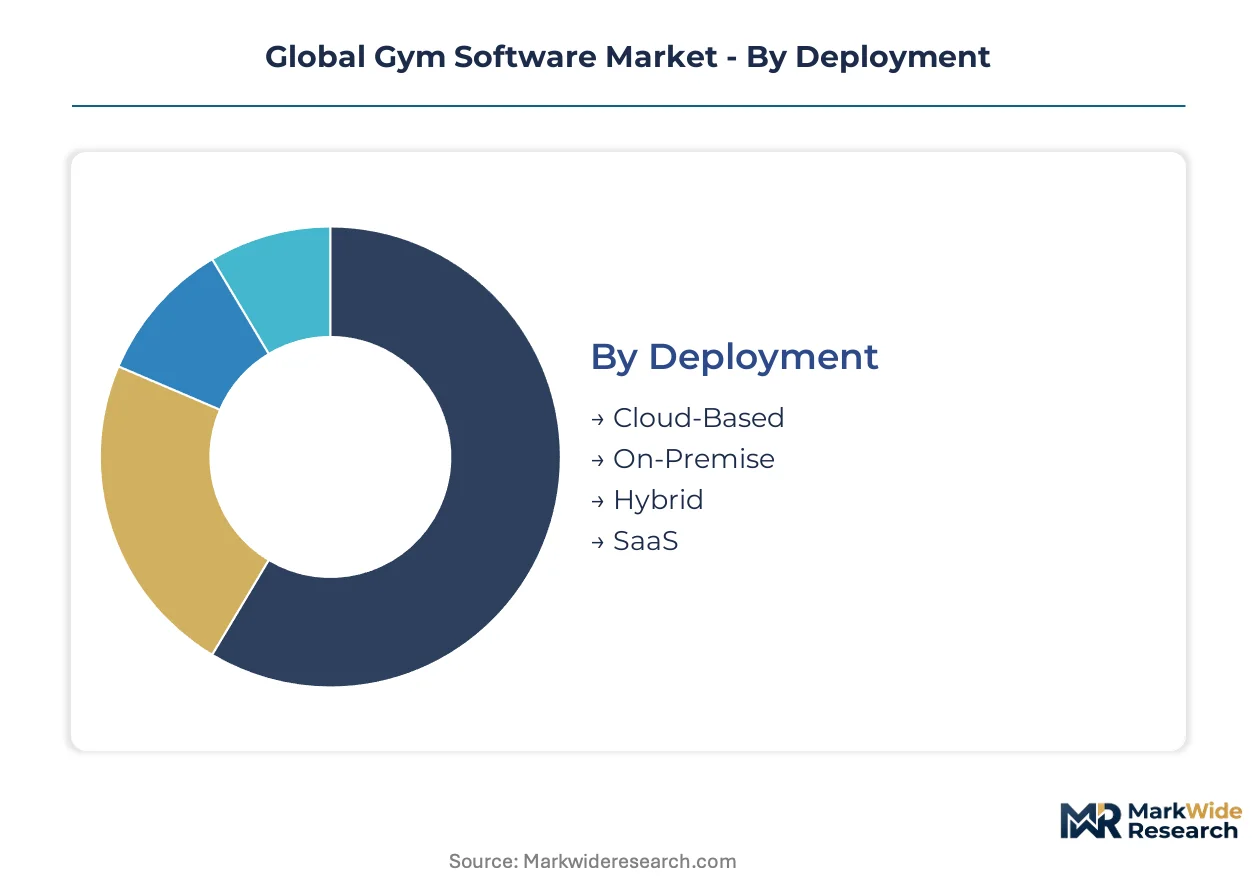
Gym software procurement patterns diverge sharply across deployment models and end-user technical capacity, with franchise operators demanding unified stacks while independent studios tolerate fragmented point solutions. Segmentation reveals where vendor R&D investments concentrate versus where price-sensitive adoption lags.
Deployment:
After-sales-service intensity varies dramatically by deployment architecture, with on-premise installations requiring dedicated field engineering and cloud models shifting burden to automated patching and remote diagnostics.
- Cloud-Based:Multi-tenant architectures with automatic security updates and API extensibility dominate franchise procurement in the United States, where remote accessibility across state lines is non-negotiable for corporate oversight. Demand concentrates among operators with 10+ locations seeking centralized data lakes and eliminating patchwork local infrastructure.
- On-Premise:Legacy server installations persist in European jurisdictions with strict data residency requirements under GDPR, particularly German boutique operators maintaining physical control over member biometric records. These deployments demand 18-24 month hardware refresh cycles and on-site technical support contracts that compress vendor margins.
- Hybrid:Edge computing nodes processing biometric entry locally while syncing to centralized dashboards are gaining traction in Netherlands boutique fitness chains seeking latency reduction for member check-ins.
- SaaS:Direct-to-gym subscription models with localized payment gateway integrations are penetrating underpenetrated independent Pilates and barre studios in Berlin and Munich.
By volume, Cloud-Based leads. By growth pace, Hybrid is ahead.
Solution Offering:
Cost tier stratification separates premium integrated suites from modular point solutions, with pricing scaling according to automation depth and API connectivity breadth.
- Membership Management:Core lifecycle automation encompassing enrollment, renewal, and access credential provisioning serves as the entry-level purchase for spreadsheet-dependent independent operators. Demand concentrates in India where domestic vendors leverage PLI scheme incentives to price aggressively into Southeast Asian franchise markets.
- Billing & Payments:Recurring payment processing with multi-currency support and failed payment recovery workflows commands premium pricing in wellness retreat verticals with multi-day programming requirements. United States Fortune 500 benefits administrators drive standardization across regional club networks through master service agreements bundling this capability with broader employee benefit platforms.
- Scheduling:Class and appointment booking with waitlist management and capacity optimization algorithms.
- Performance Tracking:VO2 max integration and recovery metric visualization through API-connected wearable ecosystems.
- Marketing Automation:Personalized engagement workflows and predictive churn algorithms subject to EU AI Act human-in-the-loop override requirements.
By revenue contribution, Billing & Payments dominates. By expansion trajectory, Performance Tracking is climbing the fastest.
Application:
Customer type differentiation separates high-volume transaction environments from relationship-intensive coaching contexts, with software requirements diverging on scheduling complexity and biometric data depth.
- Fitness Centers:High-throughput facilities with 24/7 access control and group class management require robust hardware integration and 99.99% uptime guarantees during peak January enrollment periods.
- Personal Training:One-on-one and small-group coaching operations prioritize VO2 max and recovery metric justification for premium rate structures.
- Yoga Studios:Mindfulness-focused operators with brand-sensitive member experiences demand scheduling modules with accommodation and meal-planning extensions.
- Martial Arts Schools:Belt progression tracking and tournament registration management with family account structures.
- Dance Centers:Recital and performance scheduling with costume inventory integration and parent portal requirements.
By installed base, Fitness Centers leads. By SaaS conversion potential, Yoga Studios is expanding most quickly.
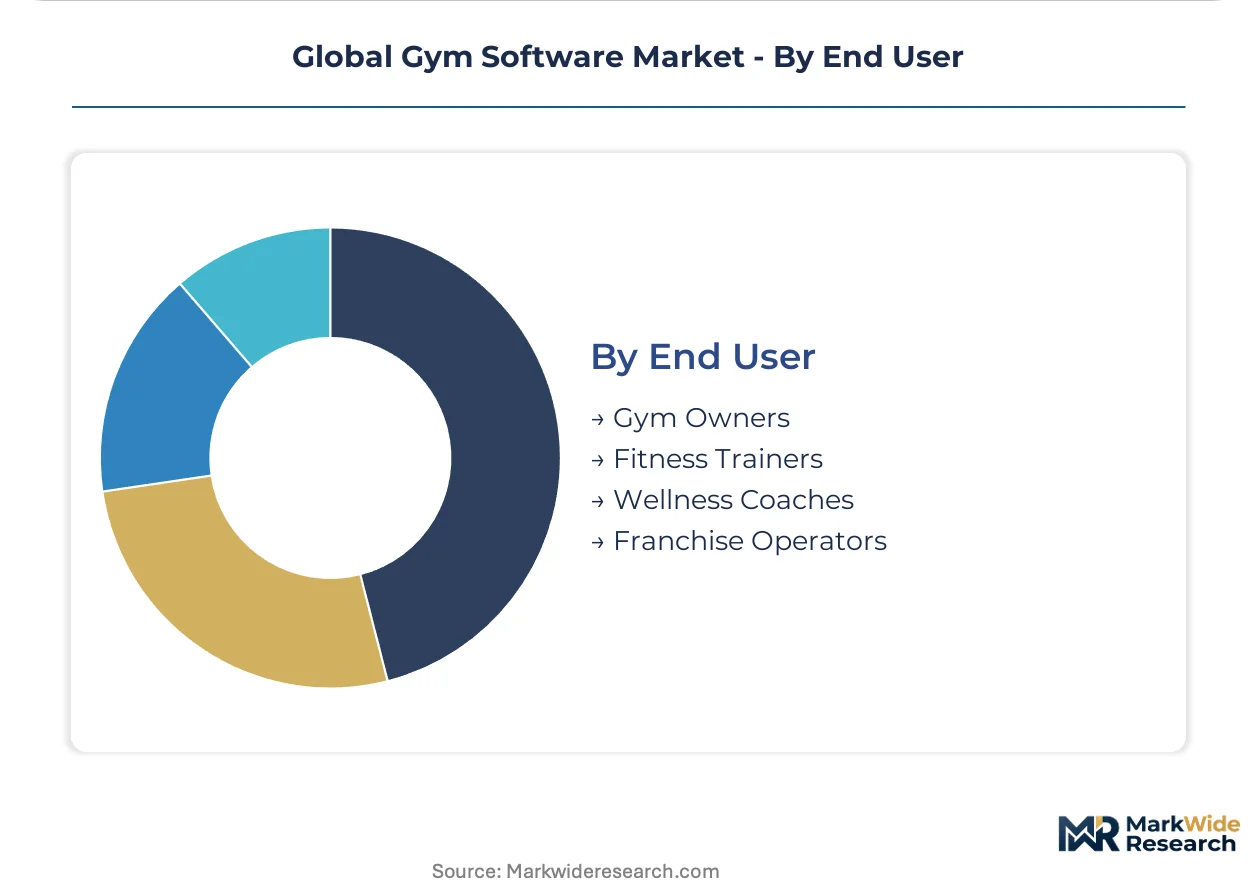
End User:
Volume concentration among franchise operators with consolidated procurement authority contrasts with fragmented decision-making among independent trainers and coaches.
- Gym Owners:Independent single-location operators prioritize cost minimization and often remain on spreadsheet-based management until competitive pressure or payment processing inefficiencies force migration.
- Fitness Trainers:Individual practitioners seeking client management and performance analytics tools justify subscription costs through premium personal training tier differentiation.
- Wellness Coaches:Holistic health practitioners requiring nutrition tracking and lifestyle goal integration alongside standard fitness metrics.
- Franchise Operators:Multi-location corporate entities with centralized IT governance mandate unified billing, scheduling, and performance analytics into single-dashboard environments.
By purchasing volume, Franchise Operators leads. By conversion velocity, Fitness Trainers is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic fiber-optic cable infrastructure and hyperscale cloud regions in Northern Virginia, Frankfurt, and Mumbai underwrite the geography's role in gym software deployment. These digital corridors enable real-time synchronization of biometric data across multi-location franchise networks. Regulatory divergence across jurisdictions is fragmenting vendor architecture requirements.
United States
Fortune 500 benefits administrators in Chicago and New York Metro are consolidating vendor relationships under master service agreements that bundle gym software with broader employee benefit platforms. The California Consumer Privacy Act imposes dual compliance frameworks alongside federal standards for vendors serving chains based in Los Angeles and San Francisco. Dallas-Fort Worth anchors the highest concentration of multi-location franchise operators mandating centralized data lakes across state lines.
Germany
Independent Pilates and barre studios in Berlin and Munich remain on spreadsheet-based management, presenting first-mover SaaS conversion potential for vendors with localized payment gateway integrations. GDPR and the EU AI Act impose strict boundaries on automated member profiling and predictive churn algorithms, forcing upgrades to auditable cloud infrastructure. The Rhine-Ruhr metropolitan region hosts the densest cluster of boutique fitness chains accelerating adoption of integrated management platforms.
Netherlands
Boutique fitness operators in Amsterdam and Rotterdam are deploying edge computing nodes embedded within club access control hardware to process biometric entry locally. GDPR compliance requirements are reshaping data governance protocols for member analytics. The Randstad conurbation leads European adoption of hybrid deployment models that compress pure-SaaS margins while enabling premium pricing.
India
Domestic vendors capturing incentives under the PLI scheme for registered IT exports can price aggressively into Southeast Asian franchise markets. Demand concentrates in Maharashtra and Karnataka where domestic software vendors leverage export incentives to maintain margin structures unavailable to US and European competitors. Bangalore anchors the primary development cluster for cloud-based membership management platforms serving independent gym operators.
United Kingdom
Wellness retreat operators in London and the Southeast are driving demand for scheduling modules with accommodation and meal-planning extensions beyond standard gym workflows. Post-Brexit data adequacy arrangements with the EU are complicating cross-border member data transfers for chains operating in both jurisdictions. The M4 corridor hosts the highest density of yoga studios where brand recognition drives purchasing decisions for specialized software platforms.
Global Gym Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying scheduling modules, payment gateways, and biometric APIs. The vendor base organizes around three tiers: all-in-suite providers with unified billing-scheduling-analytics stacks, best-of-breed specialists with deep vertical functionality, and regional SaaS vendors with localized payment integrations. Franchise procurement teams are consolidating around single-dashboard environments that elevate switching costs. Competitive moves concentrate on API standardization efforts and strategic partnerships with wearable hardware manufacturers.
Within the European platform tier, Virtuagym leverages its headquarters location to sustain channel partnerships with boutique studios across Germany and the Netherlands. ABC Fitness Solutions, LLC anchors its competitive position through deep integration capabilities with legacy club management systems. MINDBODY, Inc. occupies a distinct position in wellness retreat and yoga studio verticals where brand recognition influences purchasing decisions. These three entities exemplify the geographic and vertical specialization strategies that define competitive positioning in this market.
| Leading Market Players |
|---|
| Virtuagym |
| Wodify Technologies, LLC |
| ABC Fitness Solutions, LLC |
| Exercise.com, Inc. |
| Zen Planner, LLC |
| MINDBODY, Inc. |
| Xplor Technologies |
| PushPress, LLC |
| Daxko, LLC |
| Others |
Supply & Pricing Matrix
Transatlantic fiber-optic corridors linking Northern Virginia to Frankfurt and Mumbai shape cost dynamics for gym software vendors, concentrating cloud infrastructure spend in hyperscale regions while forcing price differentiation between franchise operators with volume leverage and independent studios absorbing full freight costs.
Pricing Analysis
Volume-discount tiering structures separate enterprise franchise agreements from independent studio subscriptions. Three-tier pricing stratifies across premium API-integrated suites, standard cloud-based modules, and economy self-service tiers. Price differentiation rests on deployment complexity and wearable ecosystem connectivity depth. Pricing pressure stems from PLI scheme-enabled Indian vendors undercutting US and European competitors in Southeast Asian markets. Independent Pilates and barre operators in Berlin and Munich exhibit highest price sensitivity, while Fortune 500 benefits administrators negotiate least.
Supply Chain Analysis
Supplier-financing facilities extended by hyperscale cloud providers in Northern Virginia, Frankfurt, and Mumbai compress working capital cycles for software vendors. Engineering talent concentrates in Bangalore, Berlin, and Austin. Raw material dependencies center on GPU compute capacity, biometric sensor hardware from Taiwan and South Korea, and API middleware licensing. Single-source vulnerability runs through AWS, Azure, and GCP concentration for 99.99% uptime guarantees. Distribution runs through direct-to-gym SaaS channels and corporate benefits administrator master service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
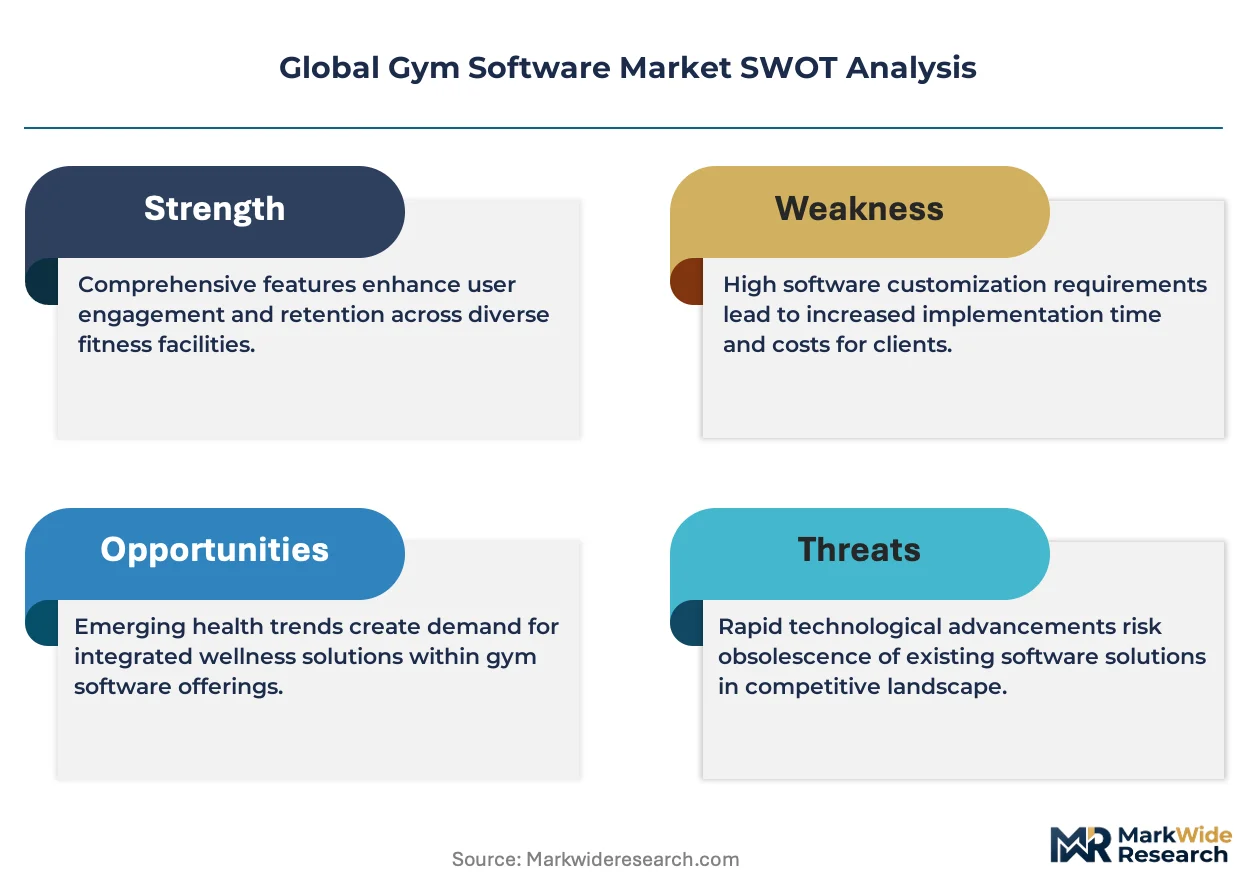
Gym software incumbents face substitution pressure from verticalized employee wellness platforms bundling fitness tracking with broader benefits administration, requiring defensive architecture investments to maintain standalone viability.
For Market Incumbents: Harden API interoperability moats against disintermediation by HRIS-integrated wellness platforms. Deepen edge computing partnerships with Dutch boutique chains to justify hybrid deployment premiums. Prioritize GDPR and EU AI Act compliance tooling as competitive differentiator against US-based challengers. Consolidate channel control through exclusive payment gateway integrations in underpenetrated German markets.
For New Entrants and Emerging Players: Independent Pilates and barre studios in Berlin and Munich present first-mover SaaS conversion opportunity with localized payment infrastructure. Wellness retreat verticals with accommodation and meal-planning extensions offer adjacent scheduling module demand beyond standard gym workflows. Target PLI scheme qualification to price aggressively into Southeast Asian franchise markets while maintaining margin structures unavailable to Western competitors.
For Investors and Strategic Acquirers: Carve-out targets emerge from legacy club management system vendors with stranded middleware assets and regional customer bases. Long-term viability centers on AI-driven churn prediction capabilities and biometric data governance tooling. Monitor EU AI Act enforcement patterns as inflection indicator for compliance-tech valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies billing, scheduling, and analytics into single-dashboard environments for franchise operators. |
| Strategic Partnership | Deepens wearable hardware API connectivity for VO2 max and recovery metric visualization. |
| Geographic Expansion | Captures PLI scheme incentives to price competitively into Southeast Asian franchise markets. |
| Acquisition of Specialist Firm | Absorbs edge computing node capabilities for hybrid deployment models in Netherlands boutique chains. |
| Product Launch | Introduces EU AI Act-compliant retention algorithms with human-in-the-loop override documentation. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with gym software CTOs, franchise procurement directors, boutique studio owners, and integration specialists; and secondary validation through SEC filings, hyperscaler capex disclosures, App Annie platform analytics, and EU regulatory filings. Bottom-up triangulation across deployment model, solution offering, application vertical, and end-user type segments anchored volume estimates. Top-down cross-checks against franchise operator IT spend benchmarks and cloud infrastructure consumption patterns refined value projections.
Forecast inputs considered subscription pricing trajectories, API-connected wearable ecosystem expansion rates, and multi-location franchise standardization mandates across the projection horizon. Segmentation dimensions modeled encompass deployment architecture, solution module depth, customer type technical capacity, and regional regulatory cluster. CAGRs derived from fitted growth curves against historical SaaS adoption patterns in adjacent verticals. Biometric data reclassification risk and EU AI Act compliance cost burdens factored as scenario variables.
Macroeconomic conditions sit as an overlay; deviation in enterprise software IT budgets, cloud infrastructure pricing, or cross-border data transfer policy would shift the trajectory. Forecasts reflect documented assumptions regarding franchise operator consolidation velocity and wearable hardware partnership penetration. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Exploration and Production (E&P) Software Market
Software & Services
Skills Management Software Market
Software & Services
Mining Software Market
Software & Services
Supply Chain Management (SCM) Software Market
Software & Services
Jobsite Management Software Market
Software & Services
Global Business Card Software Market
Software & Services
Global Product Information Management (PIM) Software Market
Software & Services
Global UIUX Software Market
Software & Services
Relational Database Management System Market
Software & Services
Global AI Writing Assistant Software Market
Software & Services
HACCP Software Market
Software & Services
Construction Simulation Software Market
Software & Services
Point of Sale (Pos) Software Market
Software & Services
Special Effects (SFX) Software Market
Software & Services
Global App Store Optimization Software Market
Software & Services
Global Animation Software Market