
 Parametric Design Software Market | 2026-2036
Parametric Design Software Market Size, Share, and Industry Trends Forecast 2026-2036
Parametric Design Software Market Analytics
Platform licensing is rewriting how value migrates from perpetual sales to recurring revenue pools in parametric design. Autodesk sustains broad architectural penetration through its cloud-connected portfolio. Dassault Systèmes anchors high-end engineering workflows with deep simulation integration. PTC specializes in industrial parametric applications where geometric constraint management drives precision manufacturing.
Parametric design software encodes geometric relationships through variable-driven algorithms that propagate design changes across interconnected model elements, typically supporting NURBS surfaces, history-based feature trees, and constraint solvers with millimeter-level precision. Its primary purpose is to compress iteration cycles in complex product development and capital project delivery. Cloud-based deployment is capturing the fastest expansion as distributed teams demand concurrent modeling access. Building Information Modeling retains the largest installed base where structural interoperability commands premium pricing. Generative design represents the emerging margin pool as AI-powered topology optimization displaces manual iteration in aerospace and automotive applications.
ISO 19650 standards for information management are reshaping how parametric tools handle data interoperability across construction project lifecycles. The EU Green Deal's embodied carbon tracking requirements are forcing software vendors to embed material lifecycle calculators directly into parametric workflows. Stakeholders must decide whether to build native sustainability analytics or partner with specialized environmental data providers.
Market Dynamics
Generative AI integration is compressing design iteration cycles from weeks to hours, forcing incumbent vendors to rearchitect core engines around neural topology optimization while defending installed-base revenue from cloud-native challengers.
Growth Catalysts
- ISO 19650 Mandates:Construction projects across Germany, the United Kingdom, and France now require federated data environments that only advanced parametric platforms can orchestrate, pulling mid-tier architecture firms into compliance-driven upgrades.
- Automotive Lightweighting:Topology optimization for electric vehicle battery enclosures and chassis components is accelerating adoption among Tier-1 suppliers seeking automated mass reduction without manual redesign loops.
- Cloud-Native Collaboration:Distributed engineering teams in aerospace hubs like Toulouse, Seattle, and Bangalore demand concurrent parametric modeling access that legacy desktop installations cannot provide.
Market Restraints
- GPU Compute Cost Volatility:Real-time generative design workloads depend on NVIDIA and AMD datacenter hardware whose pricing swings directly squeeze SaaS gross margins.
- Vendor Lock-In Architecture:Deep constraint solver integrations and proprietary file formats create switching costs that deter multi-vendor environments, concentrating buyer risk with single suppliers.
- Interoperability Friction:NURBS translation errors between parametric kernels and mesh-based simulation tools force manual rework, limiting automated workflow completeness.
Strategic Opportunities
- India Manufacturing Digitization:PLI scheme incentives for domestic electronics and automotive production are creating first-mover advantages for parametric vendors localizing cloud infrastructure.
- EU Green Deal Embodied Carbon Tracking:Mandatory lifecycle calculators embedded directly into parametric workflows open premium pricing for sustainability-integrated platforms.
- Digital Twin Convergence:Merging parametric geometry engines with IoT sensor feeds and physics-based simulation enables continuous design-in-operation feedback loops for industrial asset operators.
Industry Challenges
- Computational Geometry Talent Scarcity:Constraint solver development and NURBS kernel optimization require PhD-level expertise that pools narrowly in academic institutions and legacy CAD vendors.
- Legacy System Integration Complexity:Decades-old PDM environments and custom PLM implementations resist API-based connectivity, extending enterprise sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parametric Design Software Market |
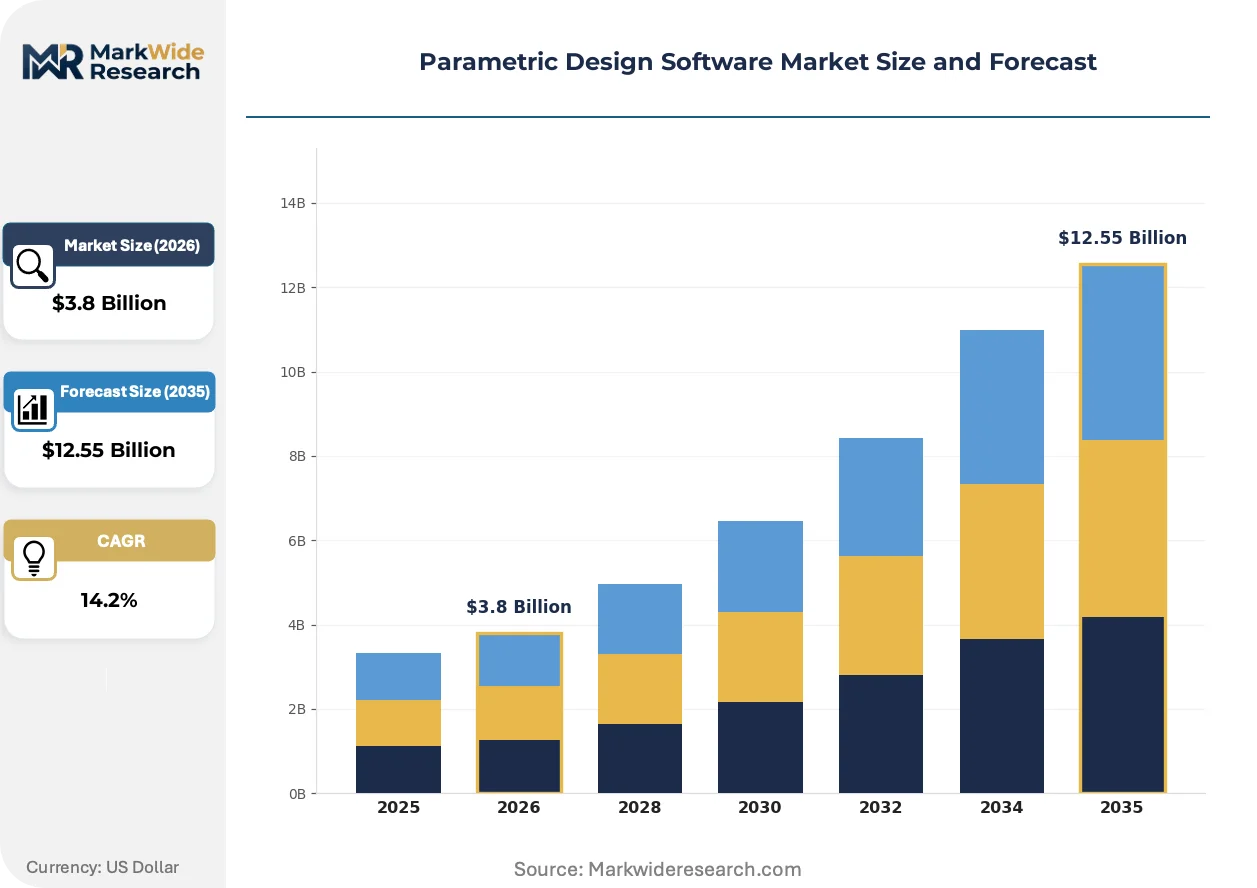
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Modeling, Building Information Modeling, Computational Design, Generative Design End User: Architects, Engineers, Designers, Construction Firms Deployment: On-Premise, Cloud-Based, Hybrid, Client-Server Feature: Real-Time Collaboration, Interactive Visualization, Simulation, Parametric Constraints |
| Companies Covered | Bentley Systems, Dassault Systèmes, Autodesk, Allplan, Onshape, SolidWorks, PTC, Fusion 360, Graphisoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parametric Design Software Market Evolving Landscape
Neural network architectures trained on geometric datasets are displacing rule-based optimization engines, compressing the boundary between design exploration and manufacturing feasibility into a single computational layer.
Real-time ray-traced rendering is virtualizing design review workflows that previously required physical prototyping. Automotive studios in Stuttgart and Turin now evaluate surface quality through GPU-accelerated visualization before committing to clay models. This compression eliminates material waste and accelerates stakeholder sign-off cycles.
EU AI Act risk classification requirements are mandating explainability in generative design algorithms used for safety-critical structural components. Aerospace suppliers must now document how topology optimization arrived at load-bearing geometries, forcing vendors to embed audit trails and constraint logging into solver outputs. German certification bodies are developing sector-specific conformity assessment protocols.
Subscription fatigue among mid-market architecture practices is fragmenting procurement toward modular, usage-metered licensing. Firms in Melbourne, Copenhagen, and São Paulo increasingly unbundle core parametric modeling from simulation and rendering capabilities, purchasing only what project pipelines require. This behavior pressures vendors to maintain feature parity across tiered service levels without engineering redundancy.
Parametric Design Software Market Segmentation
Parametric design software segments diverge sharply in procurement cadence. Cloud-native deployments refresh licenses quarterly while on-premise installations persist for seven to ten years. Understanding these velocity differentials shapes vendor pricing architecture and R&D resource allocation.
Product Type:
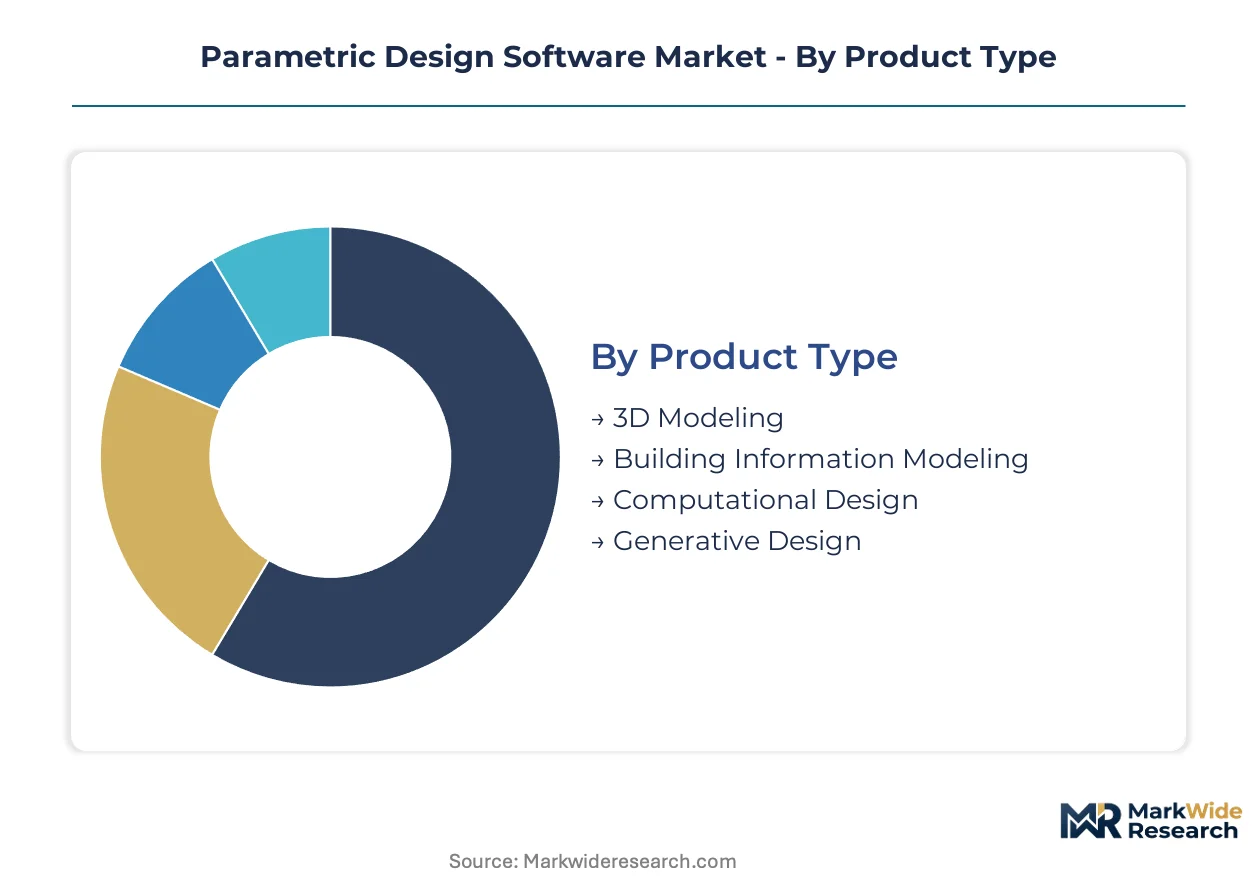
Building Information Modeling carries the longest replacement cycles among parametric categories, while Generative Design contracts compress to annual renewal terms as capabilities evolve.
- 3D Modeling:Core geometric kernel technology supporting NURBS surfaces and solid modeling operations with history-based feature trees. Manufacturing hubs in Stuttgart and Turin drive demand for precision surface quality validation prior to physical prototyping.
- Building Information Modeling:Federated data environments integrating structural, MEP, and architectural parametric models with ISO 19650 compliance workflows. German and UK construction mandates are pulling mid-tier architecture firms into mandatory platform upgrades regardless of budget cycles.
- Computational Design:Script-driven geometric exploration using visual programming interfaces. Design studios in Copenhagen and São Paulo deploy these tools for complex facade patterning and structural optimization.
- Generative Design:AI-powered topology optimization replacing manual iteration loops. Aerospace suppliers in Toulouse and automotive Tier-1s in Detroit are expanding adoption for battery enclosure lightweighting and chassis mass reduction.
Building Information Modeling dominates installed base. Generative Design is where expansion concentrates.
End User:
Engineering teams command the highest per-seat licensing values, while construction firms represent the most price-sensitive procurement segment with compressed decision timelines.
- Architects:Primary consumers of facade and spatial parametric tools with emphasis on aesthetic exploration and environmental performance simulation. Subscription fatigue in Melbourne and São Paulo is fragmenting procurement toward modular, usage-metered licensing.
- Engineers:Structural and mechanical specialists requiring deep constraint solver precision and simulation integration. Demand concentrates among German automotive suppliers and French aerospace clusters seeking automated optimization workflows.
- Designers:Industrial and product design practitioners leveraging real-time rendering for stakeholder visualization. GPU-accelerated ray-tracing is virtualizing review cycles previously requiring physical clay models.
- Construction Firms:Field-oriented users prioritizing clash detection and sequencing visualization over generative capabilities. EU Green Deal embodied carbon tracking requirements are forcing sustainability calculator integration into procurement evaluations.
Engineers generate the highest revenue per seat. Construction firms are climbing the fastest as compliance mandates drive technology adoption.
Deployment:
Cloud infrastructure investments are accelerating refresh cycles, while client-server architectures at legacy manufacturers show minimal turnover.
- On-Premise:Perpetual license models with localized data sovereignty for defense and classified project requirements. German and US aerospace contractors maintain these installations for ITAR and security compliance.
- Cloud-Based:SaaS delivery enabling concurrent modeling access for distributed teams. Bangalore and Seattle engineering hubs demand this architecture for round-the-clock development cycles across time zones.
- Hybrid:Mixed environments preserving sensitive IP on-premise while leveraging cloud compute for rendering and simulation bursts. Tier-1 automotive suppliers in Stuttgart favor this model for competitive security.
- Client-Server:Legacy architectures persisting at established manufacturers with decades-old PDM integrations. Extended sales cycles reflect the complexity of API-based connectivity with custom PLM implementations.
On-Premise retains the largest legacy footprint. Cloud-Based is gaining share fastest as distributed collaboration becomes non-negotiable.
Feature:
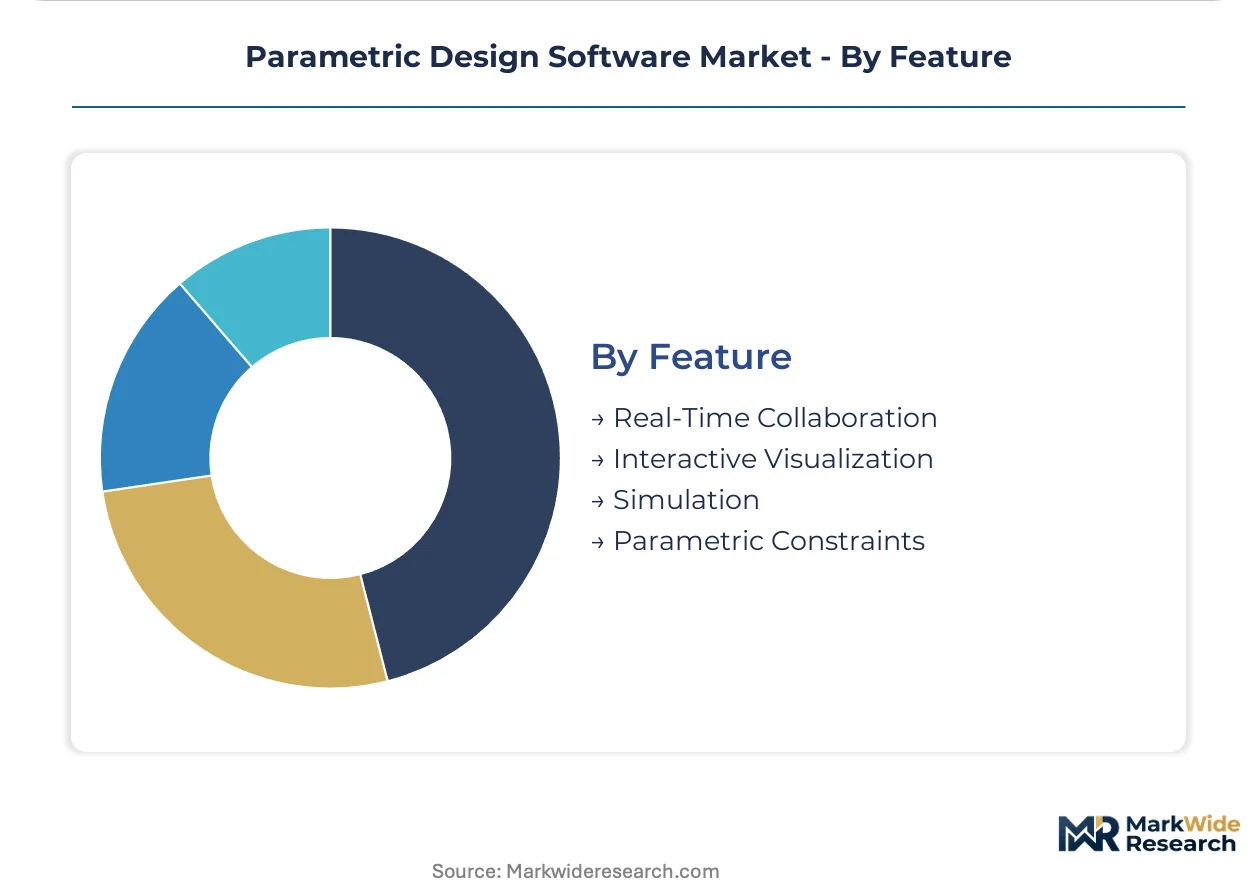
Parametric constraints form the foundational layer with slowest enhancement cycles, while real-time collaboration capabilities refresh quarterly.
- Real-Time Collaboration:Concurrent editing and version control for distributed design teams. Aerospace clusters in Toulouse and Seattle require this capability for multi-site fuselage and wing development programs.
- Interactive Visualization:GPU-accelerated rendering and virtual reality review environments. Automotive studios are eliminating physical prototyping waste through surface quality evaluation in digital space.
- Simulation:Integrated structural, thermal, and fluid analysis within parametric workflows. Topology optimization for electric vehicle components is accelerating demand among battery enclosure designers.
- Parametric Constraints:Core geometric relationship engines propagating design changes across interconnected model elements. Millimeter-level precision requirements in precision manufacturing anchor this as the non-negotiable baseline capability.
Parametric Constraints anchors every platform. Real-Time Collaboration is where vendors are investing most aggressively to differentiate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. German engineering teams prioritize deep simulation integration, while Indian manufacturing hubs favor cloud-native accessibility over legacy feature depth.
United States
Defense contractors and aerospace clusters in Seattle demand ITAR-compliant on-premise installations. FAA certification workflows for commercial aircraft components mandate audit-trail documentation in generative design outputs. Boeing suppliers in Everett and Wichita anchor high-value engineering seats.
Germany
Automotive lightweighting for electric vehicle chassis drives topology optimization demand. KBA conformity assessment protocols and EU AI Act explainability requirements reshape solver development priorities. Stuttgart and Munich host concentrated Tier-1 supplier engineering centers.
China
Domestic electronics manufacturing under MIIT industrial policy accelerates cloud infrastructure localization. Dual carbon goals and GB standards for building energy performance force sustainability calculator integration. Shenzhen and Shanghai engineering hubs demand concurrent modeling for round-the-clock development.
India
PLI scheme incentives for domestic automotive and electronics production create first-mover opportunities for localized SaaS delivery. BIS standards adoption lags, compressing procurement decision timelines. Bangalore and Pune engineering centers drive cloud-based collaboration demand.
United Kingdom
ISO 19650 mandates for federated data environments pull mid-tier architecture firms into compliance-driven upgrades. CSRD disclosure requirements extend carbon tracking obligations through construction supply chains. London and Manchester practices fragment procurement toward modular licensing.
Parametric Design Software Market Competitive Landscape
Capability concentration sits with heritage CAD vendors possessing deep constraint solver expertise; scale advantage sits with cloud-native challengers offering frictionless deployment. The vendor base stratifies across three tiers: integrated platform providers, specialized engineering suites, and emerging SaaS-native tools. Dominant competitive moves include strategic partnerships for sustainability data integration and geographic expansion through localized cloud infrastructure.
Within the integrated platform tier, Autodesk and Dassault Systèmes exemplify divergent architectural philosophies. Bentley Systems occupies a position bridging infrastructure-heavy BIM workflows with generative design capabilities. PTC anchors the precision manufacturing segment where geometric constraint management commands premium pricing. Onshape represents the cloud-native archetype, having built distribution without legacy desktop dependencies.
| Leading Market Players |
|---|
| Bentley Systems |
| Dassault Systèmes |
| Autodesk |
| Allplan |
| Onshape |
| SolidWorks |
| PTC |
| Fusion 360 |
| Graphisoft |
| Others |
Value Network & Pricing Analysis
Overcapacity in cloud compute infrastructure across US West Coast and European data center hubs is compressing SaaS delivery costs while intensifying vendor competition for enterprise parametric design contracts, forcing pricing discipline that feeds back into supplier consolidation among GPU hardware providers.
Pricing Analysis
Long-term enterprise licensing contracts anchor the pricing architecture for parametric design platforms, though project-based procurement is fragmenting among mid-market architecture practices. Three-tier pricing structure across premium, standard, and economy levels differentiates by simulation depth and collaboration seat count, with ISO 19650 certification tiers commanding measurable premiums. Cost compression in standard-tier subscriptions is intensifying because cloud-native challengers are undercutting legacy desktop incumbents. Construction firms exhibit the highest price sensitivity, while aerospace engineering clusters show minimal elasticity for precision constraint solver capabilities.
Supply Chain Analysis
Extended payment terms from Tier-1 automotive suppliers in Germany and France are reshaping cash flow dynamics for parametric software vendors serving precision manufacturing. Supply concentrates in the United States, Germany, and China for core geometric kernel development, with India emerging as a delivery hub for cloud infrastructure localization. NVIDIA and AMD datacenter hardware, proprietary constraint solver libraries, and ISO certification audit services constitute critical input dependencies. Single-source vulnerability in GPU compute silicon creates exposure to pricing volatility that vendors cannot easily hedge. Distribution runs through direct enterprise sales teams for large engineering accounts and channel partners for mid-market architectural practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among consolidated aerospace and automotive OEMs that negotiate enterprise-wide parametric platform contracts, fragmenting procurement leverage previously held by dispersed mid-tier firms.
For Market Incumbents: Insulate core constraint solver IP through selective patent enforcement while accelerating cloud-native rearchitecture to defend against SaaS challengers. Deepen backward integration into generative AI training infrastructure to control topology optimization model development costs. Prioritize ISO 19650 compliance certification investments to lock in construction sector switching costs.
For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point for BIM-native parametric tools without legacy PDM integration burdens. Cloud-first computational design platforms for Indian PLI scheme manufacturing incentives offer second-mover advantages over established vendors with localized infrastructure. Partner with environmental data providers for EU Green Deal carbon calculator integration rather than building native sustainability analytics.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native parametric platforms with usage-metered billing and quarterly refresh cycles. Long-term viability across the analysis window favors vendors with hybrid deployment flexibility and federated data environment orchestration capabilities. Watch for inflection in generative design algorithm explainability investments as EU AI Act enforcement tightens conformity assessment requirements for safety-critical structural applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Merging parametric geometry engines with IoT sensor feeds enables continuous design-in-operation feedback loops for industrial asset operators. |
| Strategic Partnership | Sustainability data provider alliances embed embodied carbon calculators directly into parametric workflows for EU Green Deal compliance. |
| Geographic Expansion | Localized cloud infrastructure in Bangalore and Pune captures PLI scheme manufacturing digitization incentives before incumbent vendors establish presence. |
| Acquisition of Specialist Firm | Constraint solver talent pools narrowly in academic institutions; targeted acquisitions accelerate neural topology optimization capability development. |
| Product Launch | Real-time ray-traced rendering modules virtualize automotive design review cycles previously requiring physical clay model prototyping in Stuttgart and Turin. |
Research Methodology
Desk research of SEC filings from publicly traded CAD vendors, hyperscaler capex disclosures, and ISO standards documentation preceded structured interviews with CTOs at aerospace engineering clusters, IT procurement officers at Tier-1 automotive suppliers, platform integration specialists, and channel partners serving mid-market architecture practices. Bottom-up sizing of cloud-native and on-premise deployment revenue pools was cross-validated against top-down industry spend estimates from construction and manufacturing sector surveys.
Assumptions around ISO 19650 mandate adoption timelines, GPU compute cost trajectories, and PLI scheme incentive disbursement schedules were held fixed across baseline scenarios while generative AI capability maturation and EU AI Act enforcement intensity were varied in sensitivity testing. Segmentation modeling incorporated deployment model, organization size by engineering headcount, vertical industry, integration complexity with legacy PDM environments, and regional regulatory compliance cluster. CAGRs were derived from fitted growth curves applied to vendor-reported subscription renewal rates and new customer acquisition data.
Macroeconomic conditions sit as an overlay; deviation in datacenter construction investment cycles, semiconductor capital equipment spending, or construction sector output would shift the trajectory. Forecasts reflect documented assumptions around compliance mandate implementation schedules and technology substitution elasticities. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Landscape Software Market
Software & Services
Investor Relations (IR) Website Builder Software Market
Software & Services
Indonesia IT Services Market
Software & Services
Laser Engraving Software Market
Software & Services
IT Service Management Tools Market
Software & Services
Global Big Data Software Market
Software & Services
Interior Design Software Market
Software & Services
Collaboration Tools Market
Software & Services
Channel Management Software Market
Software & Services
File Sharing Software Market
Software & Services
Home Design Software Market
Software & Services
Time Series Databases Software Market
Software & Services
Global Manufacturing Operations Management (MOM) Software Market
Software & Services
Productivity Management Software Market
Software & Services
Bankruptcy Software Market
Software & Services
POS Software Market