
 Mining Software Market | 2026-2036
Mining Software Market Size, Share, and Industry Trends Forecast 2026-2036
Mining Software Market Outlook
Mid-tier mining contractors are bifurcating from large integrated miners as the fastest-growing buyer archetype for subscription-based planning and dispatch tools. Hexagon Mining leverages its sensor-to-software stack to dominate underground fleet optimization. Datamine competes through deep specialization in geological modeling workflows for narrow-vein operations. Seequent Leapfrog anchors its position in implicit modeling for resource estimation across copper-gold porphyry deposits.
Mining software encompasses digital platforms that integrate geological databases, mine planning algorithms, and real-time equipment telemetry to optimize extraction economics and safety outcomes. Core functional parameters include block model resolution down to sub-meter scales, pit optimization using Lerchs-Grossmann algorithms, and dispatch systems processing 500+ truck cycles per shift. Cloud deployment is displacing on-premise installations fastest among junior explorers lacking capital for server infrastructure. Artificial Intelligence and Machine Learning segments capture disproportionate R&D investment as vendors train neural networks on drill-core imagery for automated lithology classification. Planning software retains the largest revenue pool due to multiyear licensing cycles tied to feasibility studies and life-of-mine schedules.
Canada's tailings management regulator enforces dam safety audits that require digital monitoring integration, while the EU's CSRD mandates granular Scope 3 emissions reporting that mining software must automate. Australia's Work Health and Safety frameworks push underground operators toward real-time proximity detection systems linked to dispatch platforms. Stakeholders must weigh vendor consolidation risk against the interoperability demands of multi-asset portfolios spanning jurisdictions with divergent digital disclosure standards.
Market Dynamics
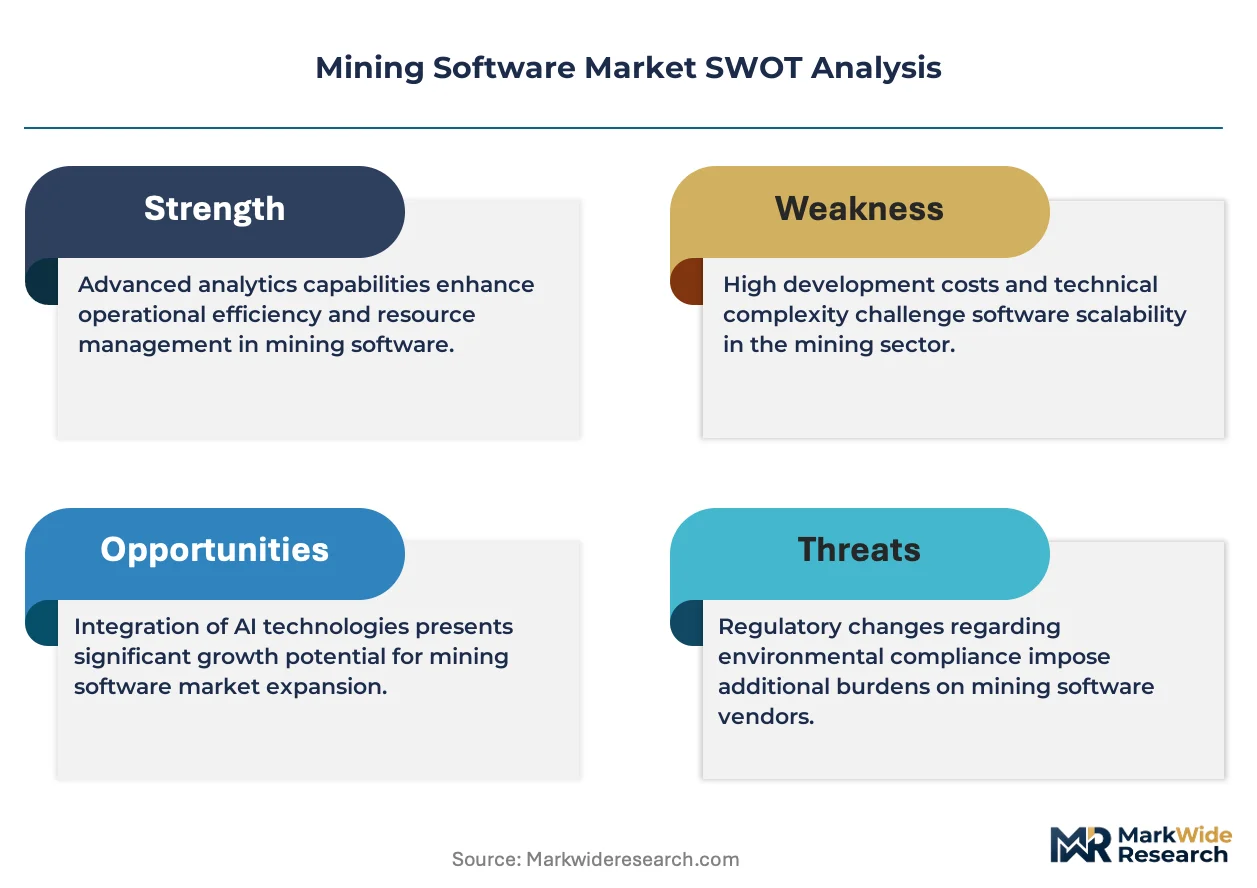
Cloud deployment architectures are compressing capital barriers for junior miners while Canada's dam safety audits and the EU's CSRD emissions mandates force legacy on-premise systems toward obsolescence.
Growth Catalysts
- Canada's tailings dam safety audits:Federal regulators mandate real-time digital monitoring integration, forcing operators to upgrade legacy telemetry with cloud-connected sensor networks.
- Copper-gold porphyry deposits:Implicit modeling demand accelerates as tier-one explorers in Chile's Atacama belt require sub-meter block resolution for feasibility studies.
- Underground proximity detection:Australia's Work Health and Safety frameworks push real-time dispatch integration for collision avoidance in narrow-vein operations.
Market Restraints
- Server infrastructure capital:On-premise hardware cycles lock mid-tier contractors into five-year depreciation schedules that cloud subscriptions cannot immediately displace.
- Western Australia concentration:Iron ore planning software demand clusters in the Pilbara, creating geographic revenue vulnerability to commodity price swings.
- Interoperability friction:Vendor-specific data formats block seamless migration between geological modeling and fleet dispatch platforms.
Strategic Opportunities
- Saskatchewan potash corridor:Solution mining operators underinvested in digital planning present white-space demand for subscription-based life-of-mine scheduling tools.
- EU CSRD Scope 3 automation:Sustainability disclosure mandates create embedded software demand for emissions traceability across copper concentrate supply chains.
- Neural network lithology classification:Convergence of drill-core imagery databases with machine learning training pipelines compresses geological interpretation timelines.
Industry Challenges
- Mine planning algorithm expertise:Lerchs-Grossmann pit optimization specialists command premium compensation that mid-tier vendors struggle to retain.
- Legacy dispatch integration:Real-time equipment telemetry retrofitting requires custom API development for heterogeneous fleet ages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mining Software Market |
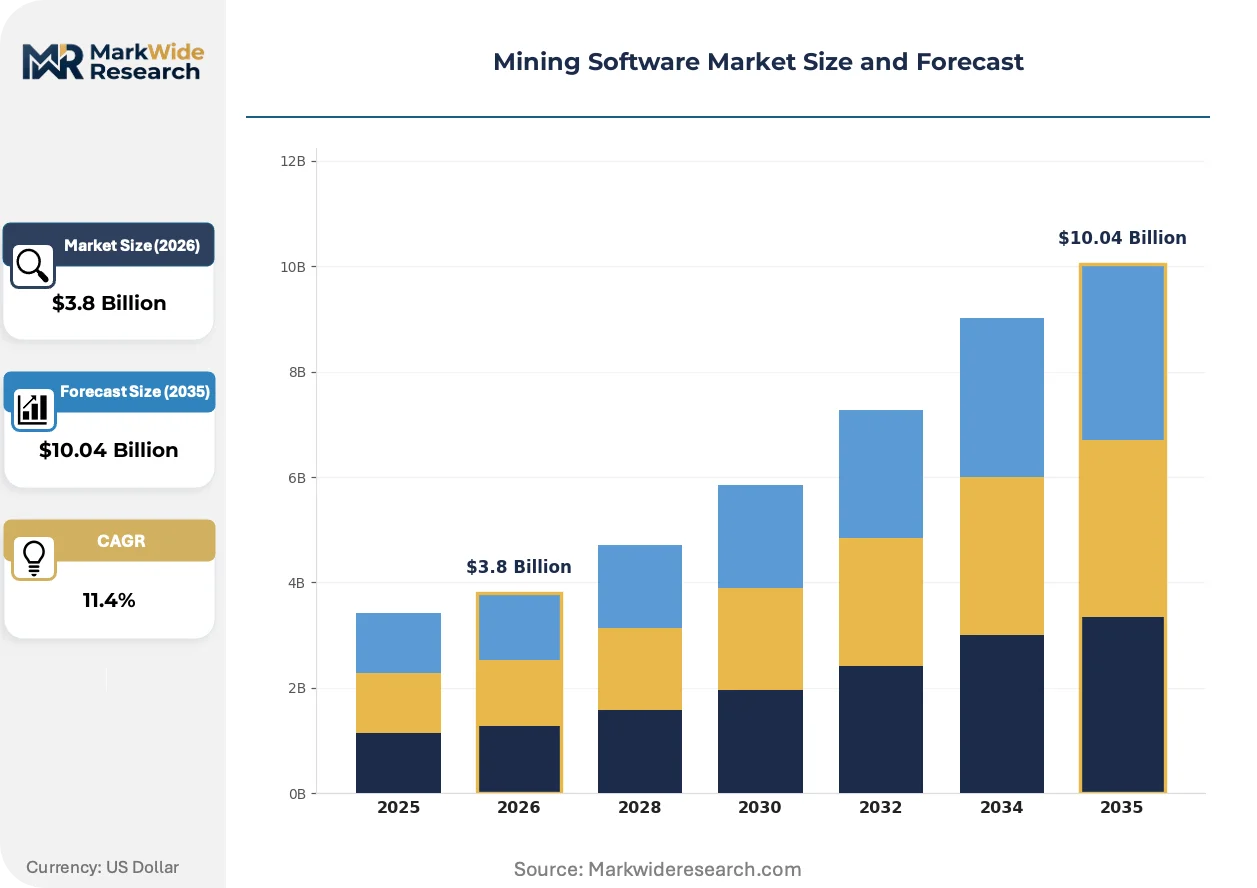
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Planning, Exploration, Analytics, Dispatch Deployment: On-Premise, Cloud, Hybrid, Mobile End User: Mining Companies, Contractors, Consultants, Equipment Suppliers Technology: Artificial Intelligence, Machine Learning, Blockchain, IoT |
| Companies Covered | Carlson Mining, Seequent Leapfrog, Hexagon Mining, Micromine, Datamine, Maptek Vulcan, Deswik, K-MINE, GEOVIA Surpac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mining Software Market Strategic Shifts
Artificial intelligence training pipelines and modular cloud architectures are compressing the traditional multiyear software procurement cycle into iterative subscription renewals tied to operational metrics.
Edge computing nodes for underground fleet telemetry is miniaturizing. Mid-tier contractors in Chile's copper belt deploy palm-sized processing units on haul trucks, eliminating surface server dependency for cycle-time optimization. This hardware compression enables real-time dispatch decisions in tunnel environments with intermittent connectivity.
CSRD sustainability disclosure rules in Europe mandate automated Scope 3 emissions reporting for mining concentrates. Software vendors embed carbon calculators directly into logistics planning modules. Copper exporters to EU smelters face the steepest compliance timelines, accelerating procurement of traceability-enabled platforms.
Subscription pricing for planning tools now unbundles from perpetual licensing. Junior explorers in Western Australia prefer monthly fees tied to drill-meter volumes rather than upfront feasibility-study commitments. This consumption-linked model concentrates among gold developers with compressed exploration timelines.
Mining Software Market Segmentation
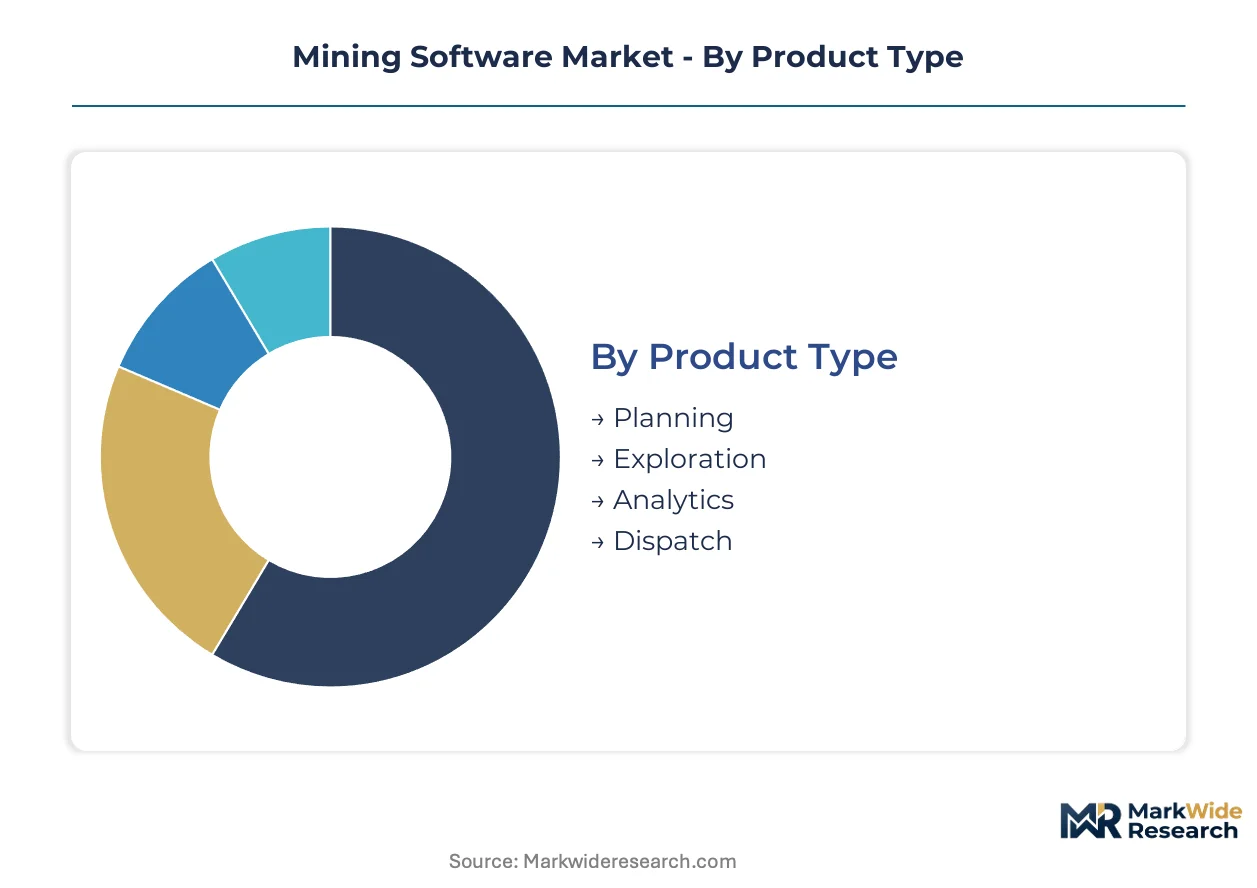
Segmentation in mining software reveals how substitution pressures reshape procurement patterns across deployment architectures and end-user archetypes. Buyers increasingly cross-shop between traditional perpetual licenses and consumption-based alternatives, forcing vendors to defend position through functional specialization rather than lock-in.
Product Type:
Planning software faces the strongest substitution threat from integrated platform bundles that absorb scheduling and dispatch functions into unified subscriptions.
- Planning:Life-of-mine scheduling tools with Lerchs-Grossmann pit optimization and block model resolution down to sub-meter scales anchor procurement budgets. Western Australia's iron ore developers in the Pilbara drive multiyear licensing tied to feasibility studies, though cloud alternatives erode perpetual license dominance.
- Exploration:Geological modeling platforms with implicit surface reconstruction and drill-core database management concentrate demand among junior explorers in Chile's Atacama copper belt. Subscription pricing tied to drill-meter volumes accelerates displacement of upfront capital commitments.
- Analytics:Dashboard and reporting modules aggregate telemetry streams for operational KPI tracking.
- Dispatch:Real-time fleet optimization systems process 500+ truck cycles per shift for surface and underground operations.
Planning anchors the volume base while Exploration gains share at the steepest rate as subscription models penetrate junior mining budgets.
Deployment:
Cost tier stratification separates capital-constrained juniors from integrated miners with sunk infrastructure investments.
- Cloud:Browser-based architectures eliminate server capital for mid-tier contractors and exploration juniors. Canada's tailings dam safety audits and the EU's CSRD emissions mandates accelerate migration as compliance requires scalable data retention and real-time connectivity.
- Hybrid:Split architectures keep sensitive geological data on-premise while pushing telemetry analytics to cloud nodes. Saskatchewan's potash corridor operators favor this model for solution mining operations balancing security with remote access needs.
- On-Premise:Legacy server installations persist where five-year depreciation cycles lock in hardware commitments.
- Mobile:Pit and underground applications on ruggedized tablets enable field data capture without surface connectivity.
Cloud deployment expands most quickly among new buyers while Hybrid retains loyalty among security-sensitive brownfield operators.
End User:
Customer type fragmentation splits procurement authority between owner-operators and outsourced service providers.
- Mining Companies:Integrated owner-operators with multi-asset portfolios demand interoperability across geological modeling, planning, and dispatch platforms. Australia's Work Health and Safety frameworks push underground operators toward real-time proximity detection integration.
- Contractors:Mid-tier mining service providers represent the fastest-expanding buyer archetype for subscription-based tools. Chile's narrow-vein copper operations drive demand for specialized dispatch and fleet optimization without perpetual license burdens.
- Consultants:Independent geological and mine planning advisors require portable licenses across client engagements.
- Equipment Suppliers:OEMs embed telemetry and diagnostics software as value-added fleet management offerings.
Mining Companies command the largest contract values while Contractors drive subscription pricing innovation through consumption-linked models.
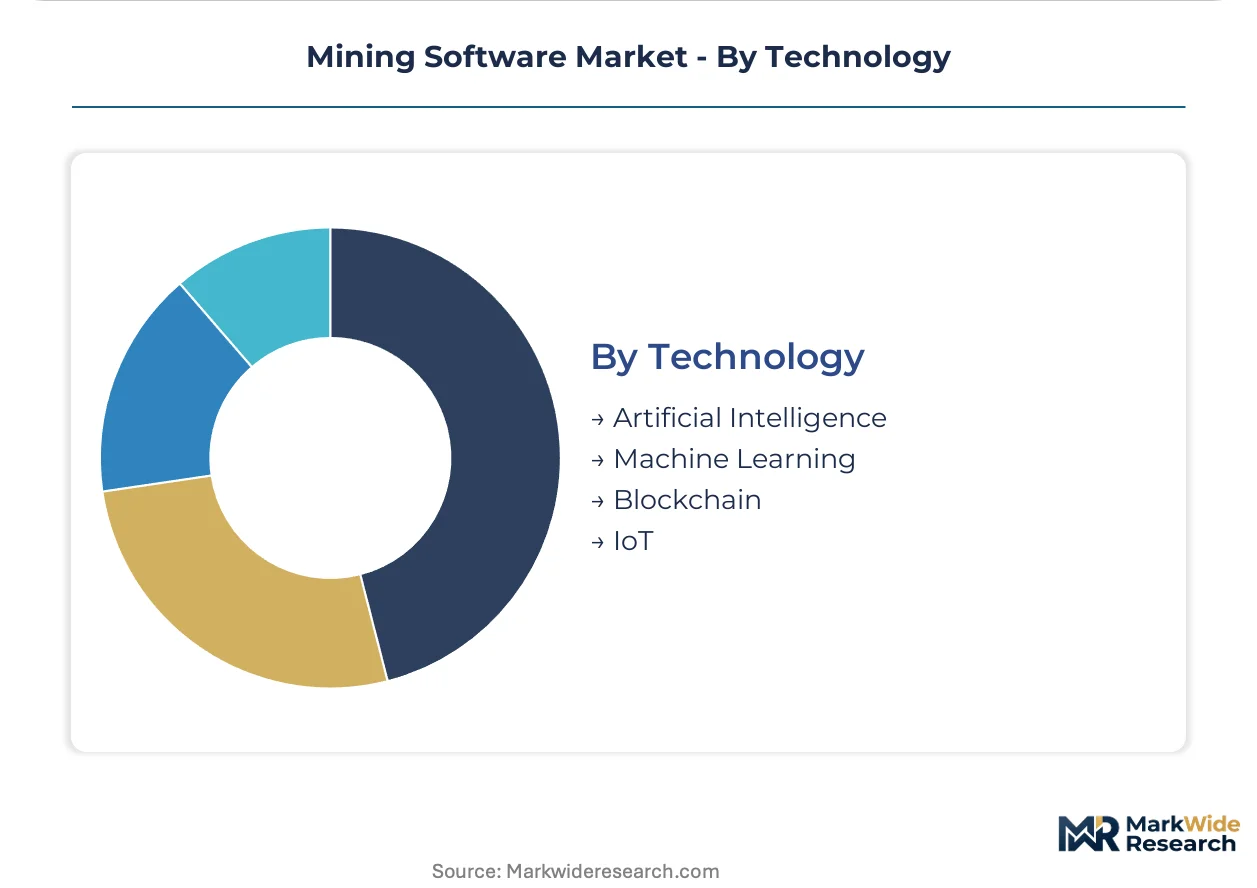
Technology:
Maturity gradients separate proven operational tools from experimental deployments with unproven ROI timelines.
- Artificial Intelligence:Neural network training on drill-core imagery enables automated lithology classification and resource estimation acceleration. Copper-gold porphyry explorers in Western Australia and Chile deploy AI to compress geological interpretation timelines from months to weeks.
- Machine Learning:Predictive maintenance algorithms processing equipment telemetry reduce unplanned downtime for haul truck fleets. Edge computing miniaturization enables real-time model inference on underground vehicles with intermittent surface connectivity.
- IoT:Sensor networks for tailings dam monitoring and equipment telemetry form the operational backbone of digital mining platforms.
- Blockchain:Supply chain traceability for conflict minerals and carbon accounting remains pilot-stage with limited production deployment.
Machine Learning delivers measurable operational savings today while Artificial Intelligence climbs the fastest as training pipelines mature and data availability expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pilbara heavy-haul rail network underwrites Australia's dominance in iron ore planning software procurement, while Chile's Calama-Antofagasta copper concentrate pipeline anchors South American demand for geological modeling platforms.
Australia
Western Australia's Pilbara iron ore developers drive multiyear licensing for life-of-mine scheduling tools with sub-meter block resolution requirements. The country's Work Health and Safety frameworks mandate real-time proximity detection integration for underground operations. Queensland's Bowen Basin coal operators accelerate cloud migration as federal dam safety audits force digital telemetry upgrades.
Chile
Copper-gold porphyry explorers in the Atacama belt deploy implicit modeling software for feasibility studies with compressed timelines. The national mining regulator enforces tailings storage facility monitoring standards that require cloud-connected sensor networks. Antofagasta's narrow-vein contractors represent the fastest-growing buyer archetype for subscription-based dispatch tools.
Canada
Saskatchewan's potash corridor operators underinvested in digital planning present white-space demand for cloud-based scheduling platforms. Federal tailings management regulations enforce dam safety audits requiring real-time monitoring integration. Ontario's Sudbury Basin nickel-copper underground mines push vendor consolidation as multi-asset portfolios demand interoperability across modeling and dispatch systems.
United States
Arizona's copper porphyry belt and Nevada's Carlin-type gold trends concentrate exploration software demand among junior developers with capital constraints. The SEC's climate disclosure rules pressure listed miners toward automated Scope 3 emissions reporting embedded in logistics planning modules. Colorado's legacy molybdenum operations retrofit heterogeneous fleet telemetry through custom API development.
South Africa
The country's platinum group metal reef operations drive demand for narrow-vein geological modeling specialization. The Department of Mineral Resources and Energy enforces mine health and safety standards that accelerate real-time dispatch adoption for collision avoidance. Rustenburg's deep-level mines deploy edge computing nodes to eliminate surface server dependency in connectivity-constrained environments.
Mining Software Market Competitive Environment
Concentration sits with diversified industrial technology conglomerates holding sensor-to-software stacks alongside specialized geological modeling boutiques. Three strategic archetypes dominate: full-stack vendors integrating telemetry hardware with planning platforms, implicit modeling specialists commanding resource estimation workflows, and dispatch optimization pure-plays serving narrow-vein contractors. Competitive moves center on portfolio diversification into adjacent sustainability disclosure automation and technology licensing partnerships with equipment OEMs.
Within the full-stack tier, Hexagon Mining and Maptek Vulcan anchor positions through hardware-software integration, while Seequent Leapfrog exemplifies the geological modeling specialist archetype with implicit surface reconstruction capabilities. Datamine occupies a position bridging planning and narrow-vein dispatch specialization for mid-tier contractors.
| Leading Market Players |
|---|
| Carlson Mining |
| Seequent Leapfrog |
| Hexagon Mining |
| Micromine |
| Datamine |
| Maptek Vulcan |
| Deswik |
| K-MINE |
| GEOVIA Surpac |
| Others |
Value Chain & Pricing Dynamics
Scale economies in cloud infrastructure provision compress marginal delivery costs for software vendors, concentrating pricing power among hyperscaler-backed platforms while forcing smaller specialists toward niche functional differentiation. This concentration dynamic shapes both subscription floor pricing and the geographic reach of vendor sales operations across mining jurisdictions.
Pricing Analysis
Volume-discount tiering structures separate enterprise mining companies with multi-asset portfolios from mid-tier contractors and junior explorers. Three-tier pricing stratifies across premium enterprise licenses with dedicated support, standard professional subscriptions, and economy exploration tiers tied to drill-meter volumes. Pricing pressure stems from cloud-native entrants undercutting perpetual license incumbents with consumption-linked models. Junior explorers in Western Australia exhibit the highest price sensitivity due to capital constraints, while integrated miners in Chile's Atacama belt prioritize interoperability over cost.
Supply Chain Analysis
Just-in-time deployment preferences dominate cloud-native software delivery, though legacy on-premise installations require strategic hardware stockpiling for server infrastructure cycles. Supply concentration centers on the United States for hyperscaler cloud infrastructure, Ireland and Singapore for data residency compliance, and India for engineering talent pipelines. Raw material dependencies include semiconductor components for edge computing nodes, rare earth elements for sensor hardware, and specialized fiber optics for underground connectivity. Single-source vulnerability runs through hyperscaler platform concentration. Distribution feeds from direct vendor sales teams for enterprise accounts and channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as cloud deployment penetrates capital-constrained buyer segments previously locked out by perpetual license economics. Canada's tailings dam safety audits and the EU's CSRD mandates accelerate replacement demand for legacy telemetry systems.
For Market Incumbents: Fortify platform stickiness through deeper sensor-to-software integration that raises switching costs for mining operators with heterogeneous fleet ages. Expand API development capacity to capture retrofit demand from brownfield operations in Western Australia's Pilbara. The threat of modular cloud entrants undercutting on maintenance margins demands defensive moves toward outcome-based pricing tied to operational KPIs. For New Entrants and Emerging Players: Lead with narrow-vein dispatch specialization for mid-tier contractors in Chile's copper belt, where incumbent platform bundles overserve operational complexity needs. Saskatchewan's potash corridor presents adjacent white-space demand for solution mining planning tools with minimal competitive saturation. A consumption-linked go-to-market model tied to production volumes bypasses capital approval barriers that stall perpetual license procurement. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors geological modeling specialists with implicit surface reconstruction IP over dispatch pure-plays facing hardware commoditization. Long-term viability hinges on embedding sustainability disclosure automation into core planning workflows. The signal to watch is regulatory adoption velocity for Scope 3 emissions traceability mandates across copper concentrate supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies geological modeling with fleet dispatch for multi-asset mining companies in Australia. |
| Acquisition of Specialist Firm | Captures implicit modeling IP for copper-gold porphyry resource estimation in Chile. |
| Geographic Expansion | Establishes cloud data residency for EU CSRD compliance across Scandinavian mining operations. |
| Strategic Partnership | Links edge computing hardware with dispatch algorithms for underground connectivity constraints. |
| Product Launch | Introduces carbon calculator modules for automated Scope 3 reporting in copper logistics. |
Study Parameters
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings on compliance-driven procurement patterns. Mine planning directors, IT procurement officers at mid-tier contractors, geological modeling specialists, and tailings dam safety auditors provided operational context. Secondary sources include dam safety audit reports from Canadian regulators, EU CSRD implementation guidance, SEC climate disclosure filings, and vendor technical documentation. Bottom-up demand estimation from deployment architecture adoption patterns triangulates against top-down market sizing from vendor revenue disclosures.
Sensitivity analysis around cloud migration velocity and regulatory enforcement timelines shapes the projection framework across the analysis window. Segmentation dimensions modeled include deployment architecture, end-user archetype, product functional category, and regional regulatory cluster. CAGRs derive from fitted adoption curves calibrated to historical software procurement cycles in adjacent industrial verticals. Forecast inputs incorporate copper price volatility effects on exploration budgets and tailings dam incident frequency as compliance urgency drivers.
The analysis sits within stated boundaries; outcomes outside sustained commodity price support for copper and gold exploration would require recalibration. Forecasts reflect assumptions on regulatory enforcement consistency and hyperscaler infrastructure expansion timelines. Revision becomes warranted when cloud adoption rates among junior miners cross thresholds that accelerate perpetual license obsolescence beyond modeled parameters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Banking Team Collaboration Software Market
Software & Services
Global Database Software Market
Software & Services
Global Application Platform Market
Software & Services
Simulation Software Market
Software & Services
Server Virtualization Software Market
Software & Services
Inventory Management Software Market
Software & Services
Software Containers Market
Software & Services
Embedded Operating Systems Market
Software & Services
Mobile Application Testing Services (MATS) Market
Software & Services
Saas-Based Expense Management Market
Software & Services
Global Voip Software Market
Software & Services
Camp Management Software Market
Software & Services
North America Equity Management Software Market
Software & Services
Global Board Management Software Market
Software & Services
Global App Builder Software Market
Software & Services
Global Brain Training Software Market