
 DTH Drill Market | 2026-2036
DTH Drill Market Size, Share, and Industry Trends Forecast 2026-2036
DTH Drill Market Analytics
ISO 18758 certification for rock drilling equipment is unwinding the competitive field, forcing smaller manufacturers to absorb testing costs or exit tender pools. Sandvik leverages its captive metallurgy division to control tungsten carbide supply for premium bit inserts. Atlas Copco sustains service density through a regional parts hub network across Scandinavia and the Baltics. Epiroc anchors its position in automation-ready hammer designs that interface with teleoperation platforms.
A down-the-hole drill transmits percussive energy through a piston-driven hammer located at the bit face, operating at blow frequencies of 25–35 Hz and air pressures between 17–24 bar to fracture competent rock formations. The tool serves primary blasting, water well completion, and geotechnical investigation where rotary methods lack penetration rates. Hammers and bits command the majority of replacement revenue as consumable wear items with predictable replacement cycles. Blast hole applications absorb the largest equipment volume as open-pit miners prioritize bench drilling productivity. Pneumatic technology retains dominance in remote sites lacking hydraulic infrastructure, though hydraulic systems gain share where fuel efficiency regulations tighten.
MSHA ventilation standards in the United States and REACH substance restrictions in Europe constrain lubricant formulations and elastomer specifications for hammer seals. EPA Tier 4 Final emissions rules elevate compressor costs for pneumatic rigs, shifting procurement criteria toward total cost of ownership. ISO 18758 and national mining inspectorates in Brazil and South Africa impose periodic recertification burdens on importers. Stakeholders must track how diesel-hybrid compressor architectures evolve against underground electrification mandates and whether battery-powered hammers emerge as viable alternatives in methane-sensitive workings.
Market Dynamics
Pneumatic DTH systems face a structural squeeze as EPA Tier 4 Final compressor costs and underground electrification mandates in mining jurisdictions force capital planners to reassess total cost of ownership against emerging battery-hammer alternatives.
Growth Catalysts
- Copper belt expansion:Peru's open-pit operators are scaling blast hole drilling to feed smelter expansions, pulling premium hammer capacity toward South American logistics hubs.
- ISO 18758 certification:The rock drilling equipment standard is consolidating tender pools by disqualifying uncertified suppliers from Australian and South African mine procurement cycles.
- Automated rig integration:Underground mines in Chile are retrofitting teleoperation interfaces to existing hammer fleets, preserving capital while capturing productivity gains.
Market Restraints
- Tungsten carbide supply concentration:Captive metallurgy capabilities at major integrated manufacturers lock independent bit producers into spot market carbide pricing with volatile pass-through terms.
- REACH elastomer restrictions:ECHA substance limitations on seal compounds force reformulation cycles that extend hammer rebuild intervals and complicate aftermarket parts planning.
- Compressed air infrastructure dependency:Remote sites lacking grid-connected compressor stations absorb diesel fuel cost volatility that hydraulic alternatives sidestep through direct engine power.
Strategic Opportunities
- Water well completion:Arid climate adaptation programs in Australia's Murray-Darling basin are expanding DTH penetration for deep aquifer access beyond traditional mining demand.
- Battery-hammer convergence:Methane-sensitive workings in Poland's hard coal sector are piloting cordless percussion units that eliminate compressor ventilation burdens.
- Parts hub localization:Epiroc's Scandinavian distribution model offers a template for regional service density in underpenetrated Central Asian mining frontiers.
Industry Challenges
- Teleoperation skill gaps:Mine operators in South Africa's platinum reefs struggle to source drill rig technicians cross-trained in automation system diagnostics and mechanical hammer maintenance.
- Recertification timeline compression:Brazil's national mining inspectorate demands periodic ISO 18758 renewal cycles that disrupt import logistics and strain documentation resources at smaller distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DTH Drill Market |
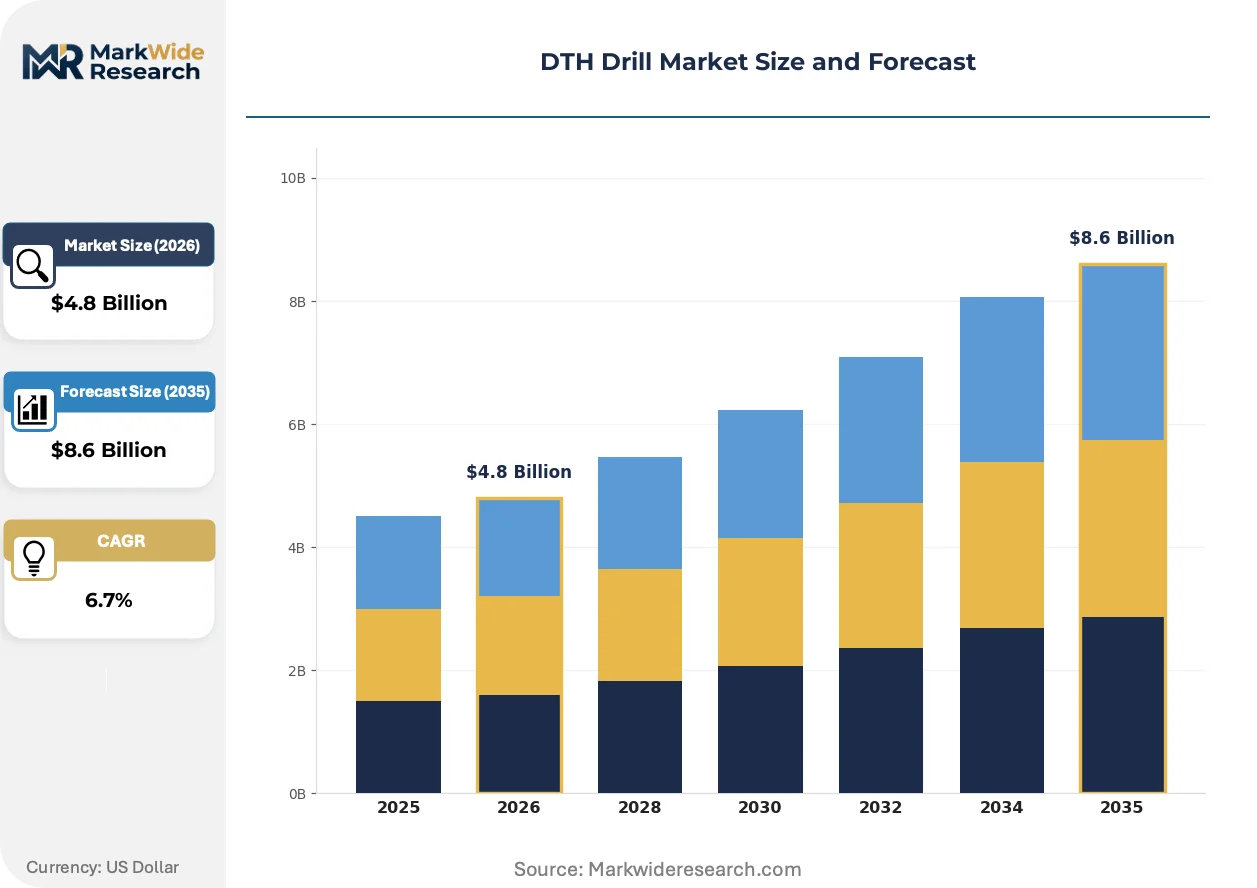
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hammers, Bits, Accessories, Compressors End User: Mining, Construction, Oil & Gas, Water Well Technology: Pneumatic, Hydraulic, Electric, Mechanical Application: Blast Hole, Geotechnical, Exploration, Foundation |
| Companies Covered | Sandvik, Atlas Copco, Epiroc, Boart Longyear, Mincon, Halco Rock Tools, Numa, Rockmore, Drill King, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DTH Drill Market Evolving Landscape
Hammer technology is splitting along automation-readiness lines as manufacturers place diverging bets on pneumatic endurance versus electrification pathways, while regulatory pressure on diesel emissions accelerates equipment replacement cycles.
Hammer-bit interface standardization is bifurcating the installed base. Premium automated rigs in Australian iron ore operations demand quick-change bit systems with embedded wear sensors, while legacy pneumatic fleets in remote Indonesian nickel sites retain threaded shank designs to maximize inventory fungibility. The specification gap is compressing aftermarket parts interoperability and forcing distributors to carry dual SKU sets.
EPA Tier 4 Final emissions rules are elevating diesel compressor capital costs by fifteen to twenty-five percent for pneumatic rig operators. Open-pit contractors in Arizona's copper districts are responding by extending rebuild intervals on existing compressors rather than accepting new equipment procurement cycles, deferring fleet turnover and compressing hammer replacement revenue timing.
Service contract unbundling is disrupting traditional distributor economics. Large mining houses in Chile's Atacama region are separating hammer rebuild services from parts supply, awarding labor contracts to specialized workshops while sourcing consumables through direct manufacturer agreements. The disintermediation is visible most acutely in high-volume blast hole operations where volume scale justifies captive maintenance capabilities.
DTH Drill Market Segmentation
DTH drill procurement patterns diverge sharply across equipment categories, with substitution pressures from electrification and automation reshaping capital allocation. Understanding segment-level vulnerability to technology displacement guides supplier positioning and inventory planning.
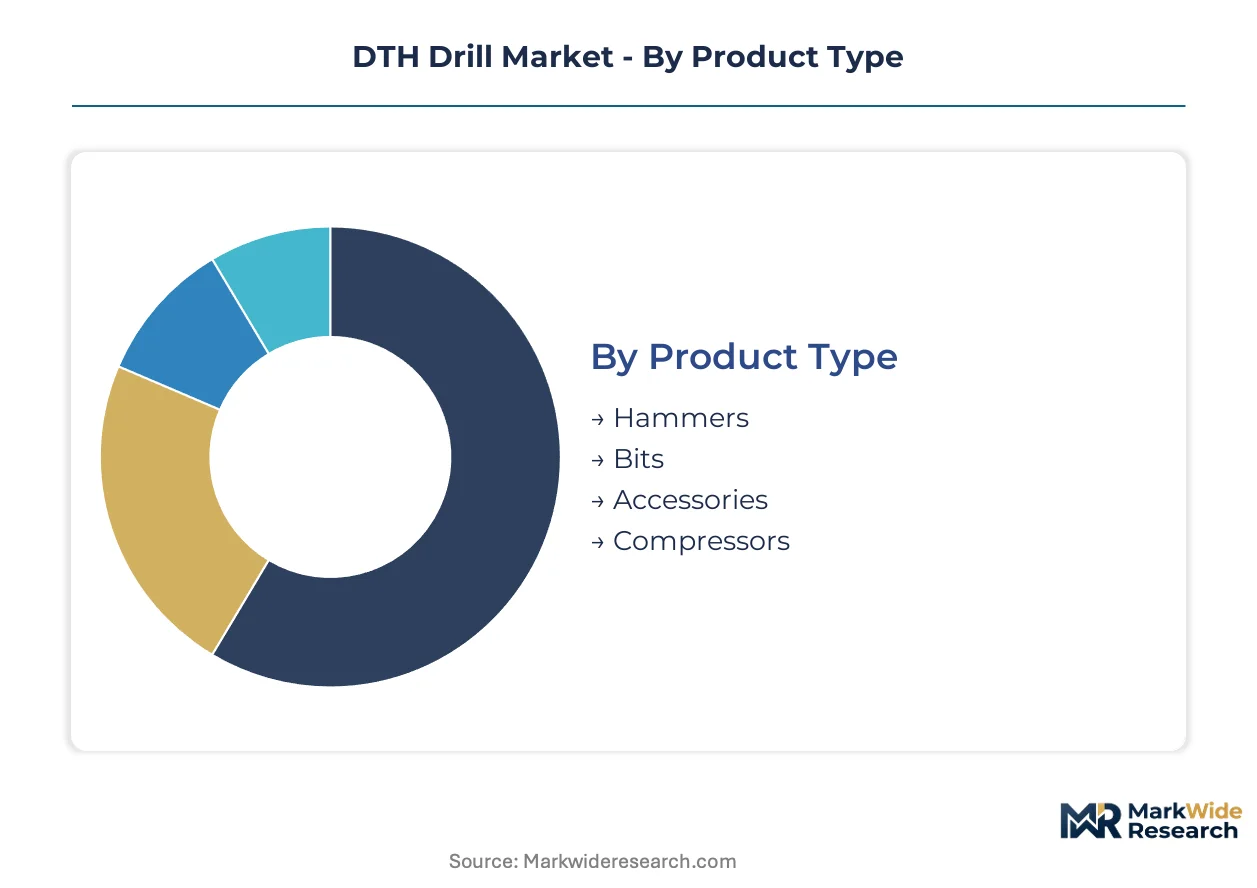
Product Type:
Hammers and bits face intensifying substitution pressure from battery-powered alternatives and quick-change automation interfaces, while compressors absorb regulatory cost shocks from emissions compliance.
- Hammers:Piston-driven percussive units operating at 25–35 Hz blow frequencies transmit energy directly to the bit face. Australian underground mines and Chilean copper operations are retrofitting teleoperation-ready hammer designs to preserve capital while capturing automation productivity gains.
- Bits:Tungsten carbide insert configurations dominate competent rock penetration, with captive metallurgy capabilities at integrated manufacturers locking independent producers into volatile spot market carbide pricing. Peru's open-pit copper belt and South Africa's platinum reefs absorb the largest premium bit volumes for blast hole applications.
- Accessories:Drill rods, shank adapters, and coupling sleeves complete the down-hole string assembly.
- Compressors:Diesel-powered air supply units face EPA Tier 4 Final cost escalation of fifteen to twenty-five percent, pushing Arizona copper contractors toward extended rebuild intervals rather than new equipment procurement.
Hammers retain volume leadership; bits hold the steepest expansion curve driven by predictable replacement cycles in high-volume mining operations.
End User:
Cost tier stratification separates capital-intensive mining procurement from price-sensitive construction contracting, with water well completion emerging as a climate-adjacent growth corridor.
- Mining:Open-pit and underground operations prioritize bench drilling productivity and automated rig integration. ISO 18758 certification requirements in Australia and South Africa are consolidating tender pools by disqualifying uncertified suppliers.
- Construction:Infrastructure and building foundation projects favor rental fleet economics and threaded shank compatibility for inventory fungibility.
- Oil & Gas:Exploration and production drilling demands high-pressure pneumatic systems for deep formation penetration.
- Water Well:Arid climate adaptation programs in Australia's Murray-Darling basin are expanding DTH penetration for deep aquifer access beyond traditional extractive demand.
Mining commands absolute revenue share; water well completion is gaining share fastest as drought resilience infrastructure accelerates.
Technology:
Application-driven technology selection splits between remote sites lacking hydraulic infrastructure and regulated jurisdictions where fuel efficiency mandates favor direct engine power alternatives.
- Pneumatic:Compressed air systems retain dominance in remote Indonesian nickel sites and grid-disconnected frontiers where diesel fuel cost volatility is accepted for operational simplicity.
- Hydraulic:Direct engine power transmission sidesteps compressor infrastructure dependency and ventilation burdens, gaining share where EPA emissions rules tighten.
- Electric:Cordless percussion units are piloting in Poland's hard coal sector to eliminate compressor ventilation requirements in methane-sensitive workings.
- Mechanical:Rotary-percussive hybrid configurations serve specialized geotechnical investigation applications.
Pneumatic systems retain installed base dominance; electric technology is climbing the fastest as underground electrification mandates propagate.
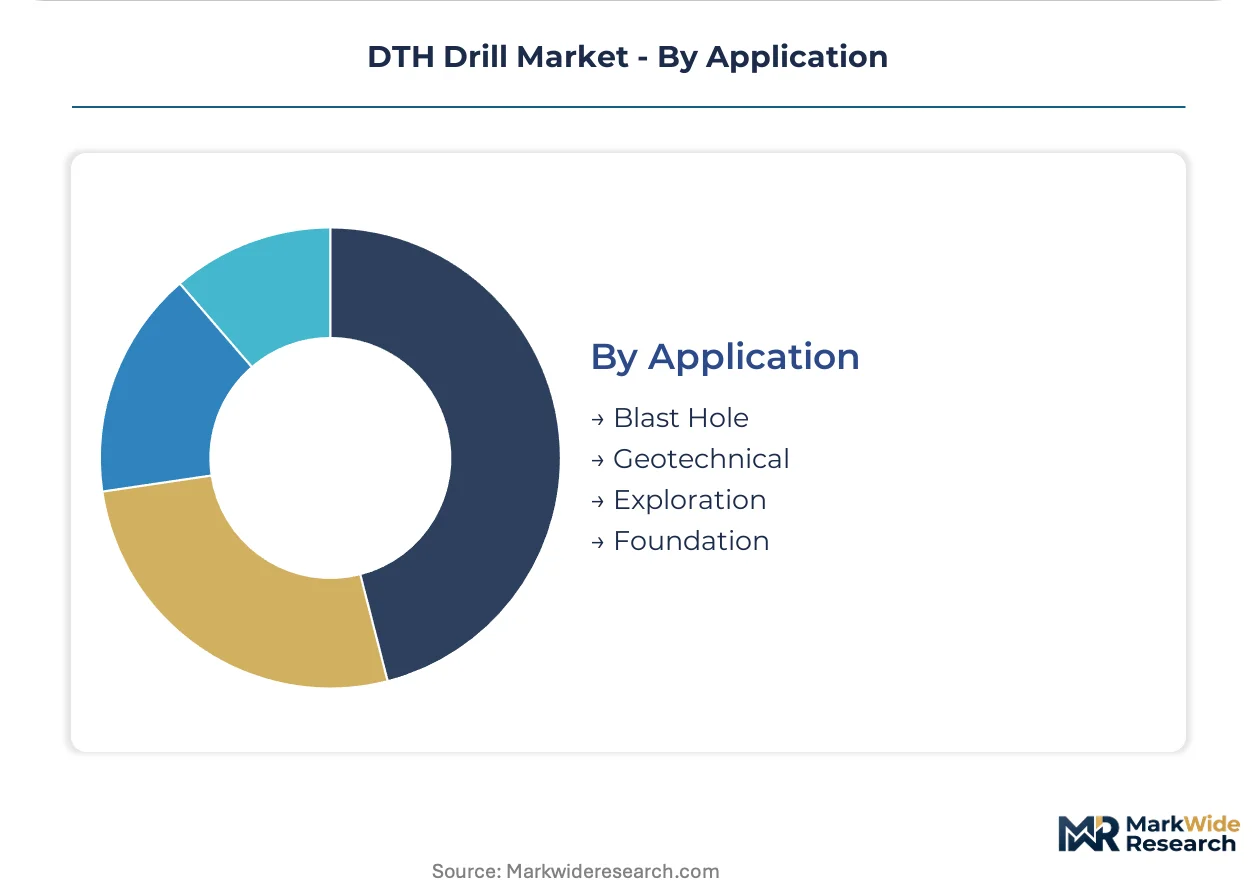
Application:
Volume concentration in blast hole drilling creates margin pressure from service contract unbundling, while specialized applications sustain premium pricing through technical complexity.
- Blast Hole:Primary bench drilling for open-pit fragmentation absorbs the largest equipment volume globally. Chilean mining houses are separating hammer rebuild services from parts supply, disintermediating traditional distributor economics.
- Geotechnical:Site investigation and slope stability assessment require precision penetration rates in varied formations.
- Exploration:Mineral resource definition drilling demands portable rig configurations for remote access.
- Foundation:Piling and ground improvement applications favor rental fleet flexibility and rapid mobilization.
Blast hole drilling retains volume leadership; geotechnical applications hold the steepest expansion trajectory as infrastructure resilience standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capital planners in open-pit copper and underground platinum operations drive procurement concentration across five mining-intensive economies. Regulatory pressure on diesel emissions and electrification mandates reshape equipment replacement timing in each jurisdiction.
Australia
Underground iron ore and gold producers in Western Australia retrofit teleoperation-ready hammer designs to preserve capital while capturing automation productivity gains. The country's national mining inspectorate enforces ISO 18758 recertification cycles that disqualify uncertified suppliers from tender pools. The Pilbara region concentrates blast hole drilling demand as Rio Tinto and BHP scale bench productivity programs.
Chile
State-owned Codelco and private operators in the Atacama Desert expand open-pit copper extraction to feed smelter capacity additions. The national mining regulator SERNAGEOMIN tightens ventilation standards for underground pneumatic equipment. Antofagasta anchors hammer replacement volume as mining houses unbundle service contracts from parts supply.
Peru
Southern Copper and Buenaventura scale blast hole drilling across the Andean copper belt to meet Chinese concentrate demand. The Ministry of Energy and Mines imposes periodic equipment inspection protocols aligned with ISO standards. The Arequipa region concentrates premium bit consumption as open-pit operators prioritize penetration rates in competent formations.
South Africa
Anglo American Platinum and Sibanye-Stillwater maintain reef drilling intensity in the Bushveld Complex despite electricity grid instability. The Department of Mineral Resources and Energy enforces ventilation requirements through the Mine Health and Safety Inspectorate. Rustenburg and Limpopo provinces concentrate automated rig retrofit demand as operators seek to reduce labor exposure in deep workings.
United States
Freeport-McMoRan and Barrick extend compressor rebuild intervals at Arizona copper operations to defer EPA Tier 4 Final compliance costs. The Mine Safety and Health Administration enforces ventilation standards that elevate total cost of ownership calculations for pneumatic fleets. The Southwest copper district concentrates equipment procurement as contractors balance fuel price volatility against hydraulic alternative capital requirements.
DTH Drill Market Competitive Landscape
Player mix skews toward integrated metallurgy-and-equipment conglomerates alongside specialized hammer-bit assemblers. The field consolidates around three tiers: captive tungsten carbide producers commanding premium bit pricing, automation-ready hammer designers interfacing with teleoperation platforms, and regional parts distributors absorbing ISO certification burdens. Strategic moves concentrate on backward integration into carbide supply and geographic expansion of service hub networks.
Within the integrated tier, Sandvik leverages captive metallurgy capabilities to control insert supply for premium bit configurations. Atlas Copco sustains regional service density through parts hub networks across Scandinavia and adjacent markets. Epiroc anchors automation-ready positioning through hammer designs engineered for teleoperation interfaces. These three exemplify divergent bets on pneumatic endurance versus electrification pathways.
| Leading Market Players |
|---|
| Sandvik |
| Atlas Copco |
| Epiroc |
| Boart Longyear |
| Mincon |
| Halco Rock Tools |
| Numa |
| Rockmore |
| Drill King |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between Chilean copper operators and hammer suppliers lock in tungsten carbide allocation and provide price visibility against spot market volatility. These contracts absorb EPA Tier 4 Final cost pass-throughs while insulating buyers from Australian ISO 18758 recertification surcharges.
Pricing Analysis
Cost-plus contracts with tungsten carbide indexation dominate hammer and bit procurement. Three-tier pricing structure across premium automation-ready, standard certified, and economy threaded-shank tiers separates Australian iron ore operators from Indonesian nickel contractors. Cost compression in the economy tier intensifies because diesel fuel volatility erodes pneumatic fleet operating margins. Construction rental fleets exhibit highest price sensitivity; mining houses with captive maintenance capabilities show lowest sensitivity due to unbundled service economics.
Supply Chain Analysis
Strait of Malacca transit underwrites carbide powder movement from Chinese metallurgy plants to Swedish manufacturing hubs. Supply concentration in Sweden, China, and Australia shapes hammer assembly and bit insert fabrication. Raw material dependencies center on tungsten ore, cobalt binder alloys, and high-grade tool steel forgings. Single-source vulnerability runs through Sandvik's captive carbide production. Distribution runs through regional parts hubs in Scandinavia, Chile, and Western Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. ISO 18758 certification requirements create switching costs that lock mining operators into qualified supplier relationships.
For Market Incumbents: Fortify automation-ready hammer portfolios against battery-powered substitution threats in methane-sensitive workings. Deepen backward integration into carbide supply to neutralize spot price volatility. Expand Scandinavian-style parts hub density into Central Asian mining frontiers to preempt service contract unbundling. For New Entrants and Emerging Players: Lead with water well completion equipment targeting Australia's Murray-Darling basin drought adaptation programs. The most penetrable segment lies in cordless percussion pilots for Poland's hard coal sector. Pursue direct manufacturer agreements with mining houses that have separated parts supply from rebuild services. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among distributors with ISO 18758 certification capabilities and regional parts hub networks. Long-term viability favors acquisition targets with automation interface engineering and captive metallurgy access. Watch battery-hammer pilot results in Polish underground workings as electrification inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbide Supply | Sandvik's metallurgy division secures insert quality and insulates margins from cobalt price swings. |
| Automation Interface Engineering | Epiroc's teleoperation-ready hammer designs capture Chilean retrofit demand without full fleet replacement. |
| Regional Parts Hub Expansion | Atlas Copco's Scandinavian distribution model reduces downtime costs for Australian iron ore operators. |
| ISO 18758 Certification Investment | Certified suppliers qualify for South African and Australian mine tenders that exclude uncertified competitors. |
| Battery-Hammer Pilot Deployment | Cordless percussion trials in Poland's methane-sensitive workings test compressor elimination viability. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of MSHA ventilation directives, EPA emissions filings, and ISO certification databases. Interviews with maintenance directors at open-pit copper operations, aftermarket service heads at Scandinavian distributors, and procurement leads at Australian iron ore producers inform demand-side dynamics. Trade flow data from Swedish export statistics, Chilean mining ministry equipment registries, and South African mineral resources inspection records provide supply-side validation. Bottom-up equipment unit estimates and top-down mining capex allocations triangulate market sizing.
Segmentation dimensions modeled include product type, end user industry, technology architecture, application method, and regional regulatory cluster across the analysis window. CAGRs derive from equipment replacement cycle analysis, automation adoption curves, and electrification mandate propagation patterns. Forecast inputs incorporate tungsten carbide price trajectory assumptions and compressor fleet turnover timing under EPA Tier 4 Final compliance costs.
Forecasts assume regulatory continuity in EPA emissions enforcement and ISO 18758 certification regimes; material policy shifts would require re-modeling. Technology displacement risk from battery-powered alternatives and underground electrification mandates could accelerate or delay hammer replacement cycles. Practitioners should keep alternative scenarios live as electrification pilot results and carbide supply concentration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Mining Machinery Battery Market
Mining Equipment
Smart Mining Technologies Market
Mining Equipment
Mining Drill Market
Mining Equipment
Mine Ventilation System Market
Mining Equipment
Mine Scaler Market
Mining Equipment
Crawler Drill Rig Market
Mining Equipment
Global Underground Mining Loader Market
Mining Equipment
Mining Tester Market
Mining Equipment
Hydraulic Drilling Rig Market
Mining Equipment
Stone Mining and Quarrying Market
Mining Equipment
Global Autonomous Mining Equipment Market
Mining Equipment
Autonomous Mining Truck Market
Mining Equipment
Mining Machinery Market
Mining Equipment
Mining Equipment Market
Mining Equipment
Global Automated Mining Equipment Market
Mining Equipment
Global Large Mining Shovels Market