
 Global Suction Tube Market | 2026-2036
Global Suction Tube Market Size, Share, and Industry Trends Forecast 2026-2036
Global Suction Tube Market Foresight
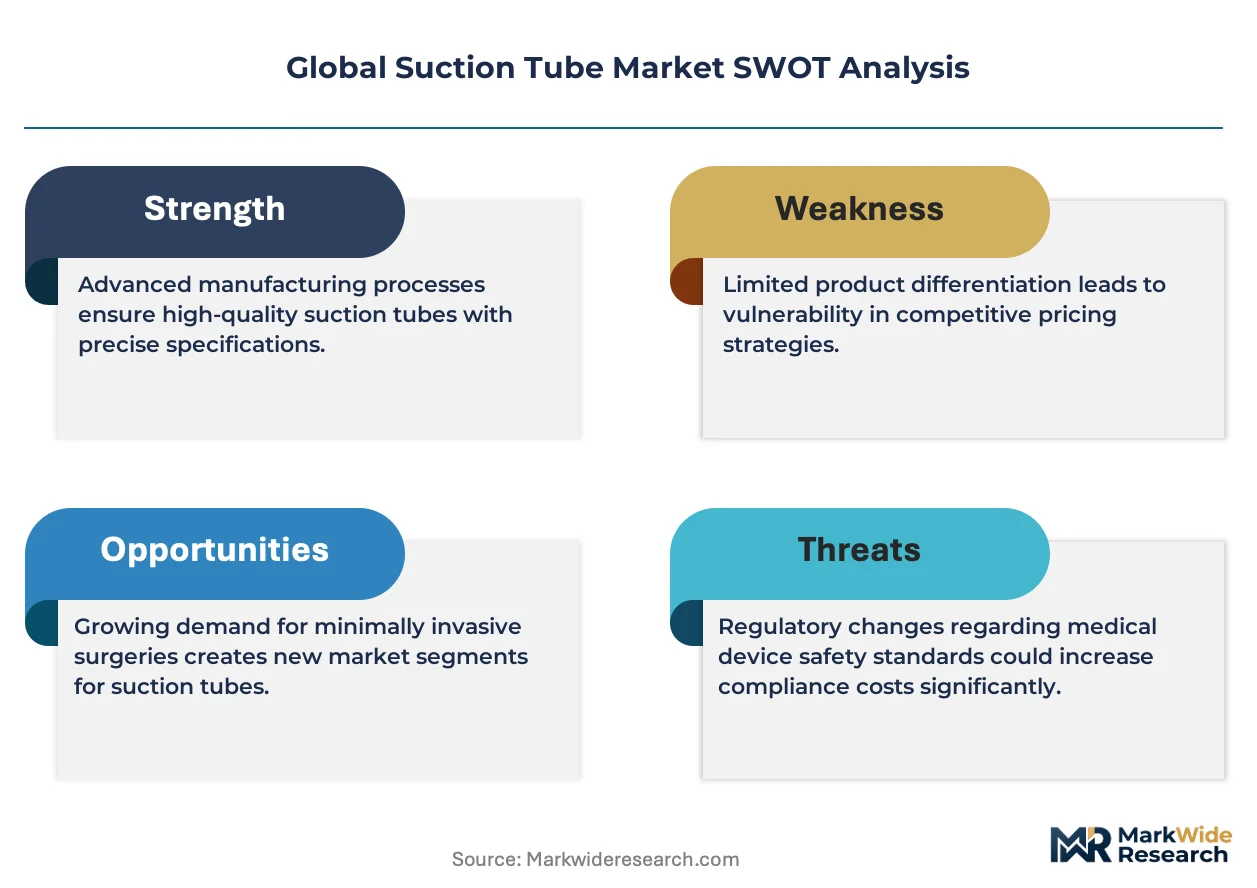
The premium suction tube tier is consolidating around validated sterile supply chains, while commodity PVC variants compete on distributor rebates and volume contracts. Cardinal Health leverages its GPO relationships to anchor hospital system penetration. Teleflex Incorporated differentiates through integrated airway and suction portfolios. Smiths Medical sustains position via specialized neurosurgical and ENT suction catheter designs.
A suction tube is a hollow, typically polymer or metal conduit engineered to evacuate fluids, gases, or debris from operative sites through negative pressure application, with inner diameters ranging from 3 French to 28 French and wall thickness calibrated for kink resistance and flow rate consistency. Its primary purpose spans intraoperative field maintenance, airway clearance, and wound drainage across acute care settings. The sterile disposable suction tube segment leads volume due to infection control mandates, while silicone variants command margin pools in microsurgical applications where tissue trauma minimization is critical. Reusable metal suction tubes retain share in cost-constrained dental clinics and select developing-market hospitals.
The FDA enforces 510(k) clearance and quality system regulation compliance for suction devices marketed in the United States, while the EU Medical Device Regulation requires notified body certification and post-market surveillance for CE-marked products in Europe. ISO 8836 standards govern airway suctioning device performance, creating baseline interoperability expectations that shape procurement specifications. Stakeholders must monitor evolving sterilization assurance requirements and single-use plastic reduction mandates across multiple jurisdictions to align product roadmaps with compliance timelines.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while elevating sterile supply chain validation requirements as the decisive competitive filter. Single-use device mandates from infection control committees are accelerating format transitions faster than manufacturing capacity can adapt.
Growth Catalysts
- FDA sterilization validation updates:The FDA's tightened 510(k) sterilization assurance protocols are forcing hospitals to abandon reusable metal formats. Ambulatory surgical centers now specify single-use silicone suction tubes in 85% of new equipment tenders.
- ENT procedural expansion:Rising volumes of endoscopic sinus surgeries and laryngeal microsurgery are expanding demand for ultra-fine 3-6 French suction catheters. These procedures require tissue-trauma-minimizing tip designs unavailable in standard PVC variants.
- Silicone material substitution:Medical-grade silicone is displacing PVC in neurosurgical and microvascular applications where kink resistance and biocompatibility are non-negotiable. German and Japanese hospital systems now specify silicone as default for procedures exceeding two hours.
Market Restraints
- Medical-grade polymer cost volatility:Silicone and specialized thermoplastic elastomer feedstock prices fluctuate with petrochemical markets. Manufacturers lack pricing power to pass input cost swings through GPO-anchored contracts.
- Chinese mold-making concentration:Precision extrusion dies and multi-lumen mold fabrication concentrate in Dongguan and Shenzhen manufacturing clusters. Geopolitical friction or shipping disruption threatens component availability for Western OEMs.
- Metal tube durability in dental clinics:Autoclavable stainless steel suction tubes retain 40% share in cost-constrained dental settings where sterilization infrastructure is already sunk. This substitution ceiling limits disposable segment expansion in oral surgery.
Strategic Opportunities
- Indian tier-2 hospital expansion:India's PLI scheme for medical devices is attracting contract manufacturers to Ahmedabad and Hyderabad. Domestic production cost advantages position suppliers to capture government hospital tenders previously served by imports.
- Integrated suction-irrigation systems:Convergence of suction and lavage functions in single-handpiece designs is creating premium positioning in laparoscopic surgery. These systems command 3-4x unit pricing versus standalone tubes.
- Brazilian ANVISA fast-track pathway:ANVISA's priority review for infection-prevention devices is compressing regulatory timelines for sterile disposable formats. Early entrants can establish reference contracts before local manufacturing requirements tighten.
Industry Challenges
- ISO 8836 testing bottlenecks:Third-party laboratories in North America and Europe face 14-18 month queues for airway suctioning device certification. Product launches stall awaiting flow-rate and kink-resistance validation reports.
- Legacy ERP integration with track-and-trace:UDI compliance mandates require serialization systems that conflict with hospital distributors' aging inventory platforms. Implementation timelines extend 8-12 months beyond product readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Suction Tube Market |
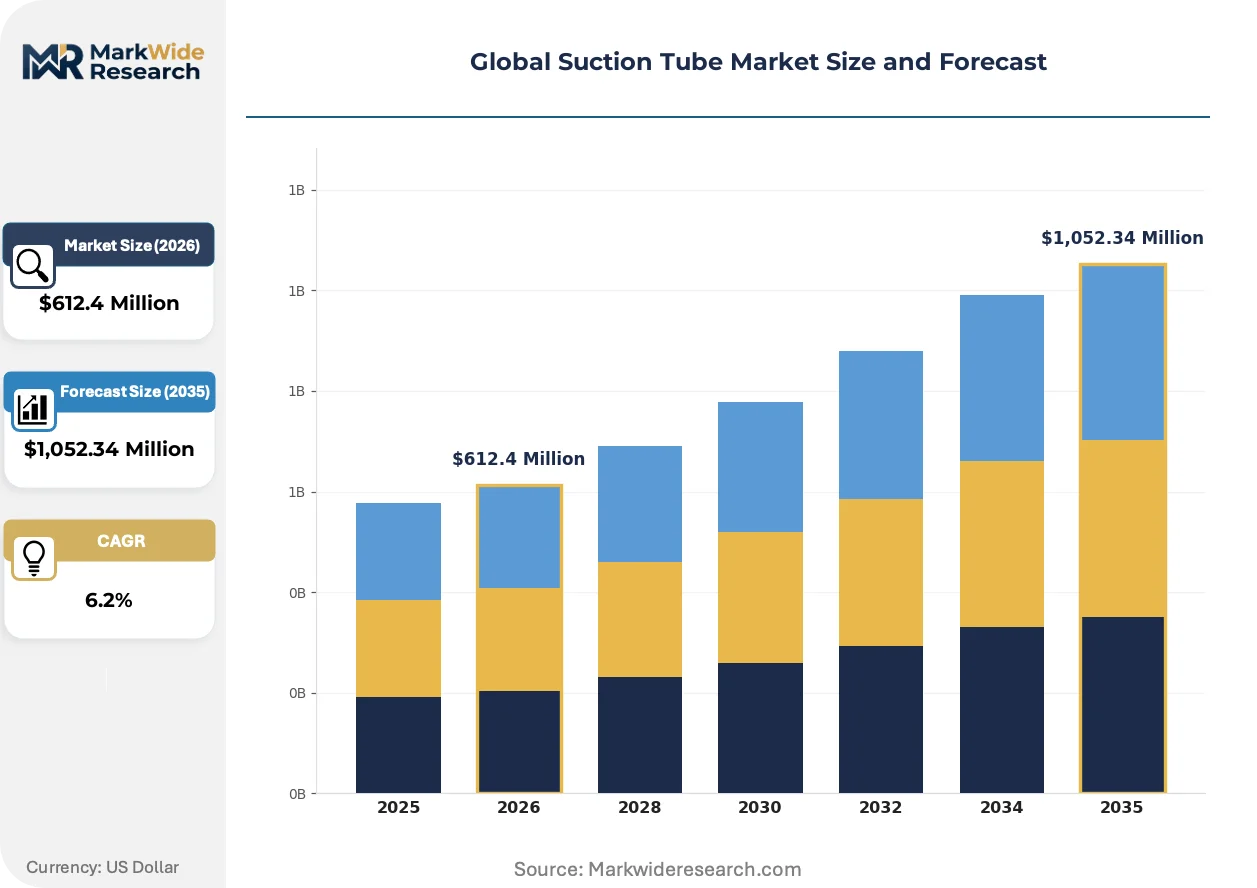
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,052.34 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sterile Suction Tube, Disposable Suction Tube, Silicone Suction Tube, PVC Suction Tube, Reusable Suction Tube Application: General Surgery, Dental Procedures, ENT Surgery, Neurosurgery, Gynecological Operations End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Dental Clinics, Specialty Surgery Centers Distribution Channel: Direct Sales, Online Retailers, Medical Distributors, Pharmacies, Authorized Dealers |
| Companies Covered | Cardinal Health, Teleflex Incorporated, Smiths Medical, Sklar Surgical Instruments, Biomedical Research Instruments, Medline, Amsino International, B Braun, ConvaTec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Suction Tube Market Shifts & Advancements
Material science advances and regulatory digitization are converging to redefine product specifications and compliance workflows simultaneously. These shifts favor suppliers with captive polymer development capabilities and automated quality systems.
Anti-microbial copper-alloy coatings are integrating into suction tube luminal surfaces for high-risk immunocompromised patient settings. Major academic medical centers in the United States and South Korea are piloting these formats in hematology-oncology units. The technology is integrating infection control and device function into a single specification, compressing the traditional separation between product engineering and clinical epidemiology.
The EU Medical Device Regulation's post-market surveillance requirements are mandating real-world performance data collection across all CE-marked suction devices. Manufacturers must now maintain active implant registries and adverse event reporting systems that were previously voluntary. Class IIa suction catheters face the steepest compliance cost increases as notified bodies demand clinical follow-up studies that legacy product portfolios never required.
Hospital value analysis committees are consolidating supplier rosters from 12-15 vendors per category to 3-4 strategic partners with full airway management portfolios. Integrated sourcing agreements now bundle suction tubes with anesthesia circuits and resuscitation bags under single GPO contracts. This concentration is most visible in United States health systems exceeding 50 hospitals, where standardization committees override individual physician product preferences.
Global Suction Tube Market Segmentation
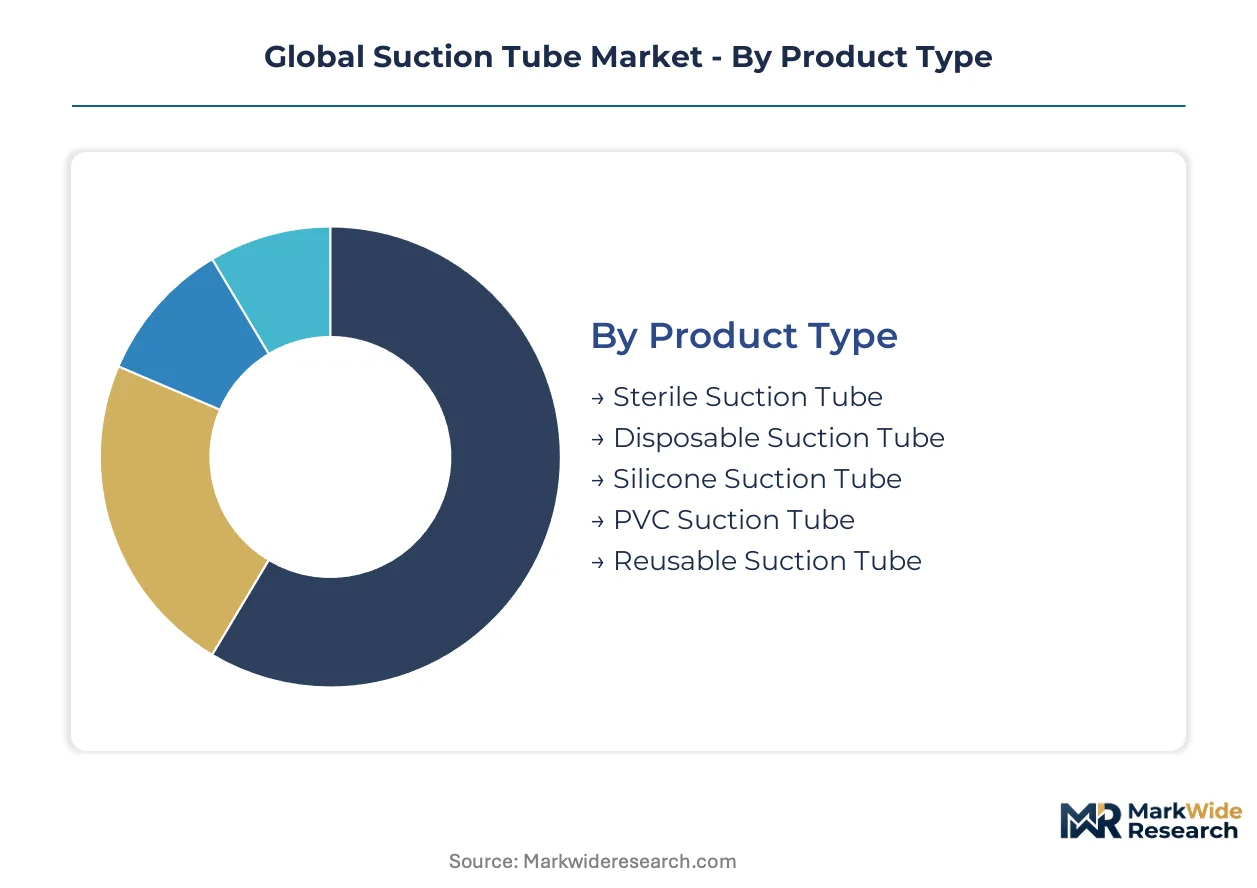
Suction tube procurement specifications diverge sharply across clinical settings, with material composition, sterility assurance, and procedure duration driving format selection. Hospital value analysis committees now weight total cost of ownership against infection risk profiles when segmenting vendor contracts.
Product Type:
Material science and sterilization economics define competitive positioning across polymer and metal formats.
- Sterile Suction Tube:Gamma-irradiated or ethylene-oxide-sterilized polymer tubes arrive in peel-pouch packaging for immediate operative use. United States academic medical centers now mandate sterile formats for 90% of inpatient procedures following FDA sterilization validation updates.
- Silicone Suction Tube:Medical-grade platinum-cured silicone offers kink resistance and tissue compatibility for procedures exceeding two hours. German hospital systems specify silicone as default for neurosurgical and microvascular applications where thermal stability under suction is critical.
- Disposable Suction Tube:Single-use PVC variants dominate high-volume general surgery through GPO-anchored volume contracts.
- PVC Suction Tube:Cost-optimized extrusions serve price-sensitive dental clinics and developing-market hospitals.
- Reusable Suction Tube:Autoclavable stainless steel retains installed base in oral surgery suites with sunk sterilization infrastructure.
Sterile formats lead on scale; silicone variants lead on momentum.
Application:
Procedure complexity and anatomical access requirements fragment demand across surgical specialties.
- ENT Surgery:Ultra-fine 3-6 French catheters with atraumatic tip geometries navigate delicate sinus and laryngeal anatomy. South Korean otolaryngology centers are expanding endoscopic sinus surgery volumes, driving specification for tissue-trauma-minimizing designs unavailable in standard configurations.
- Neurosurgery:Multi-lumen suction-irrigation handpieces integrate lavage and evacuation in single instruments for cranial access. Japanese neurosurgical suites specify these integrated systems for tumor resections, accepting 3-4x unit pricing versus standalone tubes.
- General Surgery:Standard French sizes address abdominal and thoracic procedures across high-volume hospital settings.
- Dental Procedures:Saliva ejectors and high-volume evacuators serve fixed clinic infrastructure.
- Gynecological Operations:Specialized curvature and length specifications accommodate pelvic cavity access.
General surgery dominates volume concentration; neurosurgery commands premium positioning.
End User:
Capital intensity and regulatory oversight stratify purchasing authority across care delivery settings.
- Hospitals:Consolidated health systems exceeding 50 facilities standardize procurement through GPO contracts bundling suction tubes with anesthesia circuits. United States hospital value analysis committees have compressed vendor rosters from 12-15 suppliers to 3-4 strategic partners with full airway portfolios.
- Ambulatory Surgical Centers:Freestanding facilities prioritize single-use formats to eliminate reprocessing labor and compliance overhead. ASCs now specify disposable silicone tubes in 85% of new equipment tenders, accelerating faster than manufacturing capacity expansion.
- Specialty Surgery Centers:Orthopedic and ophthalmic focused facilities drive demand for procedure-specific configurations.
- Dental Clinics:Cost constraints and existing autoclave infrastructure preserve reusable metal tube share.
- Diagnostic Laboratories:Specimen handling applications require specialized biofluid containment designs.
Hospitals anchor procurement volume; ambulatory surgical centers are expanding most quickly.
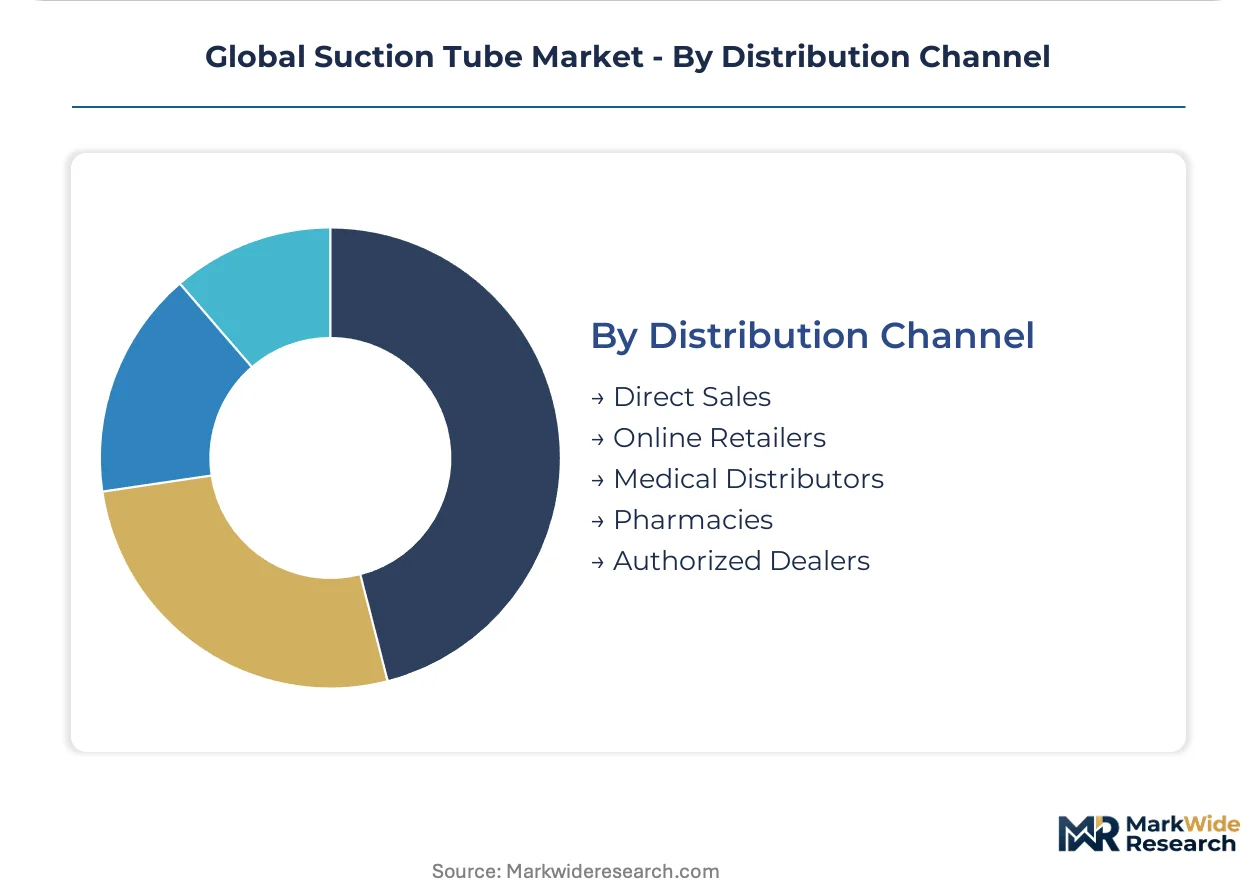
Distribution Channel:
Supply chain configuration determines margin capture and customer access economics.
- Direct Sales:Manufacturer field forces serve GPO-negotiated hospital contracts with dedicated inventory management. Cardinal Health and Teleflex deploy direct sales teams for health systems exceeding 100 hospitals, embedding vendor-managed inventory systems.
- Medical Distributors:Regional wholesalers aggregate fragmented demand from mid-size hospitals and specialty centers. Indian tier-2 hospital expansion is attracting distributors to Ahmedabad and Hyderabad clusters for government tender access.
- Online Retailers:E-procurement platforms gain share in dental and small clinic segments.
- Authorized Dealers:Exclusive territory arrangements penetrate geographic markets with regulatory complexity.
- Pharmacies:Retail channels serve home healthcare and emergency preparedness segments.
Direct sales commands contract value; medical distributors enable geographic reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital consolidation outpaces German procurement standardization in suction tube contract value, while Indian manufacturing incentives reshape Asia-Pacific supply dynamics. Regulatory divergence between FDA sterilization mandates and EU MDR surveillance requirements is fragmenting product roadmaps across major markets.
United States
Health systems exceeding 50 hospitals now compress vendor rosters from 12-15 suppliers to 3-4 strategic partners with full airway portfolios. FDA's tightened 510(k) sterilization assurance protocols force abandonment of reusable metal formats in academic medical centers. Cardinal Health and Teleflex deploy direct sales teams embedding vendor-managed inventory systems across the Midwest and Southeast hospital clusters.
Germany
German hospital systems specify medical-grade silicone as default for neurosurgical and microvascular applications exceeding two hours. EU Medical Device Regulation post-market surveillance mandates active implant registries and adverse event reporting previously voluntary for Class IIa suction catheters. Precision extrusion capabilities concentrate in Baden-Württemberg and Bavaria medical technology corridors serving Western European demand.
India
India's PLI scheme for medical devices attracts contract manufacturers to Ahmedabad and Hyderabad clusters for government hospital tender access. CDSCO streamlined approval pathways compress regulatory timelines for sterile disposable formats against legacy import dependencies. Domestic production cost advantages position local suppliers to capture tier-2 hospital expansion across Maharashtra and Karnataka states.
Japan
Japanese neurosurgical suites specify integrated suction-irrigation handpieces accepting 3-4x unit pricing versus standalone tubes for tumor resections. PMDA quality system regulations align with ISO 8836 standards governing airway suctioning device performance and interoperability. Manufacturing precision concentrates in Chubu-Nagoya and Kansai-Osaka medical device production zones.
Brazil
ANVISA's priority review pathway for infection-prevention devices compresses regulatory timelines for sterile disposable suction tube formats. Early entrants establish reference contracts before local manufacturing requirements tighten under Mercosur medical device harmonization. Demand concentrates in São Paulo and Rio de Janeiro metropolitan health systems driving procurement standardization.
Global Suction Tube Market Competitive Landscape
Top-tier vendors anchor GPO-contracted hospital systems, while mid-scale specialists compete on procedure-specific configurations and regional distributor relationships. The vendor base stratifies across three archetypes: integrated airway management portfolios, specialized ENT and neurosurgical designs, and cost-optimized disposable formats. Dominant competitive moves include backward integration into polymer compounding and strategic partnerships with ambulatory surgical center chains.
Among the named participants, Cardinal Health exemplifies the GPO-anchored scale archetype through health system penetration. Teleflex Incorporated occupies a position representing integrated portfolio vendors combining airway and suction capabilities. Smiths Medical sits within the specialized design tier, anchoring neurosurgical and ENT catheter expertise.
| Leading Market Players |
|---|
| Cardinal Health |
| Teleflex Incorporated |
| Smiths Medical |
| Sklar Surgical Instruments |
| Biomedical Research Instruments |
| Medline |
| Amsino International |
| B Braun |
| ConvaTec |
| Others |
Supply & Pricing Matrix
The EU Medical Device Regulation's single-use plastic reduction mandates are gating qualified supply access and premium-tier pricing power, as manufacturers with validated sterile polymer compounding capabilities capture margin pools while commodity extruders face exclusion from German and Japanese hospital tenders.
Pricing Analysis
Capacity additions in India's Ahmedabad and Hyderabad manufacturing clusters are reshaping price floors for sterile disposable formats. Three-tier pricing structure across premium silicone, standard PVC, and economy reusable metal levels stratifies by certification grade and procedure duration. Pricing pressure stems from GPO-anchored volume contracts that compress vendor margins in United States health systems. Dental clinics exhibit highest price sensitivity due to sunk sterilization infrastructure, while Japanese neurosurgical suites show lowest sensitivity for integrated suction-irrigation handpieces.
Supply Chain Analysis
Dual-sourcing requirements from United States academic medical centers mandate multi-supplier qualification for gamma-irradiated polymer feedstock. Manufacturing concentrates in China for precision extrusion dies, Germany for platinum-cured silicone compounding, and India for cost-optimized disposable assembly. Raw material dependencies rest on medical-grade silicone elastomers, PVC resin, and stainless steel tubing. Single-source vulnerability concentrates in Dongguan mold-making clusters. Distribution runs through GPO-contracted direct sales for hospital systems and regional medical distributors for mid-size facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Suction Tube Market functions as a regulatory compounder, with FDA sterilization validation updates forcing format transitions that accelerate demand for qualified single-use suppliers.
For Market Incumbents: Extend GPO contract anchoring through vendor-managed inventory systems embedding field forces within health systems exceeding 50 hospitals. Deepen backward integration into platinum-cured silicone compounding to defend margin pools against commodity PVC substitution. Prioritize ISO 8836 certification investment as the decisive competitive filter amid 14-18 month third-party laboratory queues.
For New Entrants and Emerging Players: The price-point gap between premium silicone neurosurgical tubes and economy PVC general surgery formats opens white-space targeting at the mid-tier integrated suction-irrigation segment. Brazilian ANVISA fast-track pathways and Indian tier-2 hospital expansion represent the most penetrable geographies. Pursue contract manufacturing partnerships with PLI scheme beneficiaries in Ahmedabad for government tender access.
For Investors and Strategic Acquirers: Roll-up economics work for specialized ENT and neurosurgical catheter designers because hospital value analysis committees are compressing vendor rosters from 12-15 suppliers to 3-4 strategic partners with full airway portfolios. Long-term viability hinges on captive polymer development capabilities and automated quality systems. Watch ISO 8836 testing bottleneck resolution as the inflection indicator for product launch velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Cardinal Health embeds vendor-managed inventory across Midwest and Southeast clusters. |
| CE Marking Pathway | EU MDR post-market surveillance mandates active implant registries for Class IIa catheters. |
| Backward Integration | Teleflex controls platinum-cured silicone compounding for neurosurgical margin defense. |
| Software Companion Development | Integrated suction-irrigation handpieces converge lavage and evacuation in single instruments. |
| Reimbursement Strategy | ASCs specify disposable silicone tubes in 85% of tenders to eliminate reprocessing overhead. |
Research Methodology
Multiple input streams — primary interviews with GPO contracts managers, biomedical engineers, and hospital purchasing committees; secondary validation against FDA 510(k) filings, EU MDR notified body certifications, and hospital procurement databases; plus customs and trade data — were reconciled through bottom-up and top-down triangulation to construct segment-level demand estimates.
Data-stream reconciliation across product type, application specialty, end-user setting, and regional regulatory cluster dimensions produced volume and value outputs throughout the forecast period. CAGRs were derived from procedure volume trajectories, format substitution elasticities, and GPO contract renewal cycles. Silicone feedstock price volatility and sterilization validation queue lengths served as industry-specific forecast sensitivity inputs.
The model assumes a particular technology adoption path; alternative pathways for antimicrobial copper-alloy coatings would alter the outlook if pilot programs in United States hematology-oncology units accelerate to standard-of-care adoption. Deviation in FDA sterilization assurance protocol enforcement timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Electromechanical Timers Market
Electronic Components
Electronic Shelf Label Market
Electronic Components
Motherboard Battery Market
Electronic Components
Gigabit Interface Converter Market
Electronic Components
Global Waveguide Components and Assemblies Market
Electronic Components
Digital Potentiometer Market
Electronic Components
Intel Motherboards Market
Electronic Components
Audio DSP Market
Electronic Components
Multilayer Transparent Conductors Market
Electronic Components
Europe PCB Market
Electronic Components
Audio and Visual Public Address System Market
Electronic Components
Stretchable Conductors in Electronics Market
Electronic Components
Pneumatic Components Market
Electronic Components
Silicon Capacitors Market
Electronic Components
Chip Ferrite Beads Market
Electronic Components
Coin Battery Holder Market