
 DNA Methylation Market | 2026-2036
DNA Methylation Market Size, Share, and Industry Trends Forecast 2026-2036
DNA Methylation Market Intelligence
Direct-to-researcher distribution channels is reshaping how epigenetic tools reach end users, bypassing traditional distributor markups for high-volume sequencing consumables. Illumina Inc. anchors the platform segment through captive instrument placements that lock in reagent pull-through. Thermo Fisher Scientific Inc. extends its position via integrated workflow bundles spanning sample prep through data analysis. QIAGEN N.V. specializes in standardized kit formats that reduce protocol variability across multi-site clinical studies.
DNA methylation denotes the enzymatic addition of methyl groups to cytosine residues at CpG dinucleotides, a heritable epigenetic modification that modulates gene expression without altering primary nucleotide sequence and serves as a stable biomarker for disease stratification and therapeutic response monitoring. The technology dimension shows sequencing platforms capturing the dominant share of instrument capital expenditure while bioinformatics tools experience the fastest expansion as data volumes overwhelm existing analysis pipelines. Within applications, oncology commands the largest absolute spending on methylation-based liquid biopsy development, whereas immunology represents an emerging frontier for transplant rejection monitoring and autoimmune profiling.
FDA oversight of laboratory-developed tests and companion diagnostic validation shapes product development roadmaps for assay manufacturers seeking clinical market access. The EPA regulates chemical reagent disposal standards that influence kit formulation decisions, while ISO 13485 certification requirements govern quality management systems for diagnostic-grade production facilities. Stakeholders must weigh the trade-off between pursuing decentralized point-of-care methylation testing versus centralized reference laboratory models as reimbursement frameworks crystallize.
Market Dynamics
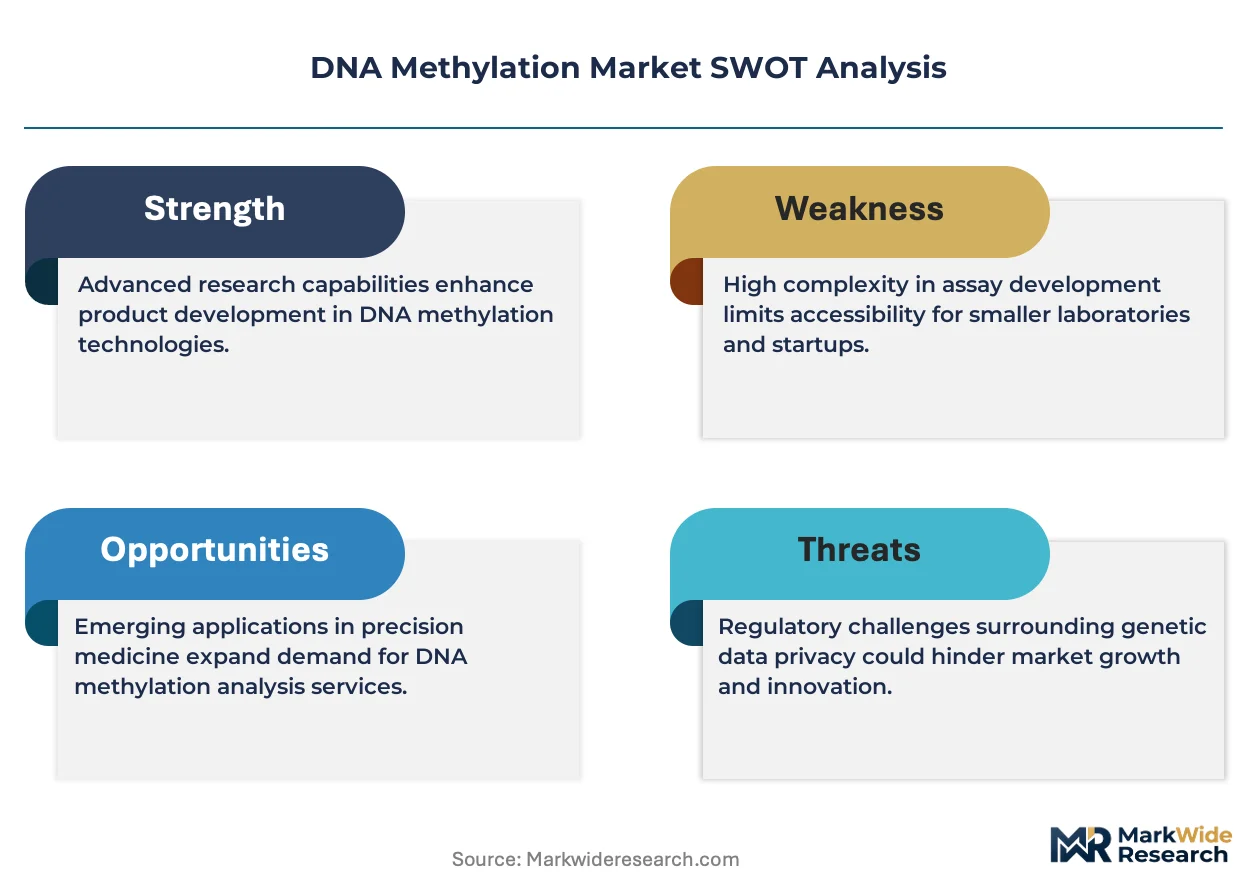
Sequencing platform concentration is compressing reagent margins while bioinformatics bottlenecks create service-layer value capture opportunities for specialized analytics providers.
Growth Catalysts
- FDA Liquid Biopsy Guidance:The FDA's expanded validation framework for companion diagnostics accelerates clinical translation timelines for methylation-based cancer screening assays.
- China Precision Medicine Initiative:Government-funded national biobank networks concentrate procurement demand for standardized methylation profiling kits across academic medical centers.
- Immunology Biomarker Expansion:Transplant rejection monitoring applications are pulling methylation platforms into clinical immunology workflows previously dominated by flow cytometry methods.
Market Restraints
- Illumina Instrument Lock-in:Captive reagent pull-through contracts on installed sequencing bases limit competitive entry for alternative platform developers.
- High-Purity Cytosine Derivative Costs:Sulfite conversion chemistry inputs exhibit price volatility tied to pharmaceutical-grade chemical supply chains.
- ISO 13485 Certification Burden:Diagnostic-grade quality management system requirements extend product development timelines by 18-24 months for clinical assay manufacturers.
Strategic Opportunities
- Point-of-Care Decentralization:Miniaturized methylation detection devices could penetrate community oncology clinics bypassing centralized reference laboratory bottlenecks.
- Autoimmune Disease Profiling:Systemic lupus erythematosus and rheumatoid arthritis represent underexplored application areas for cell-free DNA methylation signatures.
- Cloud-Native Bioinformatics:Converging AI-driven variant calling with scalable cloud compute infrastructure collapses analysis costs for multi-terabyte methylation datasets.
Industry Challenges
- Bioinformatics Talent Scarcity:Cross-trained computational biologists with epigenetic domain expertise command premium compensation in competitive labor markets.
- Multi-Site Protocol Standardization:Cross-center methylation data comparability requires harmonized sample collection, processing, and storage procedures that resist easy implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DNA Methylation Market |
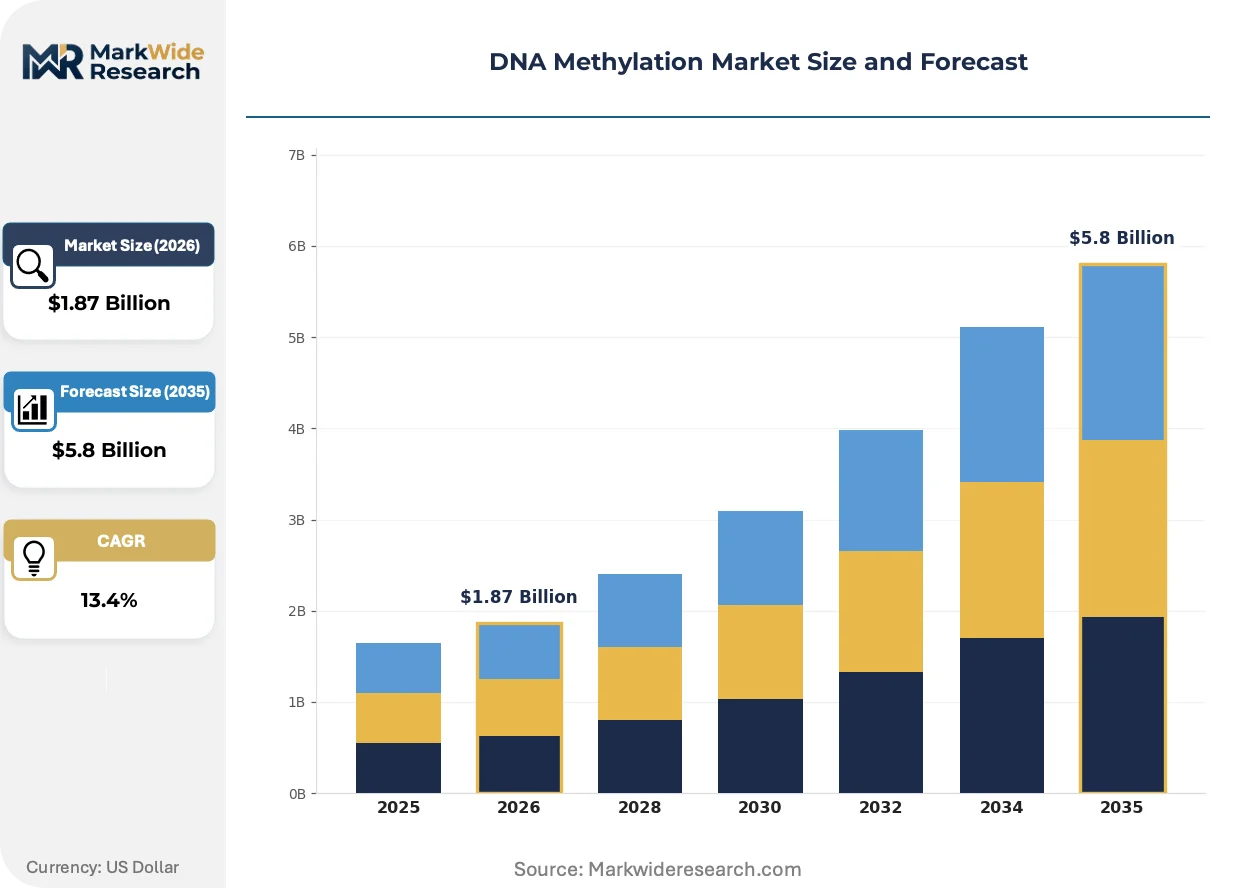
| Market Size in 2026 | $1.87 Billion |
| Market Size in 2035 | $5.8 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Kits, Platforms, Consumables Application: Oncology, Neurology, Cardiology, Immunology Technology: Sequencing, PCR, Mass Spectrometry, Bioinformatics End User: Academic Institutions, Pharmaceutical Companies, Research Organizations, Diagnostic Labs |
| Companies Covered | Illumina Inc., Thermo Fisher Scientific Inc., QIAGEN N.V., Agilent Technologies Inc., F. Hoffmann-La Roche Ltd, New England Biolabs, Abcam Limited, Bio-Rad Laboratories Inc., Zymo Research Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DNA Methylation Market Strategic Shifts & Innovations
Third-generation sequencing modalities and regulatory clarity on liquid biopsy validation are reshaping competitive positioning across the methylation detection value chain.
Long-read sequencing platforms from Pacific Biosciences and Oxford Nanopore Technologies are collapsing the cost-per-base for whole-genome methylation analysis previously dominated by short-read Illumina workflows. Academic consortia in the United States and United Kingdom are adopting these systems for de novo epigenome assembly projects. The structural consequence is compressing the addressable market for targeted methylation array products in research applications.
The FDA's 2023 guidance on tumor-informed minimal residual disease testing establishes precedent for methylation-based assay validation pathways. Clinical laboratories are restructuring quality management systems to accommodate prospective sample collection requirements. Oncology diagnostic developers in the United States face compressed timelines to secure premarket approval before reimbursement codes crystallize.
Direct-to-researcher distribution channels are displacing traditional distributor networks for high-volume sequencing consumables. Illumina's online marketplace and Thermo Fisher's e-procurement portals capture institutional purchasing volume previously flowing through regional life science distributors. This channel shift is most visible in North American and European academic research institutions with centralized procurement functions.
DNA Methylation Market Segmentation
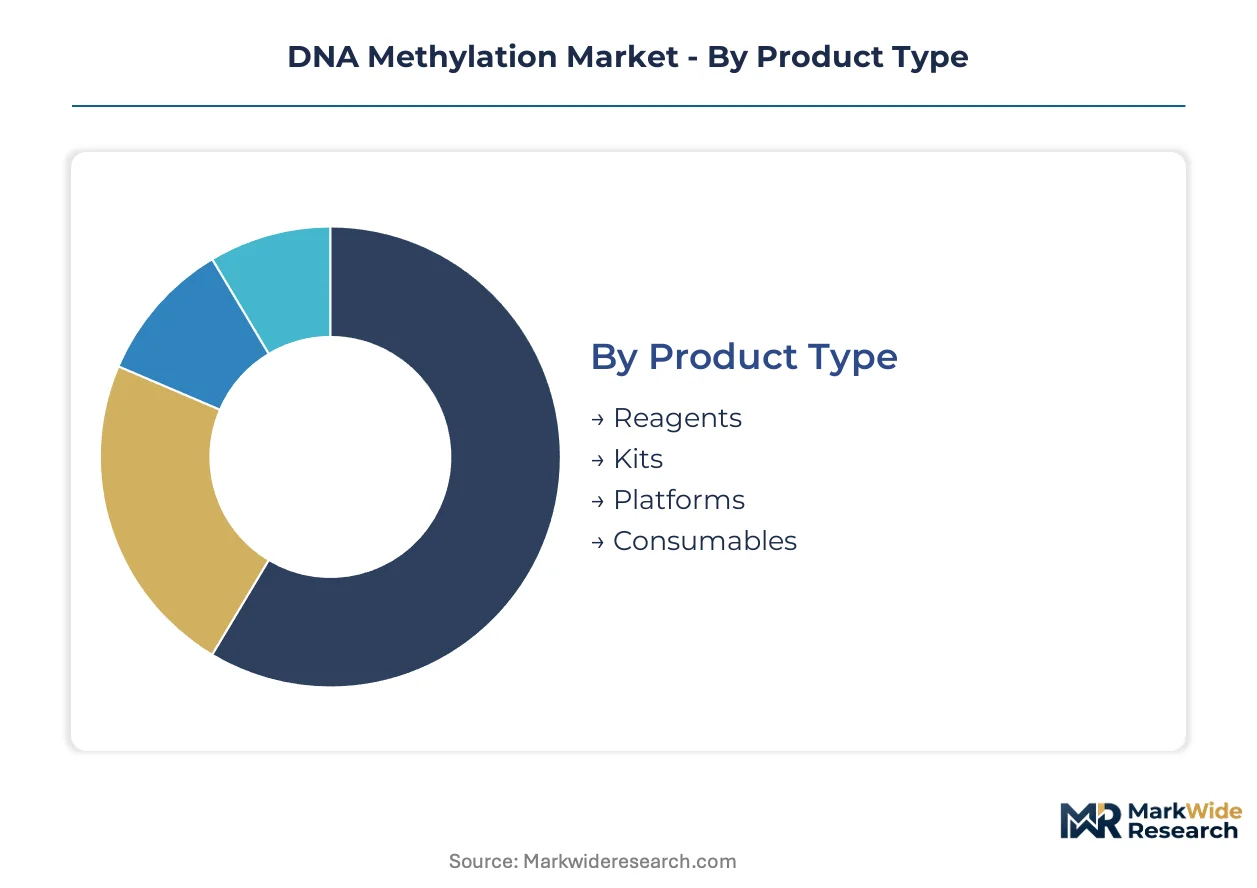
Segmentation in DNA methylation markets reflects divergent service intensity requirements across product categories. Reagent and platform vendors maintain fundamentally different customer success models, with sequencing instruments demanding multi-year field engineering relationships while consumables operate through transactional replenishment cycles.
Product Type:
After-sales service intensity varies dramatically across product categories, with platforms requiring dedicated field application scientists and annual maintenance contracts while reagents ship through automated replenishment programs.
- Reagents:Sulfite conversion chemicals, modified nucleotides, and enzymatic formulations constitute the highest-volume procurement category. Academic medical centers in Germany and the United States concentrate demand through consolidated purchasing agreements that lock in multi-year supply commitments.
- Kits:Standardized sample preparation workflows reduce protocol variability across multi-site clinical studies. CDSCO validation requirements in India and EMA quality standards in Europe drive kit manufacturers toward harmonized manufacturing footprints that simplify international registration pathways.
- Platforms:Capital equipment placements generate captive reagent pull-through through proprietary chemistries and software ecosystems. FDA premarket submission requirements extend platform development timelines while creating substantial switching costs for installed base customers.
- Consumables:Flow cells, cartridges, and single-use reaction vessels represent recurring revenue streams tied to instrument utilization rates. NMPA import licensing procedures in China create localized supply requirements that favor regional manufacturing partnerships.
Platforms hold the largest share; momentum sits with kits.
Application:
Clinical validation requirements and reimbursement pathways create tiered margin structures across therapeutic areas, with oncology commanding premium pricing for companion diagnostic applications.
- Oncology:Liquid biopsy development for minimal residual disease monitoring drives the dominant share of methylation assay investment. FDA guidance on tumor-informed testing establishes precedent for prospective sample collection requirements that reshape laboratory quality management systems.
- Neurology:Cell-free DNA methylation signatures for neurodegenerative disease stratification remain confined to research use applications. Academic consortia in the United Kingdom and Japan concentrate funding for longitudinal cohort studies that require harmonized biomarker discovery platforms.
- Cardiology:Epigenetic biomarkers for atherosclerotic risk prediction show early clinical validation signals. PMDA regenerative medicine frameworks in Japan create regulatory pathways that diverge from FDA device classification approaches.
- Immunology:Transplant rejection monitoring applications are pulling methylation platforms into clinical workflows previously dominated by flow cytometry. EMA biomarker qualification procedures govern European adoption timelines for novel immune monitoring assays.
Oncology commands the dominant revenue position; immunology represents the steepest expansion trajectory.
Technology:
Data generation costs and analytical complexity create diverging infrastructure requirements across detection modalities, with sequencing platforms demanding substantial capital commitment while PCR methods deploy through distributed laboratory networks.
- Sequencing:Short-read platforms anchor research and clinical applications through established bioinformatics pipelines. Long-read modalities from Pacific Biosciences and Oxford Nanopore are compressing cost-per-base for whole-genome methylation analysis.
- PCR:Quantitative methylation-specific PCR enables rapid turnaround for targeted clinical applications. Diagnostic laboratories in France and Germany favor PCR workflows for decentralized testing models that bypass centralized reference laboratory bottlenecks.
- Mass Spectrometry:Matrix-assisted laser desorption methods provide orthogonal validation for sequencing-derived methylation calls. Metabolomics core facilities at Swiss and Dutch academic centers maintain specialized instrumentation that supports multi-omic integration studies.
- Bioinformatics:Cloud-native analysis pipelines are collapsing processing costs for multi-terabyte methylation datasets. ISO 27001 certification requirements govern European and North American procurement decisions for genomic data processing platforms.
Sequencing holds the dominant instrument share; bioinformatics is climbing the fastest.
End User:
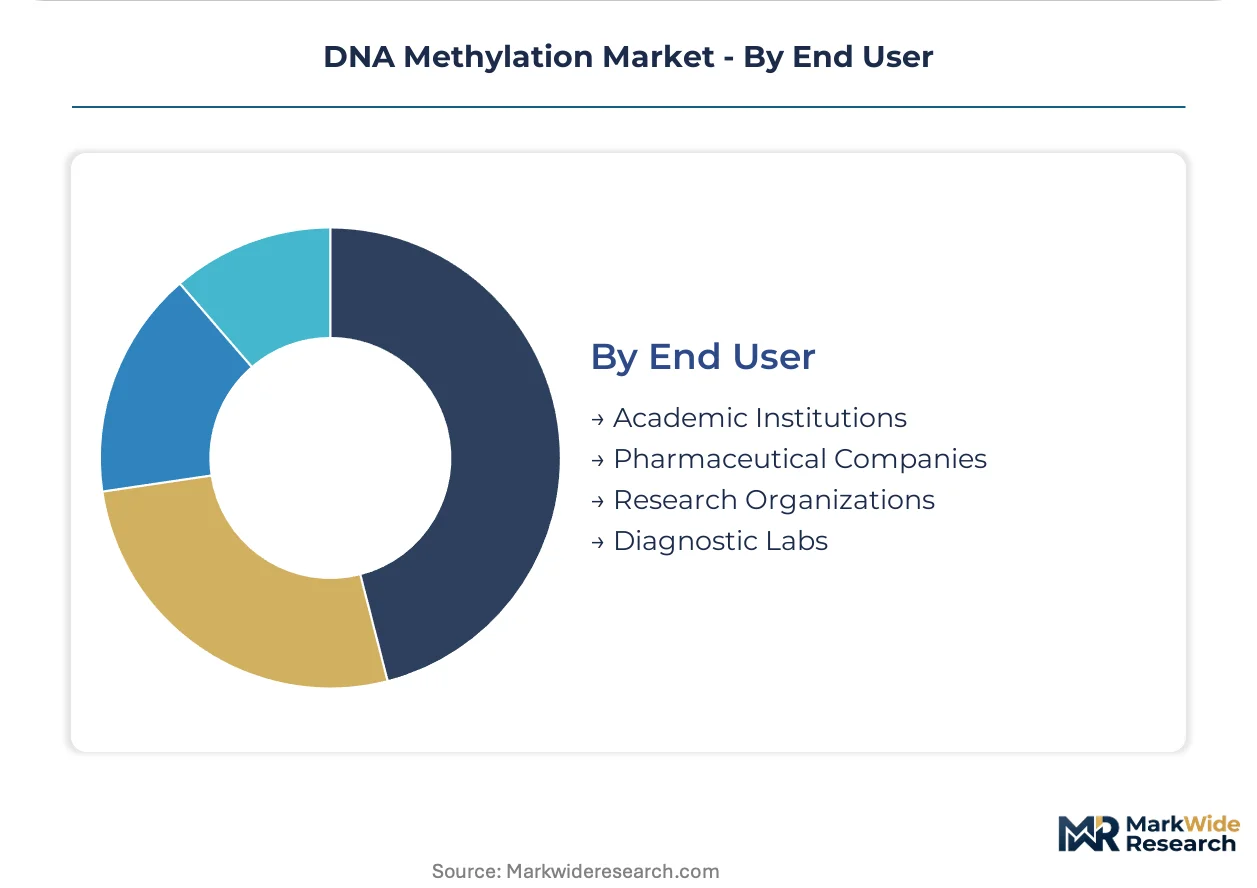
Procurement sophistication and volume scale create distinct customer segments, with pharmaceutical companies negotiating enterprise pricing while academic institutions rely on grant-funded capital acquisition cycles.
- Academic Institutions:National biobank networks in China and government-funded precision medicine initiatives concentrate reagent demand through centralized procurement functions. NIH and Wellcome Trust funding mechanisms shape platform selection criteria for epigenome assembly projects.
- Pharmaceutical Companies:Companion diagnostic co-development agreements require diagnostic-grade manufacturing capabilities and FDA premarket approval pathways. Roche, AstraZeneca, and Novartis maintain internal epigenetic profiling capabilities that compete with outsourced CRO relationships.
- Research Organizations:Non-profit institutes and government laboratories operate through competitive grant funding cycles that favor modular platform configurations. Broad Institute and EMBL-EBI data sharing policies influence standardization efforts across the research community.
- Diagnostic Labs:Clinical laboratory improvement amendment compliance and state licensing requirements govern US market entry. Quest Diagnostics and LabCorp purchasing volume shapes reagent pricing tiers for mid-sized regional laboratory networks.
Academic institutions represent the largest installed base; diagnostic labs are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Switzerland while procurement volume clusters in China and Germany, creating a geographic asymmetry between margin capture and demand scale.
United States
FDA liquid biopsy guidance and NIH precision medicine funding drive platform adoption across academic medical centers. The 21st Century Cures Act provisions accelerate companion diagnostic validation pathways for methylation-based cancer assays. The Boston-Cambridge biotech corridor anchors epigenetic biomarker development through Broad Institute consortia and venture-backed liquid biopsy startups.
Germany
Consolidated purchasing agreements at Charité Berlin and Heidelberg University Hospital concentrate reagent demand through centralized procurement functions. EMA biomarker qualification procedures govern adoption timelines for novel methylation assays in transplant rejection monitoring. The Rhine-Main biotech cluster around Frankfurt hosts specialized CROs supporting multi-site clinical epigenetics studies.
China
Government-funded national biobank networks and NMPA import licensing requirements shape localized supply strategies for sequencing consumables. The 14th Five-Year Plan precision medicine initiative directs capital toward domestic platform development. The Yangtze River Delta biotech corridor in Shanghai-Suzhou concentrates manufacturing partnerships for diagnostic-grade methylation kits.
Japan
PMDA regenerative medicine frameworks create distinct regulatory pathways for epigenetic biomarkers in cell therapy applications. METI funding for genomic medicine infrastructure supports platform placements at RIKEN and national university hospitals. The Kansai region around Osaka anchors specialized reagent manufacturing for the Asia-Pacific clinical laboratory market.
United Kingdom
Wellcome Trust epigenome assembly projects and NHS Genomic Medicine Service procurement drive platform selection criteria for research consortia. MHRA post-Brexit regulatory divergence creates parallel validation requirements for diagnostic-grade assays. The Cambridge-London corridor concentrates liquid biopsy development through Cancer Research UK-funded initiatives and university spinouts.
DNA Methylation Market Key Industry Players
Platform-integrated conglomerates and specialized reagent suppliers split the market along capital intensity lines. Three structural archetypes dominate: sequencing instrument vendors with captive reagent ecosystems, workflow-integrated life science conglomerates, and focused nucleic acid chemistry specialists. Competitive moves center on multi-year field service contracts that lock in institutional customers and direct-to-researcher e-procurement channels that bypass traditional distributor networks.
Within the platform-integrated tier, Illumina Inc. and Thermo Fisher Scientific Inc. exemplify the capital equipment model that generates recurring consumable revenue through proprietary chemistries. QIAGEN N.V. occupies a position representing standardized kit formats that reduce protocol variability across multi-site clinical studies. These three companies anchor distinct competitive positions without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Illumina Inc. |
| Thermo Fisher Scientific Inc. |
| QIAGEN N.V. |
| Agilent Technologies Inc. |
| F. Hoffmann-La Roche Ltd |
| New England Biolabs |
| Abcam Limited |
| Bio-Rad Laboratories Inc. |
| Zymo Research Corporation |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta biotech corridor concentrates domestic manufacturing capacity for sulfite conversion reagents and modified nucleotides, creating regional pricing power that radiates through Asia-Pacific procurement networks. German and Swiss chemical suppliers maintain premium positioning for pharmaceutical-grade cytosine derivatives through ISO 13485-certified production facilities that command 40-60% markups over standard research-grade inputs.
Pricing Analysis
Configured-to-order pricing for diagnostic-grade kits commands substantial premiums over standard research-use formats, with FDA premarket submission requirements and ISO 13485 certification tiers driving stratification across premium, standard, and economy levels. Academic medical centers in Germany and the United States negotiate volume-based contracts that compress per-unit costs by 15-25% compared to grant-funded ad hoc purchasing. Price erosion runs through the sequencing consumables tier as Illumina's captive reagent pull-through contracts limit competitive entry and force alternative platform developers into aggressive discounting. Pharmaceutical companies show lowest price sensitivity due to companion diagnostic co-development timelines, while regional diagnostic laboratories in India and Southeast Asia prioritize cost minimization over certification tier.
Supply Chain Analysis
Lonza Group and Samsung Biologics hold contract manufacturing capacity for GMP-grade nucleic acid chemistry inputs that feed diagnostic kit assembly operations. China, Germany, and Switzerland anchor supply for sulfite conversion reagents, modified cytosine bases, and enzymatic formulations. Raw material dependencies center on pharmaceutical-grade acrylamide, boronate affinity matrices, and fluorophore-conjugated oligonucleotides. Single-source vulnerability concentrates in long-read sequencing flow cell production where Oxford Nanopore and Pacific Biosciences maintain proprietary manufacturing. Distribution runs through direct-to-researcher e-procurement portals at Illumina and Thermo Fisher that displace traditional life science distributors in North American and European academic markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The DNA methylation market sits in early-cycle expansion as FDA liquid biopsy guidance accelerates clinical validation pathways for minimal residual disease assays. Penetration remains below 15% in immunology applications and point-of-care oncology settings, creating substantial runway for platform and reagent vendors.
For Market Incumbents: Build switching-cost moats through multi-year field service contracts that embed application scientists within academic medical center workflows. Defensive moves center on backward integration into GMP-grade nucleic acid chemistry manufacturing to secure supply of high-purity cytosine derivatives, alongside cloud-native bioinformatics platform development that locks in data analysis recurring revenue. The threat of long-read sequencing cost compression demands rapid targeted array product repositioning toward clinical validation applications where regulatory barriers protect installed base relationships. For New Entrants and Emerging Players: Pursue autoimmune disease profiling as the most penetrable application frontier, with systemic lupus erythematosus and rheumatoid arthritis cell-free DNA signatures showing early biomarker discovery signals but minimal competitive saturation. Geographic white space concentrates in India's CDSCO-regulated diagnostic market and Southeast Asia's emerging precision medicine initiatives. The go-to-market angle favors standardized kit formats that reduce protocol variability across multi-site clinical studies, mirroring QIAGEN's established positioning but targeting mid-tier regional laboratory networks excluded from enterprise purchasing agreements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors bioinformatics specialists with ISO 27001-certified cloud infrastructure and AI-driven variant calling capabilities that collapse analysis costs for multi-terabyte methylation datasets. Long-term viability over a 5-10 year window hinges on regulatory data rights and companion diagnostic co-development partnerships with top-20 pharmaceutical companies. Acquisition target archetypes include cloud-native analytics platforms with existing hospital system integrations and point-of-care device developers with miniaturized methylation detection IP. The signal to watch is NMPA approval velocity for domestic Chinese platform developers, which would signal regulatory pathway maturation and trigger consolidation pressure on Western vendors.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Establishes clinical market access for methylation-based companion diagnostics in oncology. |
| Cloud-Native Bioinformatics Platform | Collapses processing costs for multi-terabyte datasets through AI-driven variant calling integration. |
| Backward Integration into GMP Chemistry | Secures captive supply of pharmaceutical-grade sulfite conversion reagents against price volatility. |
| Direct-to-Researcher E-Procurement Channel | Bypasses traditional distributor markups for high-volume sequencing consumables in academic markets. |
| Autoimmune Disease Biomarker Expansion | Pulls methylation platforms into transplant rejection monitoring workflows previously dominated by flow cytometry. |
Research Approach
Initial hypotheses were tested against primary input from diagnostic laboratory directors, regulatory affairs specialists at assay manufacturers, pharmaceutical companion diagnostic leads, and academic epigenetics researchers, then refined through secondary validation. Primary fieldwork encompassed structured interviews with hospital procurement managers at Charité Berlin and Massachusetts General Hospital, platform engineering leads at sequencing instrument vendors, and CRO executives managing multi-site clinical epigenetics studies. Secondary sources included FDA premarket submission databases, EMA biomarker qualification procedures, NIH precision medicine funding disclosures, and NMPA import licensing records. Bottom-up triangulation across reagent volume estimates, instrument placement data, and service revenue models was cross-checked against top-down market sizing from national biobank procurement budgets and pharmaceutical R&D expenditure disclosures.
Demand-supply balance modeling anchored volume projections across the analysis window, with segmentation dimensions spanning product type (reagents, kits, platforms, consumables), application (oncology, immunology, neurology, cardiology), technology modality (sequencing, PCR, mass spectrometry, bioinformatics), and end user (academic institutions, pharmaceutical companies, diagnostic laboratories, research organizations). CAGRs were derived from fitted growth curves calibrated to historical adoption patterns in liquid biopsy and precision medicine markets, with explicit modeling of FDA guidance impact on clinical translation timelines and China 14th Five-Year Plan funding allocation trajectories.
Sensitivities concentrate around NMPA regulatory timeline acceleration, long-read sequencing cost compression velocity, and bioinformatics talent scarcity impacts on service-layer value capture. Forecasts reflect documented assumptions regarding reimbursement code crystallization for methylation-based assays and companion diagnostic co-development partnership formation rates. Quarterly review of FDA premarket approval submissions, EMA biomarker qualification decisions, and national biobank procurement tender announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Genetic Testing Service Market
Genomics
Global Molecular Cytogenetics Market
Genomics
Next-Generation Sequencing (NGS) Workflow Quality Control Test Kits and Instruments Market
Genomics
Agrigenomics Market
Genomics
Microbiome Sequencing Market
Genomics
Digital Genome Market
Genomics
Genomics Personalized Health Market
Genomics
Restriction Endonucleases Market
Genomics
Whole Genome Amplification Market
Genomics
NGS Automation Market
Genomics
Hereditary Testing Market
Genomics
Middle East and Africa Whole Exome Sequencing Market
Genomics
Spatial Genomics and Transcriptomics Market
Genomics
China Genetic Testing Market
Genomics
Sequencing Electrophoresis Systems Market
Genomics
Pharmacogenomics Technology Market