
 China Sealants Market | 2026-2036
China Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
China Sealants Market Outlook
Electric vehicle battery pack assembly is hardening as the fastest-growing demand vertical for advanced sealants in China. Guangzhou Baiyun Chemical Industry Co., Ltd. leverages its southern China manufacturing base to supply construction-grade silicone sealants at scale. Chengdu Guibao Science & Technology Co., Ltd. anchors its position through specialized R&D in high-temperature resistant formulations for industrial applications. Wacker Chemie AG competes by extending its international technology portfolio into localized production serving electronics manufacturers in eastern China.
China sealants are polymeric compounds formulated to fill gaps, prevent fluid leakage, and bond dissimilar substrates under varying thermal and mechanical stress, typically specified by elongation at break, Shore A hardness, and cure time parameters. Silicone formulations dominate the product type landscape due to their UV stability and temperature resistance in building envelope applications, while polyurethane grades capture expanding share in automotive sealing where flexibility under vibration matters. The construction end use industry remains the largest volume sink, though electronics adhesion applications are deepening as semiconductor packaging demands thermally conductive gap-filling compounds.
SAMR enforces GB standards governing volatile organic compound emissions in construction sealants, directly elevating compliance costs for domestic manufacturers. MEE implements environmental inspections that restrict solvent-based production processes, pushing formulation shifts toward waterborne and low-VOC chemistries. MIIT oversees material substitution mandates in automotive supply chains that favor lightweight bonded assemblies over mechanical fastening. Stakeholders must monitor how China's evolving dual carbon enforcement timeline reshapes raw material sourcing and plant certification requirements.
Market Dynamics
China's dual carbon enforcement timeline is compressing formulation cycles across sealant manufacturing, forcing rapid shifts from solvent-based to waterborne and low-VOC chemistries in construction and automotive supply chains.
Growth Catalysts
- Building energy efficiency mandates:GB standards for thermal insulation in commercial envelopes are expanding specification volumes for high-performance silicone sealants in Jiangsu and Zhejiang provinces.
- New energy vehicle battery assembly:Pack sealing requirements for thermal management and vibration resistance are pulling advanced polyurethane and silicone formulations into automotive tier-one supply chains.
- Yangtze River Delta concentration:Shanghai's electronics manufacturing cluster is deepening demand for thermally conductive gap-fillers in semiconductor packaging and display assembly.
Market Restraints
- Silicone feedstock volatility:Reliance on metallurgical-grade silicon and methyl chloride intermediates exposes margins to energy cost swings in southwestern smelting regions.
- MEE environmental inspection cycles:Unannounced solvent emissions audits force production stoppages that disrupt just-in-time delivery commitments to construction project schedules.
- Mechanical fastening substitution:Lightweight aluminum and composite joining in automotive body shops retains share where adhesive cure times conflict with takt-time requirements.
Strategic Opportunities
- Western China industrial expansion:Chengdu-Chongqing manufacturing corridors are underpenetrated for high-temperature industrial sealants serving aerospace and power equipment sectors.
- SAMR low-VOC certification acceleration:Early compliance with forthcoming GB revisions positions domestic formulators for preferred supplier status in government-funded infrastructure.
- Direct-to-contractor digital channels:E-procurement platforms for construction materials are disintermediating traditional distributor networks in tier-two and tier-three cities.
Industry Challenges
- Formulation chemist scarcity:Cross-trained polymer scientists capable of balancing rheology, adhesion, and emissions compliance command premium compensation in eastern China labor markets.
- Dual-carbon plant certification timelines:Retrofitting solvent recovery systems and obtaining MEE green-factory designation extends capital deployment cycles by twelve to eighteen months.
- Legacy specification lock-in:State-owned construction conglomerates maintain approved vendor lists that delay qualification of innovative waterborne products despite regulatory pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Sealants Market |
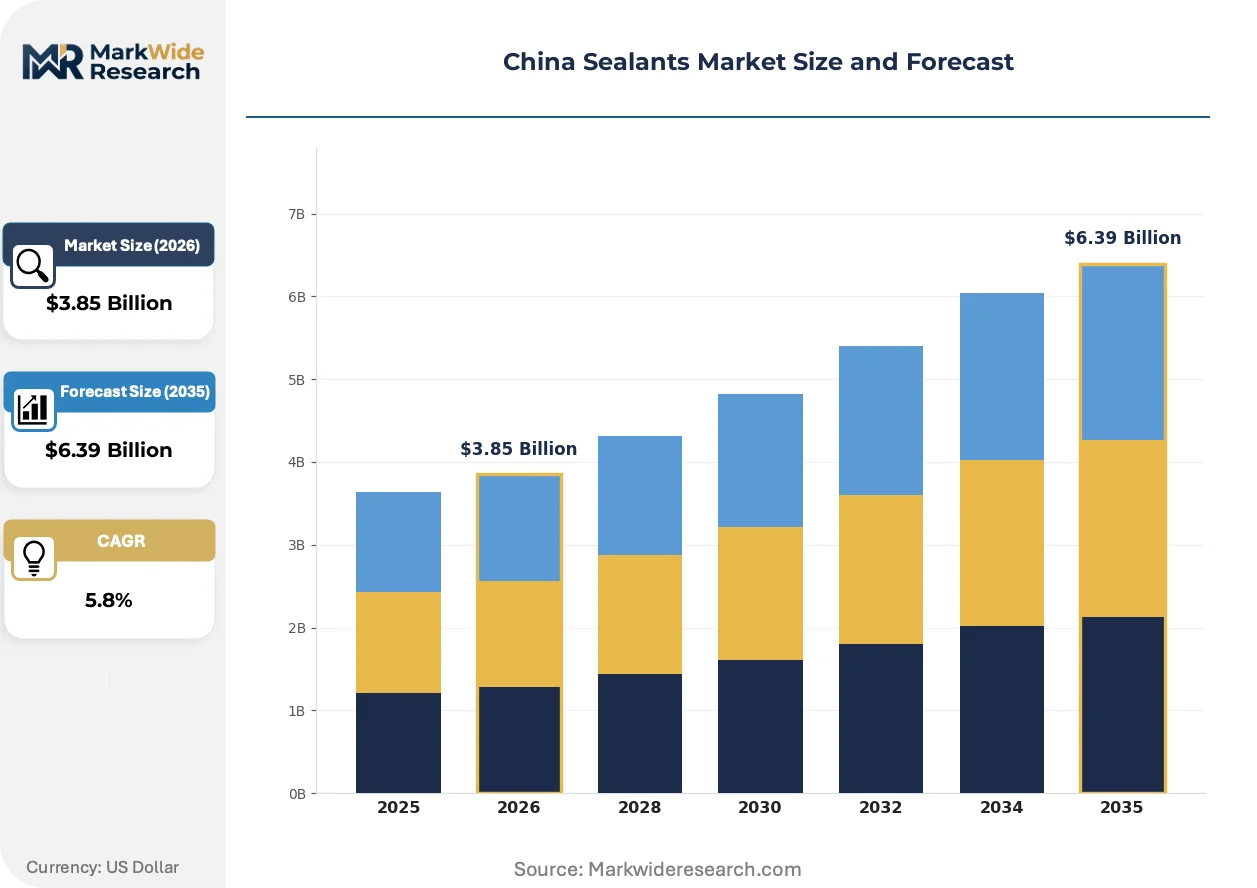
| Market Size in 2026 | $3.85 Billion |
| Market Size in 2035 | $6.39 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Silicone, Acrylic, Epoxy End Use Industry: Construction, Automotive, Aerospace, Electronics Application: Sealing, Adhesion, Insulation, Coating Distribution Channel: Online Retail, Distributors, Direct Sales, Specialty Stores |
| Companies Covered | Chengdu Guibao Science & Technology Co., Ltd., Guangzhou Baiyun Chemical Industry Co., Ltd., Guangzhou Jointas Chemical Co., Ltd., Sika AG, Henkel AG & Co. KGaA, 3M Company, Dow Inc., H.B. Fuller Company, Wacker Chemie AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Sealants Market Strategic Shifts
Formulation chemistry and procurement architecture are shifting in parallel, with sustainability compliance and supply chain digitization now inseparable from product specification decisions in China's sealant markets.
Two-component silicone systems with accelerated room-temperature vulcanization are overtaking single-component cartridges in high-volume automotive sealing operations. Battery pack assemblers in Ningbo and Changzhou are adopting these systems to eliminate heat-cure bottlenecks. The compression of cure cycles is overtaking traditional process design in tier-one supplier evaluations.
MEE's expansion of carbon emissions accounting to chemical manufacturing is tightening reporting requirements for sealant producers above ten thousand tons annual output. Facilities in Shandong and Guangdong provinces face mandatory installation of continuous emissions monitoring systems. Construction-grade silicone manufacturers are responding by consolidating production at certified green-factory sites with captive renewable power.
Buyers in electronics assembly are unbundling technical service from material supply, contracting directly with application engineering specialists rather than accepting bundled distributor support. Display manufacturers in Suzhou and Hefei now specify sealant performance through joint qualification protocols with equipment integrators. This service decoupling is most visible in flat-panel and semiconductor packaging supply chains where precision dispensing requires specialized expertise.
China Sealants Market Segmentation
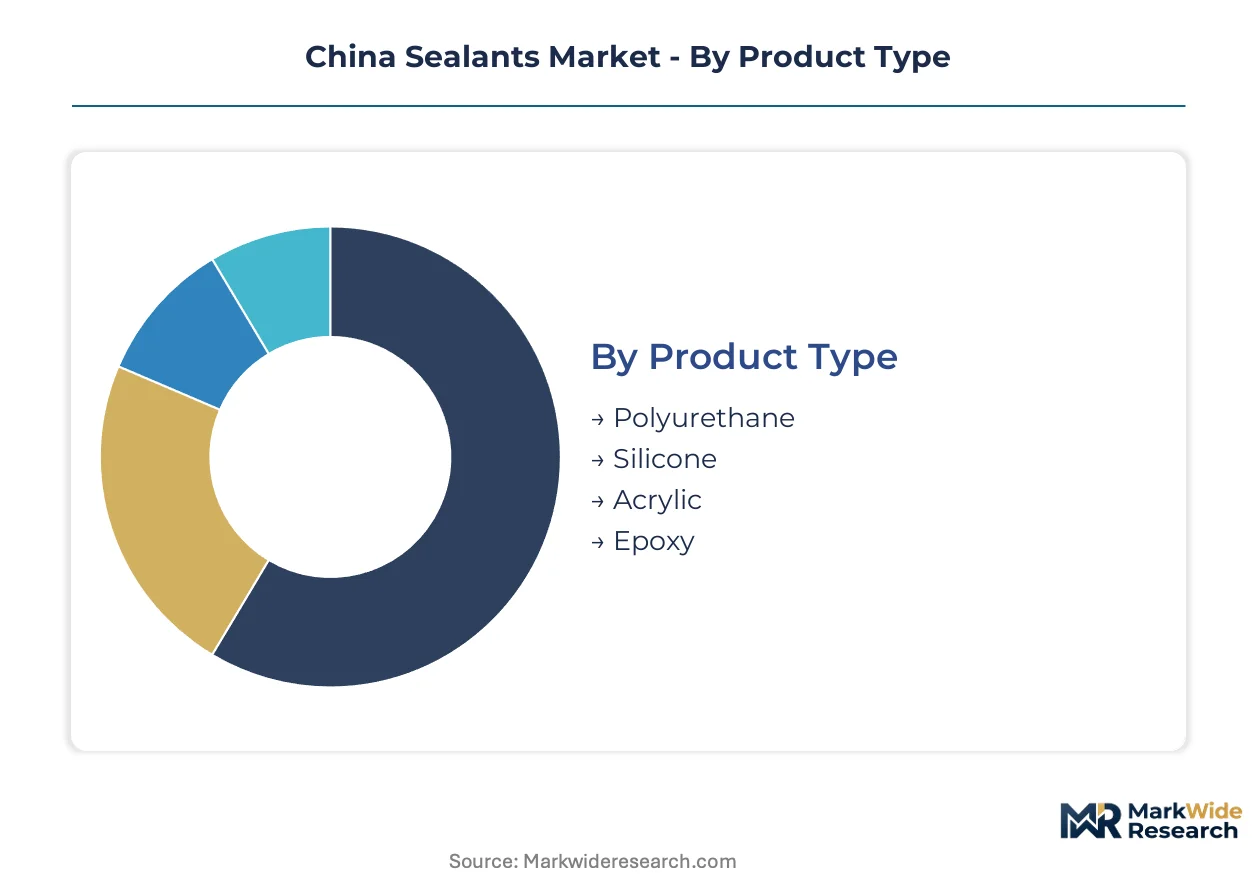
Sealant procurement in China follows distinct technical and commercial logics across product chemistry, end-use requirements, and supply channel preferences. Specification engineers in construction and automotive sectors weight performance parameters differently, creating tiered demand patterns that manufacturers must map precisely.
Product Type:
Buyers select chemistries based on thermal tolerance, UV exposure, and substrate compatibility rather than price alone.
- Silicone:Formulated from polydimethylsiloxane polymers with exceptional temperature stability from -60°C to 300°C. GB standards for building energy efficiency in Jiangsu and Zhejiang provinces are pulling high-modulus architectural grades into commercial envelope specifications, though feedstock volatility in southwestern metallurgical silicon smelting regions compresses margin predictability.
- Polyurethane:Two-component systems built on isocyanate-polyol reactions delivering superior elasticity and abrasion resistance. Battery pack assemblers in Ningbo and Changzhou specify these for thermal management gap-filling where vibration damping under mechanical stress matters most.
- Acrylic:Waterborne emulsions with rapid tack development and paintable surfaces, specified primarily for interior finishing applications in residential construction.
- Epoxy:Rigid thermosetting systems offering chemical resistance and high compressive strength, deployed in industrial flooring and heavy equipment bonding.
Volume sits with Silicone; growth tilts toward Polyurethane.
End Use Industry:
Application environments dictate certification requirements and formulation complexity across China's industrial sectors.
- Construction:Curtain wall, window, and structural glazing applications consuming cartridge and sausage-packaged sealants. SAMR enforcement of GB volatile organic compound limits is elevating compliance costs for solvent-based products in government-funded infrastructure projects.
- Automotive:Direct glazing, body sealing, and battery pack assembly requiring OEM-tier qualification protocols. MIIT material substitution mandates favor lightweight bonded assemblies over mechanical fastening in new energy vehicle platforms.
- Aerospace:Fuel tank sealing and fuselage bonding with extreme temperature cycling specifications, concentrated in Chengdu-Chongqing manufacturing corridors.
- Electronics:Semiconductor packaging and display assembly demanding thermally conductive gap-fillers with precise rheology control.
Construction commands current volume; Electronics climbs the fastest.
Application:
Functional purpose determines cure chemistry selection and equipment integration requirements.
- Sealing:Gap-filling and fluid exclusion in static joints, the foundational specification driving bulk silicone consumption.
- Adhesion:Structural bonding of dissimilar substrates where load transfer and durability under cyclic stress predominate.
- Insulation:Thermal and acoustic barrier applications expanding with building energy efficiency mandates.
- Coating:Protective surface treatments with sealant-grade flexibility for expansion joint coverage.
Sealing anchors present volume; Adhesion gains share fastest.
Distribution Channel:
Procurement architecture is fragmenting as digital platforms disintermediate traditional supply relationships.
- Distributors:Regional stocking networks maintaining technical service capabilities for specification support in tier-two and tier-three cities.
- Direct Sales:Manufacturer-to-contractor relationships for large-scale infrastructure projects with customized formulation requirements.
- Online Retail:E-procurement platforms capturing standard-grade construction sealants through transparent pricing and consolidated logistics.
- Specialty Stores:Localized outlets serving maintenance and repair segments with immediate availability.
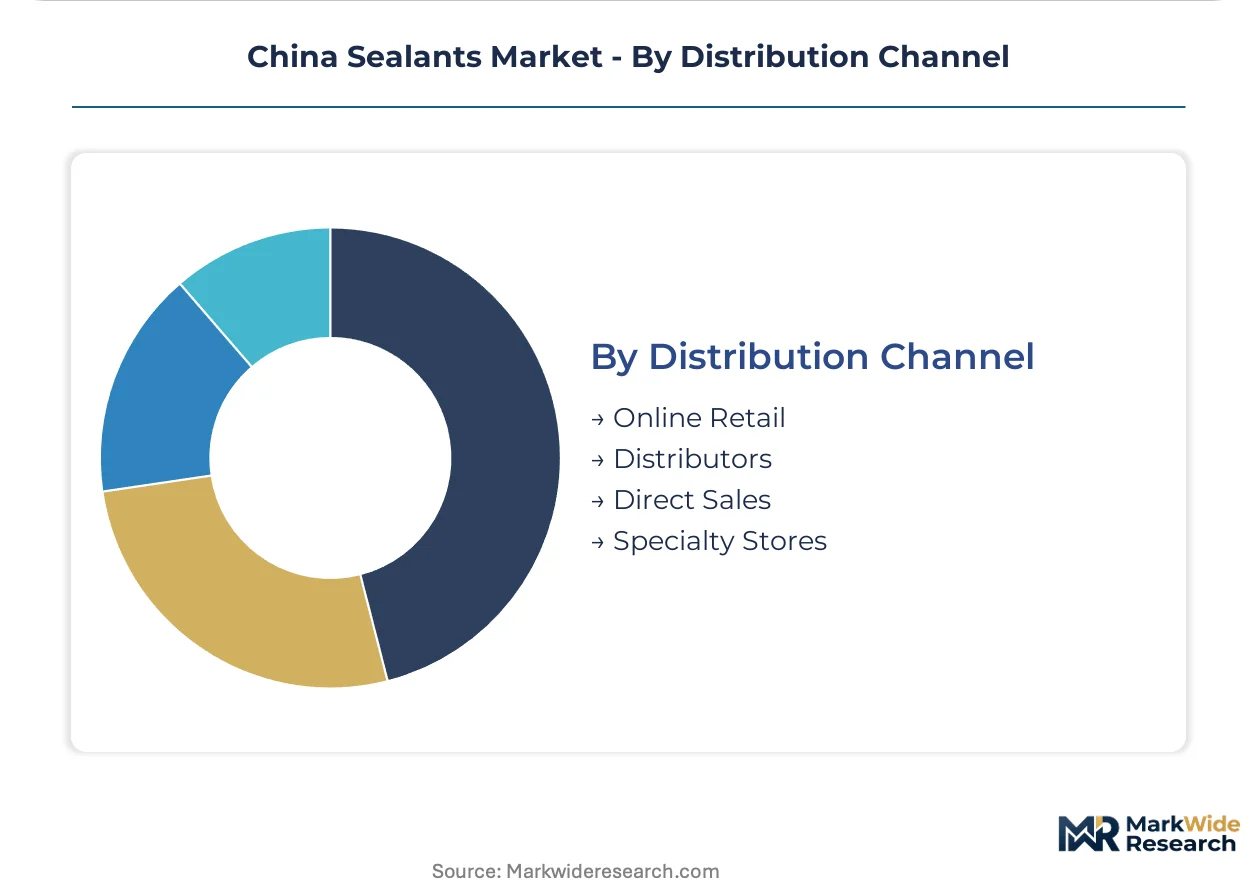
Distributors hold current volume; Online Retail expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's sealant production concentrates in coastal manufacturing belts, while consumption spreads across inland industrial corridors. This geographic mismatch creates distinct regional specialization patterns.
Yangtze River Delta
Shanghai and Jiangsu province dominate electronics-grade sealant consumption for semiconductor packaging and display assembly. SAMR enforces GB standards for volatile organic compound emissions that elevate compliance costs for local formulators. Suzhou and Hefei manufacturing clusters pull thermally conductive gap-fillers into flat-panel and chip packaging supply chains.
Pearl River Delta
Guangdong province anchors construction-grade silicone production serving southern China's building envelope market. MEE environmental inspection cycles force solvent-based production stoppages that disrupt delivery schedules. Guangzhou and Shenzhen industrial zones supply cartridge and sausage-packaged sealants for curtain wall and structural glazing applications.
Beijing-Tianjin-Hebei
The northern corridor drives demand for high-performance sealants in infrastructure and transportation equipment. MIIT material substitution mandates favor lightweight bonded assemblies in regional automotive manufacturing. Tianjin port facilities handle imported specialty polymers for electronics and aerospace tier-one suppliers.
Sichuan-Chongqing
The western manufacturing corridor remains underpenetrated for high-temperature industrial sealants serving aerospace and power equipment sectors. Dual carbon enforcement timelines compress formulation cycles for regional producers. Chengdu anchors specialized research and development in heat-resistant formulations for industrial bonding applications.
Shandong Peninsula
Shandong province hosts bulk silicone production facilities facing mandatory carbon emissions accounting above ten thousand tons annual output. MEE requires continuous emissions monitoring systems at chemical manufacturing plants. Qingdao and Yantai industrial zones consolidate production at certified green-factory sites with captive renewable power.
China Sealants Market Competitive Environment
Top-tier vendors anchor premium formulation segments, while mid-scale domestic specialists capture volume in construction-grade applications. The vendor base organizes around technology licensing partnerships, captive raw material supply, and regional distribution density. Three archetypes dominate: multinational technology licensors, integrated domestic formulators, and regional construction-grade specialists. Competitive moves concentrate on green-factory certification acceleration and direct-to-contractor digital channel expansion.
Within the multinational tier, Sika AG, Henkel AG & Co. KGaA, and Dow Inc. occupy positions defined by international technology portfolios and localized production capabilities. These firms exemplify the technology-licensing archetype, extending global formulation expertise into China-specific applications. Domestic specialists including Chengdu Guibao Science & Technology Co., Ltd. and Guangzhou Baiyun Chemical Industry Co., Ltd. represent the integrated formulator model, combining regional manufacturing presence with specialized research and development. Wacker Chemie AG sits within a hybrid position, bridging international technology access with eastern China electronics manufacturing proximity. Guangzhou Jointas Chemical Co., Ltd. anchors the construction-grade specialist archetype through southern China manufacturing scale.
| Leading Market Players |
|---|
| Chengdu Guibao Science & Technology Co., Ltd. |
| Guangzhou Baiyun Chemical Industry Co., Ltd. |
| Guangzhou Jointas Chemical Co., Ltd. |
| Sika AG |
| Henkel AG & Co. KGaA |
| 3M Company |
| Dow Inc. |
| H.B. Fuller Company |
| Wacker Chemie AG |
| Others |
Value Chain & Pricing Dynamics
Formulation chemist scarcity in eastern China labor markets widens pricing spreads between premium certified grades and commodity construction sealants. SAMR compliance costs for GB volatile organic compound standards concentrate in high-performance tiers, compressing margins for domestic manufacturers lacking green-factory certification while multinational licensors preserve pricing power through technology differentiation.
Pricing Analysis
Margin tightening in standard-grade construction sealants reflects feedstock volatility in southwestern metallurgical silicon smelting regions and MEE environmental inspection disruptions. Three-tier pricing structure across premium certified, standard compliant, and economy solvent-based levels separates qualified suppliers for government infrastructure from commodity players. Price differentiation hinges on SAMR low-VOC certification status and captive renewable power at production sites. State-owned construction conglomerates exhibit lowest price sensitivity due to approved vendor list requirements, while tier-two contractor digital procurement channels drive hardest bargaining on standard grades.
Supply Chain Analysis
Metallurgical-grade silicon feedstock rests on southwestern China smelting corridors and methyl chloride intermediates draw from Shandong and Jiangsu chemical clusters. Silicone polymer production concentrates in Guangdong, Jiangsu, and Shandong provinces with polyurethane isocyanate supply anchored in Shanghai and Ningbo manufacturing zones. Single-source vulnerability sits with high-purity silicon metal for electronics-grade sealants facing energy cost swings. Distribution runs through regional stocking distributors maintaining technical service capabilities for specification support, though e-procurement platforms disintermediate tier-two and tier-three city channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The China sealants market constitutes a consolidation play as dual carbon enforcement timelines and SAMR certification requirements force sub-scale solvent-based producers toward exit or acquisition.
For Market Incumbents: Extend green-factory certification acceleration to capture government-funded infrastructure preferred supplier status before GB revision implementation. Backward integration into captive metallurgical silicon supply secures margin predictability against southwestern smelting energy cost swings. Defensive positioning requires consolidating production at MEE-certified sites with renewable power to neutralize environmental inspection disruption risks from unannounced solvent emissions audits. For New Entrants and Emerging Players: E-procurement platform partnerships offer lowest-friction channel access for standard-grade construction sealants in tier-two and tier-three cities outside distributor technical service territories. The Chengdu-Chongqing western corridor remains underpenetrated for high-temperature industrial sealants serving aerospace and power equipment sectors with limited incumbent R&D presence. Joint qualification protocols with equipment integrators bypass legacy specification lock-in at state-owned construction conglomerates. For Investors and Strategic Acquirers: The window for entry favors domestic mid-cap formulators with SAMR pre-certification against forthcoming GB revisions and established Yangtze River Delta electronics manufacturing proximity. Acquisition targets should demonstrate specialized polyurethane or thermally conductive silicone formulation capabilities aligned with new energy vehicle battery assembly and semiconductor packaging demand verticals. Watch MEE carbon emissions accounting expansion to chemical manufacturing above ten thousand tons annual output as inflection indicator for forced consolidation among uncertified producers.| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | MEE green-factory certification secures preferred supplier status in government-funded infrastructure procurement. |
| Backward Integration | Captive metallurgical silicon supply neutralizes feedstock volatility from southwestern smelting energy cost swings. |
| Long-term Supply Agreement | Battery pack assemblers in Ningbo and Changzhou lock in polyurethane formulation volumes through OEM-tier qualification. |
| Joint Venture | Technology licensing partnerships with multinational licensors accelerate electronics-grade sealant qualification in Suzhou clusters. |
| Capacity Expansion | Consolidated production at certified green-factory sites with renewable power addresses MEE continuous emissions monitoring requirements. |
Study Parameters
Document review covered SAMR regulatory filings, MEE environmental inspection protocols, MIIT material substitution mandates, and customs trade data for silicone polymer imports, complemented by interviews with formulation R&D directors, procurement leads at automotive tier-one suppliers, construction project specification engineers, and regional distribution channel managers. Primary fieldwork across Shanghai, Jiangsu, Guangdong, and Sichuan manufacturing clusters was triangulated against secondary validation from GB standard revision drafts and state-owned construction conglomerate approved vendor lists. Bottom-up volume modeling from end-use industry consumption patterns was cross-referenced with top-down value estimates from production facility capacity disclosures.
Historical shipment data was cross-referenced against panel input from plant managers and technical directors across the projection horizon. Segmentation dimensions modeled include product chemistry type, end-use industry vertical, application function, and distribution channel format alongside regional production hub concentration. CAGRs were derived from elasticity-adjusted demand projections incorporating new energy vehicle production schedules and building energy efficiency mandate implementation timelines. Electronics-grade sealant demand was calibrated against semiconductor packaging and flat-panel display assembly capacity expansion in Suzhou and Hefei clusters.
Several conditions sit outside the modeled scope, including potential relaxation of dual carbon enforcement timelines, abrupt shifts in state-owned construction conglomerate procurement centralization, and unanticipated breakthroughs in mechanical fastening substitution for adhesive bonding. Forecasts reflect documented assumptions regarding GB standard revision implementation pacing and MEE inspection cycle intensity. A small set of named triggers warrants ongoing watch: MEE carbon emissions accounting threshold adjustments, SAMR low-VOC certification acceleration timelines, and feedstock energy cost volatility in southwestern metallurgical silicon regions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Low VOC Adhesive Market
Adhesives & Sealants
UV Cured Adhesives Market
Adhesives & Sealants
Global Adhesion Barrier Market
Adhesives & Sealants
Europe Waterborne Adhesives Market
Adhesives & Sealants
Germany Adhesives Market
Adhesives & Sealants
Adhesives and Sealants Market
Adhesives & Sealants
Specialty Adhesives Market
Adhesives & Sealants
Textile Binders Market
Adhesives & Sealants
Butyl Adhesive Market
Adhesives & Sealants
Plastic Adhesives Market
Adhesives & Sealants
Global Non-Woven Adhesives Market
Adhesives & Sealants
Global Construction Adhesives and Sealants Market
Adhesives & Sealants
Reactive Adhesives Market
Adhesives & Sealants
Asia-Pacific Epoxy Curing Agents Market
Adhesives & Sealants
Mexico Sealants Market
Adhesives & Sealants
Middle East & Africa Construction Adhesives & Sealants Market