
 DCT Mechatronic Control Unit Market | 2026-2036
DCT Mechatronic Control Unit Market Size, Share, and Industry Trends Forecast 2026-2036
DCT Mechatronic Control Unit Market Insights
ISO 26262 functional safety certification is bifurcating the supplier landscape into qualified tier-1 incumbents and excluded aspirants. Bosch leverages its in-house semiconductor capabilities to sustain full-stack control over safety-critical firmware development. ZF Friedrichshafen anchors European supply through captive hydraulic valve body production integrated with mechatronic assembly. Continental competes on adaptive learning algorithms that reduce shift latency across dual-clutch architectures.
A DCT Mechatronic Control Unit constitutes an integrated electro-hydraulic system managing clutch engagement, gear selection, and torque transfer in dual-clutch transmissions, typically operating at hydraulic pressures between 40 and 80 bar with response times under 100 milliseconds. Its primary purpose is to synchronize engine output with driveline demands while optimizing fuel efficiency and shift comfort. The shift-by-wire technology segment commands premium positioning as automakers eliminate mechanical linkages, while torque vectoring functionality represents the fastest-growing capability subset for performance-oriented platforms. Hydraulic mechatronic units still occupy the largest volume share among product types due to their established presence in mass-market passenger cars.
NHTSA in the United States enforces failure-mode diagnostics that mandate redundant sensor architectures within transmission control modules. EMA's REACH compliance requirements in Europe restrict specific hydraulic fluid additives, compelling reformulation of actuator lubricants. China's MIIT implements GB standards for new energy vehicle powertrain integration that directly specify mechatronic control performance thresholds. Stakeholders must monitor how software-defined vehicle architectures reshape hardware-software boundaries in transmission control procurement decisions.
Market Dynamics
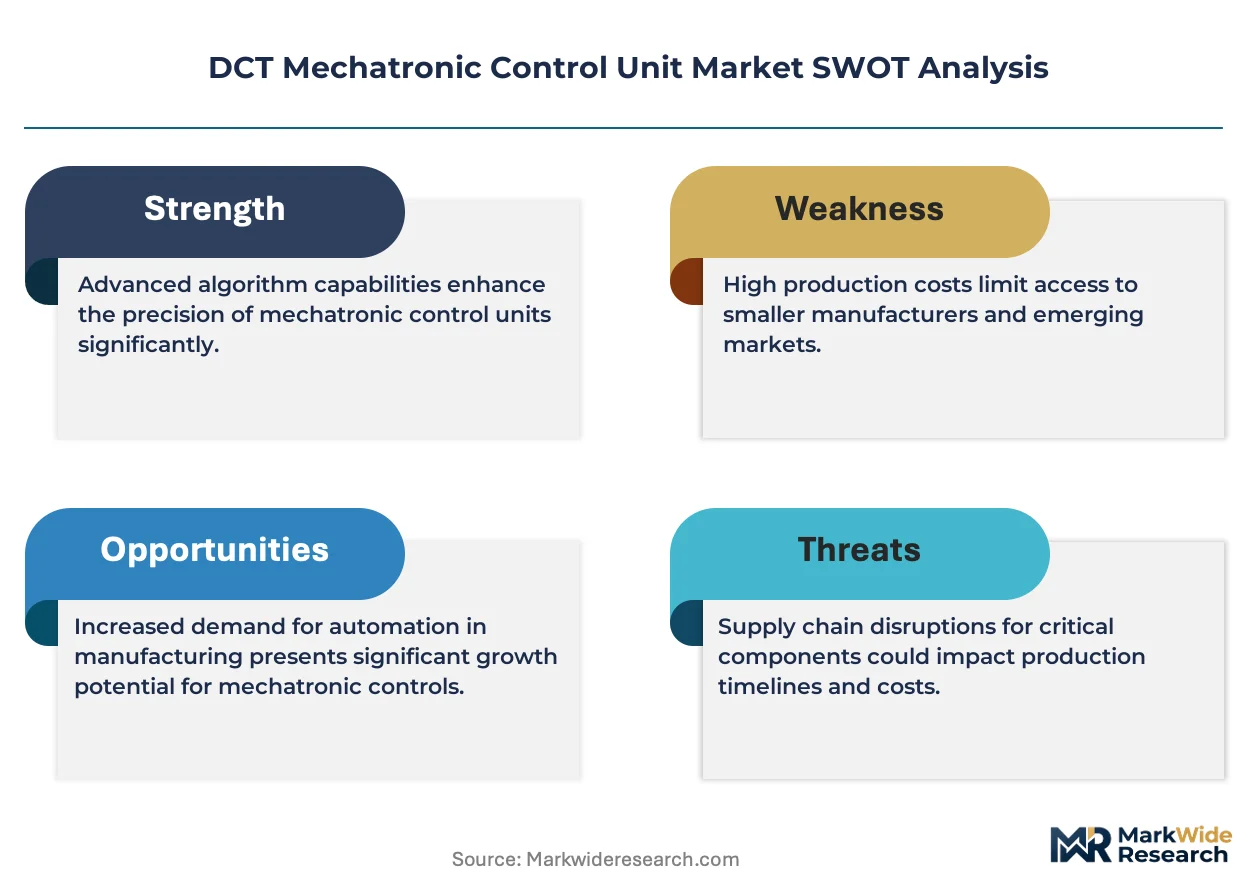
Software-defined vehicle architectures are dissolving traditional hardware-software boundaries in transmission control procurement, forcing tier-1 suppliers to restructure development roadmaps around over-the-air update capabilities and functional safety recertification cycles.
Growth Catalysts
- Euro 7 emission standards:German and Chinese passenger car manufacturers are expanding procurement of advanced DCT control systems as tightening powertrain efficiency requirements mandate precise torque management.
- Dual carbon goals:China's MIIT implementation of GB standards for new energy vehicle powertrain integration directly specifies mechatronic control performance thresholds for hybrid and battery-electric platforms.
- Shift-by-wire technology:Automakers eliminating mechanical linkages drives premium positioning for integrated electro-hydraulic architectures with sub-100 millisecond response times.
Market Restraints
- ISO 26262 certification barriers:Functional safety requirements bifurcate the supplier landscape into qualified tier-1 incumbents and excluded aspirants, concentrating supply among semiconductor-integrated manufacturers.
- Hydraulic fluid additive restrictions:EMA's REACH compliance requirements in Europe compel reformulation of actuator lubricants, increasing R&D burden for established hydraulic mechatronic unit producers.
- Silicon carbide inverter substitution:Advances in wide-bandgap power electronics threaten conventional hydraulic control architectures in high-voltage electric vehicle platforms.
Strategic Opportunities
- Torque vectoring capability expansion:Performance-oriented platforms represent the fastest-growing capability subset for integrated mechatronic architectures managing lateral torque distribution.
- Adaptive learning algorithm deployment:Shift latency reduction across dual-clutch transmissions creates differentiation for suppliers with embedded AI-driven calibration systems.
- Redundant sensor architecture mandates:NHTSA failure-mode diagnostics in the United States open specification windows for suppliers with captive semiconductor and firmware development capabilities.
Industry Challenges
- Functional safety engineering talent scarcity:ISO 26262 ASIL-D certification expertise concentrates among incumbent suppliers, constraining workforce mobility and inflating compensation for qualified firmware architects.
- Legacy powertrain integration complexity:Mechatronic control units must maintain backward compatibility with existing dual-clutch transmission architectures while enabling software-defined update pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DCT Mechatronic Control Unit Market |
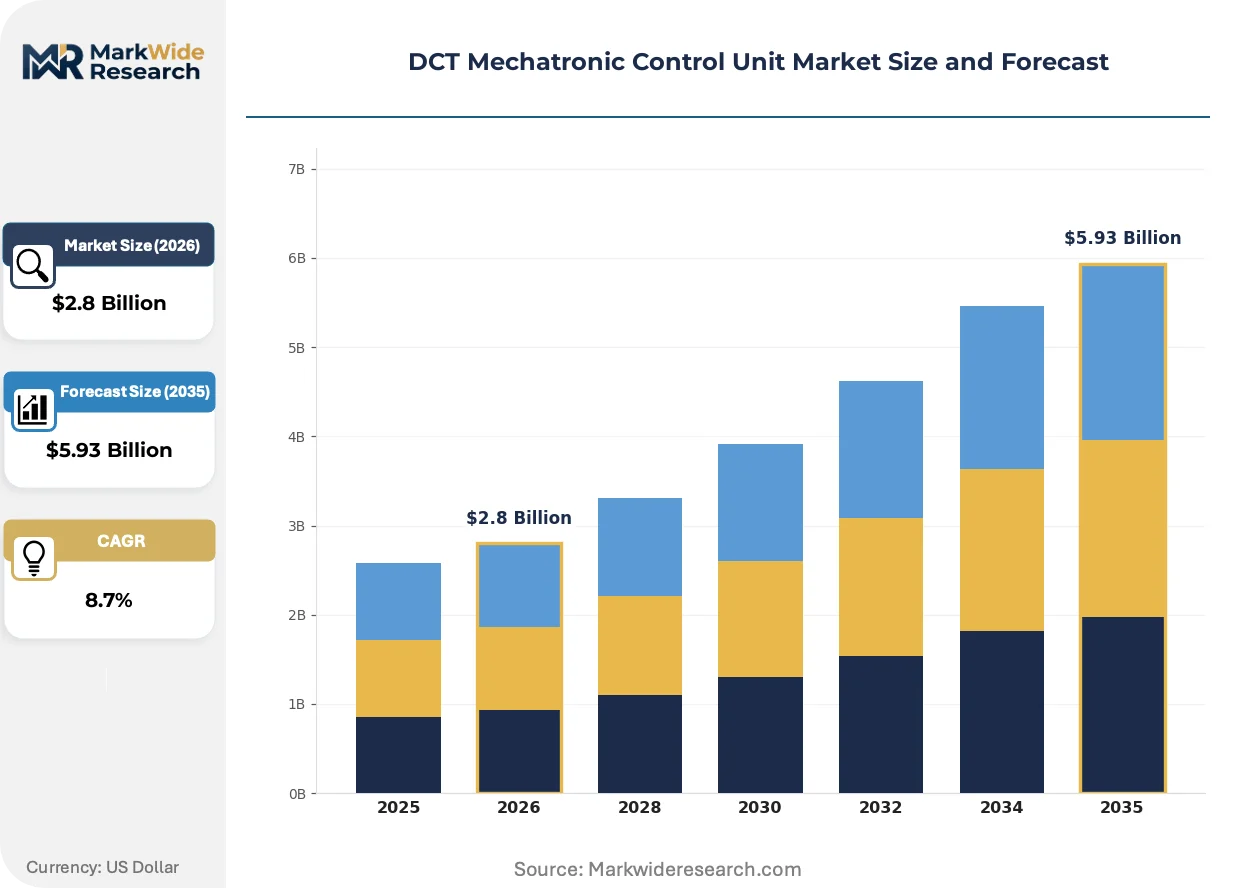
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Mechatronic Unit, Electronic Control Unit, Sensor Module, Actuation Module Technology: PWM Control, CAN Bus Communication, Adaptive Learning, Torque Vectoring, Shift-by-Wire Application: Sports Vehicles, Commercial Transport, Heavy Machinery, Electric Vehicles, Luxury Cars End User: Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers, Fleet Operators |
| Companies Covered | Bosch, Continental, ZF Friedrichshafen, BorgWarner, Schaeffler, Hitachi Astemo, Denso, Aisin, Magna International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DCT Mechatronic Control Unit Market Trends and Innovations
Integrated electro-hydraulic architectures are converging with semiconductor-level control, compressing development cycles and redrawing competitive boundaries between transmission specialists and chip suppliers.
Mechatronic control firmware is fragmenting across safety-critical and non-safety domains as automakers partition torque management algorithms between domain controllers and transmission-mounted units. Tier-1 suppliers with in-house semiconductor capabilities capture full-stack development contracts, while pure-play software vendors face exclusion from ASIL-D certification pathways. This technical bifurcation compresses margins for mid-tier hardware assemblers lacking silicon design expertise.
REACH compliance requirements from EMA are restricting specific hydraulic fluid additives, compelling reformulation of actuator lubricants across European supply chains. Manufacturers with captive chemical engineering capabilities internalize compliance costs, while dependent suppliers face procurement disruption from qualified fluid source constraints. Hydraulic mechatronic units serving mass-market passenger cars encounter the steepest reformulation timelines.
Automaker sourcing departments are consolidating transmission control procurement under software-defined vehicle platform contracts, displacing component-level negotiations with system-level agreements. Tier-1 suppliers with end-to-end torque management capabilities capture expanded scope, while specialized hydraulic valve body producers face margin compression from bundled pricing. This concentration is most visible in German and Chinese OEM procurement organizations.
DCT Mechatronic Control Unit Market Segmentation
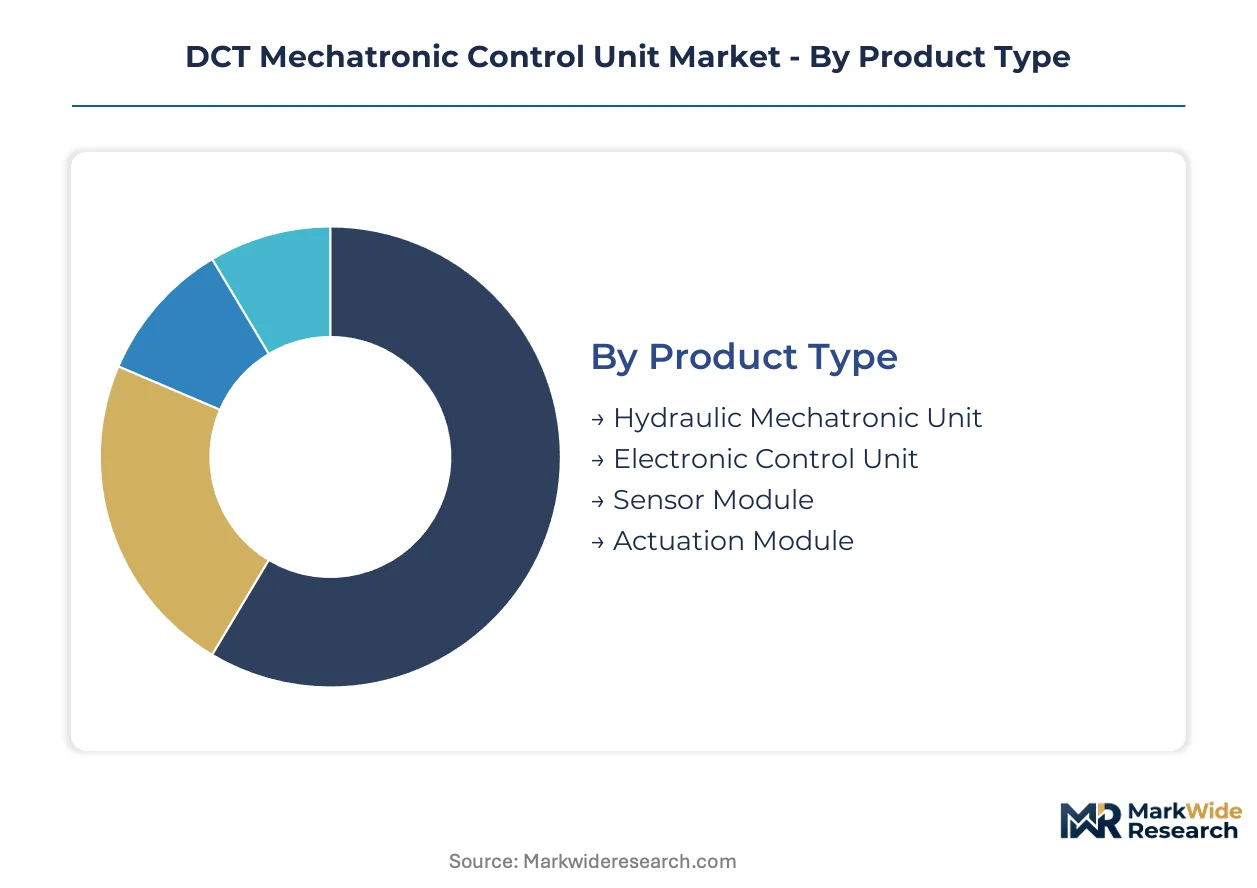
DCT mechatronic control unit procurement patterns diverge sharply across product architectures, with hydraulic-electronic integration levels determining supplier qualification tiers. Technology roadmaps and application requirements reshape segment boundaries as software-defined vehicle platforms consolidate control functions.
Product Type:
Silicon carbide inverter substitution pressure falls heaviest on hydraulic-dependent architectures, while solid-state electronic modules face less immediate displacement risk from wide-bandgap power electronics.
- Hydraulic Mechatronic Unit:Integrated electro-hydraulic systems operating at 40-80 bar pressure with sub-100 millisecond response times dominate mass-market passenger car procurement in Germany and China. Established dual-clutch transmission architectures in European volume manufacturing anchor sustained demand despite REACH-driven fluid reformulation burdens.
- Electronic Control Unit:Safety-critical firmware domains partitioned from non-safety algorithms concentrate development among semiconductor-integrated tier-1 suppliers. ISO 26262 ASIL-D certification requirements bifurcate the supplier landscape into qualified incumbents with in-house silicon capabilities and excluded hardware assemblers.
- Sensor Module:NHTSA-mandated redundant sensor architectures for failure-mode diagnostics specify dual-channel torque and position sensing in United States-bound vehicle platforms.
- Actuation Module:REACH-compliant hydraulic fluid compatibility constraints reshape European supply chains for clutch and gear selection actuators.
Hydraulic mechatronic units anchor the volume base while electronic control units gain share at the steepest rate.
Technology:
Cost tier stratification separates legacy PWM architectures from premium positioning commanded by integrated torque management capabilities.
- Shift-by-Wire:Elimination of mechanical linkages enables premium positioning for integrated electro-hydraulic architectures with sub-100 millisecond response times. German and Chinese OEM procurement organizations consolidate transmission control sourcing under software-defined vehicle platform contracts, expanding scope for full-stack torque management suppliers.
- Torque Vectoring:Lateral torque distribution management for performance-oriented platforms represents the capability subset expanding most quickly. Adaptive learning algorithms reduce shift latency across dual-clutch architectures, creating differentiation for embedded AI-driven calibration systems.
- PWM Control:Legacy pulse-width modulation architectures serve cost-sensitive mass-market applications with established hydraulic valve body integration.
- CAN Bus Communication:Domain controller partitioning of transmission control functions reshapes mechatronic unit interface requirements.
- Adaptive Learning:Embedded AI-driven calibration systems differentiate suppliers competing on shift latency reduction metrics.
PWM control anchors the volume base while torque vectoring climbs the fastest in share expansion.
Application:
Volume concentration patterns track powertrain electrification trajectories, with hybrid and battery-electric platforms reshaping segment priorities.
- Electric Vehicles:China's MIIT GB standards for new energy vehicle powertrain integration specify mechatronic control performance thresholds for seamless torque management in hybrid and battery-electric architectures. Integrated mechatronic architectures enable the precise torque modulation required for dual-motor and multi-speed electric drivelines.
- Luxury Cars:Premium positioning for shift-by-wire and adaptive learning capabilities concentrates demand among German OEM flagship platforms with consolidated software-defined vehicle procurement.
- Sports Vehicles:Torque vectoring functionality requirements drive specification of lateral torque distribution capabilities in performance-oriented platforms.
- Commercial Transport:Durability-focused hydraulic mechatronic units serve fleet operators with extended service interval requirements.
- Heavy Machinery:High-torque hydraulic actuation architectures address off-highway powertrain control demands.
Luxury cars anchor the volume base while electric vehicles expand most quickly in application share.
End User:
Supply concentration among tier-1 incumbents with captive semiconductor capabilities displaces component-level negotiations with system-level platform contracts.
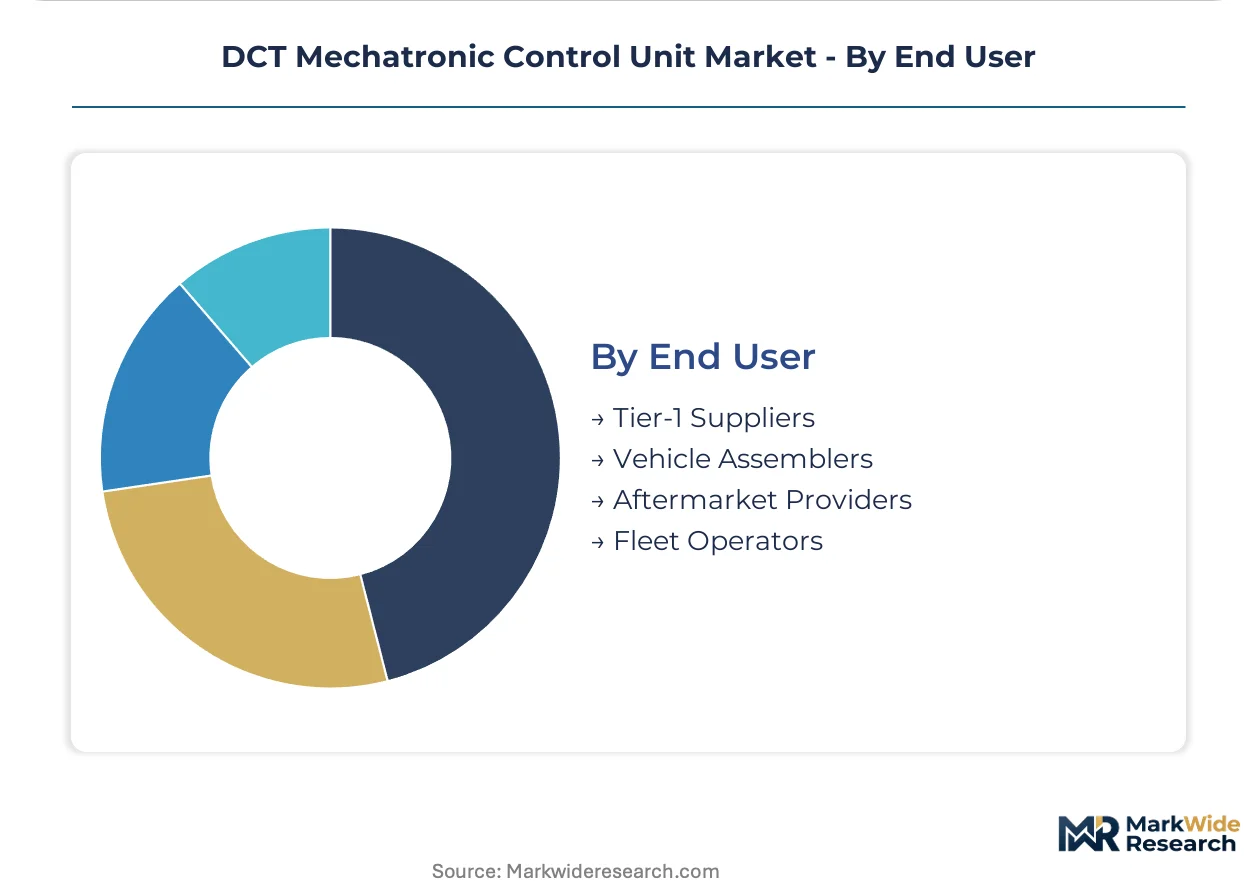
- Tier-1 Suppliers:Full-stack control over safety-critical firmware development and in-house semiconductor capabilities captures expanded scope under automaker software-defined vehicle procurement consolidation. Bosch and ZF Friedrichshafen anchor European supply through integrated hydraulic valve body and mechatronic assembly.
- Vehicle Assemblers:German and Chinese OEM sourcing departments displace component-level negotiations with bundled system-level agreements covering end-to-end torque management.
- Aftermarket Providers:ISO 26262 certification barriers constrain independent service provider access to safety-critical control module replacement.
- Fleet Operators:Commercial transport procurement prioritizes hydraulic mechatronic unit durability and extended service intervals.
Vehicle assemblers anchor the volume base while tier-1 suppliers gain share at the steepest rate in contract scope expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors German automotive component exports through dedicated automotive terminals handling mechatronic assemblies bound for Chinese manufacturing clusters. This maritime infrastructure underwrites trans-Eurasian supply chains for dual-clutch transmission control systems.
Germany
Stuttgart-based OEM procurement teams specify integrated hydraulic valve body systems for Euro 7-compliant powertrains. KBA enforces type-approval protocols for transmission control modules under UN-ECE regulations. Bavaria's Ingolstadt and Munich manufacturing corridors concentrate captive mechatronic assembly operations for premium vehicle platforms.
China
Shanghai's Yangshan Deep Water Port facilitates import of European hydraulic control components for domestic dual-clutch transmission assembly. MIIT's GB standards for new energy vehicle powertrain integration mandate specific mechatronic performance thresholds. Shenzhen and Guangzhou electronics clusters supply sensor modules for integrated torque management systems.
United States
Michigan's Detroit-Ann Arbor corridor anchors Tier-1 supplier engineering centers developing NHTSA-compliant redundant sensor architectures. The regulator mandates failure-mode diagnostics for transmission control modules in passenger vehicles. South Carolina's BMW Spartanburg plant sources mechatronic units for North American SUV production.
Japan
Nagoya's Chubu manufacturing belt concentrates precision hydraulic component fabrication for dual-clutch transmission suppliers. METI oversees industrial standards coordination between automotive and semiconductor sectors. Toyota City maintains integrated development pipelines linking transmission engineering with mechatronic control firmware.
South Korea
Ulsan's Hyundai Motor complex drives domestic demand for shift-by-wire mechatronic architectures in hybrid vehicle platforms. The national industrial regulator enforces alignment between automotive electronics and telecommunications standards. Seoul Capital Area engineering centers develop adaptive learning algorithms for reduced shift latency.
DCT Mechatronic Control Unit Market Competitive Landscape
Listed leaders compete with private specialists across semiconductor-integrated control system development, concentrating supply among entities with captive silicon design capabilities. The supplier landscape bifurcates sharply around ISO 26262 ASIL-D certification thresholds. Three archetypes dominate: diversified industrial conglomerates with full-stack capabilities, transmission specialists with integrated hydraulic production, and electronics-focused component suppliers. Competitive moves center on functional safety recertification cycles and over-the-air update capability integration.
Within the diversified conglomerate tier, Bosch and Continental represent integrated development models spanning semiconductor design through mechatronic assembly. ZF Friedrichshafen anchors the transmission specialist archetype through European supply chain integration. These three entities exemplify how captive capabilities in safety-critical firmware development reshape contract scope under automaker software-defined vehicle procurement consolidation.
| Leading Market Players |
|---|
| Bosch |
| Continental |
| ZF Friedrichshafen |
| BorgWarner |
| Schaeffler |
| Hitachi Astemo |
| Denso |
| Aisin |
| Magna International |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at German hydraulic valve body foundries and Chinese sensor module fabs shapes both supply concentration and price floors across the DCT mechatronic control unit landscape. Automaker procurement consolidation under software-defined vehicle contracts compresses margins for mid-tier hardware assemblers lacking silicon design capabilities, while REACH-driven fluid reformulation burdens add compliance premiums to European-sourced hydraulic architectures.
Pricing Analysis
Volume-discount tiering structures stratify across ASIL-D certification grades, with ISO 26262-qualified tier-1 suppliers commanding 40-60% premiums over hardware assemblers excluded from safety-critical firmware domains. Price differentiation hinges on semiconductor integration depth and after-sales calibration service bundling. Pricing pressure stems from silicon carbide inverter substitution threats in high-voltage electric vehicle platforms, with mass-market passenger car OEMs exhibiting highest price sensitivity and German luxury vehicle assemblers least.
Supply Chain Analysis
Inbound logistics costs through the Port of Hamburg and Shanghai Yangshan Deep Water Port fluctuate with container availability on trans-Eurasian automotive trade lanes. Manufacturing concentration centers on Germany, China, and Japan, with hydraulic valve bodies sourced from Stuttgart-area foundries and sensor modules from Shenzhen electronics clusters. Supply chains draw from specialty hydraulic fluids, silicon wafers, and rare-earth magnets, facing single-source vulnerability in ASIL-D-certified firmware IP. Distribution runs through captive tier-1 assembly plants co-located with OEM transmission facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software update and calibration service contracts expand faster than hardware unit sales as automakers prioritize over-the-air functional safety recertification cycles. This service-attach dynamic restructures supplier economics toward recurring revenue models.
For Market Incumbents: Compound defensive positioning by deepening backward integration into semiconductor design and capturing full-stack torque management contracts before automaker procurement consolidation hardens. Prioritize ISO 26262 ASIL-D recertification cycle acceleration to exclude aspirant competitors from safety-critical domains. Extend captive hydraulic fluid engineering capabilities to internalize REACH compliance costs and displace dependent suppliers facing qualified source constraints.
For New Entrants and Emerging Players: Anchor in aftermarket diagnostic tool development and non-safety-critical algorithm layers where certification barriers are lowest. Target sensor module supply to Chinese NEV manufacturers under MIIT GB standards implementation, where domestic sourcing preferences create specification windows. Pursue white-label firmware development partnerships with mid-tier hardware assemblers lacking in-house silicon capabilities.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among tier-1 suppliers with integrated safety-critical firmware and over-the-air update infrastructure, positioning these archetypes for superior cash flow quality across the 5-10 year electrification transition. Monitor silicon carbide inverter adoption curves in premium electric vehicle platforms as the critical inflection signal for hydraulic mechatronic unit displacement risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Functional Safety Recertification Acceleration | ISO 26262 ASIL-D expertise concentration locks out aspirant competitors from German and Chinese OEM supply. |
| Semiconductor Backward Integration | In-house silicon design captures full-stack development contracts under software-defined vehicle procurement consolidation. |
| Hydraulic Fluid Reformulation Investment | REACH-compliant captive chemistry capabilities internalize compliance costs and secure European supply continuity. |
| Adaptive Learning Algorithm Deployment | Embedded AI-driven calibration systems differentiate suppliers competing on shift latency reduction metrics. |
| Over-the-Air Update Infrastructure Buildout | Remote functional safety recertification enables recurring service revenue streams beyond hardware unit sales. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, Tier-1 supplier procurement directors, transmission control firmware architects, and aftermarket service operations managers. Secondary validation drew from NHTSA failure-mode diagnostic filings, MIIT GB standards documentation, UN-ECE type-approval protocols, IHS Markit vehicle production databases, and SEC filings from listed automotive component suppliers. Bottom-up unit demand estimates triangulated against top-down powertrain electrification scenario modeling.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmentation by propulsion architecture, vehicle class, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from regression analysis against powertrain efficiency regulation timelines and electric vehicle penetration curves. Industry-specific inputs included dual-clutch transmission adoption rates by geography, ISO 26262 certification lag times, and software-defined vehicle platform rollout schedules.
Underlying assumptions cover sustained Euro 7 and China dual carbon policy enforcement, with deviation risk concentrated in silicon carbide inverter substitution pace and REACH hydraulic fluid additive restriction scope expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Surface Acoustic Wave Sensors Market
Sensors and Controls
Wearable Thermometers Market
Sensors and Controls
Global Industrial Temperature Controller Market
Sensors and Controls
Middle East and Africa Wearable Sensors Market
Sensors and Controls
US Vibration Sensors Market
Sensors and Controls
APAC Temperature Sensors Market
Sensors and Controls
LAMEA Active Sensor Market
Sensors and Controls
Global Collision Avoidance Sensors Market
Sensors and Controls
MEMS Market
Sensors and Controls
Sensor Data Analytics Market
Sensors and Controls
3D Sensors Market
Sensors and Controls
Acoustic Respiration Sensors Market
Sensors and Controls
Seismic Monitoring Equipment Market
Sensors and Controls
Fingerprint Identification Chip Market
Sensors and Controls
Capacitive Position Sensors Market
Sensors and Controls
Accelerometer and Gyroscope Market