
 Global Methyl Acrylate Market | 2026-2036
Global Methyl Acrylate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Methyl Acrylate Market Foresight
Specialized chemical process engineering talent is unwinding capacity bottlenecks across Asian methyl acrylate plants. BASF leverages its Ludwigshafen integrated site to sustain captive propylene oxide feedstock for acrylate esters. Arkema competes through specialty-grade monomer production at its Carling facility in France. Dow anchors North American supply with its Freeport, Texas, complex and backward integration into crude acrylic acid.
Methyl acrylate is an ester of acrylic acid, produced via acid-catalyzed esterification of acrylic acid with methanol, typically yielding a colorless liquid with a pungent odor and a molecular weight of 86.09 g/mol; it serves primarily as a reactive building block for polymer synthesis in coatings, adhesives, and textile treatments. The monomer segment dominates volume flows into paint manufacturers seeking waterborne acrylic formulations. Copolymer grades for electronics manufacturers represent the fastest-expanding margin pool as semiconductor packaging adhesives tighten purity thresholds. Emulsion products for textile producers remain mature, with pricing power eroding amid Asian capacity overhang.
REACH registration requirements in Europe restrict non-compliant monomer imports, while China's MEE enforces VOC emission caps at Jiangsu and Zhejiang chemical parks. EPA New Chemicals Program reviews in the United States slow novel acrylate derivative introductions. Stakeholders must monitor how EU Green Deal carbon-border adjustments reshape cost competitiveness for Saudi and Korean export volumes.
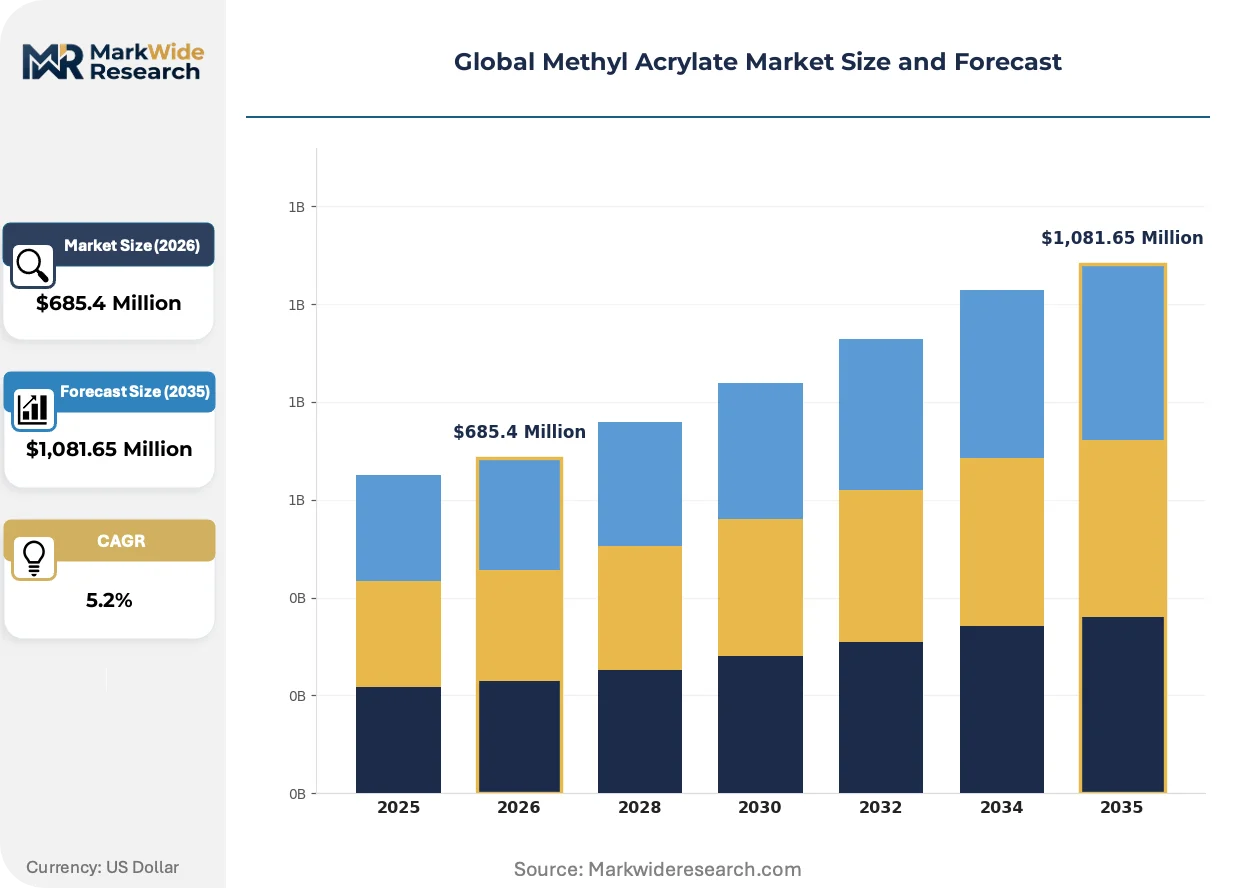
Market Dynamics
Consolidation of methyl acrylate production into China's coastal chemical parks is redrawing feedstock procurement networks and forcing European buyers to absorb higher compliance costs under REACH registration requirements.
Growth Catalysts
- Waterborne coating mandates:China's MEE enforces VOC emission caps at Jiangsu and Zhejiang chemical parks, accelerating acrylic emulsion substitution for solvent-based systems in architectural paints.
- Semiconductor packaging purity thresholds:Electronics manufacturers demand copolymer-grade methyl acrylate with sub-ppm impurity levels for advanced adhesive applications in chip bonding processes.
- Integrated propylene oxide supply:Captive feedstock production at Ludwigshafen-scale complexes secures margin stability for acrylate ester manufacturers against methanol price volatility.
Market Restraints
- Crude acrylic acid concentration:North American supply depends on Freeport-scale complexes with limited alternative sourcing during turnaround seasons.
- Substitution by bio-based acrylates:Renewable ester platforms from fermentation-derived acrylic acid threaten commodity-grade methyl acrylate in packaging adhesives.
- REACH purity escalation:ECHA registration requirements tighten impurity specifications for non-European monomer imports, raising analytical and certification burdens.
Strategic Opportunities
- India specialty chemical parks:PLI scheme incentives for acrylate derivative manufacturing attract investment away from saturated Chinese coastal zones.
- EU Green Deal carbon-border adjustments:CBAM implementation creates first-mover advantage for European producers with verified low-carbon process credentials.
- Digital twin process optimization:Convergence of predictive analytics with continuous esterification reactors enables real-time purity control and yield recovery.
Industry Challenges
- Specialized chemical process engineering scarcity:Asian plant expansions compete for talent capable of optimizing acid-catalyzed esterification throughput and selectivity.
- Legacy batch reactor retrofit complexity:Continuous processing upgrades require extended downtime and capital allocation that mid-scale producers struggle to justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Methyl Acrylate Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monomer, Polymer, Copolymer, Resin, Emulsion Application: Adhesives, Coatings, Textile Finishing, Electronics, Wood Protection End User: Paint Manufacturers, Textile Producers, Electronics Manufacturers, Chemical Manufacturers, Construction Firms Distribution Channel: Direct Sales, Distributors, Online Retailers, Industrial Suppliers, International Traders |
| Companies Covered | LG Chem, Dow, BASF, Arkema, Mitsubishi Chemical Group, NIPPON SHOKUBAI CO., LTD., Evonik Industries, Shanghai Huayi Acrylic Acid Co., Ltd., SIBUR INTERNATIONAL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Methyl Acrylate Market Shifts & Advancements
Process intensification and regulatory stringency are splitting methyl acrylate production into distinct technology tiers while reshaping how buyers evaluate supplier qualifications beyond price metrics.
Continuous esterification reactor technology is bifurcating the methyl acrylate manufacturing landscape. These systems replace traditional batch processing with steady-state operation that cuts methanol recycle rates and improves thermal efficiency. Specialty-grade producers at Carling-scale facilities adopt this technology fastest to meet semiconductor adhesive purity requirements. The technology is bifurcating the market into high-purity continuous producers and commodity batch operators facing margin compression.
REACH registration dossier updates now mandate extended toxicity data for acrylate esters used in consumer-facing applications. ECHA's 2024 substance evaluation wave targets residual monomer levels in polymer dispersions for textile coatings. Paint manufacturers reformulating for the EU market must document supply chain compliance back to acrylic acid feedstock, favoring integrated producers with captive registration portfolios.
Buyers in electronics adhesives now unbundle certification documentation from volume contracts, treating REACH compliance and ISO 17025 analytical certificates as standalone procurement criteria. This decoupling pressures traders and distributors who lack direct manufacturing relationships with registered producers. The shift is most pronounced in German and French automotive electronics supply chains where OEMs audit monomer provenance for semiconductor packaging materials.
Global Methyl Acrylate Market Segmentation
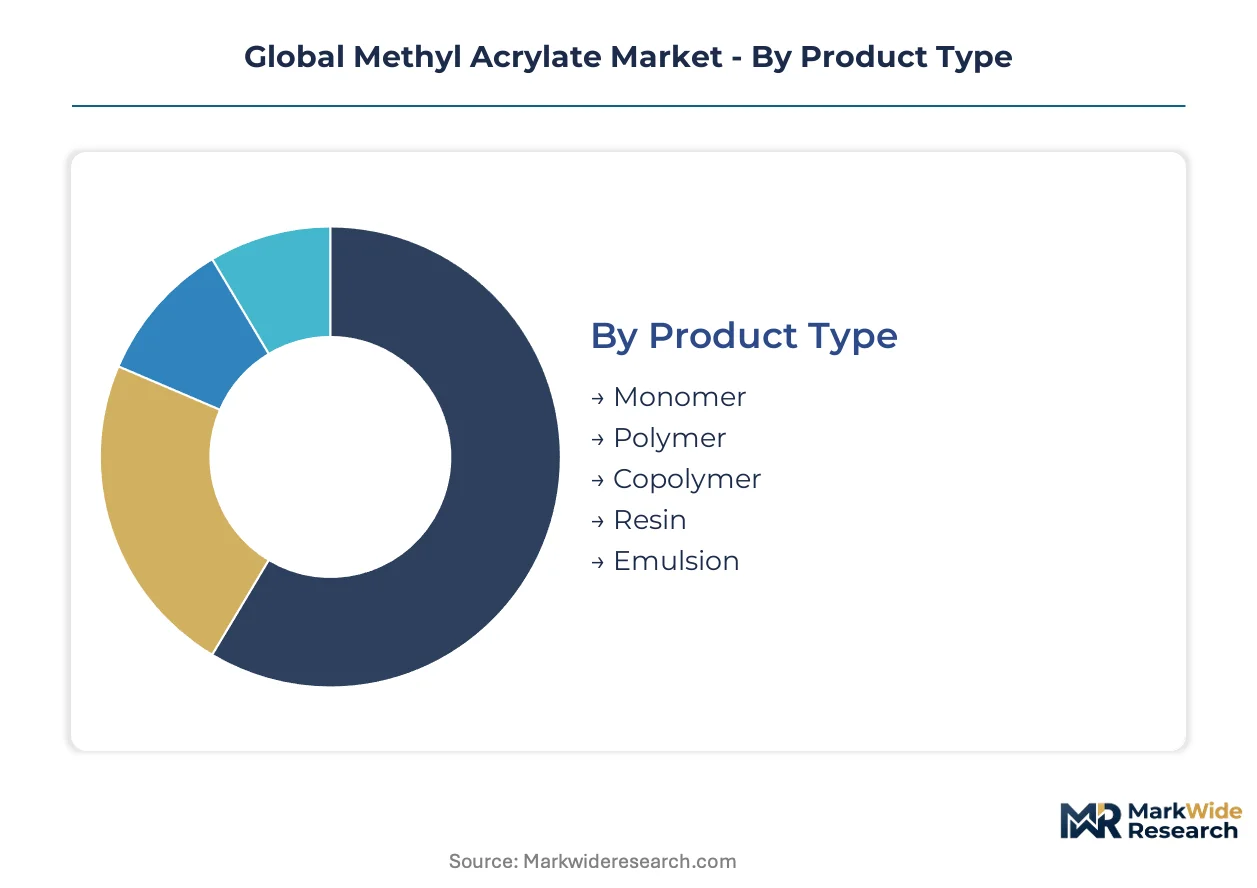
Segmentation in methyl acrylate markets separates commodity-grade volume plays from specialty-grade margin pools. Buyers in electronics and automotive coatings now unbundle certification from volume, forcing suppliers to qualify across purity tiers rather than compete on price alone.
Product Type:
Margin concentration sits in copolymer and specialty monomer grades serving semiconductor packaging and automotive electronics.
- Monomer:Colorless liquid produced via acid-catalyzed esterification with 86.09 g/mol molecular weight. Paint manufacturers in China absorb volume for waterborne architectural coatings under MEE VOC enforcement at Jiangsu and Zhejiang chemical parks.
- Copolymer:Sub-ppm purity grades for chip bonding adhesives in semiconductor packaging. Electronics manufacturers in Germany and South Korea demand ISO 17025 analytical certificates separate from volume contracts.
- Polymer:Intermediate chain lengths for industrial adhesives and sealants.
- Resin:Cross-linked matrices for protective coatings and composite binders.
- Emulsion:Water-dispersed particles for textile finishing applications; pricing power erodes amid Asian capacity overhang.
Monomer holds installed capacity. Copolymer is rotating up the share rankings.
Application:
Application mix tracks regulatory enforcement intensity across jurisdictions with strict VOC limits.
- Electronics:Advanced adhesive formulations for semiconductor packaging and flexible circuit boards. South Korean and Taiwanese chip fabricators specify ultra-low residual monomer levels under customer quality agreements.
- Coatings:Waterborne acrylic systems displacing solvent-based alternatives in architectural and automotive finishes. China's MEE emission caps accelerate substitution at manufacturing clusters in Guangdong and Shandong.
- Adhesives:Pressure-sensitive and structural bonding applications across packaging and assembly.
- Textile Finishing:Fabric coatings and binders facing REACH dossier updates on residual monomer toxicity.
- Wood Protection:Preservative carriers and moisture barriers for exterior lumber treatments.
Coatings maintains volume leadership. Electronics claims the steepest expansion trajectory.
End User:
Customer concentration favors integrated producers with captive registration portfolios and direct technical service capabilities.
- Electronics Manufacturers:Semiconductor and display panel producers auditing monomer provenance through supply chains. German automotive electronics OEMs require ECHA-registered feedstock documentation back to acrylic acid origin.
- Paint Manufacturers:Architectural and industrial coating formulators consolidating procurement around REACH-compliant suppliers. French and Italian producers absorb higher certification costs to maintain EU market access.
- Textile Producers:Fabric finishers in India and Bangladesh sourcing emulsion grades for export-oriented garment manufacturing.
- Chemical Manufacturers:Derivative producers and toll converters requiring bulk monomer for downstream acrylate synthesis.
- Construction Firms:Direct purchasers of wood protection and concrete admixture formulations.
Paint manufacturers hold procurement scale. Electronics manufacturers are rotating up the share rankings.
Distribution Channel:
Channel structure bifurcates between registered producers with direct technical relationships and traders facing documentation decoupling.
- Direct Sales:Long-term contracts with integrated producers supplying certified grades to electronics and automotive customers. BASF and Arkema leverage Ludwigshafen and Carling registrations for direct German and French market access.
- Distributors:Regional stockists managing inventory for mid-scale paint and adhesive formulators. Traders without manufacturing relationships face pressure as buyers unbundle certification from volume.
- Industrial Suppliers:Technical distributors offering formulation support and blending services.
- Online Retailers:Niche platforms serving small-batch research and specialty chemical buyers.
- International Traders:Cross-border merchants navigating REACH import compliance and carbon-border adjustment exposure under EU Green Deal implementation.
Direct sales holds relationship density. Distributors are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs methyl acrylate volumes for waterborne architectural coatings, while Germany and South Korea concentrate demand in semiconductor-grade copolymers for electronics adhesives. This consumption-mix differential shapes how suppliers configure purity tiers and certification portfolios across geographies.
China
Paint manufacturers at Jiangsu and Zhejiang chemical parks drive methyl acrylate consumption for VOC-compliant acrylic emulsions. MEE emission caps enforce substitution of solvent-based systems, consolidating production into coastal parks with integrated wastewater treatment. Ningbo and Shanghai clusters now host specialty acrylate lines serving both domestic coating formulators and export-oriented electronics assemblers.
Germany
Automotive electronics OEMs in Bavaria and Baden-Württemberg specify ECHA-registered methyl acrylate for semiconductor packaging adhesives. REACH registration requirements tighten impurity specifications for imported monomers, raising analytical burdens on non-European suppliers. Ludwigshafen's integrated chemical complex anchors captive propylene oxide feedstock for acrylate ester production serving domestic and neighboring markets.
South Korea
Chip fabricators in Gyeonggi Province and Suwon demand sub-ppm purity copolymer grades for advanced bonding applications. MFDS chemical substance regulations align with customer quality agreements requiring ISO 17025 analytical documentation. Yeosu and Ulsan petrochemical complexes host acrylate derivative capacity feeding both domestic semiconductor packaging and export electronics supply chains.
United States
Coating formulators in Texas and Louisiana rely on Gulf Coast acrylic acid supply for methyl acrylate production. EPA New Chemicals Program reviews slow novel derivative introductions, favoring established producers with existing PMN clearances. Freeport complex operations anchor North American supply with backward integration into crude acrylic acid during normal operating seasons.
India
PLI scheme incentives attract acrylate derivative investment toward Gujarat and Maharashtra specialty chemical parks. BIS standards for industrial chemicals create compliance pathways for domestic formulators previously dependent on Chinese imports. Dahej and Mundra clusters emerge as alternative sourcing hubs as buyers diversify from saturated Chinese coastal zones.
Global Methyl Acrylate Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with production concentration favoring complexes with captive feedstock and registration portfolios. The upper tier commands premium positioning through ECHA-registered supply chains and direct technical relationships with electronics manufacturers. Mid-scale batch operators face margin compression from continuous processing adopters and purity escalation requirements. Competitive moves center on capacity consolidation in low-carbon chemical parks and technology licensing for process intensification upgrades.
Within the integrated leader tier, BASF and Arkema exemplify archetypes combining captive feedstock with regulatory registration depth, while Dow anchors North American positioning through Gulf Coast complex operations. LG Chem and Mitsubishi Chemical Group represent Asia-Pacific producers navigating MEE enforcement and semiconductor-grade purity demands. Shanghai Huayi Acrylic Acid Co., Ltd. occupies a position among Chinese specialists consolidating capacity in coastal chemical parks under environmental compliance pressure.
| Leading Market Players |
|---|
| LG Chem |
| Dow |
| BASF |
| Arkema |
| Mitsubishi Chemical Group |
| NIPPON SHOKUBAI CO., LTD. |
| Evonik Industries |
| Shanghai Huayi Acrylic Acid Co., Ltd. |
| SIBUR INTERNATIONAL |
| Others |
Supply & Pricing Matrix
Waterborne acrylic emulsion substitution for solvent-based coatings simultaneously redistributes methyl acrylate demand toward China's coastal chemical parks and compresses margins for commodity-grade batch producers unable to meet MEE purity thresholds. This substitution dynamic forces European buyers to absorb REACH certification premiums while Asian integrated complexes capture volume growth through captive feedstock economics.
Pricing Analysis
Long-term offtake contracts dominate procurement between integrated producers and electronics manufacturers, insulating semiconductor-grade copolymer pricing from methanol volatility while spot transactions govern commodity monomer flows to paint formulators. Three-tier pricing structure across premium, standard, and economy levels separates ECHA-registered specialty grades from ISO 17025-certified standard tiers and unregistered economy batches. Cost compression in the economy tier is intensifying because Jiangsu and Zhejiang capacity expansions outstrip regional demand absorption. Paint manufacturers in China exhibit highest price sensitivity, while German automotive electronics OEMs prioritize registration depth over unit economics.
Supply Chain Analysis
Inventory buffers at Ludwigshafen-scale complexes extend to six weeks of captive propylene oxide coverage, insulating continuous esterification operations from methanol delivery disruptions. Supply concentrates in China, Germany, and South Korea, with crude acrylic acid feedstock drawing from Gulf Coast, North Sea, and Middle Eastern propylene oxidation capacity. Tariff exposure on non-European monomer imports under EU Green Deal carbon-border adjustments threatens Korean and Saudi export competitiveness. Distribution runs through direct technical relationships for specialty grades and regional stockists for commodity volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The methyl acrylate market functions as a regulatory-moat structure where ECHA registration portfolios and captive feedstock integration create switching costs that entrench incumbents against commodity challengers.
For Market Incumbents: Fortify registration depth by extending ECHA dossier coverage to residual monomer specifications in textile coating applications, countering Arkema's Carling positioning. Secure captive propylene oxide supply through Ludwigshafen-scale complex optimization, defending against Dow's Freeport backward integration. Prioritize continuous reactor yield recovery technology to widen cost advantage over legacy batch operators in China's coastal parks. For New Entrants and Emerging Players: Differentiate on semiconductor-grade copolymer purity by targeting sub-ppm impurity thresholds for South Korean chip fabricators underserved by existing suppliers. Exploit white-space in India's PLI-incentivized specialty chemical parks at Dahej and Mundra, where BIS compliance creates barrier-reduced entry against saturated Chinese zones. Pursue toll manufacturing partnerships with European distributors lacking direct producer relationships. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale continuous processing adopters with incomplete registration portfolios but demonstrated yield optimization capability. Long-term viability favors assets with verified low-carbon process credentials ahead of EU Green Deal carbon-border adjustment full implementation. Monitor ECHA substance evaluation waves targeting acrylate ester toxicity data as signal for registration compliance cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Oxide | Ludwigshafen and Freeport complexes anchor margin stability against methanol price swings. |
| Continuous Esterification Reactor Upgrade | Carling-scale facilities achieve semiconductor-grade purity thresholds through steady-state operation. |
| ECHA Registration Portfolio Extension | Paint manufacturers in France and Italy absorb certification premiums for EU market access. |
| PLI Scheme Capacity Placement in India | Dahej and Mundra clusters diversify supply geography from saturated Jiangsu chemical parks. |
| Digital Twin Process Optimization | Predictive analytics convergence enables real-time purity control in continuous esterification systems. |
Research Methodology
Operator-level perspectives from plant managers at integrated acrylate complexes, procurement leads at German automotive electronics OEMs, and technical R&D directors at coating formulators anchored the qualitative base. Secondary validation drew from ECHA registration dossiers, SEC 10-K filings of listed chemical producers, customs trade data for acrylic acid derivatives, and Cefic sector reports. Bottom-up capacity utilization assessments triangulated against top-down demand modeling across application segments.
Sensitivity analysis tested forecast robustness to methanol price volatility, REACH compliance cost escalation, and MEE enforcement intensity variations across the projection horizon. Segmentation dimensions modeled include grade tier (monomer, copolymer, emulsion), end-use industry (electronics, coatings, textiles), and regional production hub configuration. CAGRs derived from installed capacity expansion schedules weighted by utilization rate assumptions and purity premium capture rates.
The analysis sits within stated boundaries; outcomes outside sustained MEE enforcement at Jiangsu and Zhejiang parks or delayed EU Green Deal CBAM implementation would require recalibration. Forecasts reflect documented assumptions regarding continuous reactor adoption curves and semiconductor packaging adhesive specification trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Anti-Tack Agents Market
Adhesives & Sealants
Structural Adhesives Market
Adhesives & Sealants
Europe Hot-Melt Adhesives Market
Adhesives & Sealants
Dental Impression Tray Adhesives Market
Adhesives & Sealants
Thailand Sealants Market
Adhesives & Sealants
Joint Sealants Market
Adhesives & Sealants
United States Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Middle East & Africa Construction Adhesives & Sealants Market
Adhesives & Sealants
Global Adhesion Promoter Market
Adhesives & Sealants
Middle-East and Africa Reactive Adhesives Market
Adhesives & Sealants
Tile Adhesive Market
Adhesives & Sealants
North America Epoxy Curing Agents Market
Adhesives & Sealants
Asia-Pacific Automotive Adhesives and Sealants Market
Adhesives & Sealants
India Adhesives and Sealants Market
Adhesives & Sealants
Asia-Pacific Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
South America Epoxy Adhesives Market