
 India Travel Insurance Market | 2026-2036
India Travel Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
India Travel Insurance Market Foresight
API-first distribution is fragmenting traditional agency networks across the India travel insurance sector. HDFC ERGO General Insurance leverages proprietary digital platforms to embed policies within airline checkout flows. ICICI Lombard General Insurance anchors its position through direct partnerships with online travel agencies. Bajaj Allianz General Insurance differentiates via specialized coverage for adventure and pilgrimage segments.
Travel insurance constitutes a short-term risk-transfer instrument underwritten against trip cancellation, medical contingencies, and baggage loss during domestic or international journeys; policies typically specify per-occurrence limits, deductible tiers, and territorial exclusions calibrated to destination risk profiles. Single Trip policies dominate premium volume among infrequent leisure travelers, while Multi Trip coverage captures the fastest expansion as frequent corporate flyers seek annualized convenience. Medical Expenses coverage commands the deepest margin pool due to elevated claims severity in North American and European destinations where hospitalization costs scale exponentially.
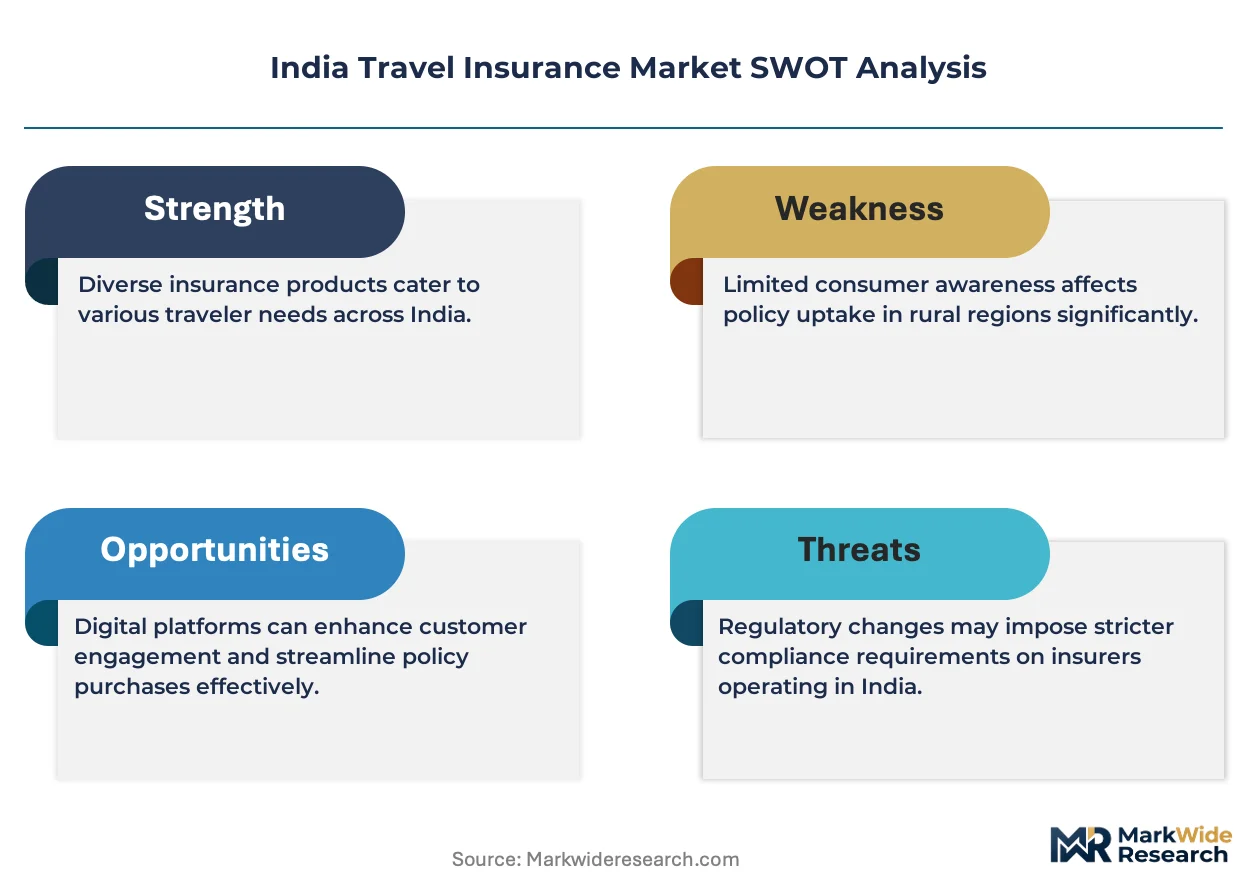
IRDAI mandates solvency margins and product filing approvals that constrain speed-to-market for new coverage variants, while the Insurance Ombudsman framework shapes dispute-resolution standards affecting customer retention. BIS guidelines on data localization intersect with GDPR extraterritoriality for European-bound travelers, complicating cloud infrastructure choices for policy administration platforms. Stakeholders must monitor how embedded finance partnerships with ride-hailing and hospitality platforms reshape customer acquisition economics relative to traditional broker channels.
Market Dynamics
API-first distribution is fragmenting traditional agency networks across the India travel insurance sector, as embedded finance partnerships with airlines and online travel agencies displace conventional broker channels. IRDAI's sandbox regulations for digital insurance products are accelerating this structural shift toward platform-native policy distribution.
Growth Catalysts
- IRDAI Sandbox Framework:The regulator's controlled testing environment permits insurers to pilot parametric and usage-based travel products without full filing approvals, compressing speed-to-market for digital-native offerings.
- Outbound Travel Concentration:Maharashtra and Karnataka generate disproportionate premium volumes as Mumbai and Bangalore residents account for elevated international departure rates, creating geographic demand density that rewards targeted distribution.
- Embedded Distribution Technology:Proprietary digital platforms enable real-time policy issuance within airline checkout flows and hospitality booking engines, reducing customer acquisition friction and expanding addressable touchpoints.
Market Restraints
- Solvency Margin Requirements:IRDAI-mandated capital reserves constrain insurers' capacity to underwrite high-frequency, low-margin travel products at scale, limiting competitive pricing flexibility.
- Claims Severity in Developed Destinations:Medical expense coverage for North American and European territories exposes underwriters to hospitalization cost inflation that outpaces premium rate adjustments.
- Data Localization Compliance:BIS guidelines on domestic data storage intersect with GDPR extraterritoriality for European-bound travelers, complicating cloud infrastructure architecture and increasing operational overhead.
Strategic Opportunities
- Adventure and Pilgrimage Segments:Specialized coverage for trekking, mountaineering, and religious circuit travel remains underpenetrated relative to standard leisure products, offering margin expansion potential.
- Multi-Trip Annual Policies:Frequent corporate flyers seek convenience through single-annual coverage, a product category capturing faster expansion than single-trip alternatives.
- Ride-Hailing and Hospitality Platforms:Embedded finance partnerships with mobility and accommodation aggregators reshape customer acquisition economics relative to traditional broker commissions.
Industry Challenges
- Dispute-Resolution Complexity:The Insurance Ombudsman framework shapes retention standards, yet claim adjudication delays and documentation requirements generate customer friction that erodes renewal rates.
- Legacy System Integration:Established insurers face technical debt when connecting proprietary policy administration platforms to third-party distribution APIs, slowing embedded partnership deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Travel Insurance Market |
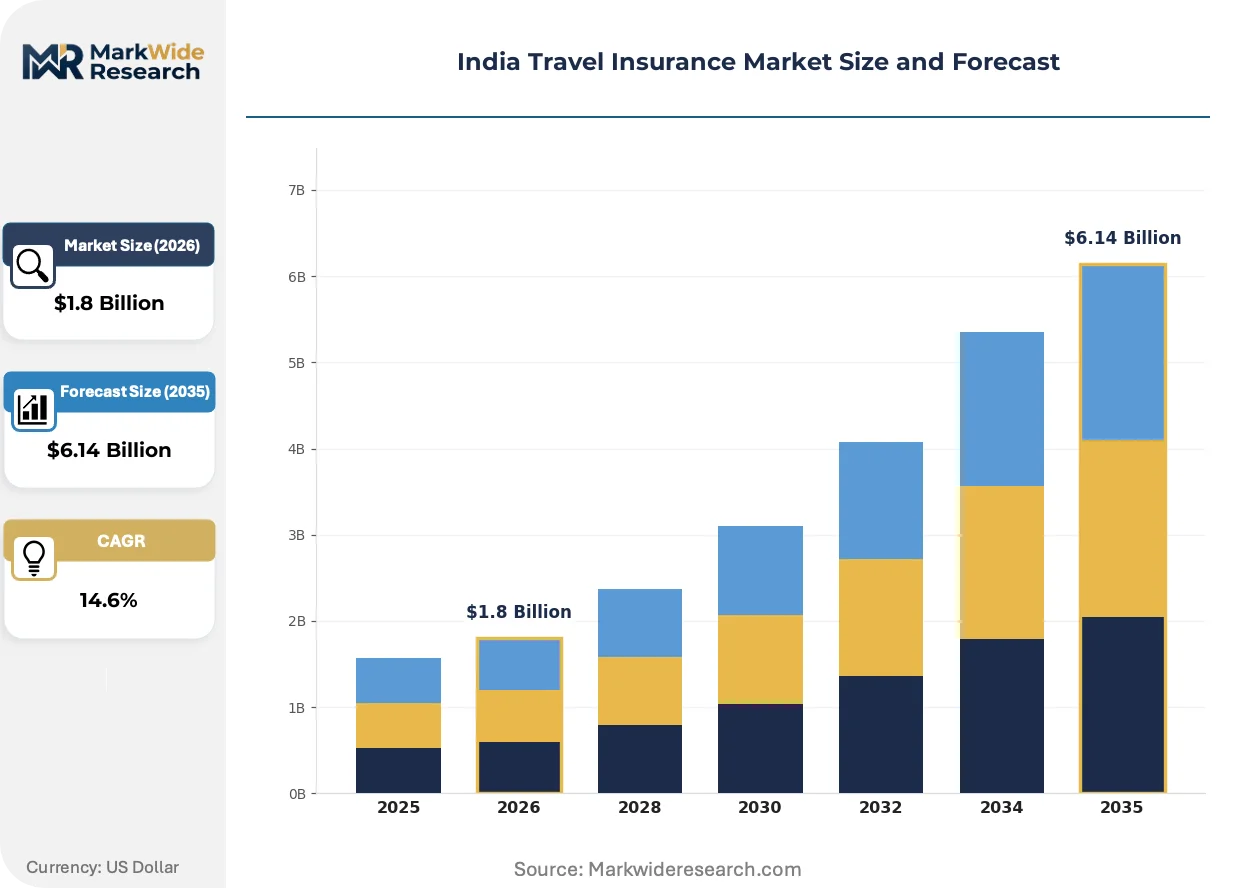
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Single Trip, Multi Trip, Annual, Long-Term Coverage Type: Medical Expenses, Trip Interruption, Loss of Luggage, Emergency Evacuation Customer Segment: Individual Travelers, Family Travelers, Corporate Clients, Student Travelers Distribution Channel: Online Travel Agencies, Insurance Brokers, Direct Sales, Mobile Apps |
| Companies Covered | HDFC ERGO General Insurance, Aditya Birla Travel Insurance, ICICI Lombard General Insurance, SBI Travel Insurance, Future Generali Travel Insurance, Bajaj Allianz General Insurance, Reliance General Insurance, Star Travel Insurance, Tata AIG General Insurance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Travel Insurance Market Shifts & Advancements
Digital underwriting infrastructure is actively reshaping product development cycles and distribution economics across the India travel insurance market. Three convergent developments are compressing traditional value chain segments while opening new customer touchpoints.
Parametric claims settlement is migrating from experimental pilot programs to core product architecture. These automated payout mechanisms trigger disbursements upon verified flight delays or baggage mishandling without manual documentation review. Budget carriers and corporate travel managers are adopting this technology fastest. The shift is compressing claims processing from weeks to hours, forcing traditional insurers to restructure back-office operations or cede price-sensitive segments.
IRDAI's digital insurance sandbox regulations are mandating streamlined product filing pathways for technology-enabled coverage variants. The framework permits controlled market testing of micro-duration and usage-based policies before full regulatory approval. Insurtech partnerships and direct-to-consumer platforms are most affected, responding by accelerating pilot deployments for trip-cancellation and medical expense products targeting specific traveler demographics.
Corporate procurement of group travel coverage is consolidating purchasing authority within centralized travel management functions. This behavioral shift displaces fragmented individual policy purchases by frequent business travelers. The change is most visible among technology and professional services firms headquartered in Bangalore and Hyderabad, where finance teams negotiate annual master policies covering entire employee populations.
India Travel Insurance Market Segmentation
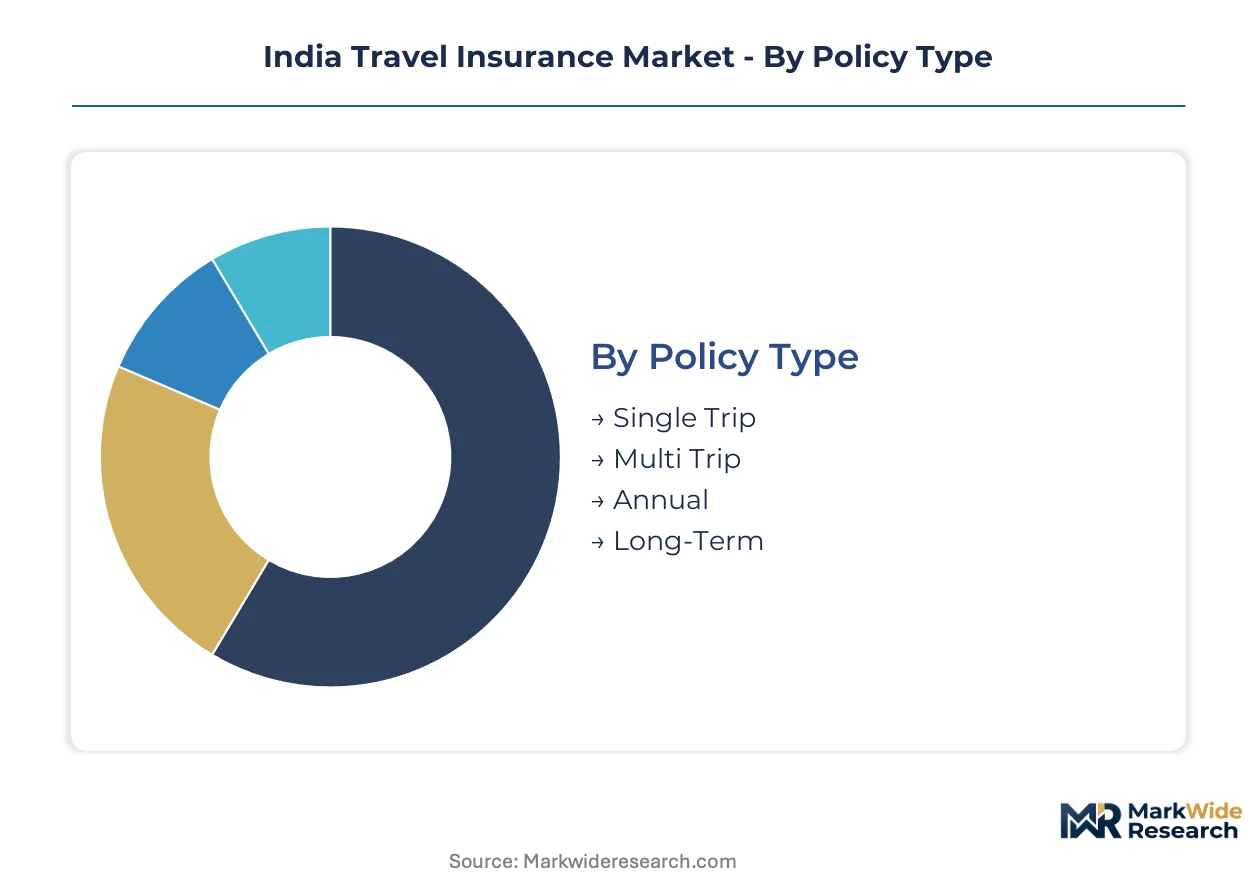
Travel insurance segmentation in India reflects divergent risk profiles across journey frequency, destination medical costs, and procurement authority. Insurers calibrate pricing tiers and distribution channels to match these behavioral clusters, with digital-native segments commanding disproportionate investment.
Policy Type:
Policy duration spans infrequent leisure purchases through annualized corporate convenience, with each tier demanding distinct underwriting economics and renewal mechanics.
- Single Trip:Short-duration coverage activated per journey dominates premium volume among occasional vacationers from Maharashtra and Karnataka. Mumbai and Bangalore residents generate concentrated demand as outbound leisure travel normalizes post-pandemic.
- Multi Trip:Annualized convenience products capture the steepest expansion trajectory as frequent corporate flyers seek administrative efficiency. Bangalore-based technology firms consolidate purchasing through centralized travel management functions.
- Annual:Calendar-year coverage bundles domestic and international protection for high-frequency travelers. Hyderabad professional services firms negotiate master policies covering entire employee populations.
- Long-Term:Extended-duration products serve expatriate assignments and multi-year educational placements. Underwriters price for cumulative medical inflation exposure in North American and European territories.
The dominant share belongs to Single Trip, while Multi Trip is closing the gap fastest.
Coverage Type:
Risk transfer mechanisms align premium pools with claims severity, creating margin stratification across medical contingencies versus baggage inconvenience.
- Medical Expenses:Hospitalization cost protection commands the deepest margin pool due to exponential claims severity in developed destinations. North American and European hospitalization costs outpace premium rate adjustments, compressing underwriting results.
- Trip Interruption:Cancellation and curtailment coverage activates upon documented unforeseen events. Corporate procurement teams in Mumbai prioritize this protection for non-refundable business travel expenditures.
- Loss of Luggage:Baggage protection addresses carrier mishandling and theft incidents. Parametric settlement pilots are compressing claims processing from weeks to hours on this lower-severity line.
- Emergency Evacuation:Medical repatriation and emergency transport coverage addresses catastrophic scenarios. Adventure travel segments in Uttarakhand and Himachal Pradesh drive specialized demand for helicopter evacuation provisions.
Medical Expenses retains the largest premium share, though Emergency Evacuation is gaining traction fastest among adventure and pilgrimage segments.
Customer Segment:
Procurement authority and risk tolerance diverge sharply between individual discretion and corporate purchasing consolidation.
- Individual Travelers:Discretionary purchasers selecting coverage through airline checkout flows and online travel agencies. Price sensitivity dominates, with embedded distribution reducing friction at point-of-sale.
- Family Travelers:Multi-generational coverage units seeking comprehensive protection for dependent travelers. Karnataka households demonstrate elevated attachment rates for medical expense riders on international leisure journeys.
- Corporate Clients:Centralized procurement of group policies displaces fragmented individual purchases. Technology and professional services firms headquartered in Bangalore and Hyderabad negotiate annual master policies.
- Student Travelers:Educational placement coverage spanning semester-abroad and full-degree programs. Long-duration medical expense exposure requires specialized underwriting for university-mandated insurance compliance.
Individual Travelers constitute the volume base, while Corporate Clients are expanding their share most rapidly through group policy consolidation.
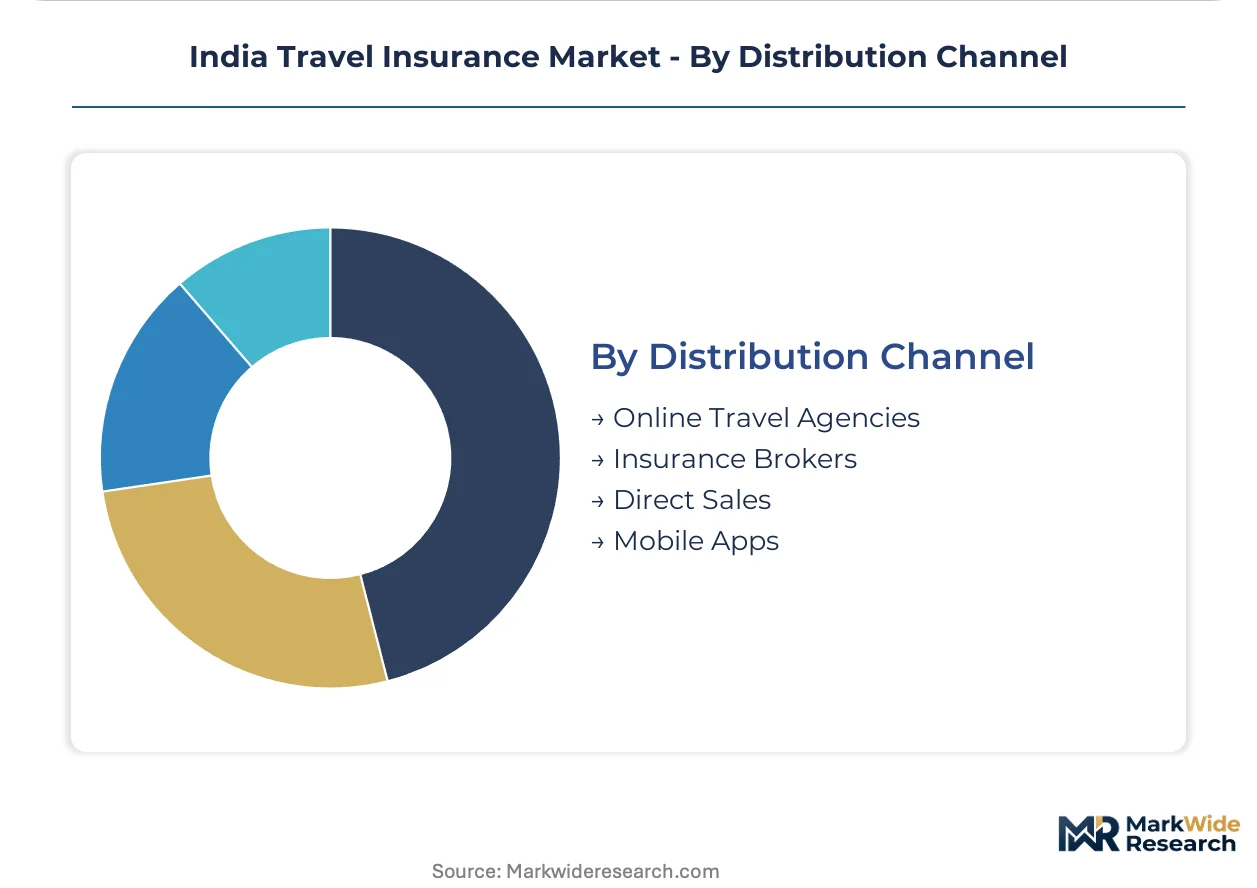
Distribution Channel:
Customer acquisition economics are restructuring as platform-native distribution displaces traditional intermediation.
- Online Travel Agencies:Embedded policy issuance within flight and hotel booking engines captures travelers at peak purchase intent. MakeMyTrip and Yatra anchor this channel with proprietary insurance partnerships.
- Insurance Brokers:Traditional intermediaries retain relevance for complex corporate placements and claims advocacy. Commission structures face compression as direct digital channels expand.
- Direct Sales:Insurer-owned digital platforms and call centers serve price-comparison shoppers. HDFC ERGO and ICICI Lombard invest in proprietary infrastructure to reduce acquisition costs.
- Mobile Apps:Smartphone-native distribution targets younger demographics with instant policy issuance and claims submission. IRDAI sandbox regulations accelerate pilot deployments for micro-duration products on this channel.
Online Travel Agencies command the dominant position, yet Mobile Apps are scaling fastest among digital-native traveler demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's travel insurance flows concentrate along outbound corridors from Mumbai to Dubai and London, with premium generation tracking international departure volumes from western and southern metros. State-level regulatory interpretations and airport infrastructure capacity shape sub-regional market development.
Maharashtra
Mumbai's Chhatrapati Shivaji Maharaj International Airport processes India's highest outbound passenger volumes, driving concentrated demand for Schengen and Gulf destination coverage. The state's insurance regulator enforces IRDAI solvency guidelines with particular scrutiny on travel product filings. Pune's corporate technology parks generate secondary demand through business traveler pools.
Karnataka
Bangalore Kempegowda International Airport anchors South India's premium travel insurance generation, with technology sector employees purchasing high-frequency multi-trip policies. Karnataka's state-level consumer protection forums actively adjudicate travel claims disputes under national Insurance Ombudsman frameworks. Whitefield and Electronic City office clusters drive corporate group policy consolidation.
Delhi-NCR
Indira Gandhi International Airport's connectivity to North American and European destinations exposes underwriters to elevated medical expense claims severity. The National Capital Region's diplomatic and expatriate communities sustain demand for long-term international coverage products. Gurugram's financial services corridor houses regional headquarters for multiple general insurers competing on travel portfolios.
Tamil Nadu
Chennai International Airport's Gulf and Southeast Asia routes support steady single-trip policy volumes among leisure and labor migration segments. Tamil Nadu's state consumer commission enforces strict documentation standards for travel claim settlements. Coimbatore's manufacturing clusters generate corporate travel demand distinct from Bangalore's technology profile.
Telangana
Hyderabad Rajiv Gandhi International Airport's expansion has shifted some South India premium volume away from Bangalore and Chennai corridors. Telangana's startup ecosystem incubates insurtech distribution platforms targeting embedded travel insurance partnerships. HITEC City's professional services firms negotiate centralized group policies covering international consulting travel.
India Travel Insurance Market Competitive Landscape
Channel-controlling players compete with product-specialist players across India's travel insurance sector, creating a tiered structure where distribution access often outweighs underwriting differentiation. The market consolidates around three strategic archetypes: integrated financial conglomerates with proprietary digital platforms, generalist insurers leveraging broker networks, and niche specialists targeting adventure or pilgrimage segments. Dominant competitive moves include embedded partnership formation with online travel agencies and parametric claims technology deployment.
Among integrated financial conglomerates, HDFC ERGO General Insurance and ICICI Lombard General Insurance occupy positions defined by direct airline and OTA distribution control. Bajaj Allianz General Insurance exemplifies the specialization archetype, with brand positioning tied to adventure and religious circuit coverage. These three entities represent distinct competitive vectors: platform-native distribution scale, traditional insurer breadth, and segment-focused product depth.
| Leading Market Players |
|---|
| HDFC ERGO General Insurance |
| Aditya Birla Travel Insurance |
| ICICI Lombard General Insurance |
| SBI Travel Insurance |
| Future Generali Travel Insurance |
| Bajaj Allianz General Insurance |
| Reliance General Insurance |
| Star Travel Insurance |
| Tata AIG General Insurance |
| Others |
Supply & Pricing Matrix
Mumbai's Chhatrapati Shivaji Maharaj International Airport anchors premium concentration as India's busiest outbound corridor, with capacity dynamics at this hub directly translating to pricing power for insurers controlling embedded distribution partnerships with airlines and online travel agencies operating through this gateway.
Pricing Analysis
Cost-plus contracts with medical provider networks in North America and Europe carry automatic indexation clauses tied to hospitalization cost inflation, forcing annual premium recalibration. Three-tier pricing structure across premium, standard, and economy levels segments travelers by destination risk profile and coverage depth. Cost compression in the economy tier is intensifying because embedded distribution partnerships commoditize basic medical and baggage coverage. Individual leisure travelers booking through airline checkout flows exhibit highest price sensitivity, while corporate procurement teams negotiating annual master policies demonstrate lowest sensitivity due to risk-transfer prioritization over premium minimization.
Supply Chain Analysis
Extended payment terms from online travel agencies and airline distribution platforms stretch insurer working capital cycles, with supply-chain finance facilities increasingly bridging receivable gaps. Claims servicing draws from medical provider networks in the United States, United Kingdom, and Thailand, alongside assistance company partnerships for emergency evacuation coordination. Raw material inputs span actuarial data feeds, medical cost databases, and flight status APIs for parametric claims triggering. Single-source vulnerability concentrates in legacy policy administration platforms that struggle with real-time API integration. Distribution runs through embedded partnerships with hospitality aggregators, mobility platforms, and direct insurer digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India travel insurance is recovering through the corporate travel normalization cycle, with business traveler policy volumes rebounding as technology and professional services firms restore pre-pandemic mobility levels.
For Market Incumbents: Pre-empt parametric claims technology deployment by insurtech challengers through accelerated pilot programs for flight delay and baggage mishandling automation. Consolidate API integration capabilities to defend against embedded finance partnerships that disintermediate traditional broker channels. Channel control remains the critical lever for retention. For New Entrants and Emerging Players: Establish a beachhead in adventure travel coverage for Uttarakhand and Himachal Pradesh trekking circuits, where specialized helicopter evacuation provisions remain underpenetrated relative to standard leisure products. Target pilgrimage segment annual policies for religious circuit travelers as the most penetrable white-space opportunity. Pursue direct mobile app distribution with instant policy issuance to bypass incumbent OTA gatekeeper relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors insurers with proprietary parametric claims infrastructure and embedded distribution API portfolios over legacy-dependent generalists. Long-term viability over the coming decade hinges on successful platform-native customer acquisition economics rather than traditional commission structures. Watch IRDAI sandbox approval velocity as the signal indicating regulatory appetite for digital-native product innovation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Claims Technology Deployment | Automated flight delay and baggage mishandling payouts compress processing from weeks to hours, forcing operational restructuring. |
| Embedded Distribution Partnership Formation | Real-time policy issuance within MakeMyTrip and airline checkout flows captures travelers at peak purchase intent moments. |
| Adventure Segment Product Specialization | Helicopter evacuation coverage for Himalayan trekking circuits opens margin expansion in underpenetrated risk pools. |
| Corporate Master Policy Consolidation | Centralized procurement by Bangalore technology firms displaces fragmented individual purchases with annualized convenience products. |
| Mobile-Native Channel Development | Smartphone-first distribution targets younger demographics with instant issuance enabled by IRDAI sandbox regulations. |
Research Methodology
Operator-level perspectives from insurance product managers, airline partnership directors, online travel agency executives, and corporate travel procurement leads anchored the qualitative base. Primary interviews combined with secondary validation from IRDAI regulatory filings, insurance ombudsman dispute records, airport authority passenger statistics, and embedded finance partnership announcements. Bottom-up policy volume estimates triangulated against top-down premium pool calculations across the analysis window.
Scenario-bracketing framed the analytical approach, with optimistic and conservative bounds reflecting corporate travel recovery velocity and medical cost inflation trajectories. Segmentation dimensions modeled include policy duration tier, coverage type, customer procurement authority, and distribution channel architecture. CAGRs derived from trend extrapolation of outbound departure volumes, premium rate adjustments, and embedded partnership penetration curves. Forecast inputs incorporated IRDAI sandbox approval timelines and parametric claims adoption rates.
Stress conditions across corporate travel normalization pace, North American hospitalization cost inflation, and GDPR-BIS data localization compliance friction were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory continuity and technology partnership scalability. Macroeconomic downturn depressing outbound leisure travel, abrupt IRDAI solvency requirement tightening, or insurtech platform security breaches would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
GCC Health Insurance Market
Insurance
India Property & Casualty Insurance Market
Insurance
US Long-Term Care Private Insurance Market
Insurance
Musical Instrument Insurance Market
Insurance
Japan Bancassurance Market
Insurance
EV Insurance Market
Insurance
Financial Guarantee Market
Insurance
Entertainment Insurance Market
Insurance
Saudi Arabia Health & Medical Insurance Market
Insurance
Europe Bancassurance Market
Insurance
UK Dental Insurance Market
Insurance
Aviation Insurance Market
Insurance
Insurance Analytics Market
Insurance
Peru Insurance Market
Insurance
Endowment Insurances Market
Insurance
Telecommunication Insurance Market