
 Europe Transformer Market | 2026-2036
Europe Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Transformer Market Foresight
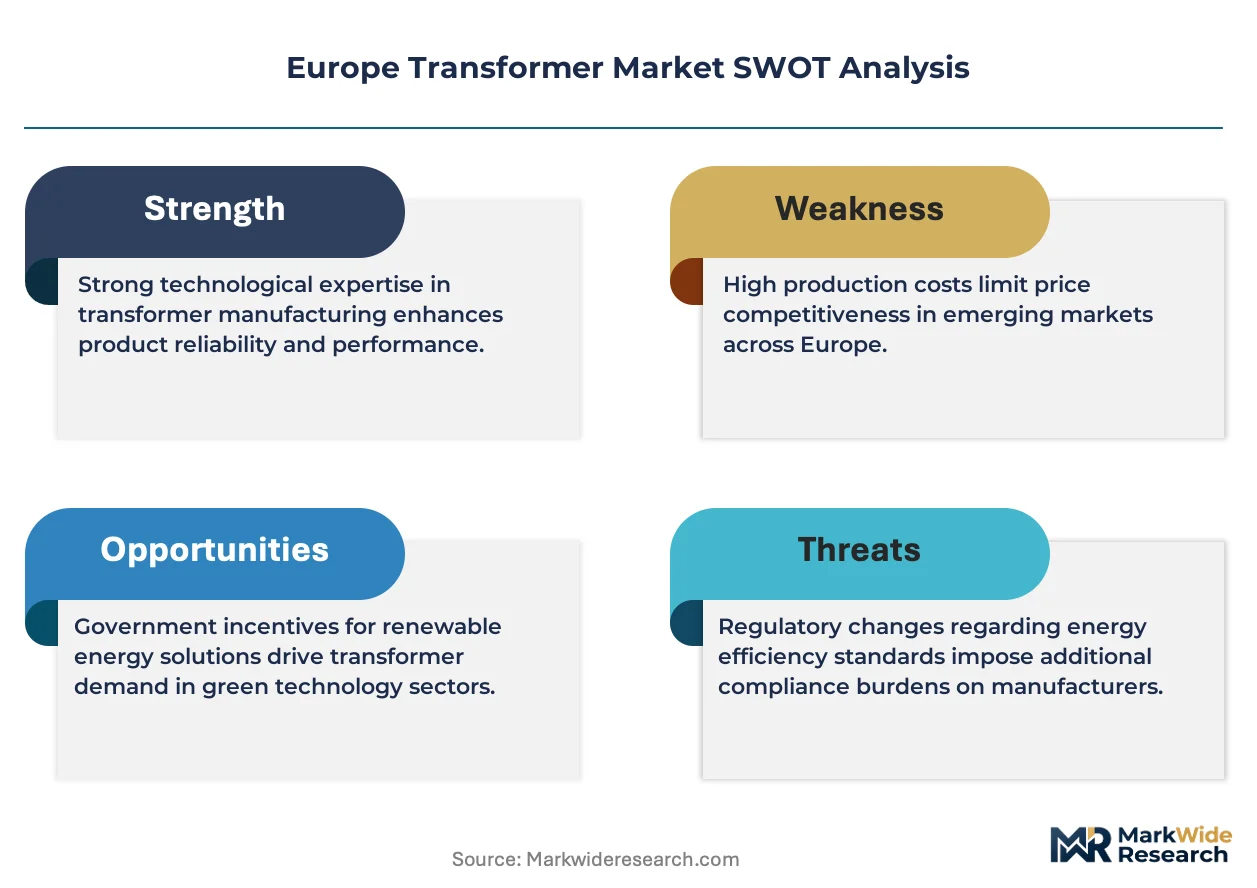
CE marking under the EU's Low Voltage Directive and the F-Gas Regulation is bifurcating the competitive landscape between qualified incumbents and excluded entrants. Siemens Energy sustains manufacturing scale across German and Austrian facilities for grid-scale power transformers. Schneider Electric SE leverages its integrated digital-energy platform to differentiate smart transformer offerings. ABB Ltd. anchors Nordic offshore wind interconnection projects with specialized high-voltage direct current converter stations.
A transformer is an electromagnetic static device that transfers electrical energy between circuits through mutual induction, typically operating at frequencies of 50 Hz or 60 Hz with voltage ratings spanning from distribution-level 11 kV to ultra-high-voltage 765 kV and above. Its core function is to step up voltage for efficient long-distance transmission and step down voltage for safe end-use consumption across industrial, commercial, and residential settings. Oil-immersed technology dominates utility-scale installations due to superior thermal performance and insulation properties, while dry-type units capture commercial and indoor industrial segments where fire safety codes restrict liquid-filled equipment. Step-up transformers lead capital deployment as renewable generation assets require voltage elevation for grid injection, and isolation transformers occupy premium positions in data center and medical applications demanding power quality assurance.
ECHA's REACH framework restricts hazardous substances in transformer fluids and insulating materials, compelling reformulation of mineral oil alternatives and bio-based esters. The EU Green Deal's REPowerEU targets and the F-Gas Regulation's phasedown of fluorinated greenhouse gases are accelerating demand for gas-insulated transformer technologies with lower global warming potential. Stakeholders must monitor the interplay between national grid codes and harmonized EU standards as member states transpose decarbonization mandates into procurement specifications.
Market Dynamics
The EU Green Deal's electrification mandates are compressing procurement timelines for grid-scale power transformers while tightening efficiency thresholds under Ecodesign regulations. Offshore wind developers across the North Sea corridor are accelerating high-voltage unit orders ahead of interconnection deadlines.
Growth Catalysts
- REPowerEU targets:The EU's renewable energy acceleration framework mandates grid reinforcement investments, pulling forward demand for 400 kV and 765 kV step-up transformers at offshore wind injection points.
- Bio-based ester fluids:ECHA's REACH restrictions on mineral oil alternatives are driving adoption of synthetic and natural ester insulating liquids in environmentally sensitive installations across Germany and Denmark.
- Nordic interconnection projects:Grid operators in Norway, Sweden, and Finland are commissioning high-voltage direct current converter stations to balance renewable generation variability across the Scandinavian peninsula.
Market Restraints
- Grain-oriented electrical steel concentration:Supply of specialized transformer core material concentrates among a limited set of European and Asian metallurgical producers, exposing lead times to raw material allocation decisions.
- F-Gas Regulation phasedown:The EU's fluorinated greenhouse gas restrictions are forcing premature retirement of gas-insulated transformer designs using sulfur hexafluoride, compressing replacement cycles before technical end-of-life.
- Copper price volatility:Winding material costs fluctuate with commodity exchange pricing, complicating fixed-price contracting for utility-scale units with eighteen-month production horizons.
Strategic Opportunities
- Polish grid modernization:Poland's coal-to-renewables transition is creating demand for distribution transformers and substation upgrades as the national operator reconfigures network topology.
- Digital twin integration:Convergence of transformer monitoring sensors with cloud-based analytics platforms enables predictive maintenance contracts that extend equipment service life and capture recurring revenue streams.
- CE marking acceleration:The Low Voltage Directive's conformity assessment streamlining is reducing time-to-market for qualified manufacturers seeking cross-border access within the single market.
Industry Challenges
- High-voltage testing capacity:Shortage of certified test bays capable of handling 765 kV units is extending delivery schedules for ultra-high-voltage projects.
- Legacy asset integration:Grid operators face interoperability complexity when connecting smart transformer monitoring systems to decades-old SCADA infrastructure.
- Specialized winding technicians:The craft skill base for precision transformer coil manufacturing is aging across Central European manufacturing regions without adequate apprenticeship pipeline replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Transformer Market |
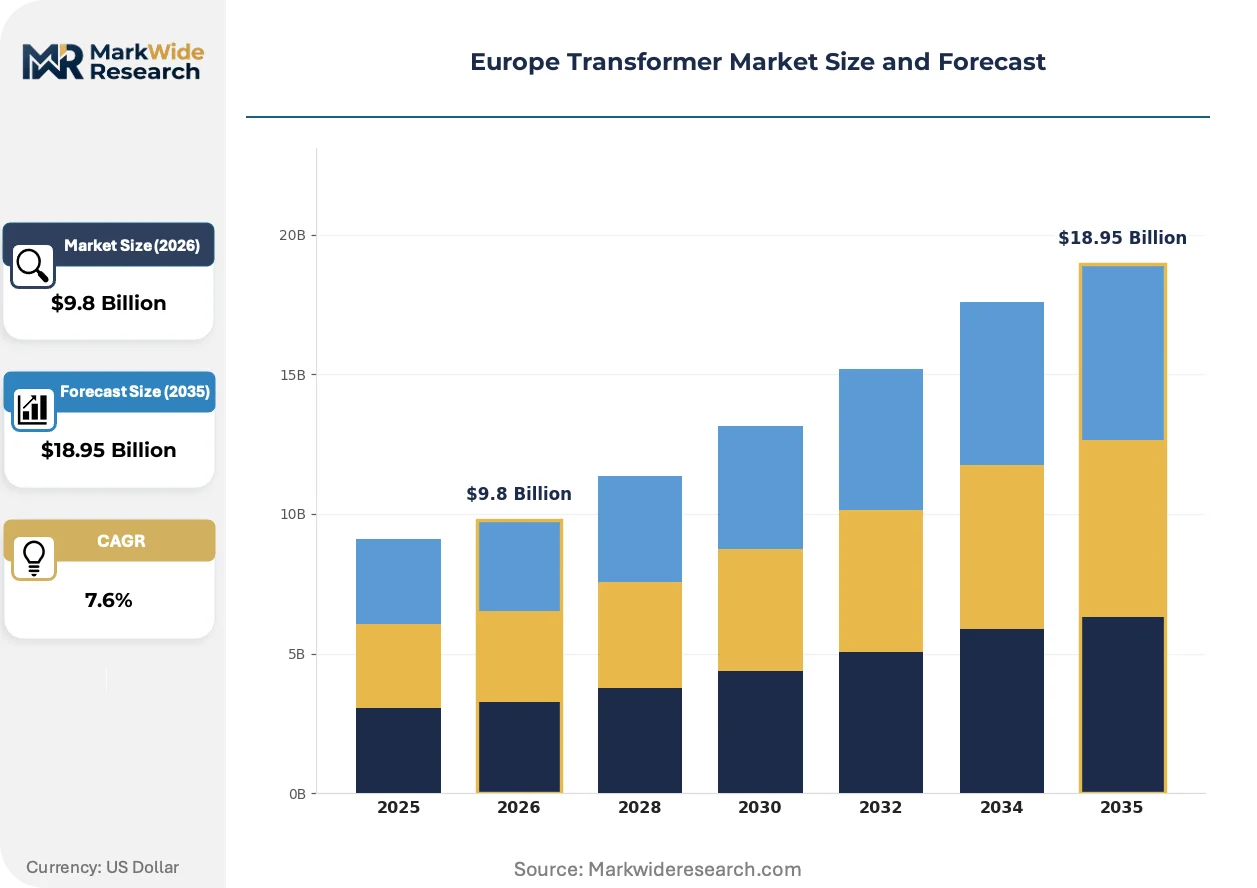
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $18.95 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Step-up, Step-down, Isolation, Auto-transformer Installation: Industrial, Commercial, Residential, Utility End User: Renewable Energy, Oil & Gas, Transportation, Power Generation Technology: Oil-immersed, Air-cooled, Dry type, Vacuum |
| Companies Covered | Schneider Electric SE, SGB-SMIT Group, Hitachi Energy, Efacec Power Solutions SA, Eaton Corporation plc, Siemens Energy, GE Vernova, CG Power Systems Belgium NV, ABB Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Transformer Market Shifts & Advancements
Transformer technology is pivoting toward higher efficiency ratings and integrated digital monitoring as regulatory pressure and grid complexity converge. Material substitution and service model evolution are reshaping competitive positioning.
Natural ester insulating fluids derived from vegetable oil feedstocks are supplanting mineral oil in distribution and power transformer applications where fire safety and environmental risk drive specification. Data center operators and urban substation developers are specifying these fluids to satisfy local authority planning conditions. The shift is compressing demand for conventional petroleum-based insulating oils and redirecting R&D investment toward biodegradable alternatives with comparable dielectric performance.
ECHA's REACH framework is restricting hazardous substances in transformer fluids and solid insulation materials, compelling reformulation of established product lines. Manufacturers are redesigning material stacks to eliminate restricted phthalates and heavy metal stabilizers from gasket and barrier components. The regulatory pressure falls most heavily on small and mid-sized transformer producers lacking dedicated compliance departments, favoring incumbents with integrated chemical safety testing capabilities.
Utility procurement departments are consolidating transformer purchasing through framework agreements that bundle installation, commissioning, and long-term service into single-source contracts. Traditional equipment-only vendors are losing access to major transmission operator tenders as buyers seek lifecycle cost accountability. The consolidation is most advanced in Germany and the Netherlands, where TenneT and similar operators have shifted to performance-based contracting models.
Europe Transformer Market Segmentation
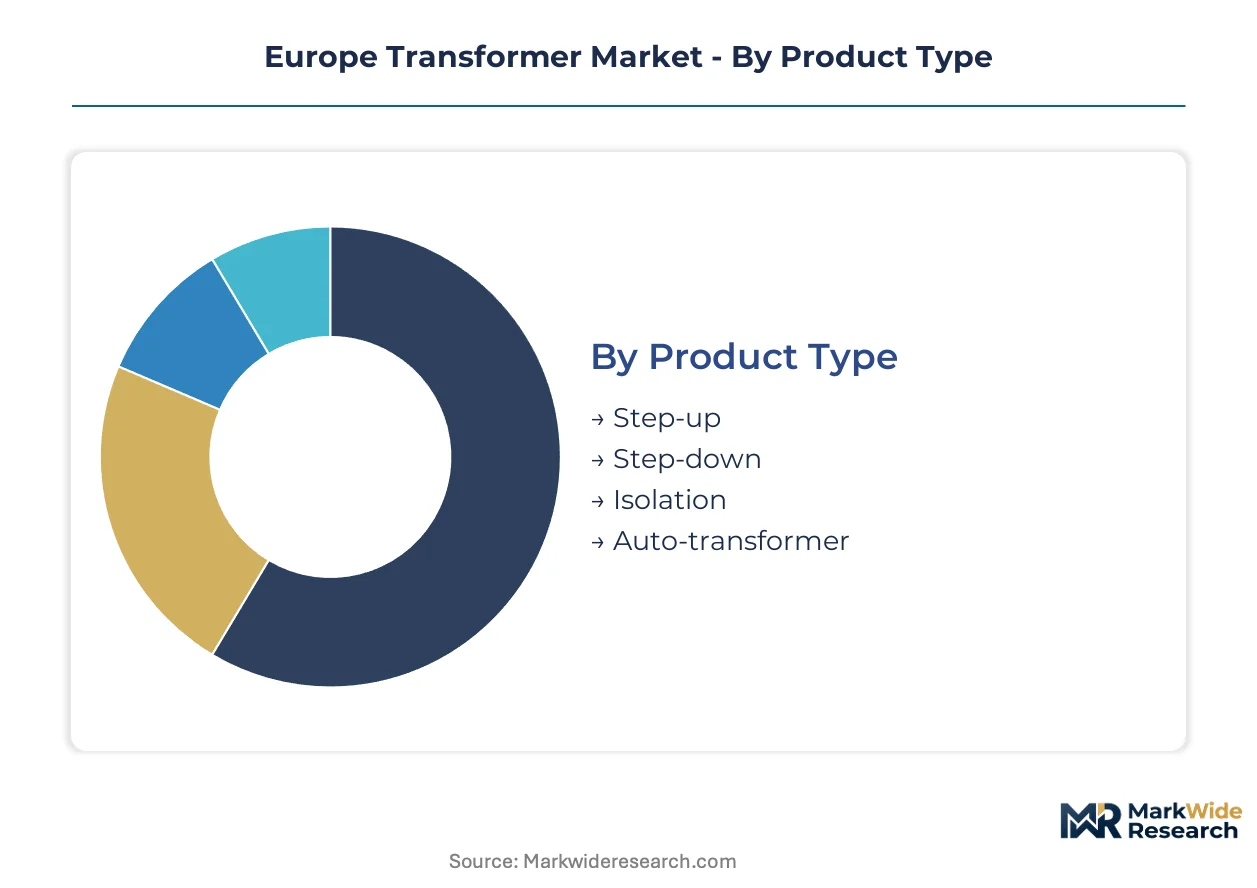
Transformer procurement across Europe bifurcates sharply by application voltage and cooling technology, with margin concentration shifting toward high-voltage units serving offshore wind interconnection. Understanding segment boundaries clarifies where efficiency regulations and material substitution pressures reshape supplier economics.
Product Type:
Margin pools concentrate in high-voltage step-up configurations where specialized core steel and precision winding commands pricing premiums.
- Step-up:These units elevate generator output voltage for efficient long-distance transmission, typically handling 400 kV to 765 kV ratings. North Sea offshore wind developers in Germany and Denmark are pulling forward orders to meet REPowerEU interconnection deadlines. The dominant share belongs to Step-up, while Isolation is closing the gap fastest.
- Isolation:Galvanic separation between primary and secondary circuits protects sensitive loads from voltage transients and ground faults. Data center operators in Frankfurt and Amsterdam clusters specify these units for power quality assurance under strict uptime SLAs.
- Step-down:Distribution-level units reduce transmission voltage to utilizable levels across 11 kV to 132 kV ranges. Polish grid modernization programs are driving replacement demand as coal plant retirements reconfigure network topology.
- Auto-transformer:Single-winding designs offer compact footprint and lower material content for voltage ratios under 3:1. Nordic transmission operators deploy these for grid interconnection where space constraints dominate substation design.
Step-up configurations command the dominant revenue position, though Isolation transformers are gaining share fastest among premium industrial applications.
Installation:
Application setting determines fire safety codes, environmental exposure, and maintenance accessibility requirements.
- Utility:Grid-scale installations at transmission substations and renewable injection points handle the highest power flows. TenneT and similar operators across Germany and the Netherlands are consolidating procurement through lifecycle performance contracts.
- Industrial:Heavy manufacturing facilities require robust units tolerant of harmonic distortion and load cycling. Germany's industrial belt sustains replacement demand as aging assets approach technical end-of-life.
- Commercial:Office complexes and retail infrastructure favor compact, low-noise designs. Urban planning restrictions in Paris and Milan are accelerating adoption of dry-type units with reduced fire risk profiles.
- Residential:Distribution transformers serving low-voltage networks face standardization pressure under Ecodesign efficiency mandates. Local distribution system operators across France and Spain are optimizing procurement through framework agreements.
Utility installations retain the largest installed base, while Industrial applications are expanding most quickly amid manufacturing reshoring initiatives.
End User:
Customer sector alignment determines exposure to electrification policy and commodity price cycles.
- Renewable Energy:Wind and solar generation assets require voltage elevation and grid synchronization capabilities. Offshore wind projects across the North Sea corridor are commissioning specialized high-voltage direct current converter stations.
- Power Generation:Conventional and dispatchable generation facilities need reliable step-up infrastructure for bulk power injection. Combined-cycle gas turbine installations in Italy are driving medium-term demand as coal retirements accelerate.
- Transportation:Rail electrification and EV charging infrastructure require compact, high-reliability units. High-speed rail expansion across Spain is creating demand for traction power transformers with strict harmonic performance specifications.
- Oil & Gas:Upstream and downstream facilities demand explosion-proof and corrosion-resistant designs. North Sea platform electrification projects are specifying compact submersible units for offshore installation.
Renewable Energy commands the dominant demand position, with Transportation climbing fastest as rail electrification accelerates.
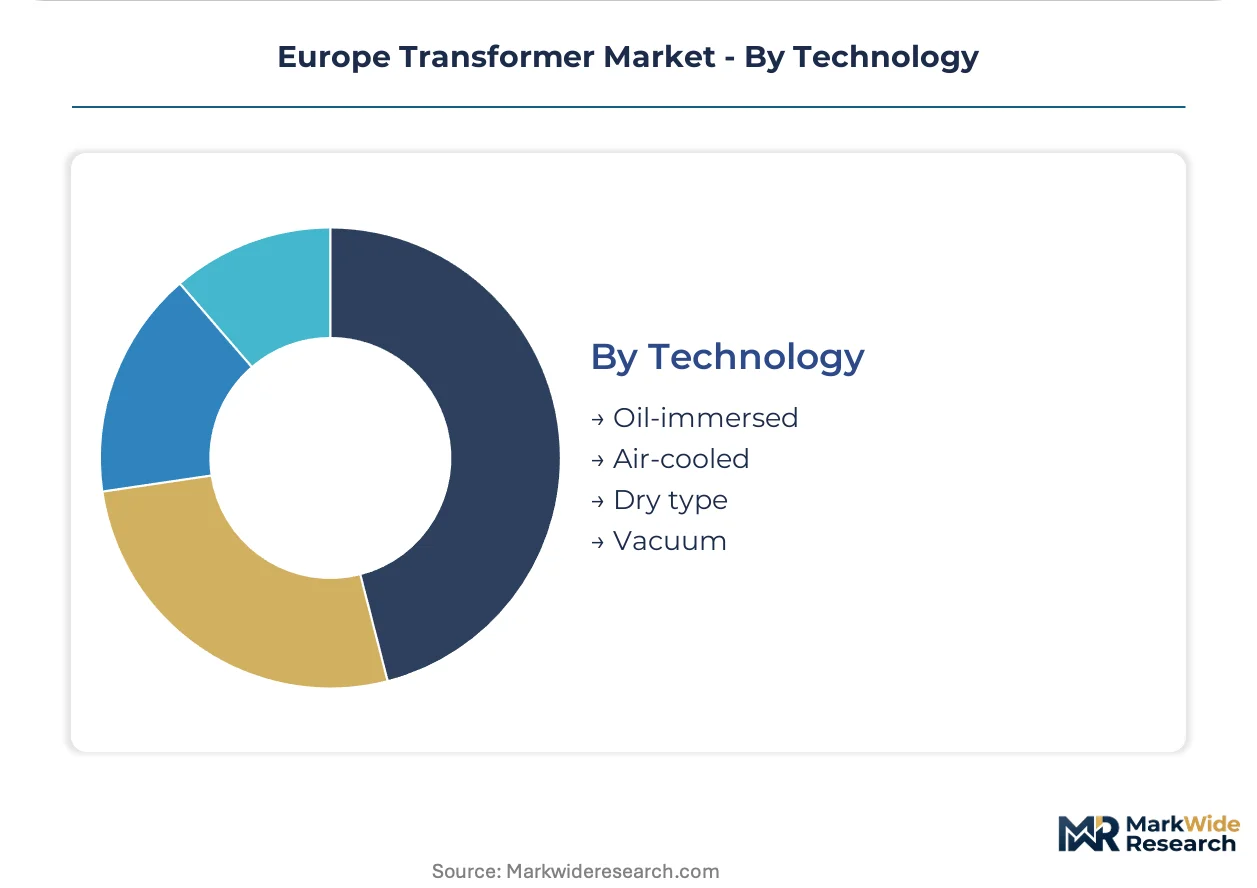
Technology:
Cooling and insulation technology selection balances thermal performance against environmental risk and regulatory compliance.
- Oil-immersed:Mineral oil or ester fluid filling provides superior heat dissipation and dielectric strength for high-power applications. ECHA's REACH restrictions are compelling reformulation toward bio-based ester alternatives in environmentally sensitive German and Danish installations.
- Dry type:Air and solid insulation eliminate liquid fire risk for indoor and urban applications. Data center developers in Frankfurt and Amsterdam are specifying these units to satisfy local authority planning conditions.
- Air-cooled:Forced or natural convection designs serve medium-power applications where oil containment is impractical. Swedish and Finnish distribution networks are adopting these for remote substations with limited maintenance access.
- Vacuum:Vacuum interrupter integration enables compact switchgear combination and reduced maintenance. Specialized applications in medical imaging and semiconductor fabrication require these ultra-reliable configurations.
Oil-immersed technology holds the dominant installed base, though Dry type is gaining share fastest as urban fire codes tighten and bio-based fluids mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's REPowerEU targets and Ecodesign efficiency mandates are compressing procurement timelines for high-voltage units across member states. Grid operators from the North Sea corridor to the Baltic rim are accelerating interconnection investments ahead of renewable integration deadlines.
Germany
TenneT's North Sea offshore wind grid expansion is driving demand for 400 kV and 765 kV step-up transformers at connection points from Emden to Wilhelmshaven. The Federal Network Agency's grid development plans mandate 14 GW of offshore capacity by 2030. Bavaria's industrial belt sustains replacement cycles for distribution transformers as manufacturing reshoring strains aging substation infrastructure.
United Kingdom
National Grid ESO's Great Grid Upgrade requires high-voltage direct current converter stations to interconnect Scottish offshore wind with southern demand centers. Ofgem's price control framework RIIO-2 channels capital toward transmission reinforcement. The Humber cluster and Dogger Bank development zones are commissioning specialized units for 3.6 GW of offshore capacity.
France
RTE's investment program targets 100 TWh of additional renewable integration by 2030, requiring transformer upgrades at solar and onshore wind injection points. The CRE's tariff structure incentivizes grid modernization through regulated asset base expansion. The Grand Est and Hauts-de-France regions are seeing concentrated substation investments to accommodate Belgian and German cross-border flows.
Poland
PSE's coal-to-renewables transition is reconfiguring network topology across the national grid, creating demand for distribution transformers and 220 kV substation upgrades. The National Energy and Climate Plan mandates 23 GW of offshore wind by 2040. The Pomeranian Voivodeship is emerging as a manufacturing and installation hub for Baltic Sea interconnection projects.
Netherlands
TenneT's 2 GW standardization program for offshore grid connections is streamlining transformer procurement through framework agreements. The Dutch Climate Agreement's electrification targets require distribution network capacity expansion in Randstad urban corridors. Rotterdam's port electrification and industrial cluster decarbonization are driving demand for specialized step-down units.
Europe Transformer Market Competitive Landscape
Listed leaders compete with private specialists across technology licensing and service bundling dimensions. The vendor base organizes into three tiers: integrated energy majors with full-lifecycle platforms, regional fabricators with national grid relationships, and technology licensors supplying core components. Archetypes include CE-marking incumbents leveraging conformity assessment scale, ester fluid specialists capturing bio-based substitution demand, and digital-integrated providers selling predictive maintenance contracts. Consolidation pressure is intensifying as framework agreements bundle installation and long-term service, while raw material volatility is forcing hedging partnerships with electrical steel and copper suppliers.
Among France-based integrated energy groups, Schneider Electric SE exemplifies the digital-energy platform archetype. Siemens Energy and ABB Ltd. anchor the high-voltage project tier, representing European incumbents with specialized manufacturing scale for grid-scale and offshore interconnection applications. These three occupy positions that reflect divergent strategic bets on service integration versus equipment specialization.
| Leading Market Players |
|---|
| Schneider Electric SE |
| SGB-SMIT Group |
| Hitachi Energy |
| Efacec Power Solutions SA |
| Eaton Corporation plc |
| Siemens Energy |
| GE Vernova |
| CG Power Systems Belgium NV |
| ABB Ltd. |
| Others |
Supply & Pricing Matrix
CE marking under the EU's Low Voltage Directive gates both supply qualification and price differentiation simultaneously, compressing margins for non-compliant fabricators while enabling certified incumbents to capture service-bundling premiums. Buyers face bifurcated procurement economics where conformity assessment scale translates directly into contract access.
Pricing Analysis
Certification level creates the primary spread between qualified incumbents and excluded entrants. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking status, ester fluid specification, and digital monitoring integration. Cost compression in standard-tier units is intensifying because grain-oriented electrical steel allocation favors volume buyers. Utility procurement departments show lowest price sensitivity due to lifecycle cost accountability, while commercial developers in urban corridors exhibit highest sensitivity to upfront capital outlay.
Supply Chain Analysis
Grain-oriented electrical steel production concentrates in Germany, Japan, and South Korea, exposing European transformer fabricators to raw material allocation decisions by metallurgical specialists. Winding copper draws from Chilean and Peruvian mining output, with refined product flowing through German and Belgian distribution hubs. Single-source vulnerability in specialized core steel creates extended lead time risk for ultra-high-voltage projects. Distribution runs through direct utility framework agreements and EPC contractor intermediaries for industrial installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's transformer market sits in early-cycle expansion as REPowerEU offshore wind targets pull forward high-voltage unit procurement ahead of interconnection deadlines. Grid electrification mandates are accelerating replacement cycles beyond technical end-of-life.
For Market Incumbents: Shield manufacturing scale advantages by securing long-term grain-oriented electrical steel offtake agreements with Nippon Steel and ThyssenKrupp. Deepen backward integration into copper winding production to offset commodity price volatility. Prioritize predictive maintenance platform development to defend against digital-native service competitors.
For New Entrants and Emerging Players: Predictive maintenance service gaps in legacy SCADA integration present white-space opportunity. Target Polish distribution transformer replacement demand where national grid modernization lacks incumbent lock-in. Pursue ester fluid retrofit partnerships with environmentally sensitive German and Danish operators as entry vector.
For Investors and Strategic Acquirers: F-Gas Regulation phasedown reshapes the acquisition landscape toward gas-insulated alternative specialists. Five-to-ten year viability favors vertically integrated fabricators with captive core steel relationships. Monitor Baltic Sea offshore wind lease announcements as inflection indicator for high-voltage order flow acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Ester Fluid Certification | ECHA REACH compliance unlocks German and Danish environmentally sensitive substation contracts. |
| Digital Twin Platform Integration | Siemens Energy and Schneider Electric leverage cloud analytics for predictive maintenance revenue streams. |
| High-Voltage Testing Bay Expansion | 765 kV capability shortage extends delivery schedules for North Sea interconnection projects. |
| Polish Manufacturing Footprint Establishment | PSE grid modernization creates demand for 220 kV substation upgrade capacity. |
| Copper Supply Hedging Partnerships | Commodity exchange volatility complicates fixed-price contracting for eighteen-month production horizons. |
Research Methodology
Initial hypotheses were tested against primary input from utility procurement officers, transformer plant managers, EPC contractors, and grid planning engineers and refined through secondary validation. Primary fieldwork combined structured interviews with secondary triangulation against EU transmission operator investment disclosures, ECHA regulatory filings, and customs trade data for grain-oriented electrical steel flows. Bottom-up unit demand modeling and top-down grid investment aggregation were cross-checked for variance.
Variance decomposition across voltage rating, cooling technology, end-use sector, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level demand build-ups and capacity expansion announcements over the projection horizon. Forecast inputs incorporated offshore wind interconnection timelines under REPowerEU and Ecodesign efficiency mandate compliance curves.
Forecasts assume regulatory continuity in EU Green Deal implementation and F-Gas Regulation phasedown schedules; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as Baltic Sea offshore wind lease awards and national grid code transpositions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
India Transformer Market
Transformers
Neon Transformer Market
Transformers
Rail Traction Transformers Market
Transformers
Asia-Pacific Power Transformer (Below 100 MVA) Market
Transformers
Transformer Steel Market
Transformers
United Arab Emirates Transformer Market
Transformers
Liquid Filled Transformer Market
Transformers
Renewable Energy Transformer Market
Transformers
United States Dry-Type Transformer Market
Transformers
Box Transformer Substation Market
Transformers
Middle East and Africa Transformer Market
Transformers
Locomotive Traction Transformer Market
Transformers
Cast Resin Transformers Market
Transformers
Oil Filled Transformer Market
Transformers
Gas Insulated Transformer Market
Transformers
Transformer Oil Market