
 Asia-Pacific Textile Garment Market | 2026-2036
Asia-Pacific Textile Garment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Textile Garment Market Outlook
Project finance for automated spinning and dyeing facilities is tilting competitive advantage toward capital-rich operators with balance-sheet depth. Shenzhou International Group leverages captive knitting and dyeing capacity to anchor margins on synthetic sportswear contracts. Texhong Textile sustains large-scale cotton yarn output across Jiangsu and Vietnam, competing on spindle count and raw-cotton procurement scale. Raymond Ltd differentiates through in-house worsted weaving and wool finishing, occupying premium formalwear niches that resist commoditization.
Asia-Pacific textile garments encompass finished apparel and intermediate fabrics engineered from natural, synthetic, or blended fibers through weaving, knitting, or non-woven bonding processes, with specifications spanning yarn count, fabric weight, tensile strength, and colorfastness to meet end-use performance requirements. Woven fabrics dominate formal and denim applications where structural stability matters, while knitted fabrics lead growth in stretch-active sportswear and casualwear segments. Technical textiles command margin pools in industrial filtration and medical protective applications, though fashion industry volume still drives overall throughput across spinning and finishing assets.
China's SAMR enforces GB 18401 national general safety technical code for textile products, restricting formaldehyde and azo dye content in garments sold domestically. India's BIS certification scheme for textile products mandates quality benchmarks on fiber content labeling and colorfastness, shaping export readiness for EU and US buyers. Vietnam's Ministry of Industry and Trade coordinates with EU F-Gas Regulation alignment for climate-controlled finishing plants. Stakeholders must monitor how diverging chemical compliance regimes across these jurisdictions reshape sourcing geography and capital allocation for dyeing and finishing capacity.
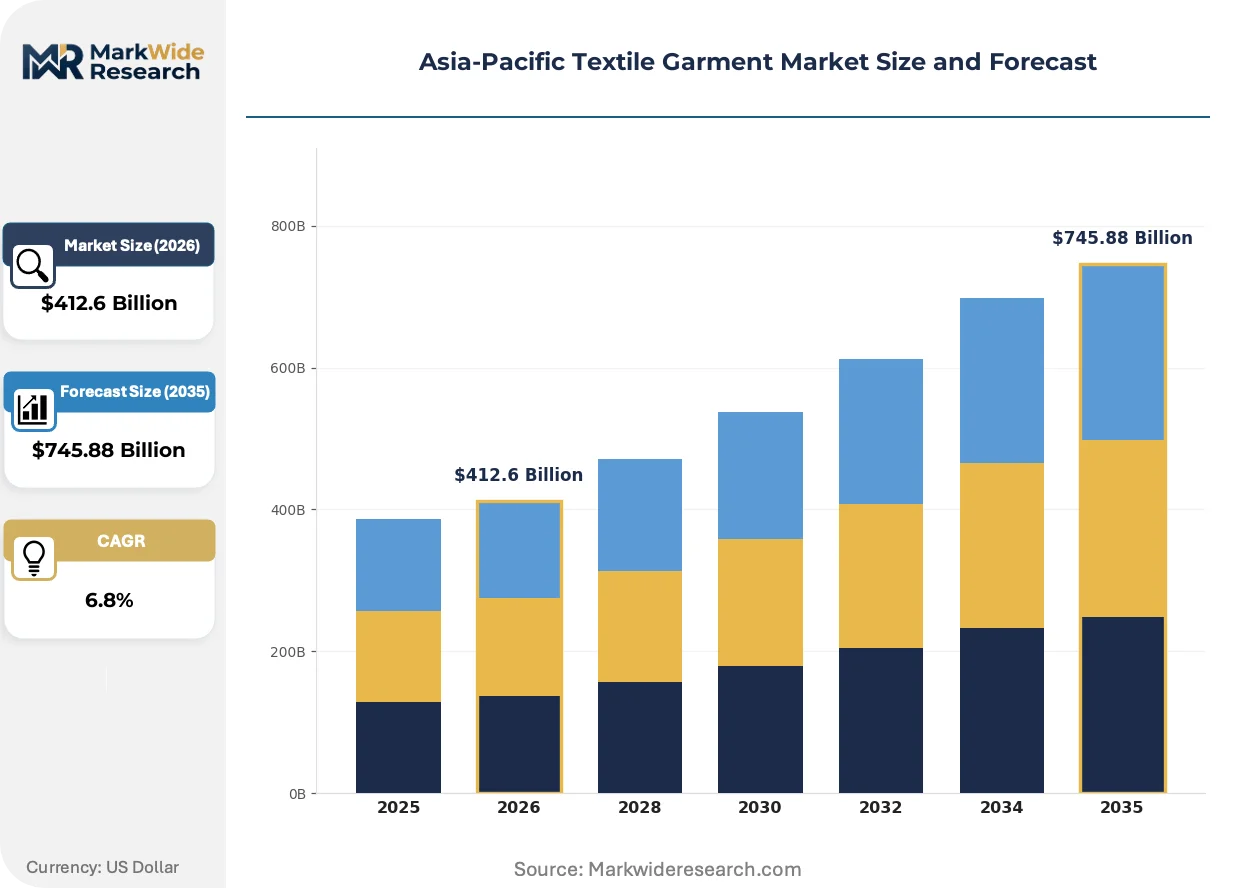
Market Dynamics
China's GB 18401 chemical safety standards are tightening compliance burdens across Yangtze River Delta dyeing clusters, forcing capital reallocation toward effluent treatment and azo-free dye systems while Vietnamese export processing zones capture redirected fast-fashion volume under EU EBA tariff preferences.
Growth Catalysts
- Moisture-wicking knitted fabrics:Southeast Asian sportswear brands are expanding procurement as athletic participation rises across Indonesia, Thailand, and Vietnam.
- EU EBA tariff preferences:Vietnam's garment export processing zones attract European fast-fashion buyers seeking duty-free access, concentrating factory clusters around Ho Chi Minh City and Binh Duong.
- Dual carbon goals:China's MEE enforcement is accelerating renewable energy adoption in Jiangsu and Zhejiang textile parks, lowering carbon-adjusted export costs for compliant operators.
Market Restraints
- Raw cotton price volatility:Xinjiang cotton sourcing restrictions and Indian monsoon variability are compressing spinning margins across South Asia.
- Dyehouse concentration risk:Over 60% of Asia-Pacific synthetic fabric finishing capacity clusters in China's Zhejiang and Jiangsu provinces, exposing supply chains to regional environmental shutdowns.
- Technical textile substitution:Non-woven polypropylene is displacing woven fabrics in single-use medical protective applications.
Strategic Opportunities
- Technical textile expansion:Industrial filtration and medical protective applications command margin pools above commoditized fashion volume.
- India's PLI scheme for textiles:Man-made fiber apparel and technical textile investments qualify for production-linked incentives, redirecting capital from China.
- Digital fabric marketplace penetration:Bangladesh and Vietnam garment exporters are adopting blockchain-verified fiber tracing to meet EU Deforestation Regulation compliance requirements.
Industry Challenges
- Colorfastness certification timelines:India's BIS mandatory quality benchmarks delay export readiness for EU and US buyers by 8-12 weeks.
- Legacy dyeing asset retrofitting:Waterless supercritical CO2 dyeing systems require $15-25 million per installation, stranding mid-scale operators with conventional jet dyeing equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Textile Garment Market |
| Market Size in 2026 | $412.6 Billion |
| Market Size in 2035 | $745.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Fabrics, Knitted Fabrics, Non-woven Fabrics, Technical Textiles End User: Fashion Industry, Sportswear, Home Textiles, Industrial Applications Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Distributors Fabric Composition: Cotton, Polyester, Nylon, Rayon |
| Companies Covered | Toray Industries, Bombay Dyeing and Manufacturing Company Ltd, Shenzhou International Group, Vardhman Textiles Ltd, Raymond Ltd, Weiqiao Textile, Arvind Ltd, Luthai Textile, Texhong Textile Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Textile Garment Market Strategic Shifts
Digital traceability platforms and sustainable chemistry are restructuring competitive advantage across Asia-Pacific textile supply chains, with compliance technology becoming as critical as spindle count in contract negotiations.
Recycled polyester fiber production is hybridizing mechanical and chemical recycling pathways to achieve fiber-to-fiber circularity. Vietnamese and Indonesian sportswear suppliers are adopting mass-balance certified inputs at scale. This convergence is compressing virgin PET resin demand while creating premium pricing tiers for verified recycled content.
China's SAMR enforcement of GB 18401 national general safety technical code is restricting formaldehyde and azo dye content in domestic garments. Dyeing operators in Shaoxing and Changzhou are installing advanced oxidation process effluent treatment to maintain production licenses. Export-oriented synthetic fabric producers face the steepest compliance cost escalation.
European fast-fashion buyers are consolidating supplier rosters and demanding pre-certified chemical compliance documentation. Vietnam's garment export processing zones are responding by embedding third-party testing laboratories within factory clusters. This behavioral shift concentrates procurement volume among operators with captive dyeing and in-house laboratory certification capacity.
Asia-Pacific Textile Garment Market Segmentation
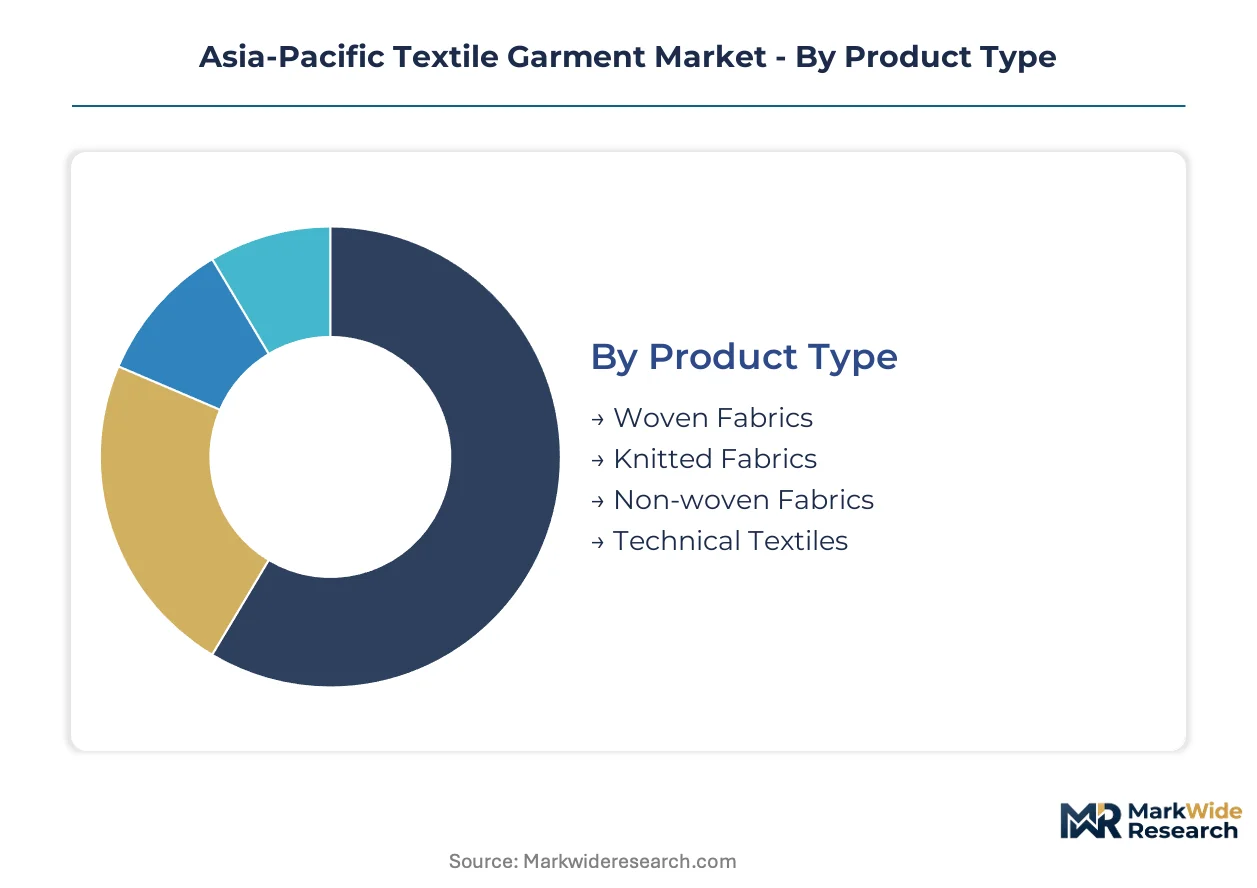
Segmentation reveals how Asia-Pacific textile garment demand fragments across production cycles, from rapid-turn sportswear knits to long-lead technical textile contracts. Understanding these velocity differences shapes inventory positioning and capital allocation for spinning, weaving, and finishing assets across the region.
Product Type:
Cycle times vary dramatically: knitted fabrics turn in 3-6 weeks for fast-fashion replenishment, while technical textiles stretch to 6-12 months for specification-driven industrial orders.
- Woven Fabrics:Interlaced warp and weft yarns create structural stability for formalwear, denim, and shirting applications. Vietnam's garment export processing zones concentrate European fast-fashion demand for rigid denim and poplin shirting under EU EBA tariff preferences.
- Knitted Fabrics:Looped yarn structures deliver stretch and recovery for activewear and casual basics. Southeast Asian sportswear brands in Indonesia and Thailand are expanding procurement of moisture-wicking polyester knits as athletic participation rises.
- Non-woven Fabrics:Fiber-bonded sheets without yarn interlacing serve disposable medical protective and filtration markets.
- Technical Textiles:Engineered performance specifications for industrial filtration, geotextiles, and medical applications command premium margin pools above commoditized fashion volume.
Woven fabrics anchor the volume base while knitted fabrics gain share at the steepest rate.
End User:
Margin structures diverge sharply: fashion industry contracts compete on spindle count and dyehouse scale, while industrial applications reward R&D intensity and certification depth.
- Fashion Industry:Volume-driven apparel for European and North American retail buyers dominates throughput across China and Vietnam factory clusters. China's GB 18401 chemical safety standards are tightening compliance burdens for formaldehyde and azo dye content, forcing capital reallocation toward effluent treatment systems.
- Sportswear:Performance specifications for moisture management, compression, and thermal regulation drive synthetic fiber demand. Vietnamese suppliers are embedding third-party testing laboratories within factory clusters to deliver pre-certified chemical compliance documentation.
- Home Textiles:Bedding, upholstery, and decorative fabrics compete on colorfastness and hand-feel differentiation.
- Industrial Applications:Filtration media, conveyor belting, and reinforcement textiles require tensile strength and chemical resistance certifications.
Fashion industry contracts absorb the highest absolute spindle hours while sportswear specifications expand most quickly.
Distribution Channel:
Channel economics reflect buyer concentration: direct-to-brand distributor relationships dominate bulk contract flow, while online retail fragments order sizes and compresses lead times.
- Online Retail:Direct-to-consumer platforms are compressing traditional wholesale margins and demanding smaller minimum order quantities from Bangladesh and Vietnam garment exporters.
- Specialty Stores:Curated assortments for premium and technical apparel reward certified sustainable sourcing and blockchain-verified fiber tracing.
- Supermarkets:High-volume, low-margin basics compete on price per meter and standardized quality grades.
- Distributors:Aggregated procurement for mid-size regional brands concentrates negotiating power and demands flexible payment terms.
Distributor relationships still control the largest contract value while online retail climbs the fastest.
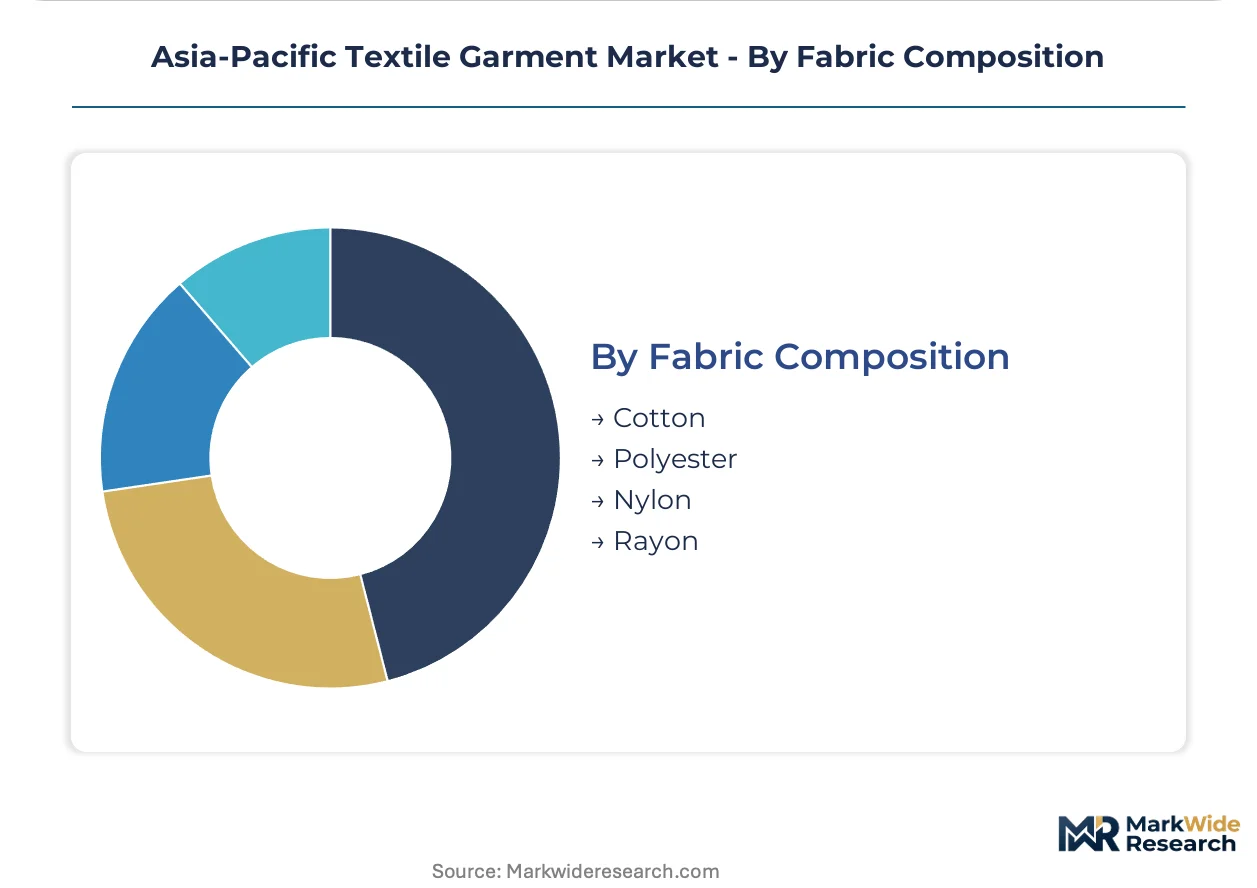
Fabric Composition:
Raw material exposure shapes margin volatility: cotton spinners face Xinjiang sourcing restrictions and Indian monsoon variability, while polyester producers ride recycled PET resin trends.
- Cotton:Natural cellulose fibers dominate comfort-driven casualwear and denim applications. India's BIS certification scheme mandates quality benchmarks on fiber content labeling, shaping export readiness timelines.
- Polyester:Synthetic polymer fibers lead sportswear and performance applications. Vietnamese and Indonesian suppliers are adopting mass-balance certified recycled polyester inputs at scale to meet EU Deforestation Regulation compliance requirements.
- Nylon:Polyamide fibers deliver abrasion resistance for activewear outer layers and industrial applications.
- Rayon:Regenerated cellulose from wood pulp bridges natural hand-feel with synthetic processability for draped fashion fabrics.
Polyester commands the highest synthetic volume while cotton maintains share in premium casualwear segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances across Asia-Pacific textile garment markets are diverging as tariff preferences and compliance costs reshape sourcing geography. Vietnam's trade surplus with the EU is expanding under EBA duty-free access, while China's chemical safety enforcement is elevating domestic production costs and redirecting fast-fashion volume toward Southeast Asian processing zones.
China
Synthetic fabric finishing capacity concentrates in Zhejiang and Jiangsu provinces, serving domestic sportswear brands and export contracts. SAMR enforcement of GB 18401 chemical safety standards is restricting formaldehyde and azo dye content, forcing Shaoxing and Changzhou dyeing operators to install advanced oxidation process effluent treatment systems. Yangtze River Delta textile parks are accelerating renewable energy adoption under MEE dual carbon enforcement to maintain production licenses.
Vietnam
Garment export processing zones around Ho Chi Minh City and Binh Duong are capturing redirected European fast-fashion volume seeking EU EBA tariff preferences. Factory clusters are embedding third-party testing laboratories to deliver pre-certified chemical compliance documentation for consolidated buyer rosters. The Ministry of Industry and Trade coordinates with EU F-Gas Regulation alignment for climate-controlled finishing plants serving synthetic sportswear contracts.
India
Man-made fiber apparel and technical textile investments are qualifying for PLI scheme production-linked incentives, redirecting capital from Chinese competitors. BIS certification mandates quality benchmarks on fiber content labeling and colorfastness, creating 8-12 week export readiness delays for EU and US buyers. Cotton spinning margins face pressure from monsoon variability and Xinjiang cotton sourcing restrictions affecting raw material costs.
Indonesia
Sportswear brands are expanding procurement of moisture-wicking knitted fabrics as athletic participation rises across Java and Sumatra. Mass-balance certified recycled polyester inputs are being adopted at scale to meet EU Deforestation Regulation compliance requirements for export contracts. Factory clusters in West Java are upgrading dyehouse capacity to capture redirected volume from Chinese competitors facing GB 18401 compliance cost escalation.
Thailand
Technical textile production for industrial filtration and medical protective applications is commanding premium margin pools above commoditized fashion volume. Domestic sportswear demand is driving polyester knit fabric imports from regional suppliers while local finishing capacity focuses on higher-value performance specifications. Eastern Economic Corridor textile investments are targeting automotive textile and geotextile applications with longer contract cycles.
Asia-Pacific Textile Garment Market Competitive Environment
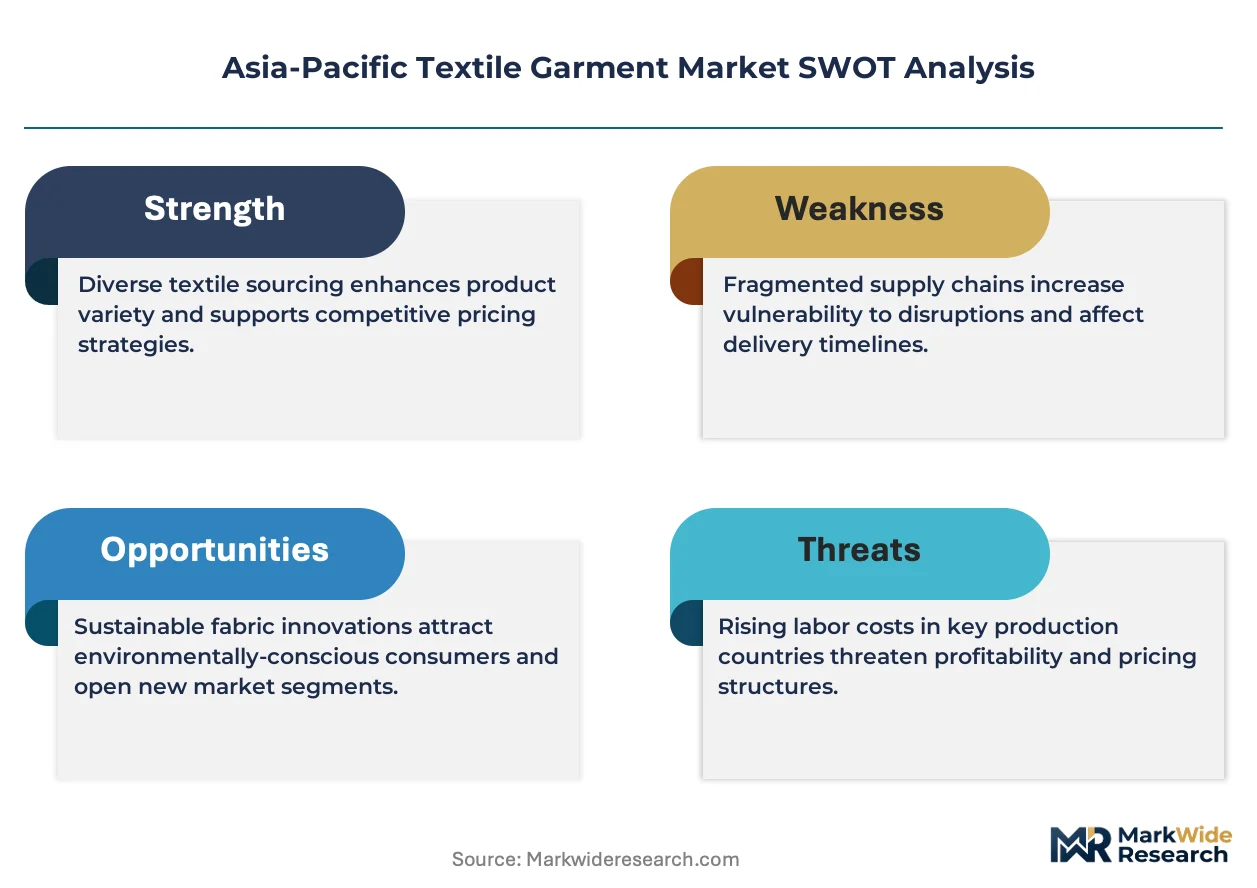
On the supply side, the industry is consolidating around capital-rich operators with captive dyeing and in-house laboratory certification capacity. Mid-scale competitors with conventional jet dyeing equipment face stranding risk as waterless supercritical CO2 systems require $15-25 million per installation. Three strategic archetypes dominate: integrated synthetic sportswear specialists, large-scale cotton yarn producers competing on spindle count, and premium formalwear operators with in-house worsted weaving. Dominant competitive moves include backward integration into fiber production and geographic expansion toward Vietnamese export processing zones.
Within the integrated synthetic sportswear tier, Shenzhou International Group and Texhong Textile Group exemplify capital-rich operators leveraging captive knitting and dyeing capacity to anchor margins on performance apparel contracts. Raymond Ltd occupies a position among premium formalwear specialists, differentiating through in-house worsted weaving and wool finishing that resists commoditization. These three companies represent the strategic archetypes reshaping competitive positioning as compliance technology becomes as critical as spindle count in contract negotiations.
| Leading Market Players |
|---|
| Toray Industries |
| Bombay Dyeing and Manufacturing Company Ltd |
| Shenzhou International Group |
| Vardhman Textiles Ltd |
| Raymond Ltd |
| Weiqiao Textile |
| Arvind Ltd |
| Luthai Textile |
| Texhong Textile Group |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in China's Zhejiang and Jiangsu dyeing clusters is compressing contract margins while forcing suppliers toward EU EBA-compliant Vietnamese facilities, creating divergent pricing power across the Asia-Pacific textile garment market.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across technical textile segments, while fashion industry procurement stratifies across premium, standard, and economy tiers based on certification grade and volume scale. Price differentiation stems from GB 18401 compliance documentation depth and captive dyeing capacity ownership. Cost compression in synthetic sportswear knits is intensifying as European fast-fashion buyers consolidate supplier rosters. Distributor-channel mid-size regional brands exhibit highest price sensitivity, whereas technical textile industrial applications show lowest sensitivity due to specification-driven procurement.
Supply Chain Analysis
Shenzhou International Group, Texhong Textile Group, and Raymond Ltd hold concentrated captive knitting, spinning, and finishing capacity across China and Vietnam. Raw material flows draw from Xinjiang cotton, recycled PET resin, and imported wool fiber. Supply chain risk centers on single-source vulnerability from over sixty percent of synthetic fabric finishing capacity clustering in Zhejiang and Jiangsu provinces. Distribution runs through direct-to-brand relationships for bulk contracts and fragmented online retail channels for smaller order quantities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as European fast-fashion brands consolidate supplier rosters and demand pre-certified chemical compliance documentation, shifting negotiation leverage toward procurement departments.
For Market Incumbents: Insulate margin pools by deepening captive dyeing capacity in Vietnamese export processing zones and embedding third-party testing laboratories within factory clusters. Non-woven polypropylene substitution in medical protective applications threatens woven fabric incumbents. Certification investment in GB 18401 and EU EBA compliance documentation anchors contract renewal rates. For New Entrants and Emerging Players: Build out technical textile production for industrial filtration and geotextile applications in Thailand's Eastern Economic Corridor, where longer contract cycles and lower buyer concentration reduce competitive intensity. India's PLI scheme for man-made fiber apparel offers the most penetrable incentive environment. Go-to-market positioning should emphasize blockchain-verified fiber tracing for EU Deforestation Regulation compliance. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated synthetic sportswear specialists with captive knitting and dyeing capacity serving multi-year brand contracts. Long-term viability over the next decade favors operators with balance-sheet depth for waterless supercritical CO2 dyeing retrofits. Acquisition targets should screen for in-house laboratory certification capacity. Monitor EU EBA tariff preference renewals and China's MEE dual carbon enforcement intensity as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Production | Shenzhou International Group's captive polyester knitting secures margin control on synthetic sportswear contracts. |
| Geographic Expansion toward Vietnamese Export Processing Zones | Texhong Textile's Vietnam spindle count captures EU EBA tariff preferences for European fast-fashion buyers. |
| Waterless Supercritical CO2 Dyeing Retrofit | Shaoxing operators installing advanced oxidation effluent treatment maintain production licenses under SAMR GB 18401 enforcement. |
| Blockchain-Verified Fiber Tracing Deployment | Bangladesh and Vietnam exporters meet EU Deforestation Regulation compliance through digital marketplace penetration. |
| Technical Textile R&D Investment | Thailand's Eastern Economic Corridor targets automotive textile and geotextile applications with premium margin pools. |
Study Parameters
Desk research of customs trade databases, BIS certification registries, and EU EBA tariff documentation preceded structured interviews with spinning plant managers, dyehouse operations directors, European fast-fashion procurement leads, and technical textile R&D heads. Secondary validation drew from SAMR GB standard filings, Vietnam Ministry of Industry and Trade circulars, and India PLI scheme disclosures. Bottom-up spindle count and finishing capacity estimates triangulated against top-down export value flows.
Assumptions held fixed include current EU EBA tariff preference structures and China's dual carbon enforcement trajectory, while raw cotton price volatility and Xinjiang sourcing restriction intensity were modeled as scenario variables. Segmentation dimensions spanned fabric composition, end-use application, and distribution channel across the projection horizon. CAGRs were derived from capacity utilization trends and buyer procurement pattern shifts. Industry-specific inputs included monsoon variability indices for Indian cotton spinning and F-Gas Regulation alignment timelines for Vietnamese finishing plants.
Sensitivities concentrate around EU EBA preference renewal negotiations, China's MEE environmental shutdown enforcement, and recycled PET resin supply constraints. Quarterly review of SAMR compliance cost indices, BIS certification backlog durations, and EU fast-fashion buyer consolidation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
TIC for Apparel Market
Apparel Textiles
Middle East and Africa Textile Garment Market
Apparel Textiles
Smart Apparel Market
Apparel Textiles
Global Western Wear Market
Apparel Textiles
Stockings Market
Apparel Textiles
North America Garment Steamers Market
Apparel Textiles
South America Lingerie Market
Apparel Textiles
Maternity Wear Market
Apparel Textiles
Head Scarves Market
Apparel Textiles
Down Jacket Market
Apparel Textiles
Knitwear Market
Apparel Textiles
North America Insect Repellent Apparel Market
Apparel Textiles
Asia-Pacific Digital Clothing Market
Apparel Textiles
Cooling Apparel Market
Apparel Textiles
Global Prom Dresses Market
Apparel Textiles
Apparel Supply Chain Market