
 Down Jacket Market | 2026-2036
Down Jacket Market Size, Share, and Industry Trends Forecast 2026-2036
Down Jacket Market Analysis
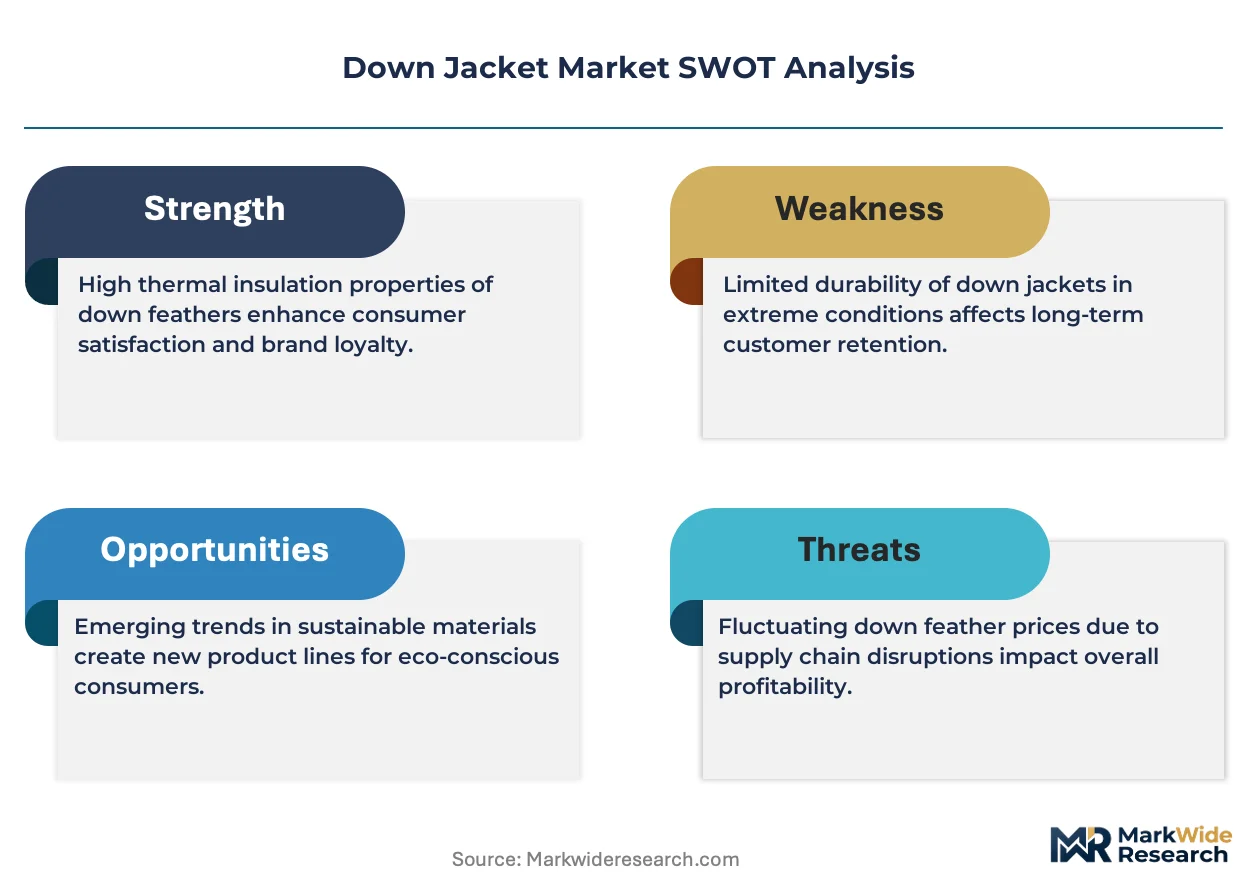
The split between premium performance and mass-market commodity tiers is realigning as fill-power specifications and traceability certifications replace brand heritage as the primary price differentiator. Moncler anchors its position through controlled scarcity and vertical mastery of high-loft goose down sourcing. Uniqlo competes on thermal engineering efficiency, leveraging its Heattech R&D pipeline to democratize lightweight insulation at volume scale. Patagonia differentiates through reclaimed down programs and repair infrastructure that extend product lifecycle value.
Down jackets are thermal garments engineered with quilted chambers containing goose or duck down clusters rated by fill power, where 800-fill and above denotes premium loft-to-weight ratios suitable for sub-zero alpine conditions. The primary commercial purpose centers on portable insulation for cold-weather mobility across urban commuting, expedition climbing, and military applications. Lightweight and packable categories dominate unit volume as consumers prioritize compressibility for travel and layering versatility, while waterproof-bonded constructions command the densest margin pools due to membrane lamination complexity. Specialty stores and online retail together control the highest-value transaction flows, though outlet channels absorb excess inventory from prior-season collections.
REACH chemical restrictions in Europe limit perfluorinated water-repellent treatments, while China's GB standards enforce down origin labeling and species verification. The EU Green Deal's extended producer responsibility frameworks are forcing brands to build take-back infrastructure or surrender market access. Stakeholders must monitor how traceability mandates reshape supplier qualification costs and whether recycled synthetic alternatives displace down in mid-tier price bands before certification investments mature.
Market Dynamics
The EU Green Deal's extended producer responsibility mandates are forcing brands to build circular infrastructure, while fill-power transparency and traceability certifications replace brand heritage as the primary price-setting mechanism across all tiers.
Growth Catalysts
- EU Green Deal textile mandates:Extended producer responsibility frameworks compel brands to establish take-back programs and recycling infrastructure, creating competitive moats for early compliance investors.
- Alpine sports participation surge:Outdoor enthusiasts represent the fastest-expanding buyer segment as expedition climbing and backcountry skiing participation climbs across mountain regions.
- China's domestic manufacturing scale:Local cold-climate consumption and captive supply chain density create self-reinforcing growth loops in the world's largest production hub.
Market Restraints
- Down feather price volatility:Avian influenza outbreaks and feed grain cost spikes create input cost instability that compresses margin predictability for non-integrated brands.
- REACH chemical restrictions:Perfluorinated water-repellent treatment bans limit durable water-resistant coating options, forcing reformulation investments without immediate performance parity.
- Recycled synthetic insulation substitution:PrimaLoft and Polartec recycled fiber technologies threaten mid-tier down displacement as warmth-to-weight ratios improve and vegan positioning gains traction.
Strategic Opportunities
- India cold-chain worker uniforms:Underpenetrated demand from pharmaceutical logistics and food distribution sectors creates institutional procurement channels for insulated workwear.
- Repair infrastructure monetization:Patagonia-style lifecycle extension services enable recurring revenue streams and customer lock-in through certified refurbishment and component replacement.
- Blockchain traceability integration:Convergence of distributed ledger technology with RFID tagging allows real-time origin verification that commands premium positioning in transparency-sensitive segments.
Industry Challenges
- GB standards compliance timeline:China's down origin labeling and species verification requirements demand supplier requalification investments that strain mid-tier brand procurement bandwidth.
- Membrane lamination capex intensity:Waterproof-bonded construction capacity requires specialized lamination equipment that locks capital into long depreciation cycles with limited flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Down Jacket Market |
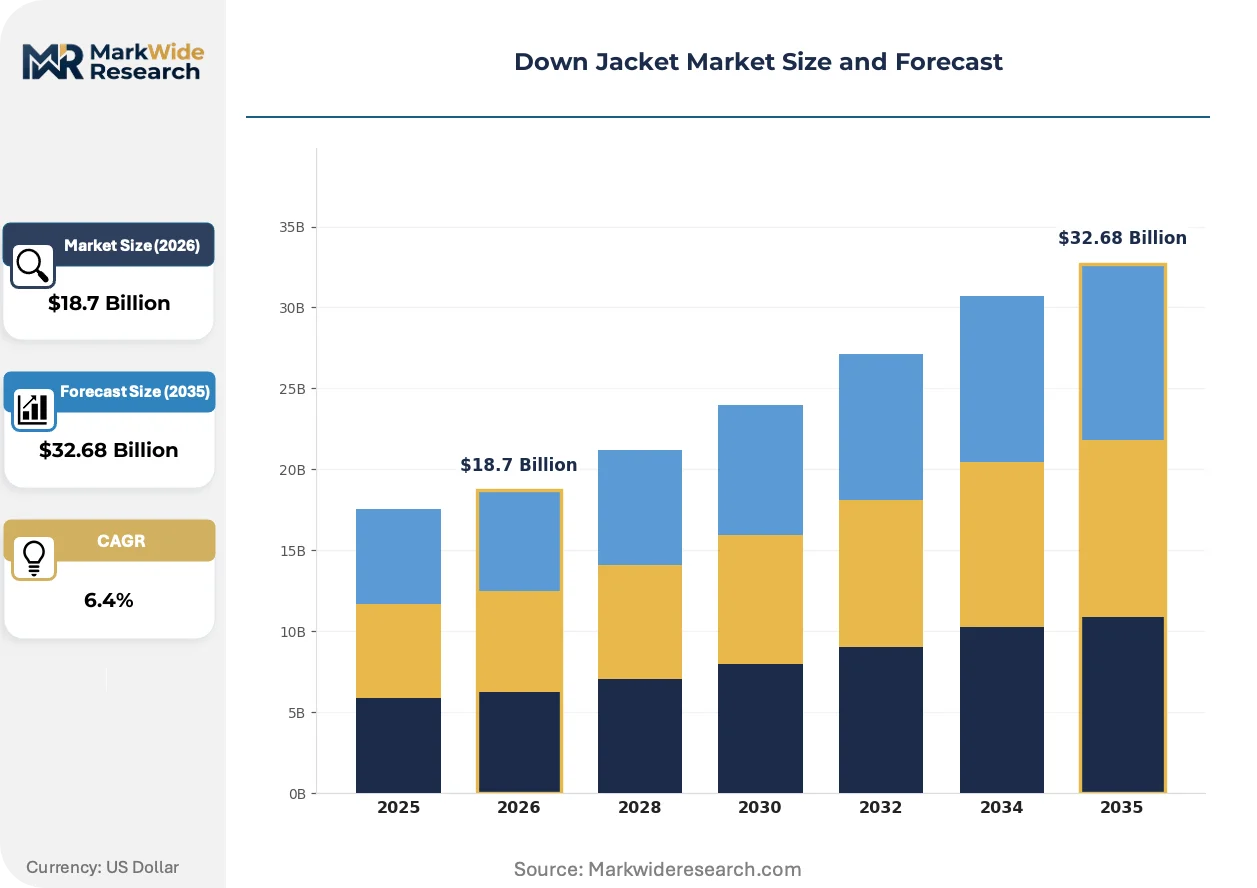
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lightweight, Insulated, Waterproof, Packable End User: Men, Women, Children, Outdoor Enthusiasts Distribution Channel: Online Retail, Specialty Stores, Department Stores, Outlets Fabric Type: Polyester, Nylon, Cotton, Canvas |
| Companies Covered | Patagonia, Uniqlo, Moncler, Woolrich, Rab, The North Face, Arc'teryx, Mountain Hardwear, Canada Goose, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Down Jacket Market Emerging Trajectories
Three intersecting forces are compressing traditional competitive advantages: thermal engineering democratization, regulatory-driven circularity mandates, and traceability technology maturation.
Mechanical stretch-woven face fabrics with inherent water resistance is overtaking laminated membrane constructions in lightweight categories. Alpine athletes and urban commuters are adopting these constructions for their breathability-to-weight ratios. The shift is compressing margin pools previously captured by Gore-Tex and eVent licensors in the sub-400-gram insulation segment.
REACH perfluorinated compound restrictions are eliminating C6 and C8 DWR chemistries from European supply chains. Brands must reformulate with silicone or hydrocarbon alternatives that sacrifice durability and require more frequent re-treatment. Specialty outdoor retailers in Germany and France report elevated return rates as consumers notice performance degradation after fewer wash cycles.
Direct-to-consumer resale platform integration is fragmenting traditional seasonal clearance patterns. Arc'teryx and REI's used gear marketplaces capture value from prior-season inventory while conditioning buyers to expect authenticated secondhand options. This channel rotation is most visible in North American urban markets where sustainability signaling outweighs new-product novelty for routine commuting applications.
Down Jacket Market Segmentation
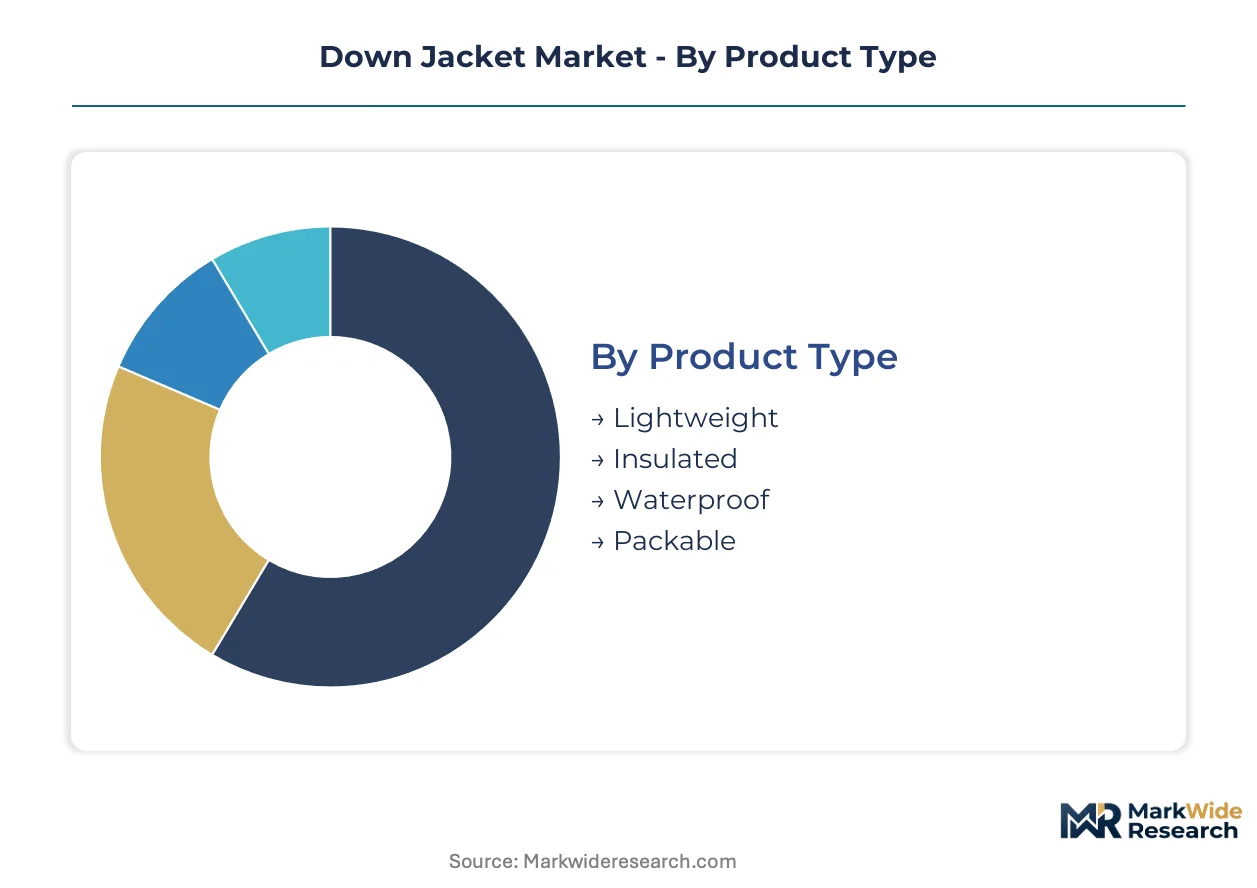
Down jacket segmentation reflects divergent thermal engineering requirements across mobility contexts, with fill-power specifications and construction complexity determining margin architecture. Category boundaries blur as urban commuters adopt alpine-grade packability and outdoor enthusiasts demand waterproof-bonded constructions for mixed-condition use.
Product Type:
Standardization dominates at volume tiers while customization concentrates in technical alpine constructions with fill-power gradations and membrane laminations.
- Lightweight:Quilted chambers with 550-650 fill power down and unlined face fabrics prioritize compressibility for travel layering. Demand clusters in urban commuting corridors across China and Japan where subway-to-office transitions require packable thermal solutions without bulk.
- Insulated:Mid-weight constructions with 700-800 fill power and baffled chamber geometry balance warmth retention with mobility for extended outdoor exposure. Outdoor enthusiasts in the European Alps and North American Rockies drive specification intensity as backcountry skiing participation climbs.
- Waterproof:Bonded membrane laminations with seam-taped down chambers command premium positioning through hydrostatic head ratings and DWR reformulations under REACH restrictions. Technical alpine applications in Norway and Switzerland absorb output from specialized lamination capacity.
- Packable:Ultra-compressible designs with 800+ fill power and stuff-sack integration target expedition climbing and emergency layering. Minimalist construction sacrifices durability for weight reduction in summit push scenarios.
Most installed capacity flows through Insulated. Expansion is steepest in Lightweight.
End User:
Volume concentration follows cold-climate population density while value concentration tracks technical performance requirements and replacement frequency.
- Men:Traditional sizing matrices and neutral colorways dominate unit economics through standardized pattern blocks and reduced SKU complexity. Core demand from North American and European urban markets where commuting applications drive seasonal replacement cycles.
- Women:Expanded size grading and silhouette variation increase pattern development costs but capture premium positioning through fitted construction and color trend responsiveness. Fastest-growing specification intensity in Chinese domestic consumption where local manufacturing enables rapid style rotation.
- Children:Growth-accommodating features and reinforced abrasion zones address durability requirements for school and recreational use. Replacement-driven demand from institutional procurement channels in cold-climate school districts.
- Outdoor Enthusiasts:Technical specification literacy drives fill-power transparency and traceability certification premiums. Alpine sports participation surges across mountain regions in France, Italy, and Austria reshape competitive positioning toward performance verification.
Volume concentration sits with Men. Value expansion is most rapid in Outdoor Enthusiasts.
Distribution Channel:
Margin capture diverges between inventory velocity in off-price channels and customer lifetime value in owned digital infrastructure.
- Online Retail:Direct-to-consumer platforms enable fill-power specification transparency and traceability storytelling that commands premium positioning. Authentication infrastructure for resale marketplaces fragments traditional seasonal clearance patterns in North American urban markets.
- Specialty Stores:Staff technical expertise and fitting services justify margin premiums for complex layering systems and alpine-grade constructions. Concentrated in mountain town economies across Colorado, British Columbia, and the Swiss cantons.
- Department Stores:Assortment breadth and promotional cadence absorb mass-market volume with reduced service intensity. Cold-climate urban centers in the Northeastern US and Northern China maintain residual relevance.
- Outlets:Prior-season inventory liquidation channels capture price-sensitive demand without diluting full-price brand positioning. Excess production from Chinese manufacturing clusters flows through regional outlet networks.
Transaction value concentrates in Online Retail. Physical footprint expansion is fastest in Specialty Stores.
Fabric Type:
Material selection balances weight minimization, abrasion resistance, and regulatory compliance across water-repellent chemistry restrictions.
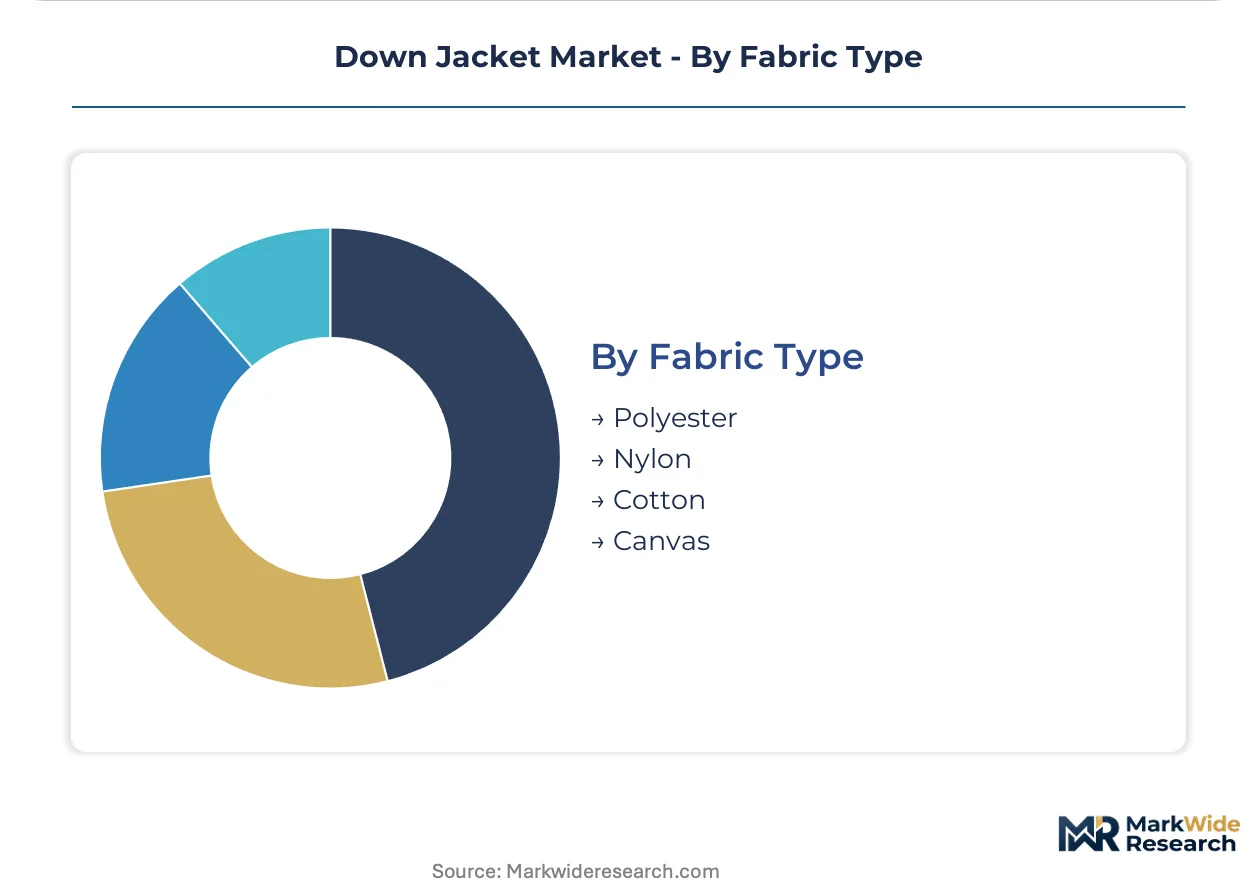
- Polyester:Recycled fiber feedstocks and mechanical stretch constructions dominate lightweight categories with inherent water resistance. REACH perfluorinated compound restrictions accelerate adoption in European supply chains.
- Nylon:High tenacity yarns and ripstop weaves provide tear resistance for technical alpine applications. Lamination compatibility sustains relevance in waterproof-bonded constructions despite DWR reformulation challenges.
- Cotton:Woven face fabrics with waxed or oil-based treatments serve heritage-positioned urban styles with limited technical performance claims. Niche positioning in Japanese and British markets with aesthetic durability preferences.
- Canvas:Heavyweight duck weaves with synthetic insulation hybrids address workwear and military procurement specifications. Institutional demand from cold-chain logistics uniforms in India and pharmaceutical distribution sectors.
Production volume flows through Polyester. Technical specification intensity is climbing fastest in Nylon.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technical design talent concentrates in alpine manufacturing clusters across Switzerland, Italy, and France where cold-climate garment engineering expertise has accumulated over decades. Workforce mobility between these centers transfers specialized knowledge in high-loft down processing and membrane lamination techniques.
China
Domestic cold-climate consumption in Beijing, Harbin, and Shenyang drives specification intensity for packable urban designs. GB standards enforced by SAMR mandate down origin labeling and species verification across all retail channels. The Yangtze River Delta manufacturing corridor around Suzhou and Hangzhou hosts vertically integrated suppliers controlling captive goose down sourcing from Anhui and Jiangsu provinces.
United States
Backcountry skiing participation surges across Colorado, Utah, and Montana, elevating demand for waterproof-bonded alpine constructions. EPA oversight of perfluorinated compound discharge limits DWR chemistry options, forcing reformulation toward silicone-based alternatives. The Denver-Boulder corridor anchors specialty retail density and technical product development talent pools.
Germany
REACH restrictions administered by ECHA eliminate C6 and C8 DWR treatments from European supply chains, compelling chemistry transitions. Munich and Stuttgart host engineering-focused outdoor brands with deep supplier relationships in Bavarian textile processing clusters. Berlin's direct-to-consumer startup ecosystem experiments with resale platform integration and circular service models.
Japan
Urban commuting patterns in Tokyo, Osaka, and Sapporo prioritize lightweight compressibility for subway-to-office transitions. METI guidelines on textile recycling infrastructure support extended producer responsibility pilot programs in Kanto and Kansai regions. Nagoya's technical textile manufacturers supply mechanical stretch-woven face fabrics with inherent water resistance.
Switzerland
Alpine expedition climbing in the Bernese Oberland and Valais cantons sustains demand for 800+ fill-power summit-grade constructions. Swissmedic-adjacent textile testing protocols influence performance certification standards adopted across EU markets. The Zurich-Geneva corridor concentrates design studios serving luxury positioning and technical alpine specifications simultaneously.
Down Jacket Market Vendor Landscape
Top-tier vendors anchor premium positioning through controlled scarcity and vertical mastery of high-loft goose down sourcing, while mass-market players compete on thermal engineering efficiency and volume scale. The vendor base stratifies across three functional tiers: heritage luxury houses, technical alpine specialists, and fast-fashion thermal democratizers. Two dominant competitive moves define current dynamics: backward integration into captive down supply chains, and direct-to-consumer resale platform construction to capture circular value.
Within the technical alpine specialist tier, Arc'teryx and Rab exemplify engineering-first positioning through advanced membrane lamination and baffle construction expertise. Among heritage luxury houses, Moncler occupies a position defined by scarcity economics and vertical control over rare white goose down sourcing. Patagonia represents the circular service archetype, anchoring competitive differentiation through reclaimed down programs and repair infrastructure that extend product lifecycle value.
| Leading Market Players |
|---|
| Patagonia |
| Uniqlo |
| Moncler |
| Woolrich |
| Rab |
| The North Face |
| Arc'teryx |
| Mountain Hardwear |
| Canada Goose |
| Others |
Supply Flow & Price Mechanics
Specialized down-processing labor pools in Anhui and Jiangsu provinces anchor cost structures across tier spreads, with wage differentials between Chinese manufacturing clusters and European finishing facilities amplifying the premium-to-economy price gap by threefold or more.
Pricing Analysis
Bundled lifecycle services versus unbundled product-only transactions now split the market's pricing architecture. Three-tier pricing structure across premium, standard, and economy levels captures differentiation through fill-power certification grade and after-sales repair infrastructure. Cost compression in the economy tier is intensifying because recycled synthetic insulation alternatives erode down's warmth-to-weight advantage. Mass-market urban commuters exhibit highest price sensitivity, while alpine expedition buyers accept premiums for traceability-verified 800+ fill-power sourcing.
Supply Chain Analysis
Single-source vulnerability sits with China's Yangtze River Delta corridor, where captive goose down sourcing from Anhui province feeds vertically integrated suppliers. Manufacturing draws from China, Vietnam, and Bangladesh for cut-and-sew operations, while raw material inputs rest on goose down clusters, high-tenacity nylon yarns, and membrane lamination films. Tariff exposure on US-bound shipments compounds margin pressure for non-integrated brands. Distribution runs through direct-to-consumer platforms, specialty mountain-town retailers, and regional outlet networks liquidating prior-season inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play between China's GB standards compliance costs and Europe's REACH-driven chemistry reformulation investments, with regulatory divergence creating margin capture opportunities for dual-certified suppliers.
For Market Incumbents: Acquire blockchain traceability infrastructure to defend against recycled synthetic insulation substitution threatening mid-tier positioning. Deepen upstream control over captive goose down sourcing in Anhui province to insulate margin predictability from avian influenza volatility. Lock in lamination equipment capacity before membrane-bonded construction capex cycles lengthen. For New Entrants and Emerging Players: Begin with India's cold-chain worker uniform segment, where pharmaceutical logistics and food distribution procurement channels remain underpenetrated by insulated workwear specialists. Target institutional buyers in Mumbai and Hyderabad with canvas-synthetic hybrid constructions certified for industrial abrasion standards. Pursue certified refurbishment service partnerships to capture circular revenue without full manufacturing investment. For Investors and Strategic Acquirers: Technical outdoor apparel conglomerates are the most active acquirer in this space, consolidating alpine-specialist brands with membrane lamination expertise and established mountain-town retail footprints. The long-term viability window favors targets with verified reclaimed down programs and repair infrastructure already generating recurring revenue. Watch for inflection when China's SAMR accelerates GB standards enforcement timelines, triggering supplier requalification cost spikes that strain mid-tier brand procurement bandwidth.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Down Sourcing | Secures Anhui province supply clusters against avian influenza price volatility. |
| Blockchain Traceability Platform Launch | Enables real-time origin verification commanding premium positioning in EU markets. |
| Repair Infrastructure Monetization | Creates recurring revenue streams through certified refurbishment and component replacement. |
| REACH-Compliant DWR Reformulation | Transitions silicone-based chemistry ahead of perfluorinated compound bans enforced by ECHA. |
| Direct-to-Consumer Resale Marketplace | Captures circular value from authenticated secondhand transactions in North American urban corridors. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with brand sourcing directors, specialty retail buyers, textile chemical engineers, and down processing facility managers combined with secondary validation from customs trade records, SAMR regulatory filings, and alpine sports participation databases. Triangulation across stakeholder inputs and documentary sources ensures cross-verified demand and supply estimates.
Input-output matrices map fill-power specifications, construction complexity tiers, and distribution channel economics across the projection horizon. Segmentation dimensions include product type, end-user archetype, fabric technology, and regional regulatory cluster. CAGRs derive from modeled unit-volume trajectories and average selling price evolution, with thermal engineering efficiency gains and sustainability certification premiums as key forecast inputs.
Several conditions sit outside the modeled scope, including acute avian influenza pandemic scenarios, abrupt REACH chemistry bans without transition periods, and synthetic insulation breakthroughs achieving down-comparable warmth-to-weight ratios. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Dye Sublimated Apparel Market
Apparel Textiles
Bridal Wear Market
Apparel Textiles
North America Textile Garment Market
Apparel Textiles
Maternity Leggings Market
Apparel Textiles
Waterproof Fabrics for Sports Apparel Market
Apparel Textiles
School Uniform Market
Apparel Textiles
Asia-Pacific Digital Clothing Market
Apparel Textiles
South America Lingerie Market
Apparel Textiles
Global Socks Market
Apparel Textiles
Stockings Market
Apparel Textiles
Maternity Wear Market
Apparel Textiles
North America Insect Repellent Apparel Market
Apparel Textiles
Middle East and Africa Footwear Sole Material Market
Apparel Textiles
Cleanroom Apparels Market
Apparel Textiles
TIC for Apparel Market
Apparel Textiles
Automotive Textiles Market