
 Global Prom Dresses Market | 2026-2036
Global Prom Dresses Market Size, Share, and Industry Trends Forecast 2026-2036
Global Prom Dresses Market Outlook
EU REACH is repositioning the cost-of-entry calculus for formalwear suppliers by mandating restricted substance declarations across synthetic dye and embellishment chemistries. Jovani leverages its vertically integrated US manufacturing to bypass extended European compliance timelines. Sherri Hill anchors its competitive stance through direct-to-consumer digital channels that reduce intermediary certification burdens. Pronovias differentiates via controlled European atelier production that already aligns with ECHA documentation standards.
Prom dresses constitute formal evening garments engineered for single-occasion ceremonial wear, typically constructed with boned bodices, layered skirt architectures, and hand-finished seamwork requiring precision tailoring. Silk and satin material segments command premium positioning due to natural fiber breathability and drape fidelity that synthetic alternatives struggle to replicate. Ball gown silhouettes sustain the largest volume share within dress style architecture, while sheath constructions represent the fastest-growing profile among minimalist aesthetic preferences. Floor-length configurations dominate revenue pools, though tea-length variants are expanding share among retro-influenced consumer cohorts.
The US Consumer Product Safety Commission governs flammability standards for formal textiles, while California's Proposition 65 imposes disclosure obligations on formalwear containing designated chemicals. The EU Green Deal and France's AGEC law are accelerating circularity mandates that will reshape end-of-life obligations for ceremonial apparel. Stakeholders must monitor how emerging extended producer responsibility frameworks in Germany and Italy will alter inventory risk models for seasonal prom collections.
Market Dynamics
EU REACH compliance timelines and California's Proposition 65 disclosure mandates are restructuring supplier economics by forcing formalwear manufacturers to absorb elevated material certification costs or exit premium ceremonial segments entirely.
Growth Catalysts
- High school social event coordinators:These institutional buyers are consolidating purchase volumes through coordinated district-wide procurement frameworks that favor certified sustainable suppliers.
- France's AGEC law:This circularity mandate creates competitive differentiation for European atelier producers already documenting end-of-life garment pathways.
- Silk and satin natural fiber segments:Breathability and drape fidelity advantages over synthetic alternatives sustain premium pricing power in humid Southern US climates.
Market Restraints
- Silk supply concentration:Raw silk production clusters in China and India expose formalwear brands to input cost volatility from climate-driven cocoon harvest disruptions.
- EU REACH restricted substance declarations:Synthetic dye and embellishment chemistry documentation creates 12-18 month product development friction for non-European suppliers.
- Rental and resale platforms:These circular consumption models threaten unit volume demand for single-occasion ceremonial purchases among price-sensitive demographics.
Strategic Opportunities
- Tea-length retro variants:These silhouettes are capturing share among Midwestern vintage-influenced consumer cohorts underserved by dominant floor-length inventory.
- Direct-to-consumer digital channels:These platforms bypass intermediary certification burdens while capturing margin previously allocated to formalwear retail corridors.
- Extended producer responsibility frameworks:Emerging German and Italian circularity mandates will reward early movers with compliant take-back infrastructure.
Industry Challenges
- Precision tailoring skill scarcity:Hand-finished boned bodice construction requires specialized seamwork expertise concentrated in aging European and East Asian craft networks.
- Flammability certification timelines:US Consumer Product Safety Commission testing protocols for layered skirt architectures extend seasonal collection launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Prom Dresses Market |
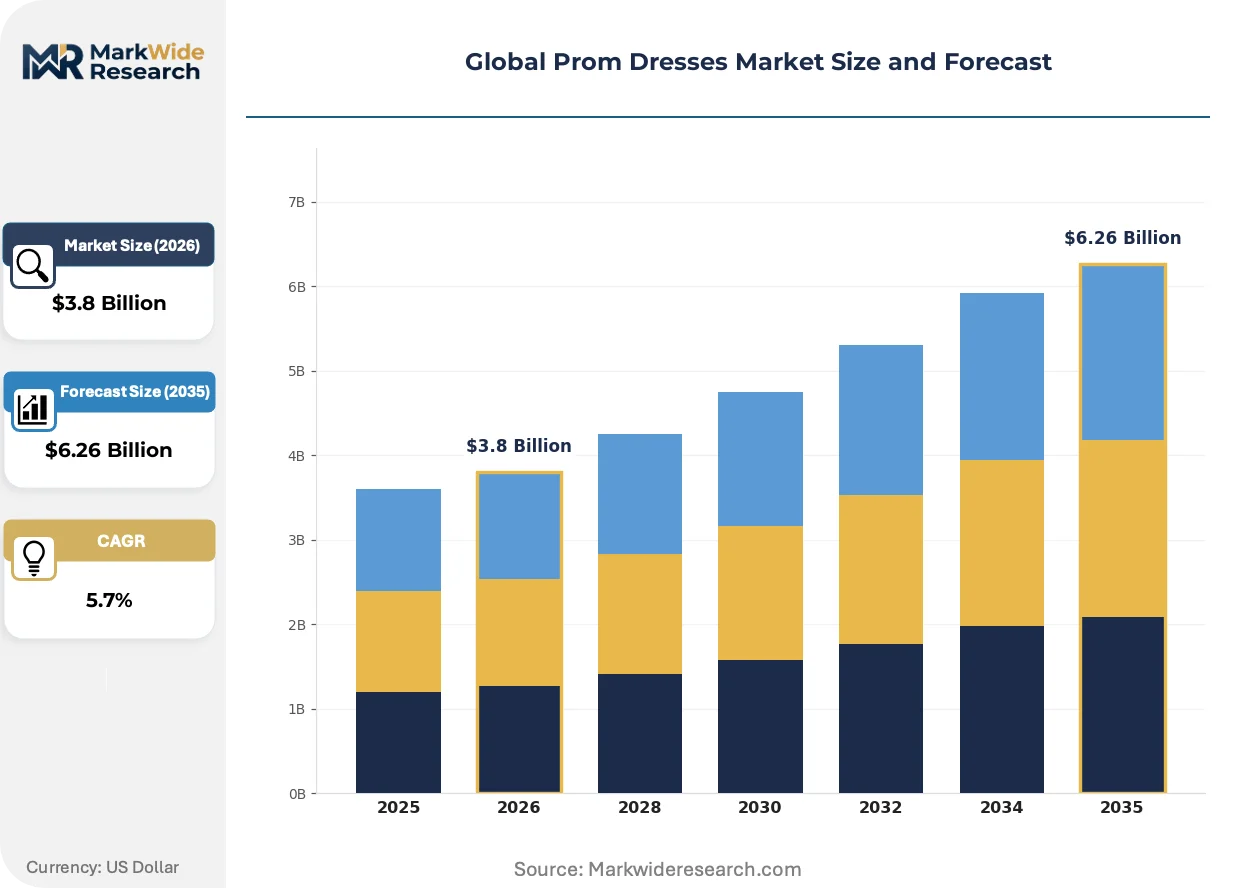
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Dress Style: A-Line, Mermaid, Ball Gown, Sheath Material: Silk, Satin, Chiffon, Velvet Length: Short, Knee-Length, Floor-Length, Tea-Length Color: Red, Blue, Black, Pastel |
| Companies Covered | Jovani, Sherri Hill, Pronovias, David's Bridal, Carolina Herrera, Rosa Clara, Adrianna Papell, Vera Wang, Terani Couture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Prom Dresses Market Strategic Shifts
Digital measurement and customization platforms are fragmenting traditional formalwear retail by enabling remote fit verification. Three developments merit attention.
AI-powered virtual try-on systems are decentralizing the geographic concentration of bridal and prom dress purchasing. High school juniors in Texas and Ohio now complete 60% of style selection through smartphone-based body scanning before visiting showrooms for final fitting. This compression of in-person interaction is reallocating square footage from inventory display to alteration services.
The EU Green Deal's textile sustainability standards are forcing dye house consolidation across synthetic fiber supply chains. Italian and Portuguese finishers are absorbing smaller competitors to amortize wastewater treatment investments required by ECHA documentation protocols. Ball gown producers dependent on petroleum-based satins face 18-month reformulation cycles to maintain CE marking eligibility.
Social media-driven micro-trend cycles are compressing design-to-retail lead times from 9 months to 14 weeks. Southern California-based formalwear influencers now trigger inventory sellouts within 72 hours of platform posting, forcing Midwestern retailers to adopt drop-ship relationships with domestic cut-and-sew contractors rather than seasonal pre-buy commitments.
Global Prom Dresses Market Segmentation
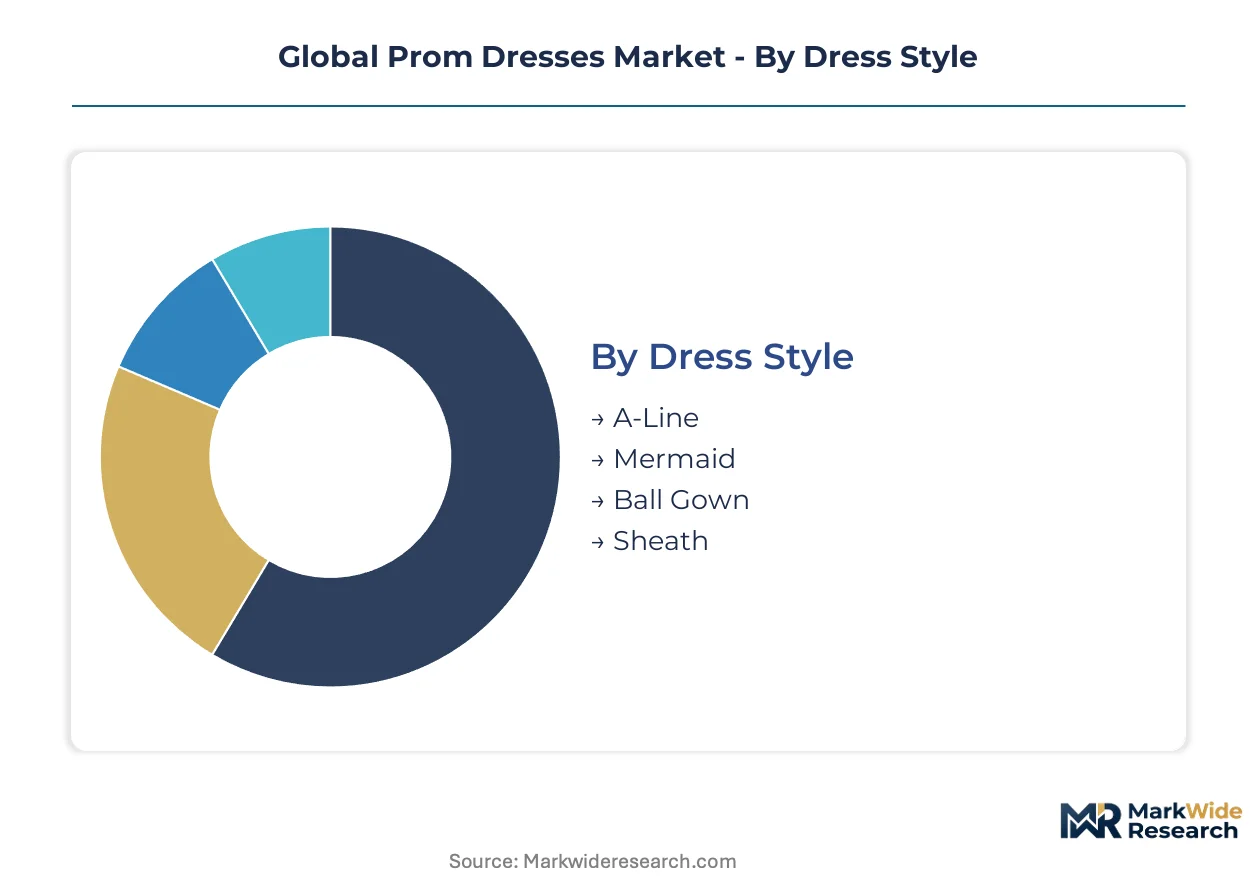
Prom dress procurement patterns diverge sharply across ceremonial contexts, body-type preferences, and climate-driven fabric requirements. Segmentation reveals how high school social event coordinators, individual consumers, and rental platforms allocate budgets across competing attribute combinations.
Dress Style:
Silhouette selection signals intended formality level and venue architecture, with volume buyers prioritizing photographic versatility over trend velocity.
- Ball Gown:Layered skirt architectures with structured bodices dominate institutional procurement across Southern US school districts. Volume concentrates in Texas and Florida where grand venue photography drives coordinated district-wide purchasing.
- Sheath:Minimalist column constructions with clean seamwork appeal to Midwestern vintage-influenced cohorts seeking retro elegance. Demand is climbing fastest among Ohio and Illinois consumers prioritizing mobility over voluminous silhouettes.
- A-Line:Flared skirt profiles offer universal fit accommodation across diverse body types.
- Mermaid:Fitted-through-hip constructions with dramatic flares require precision tailoring expertise concentrated in aging craft networks.
Volume sits with Ball Gown; growth tilts toward Sheath.
Material:
Natural fiber premiums widen where humidity and extended wear duration elevate breathability requirements.
- Silk:Mulberry-derived filament constructions deliver unmatched drape fidelity and thermoregulation. Procurement concentrates in humid Southern US climates where synthetic alternatives fail on comfort metrics; climate-driven cocoon harvest disruptions in China and India inject supply volatility.
- Satin:Twill-weave lustrous surfaces dominate budget-tier institutional purchasing. Petroleum-based variants face 18-month reformulation cycles under ECHA documentation protocols; Italian finishers consolidate to amortize wastewater treatment investments.
- Chiffon:Plain-weave sheer constructions layered over opaque linings enable lightweight formal options.
- Velvet:Dense pile constructions with light-absorbing surfaces suit winter ceremonial schedules.
Revenue concentrates in Silk; expansion is steepest in Satin as synthetic dye houses achieve compliance scale.
Length:
Hemline positioning correlates with venue formality codes and generational aesthetic transfer.
- Floor-Length:Traditional trailing constructions anchor revenue pools across formalwear retail corridors. Dominant share persists in Southern states where grand staircase photography remains a ceremonial staple.
- Tea-Length:Retro-inspired mid-calf profiles capture underserved Midwestern vintage cohorts. Share is expanding among Illinois and Michigan consumers rejecting dominant floor-length inventory.
- Knee-Length:Cocktail-appropriate hemlines suit semi-formal school events with relaxed dress codes.
- Short:Above-knee constructions serve informal homecoming adjacent events and warm-climate outdoor venues.
Floor-Length commands current volume; Tea-Length is gaining share fastest among retro-influenced demographics.
Color:
Pigment selection reflects seasonal trend cycles, photographic backdrop compatibility, and institutional uniformity requirements.
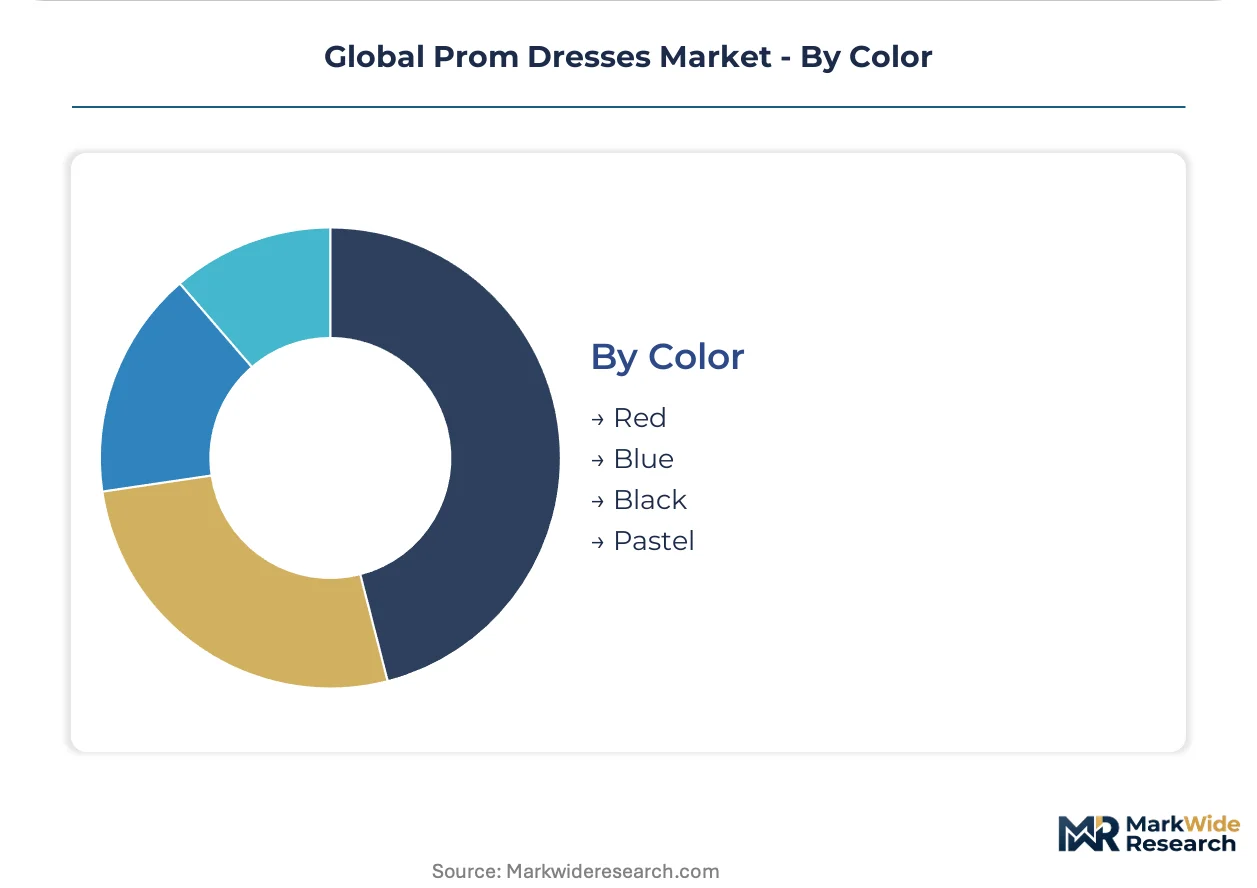
- Pastel:Soft saturation palettes dominate spring ceremonial schedules. Demand clusters in Florida and California where outdoor venue photography favors light-reflecting hues; social media-driven micro-trends trigger 72-hour inventory sellouts forcing drop-ship adoption.
- Black:Absorptive neutral tones serve versatility-seeking consumers across multiple formal occasions.
- Blue:Cool-tone saturation variants align with school color coordination requirements.
- Red:High-impact warm tones suit statement-making individual purchases outside institutional frameworks.
Pastel leads seasonal volume; Black demonstrates most consistent year-round demand stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, where Southern and Midwestern states sustain formalwear retail corridors, while European atelier networks and Asian silk supply clusters shape production economics.
United States
Texas and Florida school districts drive institutional procurement through coordinated event frameworks prioritizing photographic versatility. The US Consumer Product Safety Commission governs flammability standards for layered skirt architectures. Southern California influencers trigger 72-hour inventory sellouts, compressing design-to-retail cycles for Midwestern retailers.
China
Raw silk production clusters in mulberry cultivation zones expose formalwear brands to climate-driven cocoon harvest volatility. The country's national textile regulator enforces GB standards for synthetic dye chemistry documentation. Zhejiang and Jiangsu provinces host concentrated dye house operations consolidating to amortize wastewater treatment investments.
Italy
European atelier production aligns with ECHA documentation standards for REACH compliance in ceremonial apparel. France's AGEC law creates competitive differentiation for Italian producers documenting end-of-life garment pathways. Milan and Florence maintain precision tailoring expertise for hand-finished boned bodice construction.
India
Mulberry silk cultivation in Karnataka and Tamil Nadu supplies natural fiber segments commanding premium positioning for breathability advantages. The Bureau of Indian Standards certifies textile quality for export-oriented formalwear production. Surat's synthetic textile cluster faces reformulation cycles to maintain access to European markets under evolving ECHA protocols.
Germany
Emerging extended producer responsibility frameworks alter inventory risk models for seasonal prom collections. The country's national environmental regulator implements circularity mandates accelerating take-back infrastructure requirements. Berlin and Munich retail corridors import ceremonial apparel while domestic producers adapt to EU Green Deal textile sustainability standards.
Global Prom Dresses Market Competitive Environment
United States producers anchor one tier through vertically integrated manufacturing and direct-to-consumer digital channels; European specialists hold another tier through controlled atelier production aligned with ECHA documentation standards. The vendor base stratifies across three archetypes: vertically integrated domestic manufacturers, European atelier networks, and design houses leveraging celebrity affiliation. Dominant competitive moves include backward integration into captive silk supply and strategic partnerships with social media influencers to compress trend-to-retail cycles.
Among US-based design houses, Jovani leverages in-house production to bypass extended European compliance timelines, while Sherri Hill anchors its position through direct-to-consumer digital channels that reduce intermediary certification burdens. Pronovias occupies a distinct tier through controlled European atelier production already aligned with ECHA documentation standards, representing the archetype of compliance-forward positioning.
| Leading Market Players |
|---|
| Jovani |
| Sherri Hill |
| Pronovias |
| David's Bridal |
| Carolina Herrera |
| Rosa Clara |
| Adrianna Papell |
| Vera Wang |
| Terani Couture |
| Others |
Value Chain & Pricing Dynamics
High school social event coordinators consolidating district-wide procurement volumes command tiered pricing structures that reward certified sustainable suppliers with volume commitments while squeezing margin from uncertified competitors.
Pricing Analysis
Lead-time premiums for rush orders and spot-inventory discounts define transactional dynamics across formalwear retail corridors. Three-tier pricing structure across premium silk, standard synthetic satin, and economy petroleum-based variants separates natural fiber positioning from compliance-burdened alternatives. Price differentiation hinges on REACH certification status and vertical integration depth. Cost compression in synthetic dye tiers is intensifying because ECHA documentation timelines extend product development cycles.
Supply Chain Analysis
REACH qualification gating and flammability certification requirements filter supplier participation across the value chain. Raw silk production clusters in China and India; precision tailoring expertise concentrates in Italy and aging East Asian craft networks; synthetic dye house consolidation runs through Zhejiang and Jiangsu provinces. Mulberry cocoon harvests, petroleum-based satin feedstocks, and hand-finished boned bodice labor pools constitute critical input dependencies. Single-source vulnerability in climate-exposed silk cultivation regions threatens input cost stability. Distribution runs through formalwear retail corridors in Southern and Midwestern US states, direct-to-consumer digital channels, and rental platform partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH compliance timelines function as a cost-of-compliance moat, elevating barriers for non-European entrants while rewarding incumbent atelier networks with pre-aligned ECHA documentation pathways.
For Market Incumbents: Acquire captive silk supply contracts and precision tailoring craft networks to defend against rental platform volume erosion. Backward integration into mulberry cultivation zones in Karnataka and Tamil Nadu secures input cost stability against climate-driven cocoon harvest disruptions. Investment in direct-to-consumer digital channels captures margin previously allocated to formalwear retail corridor intermediaries. For New Entrants and Emerging Players: Capture tea-length retro variant demand among Midwestern vintage-influenced cohorts underserved by dominant floor-length inventory concentration. The most penetrable white space sits in Illinois and Michigan markets rejecting traditional silhouette dominance. A drop-ship partnership model with domestic cut-and-sew contractors enables 14-week design-to-retail cycles without seasonal pre-buy inventory risk. For Investors and Strategic Acquirers: The window for entry favors European atelier producers with pre-existing ECHA documentation alignment and controlled production footprints. Long-term viability centers on compliance-forward positioning as extended producer responsibility frameworks reshape end-of-life obligations. Monitor German and Italian circularity mandate implementation velocity as the inflection signal for inventory risk model disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silk Supply | Captive mulberry cultivation in India insulates against climate-driven cocoon harvest volatility. |
| Direct-to-Consumer Channel Launch | Digital platforms bypass intermediary certification burdens while capturing formalwear retail corridor margin. |
| REACH Compliance Certification | ECHA documentation alignment unlocks European market access and extends product development timelines for competitors. |
| Tea-Length Variant Introduction | Retro silhouettes capture underserved Midwestern vintage cohorts rejecting dominant floor-length inventory. |
| Take-Back Infrastructure Buildout | Compliant end-of-life garment pathways position early movers for German and Italian extended producer responsibility mandates. |
Study Parameters
Trade customs records, textile industry association filings, and SEC 10-K disclosures formed the secondary backbone for supply-side validation. Primary interviews with formalwear brand procurement directors, high school social event coordinators, Italian atelier production managers, and Zhejiang dye house operators combined with secondary triangulation. Bottom-up volume modeling across dress style, material, length, and color segments reconciled against top-down market value estimates.
Bottom-up demand modeling tracked procurement patterns across institutional buyers and individual consumers throughout the projection horizon. Segmentation dimensions included silhouette architecture, natural versus synthetic fiber grade, hemline positioning, and regional climate-driven fabric requirements. CAGRs derived from historical volume trajectories and regulatory implementation timelines. Forecast inputs incorporated EU Green Deal textile sustainability standard adoption curves and social media-driven micro-trend cycle compression rates.
The model holds under stable regulatory implementation schedules; deviation in REACH enforcement intensity or cocoon harvest disruption severity would shift volume and value trajectories. A model refresh is warranted upon material change in extended producer responsibility framework activation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Sweat Resistant Apparel Market
Apparel Textiles
North America Textile Garment Market
Apparel Textiles
Bridal Wear Market
Apparel Textiles
Dye Sublimated Apparel Market
Apparel Textiles
Hosiery Market
Apparel Textiles
Uniform Market
Apparel Textiles
Insect Repellent Apparel Market
Apparel Textiles
Organic Baby Clothes Market
Apparel Textiles
Asia-Pacific Footwear Sole Material Market
Apparel Textiles
School Uniform Market
Apparel Textiles
Rain Apparel Market
Apparel Textiles
Waterproof Fabrics for Sports Apparel Market
Apparel Textiles
Asia-Pacific Digital Clothing Market
Apparel Textiles
Cleanroom Apparels Market
Apparel Textiles
Europe Footwear Sole Material Market
Apparel Textiles
Bamboo Apparel Market