
 Maternity Wear Market | 2026-2036
Maternity Wear Market Size, Share, and Industry Trends Forecast 2026-2036
Maternity Wear Market Outlook
Multi-source fabric procurement is pivoting toward vertically integrated mills as brands seek tighter quality control over stretch-performance standards. Hennes & Mauritz AB leverages its fast-fashion supply chain to compress design-to-rack cycles for maternity lines. Gap Inc. sustains brand loyalty through dedicated sub-label architecture that separates maternity from mainstream assortments. Motherhood Maternity anchors its competitive stance through specialty store density in suburban retail corridors.
Maternity wear encompasses garments engineered with expandable waistbands, ruched side panels, and adjustable support structures to accommodate gestational body changes across trimesters. Cotton-dominant base layers retain market share for skin-breathability compliance, while bamboo-blend fabrics gain traction among buyers prioritizing moisture-wicking and antimicrobial properties. Online retailers capture volume leadership through algorithmic fit recommendation engines, whereas specialty stores command margin pools via personalized styling consultations. Working mothers within the customer type matrix represent the fastest-expanding segment as corporate dress-code flexibility intersects with extended gestational workforce participation.
REACH compliance in Europe restricts certain dye formulations and chemical finishes, compelling reformulation of stretch fabrics for export-bound suppliers. The US Consumer Product Safety Commission governs flammability standards for maternity sleepwear, creating testing cost barriers for new entrants. Stakeholders must monitor how sizing standardization protocols evolve alongside body-scanning technology deployment, as fit accuracy becomes the primary battleground for customer retention.
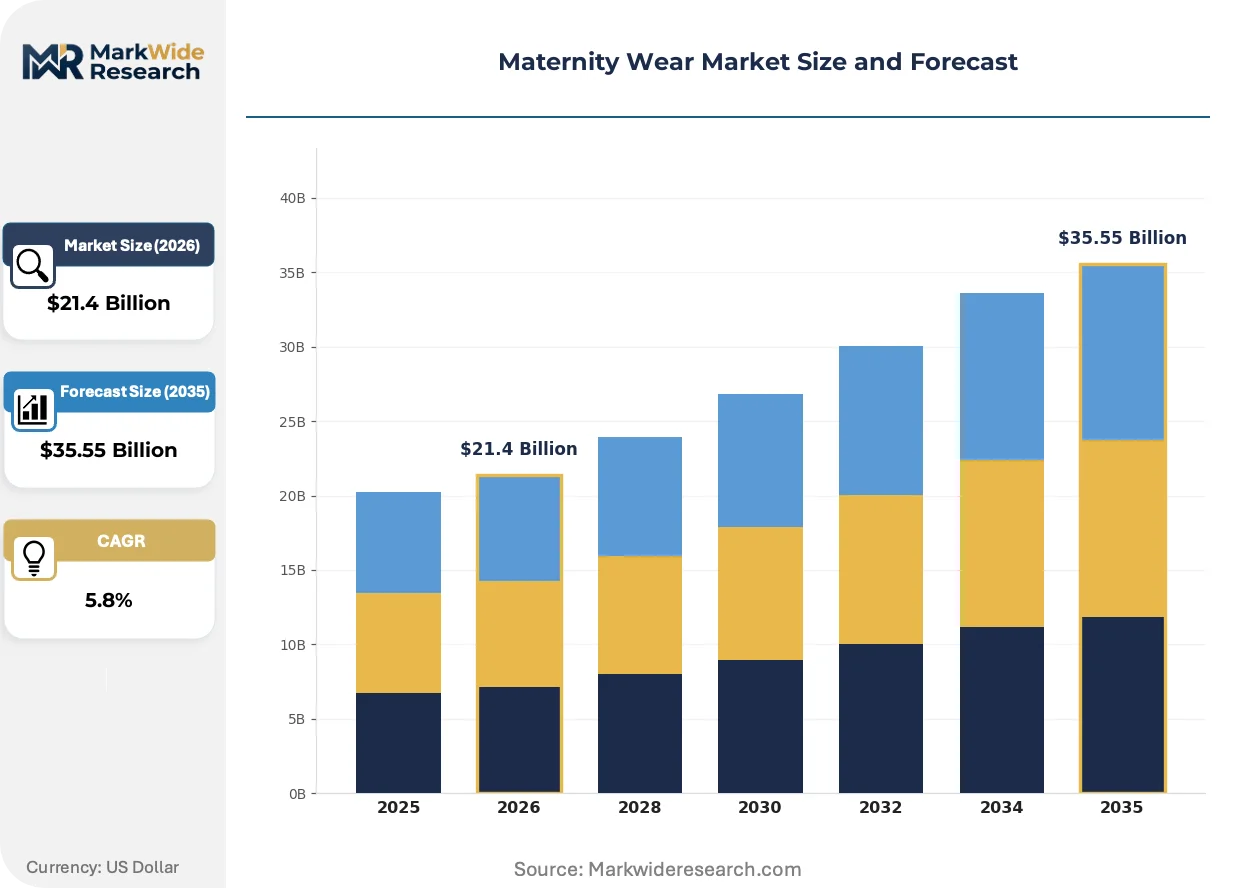
Market Dynamics
Stretch fabric chemistry and body-scan sizing technologies are compressing fit-uncertainty costs while REACH compliance in Europe and US Consumer Product Safety Commission flammability rules reshape supplier qualification requirements.
Growth Catalysts
- Professional Wardrobe Expansion:Working mothers are extending gestational workforce participation, creating sustained demand for corporate-appropriate maternity lines with adjustable support structures.
- REACH Chemical Reformulation:European dye and finish restrictions are forcing stretch-fabric innovation that transfers to higher-performance export products globally.
- Algorithmic Fit Engines:Online retailers deploying body-data matching systems are reducing return rates and capturing volume leadership in remote geographies.
Market Restraints
- Petrochemical Input Volatility:Spandex and elastane pricing swings compress margin predictability for brands dependent on synthetic stretch blends.
- Specialty Retail Concentration:Suburban mall dependency in the United States creates geographic demand fragility as foot traffic patterns shift.
- Testing Cost Barriers:US Consumer Product Safety Commission sleepwear flammability certification imposes five-figure compliance expenses that exclude new entrants.
Strategic Opportunities
- Bamboo-Blend Premiumization:Moisture-wicking and antimicrobial fabric properties command price premiums in direct-to-consumer channels targeting eco-conscious buyers.
- Vertically Integrated Mill Partnerships:Brands securing captive stretch-performance supply chains gain quality control advantages over multi-source competitors.
- Personalized Styling Services:Specialty stores converting consultation appointments into subscription relationships can defend margin pools against algorithmic competitors.
Industry Challenges
- Size Standardization Fragmentation:Competing body-scan protocols from retail technology vendors create inventory complexity and fit-inconsistency across channels.
- Trimester-Specific Design Cycles:Three distinct gestational body phases require accelerated product development timelines that strain traditional apparel planning horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maternity Wear Market |
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $35.55 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Activewear, Dresses, Tops, Bottoms Fabric Type: Cotton, Stretch, Lycra, Bamboo Customer Type: First-time Mothers, Working Mothers, Fashion-conscious, Budget-conscious Distribution Channel: Online Retailers, Boutiques, Department Stores, Specialty Stores |
| Companies Covered | Hennes & Mauritz AB, ASOS Plc, Walmart Inc., Motherhood Maternity, Macy's, Inc., Amazon.com, Inc., Gap Inc., A Pea in the Pod, Target Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maternity Wear Market Strategic Shifts
Digital measurement infrastructure and regulatory chemistry constraints are simultaneously elevating technical performance standards and compressing traditional design-to-retail timelines across maternity apparel supply chains.
Body-scan sizing technology is integrating gestational measurement databases with algorithmic pattern generation to deliver trimester-specific fit recommendations. Working mothers in professional sectors are adopting these tools fastest, reducing in-store trial dependency. The technology is integrating remote fit precision into brand loyalty architectures that previously relied on physical store relationships.
REACH compliance mandates in Europe are restricting azo dyes and certain formaldehyde-based finishes in stretch fabrics bound for EU markets. Suppliers reformulating chemical treatments for export qualification are absorbing six-month re-certification timelines. Maternity sleepwear and base-layer categories face the steepest compliance burdens as skin-contact proximity triggers stricter residue thresholds.
Direct-to-consumer subscription models are displacing transactional purchase patterns among repeat maternity buyers. Specialty retailers with suburban store density are responding with hybrid consultation-digital fulfillment services. The United States exhibits the most pronounced channel experimentation as legacy mall operators negotiate space-for-service revenue structures with dedicated maternity brands.
Maternity Wear Market Segmentation
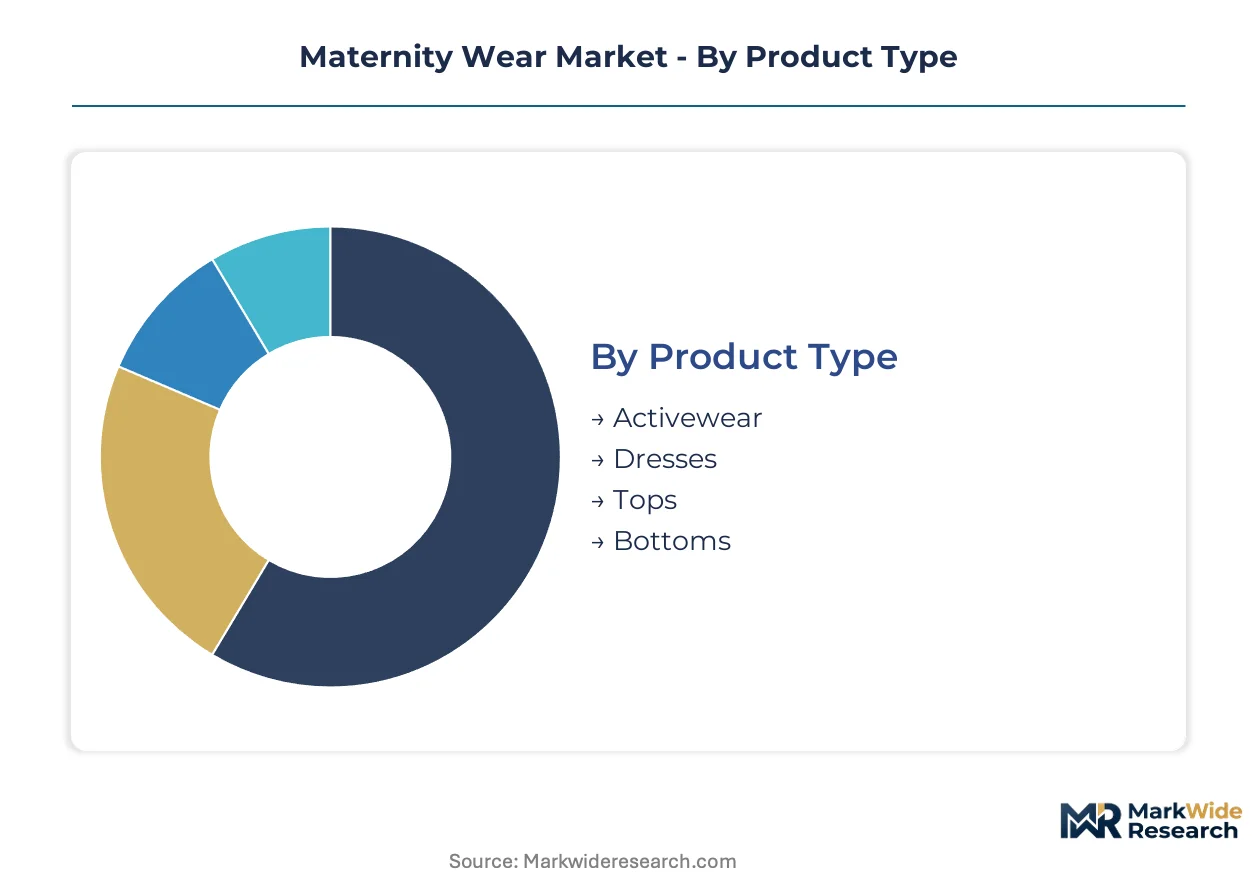
Maternity wear segmentation reflects distinct gestational phases and lifestyle priorities that reshape purchasing patterns across trimesters. Understanding these divisions enables brands to align fabric innovation, channel strategy, and pricing architecture with specific buyer workflows.
Product Type:
Upgrade cycles accelerate as body dimensions shift, forcing wardrobe refreshes every 8-12 weeks through pregnancy.
- Tops:Engineered with side ruching and empire waists to accommodate ribcage expansion without size changes. Demand clusters among working mothers in the United States seeking office-appropriate layering pieces that transition across trimesters.
- Bottoms:Feature expandable waistband systems with hidden elastic panels and adjustable support structures. Professional segments in suburban corridors drive volume as corporate dress codes require polished alternatives to standard casual wear.
- Dresses:Wrap silhouettes and A-line cuts dominate with stretch-jersey constructions for single-size multi-trimester wear.
- Activewear:Compression leggings and moisture-wicking tops serve prenatal fitness routines with reinforced belly support panels.
Volume placements concentrate in Bottoms; the faster expansion belongs to Activewear as prenatal exercise participation rises.
Fabric Type:
Cost tiers separate at the raw material level, with natural fibers commanding premium positioning against synthetic performance blends.
- Cotton:Breathable base-layer staple with skin-contact compliance for sleepwear and everyday essentials. Budget-conscious segments in value-oriented channels sustain volume despite slower moisture-management performance.
- Stretch:Elastane-blend constructions delivering shape retention through repeated washing and dimensional change. REACH reformulation requirements in Europe are elevating performance standards for export-bound suppliers.
- Bamboo:Cellulosic fiber with inherent antimicrobial properties and moisture-wicking performance. Eco-conscious buyers in direct-to-consumer channels absorb 25-40% price premiums over conventional cotton alternatives.
- Lycra:Branded elastane with superior recovery characteristics for high-compression activewear and swim applications.
Stretch fabrics dominate unit economics; bamboo-blend categories are gaining share fastest among subscription-format retailers.
Customer Type:
Application intensity varies sharply, with employment status and prior maternity experience dictating purchase frequency and quality thresholds.
- Working Mothers:Professional wardrobe requirements drive quarterly replenishment cycles with emphasis on machine-washable, wrinkle-resistant constructions. Corporate dress-code flexibility in the United States extends gestational workforce participation, sustaining demand for structured blazers and tailored separates.
- First-time Mothers:Uncertainty around sizing and body changes produces higher return rates and consultation dependency. Specialty store density in suburban retail corridors captures this segment through personalized fitting services.
- Fashion-conscious:Trend-responsive buyers prioritizing seasonal color palettes and silhouette novelty over extended wear duration.
- Budget-conscious:Price-sensitive segments concentrating purchases in discount channels and secondhand marketplaces.
Working mothers anchor revenue stability; first-time mothers show the steepest expansion trajectory as delayed childbearing increases average maternal age and disposable income.
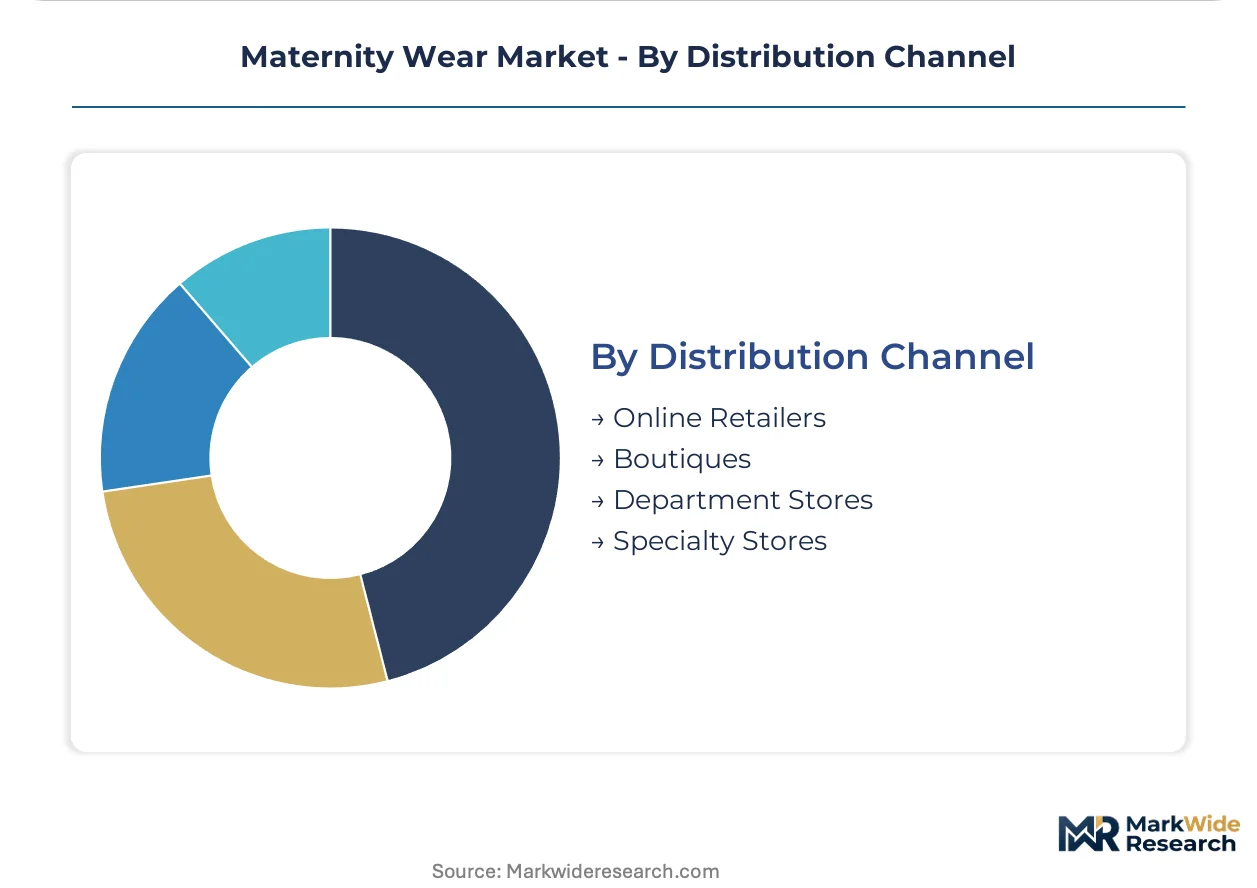
Distribution Channel:
Channel margins diverge based on service intensity, with algorithmic efficiency competing against consultative expertise for customer acquisition.
- Online Retailers:Body-scan sizing integration and algorithmic fit recommendation engines reduce return rates below physical store benchmarks. Volume leadership concentrates in the United States where direct-to-consumer infrastructure and last-mile logistics density support free-return policies.
- Specialty Stores:Personalized styling consultations and trimester-specific inventory curation defend premium price positioning. Suburban mall dependency creates geographic concentration risk as foot traffic patterns shift toward experiential retail formats.
- Department Stores:Maternity shop-in-shop configurations leverage existing traffic but struggle with dedicated staff training and inventory depth.
- Boutiques:Curated independent assortments targeting fashion-conscious segments with limited-edition designer collaborations.
Online retailers capture volume leadership; specialty stores are expanding share fastest through hybrid consultation-digital fulfillment services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cotton cultivation belts across the United States, India, and China anchor raw material sourcing for stretch-fabric production. Specialty retail infrastructure and direct-to-consumer logistics density concentrate finished goods distribution in these same markets.
United States
Suburban mall-based specialty stores and algorithmic fit engines drive channel experimentation. The US Consumer Product Safety Commission enforces flammability standards for maternity sleepwear that impose testing cost barriers. Greater Los Angeles and New York Metro host the densest concentrations of direct-to-consumer fulfillment centers serving working mother segments.
Germany
REACH compliance mandates reshape stretch-fabric chemistry for export-bound suppliers. ECHA restrictions on azo dyes and formaldehyde-based finishes trigger six-month re-certification timelines. The Rhine-Ruhr industrial corridor concentrates vertically integrated textile mills reformulating chemical treatments for EU market access.
United Kingdom
Online retailers capture volume leadership through body-scan sizing integration and free-return policies. The UK's national trading standards authority enforces textile labeling requirements that affect bamboo-blend marketing claims. London and Southeast England anchor subscription-format maternity services targeting professional wardrobe segments.
China
Domestic demand for prenatal activewear rises alongside urban fitness participation rates. MIIT and GB standards govern textile safety for skin-contact garments including maternity base layers. The Yangtze River Delta hosts the largest concentration of elastane-blend fabricators serving both domestic and export markets.
India
First-time mothers with delayed childbearing patterns show steepest expansion in disposable income brackets. BIS textile quality standards create compliance frameworks for domestic maternity wear distribution. Maharashtra and Gujarat host emerging direct-to-consumer brands leveraging cotton-dominant supply chains for price-competitive positioning.
Maternity Wear Market Competitive Environment
Portfolio diversification dominates the current landscape as incumbents extend maternity lines from adjacent apparel categories. The vendor base spans fast-fashion conglomerates, dedicated specialty retailers, and mass-market department stores with varying degrees of vertical integration. Three strategic archetypes prevail: algorithmic-fit online retailers, consultation-driven specialty stores, and scale-leveraging mass merchants. M&A activity and captive supply chain partnerships represent the dominant competitive moves reshaping quality control and margin architecture.
Within the fast-fashion archetype, Hennes & Mauritz AB exemplifies compressed design-to-rack cycle capabilities. Among dedicated specialty retailers, Motherhood Maternity occupies a position defined by suburban store density and personalized styling services. On the mass-market vector, Gap Inc. represents sub-label architecture that separates maternity assortments from mainstream product lines.
| Leading Market Players |
|---|
| Hennes & Mauritz AB |
| ASOS Plc |
| Walmart Inc. |
| Motherhood Maternity |
| Macy's, Inc. |
| Amazon.com, Inc. |
| Gap Inc. |
| A Pea in the Pod |
| Target Corporation |
| Others |
Value Chain & Pricing Dynamics
REACH chemical reformulation mandates in Europe gate qualified supply access and premium-tier pricing power, as brands absorbing six-month re-certification timelines pass compliance costs through to export-bound stretch-fabric categories while domestic-only suppliers compete on stripped-down price positioning.
Pricing Analysis
Warranty and fit-guarantee bundling separates subscription-format retailers from transactional competitors, with algorithmic sizing confidence reducing return-rate exposure that subsidizes free-shipping policies. Three-tier pricing structure across premium bamboo-blend, standard stretch-cotton, and economy pure-cotton levels tracks fabric certification grade and moisture-management performance. Price compression intensifies in synthetic stretch categories as petrochemical input volatility destabilizes margin predictability. Budget-conscious first-time mothers exhibit highest price sensitivity, while working mothers absorb premiums for machine-washable professional constructions.
Supply Chain Analysis
Domestic-content requirements in India's BIS textile standards and China's GB safety protocols are redirecting sourcing toward certified local mills for skin-contact maternity base layers. Raw cotton draws from cultivation belts across the United States, India, and China; elastane fiber feeds from Yangtze River Delta chemical clusters; bamboo pulp concentrates in Sichuan province facilities. Single-source vulnerability in spandex supply creates exposure to petrochemical price swings. Distribution runs through direct-to-consumer fulfillment centers in Greater Los Angeles and New York Metro, with suburban specialty stores anchoring last-mile consultation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where captive control over stretch-performance fabric mills determines quality consistency and margin defense against petrochemical volatility.
For Market Incumbents: Extend sub-label architecture into trimester-specific subscription tiers, locking working mothers into replenishment cycles before algorithmic competitors capture fit-data loyalty. Deepen backward integration into REACH-compliant dye houses to compress re-certification timelines for European export qualification. Defend suburban specialty store density by converting consultation appointments into hybrid digital-fulfillment relationships.
For New Entrants and Emerging Players: Direct-to-consumer algorithmic fit engines represent the most penetrable white-space channel, as legacy retailers underinvest in body-scan database development. Target first-time mothers in Indian metropolitan markets where delayed childbearing concentrates disposable income growth and BIS compliance creates barrier-filtered competition. Launch through prenatal fitness studio partnerships to capture activewear demand ahead of established maternity brands.
For Investors and Strategic Acquirers: Six-month REACH re-certification timeline extensions are the leading indicator that European export capability is consolidating among vertically integrated mill owners, signaling acquisition premiums for compliant suppliers. Long-term viability across the analysis window hinges on gestational workforce participation rates sustaining professional wardrobe demand. Watch for specialty retailers negotiating space-for-service revenue structures with distressed mall operators as the inflection signal for channel-model disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stretch-Fabric Mills | Captive REACH-compliant dye capacity accelerates European market access against multi-source competitors. |
| Algorithmic Fit Engine Deployment | Body-scan database integration reduces return rates below physical store benchmarks in remote geographies. |
| Subscription Model Launch | Trimester-specific replenishment cycles convert transactional buyers into recurring revenue streams. |
| Bamboo-Blend Premium Tier Introduction | Antimicrobial certification commands 25-40% price premiums in eco-conscious direct-to-consumer channels. |
| Hybrid Consultation-Digital Fulfillment | Specialty stores defend margin pools against pure-play online retailers through personalized styling services. |
Study Parameters
Multi-period observation of gestational workforce participation rates, stretch-fabric patent filings, and suburban retail foot-traffic indices anchored the trend analysis, supplemented by interviews with maternity brand supply chain directors, specialty store operations managers, direct-to-consumer platform engineers, and REACH compliance consultants. Secondary validation drew from US Consumer Product Safety Commission flammability test filings, ECHA substance restriction updates, customs trade data for elastane-blend imports, and SEC 10-K disclosures from apparel conglomerates. Bottom-up segment sizing triangulated against top-down category spending estimates from retail audit databases.
Segment-weighting across product type, fabric technology tier, customer employment status, and distribution channel density structured the analytical framework across the projection horizon. CAGRs derived from curve-fitting historical volume trajectories against demographic fertility rate projections and professional female labor force participation trends. Forecast inputs incorporated body-scan technology adoption curves, REACH chemical reformulation compliance timelines, and prenatal fitness participation growth rates.
Several conditions sit outside the modeled scope, including secondhand marketplace volume, informal garment-alteration services, and cross-border e-commerce duty evasion. Forecasts reflect assumptions around sustained corporate dress-code flexibility and stable petrochemical feedstock availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Dye Sublimated Apparel Market
Apparel Textiles
North America Insect Repellent Apparel Market
Apparel Textiles
Uniform Market
Apparel Textiles
Asia-Pacific Footwear Sole Material Market
Apparel Textiles
Global Socks Market
Apparel Textiles
Functional Apparel Market
Apparel Textiles
Europe Textile Garment Market
Apparel Textiles
North America Footwear Sole Material Market
Apparel Textiles
Japan Denim Jeans Market
Apparel Textiles
Bamboo Apparel Market
Apparel Textiles
Braille Clothing Tags Market
Apparel Textiles
Sweat Resistant Apparel Market
Apparel Textiles
Global Prom Dresses Market
Apparel Textiles
Asia-Pacific Digital Clothing Market
Apparel Textiles
North America Textile Garment Market
Apparel Textiles
Stockings Market