
 Head Scarves Market | 2026-2036
Head Scarves Market Size, Share, and Industry Trends Forecast 2026-2036
Head Scarves Market Insights
A capital-intensity divergence between artisan ateliers and industrial manufacturers is reorganizing competitive dynamics in the head scarves sector. Gucci leverages its vertical silk sourcing from Como, Italy to sustain premium positioning across European fashion capitals. Chanel anchors its heritage craft through Lesage embroidery workshops, while Hermès competes via proprietary twill-weave techniques developed at its Lyon silk mill.
Head scarves are rectangular or square textile accessories, typically measuring 70–90 cm per side, woven from natural or synthetic fibers and finished with hand-rolled or machine-sewn edges for drape and durability. Their primary commercial purpose spans functional sun protection, religious modesty compliance, and brand-signaling fashion statements. Silk scarves occupy the highest margin pool within product type segmentation due to raw material scarcity and labor-intensive finishing. Online retail channels capture the fastest expansion trajectory as direct-to-consumer platforms bypass wholesale markups, while specialty stores retain dominance in experiential luxury purchasing.
REACH chemical restrictions govern dye formulations and finishing agents across European supply chains, compelling reformulation of colorfastness treatments. The EU Green Deal's textile sustainability requirements are forcing disclosure of fiber provenance and water usage metrics. India's BIS certification mandates pH and azo-dye testing for domestic and export-bound cotton scarves. Stakeholders must monitor evolving chemical compliance thresholds and traceability mandates to secure market access and avoid stranded inventory in regulated jurisdictions.
Market Dynamics
REACH chemical restrictions and the EU Green Deal's textile sustainability mandates are forcing wholesale reformulation of dye processes and fiber provenance disclosure across European supply chains, compressing margins for non-compliant producers while advantaging vertically integrated manufacturers with captive dye facilities.
Growth Catalysts
- Modest fashion expansion in Southeast Asia:Indonesia's Muslim fashion sector is driving demand for premium silk and printed head scarf designs, with urban centers like Jakarta and Surabaya serving as design hubs.
- REACH textile chemical standards:European regulatory clarity on azo-dye bans and pH requirements is creating competitive separation between compliant and non-compliant suppliers, rewarding early reformulators.
- Digital weaving technologies:Computerized jacquard looms are enabling mass customization of intricate patterns at production scale, reducing minimum order quantities for boutique retailers.
Market Restraints
- Raw silk price volatility:Mulberry silk cocoon supply from China's Zhejiang and Jiangsu provinces fluctuates with climate conditions, destabilizing input costs for premium tier producers.
- Artisan labor scarcity:Hand-rolled hem finishing requires skilled craftspeople concentrated in Como, Lyon, and Varanasi, with aging practitioner populations limiting output expansion.
- Synthetic fiber substitution:Polyester chiffon and viscose alternatives are capturing price-sensitive segments, eroding natural fiber volume in standard-tier categories.
Strategic Opportunities
- Blockchain traceability integration:Fiber provenance tracking from mulberry farm to finished goods is commanding premium positioning among sustainability-focused buyers in Nordic markets.
- Direct-to-consumer platform expansion:Social commerce channels are bypassing wholesale markups and enabling real-time design-to-order production based on viral trend response.
- India's PLI scheme for textiles:Production-linked incentives for man-made fiber and technical textile investments are attracting capital into integrated scarf manufacturing clusters.
Industry Challenges
- Heritage craft transmission gaps:Lesage-style embroidery and traditional bandhani resist-dyeing techniques face practitioner shortages as younger workers migrate to digital design roles.
- EU Green Deal compliance timelines:Mandatory water usage disclosure and carbon footprint labeling requirements are forcing expensive ERP system overhauls for mid-sized exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Head Scarves Market |
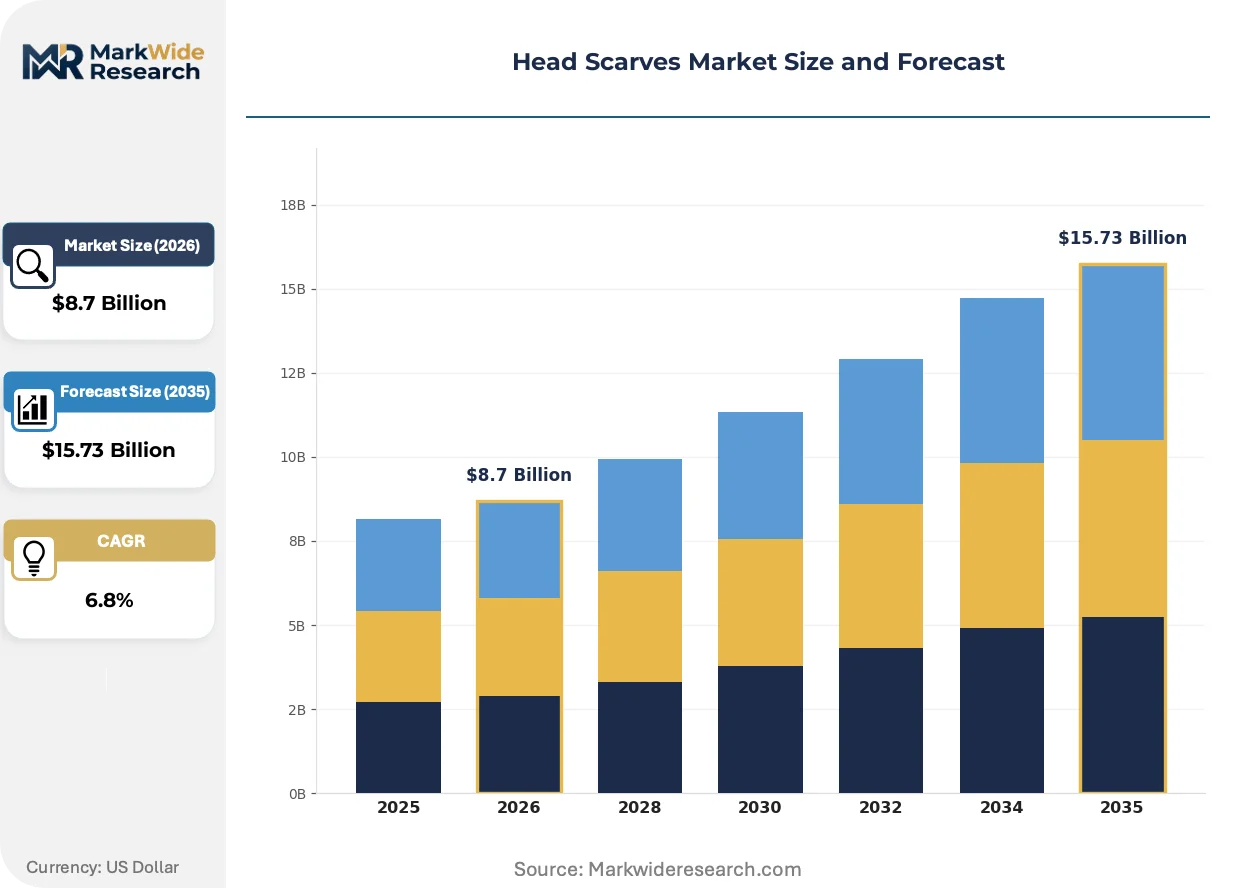
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silk Scarves, Cotton Scarves, Wool Scarves, Polyester Scarves Distribution Channel: Online Retail, Offline Retail, Specialty Stores, Fashion Boutiques Customer Type: Women, Men, Kids, Unisex Design Style: Printed, Solid, Embroidered, Textured |
| Companies Covered | Gucci, Chanel, Hermès, Burberry, Louis Vuitton, Versace, Dior, Prada, Fendi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Head Scarves Market Trends and Innovations
Digital design-to-production pipelines and regulatory traceability mandates are restructuring how head scarves are conceived, manufactured, and sold, compressing traditional seasonal cycles while elevating transparency as a purchase determinant.
Biodegradable silk alternatives derived from agricultural waste fibers are bifurcating material sourcing strategies. Luxury houses in Milan and Paris are piloting these inputs for limited capsule collections, while fast-fashion retailers in Istanbul and Dhaka accelerate conventional polyester adoption. The technology is bifurcating the premium segment into biosynthetic innovators and heritage natural-fiber defenders.
ECHA's expanded SVHC candidate list now encompasses several chromium-based mordants common in traditional silk dyeing. Italian and French finishing houses are reformulating with bio-based alternatives, absorbing 12-18 month certification delays. Specialty silk mills in Como are most affected, redirecting R&D spend from pattern innovation to chemical compliance.
Algorithmic trend forecasting is displacing traditional buyer intuition in wholesale purchasing. Multi-brand retailers in London and New York now license predictive platforms that analyze social media velocity to pre-position inventory. This shift is most visible among department store scarf buyers, who are reducing advance order commitments by 40% while increasing in-season replenishment frequency.
Head Scarves Market Segmentation
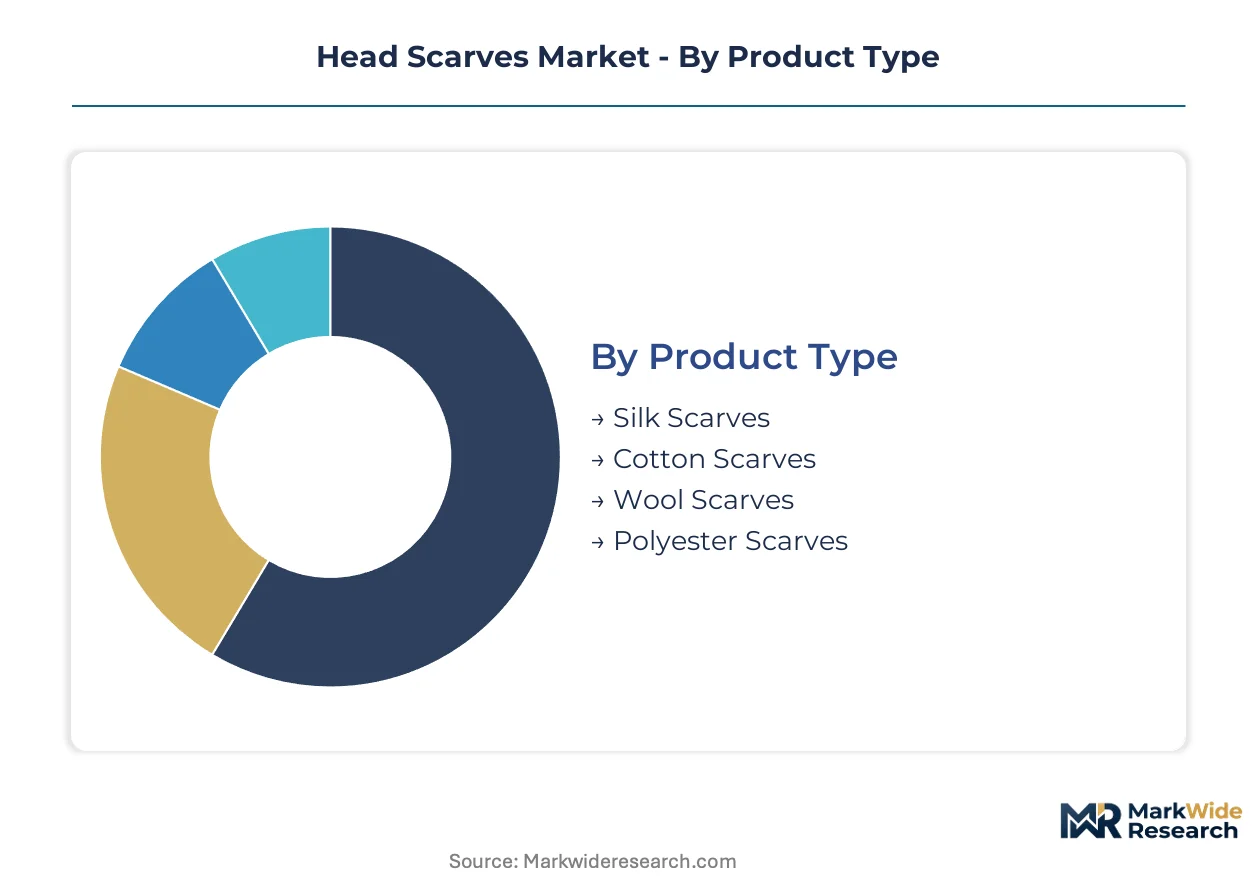
Head scarves fragment across material hierarchies, channel preferences, and demographic targeting that reshape margin structures. Manufacturers must align fiber sourcing, finishing techniques, and retail partnerships to the specific velocity and price sensitivity of each segment cluster.
Product Type:
Channel mix diverges sharply: silk and wool gravitate toward specialty stores and fashion boutiques where tactile evaluation drives conversion, while cotton and polyester dominate mass-market online retail where price transparency compresses premiums.
- Silk Scarves:Woven from mulberry silk filaments with twill or satin weaves, these accessories command the highest margin pool due to raw material scarcity and labor-intensive hand-rolled hemming. Demand concentrates in Jakarta's Muslim fashion sector and Parisian luxury houses, where REACH-compliant dyeing and heritage finishing justify price premiums.
- Cotton Scarves:Breathable plain-weave or voile constructions sourced from India's handloom clusters in Varanasi and West Bengal, these serve price-accessible modest fashion markets. India's BIS certification mandates pH and azo-dye testing, filtering export-bound production toward compliant weavers.
- Wool Scarves:Merino and cashmere blends from Himalayan and Scottish sourcing regions provide thermal functionality for temperate climates.
- Polyester Scarves:Chiffon and satin synthetics from Istanbul and Dhaka manufacturing clusters capture volume-driven fast-fashion channels.
By volume, polyester leads. By growth pace, silk is expanding most quickly.
Distribution Channel:
Cost tier alignment separates experiential high-touch retail from algorithmic mass distribution, with margin capture inversely related to operational scalability.
- Online Retail:Direct-to-consumer platforms and social commerce channels bypass wholesale markups, enabling real-time design-to-order production based on viral trend response. Algorithmic trend forecasting from London and New York licensees is displacing traditional buyer intuition, reducing advance order commitments while increasing replenishment frequency.
- Specialty Stores:Curated physical environments in Milan, Tokyo, and Dubai emphasize tactile material evaluation and personalized styling consultation. These venues retain dominance in luxury silk purchasing where drape assessment and hand-feel verification precede conversion.
- Offline Retail:Department store and multi-brand concessions remain significant for mid-tier cotton and wool volumes.
- Fashion Boutiques:Independent retailers in Surabaya, Lyon, and New York anchor discovery-oriented shopping for limited-edition and artisan-crafted pieces.
Specialty stores command the highest per-unit margins; online retail is gaining share fastest.
Customer Type:
Application focus shifts from religious modesty compliance to fashion-forward expression across gender and age boundaries.
- Women:The dominant commercial segment spanning functional sun protection, workplace accessorizing, and faith-based head covering. Urban centers in Indonesia, Malaysia, and India's metropolitan corridors drive premium silk adoption for professional and ceremonial contexts.
- Unisex:Streetwear-influenced styling and gender-neutral sizing are expanding addressable market boundaries, particularly among younger cohorts in Seoul and Berlin.
- Men:Traditional keffiyeh patterns and minimalist solid designs serve Middle Eastern and North African markets.
- Kids:Scaled-down dimensions and durable synthetic blends address school-uniform and sun-protection requirements.
Women's segment holds volume leadership; unisex is climbing the fastest.
Design Style:
Supply concentration in embroidery ateliers and digital printing clusters dictates regional competitive advantage and lead-time flexibility.
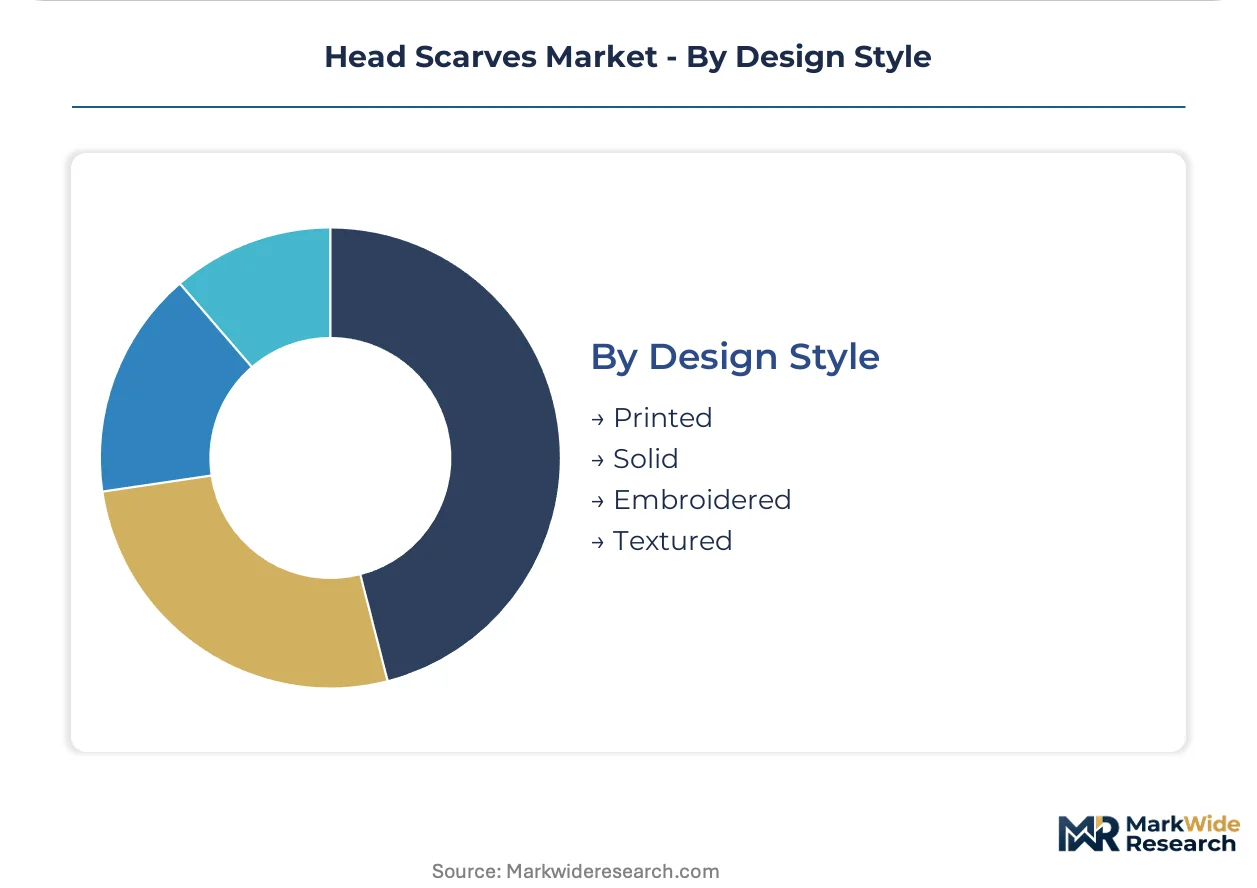
- Printed:Computerized jacquard looms and digital sublimation enable mass customization of intricate patterns at production scale, reducing minimum order quantities for boutique retailers. Surabaya and Istanbul design hubs specialize in rapid-turnaround printed collections responding to social media velocity.
- Embroidered:Lesage-style and traditional zardozi techniques face practitioner shortages as younger workers migrate to digital design roles, limiting output expansion and concentrating supply in Como, Lyon, and Varanasi heritage workshops.
- Solid:Minimalist color-field designs emphasize material quality and dye consistency over pattern complexity.
- Textured:Woven-in relief, devoré burnout, and pleated finishes add dimensional interest to premium positioning.
Printed designs lead by volume; embroidered commands the steepest expansion trajectory among premium tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian buyers demonstrate the lowest price elasticity for premium silk head scarves, while polyester substitution accelerates in Bangladesh and Vietnam where functional modesty compliance dominates purchasing decisions.
Indonesia
Jakarta's Muslim fashion sector drives premium silk adoption for professional and ceremonial contexts, with Surabaya emerging as a printed-design hub responding to social media velocity. The Ministry of Industry's Making Indonesia 4.0 initiative incentivizes digital weaving technology adoption in textile clusters. Bandung's manufacturing belt concentrates computerized jacquard production for rapid-turnaround collections.
France
Parisian luxury houses anchor heritage craft positioning through proprietary finishing techniques and controlled distribution. REACH chemical restrictions from ECHA govern dye formulations across Lyon's silk mills, compelling reformulation of chromium-based mordants. The Auvergne-Rhône-Alpes region hosts concentrated embroidery atelier networks facing practitioner transmission gaps.
Italy
Milan's fashion capital status sustains demand for tactile material evaluation in specialty retail environments where drape assessment precedes conversion. EU Green Deal textile sustainability mandates force water usage disclosure from Como-based finishing houses. The Lombardy silk district maintains vertical control over mulberry-to-garment supply chains.
India
Varanasi and West Bengal handloom clusters serve price-accessible modest fashion markets with breathable cotton constructions. BIS certification mandates pH and azo-dye testing, filtering export-bound production toward compliant weavers. The Production-Linked Incentive scheme attracts capital into integrated manufacturing clusters for man-made fiber investments.
United States
New York and Los Angeles department store buyers reduce advance order commitments by 40% while increasing replenishment frequency through algorithmic trend forecasting. No federal textile chemical standard matches REACH stringency, creating regulatory arbitrage for import sourcing. Social commerce channels enable direct-to-consumer platform expansion bypassing wholesale markups.
Head Scarves Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with heritage European houses commanding premium positioning through captive silk sourcing while Asian manufacturers capture volume through polyester specialization. The market structure rewards backward integration into raw material control and penalizes mid-tier players lacking either heritage brand equity or cost-scale advantages. Three archetypes dominate: vertically integrated luxury houses with proprietary weaving facilities, digital-native direct-to-consumer platforms, and contract manufacturers serving fast-fashion retailers. Competitive moves concentrate on M&A for embroidery atelier access and geographic expansion into Southeast Asian modest fashion hubs.
Within the heritage luxury tier, Gucci anchors Italian silk craftsmanship through Como-based vertical sourcing, while Chanel exemplifies French artisan preservation through controlled embroidery workshop networks. Hermès occupies a distinctive position via proprietary twill-weave techniques developed at its Lyon silk mill, representing the technical-innovation archetype among established houses.
| Leading Market Players |
|---|
| Gucci |
| Chanel |
| Hermès |
| Burberry |
| Louis Vuitton |
| Versace |
| Dior |
| Prada |
| Fendi |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day dye-house lead times in Como and Lyon compress pricing power for non-integrated weavers while amplifying margin capture for houses with captive finishing facilities. REACH reformulation cycles and raw silk cocoon volatility from Zhejiang are forcing tiered pricing separation between heritage natural-fiber defenders and fast-fashion polyester adopters.
Pricing Analysis
After-sales service tiers including monogramming, repair, and archival storage drive lifetime value concentration among European heritage houses. Three-tier pricing structure across premium, standard, and economy levels separates hand-rolled silk twill from machine-finished cotton voile and polyester chiffon. Cost compression in synthetic fiber tiers is intensifying because Istanbul and Dhaka manufacturers are scaling digital sublimation capacity. Fast-fashion retailers exhibit highest price sensitivity; Indonesian modest fashion buyers demonstrate lowest elasticity for REACH-compliant silk.
Supply Chain Analysis
China and India anchor mulberry silk cultivation and handloom cotton weaving respectively, while Italy and France concentrate heritage finishing and embroidery atelier networks. Raw material dependencies rest on Zhejiang province cocoon supply, Varanasi handloom labor pools, and Como-based twill weaving equipment. Single-source vulnerability concentrates in aging Lesage-style embroidery practitioners concentrated in Lyon and Varanasi. Distribution runs through direct-to-consumer platforms bypassing wholesale markups alongside specialty store concessions in Milan, Tokyo, and Dubai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Head scarves demand is recovering from pandemic-era inventory destocking as modest fashion expansion in Southeast Asia restarts premium silk procurement cycles.
For Market Incumbents: Consolidate embroidery atelier access through targeted acquisition of Varanasi and Lyon heritage workshops facing practitioner transmission gaps. Deepen backward integration into captive dye facilities to absorb REACH reformulation costs and compress lead times versus non-compliant competitors. Synthetic fiber substitution from Dhaka and Istanbul represents the primary margin pressure point; certification investment in blockchain traceability offers defensive differentiation. For New Entrants and Emerging Players: Algorithmic trend forecasting service layers present white-space opportunity where London and New York department store buyers currently license third-party platforms. Social commerce channels in Surabaya and Jakarta offer the most penetrable geography for direct-to-consumer launch with real-time design-to-order production. Target unisex streetwear styling in Seoul and Berlin as the fastest-climbing customer segment with gender-neutral sizing and minimalist solid designs. For Investors and Strategic Acquirers: Long-term, this sits as a brand-arbitrage play because heritage European houses command pricing power through controlled atelier networks while Asian volume manufacturers lack comparable equity premiums. Acquisition focus should center on mid-tier Italian and French finishing houses with REACH-compliant dye reformulations already certified. Watch ECHA SVHC candidate list expansion for chromium-based mordant alternatives as the inflection signal for chemical compliance cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Atelier Acquisition | Secures Lesage-style embroidery capacity in Lyon and Varanasi against practitioner shortages. |
| Blockchain Traceability Integration | Commands Nordic market premium positioning through fiber provenance tracking from mulberry farm. |
| Direct-to-Consumer Platform Launch | Bypasses wholesale markups via social commerce channels responding to Jakarta social media velocity. |
| REACH-Compliant Dye Reformulation | Absorbs EHA certification delays while locking out non-compliant competitors from EU market access. |
| Digital Jacquard Capacity Expansion | Reduces minimum order quantities for Surabaya boutique retailers through mass customization at scale. |
Research Methodology
A spread of perspectives from silk mill operations directors, modest fashion brand managers, specialty store buyers in Milan and Dubai, and REACH compliance officers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with these stakeholders alongside secondary validation from customs trade records, BIS certification filings, ECHA SVHC candidate list updates, and EU Green Deal textile sustainability disclosures. Bottom-up demand modeling across Indonesian Muslim fashion clusters and top-down supply assessment from Como and Lyon production data were triangulated for convergence.
Segmentation dimensions modeled include material hierarchy across silk, cotton, wool, and polyester; distribution channel mix spanning online retail, specialty stores, and fashion boutiques; and customer type across women, unisex, men, and kids. Value projections across the analysis window reflect volume-CAGR derivation from historical production data and price-trajectory assessment from trade flow analysis. Industry-specific forecast inputs incorporate raw silk cocoon supply volatility from Zhejiang climate patterns and digital weaving technology adoption rates under Indonesia's Making Indonesia 4.0 initiative.
Forecasts assume regulatory continuity in EU REACH enforcement and India's BIS certification mandates; material policy shifts would require re-modeling of dye-house compliance costs and export-bound production filtering. Specific risk factors that could revise projections include ECHA expansion of SVHC candidate list coverage, abrupt mulberry silk supply disruption from climate events, and accelerated synthetic fiber substitution in Bangladesh and Vietnam modest fashion markets. Recalibration cycles align with material shifts in regulatory threshold announcements and social commerce platform algorithm changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Bridal Gowns Market
Apparel Textiles
Asia-Pacific Textile Garment Market
Apparel Textiles
OEM Clothing Manufacturer Service Market
Apparel Textiles
Europe Textile Garment Market
Apparel Textiles
Waterproof Fabrics for Sports Apparel Market
Apparel Textiles
Africa Textile Market
Apparel Textiles
Women's Cheongsam Market
Apparel Textiles
Maternity Leggings Market
Apparel Textiles
North America Garment Steamers Market
Apparel Textiles
Europe Footwear Sole Material Market
Apparel Textiles
Cleanroom Apparels Market
Apparel Textiles
South America Lingerie Market
Apparel Textiles
Smart Clothing Market
Apparel Textiles
Blank Apparel Market
Apparel Textiles
North America Insect Repellent Apparel Market
Apparel Textiles
North America Footwear Sole Material Market