
 Global Ski Poles Market | 2026-2036
Global Ski Poles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ski Poles Market Outlook
ISO 10228 ski-pole safety certification is redrawing competitive barriers for entry into European and North American retail channels. Leki leverages its in-house aluminum forging capacity to control cost structures across premium and mid-tier lines. Black Diamond anchors its position through backcountry-specific designs that integrate avalanche probe compatibility. Atomic competes on manufacturing scale, operating one of the largest composite pole production facilities in the Salzburg region.
Ski poles are rigid shafts, typically 100–135 cm in length, constructed from aluminum alloys, carbon fiber prepregs, or hybrid composites, with wrist straps and basket assemblies designed to transfer poling force into forward momentum across groomed, powder, and touring terrain. Carbon fiber poles command the highest margin pools due to weight-sensitive demand from competitive and alpine touring segments, while aluminum retains volume leadership in rental fleets and beginner categories. The adjustable feature segment is expanding fastest as ski touring participation blurs the boundary between uphill and downhill equipment requirements.
REACH chemical restrictions in Europe, FDA oversight of strap materials in the United States, and Japan's JIS standards for sports equipment collectively elevate compliance costs for multi-region suppliers. The EU Green Deal's recycled content mandates are accelerating material substitution trials away from virgin carbon fiber toward flax-reinforced biocomposites. Stakeholders must monitor how certification divergence between European and North American testing protocols reshapes sourcing and inventory strategies.
Market Dynamics
The EU F-Gas Regulation and REACH compliance are compressing material choices across the supply base, forcing manufacturers to abandon conventional composites for bio-based alternatives and recycled aluminum sourcing. This regulatory pressure is redrawing cost structures and competitive barriers simultaneously.
Growth Catalysts
- Alpine Touring Equipment Refresh:Backcountry recreational skiers are accelerating replacement cycles as uphill-downhill hybrid disciplines blur equipment boundaries. Adjustable pole configurations capture this demand shift.
- ISO 10228 Certification Mandate:European and North American retail channels now require this safety standard for shelf placement, creating compliance-driven demand consolidation among certified suppliers.
- Innsbruck Manufacturing Cluster:Austria's concentrated R&D infrastructure and specialized labor pool anchor European pole production, reducing innovation-to-market lead times.
Market Restraints
- Virgin Carbon Fiber Cost Volatility:Petroleum-derived precursor prices fluctuate with energy markets, compressing margins on high-performance product lines.
- REACH Chemical Friction:ECHA substance restrictions on strap polymers and basket additives force reformulation cycles that extend product development timelines.
- Aluminum Supply Concentration:Primary smelting capacity concentrates in specific geographies, exposing mid-tier manufacturers to input cost spikes and tariff exposure.
Strategic Opportunities
- Flax-Reinforced Biocomposites:EU Green Deal recycled content mandates create first-mover advantage for manufacturers pioneering plant-fiber hybrid shafts.
- Avalanche-Integrated Backcountry Designs:Probe-compatible pole systems address unmet safety needs in untracked terrain segments.
- Direct-to-Consumer Channel Expansion:Specialty retailers and brand-owned digital platforms bypass traditional wholesale markups in Nordic markets.
Industry Challenges
- Certification Timeline Compression:Divergent testing protocols between European and North American standards force redundant validation cycles.
- Composite Technician Scarcity:Layup and autoclave operation skills concentrate in legacy aerospace regions, constraining production scaling.
- Legacy Inventory Stranded by Material Bans:Pre-REACH stockpiles face write-down risk as retailers enforce compliance cutoffs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ski Poles Market |
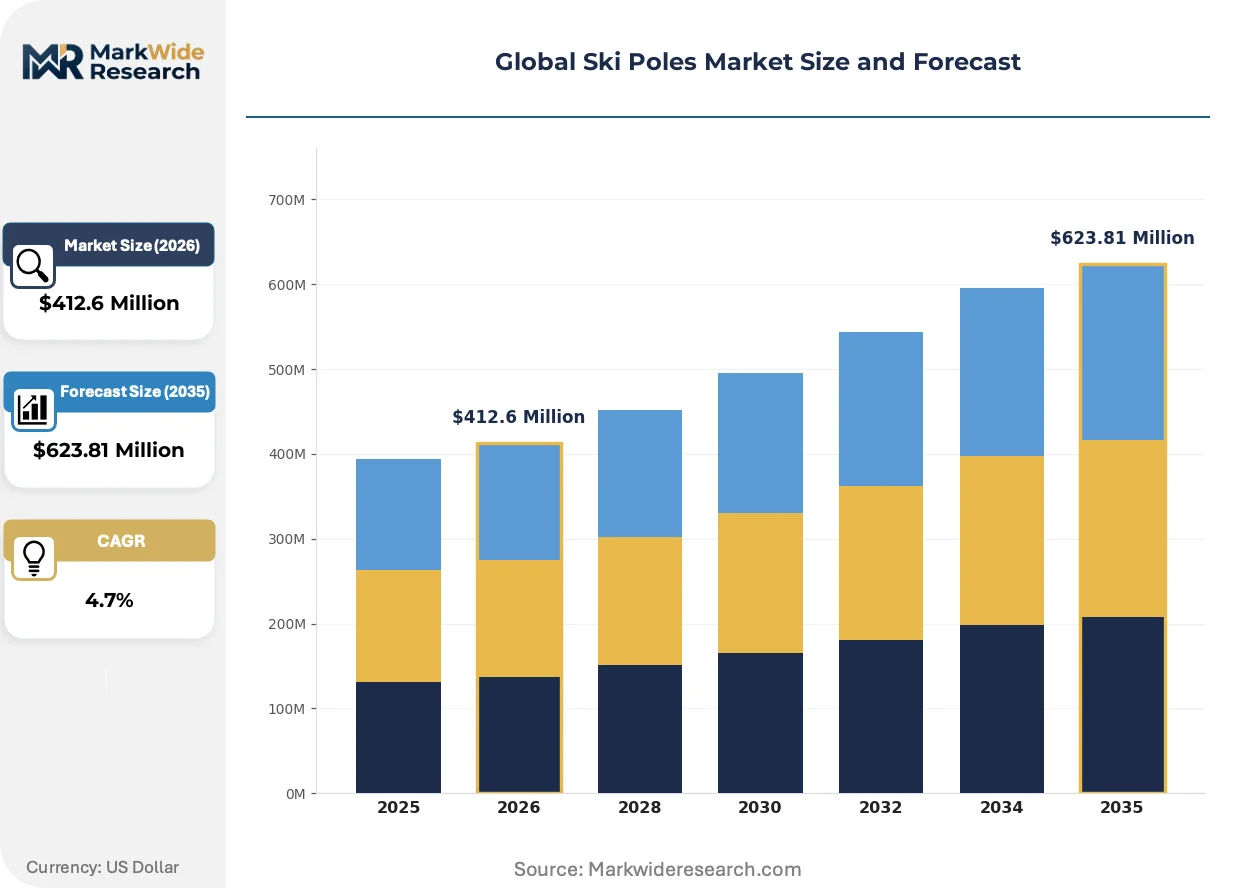
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $623.81 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Carbon Fiber, Composite, Wood Feature: Adjustable, Fixed Length, Shock Absorbing, Lightweight End User: Recreational Skiers, Professional Skiers, Beginners, Competitors Distribution Channel: Online Retail, Sports Stores, Specialty Shops, Department Stores |
| Companies Covered | K2, Line, Leki, MountainFLOW, Powder7, Black Crows, Black Diamond, Voile, Atomic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ski Poles Market Strategic Shifts
Material science advances and regulatory chemistry restrictions are fragmenting established supply relationships while creating entry points for bio-based competitors. Three distinct vectors are reshaping product architecture and go-to-market economics.
Flax-reinforced biocomposite prepregs are fragmenting the carbon fiber dominance in premium pole segments. Alpine touring athletes and competitive racers are adopting these plant-fiber hybrids for comparable stiffness-to-weight ratios. Established composite suppliers face margin compression as agricultural fiber processors enter the supply base.
REACH substance restrictions on perfluorinated compounds and specific phthalates are eliminating legacy strap and grip formulations from European distribution. Manufacturers must reformulate with bio-based elastomers or recycled TPU to maintain market access. The backcountry segment bears highest compliance cost due to extended-wear durability requirements.
Certification-driven preference sorting is restructuring retail procurement. Specialty shops now prioritize ISO 10228-compliant inventory, while rental fleets emphasize JIS-standard durability ratings. This bifurcation is most visible in Japanese and Austrian markets where regulatory enforcement and manufacturing proximity intersect.
Global Ski Poles Market Segmentation
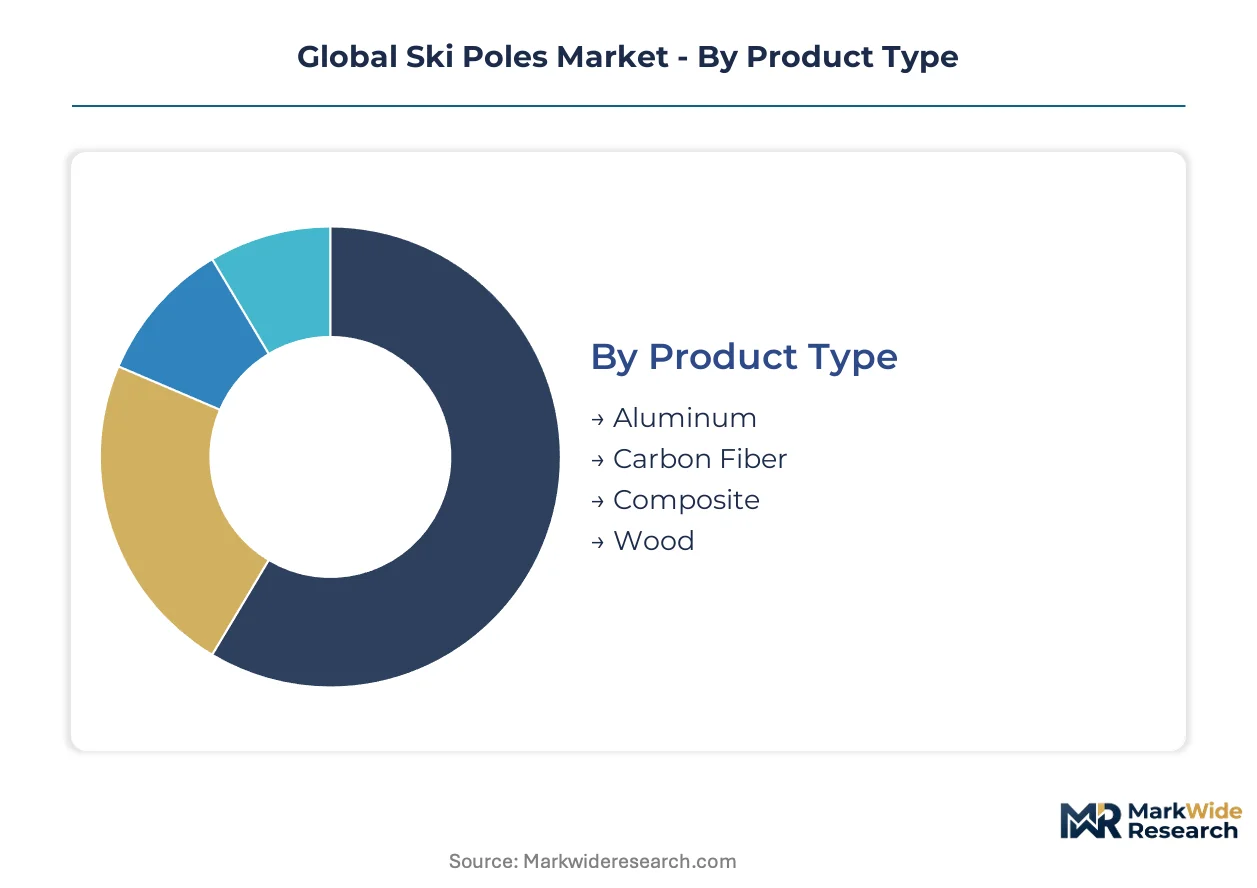
Material composition and feature engineering create divergent margin profiles across ski pole categories. Regulatory chemistry restrictions and certification requirements fragment sourcing strategies by segment tier.
Product Type:
REACH substance restrictions and EU F-Gas Regulation compliance costs vary sharply by material substrate, forcing tiered reformulation investments.
- Aluminum:6061-T6 and 7075-T6 alloys dominate rental fleet procurement and beginner category volume. Austrian manufacturers leverage recycled aluminum sourcing to meet EU Green Deal mandates while controlling input cost volatility for mid-tier lines.
- Carbon Fiber:Prepreg layups deliver maximum stiffness-to-weight ratios for competitive and alpine touring segments. Virgin petroleum-derived precursor exposure compresses margins during energy market spikes, accelerating trials with flax-reinforced biocomposite hybrids.
- Composite:Hybrid aluminum-carbon constructions balance durability and weight for all-mountain recreational use. Japanese JIS durability standards favor this construction for domestic distribution.
- Wood:Traditional laminated ash and hickory shafts retain niche demand in Nordic classic skiing and heritage product lines. Limited scale constrains supplier base to regional craftsmen.
Aluminum handles the majority of throughput; carbon fiber is gaining share fastest among certified premium suppliers.
Feature:
Adjustable mechanisms command manufacturing complexity premiums that stratify pricing across uphill-downhill hybrid disciplines.
- Adjustable:Telescoping aluminum or carbon shafts with locking mechanisms enable length modification between ascent and descent phases. Alpine touring participation in Austria and Switzerland drives fastest category expansion as equipment boundaries blur.
- Fixed Length:Traditional single-piece construction dominates rental fleet standardization and competitive racing specifications. Lowest unit cost supports volume leadership in emerging market entry categories.
- Shock Absorbing:Internal spring or elastomer dampening systems reduce wrist fatigue during groomed-trail poling. FDA strap material oversight adds compliance burden for US-bound inventory.
- Lightweight:Ultralight carbon fiber or composite constructions target gram-conscious backcountry travelers. ISO 10228 certification requirements elevate testing costs for this performance tier.
Fixed length maintains volume dominance; adjustable configurations show steepest expansion trajectory in specialty retail.
End User:
Skill-based segmentation aligns equipment durability requirements with replacement frequency and margin capture potential.
- Recreational Skiers:Weekend and vacation skiers prioritize durability and value in aluminum or composite constructions. Austrian and French alpine resorts concentrate replacement demand.
- Professional Skiers:Instructors and guides require avalanche-integrated designs with probe compatibility for backcountry safety protocols. Extended-wear durability demands strain REACH-compliant strap reformulation timelines.
- Beginners:First-time skiers drive rental fleet procurement and entry-level retail volume. Price sensitivity favors aluminum fixed-length poles with standardized sizing.
- Competitors:FIS-sanctioned racing mandates minimum weight and maximum stiffness specifications. Carbon fiber prepregs dominate with flax-hybrid trials gaining traction in cross-country disciplines.
Recreational skiers generate the bulk of unit demand; professional skiers are climbing the fastest on premium feature adoption.
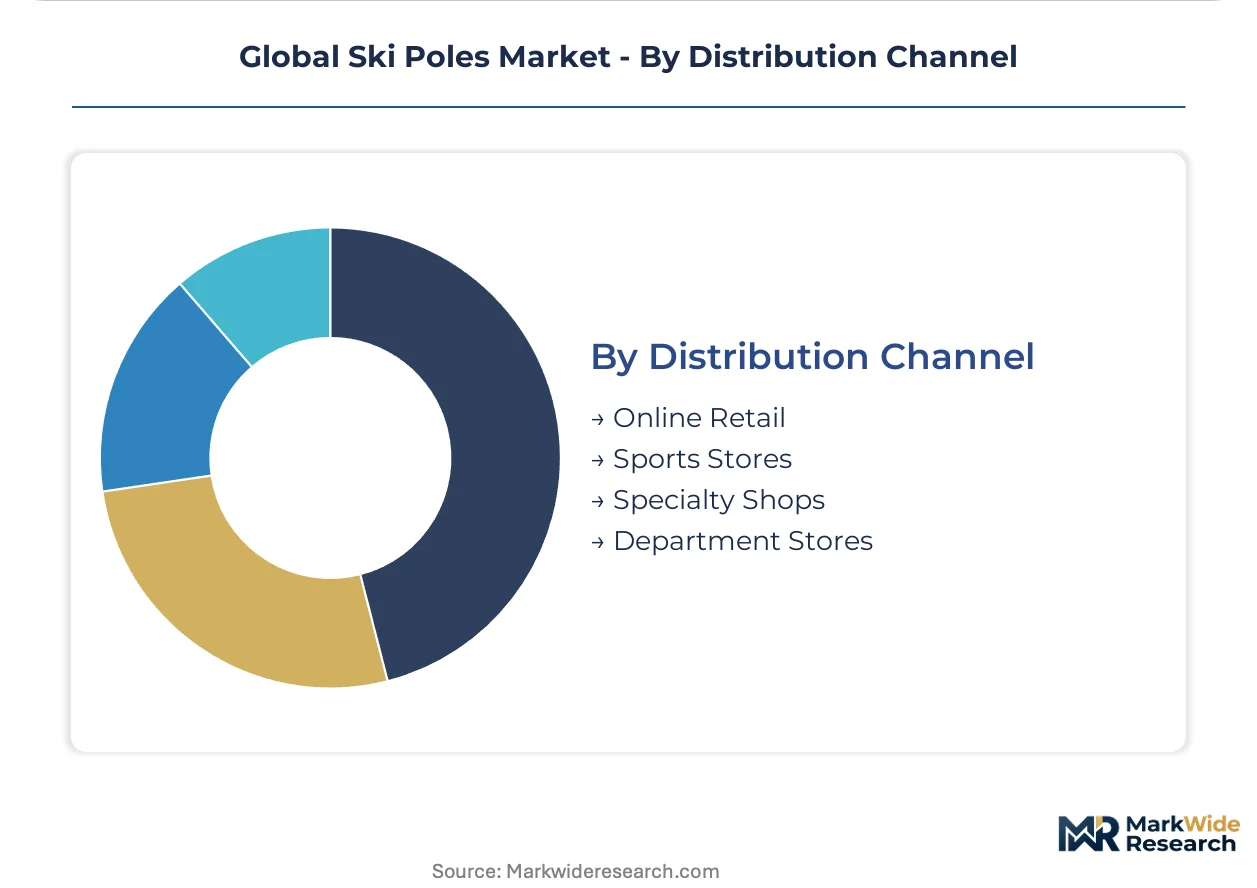
Distribution Channel:
Channel mix determines certification documentation requirements and inventory stranding risk under evolving chemical compliance deadlines.
- Online Retail:Direct-to-consumer platforms bypass wholesale markups in Nordic markets. Digital product pages must display ISO 10228 compliance documentation for European customers.
- Sports Stores:Multi-sport retailers carry mid-tier aluminum and composite lines with seasonal inventory cycles. Pre-REACH stockpiles face write-down pressure as retailers enforce compliance cutoffs.
- Specialty Shops:Dedicated ski retailers prioritize certified premium inventory with technical fitting services. Innsbruck manufacturing proximity supports just-in-time replenishment for Austrian and German markets.
- Department Stores:Mass retail channels move beginner-category aluminum poles with limited size variation. JIS-standard durability ratings dominate Japanese mass retail procurement.
Sports stores channel the highest unit volumes; specialty shops are expanding most quickly on certified premium mix.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation and REACH compliance are redrawing sourcing strategies across manufacturing footprints. Austria's Innsbruck cluster anchors European R&D and production density. Alpine touring participation in Switzerland and France concentrates demand for adjustable configurations.
Austria
Backcountry recreational skiers in Tyrol and Salzburg accelerate equipment refresh cycles. EU Green Deal recycled content mandates push manufacturers toward bio-based composites and recycled aluminum sourcing. Innsbruck's manufacturing cluster houses specialized labor pools and composite fabrication facilities serving German and Italian export markets.
United States
FDA oversight of strap materials elevates compliance costs for imported inventory. Professional ski instructors in Colorado and Utah drive avalanche-integrated pole adoption. The Pacific Northwest concentrates specialty retail procurement of certified premium lines.
Switzerland
Alpine touring participation blurs uphill-downhill equipment boundaries in Bernese Oberland and Graubünden. REACH chemical restrictions on perfluorinated compounds eliminate legacy grip formulations. Zürich-based distributors coordinate just-in-time replenishment for Austrian and German specialty shops.
Japan
JIS durability standards dominate mass retail procurement for domestic distribution. Weekend skiers in Hokkaido and Nagano prefectures sustain rental fleet demand. METI industrial policy supports composite material trials in Kansai manufacturing corridors.
France
Alpine resort concentration in Haute-Savoie and Isère drives recreational replacement demand. ECHA substance restrictions on specific phthalates force strap polymer reformulation. Lyon logistics hubs coordinate seasonal inventory flows to Italian and Spanish markets.
Global Ski Poles Market Competitive Environment
Player mix skews toward specialized alpine equipment fabricators with regional manufacturing footprints. Austrian and German entities dominate premium composite and aluminum forging capacity. Three archetypes define competitive positioning: vertically integrated material processors controlling upstream aluminum supply, backcountry specialists integrating safety features, and scale-driven assemblers operating large production facilities. Geographic expansion and certification-driven portfolio diversification represent the dominant competitive moves.
Among Austrian-based manufacturers, Leki and Atomic occupy distinct positions within the premium-tier supply base. Leki exemplifies the integrated fabricator archetype through in-house aluminum forging operations. Atomic represents scale-driven production concentration in the Salzburg region. Black Diamond anchors the backcountry specialist segment with probe-compatible safety integration. MountainFLOW sits within the emerging bio-composite tier addressing EU Green Deal compliance requirements.
| Leading Market Players |
|---|
| K2 |
| Line |
| Leki |
| MountainFLOW |
| Powder7 |
| Black Crows |
| Black Diamond |
| Voile |
| Atomic |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Austrian manufacturers and recycled aluminum processors lock in both supply access and price visibility against virgin metal volatility. These arrangements insulate mid-tier producers from spot market spikes while EU Green Deal mandates accelerate bio-composite substitution trials that redraw input cost baselines.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers. ISO 10228-compliant carbon fiber poles command manufacturing complexity premiums, while aluminum fixed-length poles serve price-sensitive rental fleets and beginner categories. Cost compression in virgin carbon fiber prepregs is intensifying because petroleum-derived precursor prices fluctuate with energy markets. Rental fleet operators exhibit highest price sensitivity; alpine touring specialists demonstrate lowest sensitivity due to performance-weight tradeoff preferences.
Supply Chain Analysis
Austria and China anchor ski pole manufacturing through distinct specializations. Austrian clusters concentrate composite fabrication and aluminum forging for European premium tiers; Chinese facilities supply aluminum shaft blanks and molded polymer components for mass-market assembly. Raw material dependencies center on petroleum-derived carbon fiber precursors, 6061-T6 and 7075-T6 aluminum alloys, and REACH-compliant elastomer formulations. Tariff exposure on primary aluminum imports strains mid-tier cost structures. Distribution runs through specialty ski retailers in Alpine markets and mass retail channels in North American and Asian geographies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as flax-reinforced biocomposites displace carbon fiber dominance in premium segments. Regulatory chemistry restrictions and certification mandates compound competitive pressure from agricultural fiber processors entering the supply base.
For Market Incumbents: Consolidate aluminum forging capacity through backward integration into recycled metal sourcing to meet EU Green Deal mandates while insulating margin structures. Lock in ISO 10228 certification pipelines to defend retail shelf access against emerging bio-composite competitors. Prioritize Innsbruck cluster proximity for just-in-time replenishment of Austrian and German specialty channels.
For New Entrants and Emerging Players: ISO 10228 fast-track certification creates regulatory moats for European market entry. Target adjustable pole configurations in Swiss and Austrian alpine touring segments where equipment refresh cycles accelerate. Deploy direct-to-consumer digital platforms in Nordic markets to bypass established wholesale markups and capture margin pools.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated fabricators with captive aluminum supply and in-house composite layup capabilities. Long-term viability hinges on material substitution readiness across the projection horizon. Monitor ECHA substance restriction timelines as inflection indicators for inventory stranding risk and reformulation capex cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Aluminum | EU Green Deal compliance secures supply access while insulating input cost volatility for mid-tier lines. |
| ISO 10228 Certification Investment | Safety standard compliance unlocks European and North American retail channel placement against uncertified rivals. |
| Flax-Reinforced Biocomposite R&D | Plant-fiber hybrid development addresses REACH chemical restrictions while capturing premium segment share from carbon fiber. |
| Avalanche-Integrated Design Launch | Probe-compatible pole systems penetrate untracked terrain segments where backcountry safety protocols drive equipment selection. |
| Direct-to-Consumer Channel Expansion | Brand-owned digital platforms bypass wholesale markups in Nordic markets and capture customer relationship data. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary validation through regulatory and trade databases. Interview subjects included composite fabrication technicians, aluminum forging plant managers, specialty ski retailer buyers, and ECHA regulatory affairs specialists. Secondary sources encompassed EU F-Gas Regulation filings, REACH substance restriction databases, Japanese JIS standard documentation, and customs trade records for aluminum and carbon fiber precursor flows. Bottom-up production capacity assessments and top-down demand modeling were triangulated against channel inventory data.
Across the analysis window, volume and value outputs were generated through segmentation modeling across material substrate, feature configuration, end-user skill tier, and distribution channel. CAGRs were derived from equipment replacement cycle analysis, alpine touring participation trends, and regulatory compliance timeline impacts. Industry-specific forecast inputs included EU Green Deal recycled content mandate schedules and ECHA substance restriction phase-out dates.
Decision-makers should treat outputs as directional under assumptions of sustained alpine touring participation growth and stable REACH enforcement timelines; material deviation in regulatory chemistry restrictions or energy market volatility would warrant model refresh. Recalibration cycles align with material shifts in ECHA substance restriction announcements and EU F-Gas Regulation amendment schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Mountain Bike Market
Outdoor and Adventure Activities
United States and Europe Horse Racing Market
Outdoor and Adventure Activities
Hunting Rangefinder Market
Outdoor and Adventure Activities
Global Personal Watercraft Market
Outdoor and Adventure Activities
Global Water Bikes Market
Outdoor and Adventure Activities
Rafting Equipment Market
Outdoor and Adventure Activities
Global Climbing Shoes Market
Outdoor and Adventure Activities
Paragliding Equipment Market
Outdoor and Adventure Activities
Adventure Sports and Activities Market
Outdoor and Adventure Activities
Outdoor Living Product Market
Outdoor and Adventure Activities
Kitesurf Kites Market
Outdoor and Adventure Activities
Ski Vacation Market
Outdoor and Adventure Activities
Fat Bike Market
Outdoor and Adventure Activities
Snowshoes Market
Outdoor and Adventure Activities
Skiing Equipment Market
Outdoor and Adventure Activities
Parasailing Equipment Market