
 Adventure Sports and Activities Market | 2026-2036
Adventure Sports and Activities Market Size, Share, and Industry Trends Forecast 2026-2036
Adventure Sports and Activities Market Insights
CE-certified safety harness specifications and ISO-rated climbing gear benchmarks are redrawing supplier qualification thresholds across the adventure sports value chain. G Adventures leverages direct-to-consumer booking platforms to sustain margin control in guided expedition segments. Mountain Travel Sobek anchors premium positioning through specialized polar and Himalayan itineraries that competitors struggle to replicate. Lindblad Expeditions dominates small-ship expedition cruising with controlled vessel ownership and naturalist-led programming.
Adventure sports and activities encompass physically demanding outdoor pursuits requiring specialized equipment, certified instruction, and managed environmental exposure, typically operating within defined risk parameters such as UIAA fall-factor ratings for climbing systems or USPA parachute deployment altitude minimums for skydiving operations. The primary commercial purpose spans recreational experience delivery, professional athletic training, and corporate group programming. Whitewater rafting and rock climbing command the largest participation bases among sport types, while safety certifications represent the fastest-growing service type as liability-conscious operators mandate documented training. Equipment rentals generate recurring revenue streams distinct from one-time gear purchases, particularly in seasonal markets where ownership costs deter casual participants.
OSHA workplace safety frameworks in the United States, the EU's CE marking requirements under the Personal Protective Equipment Regulation, and New Zealand's Adventure Activities Regulations collectively elevate operational compliance costs while filtering out informal operators. These standards reshape market access by requiring documented instructor certifications, equipment inspection protocols, and emergency response systems. Stakeholders must monitor evolving liability frameworks and certification reciprocity agreements as cross-border adventure tourism resumes structural growth.
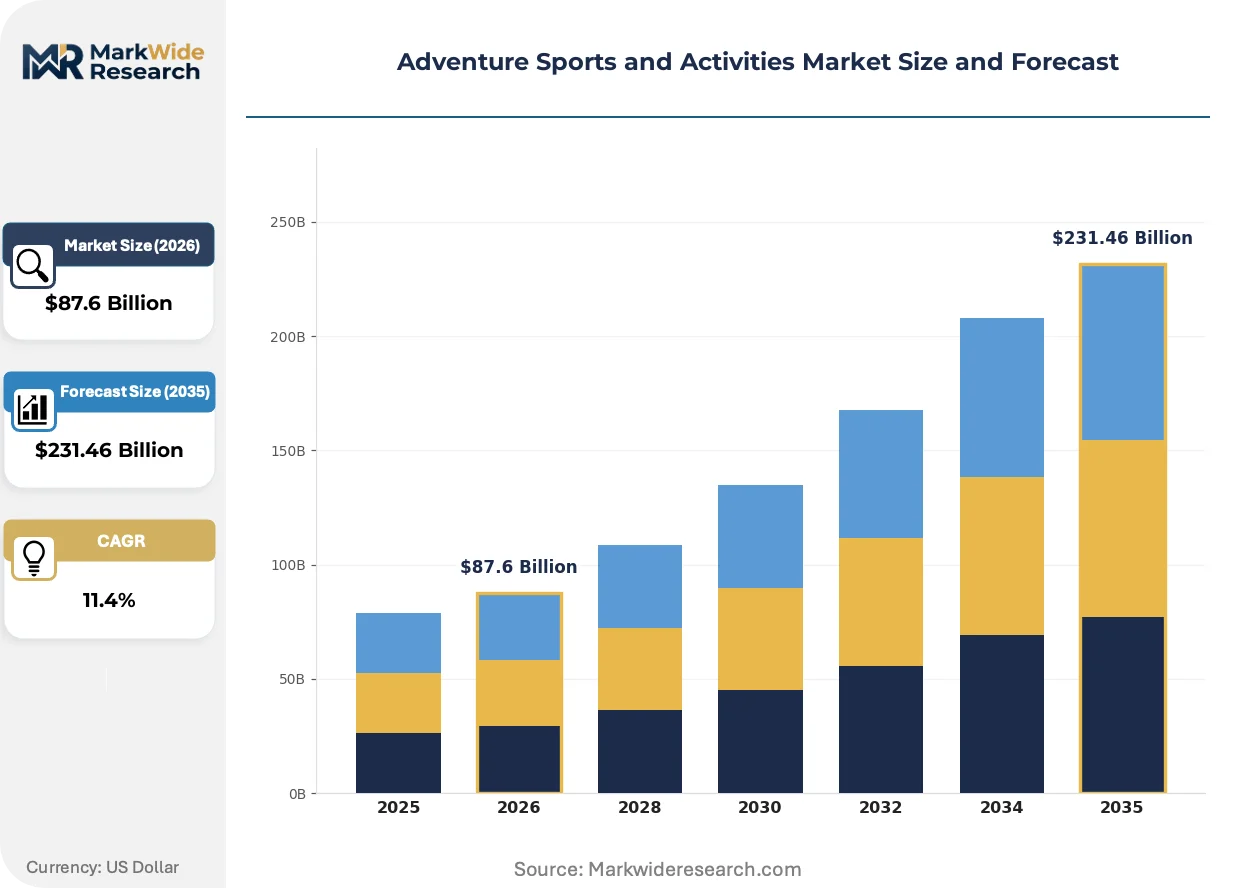
Market Dynamics
Corporate wellness procurement is redrawing demand composition as organizations replace traditional retreat formats with managed risk experiences, forcing operators to restructure pricing and liability frameworks around group contracting rather than individual bookings.
Growth Catalysts
- EU Physical Agents Directive:Mandatory vibration exposure limits for power-tool-dependent activities like ice climbing and motorized paragliding are accelerating equipment replacement cycles.
- Managed wilderness corridors:Australia's Queensland and Tasmania regional tourism boards are underwriting guide certification subsidies to anchor visitor economics in remote districts.
- Biometric monitoring integration:Real-time heart-rate and hydration tracking during high-altitude treks is expanding addressable participant demographics toward older age brackets.
Market Restraints
- Specialized textile supply concentration:Dyneema and Kevlar fiber production clusters in the Netherlands and Japan create single-source vulnerability for fall-arrest system manufacturers.
- CE marking reciprocity gaps:Non-EU operators face 14-18 month approval timelines to place equipment on European markets, freezing working capital in certification pipelines.
- Indoor climbing substitution:Climate-controlled artificial wall facilities in urban cores capture casual participants who would otherwise generate seasonal tourism revenue in natural settings.
Strategic Opportunities
- Adaptive equipment protocols:Paralympic-standard harness modifications and seated climbing systems remain underdeveloped across Southeast Asian adventure tourism markets.
- Carbon-offset bundling:Flight-intensive polar and Himalayan itineraries can attach verified reforestation credits to capture ESG-mandated corporate procurement.
- Drone-assisted search architecture:Thermal-imaging UAV deployment protocols for backcountry rescue are converging with automated flight-path software to reduce insurance underwriting costs.
Industry Challenges
- UIAA fall-factor certification backlog:Testing laboratory capacity constraints in Switzerland and Germany are extending product launch timelines by 8-12 months for climbing hardware innovators.
- Seasonal workforce liquidity:Guide retention across New Zealand's South Island operators collapses during Northern Hemisphere summer as talent migrates to European alpine contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adventure Sports and Activities Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $231.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sport Type: Rock Climbing, Skydiving, Bungee Jumping, Whitewater Rafting Equipment Type: Climbing Gear, Parachutes, Safety Harnesses, Kayaking Gear End User: Recreational Users, Professional Athletes, Educational Institutions, Corporate Groups Service Type: Guided Tours, Training Programs, Equipment Rentals, Safety Certifications |
| Companies Covered | Intrepid Group, G Adventures, Mountain Travel Sobek, ROW Adventures, TUI Group, Cox & Kings, Abercrombie & Kent, REI Adventures, Lindblad Expeditions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adventure Sports and Activities Market Trends and Innovations
Digital booking infrastructure is compressing intermediary layers while safety telemetry and adaptive equipment protocols are redefining participant eligibility criteria and operator liability structures.
Lightweight carbon-fiber carabiner and protection hardware is fragmenting traditional forged-aluminum supply relationships among technical climbing equipment manufacturers. Elite alpine guiding services in Chamonix and the Dolomites are adopting these systems despite 40-60% cost premiums. The technology is fragmenting established procurement hierarchies by enabling direct-to-guide sales models that bypass legacy distributor networks.
New Zealand's Adventure Activities Regulations audit framework is mandating documented emergency response drills and equipment traceability protocols for all commercial operators. This elevates compliance costs for small-scale providers while creating competitive separation for accredited outfits. Australian operators seeking cross-Tasman certification reciprocity are restructuring internal training programs to match these documentation standards.
Corporate group buyers are unbundling traditional package pricing to demand itemized risk-management line items and instructor qualification transparency. Regional tourism boards in Cairns and Queenstown are responding with standardized certification disclosure portals. This pattern is most visible in Australia where procurement officers face internal audit requirements for duty-of-care documentation.
Adventure Sports and Activities Market Segmentation
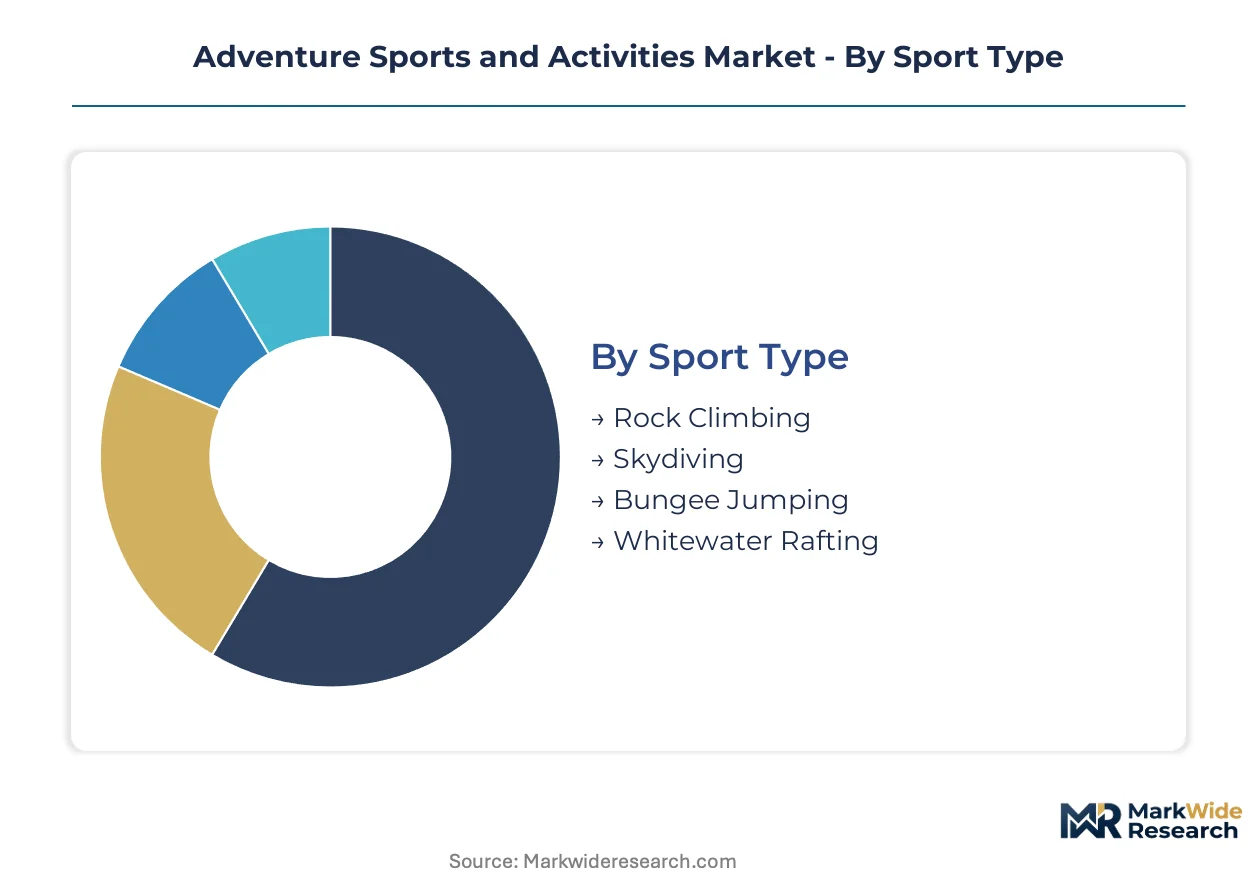
Adventure sports segmentation reveals how equipment substitution and service unbundling reshape procurement patterns across participant demographics. Distinct risk tolerances and certification requirements create divergent margin profiles that operators must navigate through targeted positioning.
Sport Type:
Indoor climbing facilities and virtual reality simulators exert substitution pressure unevenly across outdoor disciplines, with some segments facing immediate displacement while others retain irreplaceable environmental dependencies.
- Rock Climbing:Technical ascent disciplines requiring UIAA-rated protection systems and documented belay protocols. Demand concentrates in Australia's Blue Mountains and New Zealand's South Island where guide certification subsidies anchor regional visitor economics against indoor wall substitution.
- Whitewater Rafting:River descent activities utilizing self-bailing rafts and helmeted crew coordination across graded rapid classifications. Procurement from corporate wellness programs in Queensland's Cairns corridor drives group contracting volume as organizations replace traditional retreat formats.
- Skydiving:Tandem and solo freefall operations governed by USPA deployment altitude minimums and reserve parachute repacking cycles.
- Bungee Jumping:Elastic cord-based aerial deceleration systems with site-specific cord elasticity calibration and jumper weight protocols.
Whitewater rafting anchors the volume base while safety certifications gain share at the steepest rate.
Equipment Type:
Carbon-fiber innovation fragments established procurement hierarchies by enabling direct-to-guide sales models that bypass legacy distributor networks.
- Climbing Gear:Carabiners, protection hardware, and dynamic ropes rated to CE EN standards and UIAA fall-factor specifications. Lightweight carbon-fiber systems command 40-60% cost premiums in Chamonix and Dolomite alpine guiding services despite distributor bypass.
- Safety Harnesses:Fall-arrest and work-positioning systems constructed from Dyneema and Kevlar fibers with CE marking requirements under EU Personal Protective Equipment Regulation. Production concentration in Netherlands and Japanese fiber clusters creates single-source vulnerability for manufacturers.
- Parachutes:Ram-air canopy systems with documented repacking intervals and AAD automatic activation device integration.
- Kayaking Gear:Whitewater-specific paddlecraft with spray deck compatibility and hull impact resistance ratings.
Climbing gear generates the highest equipment margin pool while safety harnesses face the steepest regulatory compliance cost escalation.
End User:
Corporate procurement officers now demand itemized risk-management documentation that forces operators to restructure pricing frameworks around group contracting.
- Corporate Groups:Organizational buyers seeking managed risk experiences for team-building programming with duty-of-care audit requirements. Cairns and Queenstown tourism boards respond with standardized certification disclosure portals for procurement transparency.
- Recreational Users:Casual participants generating seasonal tourism revenue vulnerable to indoor climbing substitution in urban cores.
- Professional Athletes:Elite performers requiring competition-grade equipment and specialized training protocols.
- Educational Institutions:Schools and universities integrating adventure programming into physical education curricula.
Corporate groups command premium pricing tiers while recreational users face the strongest indoor substitution threat.
Service Type:
Digital booking infrastructure compresses intermediary layers while biometric monitoring integration expands addressable demographics toward older age brackets.
- Safety Certifications:Documented training programs with instructor qualification transparency and liability-conscious operator mandates. New Zealand's Adventure Activities Regulations audit framework elevates compliance costs while creating competitive separation for accredited outfits.
- Guided Tours:Expedition delivery with naturalist-led programming and controlled vessel or route ownership in polar and Himalayan corridors.
- Training Programs:Skills development courses with progression pathways from novice to technical competence.
- Equipment Rentals:Recurring revenue streams distinct from one-time gear purchases in seasonal markets where ownership costs deter casual participants.
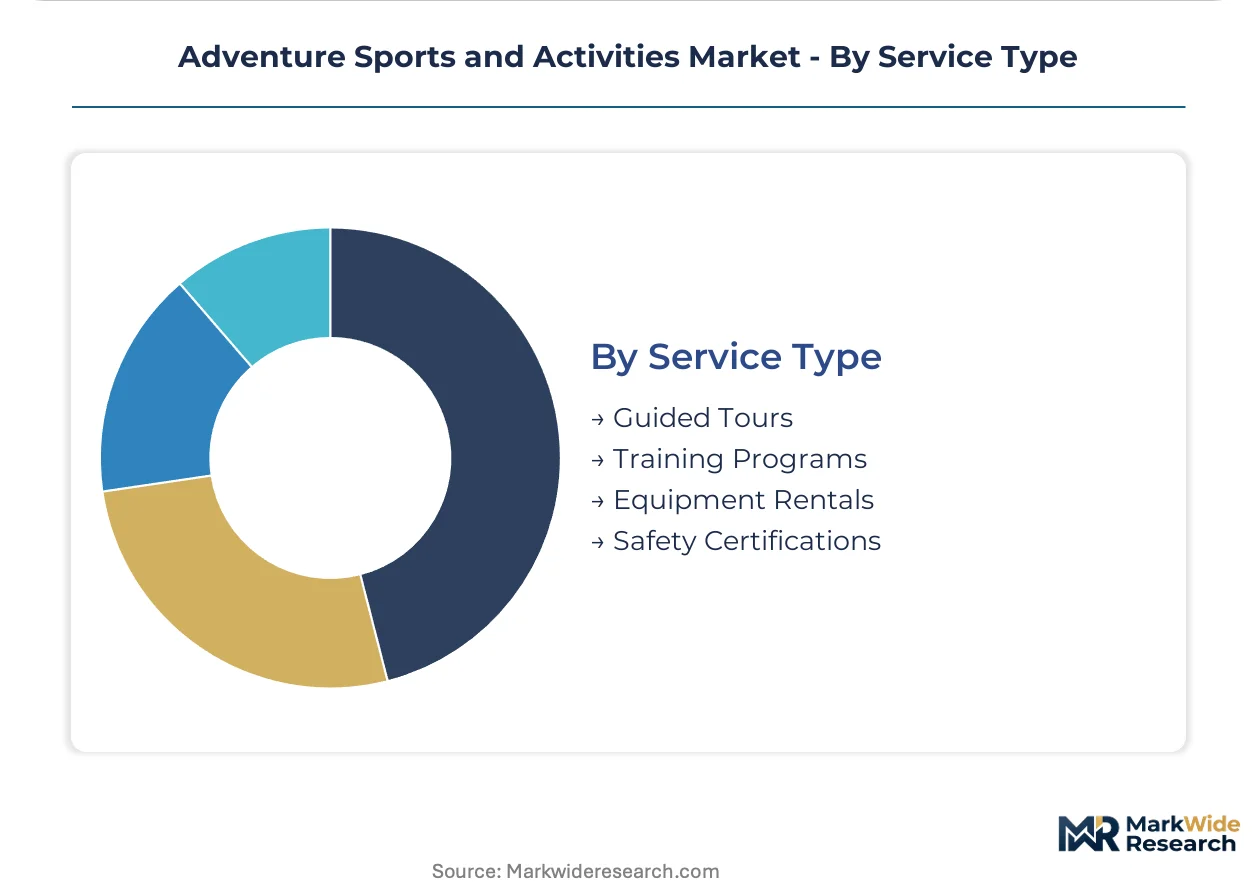
Equipment rentals provide the most stable recurring revenue base while safety certifications climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fiber production for technical climbing equipment clusters in the Netherlands and Japan, creating supply-side dependencies that shape regional market access. Equipment certification mandates and guide qualification frameworks diverge sharply across jurisdictions, forcing operators to maintain parallel compliance systems.
Australia
Queensland's Cairns corridor and Tasmania's wilderness tourism boards underwrite guide certification subsidies to anchor visitor economics in remote districts. The country's Adventure Activity Standards require documented emergency response protocols and equipment traceability. Blue Mountains operators near Sydney face indoor climbing substitution pressure from urban wall facilities.
New Zealand
South Island alpine guiding services concentrate around Queenstown and Wanaka, with seasonal workforce liquidity collapsing during Northern Hemisphere summer. The Adventure Activities Regulations audit framework mandates documented emergency response drills. Auckland-based procurement officers increasingly demand itemized risk-management documentation for corporate wellness programming.
Switzerland
Chamonix-adjacent alpine services and UIAA testing laboratories in Bern and Zurich face certification backlog extending product launch timelines. The country's fall-factor testing capacity constraints bottleneck climbing hardware innovators. Swissmedic-equivalent safety frameworks for equipment standards filter informal operators from commercial markets.
United States
OSHA workplace safety frameworks elevate operational compliance costs for commercial operators across Colorado's Front Range and Utah's Wasatch corridor. Yosemite and Moab climbing economies generate concentrated equipment demand. FAA regulations govern motorized paragliding and drone-assisted search architectures in backcountry rescue protocols.
Germany
CE marking requirements under the Personal Protective Equipment Regulation create 14-18 month approval timelines for non-EU equipment manufacturers. Bavarian alpine guiding services and Black Forest outdoor tourism clusters drive regional participation. Berlin-based corporate wellness procurement officers mandate duty-of-care documentation for adventure programming contracts.
Adventure Sports and Activities Market Competitive Landscape
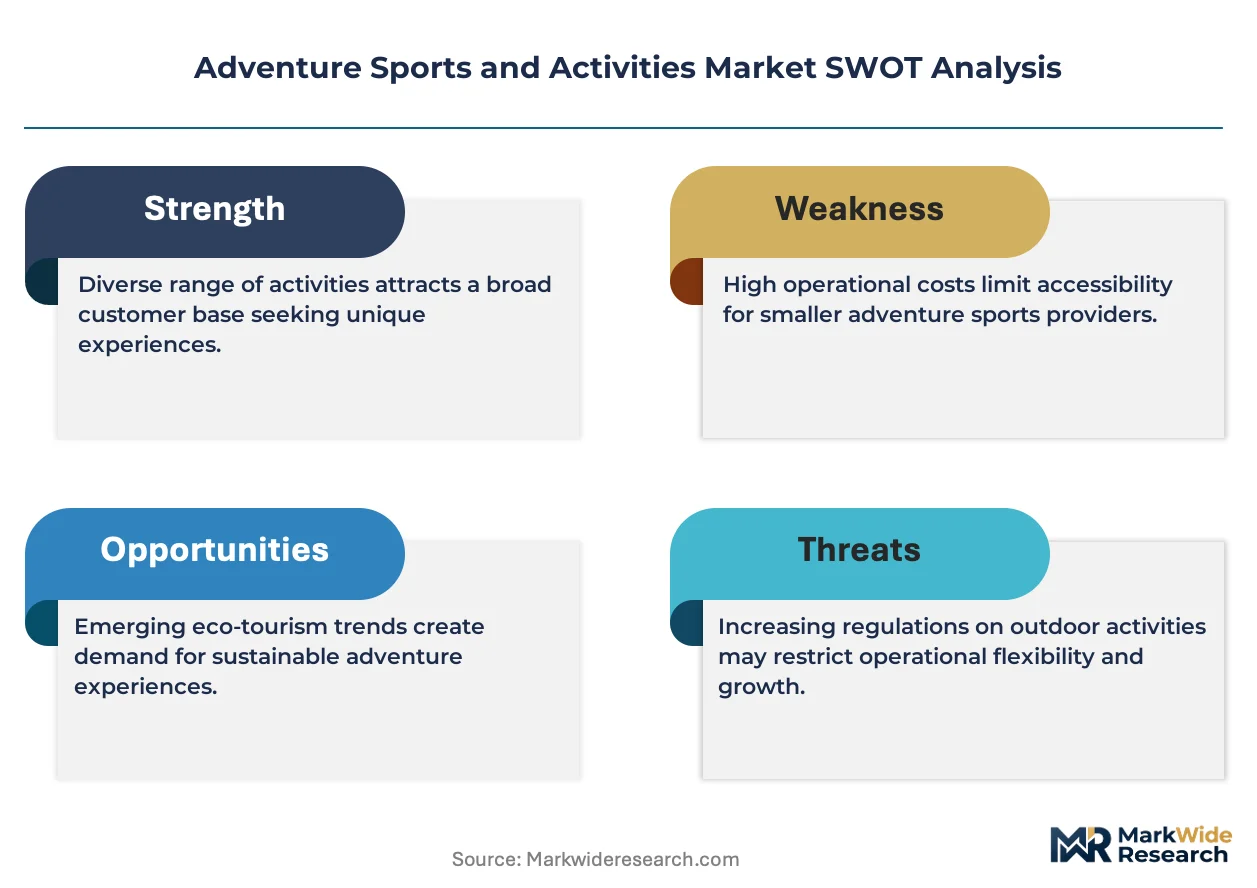
Technology leadership and cost leadership are held by different player archetypes, with premium expedition specialists maintaining controlled vessel ownership while mass-market operators leverage digital booking infrastructure. The market structures around three tiers: integrated expedition cruise operators, specialized alpine guiding services, and platform-based booking intermediaries. Dominant competitive moves include geographic itinerary diversification and direct-to-consumer channel development.
Among expedition cruise specialists, Lindblad Expeditions and G Adventures exemplify divergent archetypes. Lindblad represents the controlled-asset model with naturalist-led programming in polar corridors. G Adventures occupies the platform-optimized position, sustaining margin control through direct booking channels. Mountain Travel Sobek anchors the premium-tier vector through specialized Himalayan and polar itineraries that resist replication.
| Leading Market Players |
|---|
| Intrepid Group |
| G Adventures |
| Mountain Travel Sobek |
| ROW Adventures |
| TUI Group |
| Cox & Kings |
| Abercrombie & Kent |
| REI Adventures |
| Lindblad Expeditions |
| Others |
Pricing and Supply Chain Analysis
Long-term guide certification contracts lock in both seasonal labor access and rate visibility for operators across Queensland's Cairns corridor and New Zealand's South Island. These arrangements insulate accredited outfits from spot-market wage volatility while embedding equipment procurement commitments that stabilize Dyneema fiber pricing tiers.
Pricing Analysis
CE marking requirements under the EU Personal Protective Equipment Regulation dictate the pricing tier structure across fall-arrest and climbing protection systems. Three-tier pricing structure across premium carbon-fiber hardware, standard forged-aluminum gear, and economy rental equipment separates UIAA-certified alpine specialists from casual indoor wall operators. Cost compression in economy rental tiers is intensifying because climate-controlled urban facilities capture seasonal tourists who previously generated natural-site revenue. Corporate wellness procurement officers demonstrate the lowest price sensitivity due to duty-of-care audit mandates, while recreational casual participants face the strongest budget constraints.
Supply Chain Analysis
Dyneema and Kevlar fiber production clusters in the Netherlands and Japan create single-source vulnerability for technical climbing equipment manufacturers. Fall-arrest system assembly draws from Dutch textile weaving, Japanese polymer engineering, and Chinese hardware forging. Tariff exposure on carbon-fiber pre-preg imports from Japan disrupts lightweight carabiner production timelines. Distribution runs through specialized outdoor retail networks in Chamonix, direct-to-guide sales platforms in the Dolomites, and seasonal rental depots in Queenstown.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biometric monitoring integration is disrupting participant eligibility criteria and expanding addressable demographics toward older age brackets with managed risk profiles.
For Market Incumbents: Consolidate guide certification reciprocity agreements across Australia and New Zealand to lock in seasonal workforce liquidity. Acquire or partner with drone-assisted search architecture providers to reduce insurance underwriting exposure. Vertical integration into Dyneema fiber sourcing mitigates Netherlands and Japan supply concentration risk. For New Entrants and Emerging Players: UIAA fast-track certification partnerships with Swiss and German testing laboratories accelerate market entry timelines. Adaptive equipment protocols for Paralympic-standard harness modifications remain underdeveloped across Southeast Asian adventure tourism markets. Carbon-offset bundling for flight-intensive polar itineraries captures ESG-mandated corporate procurement. For Investors and Strategic Acquirers: Capital is best deployed toward accredited operators with documented emergency response protocols under New Zealand's Adventure Activities Regulations audit framework. Long-term viability hinges on compliance infrastructure that filters informal competitors. Monitor CE marking reciprocity negotiation progress as inflection indicator for non-EU equipment manufacturer market access.| Strategic Initiative | Industry Significance |
|---|---|
| Guide Certification Reciprocity Agreement | Cross-Tasman labor mobility stabilizes Queenstown operator staffing through Northern Hemisphere summer. |
| Carbon-Offset Bundling Program | Verified reforestation credits attached to Himalayan itineraries satisfy ESG-mandated corporate procurement criteria. |
| Drone-Assisted Search Architecture Deployment | Thermal-imaging UAV protocols reduce backcountry rescue insurance underwriting costs for alpine operators. |
| Adaptive Equipment Protocol Development | Paralympic-standard harness modifications unlock underpenetrated Southeast Asian adventure tourism demographics. |
| Direct-to-Guide Carbon-Fiber Hardware Sales | Bypassing legacy distributor networks captures 40-60% cost premium retention in Chamonix and Dolomite markets. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with expedition operators, guide certification bodies, and corporate wellness procurement officers; and secondary validation through UIAA equipment testing records, TGA safety incident databases, and regional tourism board visitor economics reports. Bottom-up triangulation across operator revenue disclosures and top-down reconciliation against Cairns and Queenstown corridor economic impact studies anchored volume estimates.
Across the projection horizon, the analytical framework modeled sport type, equipment category, and end-user archetype with service type penetration as an industry-specific dimension. CAGRs derived from segment-level growth rate reconciliation against macro adventure tourism participation trends. Forecast inputs incorporated UIAA fall-factor certification backlog timelines and seasonal workforce liquidity migration patterns between Southern and Northern Hemisphere alpine contracts.
Decision-makers should treat outputs as directional under stable regulatory reciprocity and fiber supply continuity assumptions; material deviation in CE marking approval timelines or Dyneema production capacity would warrant model refresh. Practitioners should keep alternative scenarios live as biometric monitoring integration rates and indoor climbing substitution velocity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Parasailing Equipment Market
Outdoor and Adventure Activities
Climbing Harness Market
Outdoor and Adventure Activities
Global Personal Watercraft Market
Outdoor and Adventure Activities
Spain Artificial Turf Market
Outdoor and Adventure Activities
Fat Bike Market
Outdoor and Adventure Activities
Outdoor Living Product Market
Outdoor and Adventure Activities
Hydration Packs Market
Outdoor and Adventure Activities
US Spectator Sports Market
Outdoor and Adventure Activities
India Spectator Sports Market
Outdoor and Adventure Activities
Kayak Market
Outdoor and Adventure Activities
Global Inflatable Outdoor Leisure Product Market
Outdoor and Adventure Activities
North America Climbing Gears Market
Outdoor and Adventure Activities
Adventure Gear Market
Outdoor and Adventure Activities
Hiking Cleats Market
Outdoor and Adventure Activities
Snowshoes Market
Outdoor and Adventure Activities
Leisure Centers Market