
 Motorized Pool Tube Market | 2026-2036
Motorized Pool Tube Market Size, Share, and Industry Trends Forecast 2026-2036
Motorized Pool Tube Market Foresight
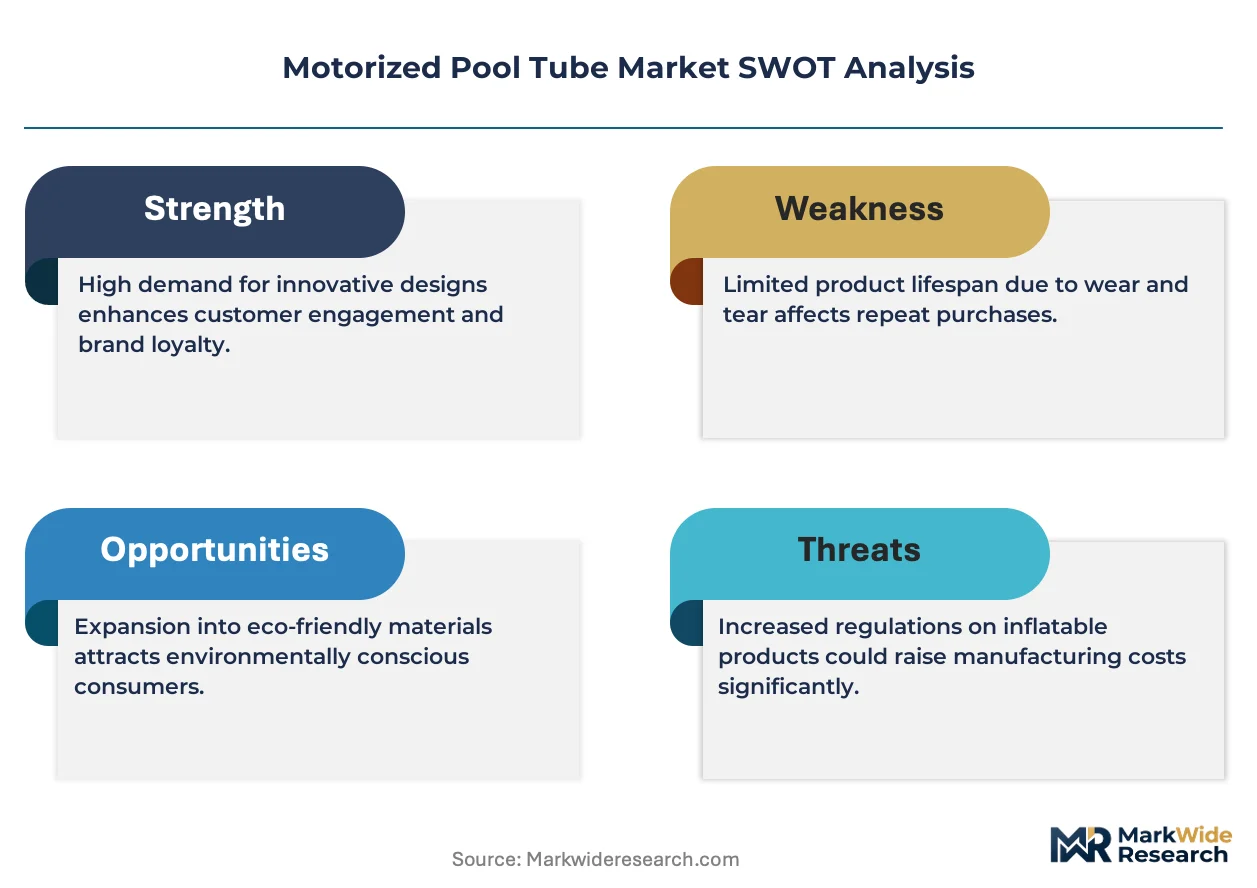
Waterproof lithium-ion battery miniaturization is narrowing the cost-performance gap between entry-level and premium motorized pool tubes. INTEX Recreation Corp leverages its mass-manufacturing scale across Asian production bases to sustain low unit economics. Bestway Inflatables & Material Corp anchors its competitive stance through backward integration into PVC and drop-stitch material supply. Poolside Tech differentiates via app-connected speed control and proprietary motor housings designed for saltwater tolerance.
A motorized pool tube is a buoyant, propulsion-equipped flotation device incorporating sealed electric motors, waterproof battery enclosures, and directional control interfaces to enable self-propelled movement across pool surfaces without paddling. Construction typically involves radio-frequency welded PVC or reinforced thermoplastic polymer shells rated for continuous submersion at depths up to one meter. Inflatable tubes retain dominant volume share due to collapsible storage and shipping efficiency, while hard-shell tubes capture margin concentration through durability warranties and integrated LED lighting systems. Battery-powered configurations lead unit sales, though solar-assisted hybrid variants are gaining traction in commercial pool installations where daytime utilization is fixed.
The Consumer Product Safety Commission enforces submersible electrical device standards that dictate insulation ratings and cord-guard specifications for mains-powered units sold in the United States. California's Proposition 65 labeling requirements and the EPA's phthalate restrictions in children's products shape material selection and compliance costs for manufacturers distributing across North American channels. Stakeholders must monitor evolving waterproofing certification protocols and regional chemical substance bans to preempt supply chain redesign cycles.
Market Dynamics
Waterproof lithium-ion battery miniaturization is compressing the performance gap between entry-level and premium motorized pool tubes, forcing incumbents to defend margin positions through proprietary motor housings and saltwater-tolerant materials rather than raw power specifications.
Growth Catalysts
- Smart Home Leisure Integration:Residential users are embedding motorized pool tubes into connected backyard ecosystems, with app-controlled speed interfaces driving replacement cycles for legacy manual units.
- California Proposition 65 Compliance:Material transparency requirements are accelerating phthalate-free PVC adoption, creating first-mover advantages for manufacturers with certified supply chains.
- Drop-Stitch Material Advances:Reinforced thermoplastic polymer construction is extending inflatable tube lifespans, reducing total cost of ownership and expanding addressable demand in seasonal climates.
Market Restraints
- Lithium-Ion Cell Cost Volatility:Raw material price swings for battery-grade lithium carbonate compress margin predictability for mid-tier assemblers lacking long-term supplier contracts.
- Radio-Frequency Welding Equipment Concentration:Sealed seam manufacturing depends on specialized machinery concentrated in Guangdong and Zhejiang provinces, exposing supply chains to regional logistics disruptions.
- Submersible Electrical Device Standards:CPSC insulation rating requirements and cord-guard specifications impose fixed compliance costs that disproportionately burden low-volume entrants.
Strategic Opportunities
- Solar-Assisted Hybrid Configurations:Commercial pool operators in sun-belt states are piloting photovoltaic-integrated tubes for daytime fixed-schedule utilization, opening B2B volume contracts.
- EPA Phthalate Restrictions:Children's product chemical bans are creating regulatory tailwinds for manufacturers with pre-certified material libraries, accelerating retailer shelf access.
- Saltwater Pool Compatibility:Corrosion-resistant motor housing technology addresses the fastest-growing residential pool chemistry segment, commanding pricing premiums in coastal markets.
Industry Challenges
- Waterproofing Certification Timelines:Third-party IPX8 validation and continuous submersion testing create 4-6 month product launch delays, compressing seasonal sales windows.
- Radio-Frequency Welding Technician Scarcity:Specialized seam-sealing expertise is concentrating among aging workforces in Asian manufacturing clusters, constraining quality-scaled expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorized Pool Tube Market |
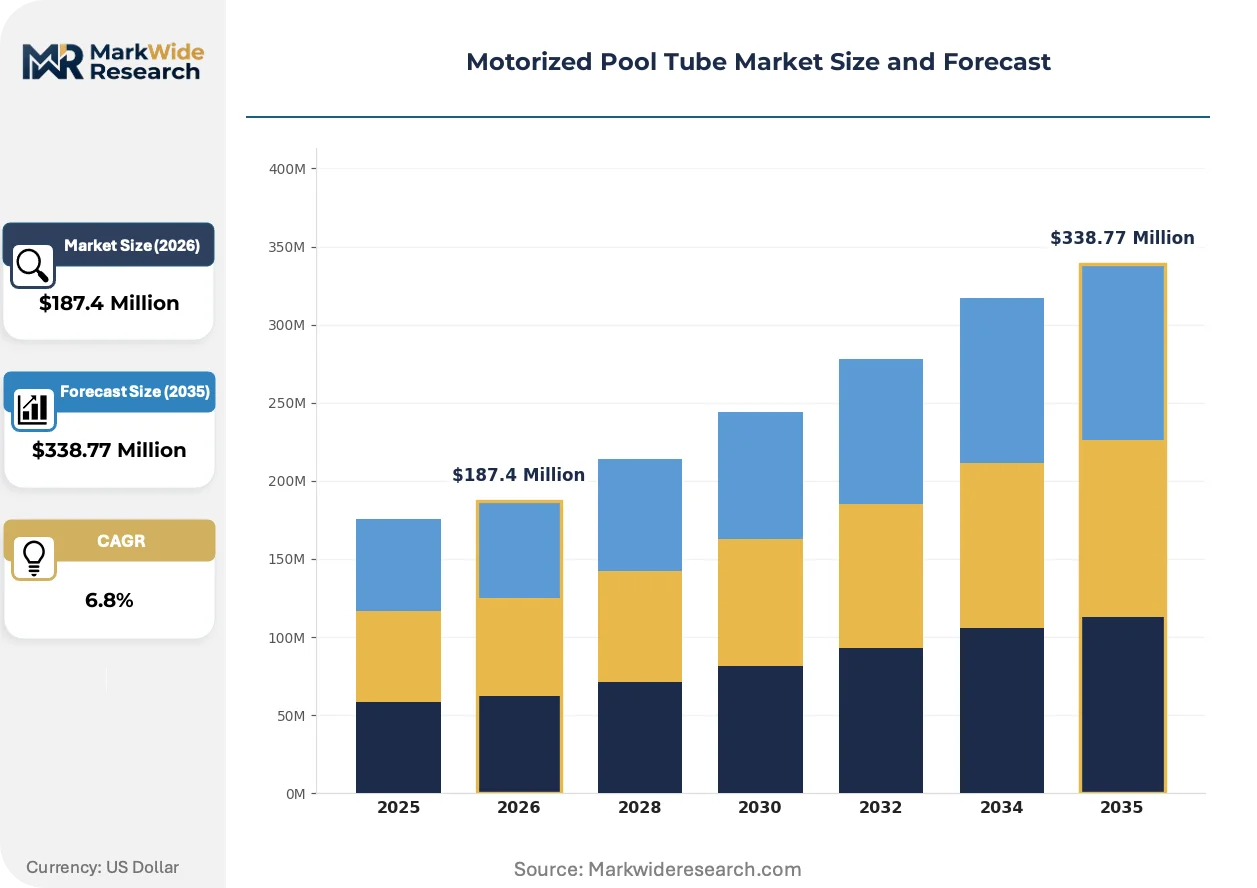
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inflatable Tubes, Hard-shell Tubes, Electric Tubes, Accessories End User: Residential Users, Commercial Pools, Water Parks, Rental Services Power Source: Battery-powered, Solar-powered, Mains-powered, Hybrid Features: Adjustable Speed, Bluetooth Connectivity, LED Lighting, Safety Features |
| Companies Covered | INTEX Recreation Corp, Bestway Inflatables & Material Corp, Swimline, FUNBOY, Poolmaster, Poolside Tech, PoolCandy, Arshiner, Airhead Sports, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorized Pool Tube Market Shifts & Advancements
Active virtualization of control interfaces is displacing physical tethered remotes, while regulatory chemical restrictions and experiential recreation spending patterns are simultaneously reshaping material selection and distribution channel priorities.
Directional control interfaces are virtualizing through smartphone app connectivity and Bluetooth Low Energy protocols. Residential buyers now expect gesture-based speed adjustment and GPS-enabled pool perimeter mapping as baseline features. This shift is virtualizing hardware margins into software-enabled recurring revenue streams for firmware-updatable units.
REACH substance restrictions and EU Green Deal circularity requirements are extending beyond European borders through multinational retailer procurement standards. Manufacturers serving German and French distribution channels must now document full polymer supply chain provenance. Hard-shell tube producers with integrated LED lighting systems face additional RoHS compliance verification for soldered circuit assemblies.
Experiential recreation spending is fragmenting traditional retail channel dominance. Specialty pool contractors and direct-to-consumer platforms are capturing share from mass-market big-box distribution for premium-tier configurations. This channel rotation is most pronounced in Texas, Florida, and Arizona metropolitan clusters where backyard renovation activity concentrates.
Motorized Pool Tube Market Segmentation
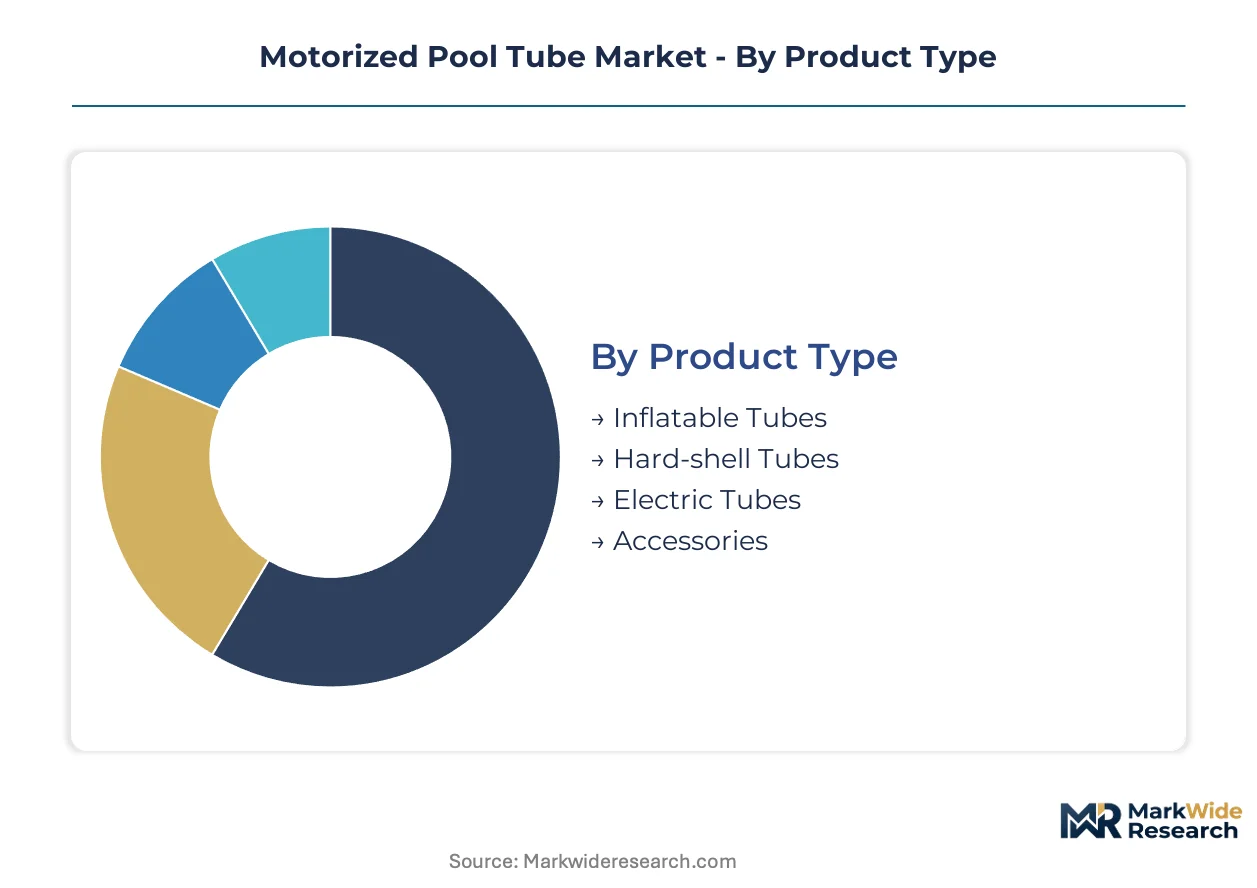
Motorized pool tube purchasing patterns diverge sharply across construction methods, user environments, and power architectures. Manufacturers must align R&D portfolios and distribution investments to the specific durability, connectivity, and energy requirements each segment demands.
Product Type:
Cost tier differentiation separates collapsible convenience from integrated durability in this foundational segmentation.
- Inflatable Tubes:Radio-frequency welded PVC or reinforced thermoplastic polymer shells rated for one-meter submersion depth. Demand concentrates in seasonal climates where storage efficiency drives purchasing decisions, particularly among residential buyers in the Northeastern United States facing winterization requirements.
- Hard-shell Tubes:Rigid polymer construction with integrated LED lighting systems and extended durability warranties. Commercial pool operators in Florida and Texas metropolitan clusters favor these units for high-rotation rental fleets where puncture resistance justifies premium positioning.
- Electric Tubes:Sealed motor housings with directional control interfaces enabling self-propelled pool surface movement.
- Accessories:Replacement battery packs, charging stations, and protective storage covers extending product lifecycles.
Inflatable tubes command the established base. The steepest expansion runs through hard-shell configurations.
End User:
Application environment dictates performance specifications, duty cycles, and procurement channel preferences across buyer categories.
- Residential Users:Backyard pool owners integrating motorized tubes into connected leisure ecosystems through smartphone app control. Smart home leisure integration in Arizona, Texas, and Florida is accelerating replacement cycles for legacy manual flotation devices.
- Commercial Pools:Hotels, resorts, and fitness centers requiring corrosion-resistant motor housings for saltwater chemistry compatibility. Procurement concentrates through specialty pool contractors rather than mass-market retail channels.
- Water Parks:High-throughput environments demanding rapid-charge battery systems and reinforced seam construction for continuous daily operation.
- Rental Services:Seasonal operators prioritizing collapsible storage density and field-repairable construction for logistics efficiency.
Commercial pools command the established base. The steepest expansion runs through residential users.
Power Source:
Energy architecture determines mobility range, charging infrastructure requirements, and regulatory compliance burdens for manufacturers.
- Battery-powered:Waterproof lithium-ion enclosures with IPX8 continuous submersion certification. Unit sales leadership reflects residential preference for untethered pool surface mobility without electrical cord hazards.
- Solar-powered:Photovoltaic-integrated surfaces charging during daytime fixed-schedule utilization. Commercial operators in sun-belt states are piloting these configurations for B2B volume contracts.
- Mains-powered:Corded operation requiring CPSC insulation ratings and cord-guard specifications for submersible electrical device compliance.
- Hybrid:Dual-mode systems combining battery storage with solar trickle-charging for extended operational windows.
Battery-powered configurations command the established base. The steepest expansion runs through hybrid architectures.
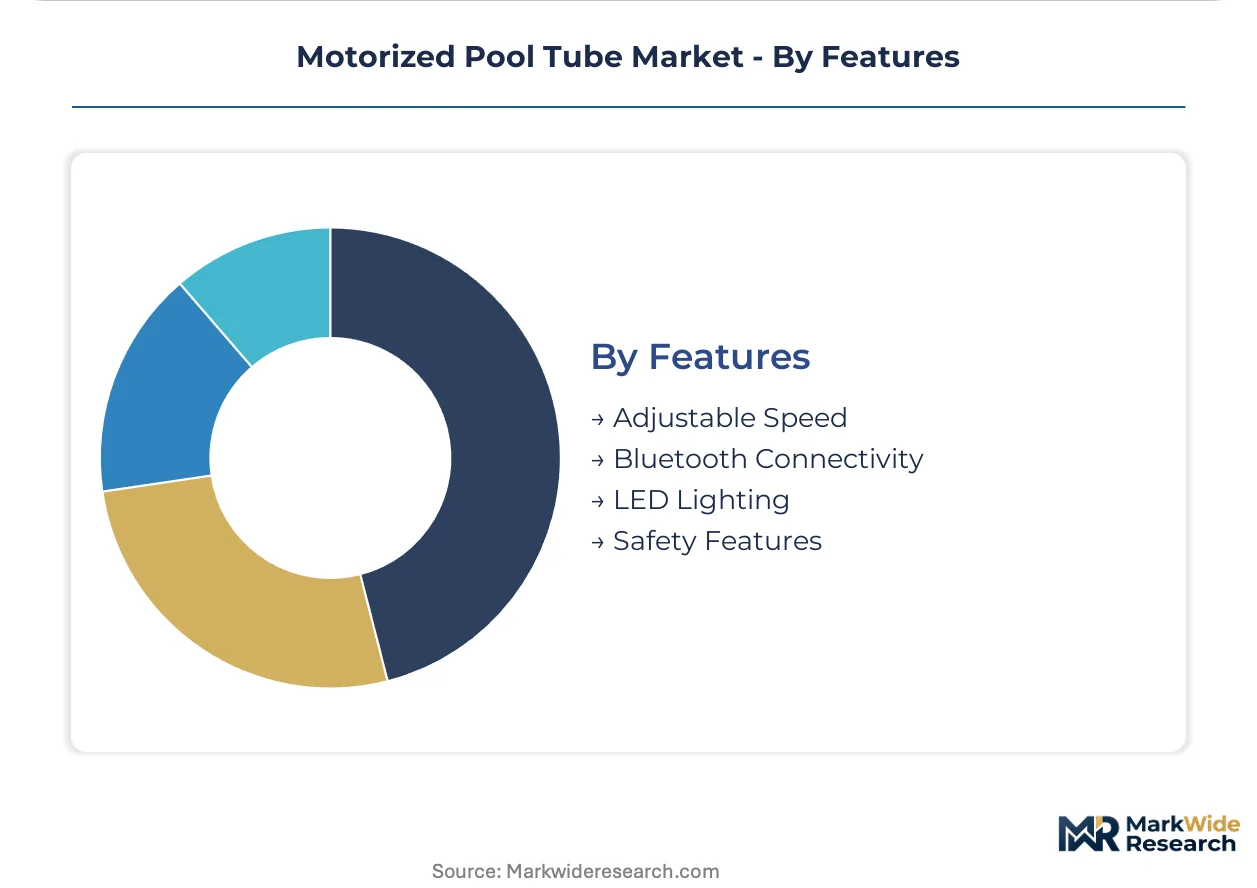
Features:
Customer type expectations around connectivity and experiential enhancement are reshaping baseline feature requirements.
- Adjustable Speed:Variable motor output controlled through physical interfaces or smartphone applications. Gesture-based adjustment is becoming baseline expectation among residential buyers.
- Bluetooth Connectivity:Low-energy protocols enabling firmware updates and GPS-enabled pool perimeter mapping. This virtualization of control interfaces is displacing physical tethered remotes.
- LED Lighting:Integrated illumination systems requiring RoHS compliance verification for soldered circuit assemblies in hard-shell tube configurations.
- Safety Features:Automatic shutoff triggers, leak detection sensors, and child-lock speed limitations addressing CPSC submersible device standards.
Adjustable speed commands the established base. The steepest expansion runs through Bluetooth connectivity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows favor Asian manufacturing clusters supplying North American and European retail channels, with finished motorized pool tubes moving westward and lithium-ion cells flowing eastward from South Korean and Japanese suppliers.
United States
Backyard pool ownership in Texas, Florida, and Arizona metropolitan clusters sustains the largest national installed base. The Consumer Product Safety Commission enforces submersible electrical device standards dictating insulation ratings and cord-guard specifications. Dallas-Fort Worth and Houston contractors are capturing share from mass-market retail through direct-to-consumer premium configurations.
China
Guangdong and Zhejiang provinces concentrate radio-frequency welding equipment and specialized seam-sealing technician pools for inflatable tube production. The Ministry of Ecology and Environment oversees chemical substance restrictions affecting phthalate-free PVC formulation requirements. Shenzhen manufacturers are integrating smartphone app connectivity as baseline export specifications for North American-bound shipments.
Germany
REACH substance restrictions and EU Green Deal circularity requirements extend through multinational retailer procurement standards affecting polymer supply chain documentation. The Federal Environment Agency monitors chemical compliance across imported recreational products. Bavarian specialty distributors are prioritizing hard-shell configurations with integrated LED lighting for commercial pool operator contracts.
Australia
Seasonal climate patterns and winterization requirements concentrate demand in Queensland and New South Wales residential markets. The Therapeutic Goods Administration framework does not directly govern pool equipment, leaving state-level electrical safety regulators to enforce submersible device standards. Melbourne and Sydney direct-to-consumer platforms are fragmenting traditional retail channel dominance for premium-tier units.
Japan
Compact residential pool formats in Tokyo and Osaka metropolitan areas favor collapsible inflatable storage solutions. The Ministry of Economy, Trade and Industry oversees battery safety certifications affecting lithium-ion enclosure imports. Nagoya-based industrial fabricators are supplying reinforced thermoplastic polymer materials to regional tube assemblers across East Asian supply chains.
Motorized Pool Tube Market Competitive Landscape
On the supply side, the industry is tiered between mass-manufacturing scale operators, material-integrated specialists, and connectivity-focused differentiators. Three strategic archetypes dominate: Asian-based volume fabricators with captive production economics, vertically integrated material suppliers controlling PVC and drop-stitch supply, and firmware-enabled specialists capturing software-margin extensions. Competitive moves concentrate on backward integration into material supply and strategic partnerships for saltwater-tolerant component sourcing.
Within the mass-manufacturing archetype, INTEX Recreation Corp and Bestway Inflatables & Material Corp exemplify scale-driven positioning through Asian production base concentration. Poolside Tech occupies a differentiated tier representing app-connected control interface specialization. These three anchors illustrate the strategic divergence between cost leadership through manufacturing scale and premium positioning through proprietary technology integration.
| Leading Market Players |
|---|
| INTEX Recreation Corp |
| Bestway Inflatables & Material Corp |
| Swimline |
| FUNBOY |
| Poolmaster |
| Poolside Tech |
| PoolCandy |
| Arshiner |
| Airhead Sports |
| Others |
Supply & Pricing Matrix
Guangdong and Zhejiang province manufacturing clusters for radio-frequency welding equipment concentrate inflatable tube production economics, pushing margin capture downstream toward firmware-enabled specialists with proprietary motor housing designs. Battery-grade lithium carbonate sourcing volatility and phthalate-free PVC certification costs further compress assemblers lacking long-term supplier contracts or backward-integrated material supply.
Pricing Analysis
Residential backyard pool owners anchor a three-tier pricing structure across premium, standard, and economy levels, with saltwater-tolerant motor housings and app-connected speed interfaces commanding substantial premiums over entry-level units. Price differentiation rests on IPX8 waterproofing certification tier and Bluetooth connectivity integration, while lithium-ion cell cost volatility is intensifying margin pressure in the mid-tier assembler segment. Seasonal climate buyers in the Northeastern United States exhibit highest price sensitivity due to compressed utilization windows, whereas Florida and Arizona metropolitan clusters show lowest sensitivity for durability-warrantied hard-shell configurations.
Supply Chain Analysis
Drop-stitch thermoplastic polymers and battery-grade lithium-ion cells feed from Chinese, South Korean, and Japanese upstream suppliers into Guangdong assembly operations. Raw material dependencies center on PVC resin formulations, reinforced seam adhesives, and sealed motor housing alloys. Single-source vulnerability concentrates in radio-frequency welding technician pools aging across Zhejiang manufacturing clusters. Distribution runs through mass-market retail channels for inflatable units while specialty pool contractors and direct-to-consumer platforms capture premium hard-shell volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart home leisure integration represents an early-cycle expansion story, with residential buyers embedding motorized pool tubes into connected backyard ecosystems at accelerating replacement rates for legacy manual flotation devices.
For Market Incumbents: Harden proprietary motor housing designs against saltwater corrosion to defend margin positions as waterproof lithium-ion miniaturization erodes power-based differentiation. Secure backward integration into phthalate-free PVC supply chains to preempt California Proposition 65 compliance cost shocks. Channel control through specialty pool contractor relationships in Texas and Florida metropolitan clusters offers defensive positioning against direct-to-consumer entrants.
For New Entrants and Emerging Players: Build out firmware-updatable control interfaces targeting the residential smart home integration segment, where app-connected speed adjustment and GPS-enabled pool perimeter mapping remain underpenetrated relative to commercial pool operator markets. Solar-assisted hybrid configurations for sun-belt state commercial operators offer a discrete white-space entry point. A go-to-market angle through direct-to-consumer platforms bypasses mass-market retail shelf access barriers.
For Investors and Strategic Acquirers: Capital is best deployed toward connectivity-focused specialists with captive firmware development capabilities and saltwater-tolerant component sourcing partnerships, as software-margin extensions represent durable value capture over the projection horizon. Acquisition target archetypes include mid-tier assemblers with certified phthalate-free material libraries but lacking proprietary technology integration. The signal to watch is CPSC submersible electrical device standard revision timelines, which would accelerate compliance-driven consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phthalate-Free PVC Supply | California Proposition 65 compliance creates first-mover shelf access advantages for certified manufacturers. |
| Saltwater-Tolerant Motor Housing R&D Investment | Corrosion-resistant designs address the fastest-growing residential pool chemistry segment in coastal markets. |
| Direct-to-Consumer Platform Launch | Specialty pool contractors in Texas and Florida are fragmenting traditional mass-market retail channel dominance. |
| Solar-Assisted Hybrid Configuration Pilot | Commercial operators in Arizona and Florida metropolitan clusters are testing photovoltaic-integrated daytime utilization models. |
| Smartphone App Connectivity Baseline Integration | Gesture-based speed adjustment and GPS pool mapping are becoming baseline residential buyer expectations. |
Research Methodology
Desk research of customs trade records, CPSC submersible device standard filings, and pool equipment distributor catalogs preceded structured interviews with inflatable tube plant managers, specialty pool contractor procurement leads, lithium-ion battery enclosure engineers, and mass-market retail category buyers. Secondary validation drew from EPA phthalate restriction guidance documents, REACH substance restriction databases, and SEC 10-K disclosures from recreational product manufacturers. Bottom-up unit shipment estimates triangulated against top-down consumer expenditure patterns across the analysis window.
Assumptions held fixed include CPSC insulation rating continuity, lithium-ion cell cost volatility within observed bands, and smart home leisure integration penetration curves; variables tested included solar-assisted hybrid adoption rates and saltwater pool chemistry migration speed. Segmentation dimensions modeled encompass construction method, end-user environment, power architecture, and connectivity feature tier. CAGRs derived from logistic adoption curve fitting against replacement cycle data and experiential recreation expenditure elasticity estimates.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by Asian mass-manufacturers or regulatory acceleration by the EPA would shift outcomes. Waterproofing certification timeline extensions or radio-frequency welding equipment supply disruptions represent specific revision risks. Cross-checking against pool renovation permit data and consumer durable goods expenditure indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Parasailing Equipment Market
Outdoor and Adventure Activities
Rafting Equipment Market
Outdoor and Adventure Activities
Global Climbing Holds Market
Outdoor and Adventure Activities
Global Personal Watercraft Market
Outdoor and Adventure Activities
Global Water Bikes Market
Outdoor and Adventure Activities
Fishing Waders Market
Outdoor and Adventure Activities
Global Inflatable Outdoor Leisure Product Market
Outdoor and Adventure Activities
Mountain Bike Market
Outdoor and Adventure Activities
Recreation Services Market
Outdoor and Adventure Activities
North America Spectator Sports Market
Outdoor and Adventure Activities
Hiking Accessories Market
Outdoor and Adventure Activities
Fat Bike Market
Outdoor and Adventure Activities
Spain Artificial Turf Market
Outdoor and Adventure Activities
United States and Europe Horse Racing Market
Outdoor and Adventure Activities
Spain Sports Tourism Market
Outdoor and Adventure Activities
Kitesurf Kites Market