
 Trekking Poles Market | 2026-2036
Trekking Poles Market Size, Share, and Industry Trends Forecast 2026-2036
Trekking Poles Market Analysis
REACH is recalibrating the cost-of-entry calculus for trekking pole manufacturers selling into European markets. Komperdell leverages its Austrian manufacturing base to sustain compliance with evolving chemical substance restrictions. Black Diamond anchors its competitive position through R&D intensity in carbon fiber layup techniques. Leki dominates the European retail channel through direct partnerships with alpine outfitters.
Trekking poles are collapsible or fixed-length shaft assemblies, typically 100-135 cm in length, constructed from aluminum alloys or carbon fiber composites, designed to transfer upper-body load to terrain during ascents and descents. Folding poles lead the product type segment due to packability advantages on technical routes, while carbon fiber commands the material category on margin strength. Ultra-light weight capacity tiers attract the fastest-growing user base among thru-hikers on long-distance trails.
EMA and ECHA frameworks govern chemical exposure limits in grip compounds and strap textiles sold across EU member states, while ISO 11199 standards inform load-bearing specifications for assistive walking devices that overlap with trekking pole engineering. The EU Green Deal extends material traceability requirements to composite supply chains. Stakeholders must monitor how evolving extended producer responsibility rules reshape sourcing economics for carbon fiber and aluminum components.
Market Dynamics
The EU Green Deal is forcing a wholesale recalibration of material sourcing economics across trekking pole supply chains, with carbon fiber traceability requirements and extended producer responsibility rules now embedded in procurement decisions.
Growth Catalysts
- Alpine Trail Expansion:The European Alps are witnessing sustained investment in maintained hiking networks, with Germany's Deutscher Alpenverein driving organized membership growth that converts directly to equipment turnover.
- REACH Compliance Maturation:Chemical substance restrictions on grip compounds and strap textiles have stabilized, allowing compliant Austrian and German manufacturers to capture shelf space from non-compliant imports.
- Carbon Fiber Layup Advances:R&D intensity in composite manufacturing is yielding sub-200-gram pole assemblies that retain torsional rigidity for technical descents.
Market Restraints
- Aluminum Alloy Volatility:Input cost swings for 7075-series aluminum extrusions compress margin predictability for mid-tier producers dependent on metal shafts.
- Carbon Fiber Supply Concentration:Precursor manufacturing clusters in Japan and select Chinese provinces create geographic chokepoints for European assemblers seeking ISO 11199-certified composite tubes.
- Fixed-Length Substitution:Traditional single-piece poles retain price advantage in entry-level retail, constraining folding mechanism adoption in budget-conscious segments.
Strategic Opportunities
- Thru-Hiker Equipment Cycles:Long-distance trail completion rates on routes like the Pacific Crest Trail are generating replacement demand cycles measured in single seasons rather than years.
- CSRD Reporting Integration:Corporate sustainability disclosure mandates are creating procurement preference for manufacturers with documented composite supply chain traceability.
- Direct-to-Consumer Channels:Alpine outfitter partnerships are being supplemented by brand-owned digital platforms that capture margin previously allocated to retail intermediaries.
Industry Challenges
- Composite Technician Scarcity:Carbon fiber layup expertise resides in aerospace and cycling industry talent pools, forcing pole manufacturers to compete for skilled laminators.
- Certification Timeline Compression:EMA and ECHA framework updates require iterative grip compound reformulation, extending product development cycles.
- Legacy Aluminum Forging Integration:Established press houses struggle to retool for hybrid metal-composite assemblies without capital-intensive facility reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trekking Poles Market |
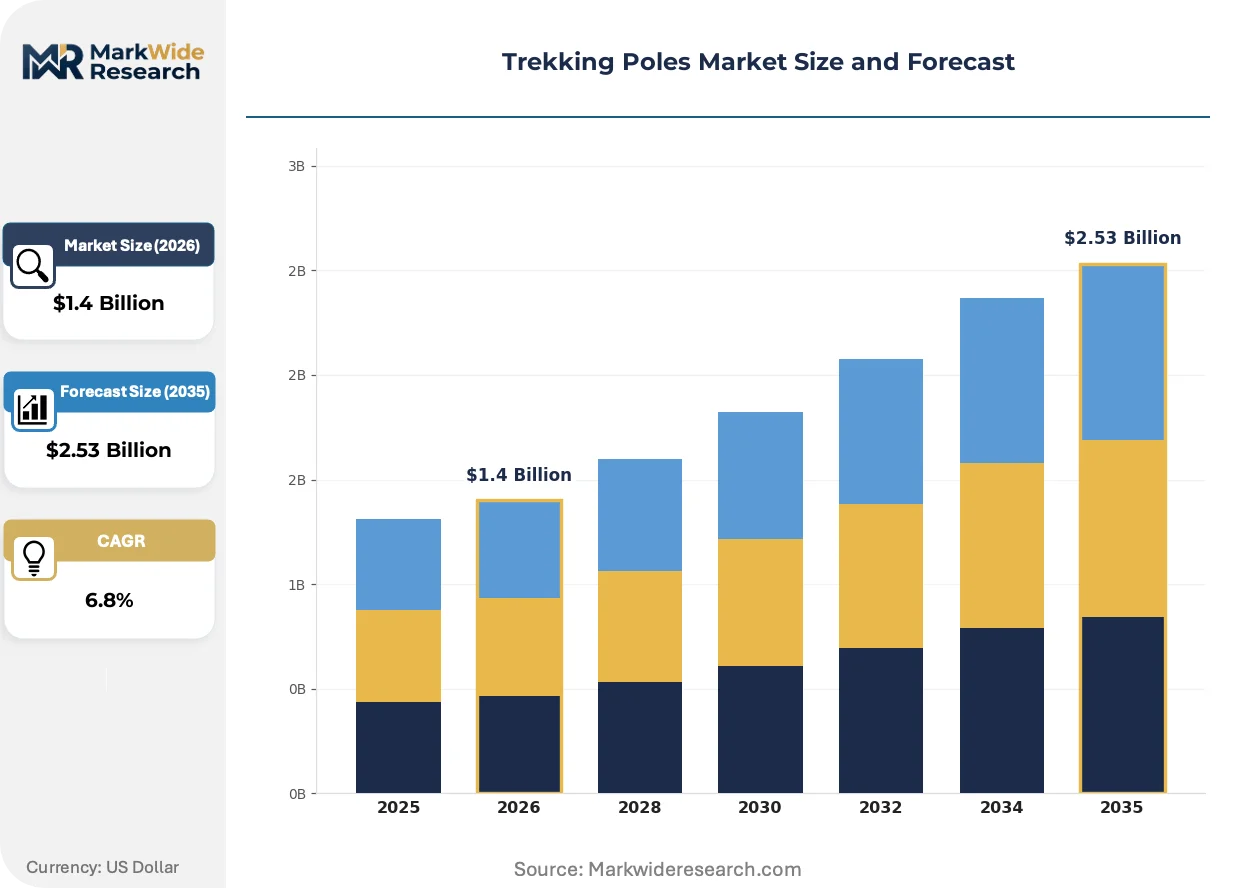
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding Poles, Telescoping Poles, Fixed-Length Poles, Shock-Absorbing Poles Material: Aluminum, Carbon Fiber, Steel, Composite End User: Outdoor Enthusiasts, Hikers, Campers, Backpackers Weight Capacity: Lightweight, Standard, Heavy-Duty, Ultra-Light |
| Companies Covered | REI Co-op, Montem Outdoor Gear, Black Diamond, Komperdell, Durston, Leki, Gossamer Gear, Trekology, MSR (Mountain Safety Research), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trekking Poles Market Emerging Trajectories
Material science convergence with regulatory traceability mandates is restructuring how trekking poles are engineered, certified, and brought to market across European distribution channels.
Carbon fiber prepreg systems is expanding into the ultra-lightweight segment as thru-hikers on alpine routes adopt sub-180-gram pole configurations for multi-week expeditions. Manufacturers are compressing traditional three-section designs into five-segment folding architectures that maintain lock integrity under torsional load.
REACH substance restriction schedules are accelerating reformulation timelines for EVA grip compounds and nylon strap textiles sold across EU member states. ECHA candidate list updates now capture phthalate alternatives previously considered safe replacements, forcing Austrian and German assemblers to maintain dual-qualified material inventories.
Buyer concentration among organized alpine clubs is displacing dispersed individual purchasing patterns in core European markets. The Deutscher Alpenverein negotiates volume procurement agreements that bundle pole purchases with membership services, compressing traditional retail margin structures in Germany and adjacent Alpine regions.
Trekking Poles Market Segmentation
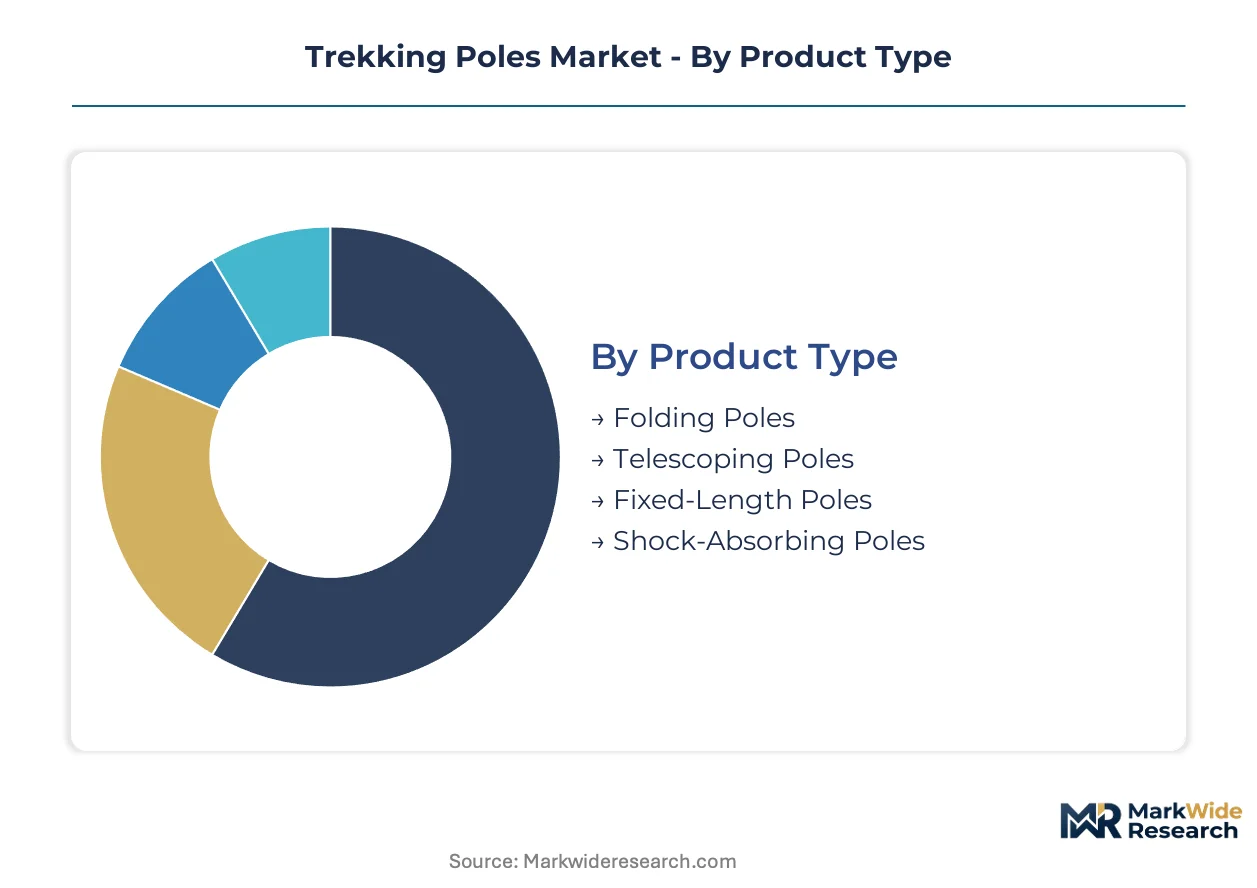
Trekking pole segmentation reveals divergent compliance burdens across product architectures. ISO 11199 load-bearing specifications apply differentially to assistive-device-adjacent categories, while REACH chemical restrictions grip compound and textile formulations unevenly by material type and end-use intensity.
Product Type:
Folding and telescoping mechanisms trigger distinct certification pathways under EMA mechanical safety frameworks, whereas fixed-length designs face lighter regulatory scrutiny.
- Folding Poles:Five-segment collapsible architectures with internal cord tension systems and push-button locking mechanisms. Demand clusters among thru-hikers on alpine routes where packability determines equipment selection, driven by multi-week expedition logistics requiring minimal base weight.
- Telescoping Poles:Two- or three-section twist-lock or lever-lock designs allowing 20-30 cm length adjustment ranges. German alpine outfitters stock these as default recommendations for Deutscher Alpenverein members seeking versatile trail-to-summit configurations, constrained by lock mechanism wear under freeze-thaw cycles.
- Fixed-Length Poles:Single-piece aluminum or carbon fiber shafts with bonded grip assemblies.
- Shock-Absorbing Poles:Internal spring or elastomer dampening systems reducing wrist impact on descents.
Leading the category by volume: Telescoping Poles. Growing fastest: Folding Poles.
Material:
Raw material selection stratifies manufacturing cost structures and supply chain traceability obligations under EU Green Deal extended producer responsibility rules.
- Carbon Fiber:Pre-impregnated composite layups yielding sub-200-gram pole assemblies with high torsional rigidity. Austrian manufacturers leverage domestic aerospace industry talent pools for lamination expertise, climbing fastest among thru-hiker segments prioritizing gram reduction over replacement cost.
- Aluminum:7075-series aircraft-grade extrusions with T6 tempering for strength-to-weight optimization. German and Austrian forging houses dominate European supply, facing margin pressure from volatile alloy input costs and energy-intensive anodizing processes.
- Steel:Chromoly or stainless shafts for heavy-duty applications.
- Composite:Hybrid fiber-reinforced polymer systems blending glass and carbon.
Carbon Fiber commands premium shelf positioning. Aluminum retains volume leadership across mass retail.
End User:
User category intensity determines grip compound exposure thresholds under ECHA candidate list monitoring and strap textile durability specifications.
- Backpackers:Multi-day wilderness travelers requiring collapsible poles with lock integrity under variable pack loads. Alpine club procurement agreements in Germany bundle these purchases with membership services, displacing individual retail transactions.
- Hikers:Day-trip and maintained-trail users representing the broadest addressable base.
- Outdoor Enthusiasts:Generalist recreational users spanning multiple activity types.
- Campers:Base-camp oriented users with lower mobility demands.
Backpackers drive replacement velocity. Hikers anchor baseline production planning.
Weight Capacity:
Load tier segmentation aligns with ISO 11199 assistive device overlap specifications and carbon fiber grade selection in composite engineering.
- Ultra-Light:Sub-180-gram configurations using high-modulus carbon fiber prepreg with minimal wall thickness. Pacific Crest Trail completion rates generate single-season replacement cycles, compressing traditional multi-year equipment lifespans.
- Lightweight:180-250-gram poles balancing durability and mass reduction.
- Standard:250-350-gram aluminum or entry carbon fiber for general trail use.
- Heavy-Duty:Reinforced shafts and extended grip zones for high-load or assistive applications.
Ultra-Light posts steepest expansion trajectory. Standard tier retains manufacturing scale advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Alpine Arc special economic zone spanning Austria, Switzerland, and northern Italy concentrates European trekking pole manufacturing through preferential tariff treatment and carbon fiber precursor access corridors.
Germany
The Deutscher Alpenverein maintains Europe's largest organized hiking membership base, converting directly to equipment turnover through bundled procurement agreements. REACH compliance maturation has stabilized chemical substance restrictions, allowing domestic assemblers to capture shelf space from non-compliant imports. Bavarian alpine outfitters in Garmisch-Partenkirchen anchor retail distribution networks serving the Austrian and Swiss border regions.
Austria
Domestic aerospace industry talent pools supply carbon fiber lamination expertise for ultra-lightweight pole configurations. The country's national materials regulator enforces ECHA candidate list monitoring for grip compound formulations. Vienna-based manufacturing clusters specialize in hybrid metal-composite assemblies, leveraging proximity to Italian carbon fiber precursor distributors.
Switzerland
Technical mountaineering culture drives premium-tier demand for sub-180-gram pole assemblies with torsional rigidity specifications. Swissmedic-adjacent mechanical safety frameworks inform product certification for assistive-device-adjacent categories. Zurich and Lucerne host specialized alpine equipment retailers that influence purchasing decisions across the German-speaking market.
United States
Pacific Crest Trail completion rates generate single-season replacement cycles among thru-hikers, compressing traditional multi-year equipment lifespans. The EPA oversees chemical exposure thresholds in grip compounds imported for domestic assembly. Seattle and Portland outdoor equipment clusters concentrate direct-to-consumer brand development and long-distance trail advocacy organizations.
Japan
METI industrial standards for carbon fiber grade classification inform procurement decisions by domestic alpine equipment distributors. Precursor manufacturing clusters in select prefectures create geographic chokepoints for European assemblers seeking ISO 11199-certified composite tubes. Nagoya-area technical textile producers supply strap materials meeting ECHA-equivalent substance restrictions for re-export markets.
Trekking Poles Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base stratifies between premium carbon fiber innovators, mid-tier aluminum forging houses, and entry-level fixed-length producers. Three archetypes dominate: Austrian-German integrated manufacturers with captive composite supply, American direct-to-consumer digital natives, and Asian contract assemblers serving private-label retailers. Capacity expansion in carbon fiber layup facilities and strategic partnerships with alpine club procurement programs constitute the dominant competitive moves reshaping channel access.
Within the integrated manufacturing tier, Komperdell and Leki exemplify archetypes combining domestic production with alpine club distribution relationships. Black Diamond anchors American premium-tier positioning through R&D intensity in composite engineering. Montem Outdoor Gear represents the specialist fabricator segment focused on ultra-lightweight configurations for thru-hiker demographics.
| Leading Market Players |
|---|
| REI Co-op |
| Montem Outdoor Gear |
| Black Diamond |
| Komperdell |
| Durston |
| Leki |
| Gossamer Gear |
| Trekology |
| MSR (Mountain Safety Research) |
| Others |
Supply Flow & Price Mechanics
Carbon fiber precursor costs originating in Japanese and select Chinese manufacturing clusters cascade through three distinct pricing tiers before reaching end-users, with EU Green Deal traceability mandates adding compliance premiums that widen spreads between documented and undocumented supply streams.
Pricing Analysis
Short lead-time premiums of 15-25 percent attach to carbon fiber pole assemblies sourced from Austrian manufacturers with REACH-qualified material inventories, while spot inventory from non-compliant Asian contract assemblers trades at discounts that compress traditional retail margin structures. Three-tier pricing structure across premium, standard, and economy levels separates ISO 11199-certified carbon fiber configurations from aluminum shaft alternatives and fixed-length entry products. Pricing pressure stems from volatile 7075-series aluminum alloy input costs that force mid-tier German forging houses to absorb margin erosion or surrender shelf space. Backpackers purchasing through Deutscher Alpenverein bundled procurement agreements exhibit lowest price sensitivity, while dispersed individual hikers in mass retail channels drive hardest bargain hunting.
Supply Chain Analysis
Freight cost differentials between air-shipped carbon fiber precursors from Japan and sea-freight aluminum extrusions from German forging houses distort landed cost calculations for European assemblers competing on gram-reduction specifications. Geographic supply concentration centers on Austria, Germany, and northern Italy for final assembly, with carbon fiber precursor manufacturing clustered in Japan and select Chinese provinces creating single-source vulnerability for ISO 11199-certified composite tubes. Raw material dependencies rest on acrylonitrile precursor feedstocks, 7075-series aluminum billets, and ECHA-compliant EVA grip compounds. Distribution runs through alpine outfitter partnerships in Bavaria and direct-to-consumer digital platforms capturing margin previously allocated to retail intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The trekking poles market functions as a cost-of-compliance story where REACH substance restriction schedules and EU Green Deal extended producer responsibility rules erect barrier-to-entry moats favoring incumbent Austrian and German manufacturers with documented supply chain traceability.
For Market Incumbents: Deploy alpine club procurement program expansion as the primary lever to lock in volume commitments from Deutscher Alpenverein and adjacent organized membership bases, insulating against direct-to-consumer digital native entrants. Deepen backward integration into carbon fiber layup capabilities by recruiting aerospace industry laminators from Vienna-area talent pools, countering composite technician scarcity that constrains ultra-lightweight production scaling. Maintain dual-qualified material inventories to absorb iterative ECHA candidate list updates without product development cycle compression. For New Entrants and Emerging Players: Sub-180-gram carbon fiber configurations for Pacific Crest Trail thru-hikers represent the most penetrable white-space target, as single-season replacement cycles generate volume velocity independent of alpine club distribution control. Direct-to-consumer digital platforms with trail-advocate content marketing bypass entrenched outfitter relationships that incumbent Austrian manufacturers dominate. Target warranty-forward positioning that converts equipment failure risk into subscription-style replacement revenue, differentiating from transactional retail models. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier aluminum forging houses in southern Germany with press house infrastructure adaptable to hybrid metal-composite assemblies, as energy-intensive anodizing cost spikes force consolidation among undifferentiated metal-shaft producers. Long-term viability across the projection horizon hinges on CSRD reporting integration capabilities that secure procurement preference from sustainability-mandated buyers. Watch carbon fiber precursor price stabilization in Japanese manufacturing clusters as the inflection signal for margin recovery in composite-dependent assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Fiber Layup Facility Expansion | Austrian manufacturers leverage domestic aerospace talent pools to capture thru-hiker demand for sub-180-gram configurations. |
| REACH Compliance Certification Investment | German assemblers secure shelf space from non-compliant imports as ECHA substance restrictions tighten. |
| Alpine Club Procurement Partnership | Deutscher Alpenverein bundled agreements displace traditional retail margin structures in core European markets. |
| Direct-to-Consumer Platform Launch | Brand-owned digital channels capture margin previously allocated to Bavarian outfitter intermediaries. |
| Hybrid Metal-Composite Assembly Development | Vienna-based clusters integrate aluminum forging with carbon fiber lamination for versatile trail-to-summit configurations. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with carbon fiber procurement managers at Austrian manufacturing clusters, alpine outfitter buyers in Bavaria, composite engineering leads from aerospace talent pools, and ECHA regulatory affairs specialists. Bottom-up assembly of production volumes by shaft material and product architecture was cross-validated against top-down expenditure estimates from Deutscher Alpenverein membership surveys and Pacific Crest Trail completion databases.
Data-stream reconciliation between import manifests for Japanese carbon fiber precursors and domestic European forging output established baseline supply assumptions across the projection horizon. Segmentation modeling incorporated product type, material grade, end-user intensity, and weight capacity tier as discrete dimensions. CAGRs were derived from trend extrapolation of alpine trail network investment flows and replacement cycle compression observed among thru-hiker demographics. Forecast inputs included REACH substance restriction timelines and EU Green Deal extended producer responsibility implementation phases.
Forecast precision tightens around the base case; tail outcomes carry wider variance under carbon fiber precursor supply disruptions or accelerated ECHA candidate list expansions capturing phthalate alternatives. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Skiing Equipment Market
Outdoor and Adventure Activities
Global Ski Poles Market
Outdoor and Adventure Activities
Global Climbing Holds Market
Outdoor and Adventure Activities
Hiking Gear and Equipment Market
Outdoor and Adventure Activities
Recreation Services Market
Outdoor and Adventure Activities
Hunting Rangefinder Market
Outdoor and Adventure Activities
Wakeboard Market
Outdoor and Adventure Activities
Adventure Gear Market
Outdoor and Adventure Activities
Outdoor Backpack Market
Outdoor and Adventure Activities
Fat Bike Market
Outdoor and Adventure Activities
Fishing Waders Market
Outdoor and Adventure Activities
Climbing Harness Market
Outdoor and Adventure Activities
Spain Artificial Turf Market
Outdoor and Adventure Activities
Speed Chute Market
Outdoor and Adventure Activities
Global Inflatable Outdoor Leisure Product Market
Outdoor and Adventure Activities
Kayak Market