
 Asia Pacific Sports Team and Clubs Market | 2026-2036
Asia Pacific Sports Team and Clubs Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Sports Team and Clubs Market Insights
Australia's stadium infrastructure modernization is reshaping revenue architecture across the Asia Pacific sports ecosystem. Mumbai Indians leverages its IPL brand equity to sustain merchandise volume across South Asian diaspora markets. Melbourne City FC anchors City Football Group's regional network through youth academy pipelines and A-League commercial rights. Chennai Super Kings dominates southern India's cricket economy through membership loyalty programs and regional sponsorship lock-ins.
Asia Pacific sports teams and clubs comprise organized competitive entities ranging from professional franchises to amateur associations, governed by league licensing systems, player salary frameworks, and broadcast distribution protocols that monetize athletic performance through ticketed events, media rights, and brand licensing. The sector's primary commercial purpose centers on aggregating fan attention into repeatable revenue streams across live and digital channels. Revenue stream segmentation reveals broadcasting rights capturing the dominant margin pool as streaming platforms bid for exclusive territory licenses, while sponsorship revenue accelerates fastest through embedded branding in esports crossover properties. Organization type segmentation shows professional teams consolidating operational control as youth academies feed talent pipelines under franchise-owned structures.
Australia's Therapeutic Goods Administration and Sports Integrity Australia frameworks govern athlete health protocols and betting integrity standards that shape club operational compliance costs. Japan's Consumer Affairs Agency and J.League licensing rules regulate merchandise authenticity and foreign player quotas that determine roster construction economics. India's BIS certification requirements and state-level entertainment tax structures influence stadium development timelines and pricing accessibility. Stakeholders must monitor how fragmented national regulatory regimes interact with cross-border digital broadcast licensing to preserve revenue portability.
Market Dynamics
Broadcasting rights fragmentation across streaming platforms is compressing revenue predictability for Asia Pacific sports franchises while simultaneously expanding total addressable fan bases through direct-to-consumer channels. India's IPL media auction cycles and Japan's J.League streaming partnerships exemplify this structural tension between reach expansion and pricing volatility.
Growth Catalysts
- India's PLI scheme for sports infrastructure:Central government production-linked incentives accelerate stadium construction timelines and reduce capital deployment risk for private franchise operators seeking permanent venue assets.
- Esports crossover licensing:Traditional cricket and football clubs monetize brand equity through gaming partnerships, capturing younger demographics via mobile-first engagement platforms and in-game cosmetic sales.
- Southeast Asian sports tourism corridors:Thailand, Vietnam, and Indonesia develop integrated hospitality-entertainment zones around major sporting venues, extending match-day revenue into multi-day visitor spending.
Market Restraints
- Foreign player quota rigidities:J.League and A-League roster restrictions limit talent pool access and inflate domestic player salary premiums beyond sustainable wage-to-revenue ratios.
- Stadium construction cost escalation:Steel and specialized seating system input costs in Australia have risen substantially, stretching public-private partnership return timelines.
- State-level entertainment tax fragmentation:India's varying entertainment duty structures across Maharashtra, Tamil Nadu, and Karnataka create pricing arbitrage complexity and venue selection distortions.
Strategic Opportunities
- Tier-II Indian city franchise expansion:Indore, Lucknow, and Guwahati present underpenetrated cricket markets with stadium-ready infrastructure and corporate sponsorship liquidity.
- Women's league property development:Australia's AFLW and India's WPL demonstrate scalable broadcast appetite for women's competitions with lower rights acquisition costs and faster sponsor conversion cycles.
- Biometric fan authentication systems:Convergence of facial recognition and mobile wallet technology enables frictionless stadium entry and personalized concession commerce.
Industry Challenges
- Multi-jurisdiction betting integrity compliance:Sports Integrity Australia frameworks and emerging Indian state gambling regulations impose divergent monitoring and reporting obligations on clubs with cross-border digital audiences.
- Legacy stadium technology retrofitting:5G infrastructure deployment and cashless payment system integration require substantial capital outlay at venues built before 2010 without structural provisions for fiber density.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Sports Team and Clubs Market |
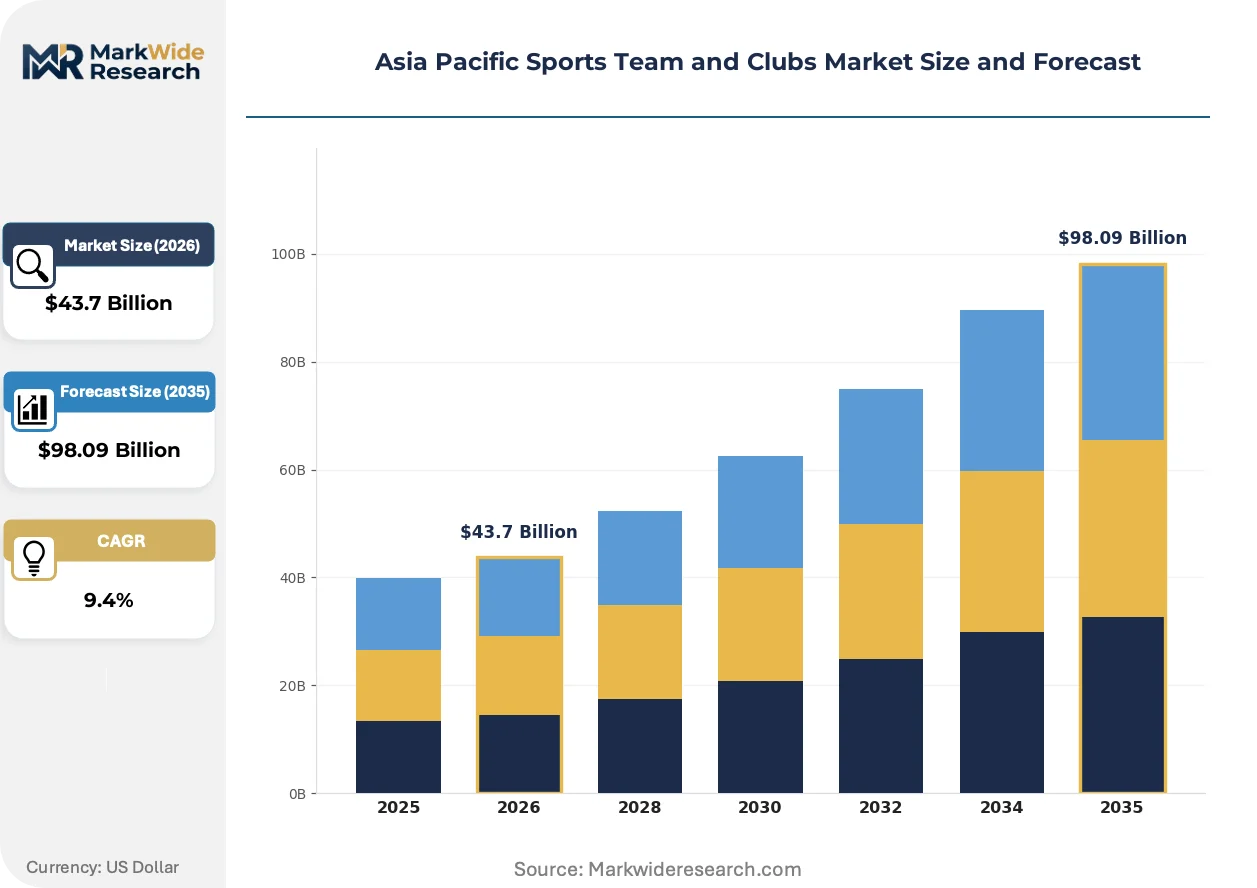
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $98.09 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Organization Type: Professional Teams, Amateur Clubs, Youth Academies, Non-Profit Organizations Revenue Stream: Ticket Sales, Merchandise, Sponsorships, Broadcasting Rights Membership Model: Full Member, Associate Member, Corporate Member, Lifetime Member Customer Type: Fans, Sponsors, Media Partners, Players |
| Companies Covered | Chennai Super Kings, Mumbai Indians, Melbourne City FC, Kawasaki Racing Team, Sri Lanka Cricket, The Raintree Club, The Johor Southern Tigers, Lion City Sailors, Vissel Kobe, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Sports Team and Clubs Market Trends and Innovations
Digital-native fan engagement architectures are supplanting traditional membership models across Asia Pacific sports franchises, compressing the distance between content consumption and commercial transaction. This transformation privileges platforms that integrate viewing, wagering, and merchandise within unified mobile experiences.
AI-powered player performance analytics is collapsing the information asymmetry between franchise front offices and broadcast commentators, enabling real-time predictive insights during live matches. IPL and Big Bash League franchises deploy these tools for in-game strategy adjustments and fantasy sports integration. The compression of decision-cycle latency is reshaping coaching staff composition and data science hiring priorities.
Japan's Consumer Affairs Agency has tightened merchandise authenticity certification requirements for officially licensed club products, elevating compliance costs for apparel suppliers while protecting brand equity against counterfeit penetration. J.League clubs now face mandatory supply chain documentation for all fan merchandise categories. Smaller market franchises in regional prefectures disproportionately bear the administrative burden relative to their revenue base.
Fan purchasing behavior has rotated toward experience-anchored spending over physical merchandise accumulation, particularly among urban millennials in Singapore and Sydney. Stadium hospitality packages and post-match player access events capture wallet share previously directed at replica kits. This shift pressures traditional retail licensing partners to develop service-layer revenue streams alongside product sales.
Asia Pacific Sports Team and Clubs Market Segmentation
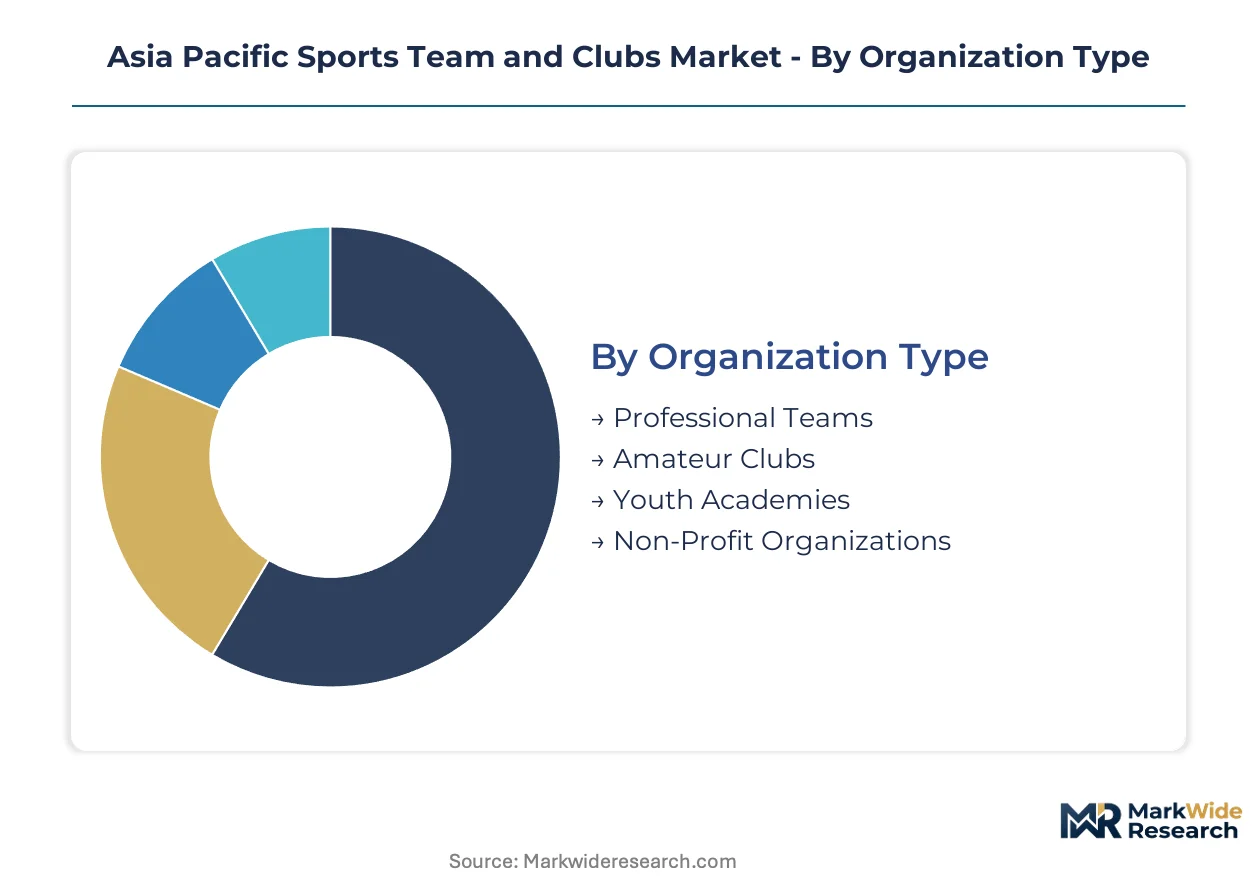
Asia Pacific sports franchises deploy distinct organizational architectures and revenue architectures to capture fan attention across heterogeneous market maturity levels. Segmentation reveals how IPL cricket franchises, J.League football clubs, and Australian A-League operators optimize membership structures and commercial partnerships against divergent regulatory and infrastructure backdrops.
Organization Type:
Cost tier determines capital intensity and governance complexity across the Asia Pacific sports ecosystem, separating asset-heavy professional operations from community-anchored amateur structures.
- Professional Teams:Franchise-owned entities operating under league licensing systems with player salary caps, stadium assets, and broadcast revenue sharing. Mumbai Indians and Chennai Super Kings anchor India's cricket economy through corporate ownership structures that monetize brand equity across merchandise and digital channels. These operations concentrate revenue in Maharashtra and Tamil Nadu where corporate sponsorship liquidity supports premium roster construction.
- Amateur Clubs:Community-based competitive entities relying on volunteer management and local facility access without professional player contracts. Demand clusters in Australia's suburban football networks and Japan's prefectural baseball leagues where participation fees and municipal subsidies sustain operations.
- Youth Academies:Talent development pipelines feeding professional rosters through age-graded coaching infrastructure and scholarship systems. Melbourne City FC's academy network exemplifies City Football Group's regional strategy for capturing emerging Australian football talent before European transfer markets.
- Non-Profit Organizations:Governance-focused entities managing sporting associations, referee development, and grassroots program administration. These structures dominate Southeast Asian markets where Thailand and Vietnam rely on federation-led infrastructure development.
Professional Teams commands the established base. The steepest expansion runs through Youth Academies.
Revenue Stream:
Application-specific monetization channels separate predictable recurring income from event-dependent and rights-volatile revenue pools.
- Broadcasting Rights:Exclusive territory licenses sold to streaming platforms and linear networks, commanding the dominant margin pool across IPL media auctions and J.League digital partnerships. India's fragmented state-level entertainment tax structures create pricing arbitrage complexity that shapes venue selection for broadcast-optimized fixtures.
- Sponsorships:Embedded brand partnerships spanning jersey branding, stadium naming rights, and esports crossover licensing. This stream accelerates fastest through mobile-first engagement platforms targeting younger demographics in Singapore and Sydney.
- Merchandise:Licensed apparel and equipment sales governed by Japan's Consumer Affairs Agency authenticity certification requirements. Compliance costs elevate for smaller J.League franchises in regional prefectures relative to their revenue base.
- Ticket Sales:Match-day admissions and season memberships, pressured by fan rotation toward experience-anchored hospitality packages over pure attendance.
Broadcasting Rights anchors current revenue concentration. Sponsorships demonstrates the fastest climb.
Membership Model:
Customer type stratification determines engagement depth and lifetime value extraction across digital-native and traditional fan architectures.
- Full Member:Premium tier with voting rights, priority ticketing, and exclusive content access. Chennai Super Kings leverages southern India's cricket economy through loyalty programs that lock in regional corporate sponsorship.
- Associate Member:Mid-tier engagement with limited voting privileges and standard ticketing priority. This segment captures urban millennials in Sydney and Melbourne rotating toward experience-anchored spending.
- Corporate Member:Business-focused packages bundling hospitality access, client entertainment, and brand association rights. Demand concentrates in India's tier-II city expansion markets where Indore and Lucknow present underpenetrated corporate liquidity.
- Lifetime Member:Capital-contribution tier with perpetual benefits and legacy recognition. Australia's stadium modernization programs attract this segment through premium seating and post-match player access events.
Full Member retains the core base. Corporate Member shows the steepest trajectory.
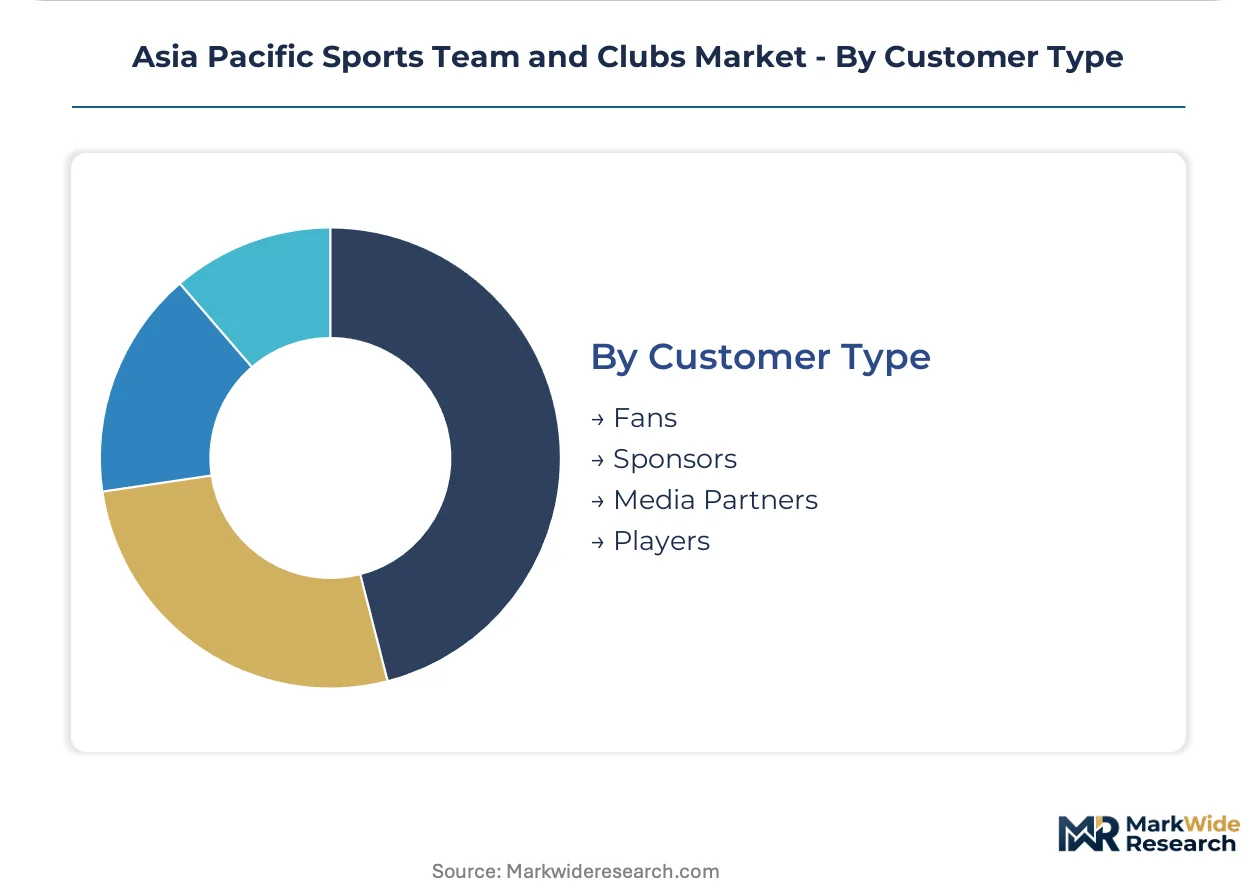
Customer Type:
Volume concentration varies across direct consumer, commercial, and intermediary channels with divergent acquisition costs and retention economics.
- Fans:Individual consumers purchasing tickets, merchandise, and digital subscriptions. AI-powered performance analytics and fantasy sports integration compress decision-cycle latency for this segment across IPL and Big Bash League properties.
- Sponsors:Corporate entities seeking brand association through jersey branding, stadium naming, and digital inventory. Australia's Sports Integrity Australia frameworks and emerging Indian state gambling regulations impose divergent compliance obligations on clubs with cross-border audiences.
- Media Partners:Broadcasters and streaming platforms acquiring exclusive territory licenses. Revenue predictability compresses as fragmentation across direct-to-consumer channels expands total addressable reach.
- Players:Talent suppliers negotiating contracts under foreign player quota rigidities that limit J.League and A-League roster flexibility and inflate domestic salary premiums.
Fans represents the volume anchor. Media Partners is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BIS certification requirements and state-level entertainment tax structures govern stadium development timelines across India, while Japan's Consumer Affairs Agency and J.League licensing rules regulate merchandise authenticity and foreign player quotas. Australia's Therapeutic Goods Administration and Sports Integrity Australia frameworks shape athlete health protocols and betting integrity standards.
India
IPL franchise expansion and cricket tourism corridors drive infrastructure investment across Maharashtra and Tamil Nadu. The PLI scheme for sports infrastructure accelerates stadium construction timelines and reduces capital deployment risk for private operators. Mumbai and Chennai anchor corporate sponsorship liquidity through membership loyalty programs and regional brand lock-ins.
Japan
J.League commercialization and professional football licensing pipelines monetize broadcast and merchandise revenue across Kanto and Kansai regions. METI standards and Consumer Affairs Agency regulations elevate compliance costs for merchandise authenticity certification. Tokyo and Osaka concentrate premium roster construction under foreign player quota frameworks that inflate domestic salary premiums.
Australia
A-League commercial rights and stadium modernization programs reshape revenue architecture across New South Wales and Victoria. Sports Integrity Australia frameworks impose betting integrity compliance costs on clubs with cross-border digital audiences. Sydney and Melbourne anchor youth academy pipelines feeding City Football Group's regional talent capture strategy.
Singapore
Lion City Sailors anchor professional football licensing and esports crossover partnerships targeting Southeast Asian fan bases. The country's national sports regulator governs athlete welfare standards and competition integrity protocols. The city-state serves as a hospitality-entertainment zone hub extending match-day revenue into multi-day visitor spending corridors.
Thailand
Sports tourism operators develop integrated hospitality zones around major venues in Bangkok and regional prefectures. Federation-led infrastructure development dominates Southeast Asian markets where municipal subsidies sustain grassroots program administration. The Johor Southern Tigers exemplify cross-border franchise expansion capturing underpenetrated corporate sponsorship liquidity.
Asia Pacific Sports Team and Clubs Market Competitive Landscape
Capability concentration sits with established IPL franchises holding brand equity and diaspora market access; scale advantage sits with multi-club ownership groups deploying standardized academy pipelines across territories. The market structures around three tiers: heritage cricket franchises with generational fan loyalty, football conglomerates with integrated data science operations, and federation-governed national bodies managing talent development infrastructure. Competitive moves center on tier-II city franchise expansion and women's league property development to capture underpenetrated broadcast appetite.
Within the heritage franchise tier, Chennai Super Kings and Mumbai Indians exemplify corporate ownership structures that monetize brand equity across merchandise and digital channels. Melbourne City FC anchors the multi-club ownership vector through City Football Group's regional network. Kawasaki Racing Team occupies a position within Japan's professional motorsport licensing pipeline, representing the specialization archetype in high-performance athletic properties.
| Leading Market Players |
|---|
| Chennai Super Kings |
| Mumbai Indians |
| Melbourne City FC |
| Kawasaki Racing Team |
| Sri Lanka Cricket |
| The Raintree Club |
| The Johor Southern Tigers |
| Lion City Sailors |
| Vissel Kobe |
| Others |
Pricing and Supply Chain Analysis
Steel and specialized seating system suppliers in China and South Korea anchor cost structures for Australian stadium modernization programs, compressing margin pools for venue operators while elevating procurement leverage for IPL franchises with permanent asset bases in India. This upstream concentration funnels pricing power toward broadcast rights holders and multi-club ownership groups with standardized infrastructure deployment across territories.
Pricing Analysis
Three-tier pricing structure across premium hospitality, standard season membership, and economy single-match tickets separates revenue extraction across India's state-level entertainment tax regimes and Japan's prefectural market tiers. Price differentiation hinges on corporate sponsorship liquidity and biometric-enabled concession integration, with premium tiers least sensitive due to locked-in hospitality contracts. Cost compression in economy ticketing is intensifying because of streaming platform fragmentation eroding match-day attendance forecasts.
Supply Chain Analysis
Australia's Sports Integrity Australia frameworks and emerging Indian state gambling regulations function as de facto export controls limiting cross-border betting technology flows and data analytics platform deployment. Manufacturing concentrates in China for LED display systems, South Korea for 5G stadium infrastructure, and Japan for merchandise authenticity certification equipment. Supply chains draw from synthetic turf components, broadcast camera arrays, and mobile wallet integration modules. Single-source vulnerability sits with specialized seating system providers. Distribution runs through league-licensed equipment consortia and federation-approved vendor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
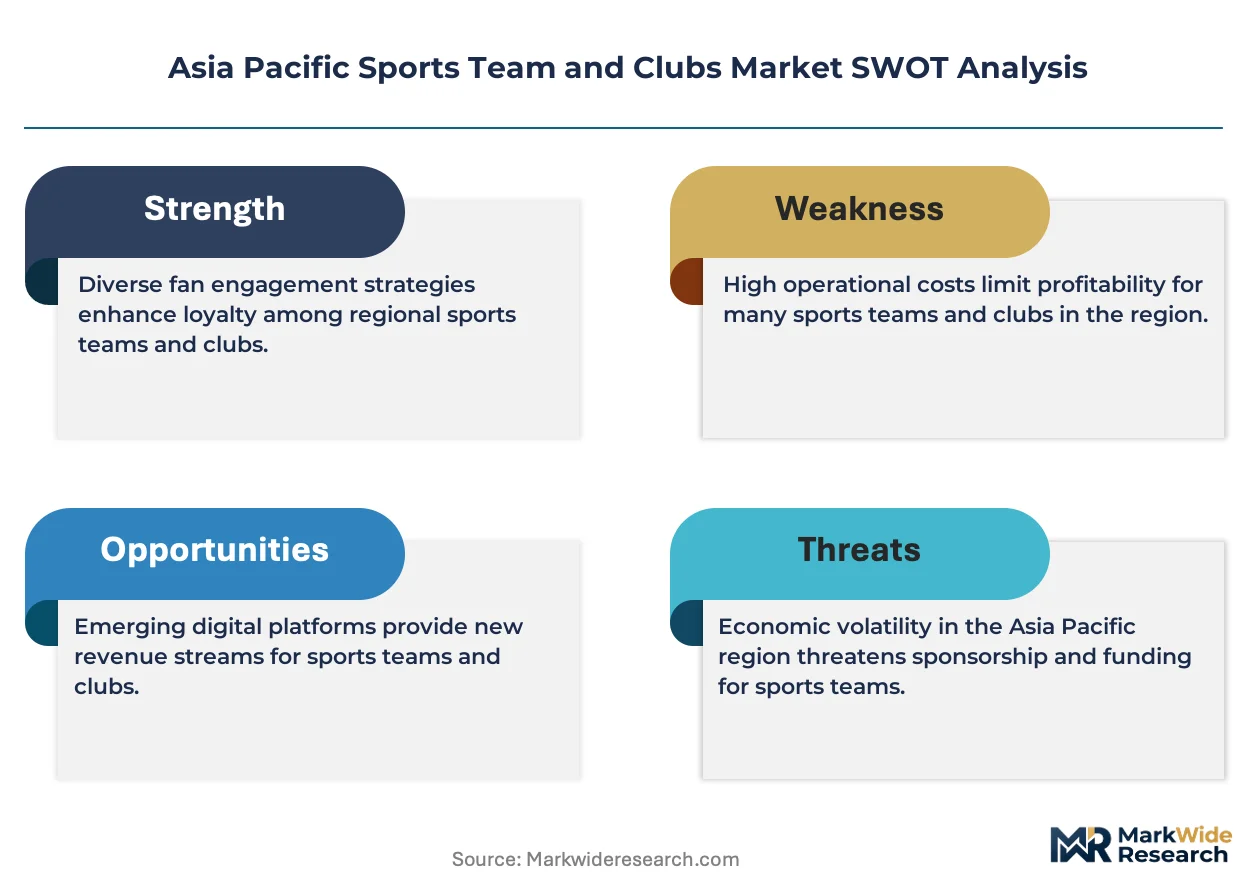
Asia Pacific sports franchise economics fragment across regulatory regimes and infrastructure maturity levels, creating niches for operators who capture emerging women's league broadcast appetite and tier-II city corporate sponsorship liquidity.
For Market Incumbents: Harden broadcast revenue predictability through exclusive streaming platform partnerships that lock in territory licenses against auction cycle volatility. Deepen upstream control over youth academy pipelines to reduce talent acquisition cost inflation from European transfer market competition. Incumbent IPL franchises must defend against J.League commercialization encroaching on Southeast Asian diaspora viewership through embedded regional sponsorship structures. For New Entrants and Emerging Players: Tier-II Indian cities including Indore, Lucknow, and Guwahati present underpenetrated cricket markets with stadium-ready infrastructure and untapped corporate hospitality demand. Women's league properties in Australia and India demonstrate faster sponsor conversion cycles with lower rights acquisition costs than established men's competitions. New entrants should anchor go-to-market strategy through esports crossover licensing partnerships that monetize mobile-first engagement platforms. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biometric-enabled stadium infrastructure and 5G deployment programs, favoring asset-light franchise licensing models over venue ownership. Acquisition targets should display integrated data science operations and regional academy networks feeding professional rosters. Investors should monitor IPL media auction clearing prices as the inflection signal for broadcast rights valuation trajectories across the analysis window.| Strategic Initiative | Industry Significance |
|---|---|
| Women's League Property Development | Australia's AFLW and India's WPL demonstrate scalable broadcast appetite with faster sponsor conversion cycles. |
| Biometric Fan Authentication Deployment | Facial recognition and mobile wallet convergence enables frictionless stadium entry across Singapore and Sydney venues. |
| Tier-II City Franchise Expansion | Indore, Lucknow, and Guwahati present underpenetrated corporate sponsorship liquidity in India's cricket economy. |
| Esports Crossover Licensing | Traditional cricket and football clubs capture younger demographics via mobile-first engagement platforms. |
| Youth Academy Pipeline Integration | Melbourne City FC exemplifies City Football Group's regional talent capture strategy before European transfer markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of BCCI annual reports, J.League financial disclosures, and Australian Sports Commission infrastructure databases. Primary interviews engaged franchise operations directors, league licensing executives, stadium development managers, and sports tourism operators across India, Japan, and Australia. Secondary validation drew from SEC filings of publicly traded ownership groups, state-level entertainment tax records, and federation governance documentation. Bottom-up revenue modeling triangulated against top-down market sizing across organization type and revenue stream segmentations.
Forecast inputs incorporate IPL media auction cycles, J.League streaming partnership renewals, and PLI scheme disbursement timelines across the projection horizon. Segmentation dimensions modeled include organization type, revenue stream, membership tier, and customer archetype against regional regulatory cluster variations. CAGRs derived from historical rights transaction values and infrastructure investment trajectories. Industry-specific inputs encompass foreign player quota adjustments and biometric technology adoption curves.
Practitioners should monitor IPL auction clearing prices, J.League foreign player policy revisions, and Indian state gambling regulation enactments for early signals of forecast deviation. Projections reflect assumptions of continued streaming platform fragmentation and sustained PLI scheme funding. Material shifts in broadcast rights auction dynamics or federal infrastructure incentive withdrawal would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
Europe Sports Management Software Market
Sports & Fitness Technology
Padel Court Operator Market
Sports & Fitness Technology
Smart Court (Sports) Market
Sports & Fitness Technology
Asia Pacific Sports Promoter Market
Sports & Fitness Technology
India Sports Team and Clubs Market
Sports & Fitness Technology
Smart Swimming Caps Market
Sports & Fitness Technology
Europe Sports Promoter Market
Sports & Fitness Technology
North America Sports Team and Clubs Market
Sports & Fitness Technology
Smart Fitness Device Market
Sports & Fitness Technology
UK Sports Management Software Market
Sports & Fitness Technology
Smart Bike Trainers Market
Sports & Fitness Technology
Smart Trainers Market
Sports & Fitness Technology
France Sports Teams and Clubs Market
Sports & Fitness Technology
Stadium and Arena Management Solution Market
Sports & Fitness Technology
North America Sports Management Software Market
Sports & Fitness Technology
Virtual Reality Fitness Market