
 Europe Spectator Sports Market | 2026-2036
Europe Spectator Sports Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Spectator Sports Market Insights
English football clubs are broadening their commercial infrastructure through stadium redevelopment and hospitality expansion. Manchester United plc leverages its global brand licensing network across Asia-Pacific markets. Real Madrid CF sustains revenue through premium seating tiers and museum tourism at the Santiago Bernabéu. FC Bayern Munich AG anchors its commercial model through diversified sponsorship portfolios and youth academy monetization.
Europe Spectator Sports encompasses organized athletic competitions designed for live or broadcast viewership, incorporating ticketing systems, media rights distribution, and experiential venue services across football, basketball, tennis, and rugby disciplines. These events generate revenue through multi-platform content delivery, merchandise logistics, and corporate partnership structures that monetize audience attention. Football dominates the Sport Type segment through established league hierarchies and continental tournament cycles that command premium broadcast valuations. The Fan Engagement dimension shows structural momentum shifting toward digital subscription models and direct-to-consumer streaming platforms that bypass traditional television intermediaries. Merchandise Sales and Sponsorship Deals retain concentrated margin pools due to exclusive licensing agreements and multi-year corporate partnerships with endemic and non-endemic brands.
The EU Green Deal mandates stadium carbon disclosures while REACH regulations govern synthetic turf materials and flame-retardant seating compounds. EMA frameworks indirectly shape athlete health protocols that affect competition scheduling and liability structures for event organizers. Stakeholders must monitor how CSRD reporting requirements will force listed sports entities to quantify environmental footprints and social governance metrics in public filings.
Market Dynamics
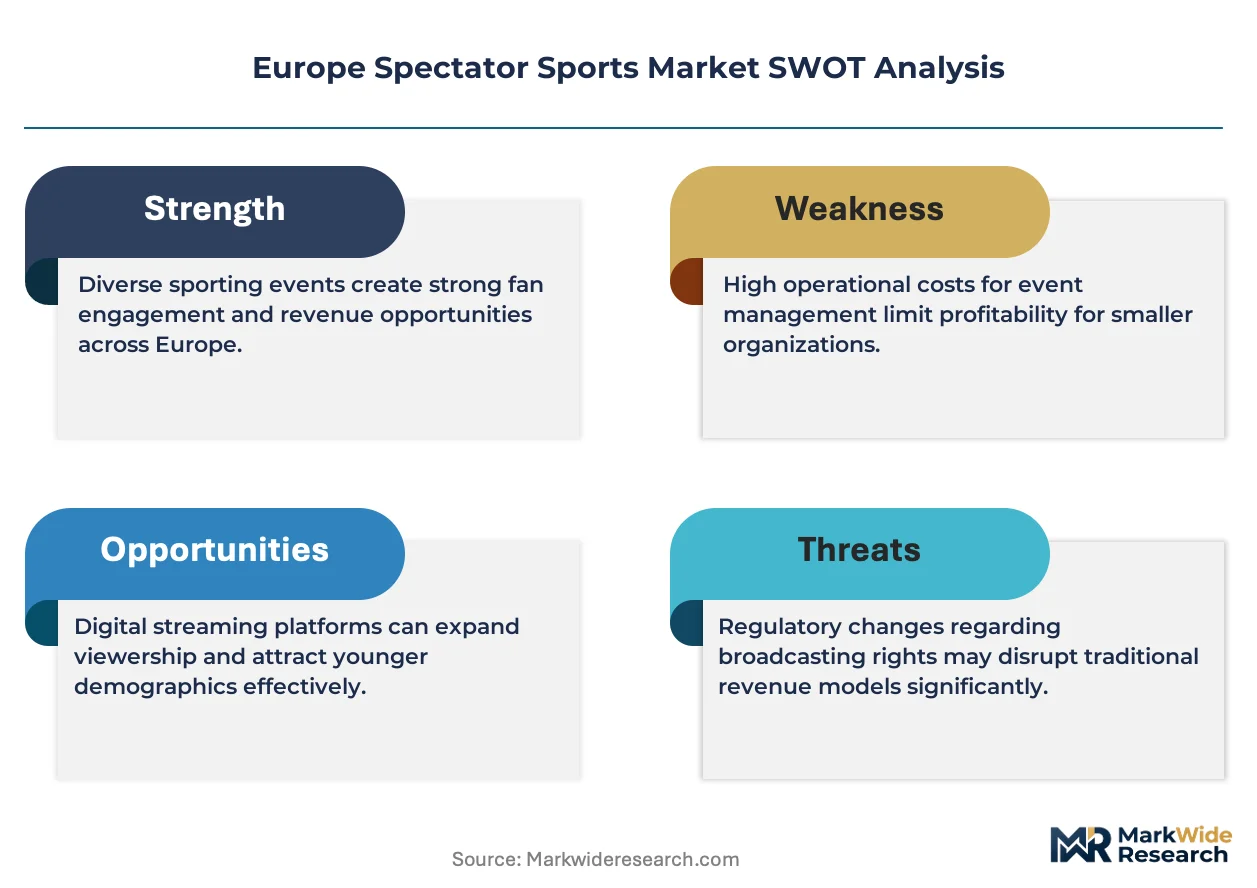
The EU Green Deal is compressing stadium infrastructure investment cycles across European leagues, forcing operators to accelerate decarbonization timelines while maintaining matchday revenue streams during retrofit construction periods.
Growth Catalysts
- CSRD Disclosure Mandates:Listed sports entities must quantify environmental footprints in public filings, creating audit demand for carbon accounting software and stadium energy management systems.
- Bundesliga Broadcasting Rights:Germany's league licensing auctions concentrate capital flows into stadium modernization and hospitality expansion projects.
- Synthetic Turf Innovation:REACH-compliant materials reduce replacement cycles and liability exposure for venue operators managing multi-use facilities.
Market Restraints
- Construction Input Volatility:Steel and concrete price fluctuations disrupt stadium redevelopment timelines, particularly affecting English football club expansion projects.
- Licensed Betting Operator Concentration:Regulatory fragmentation across EU member states limits platform scalability and increases compliance overhead for cross-border marketing.
- Legacy Seating Replacement Cycles:Flame-retardant compound regulations under REACH force premature retirement of existing stadium inventory before depreciation completion.
Strategic Opportunities
- Poland and Eastern Europe:Underpenetrated premium hospitality tiers in emerging football markets offer first-mover positioning for stadium development consortia.
- Direct-to-Consumer Streaming:Club-controlled OTT platforms bypass traditional broadcast intermediaries, capturing subscriber data and margin compression from legacy rights deals.
- EU Green Deal Subsidies:Member state recovery funds allocate capital to venue energy retrofits, reducing payback periods for solar installation and heat pump conversion projects.
Industry Challenges
- Carbon Accounting Skill Scarcity:Stadium operators lack in-house expertise to meet CSRD reporting requirements, forcing reliance on external consultants and delaying disclosure timelines.
- Multi-Use Venue Integration:Concert and esports scheduling conflicts with football fixtures create revenue optimization complexity and pitch quality degradation risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Spectator Sports Market |
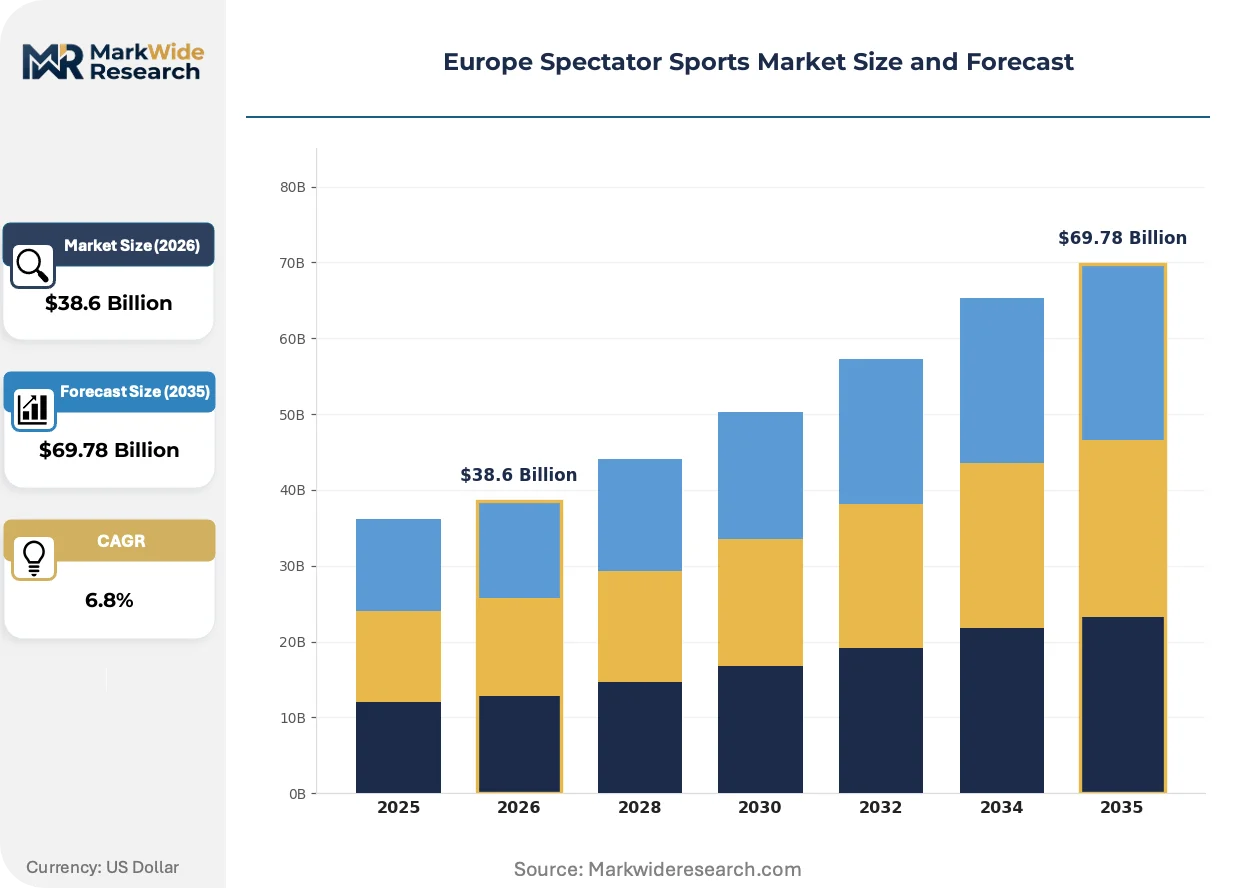
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sport Type: Football, Basketball, Tennis, Rugby Event Size: Major Events, Regional Tournaments, Local Matches, Friendly Games Fan Engagement: Social Media, Live Streaming, Merchandise Sales, Sponsorship Deals Viewing Platform: Television, Online, Mobile, In-Person |
| Companies Covered | Manchester United plc, Real Madrid CF, FC Barcelona, FC Bayern Munich AG, Premier League Ltd, UEFA Events SA, Formula One Group, La Liga, The All England Lawn Tennis and Croquet Club, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Spectator Sports Market Trends and Innovations
Digital infrastructure investment is outpacing physical stadium capacity expansion across European leagues, with capital allocation shifting toward data capture systems and personalized fan engagement platforms.
Smart stadium operating systems is unifying access control, concession transactions, and seat-level connectivity into single-platform architectures. Bundesliga and Premier League venues are deploying these systems at scale during 2025-2026 retrofit windows. This convergence is unifying previously siloed revenue streams into integrated fan journey analytics that optimize real-time pricing and inventory management.
The EU Green Deal's stadium carbon disclosure requirements are mandating granular energy reporting for facilities exceeding 50,000 spectator capacity. Operators must install sub-metering infrastructure to track scope emissions by event type and tenant activity. German and Spanish venues face the steepest compliance curves due to earlier enforcement timelines and existing municipal energy partnership structures.
Subscription fatigue among younger demographics is fragmenting traditional season ticket models into flexible micro-membership tiers. Dutch and Scandinavian clubs are piloting blockchain-based fractional seat ownership and transfer marketplaces. This behavioral pivot is most visible in markets where mobile-first payment penetration exceeds 80 percent and secondary ticket platform regulation remains permissive.
Europe Spectator Sports Market Segmentation
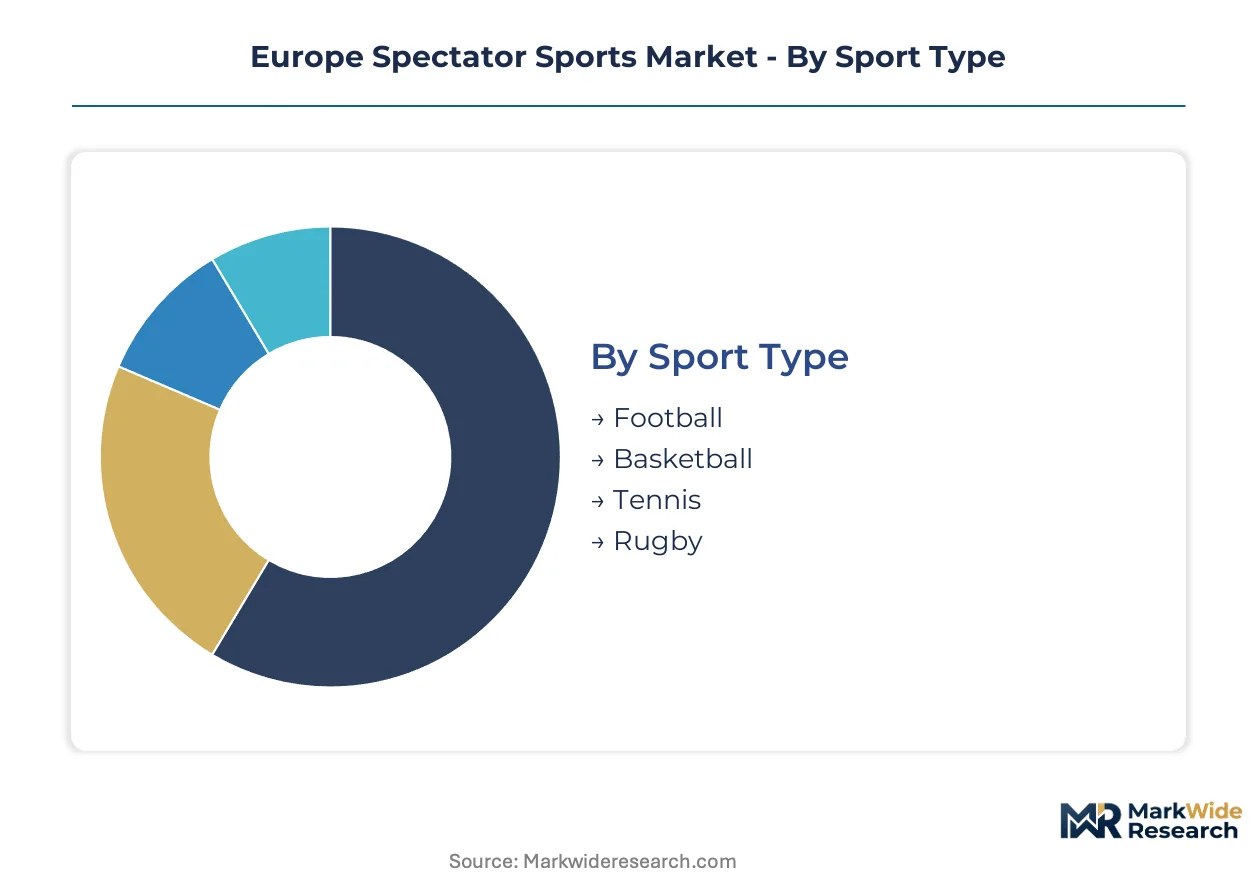
Segmentation in the Europe Spectator Sports Market reveals how revenue pools fragment across sport disciplines, event scales, and fan touchpoints. Understanding these divisions exposes where capital concentrates and where emerging monetization models are displacing legacy structures.
Sport Type:
Football operates as the standalone revenue engine with embedded commercial ecosystems spanning multiple touchpoints, while secondary sports depend on integrated league structures for financial viability.
- Football:Continental tournament cycles and established league hierarchies command premium broadcast valuations across Germany, England, and Spain. Bundesliga and Premier League licensing auctions concentrate capital flows into stadium modernization and hospitality infrastructure.
- Basketball:EuroLeague commercial structures remain secondary to football, with revenue concentrated in Mediterranean markets where domestic league viewership sustains regional broadcasting arrangements. Spanish and Turkish clubs anchor the competitive tier that attracts pan-European sponsorship interest.
- Tennis:Grand Slam events at Roland Garros and Wimbledon generate concentrated revenue windows, with ATP/WTA tour structures creating fragmented monetization across the calendar.
- Rugby:Six Nations and domestic league structures in France and England sustain professional tier viability, though commercial scale remains subordinate to football economics.
Volume placements concentrate in Football; the faster expansion belongs to Basketball as digital platform distribution extends reach into underpenetrated Eastern European markets.
Event Size:
Cost tier differentiation separates infrastructure-heavy major events from leaner regional and local formats, with hospitality and broadcast economics scaling non-linearly across the pyramid.
- Major Events:UEFA European Championships and Champions League finals require multi-city coordination and temporary venue overlays. These events absorb the largest single capital deployments for security, broadcast infrastructure, and sponsor activation zones.
- Regional Tournaments:Domestic cup competitions and second-tier league structures operate with standardized venue requirements and predictable cost bases. German DFB-Pokal and English FA Cup fixtures demonstrate this mid-tier economic model.
- Local Matches:Regular season fixtures generate recurring revenue through season ticket structures and local corporate hospitality. These events anchor cash flow stability for club operations.
- Friendly Games:Pre-season tours and exhibition fixtures command premium pricing in non-traditional markets, with Asian and North American tour stops monetizing global brand equity.
Revenue scale peaks at Major Events; margin sustainability sits strongest with Local Matches.
Fan Engagement:
Customer type stratification separates passive content consumers from active commercial participants, with data capture value escalating across the engagement depth spectrum.
- Social Media:Club-controlled platforms aggregate attention metrics that feed sponsorship valuation models. Real Madrid and Manchester United leverage these channels for direct fan relationship management.
- Live Streaming:Club-operated OTT platforms bypass traditional broadcast intermediaries, capturing subscriber data and compressing margin leakage from legacy rights structures. Bundesliga clubs are deploying these systems at scale.
- Merchandise Sales:Exclusive licensing agreements with endemic and non-endemic brands sustain concentrated margin pools. FC Bayern Munich's diversified sponsorship portfolio demonstrates this model.
- Sponsorship Deals:Multi-year corporate partnerships with betting operators, automotive brands, and financial services firms anchor commercial revenue stability across league tiers.
Transaction frequency concentrates in Merchandise Sales; the steepest expansion trajectory belongs to Live Streaming as direct-to-consumer platforms displace linear television intermediaries.
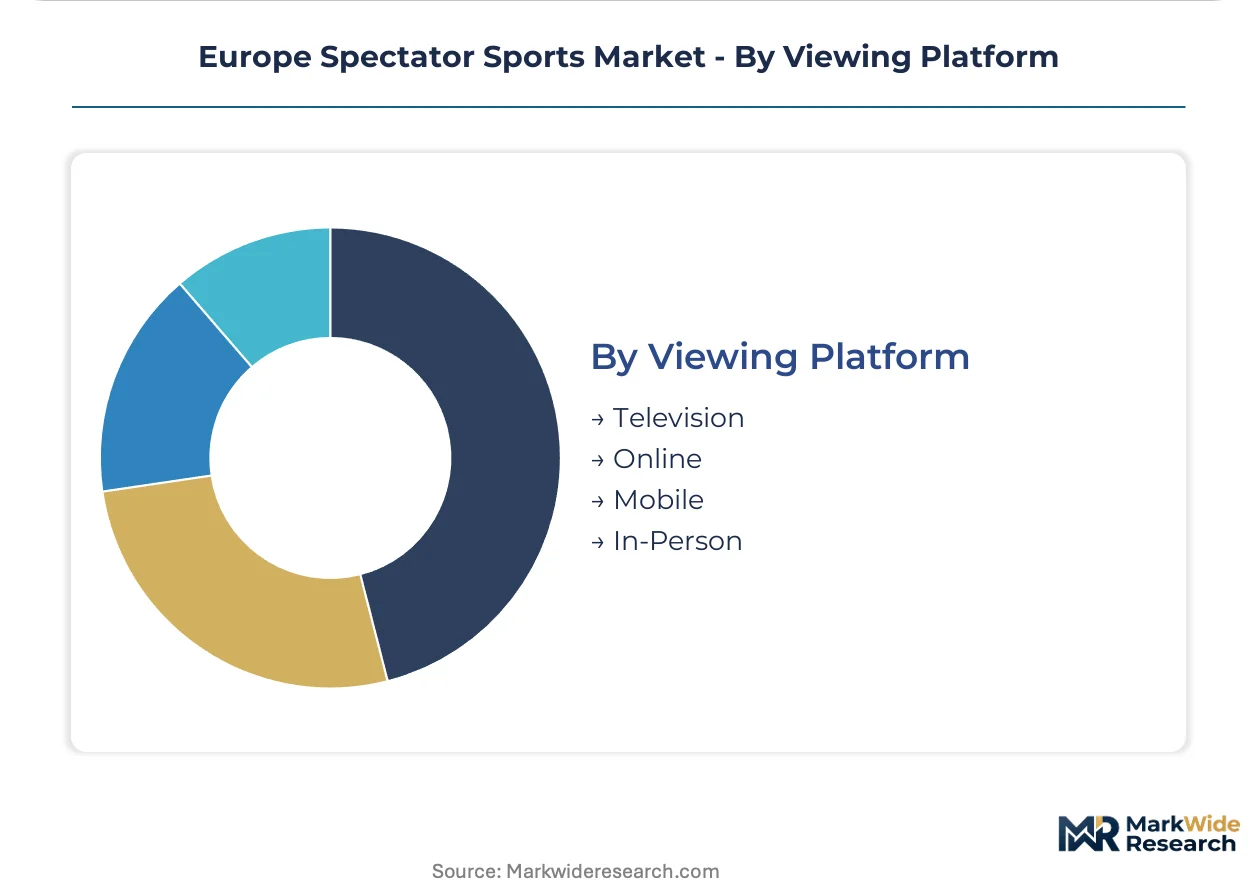
Viewing Platform:
Maturity gradients separate legacy distribution channels from emerging digital formats, with infrastructure investment cycles diverging sharply between established and nascent platforms.
- Television:Traditional broadcast licensing remains the dominant revenue channel for league operators, though subscriber erosion in younger demographics compresses long-term valuation growth.
- Online:Browser-based streaming services aggregate content across multiple leagues and sports, with advertising-supported models gaining traction in price-sensitive segments.
- Mobile:App-first consumption patterns concentrate in Dutch and Scandinavian markets where mobile payment penetration exceeds threshold levels for micro-transaction commerce.
- In-Person:Stadium attendance generates matchday revenue through ticketing, concessions, and hospitality tiers, with EU Green Deal mandates forcing infrastructure retrofit cycles.
Revenue concentration persists in Television; subscriber growth is climbing the fastest in Mobile as platform-native engagement patterns reshape consumption habits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Broadcast licensing revenue and stadium infrastructure investment anchor market development across European football economies, with regulatory pressure from Brussels reshaping capital allocation timelines.
Germany
Bundesliga media rights auctions concentrate liquidity into venue modernization and hospitality tier expansion. The EU Green Deal mandates carbon disclosure for facilities exceeding 50,000 capacity, forcing operators in Munich and Dortmund to accelerate retrofit schedules. Bavaria's stadium clusters lead heat pump conversion deployment under federal recovery fund allocations.
United Kingdom
Premier League commercial structures drive stadium redevelopment cycles across Greater London and the North West. REACH regulations govern synthetic turf materials and flame-retardant seating compounds, affecting replacement timelines for legacy inventory. Manchester and Liverpool venue operators face compressed depreciation schedules as compliance deadlines approach.
Spain
La Liga broadcasting valuations sustain premium seating and museum tourism revenue at Madrid and Barcelona facilities. EMA frameworks shape athlete health protocols that influence competition scheduling and liability structures. Catalan and Basque Country stadium clusters invest in sub-metering infrastructure to track scope emissions by event type.
France
Paris-based Grand Slam events at Roland Garros generate concentrated revenue windows with premium hospitality monetization. ANSM and CNIL oversight intersects with athlete data handling and health disclosure requirements. The Île-de-France region anchors national tournament infrastructure while provincial clubs pursue multi-use venue models.
Italy
Serie A commercial structures lag Premier League and Bundesliga valuations, creating pressure for stadium ownership reform in Milan and Turin. CE marking requirements and municipal energy partnerships shape retrofit investment decisions. Lombardy and Piedmont facilities face steeper compliance curves due to earlier enforcement timelines under regional environmental accords.
Europe Spectator Sports Market Competitive Landscape
Global majors compete with regional champions across media rights and venue infrastructure, producing a tiered structure where league operators and elite clubs capture disproportionate value. Concentration is pronounced at the apex, with mid-tier clubs and secondary sports federations operating in fragmented, geographically bounded markets. Two archetypes dominate: integrated league-and-club conglomerates with broadcast and commercial control, and standalone venue operators with hospitality specialization. Competitive moves center on exclusive content licensing and stadium asset consolidation.
Within the integrated league-and-club tier, Manchester United plc and Real Madrid CF exemplify archetypes of global brand licensing networks and premium venue monetization respectively. FC Bayern Munich AG occupies a position bridging commercial diversification with youth academy verticalization. These entities anchor the competitive set through their representation of distinct geographic and structural models.
| Leading Market Players |
|---|
| Manchester United plc |
| Real Madrid CF |
| FC Barcelona |
| FC Bayern Munich AG |
| Premier League Ltd |
| UEFA Events SA |
| Formula One Group |
| La Liga |
| The All England Lawn Tennis and Croquet Club |
| Others |
Pricing and Supply Chain Analysis
Backward integration into stadium construction and hospitality infrastructure anchors pricing power for elite European football clubs, compressing margin leakage from third-party venue operators while concentrating revenue capture across matchday and non-event commercial cycles. This structural choice ties supply security directly to the premium pricing tiers that Bundesliga and Premier League operators deploy for corporate hospitality and museum tourism offerings.
Pricing Analysis
Warranty-bundled season ticket structures separate all-inclusive hospitality packages from unbundled general admission, with premium tiers incorporating guaranteed seat replacement and priority resale marketplace access. Three-tier pricing structure across premium, standard, and economy levels stratifies by sightline quality and amenity depth, with price differentiation intensifying around UEFA competition fixtures where demand spikes. Cost compression in general admission is intensifying because secondary ticket platform competition erodes face-value capture. Younger demographics exhibit highest price sensitivity, driving micro-membership pilots in Dutch and Scandinavian markets.
Supply Chain Analysis
Direct-to-club procurement channels handle specialized stadium components, with distribution running through German steel fabricators, Italian lighting systems manufacturers, and Spanish turf technology providers. Synthetic turf materials, LED display systems, and smart seat infrastructure draw from concentrated supplier bases in these jurisdictions. Single-source vulnerability sits with REACH-compliant flame-retardant compound suppliers facing raw material allocation constraints. Logistics chokepoints emerge from just-in-time delivery requirements for mid-season retrofit windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stadium carbon retrofit capacity bottlenecks prop pricing across European leagues, with qualified contractor scarcity and EU Green Deal compliance timelines limiting supply elasticity for venue modernization projects.
For Market Incumbents: Deploy exclusive content licensing as the primary lever to lock broadcast revenue stability against direct-to-consumer platform erosion. Bundesliga and Premier League operators should accelerate backward integration into proprietary OTT infrastructure before subscriber migration accelerates. CSRD disclosure mandates create audit demand that stadium operators can monetize through energy management system partnerships. For New Entrants and Emerging Players: Betting technology providers offer the most penetrable channel partner type for stadium data integration plays, with licensed operator concentration creating white-space for compliance-software vendors. Poland and Eastern European hospitality tiers present underdeveloped premium seating markets where first-mover stadium development consortia can establish pricing benchmarks. Club-controlled fan engagement platforms represent the optimal go-to-market angle for circumventing entrenched broadcast intermediaries. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated league-and-club conglomerates with broadcast and commercial control, with long-term viability hinging on direct-to-consumer subscriber retention across five-to-ten year windows. Acquisition targets should display proprietary venue assets with multi-use revenue diversification and municipal energy partnership structures. The signal to watch is subscription fatigue migration patterns among 18-34 demographics, as this cohort's platform switching behavior indicates inflection timing for legacy broadcast valuation collapse.| Strategic Initiative | Industry Significance |
|---|---|
| Stadium Carbon Retrofit Program | EU Green Deal subsidies reduce payback periods for solar and heat pump conversions at Bundesliga venues. |
| Direct-to-Consumer Platform Launch | Club-controlled OTT systems bypass Sky and DAZN intermediaries to capture subscriber data and margin compression. |
| Synthetic Turf Innovation Partnership | REACH-compliant materials reduce replacement cycles for multi-use venues in England and Germany. |
| Premium Hospitality Tier Expansion | Underpenetrated corporate seating markets in Poland and Eastern Europe offer first-mover positioning. |
| Smart Stadium Operating System Deployment | Unified access and concession platforms optimize real-time pricing at Real Madrid and Manchester United facilities. |
Research Methodology
League financial disclosures, municipal stadium authority filings, and EU regulatory databases formed the secondary backbone, supplemented by primary interviews with venue operations directors, broadcast licensing executives, stadium construction procurement leads, and carbon accounting consultants. Bottom-up segmentation modeling across sport type, event scale, and fan engagement dimensions was cross-validated against top-down macroeconomic indicators and media rights transaction tracking.
Bottom-up demand modeling aggregated individual club revenue streams across ticketing, broadcasting, and commercial categories, while top-down validation referenced aggregate league valuations and regional GDP-correlated entertainment expenditure patterns. Segmentation dimensions included sport discipline hierarchy, venue capacity tier, viewing platform maturity, and geographic regulatory cluster. CAGRs were derived from trend extrapolation of disclosed media rights cycles and stadium investment pipelines, with carbon compliance cost curves and subscription platform adoption rates serving as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including geopolitical disruption to international friendly tour schedules and unilateral regulatory shifts in sports betting licensing frameworks. Forecasts reflect documented assumptions regarding CSRD enforcement timelines and Bundesliga media rights renewal trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
Asia-Pacific Sports Management Software Market
Sports & Fitness Technology
Asia-Pacific Fantasy Sports Market
Sports & Fitness Technology
Smart Bike Trainers Market
Sports & Fitness Technology
India Sports Team and Clubs Market
Sports & Fitness Technology
Sportswear Rental and Rotation Market
Sports & Fitness Technology
Smart Stadium Market
Sports & Fitness Technology
Smart Sports Market
Sports & Fitness Technology
Smart Swimming Caps Market
Sports & Fitness Technology
UK Sports Team and Clubs Market
Sports & Fitness Technology
Europe Sports Team and Clubs Market
Sports & Fitness Technology
Asia Pacific Sports Team and Clubs Market
Sports & Fitness Technology
Asia Pacific Sports Promoter Market
Sports & Fitness Technology
Sports Software Market
Sports & Fitness Technology
Smart Fitness Device Market
Sports & Fitness Technology
France Sports Teams and Clubs Market
Sports & Fitness Technology
Sports Team and Clubs Market