
 Paragliding Equipment Market | 2026-2036
Paragliding Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Paragliding Equipment Market Outlook
The gap between premium EN-D competition wings and entry-level EN-A training gliders is shifting as material costs and certification complexity widen price spreads. Ozone Paragliders leverages its New Zealand development base to sustain technology leadership in lightweight mountain descent designs. Advance Thun AG anchors European distribution through Swiss precision manufacturing and direct-to-school channel control. Nova Performance Paragliders differentiates via Slovenian R&D intensity in cell structure aerodynamics.
Paragliding equipment encompasses free-flight aircraft consisting of fabric wings with no rigid primary structure, typically constructed from ripstop nylon and polyester lines rated to 50-300 kg break loads, designed to harness thermal updrafts for sustained human flight. The product type dimension shows paraglides capturing the dominant margin pool due to replacement cycles tied to EN certification expiry, while harnesses with integrated back protection represent the fastest-growing sub-category as safety consciousness rises among adventure sports participants. Deployment through training academies generates the steadiest recurring demand, whereas personal use sales exhibit higher seasonality linked to regional weather patterns.
EN standards administered by the European Standards body and FAA Part 103 ultralight regulations in the United States govern airworthiness classification and pilot eligibility, directly shaping which product tiers manufacturers prioritize for cross-border market access. The EU Green Deal's pressure on petrochemical-derived fabrics is forcing material substitution trials with bio-based ripstop alternatives. Stakeholders must monitor how certification harmonization between EASA frameworks and emerging Asian regulators affects export eligibility for European manufacturers.
Market Dynamics
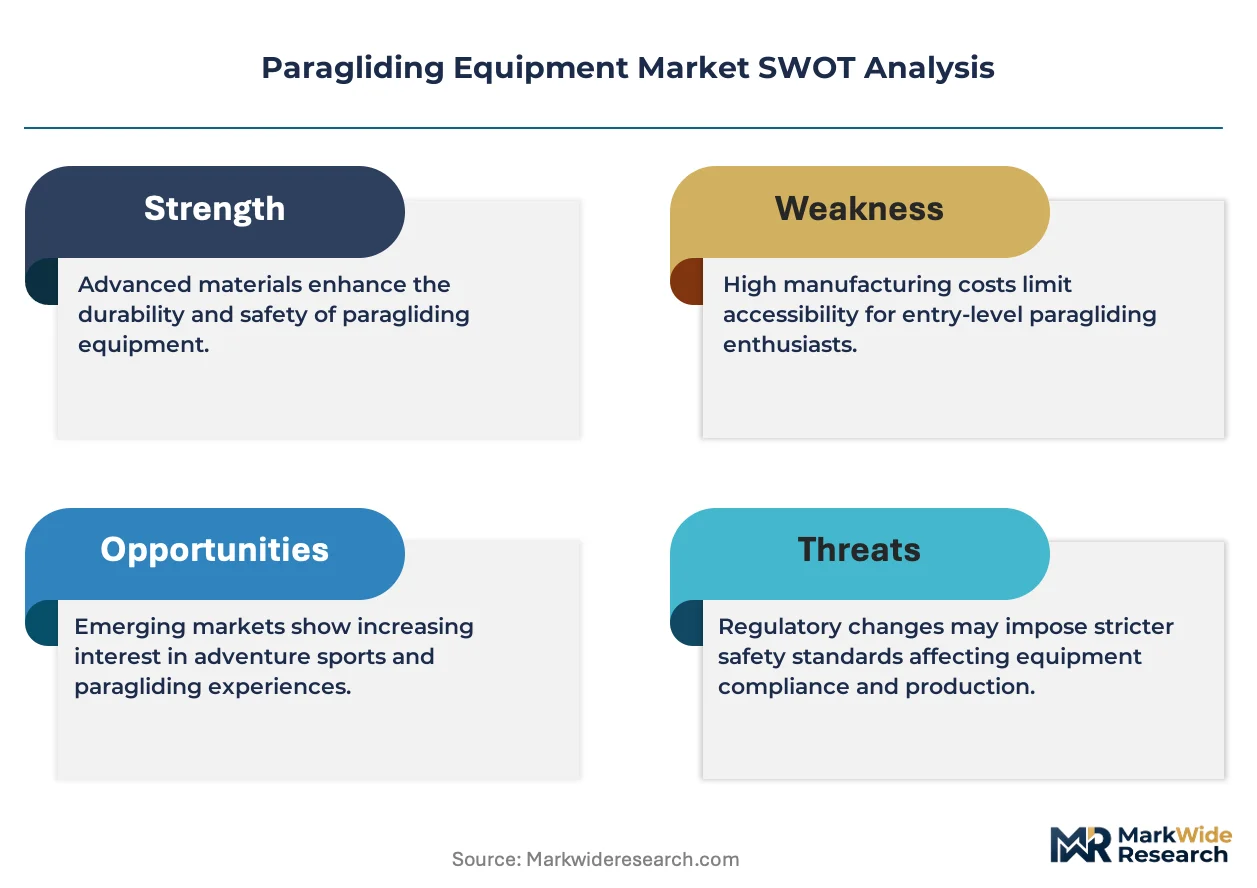
EN certification expiry cycles and the EU Green Deal's petrochemical fabric pressures are restructuring manufacturer priorities, forcing simultaneous investment in bio-based material trials and accelerated R&D pipelines to maintain airworthiness compliance.
Growth Catalysts
- Recreational tourism infrastructure:Alpine destination investments in Switzerland, France, and Austria are expanding accessible launch sites and training academy networks, pulling first-time participants into equipment purchase funnels.
- REACH-compliant material innovation:Bio-based ripstop nylon alternatives under development reduce petrochemical dependency while preserving 50-300 kg break load ratings critical for line integrity.
- Harness-integrated safety systems:Back protection technology adoption among adventure sports participants is accelerating replacement cycles for legacy harness configurations.
Market Restraints
- Petrochemical input volatility:Ripstop nylon and polyester line production depends on oil-derived feedstocks, exposing margin structures to energy price swings without viable near-term substitutes at scale.
- Certification concentration risk:EN standard testing capacity clusters in European laboratories, creating bottlenecks for manufacturers seeking cross-border market access outside the continent.
- Weather-dependent demand seasonality:Personal use sales compress into narrow thermal windows in temperate zones, forcing inventory carrying costs through off-peak quarters.
Strategic Opportunities
- EASA-Asia regulatory harmonization:Emerging Asian aviation regulators adopting European certification frameworks will streamline export eligibility for manufacturers with existing EN compliance infrastructure.
- Training academy channel capture:Direct-to-school distribution models bypass retail markup erosion while locking in recurring fleet replacement contracts tied to student throughput.
- Lightweight mountain descent convergence:Cross-pollination between paragliding and speed-flying equipment designs is opening technical product tiers for advanced alpine users.
Industry Challenges
- Aerodynamic engineering talent scarcity:Cell structure optimization expertise concentrates in Slovenian and Swiss R&D clusters, constraining manufacturer expansion outside these geographies.
- Multi-jurisdiction certification timelines:FAA Part 103 ultralight classification divergence from EN standards forces parallel testing tracks for US market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paragliding Equipment Market |
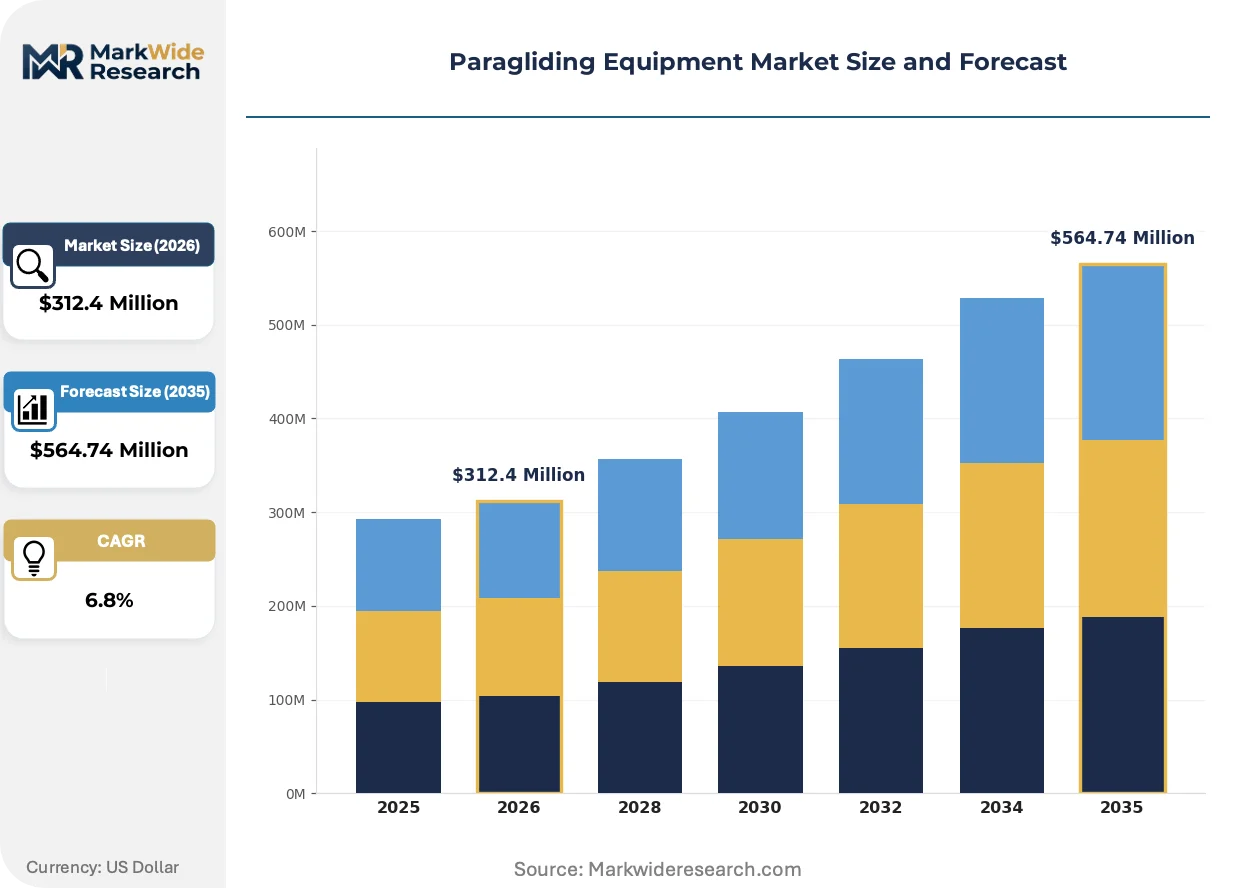
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paraglides, Harnesses, Reserve Parachutes, Accessories End User: Aeronautical Enthusiasts, Adventure Sports Participants, Schools, Professionals Deployment: Personal Use, Commercial Rental, Training Academies, Competitions Size: Lightweight, Heavyweight, Medium, Compact |
| Companies Covered | Ozone Paragliders, Advance Thun AG, Nova Performance Paragliders, Gin Gliders, Skywalk GmbH & Co. KG, Dudek Paragliders, Apco Aviation Ltd., Supair, Gradient, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paragliding Equipment Market Strategic Shifts
Material science breakthroughs and regulatory pressure on synthetic fabrics are compressing traditional product development timelines while opening new performance tiers previously unreachable with conventional construction methods.
Ultralight ripstop nylon woven with bio-based polymer threads is expanding into competition-grade wing construction. EN-D rated pilots and mountain descent specialists are adopting these configurations at accelerating rates despite premium positioning. The technology is expanding into previously weight-restricted launch environments where conventional fabric density prohibited safe deployment.
EASA frameworks are tightening alignment with EU Green Deal sustainability mandates for aviation-adjacent equipment manufacturing. Manufacturers must now document supply chain carbon intensity alongside traditional airworthiness metrics. European alpine region producers face the steepest compliance curve as domestic regulators enforce disclosure requirements ahead of import markets.
Certification-driven purchase preferences are reshaping buyer behavior across training academy procurement channels. School operators now specify EN-A and EN-B fleet compositions based on student injury liability exposure rather than purely cost minimization. This pattern concentrates most visibly in German and Austrian instructional markets where liability frameworks incentivize conservative equipment selection.
Paragliding Equipment Market Segmentation
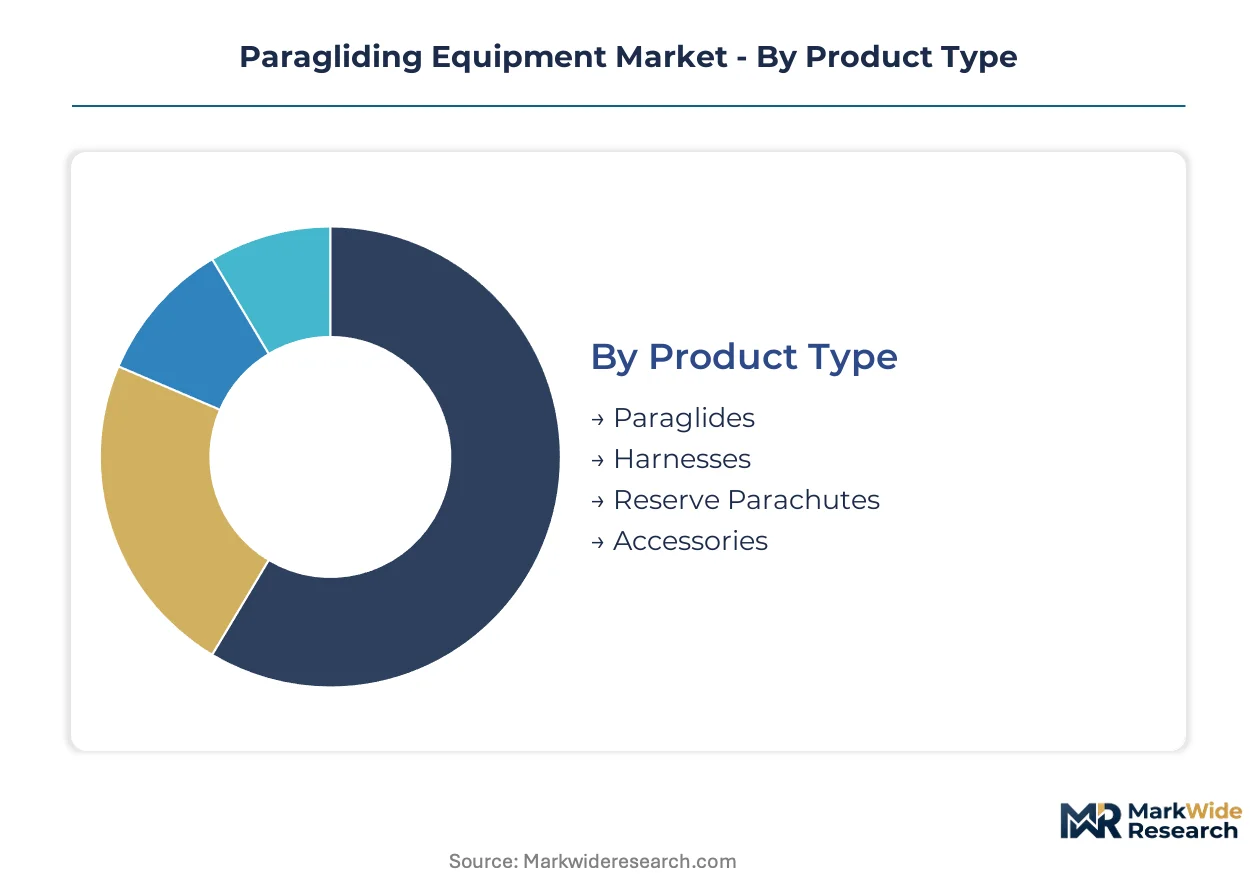
Equipment purchase decisions in paragliding diverge sharply between recreational participants prioritizing safety certification tiers and professionals optimizing for aerodynamic performance metrics. Segmentation reveals how EN rating systems, flight environment constraints, and channel access patterns reshape manufacturer portfolio priorities across distinct buyer archetypes.
Product Type:
Replacement cycles and margin capture potential drive procurement concentration toward certified airworthiness tiers rather than peripheral equipment categories.
- Paraglides:Fabric wings constructed from ripstop nylon with polyester lines rated to 50-300 kg break loads, designed to harness thermal updrafts. Demand clusters in Swiss and French alpine regions where EN certification expiry forces predictable replacement timelines among training academies and personal users.
- Harnesses:Pilot suspension systems with integrated back protection technology. Adventure sports participants in Germany and Austria are accelerating replacement of legacy configurations as liability frameworks incentivize conservative safety equipment selection in instructional settings.
- Reserve Parachutes:Emergency descent systems packed for rapid deployment. Regulatory inspection intervals in EASA jurisdictions sustain steady aftermarket demand.
- Accessories:Flight instruments, speed bars, and storage solutions. Price-sensitive entry-level buyers concentrate purchases here during initial equipment outlay.
Paraglides lead on scale; harnesses lead on momentum.
End User:
Risk tolerance and flight hour accumulation separate buyer groups across the equipment specification spectrum.
- Aeronautical Enthusiasts:Recreational pilots with moderate flight hours prioritizing EN-B and EN-C rated wings for cross-country thermal flying. Swiss and Austrian destination tourism infrastructure pulls this segment into premium product tiers.
- Adventure Sports Participants:Experience-seekers entering through tandem flights and introductory courses. Schools in France and Germany capture this cohort through rental-to-purchase conversion programs.
- Schools:Training academies operating certified fleets for student instruction. Procurement concentrates on EN-A rated equipment with conservative handling characteristics to minimize liability exposure.
- Professionals:Competition pilots and mountain descent specialists requiring EN-D rated performance wings. Slovenian and Swiss R&D clusters supply this niche with lightweight configurations for technical alpine environments.
Schools anchor procurement volume; adventure sports participants expand most quickly.
Deployment:
Channel structure determines margin retention and inventory carrying cost exposure for manufacturers.
- Personal Use:Individual ownership with seasonality compressing demand into narrow thermal windows in temperate zones. Weather-dependent purchase timing forces inventory management complexity through off-peak quarters.
- Commercial Rental:Tourist-facing operations at alpine destination sites. French and Swiss launch site investments are expanding fleet refresh cycles for this channel.
- Training Academies:Direct-to-school distribution models generating steadiest recurring demand. German and Austrian instructional markets specify EN-A and EN-B fleet compositions based on student injury liability frameworks.
- Competitions:Event-driven procurement for sanctioned aerobatic and cross-country meets. Lightweight mountain descent convergence with speed-flying equipment is opening technical product tiers for this segment.
Training academies lock in recurring revenue; personal use shows steepest expansion trajectory.
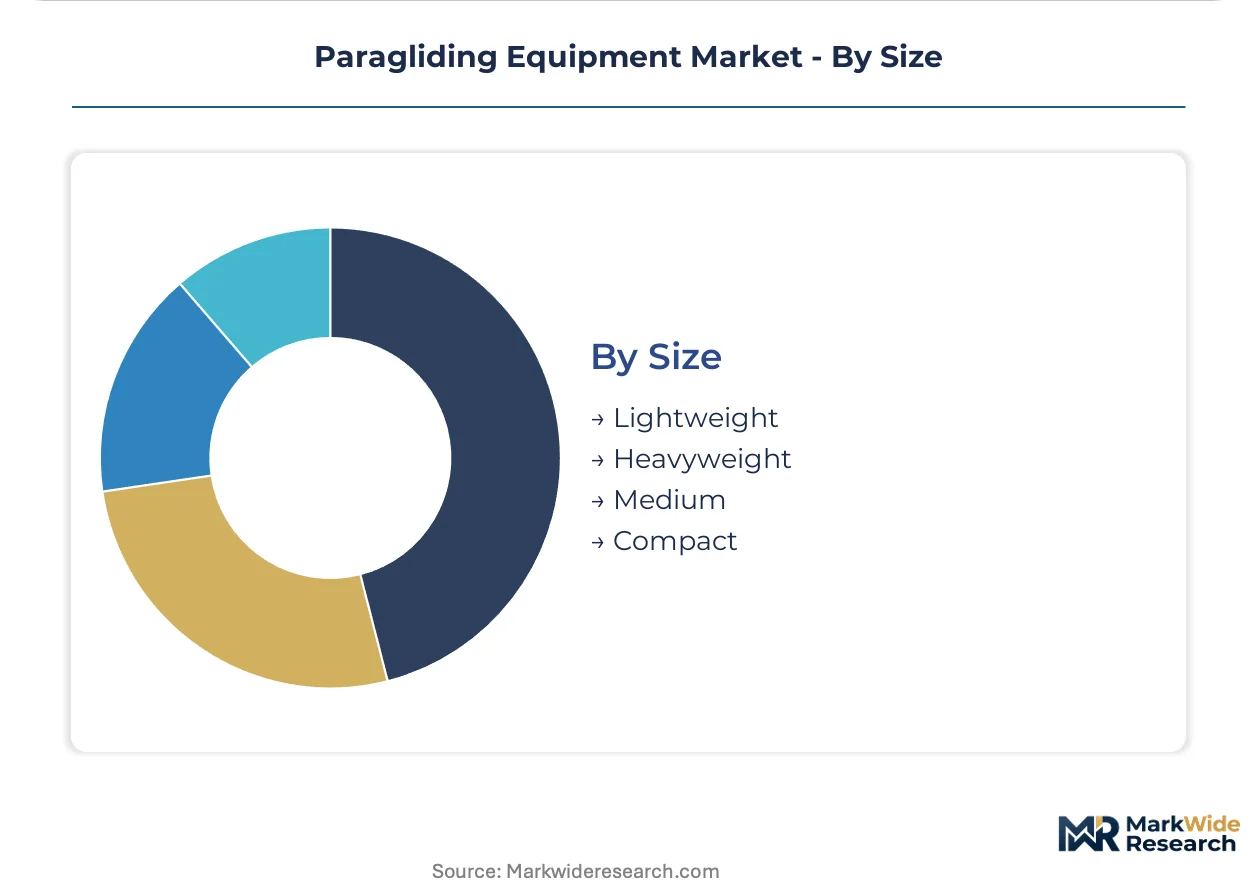
Size:
Launch environment constraints and pilot weight specifications segment demand across fabric density and line rating configurations.
- Lightweight:Ultralight ripstop nylon constructions for hike-and-fly mountain descent. Bio-based polymer thread alternatives are expanding into competition-grade wing construction under EU Green Deal pressures.
- Heavyweight:Reinforced cell structures and higher break-load line ratings for pilots exceeding standard weight ranges. Limited SKU concentration reflects niche demand profile.
- Medium:Standard configurations dominating training academy procurement. Volume scale supports manufacturer margin retention against material cost volatility.
- Compact:Packable designs for travel-intensive recreational users. REACH-compliant material innovation is reducing petrochemical dependency while preserving structural integrity ratings.
Medium configurations dominate unit volume; lightweight designs gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aerodynamic engineering talent concentrates in Slovenian and Swiss R&D clusters, anchoring European innovation leadership while Asian regulatory harmonization creates new export corridors for EN-compliant manufacturers.
Switzerland
Swiss precision manufacturing anchors European distribution networks through direct-to-school channel control. EASA frameworks enforce supply chain carbon intensity disclosure alongside traditional airworthiness metrics. The Interlaken and Bernese Oberland alpine regions concentrate training academy procurement for EN-A and EN-B rated fleet compositions.
France
French destination tourism infrastructure in Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur expands accessible launch sites and rental-to-purchase conversion programs. REACH-compliant material innovation pressures domestic manufacturers to document petrochemical dependency reduction. Annecy and Chamonix clusters dominate instructional market liability-driven equipment selection.
Germany
German instructional markets specify conservative EN-A fleet compositions based on student injury liability frameworks. The EU Green Deal accelerates bio-based ripstop nylon trials while preserving 50-300 kg break load ratings. Bavarian and Baden-Württemberg training academies generate steadiest recurring demand through direct manufacturer relationships.
Austria
Austrian alpine destination investments expand launch site networks pulling first-time participants into equipment purchase funnels. National aviation regulators align with EASA certification frameworks to streamline cross-border market access. Tyrol and Salzburg regions concentrate commercial rental fleet refresh cycles tied to tourist throughput.
United States
US adventure sports participants enter through tandem flight experiences at western mountain destinations. FAA Part 103 ultralight classification divergence from EN standards forces parallel testing tracks for European manufacturer entry. Colorado and California clusters exhibit strongest personal use sales seasonality compressing demand into narrow thermal windows.
Paragliding Equipment Market Competitive Environment
Top-tier vendors anchor EN-D competition and lightweight mountain descent tiers, while mid-tier specialists populate EN-A through EN-C training and recreational segments. Market structure exhibits moderate concentration around alpine-region engineering clusters with limited Asian manufacturing penetration. Three archetypes dominate: Swiss precision fabricators with direct-to-school distribution, Slovenian R&D-intensive cell structure specialists, and New Zealand-based lightweight design innovators. Competitive moves concentrate on training academy channel capture and bio-based material substitution partnerships under EU regulatory pressure.
Within the premium-tier vector, Ozone Paragliders represents New Zealand-based lightweight mountain descent leadership, while Advance Thun AG anchors Swiss precision manufacturing archetypes. Nova Performance Paragliders occupies the Slovenian R&D-intensive position emphasizing cell structure aerodynamics. These three exemplify how geographic engineering clusters translate into distinct competitive positioning across certification tiers and distribution channels.
| Leading Market Players |
|---|
| Ozone Paragliders |
| Advance Thun AG |
| Nova Performance Paragliders |
| Gin Gliders |
| Skywalk GmbH & Co. KG |
| Dudek Paragliders |
| Apco Aviation Ltd. |
| Supair |
| Gradient |
| Others |
Value Chain & Pricing Dynamics
Training academy procurement concentration in Germany and Austria anchors contract-based pricing models that bundle fleet replacement with instructor certification programs. This buyer archetype's volume scale and recurring demand patterns grant manufacturers pricing power against fragmented personal-use purchasers.
Pricing Analysis
Equipment-plus-service bundling dominates training academy channels while personal-use transactions favor unbundled component sales. Three-tier pricing structure across premium EN-D competition wings, standard EN-B recreational configurations, and economy EN-A training tiers separates buyer segments by certification grade and performance requirements. Pricing pressure stems from REACH-compliant bio-based material trials raising input costs without immediate scale economies. Adventure sports participants in the rental-to-purchase funnel exhibit highest price sensitivity; competition pilots sourcing through Slovenian R&D clusters show lowest.
Supply Chain Analysis
Reserve parachute repacking services and harness refurbishment flows create reverse-logistics revenue streams for certified service centers in Switzerland and France. Ripstop nylon fabric production concentrates in Germany, Italy, and China; polyester line manufacturing clusters in Austria and Slovenia. Petrochemical feedstock dependency draws from oil-derived supply chains exposed to energy price volatility. Single-source vulnerability runs through European EN certification testing capacity bottlenecks. Distribution runs through direct-to-school manufacturer relationships bypassing retail markup.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between EU Green Deal compliance costs in alpine manufacturing clusters and emerging Asian regulatory adoption of EASA frameworks creates margin expansion opportunities for EN-certified exporters.
For Market Incumbents: Deploy backward integration into bio-based ripstop polymer supply to deflect REACH cost pressures from petrochemical substitution mandates. Consolidate direct-to-school channel control in Bavarian and Baden-Württemberg training academy networks before emerging entrants replicate the model. Certification investment in EASA-Asia harmonization protocols protects against parallel testing track proliferation. For New Entrants and Emerging Players: Training academy fleet operators in Austria and Tyrol represent the most penetrable channel partner type for contract-based entry. White-space exists in lightweight mountain descent equipment cross-pollination with speed-flying designs for technical alpine users. Go-to-market execution should prioritize commercial rental fleet refresh cycles at French destination tourism sites over saturated personal-use retail. For Investors and Strategic Acquirers: Aerospace-adjacent equipment manufacturers are the most active acquirer in this space, seeking EN certification infrastructure for adjacent ultralight aviation entry. Long-term viability hinges on bio-based material substitution at scale within the projection horizon. Acquisition target archetype: Slovenian cell-structure R&D specialists with existing EASA compliance documentation. Signal to watch: Asian regulator adoption timelines for EN standard harmonization as inflection indicator for export corridor expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-based Material Certification | EU Green Deal compliance unlocks alpine manufacturer access to EASA-sanctioned supply chains. |
| Direct-to-School Channel Expansion | Bypassing retail markup in German instructional markets locks in recurring fleet replacement contracts. |
| EASA-Asia Regulatory Harmonization | Streamlined export eligibility reduces parallel testing costs for European EN-compliant manufacturers. |
| Lightweight Mountain Descent Convergence | Cross-pollination with speed-flying equipment opens technical tiers for advanced alpine competition pilots. |
| Training Academy Liability Partnership | Conservative EN-A fleet specifications in Austrian markets reduce manufacturer product liability exposure. |
Study Parameters
Coverage spans European alpine regions and emerging Asian markets, with primary inputs from each. The analysis combines structured interviews with training academy fleet managers, EN certification laboratory technical directors, ripstop nylon procurement leads at textile manufacturers, and adventure tourism destination operators with secondary validation. Sources include EASA airworthiness directive databases, EU Green Deal implementation filings, REACH compliance registries, and customs trade data for paragliding equipment categories. Bottom-up academy fleet sizing and top-down regional participation estimates were triangulated against manufacturer shipment disclosures.
Granularity-level modeling disaggregated volume and value across the analysis window by EN certification tier, deployment channel, and pilot weight-class configuration. Segmentation dimensions included product type hierarchy, end-user risk tolerance archetypes, and geographic regulatory cluster alignment. CAGRs were derived from replacement cycle analysis tied to certification expiry intervals and thermal window seasonality patterns. Industry-specific forecast inputs incorporated EASA-Asia harmonization adoption curves and bio-based material substitution trial outcomes.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petrochemical price volatility and Asian regulatory convergence timing. Forecasts reflect documented assumptions around alpine tourism infrastructure investment continuity and EN standard revision schedules. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Skiing Equipment Market
Outdoor and Adventure Activities
United States and Europe Horse Racing Market
Outdoor and Adventure Activities
Adventure Gear Market
Outdoor and Adventure Activities
Speed Chute Market
Outdoor and Adventure Activities
Outdoor Living Product Market
Outdoor and Adventure Activities
Global Personal Watercraft Market
Outdoor and Adventure Activities
North America Personal Watercraft Market
Outdoor and Adventure Activities
Hammocks Market
Outdoor and Adventure Activities
North America Climbing Gears Market
Outdoor and Adventure Activities
Kitesurf Kites Market
Outdoor and Adventure Activities
Leisure Centers Market
Outdoor and Adventure Activities
Adventure Sports and Activities Market
Outdoor and Adventure Activities
US Spectator Sports Market
Outdoor and Adventure Activities
Global Climbing Holds Market
Outdoor and Adventure Activities
Hiking Gear and Equipment Market
Outdoor and Adventure Activities
Global Water Bikes Market