
 Middle-East and Africa Cereal Bar Market | 2026-2036
Middle-East and Africa Cereal Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Cereal Bar Market Foresight
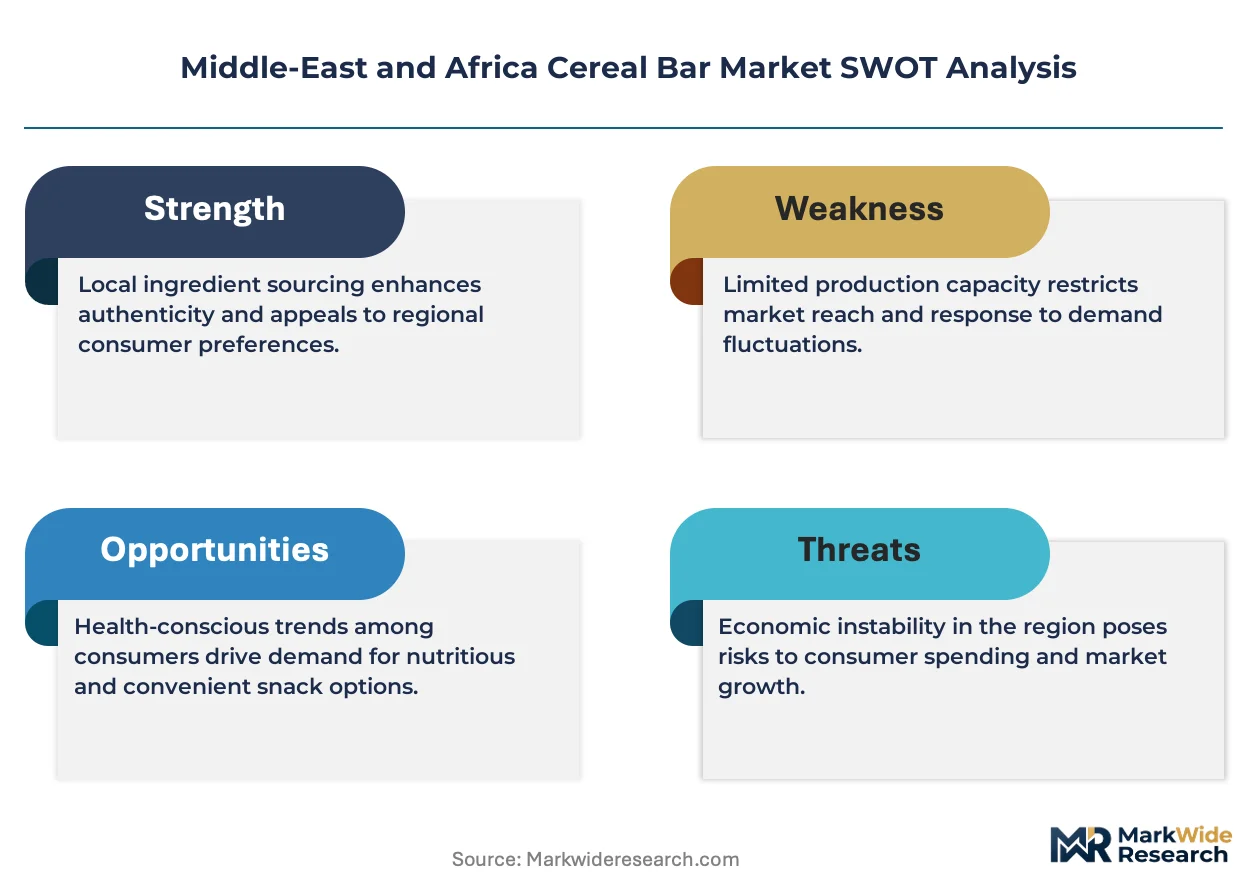
Clean-label formulation is narrowing the gap between premium and mass-market cereal bars across Middle-East and Africa manufacturing lines. General Mills Inc. leverages its supply chain scale to secure consistent oat and nut sourcing for regional production. Nestlé S.A. anchors its portfolio through localized R&D facilities in Dubai that adapt sweetness profiles to Gulf palates. Mars Incorporated differentiates via protein fortification technologies targeting athlete segments in Kenya and Nigeria.
A cereal bar is a baked or cold-pressed ready-to-eat snack comprising grains, binders, and functional additives, typically containing 150-300 calories per serving with shelf stability achieved through moisture-controlled packaging and lipid barrier films. Granola bars dominate volume across Middle-East and Africa retail channels due to lower ingredient costs and established consumer familiarity. Protein bars represent the fastest-growing product type as gym culture expands in urban South Africa and the Gulf states. Online retail channels capture disproportionate margin pools by eliminating distributor markups in markets with fragmented traditional trade.
Saudi Arabia's SFDA and South Africa's Department of Health enforce divergent sugar-content thresholds, forcing manufacturers to maintain parallel formulations or reformulate for cross-border compliance. Egypt's food safety authority applies import inspection regimes that delay European and American brand entry into North African markets. Stakeholders must monitor regulatory harmonization talks within the African Continental Free Trade Area to anticipate whether unified standards will consolidate or fragment production strategies.
Market Dynamics
The Middle-East and Africa Cereal Bar Market is being fundamentally restructured by divergent regulatory frameworks that force manufacturers to maintain parallel production lines rather than unified regional supply chains.
Growth Catalysts
- Gym Culture Expansion:Fitness center proliferation in Johannesburg and Lagos is creating dedicated protein bar demand among athlete segments that previously relied on unbranded nutrition sources.
- SFDA Front-of-Pack Rules:Saudi Arabia's tightened labeling requirements are accelerating clean-label reformulation investments that improve export readiness across Gulf Cooperation Council markets.
- E-Commerce Penetration:Online retail channels in the United Arab Emirates and Kenya are capturing margin pools by eliminating fragmented distributor markups in traditional trade networks.
Market Restraints
- Input Cost Volatility:Oat and nut sourcing from East African agricultural zones faces climate-driven yield instability that compresses manufacturer margins during drought cycles.
- Regulatory Fragmentation:Egypt's import inspection regimes create extended customs delays that deter European brand entry into North African retail channels.
- Substitution Threat:Traditional date-based energy snacks in Gulf states and roasted plantain chips in West Africa retain price advantages over packaged cereal bars.
Strategic Opportunities
- AfCFTA Harmonization:African Continental Free Trade Area regulatory talks present pathways to consolidated production strategies if sugar-content thresholds align across member states.
- Localized R&D Facilities:Dubai-based sweetness adaptation laboratories enable Gulf-specific palate engineering that mass-market imports cannot replicate.
- Cold-Press Technology Convergence:Combining HPP pasteurization with clean-label binding systems opens raw-format positioning in South Africa's premium organic channels.
Industry Challenges
- Formulation Talent Scarcity:Food technologists capable of balancing moisture-controlled packaging with lipid barrier film integration remain concentrated in South Africa and the UAE.
- Parallel Line Capex:Manufacturers serving both Saudi Arabia and South Africa must duplicate production assets to satisfy divergent Department of Health sugar ceilings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Cereal Bar Market |
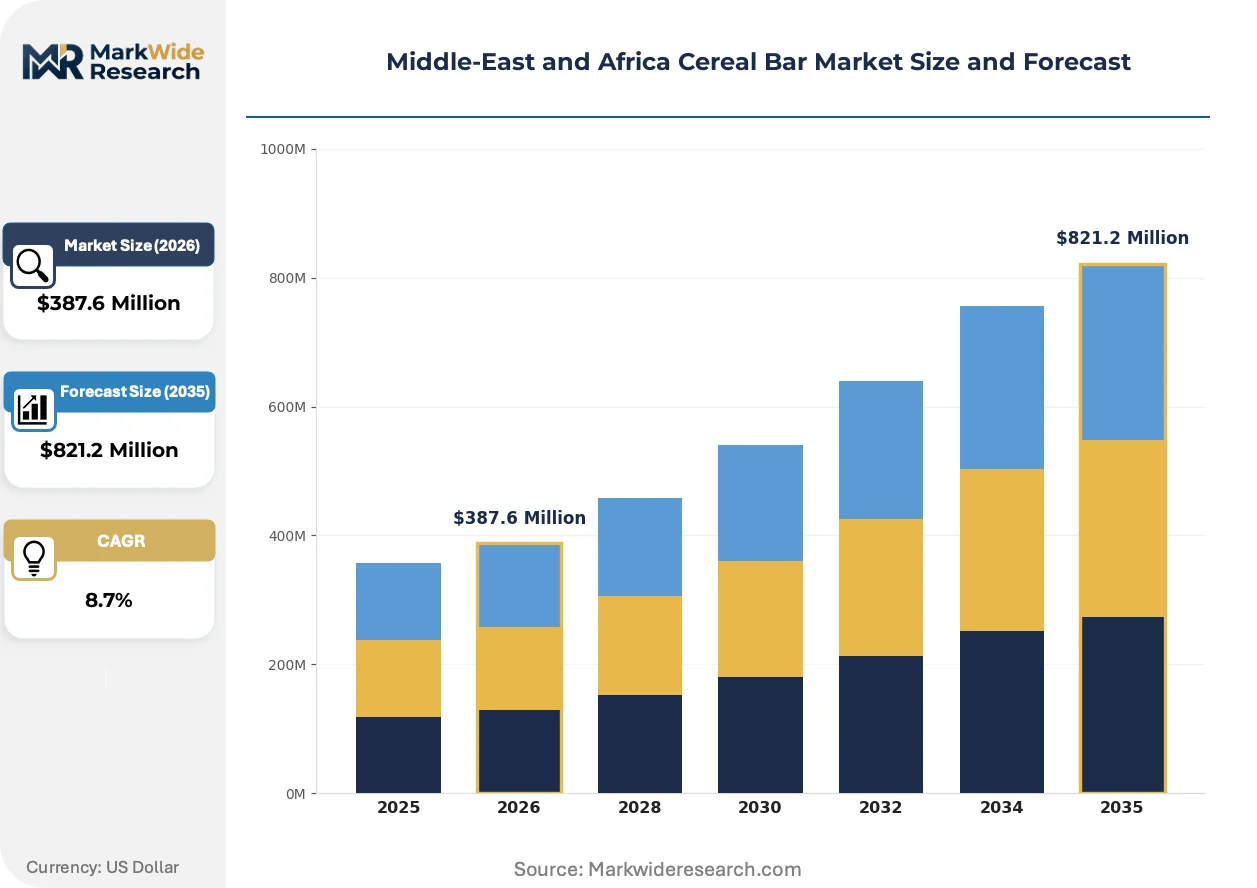
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granola Bars, Protein Bars, Nut Bars, Fruit Bars Distribution Channel: Supermarkets, Specialty Stores, Online Retail, Convenience Stores End User: Adults, Children, Athletes, Health-Conscious Consumers Packaging Type: Bags, Boxes, Wrappers, Multipacks |
| Companies Covered | General Mills Inc., The Kellogg Company, Nestlé S.A., Mars Incorporated, Mondelēz International, Inc., Clif Bar & Company, WK Kellogg Co, Kind LLC, PepsiCo Inc., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Cereal Bar Market Shifts & Advancements
Cold-press manufacturing and regulatory adaptation technologies are compressing the traditional gap between premium health-positioned bars and mass-market formulations across Middle-East and Africa production facilities.
HPP pasteurization systems are collapsing the shelf-stability advantage previously held by baked cereal bars. South African organic retailers and UAE health-food chains are adopting cold-pressed formats at accelerated rates. This technology is collapsing the premium pricing umbrella that protected early-mover clean-label brands in Gauteng and Western Cape distribution networks.
Saudi Arabia's SFDA front-of-pack labeling mandate is forcing disclosure of added sugars and sodium content on all processed food packaging. Manufacturers serving Gulf markets now reformulate core recipes to avoid red-flag nutrient warnings that deter health-conscious consumers. Protein bar segments targeting gym enthusiasts in Riyadh and Jeddah are responding fastest by swapping glucose syrups for date paste binders.
Urban professionals in Cairo and Lagos are compressing traditional meal occasions into distributed snacking events throughout workdays. Convenience store chains in Egypt and Nigeria are expanding chilled grab-and-go sections that displace sit-down breakfast occasions. This behavioral shift is most visible among banking and technology sector employees in Lagos Island and Cairo's New Administrative Capital commercial zones.
Middle-East and Africa Cereal Bar Market Segmentation
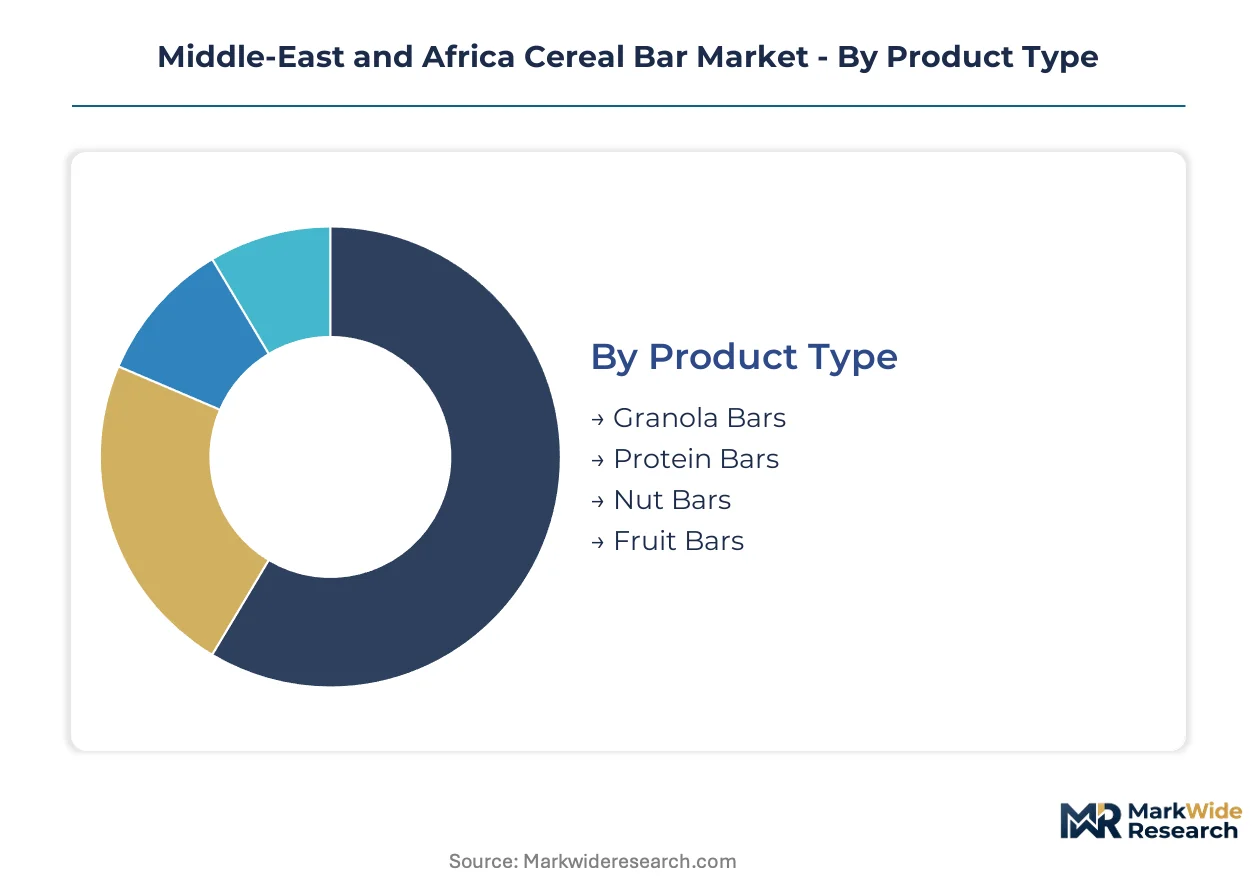
Segmentation in the Middle-East and Africa Cereal Bar Market reveals how divergent consumer occasions and channel economics create distinct margin pools. Manufacturers must align formulation investments and packaging formats to specific demand clusters rather than treating the region as a uniform consumption bloc.
Product Type:
Cost tier structures the competitive landscape across manufacturing lines, with ingredient complexity and protein fortification driving price stratification.
- Granola Bars:Baked oat-based formulations with honey or syrup binders dominate retail shelf space due to lower per-unit production costs. Demand concentrates in South Africa's Gauteng and Western Cape provinces where established breakfast routines favor familiar formats, though margin compression from private-label competition limits premium positioning.
- Protein Bars:Whey or plant-protein fortified bars with 15-25g protein content target gym culture expansion in Johannesburg and Lagos. Athlete segments in Kenya and Nigeria drive the steepest volume expansion as fitness center proliferation displaces unbranded nutrition sources.
- Nut Bars:Almond, cashew, or mixed nut formulations with minimal grain content appeal to paleo and ketogenic diet adherents in UAE health-food channels.
- Fruit Bars:Date-paste or dried fruit binders without added sugars align with SFDA front-of-pack labeling compliance requirements in Saudi Arabia.
Granola bars command the established base. The steepest expansion runs through protein bars.
Distribution Channel:
Channel selection determines margin capture efficiency, with modern trade and digital routes offering divergent paths around fragmented traditional networks.
- Supermarkets:Hypermarket and supermarket chains in Cairo and Lagos provide branded visibility and promotional scale for mass-market launches. Chilled grab-and-go sections are expanding across Egypt and Nigeria as urban professionals compress meal occasions into distributed snacking events.
- Online Retail:E-commerce platforms in the United Arab Emirates and Kenya eliminate distributor markups that erode margins in fragmented traditional trade, capturing disproportionate value pools through direct-to-consumer fulfillment.
- Specialty Stores:Health-food and organic retailers in South Africa's premium channels stock cold-pressed and clean-label formats.
- Convenience Stores:Forecourt and urban convenience formats in banking and technology commercial zones serve impulse purchase occasions.
Supermarkets anchor volume throughput. Online retail is gaining share fastest through margin structure advantages.
End User:
Customer type dictates formulation priorities, with functional requirements varying sharply between recreational consumption and performance nutrition.
- Adults:Working professionals in Cairo's New Administrative Capital and Lagos Island commercial zones drive snacking frequency as traditional breakfast occasions fragment.
- Athletes:Gym enthusiasts in Riyadh and Jeddah demand protein fortification technologies that Mars Incorporated targets through specialized product lines.
- Health-Conscious Consumers:Clean-label seekers respond to Saudi Arabia's SFDA labeling mandates by avoiding red-flag nutrient warnings on packaging.
- Children:School-lunch and after-school occasions favor lower-sugar formulations with fortified micronutrients.
Adults represent the volume foundation. Athletes show the steepest expansion trajectory as fitness infrastructure spreads.
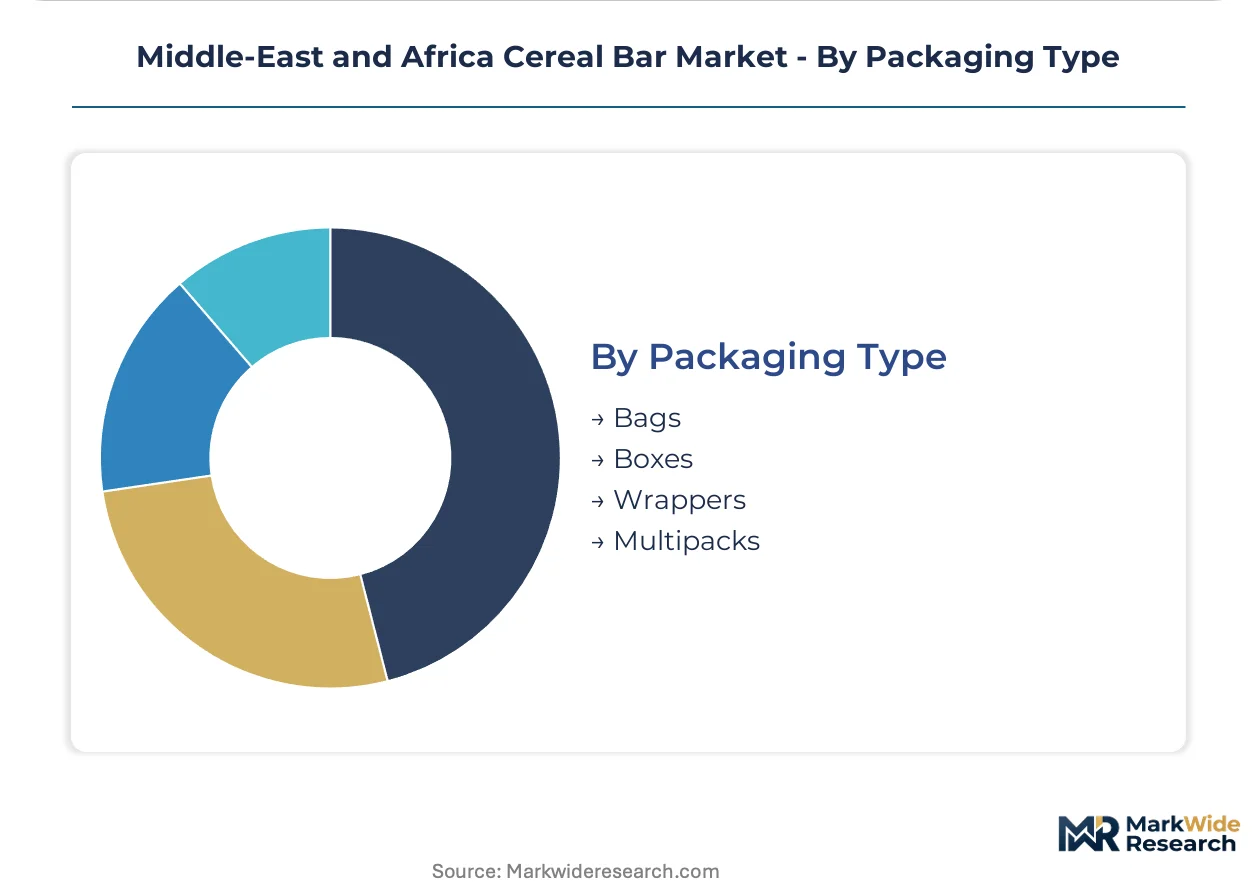
Packaging Type:
Packaging configuration shapes shelf-life economics and consumption occasion targeting across climate-variable distribution environments.
- Wrappers:Individual flow-wrap packaging with moisture-controlled barrier films achieves 150-300 calorie serving stability in high-humidity Gulf climates.
- Multipacks:Bundled formats reduce per-unit packaging costs and drive pantry-loading behavior in South African suburban households.
- Boxes:Display-ready cartons serve retail merchandising requirements in supermarket chains.
- Bags:Flexible pouch formats accommodate bulk and private-label positioning in discount channels.
Wrappers dominate single-serve occasions. Multipacks are expanding most quickly through household stock-up behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UAE-based manufacturers export reformulated clean-label bars to Saudi Arabia and Qatar under harmonized Gulf Cooperation Council standards. South Africa ships oat-based formulations northward into Kenya and Nigeria through regional distribution hubs.
Saudi Arabia
SFDA front-of-pack labeling mandates are accelerating reformulation investments among Riyadh-based producers. The regulator's red-flag nutrient warning system forces disclosure of added sugars on all processed food packaging. Jeddah's Red Sea logistics corridor handles inbound oat and nut shipments for regional manufacturing lines.
United Arab Emirates
Dubai-based sweetness adaptation laboratories enable Gulf-specific palate engineering that mass-market imports cannot replicate. MOHAP food safety standards align closely with Saudi SFDA frameworks, easing cross-border product flows. Abu Dhabi's Khalifa Industrial Zone hosts cold-press manufacturing facilities serving premium organic channels across the Gulf states.
South Africa
The Department of Health enforces sugar-content thresholds that diverge from Saudi standards, forcing parallel production strategies. Gauteng province concentrates manufacturing capacity for granola bar volume production. Western Cape health-food retailers drive adoption of HPP-pasteurized cold-pressed formats among affluent organic consumers.
Egypt
Cairo's New Administrative Capital commercial zones exhibit compressed meal occasions shifting toward distributed snacking among banking sector employees. The country's food safety authority applies import inspection regimes that delay European brand entry into North African retail channels. Alexandria's port facilities handle delayed customs clearances for inbound cereal bar ingredients.
Nigeria
Lagos Island technology sector professionals drive protein bar demand as gym culture displaces unbranded nutrition sources. The country's national food and drug regulator maintains fragmented standards that complicate cross-border trade with neighboring West African states. Kano's agricultural zones supply peanut and sesame inputs for local binding systems.
Middle-East and Africa Cereal Bar Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented traditional trade networks and emerging digital routes. The vendor base clusters around three strategic archetypes: multinational CPG conglomerates with supply chain scale, regional clean-label specialists with localized R&D capabilities, and private-label manufacturers serving discount channels. Dominant competitive moves include portfolio diversification into protein-fortified formats and strategic partnerships with fitness center distribution networks.
Among North American CPG conglomerates, General Mills Inc., Mars Incorporated, and Nestlé S.A. occupy positions that exemplify scale-driven supply chain control. General Mills Inc. represents the multinational archetype with regional production integration. Mars Incorporated anchors the protein-fortification specialist tier targeting athlete segments. Nestlé S.A. sits within the localized R&D investment category through Dubai-based sweetness adaptation facilities.
| Leading Market Players |
|---|
| General Mills Inc. |
| The Kellogg Company |
| Nestlé S.A. |
| Mars Incorporated |
| Mondelēz International, Inc. |
| Clif Bar & Company |
| WK Kellogg Co |
| Kind LLC |
| PepsiCo Inc. |
| Others |
Supply & Pricing Matrix
Regulatory fragmentation between Saudi Arabia's SFDA and South Africa's Department of Health forces manufacturers to maintain parallel production lines, widening pricing spreads between Gulf-compliant and Sub-Saharan formulations while fragmenting regional supply chain consolidation.
Pricing Analysis
Cold-press manufacturing technology commands a 40-60% premium over conventional baked formats across UAE health-food channels and South African organic retailers. Three-tier pricing structure across premium clean-label, standard granola, and economy private-label segments stratifies by protein fortification level and binding system complexity. Cost compression in the standard tier is intensifying as East African oat and nut sourcing faces climate-driven yield instability. Price sensitivity concentrates among mass-market consumers in Egypt and Nigeria, while Gulf-state gym enthusiasts exhibit low elasticity for athlete-positioned protein bars.
Supply Chain Analysis
Import inspection regimes limiting European brand entry into Egypt create supply chokepoints that favor regional manufacturers with established customs relationships. Raw material sourcing draws from East African agricultural zones for oats and nuts, UAE logistics hubs for specialty binders, and Kano's peanut and sesame zones for local West African production. Single-source vulnerability centers on oat supply concentration during drought cycles. Distribution runs through Dubai-based export platforms serving Gulf Cooperation Council markets and Johannesburg distribution hubs feeding Kenya and Nigeria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle-East and Africa Cereal Bar Market sits in early-cycle expansion as gym culture penetration in Lagos and Johannesburg displaces unbranded nutrition sources with packaged alternatives.
For Market Incumbents: Harden supply chain resilience through backward integration into East African oat sourcing to offset climate-driven yield volatility. Secure Dubai-based R&D capacity for Gulf-specific sweetness adaptation before regional specialists consolidate this capability. Defend against private-label erosion in South Africa's Gauteng province by locking exclusive retail shelf agreements with chilled grab-and-go section operators. For New Entrants and Emerging Players: Establish a beachhead in Nigeria's protein bar segment where fitness center proliferation outpaces branded supply availability. Target Egypt's convenience store channels in Cairo's New Administrative Capital banking zones where distributed snacking behavior shifts fastest. Deploy direct-to-consumer fulfillment through Kenyan e-commerce platforms to bypass fragmented traditional distributor networks. For Investors and Strategic Acquirers: Regional clean-label specialists with localized Dubai R&D facilities and established SFDA compliance track records offer the strongest acquisition positioning. Long-term viability hinges on AfCFTA regulatory harmonization consolidating fragmented sugar-content thresholds across member states. Watch for signals of unified standards emerging from continental trade talks as the inflection indicator for production strategy consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | SFDA front-of-pack compliance enables Gulf Cooperation Council market access without parallel line duplication. |
| Cold-Press Manufacturing Scale-Up | HPP pasteurization adoption in Abu Dhabi's Khalifa Industrial Zone collapses shelf-stability premiums held by baked formats. |
| Direct-to-Consumer Channel Launch | E-commerce penetration in Kenya and UAE eliminates distributor markups that erode margins in fragmented traditional trade. |
| Fitness Center Distribution Partnership | Specialized placement in Johannesburg and Lagos gyms captures athlete segments displacing unbranded nutrition sources. |
| Backward Integration into Binding Inputs | Upstream control over Kano peanut and sesame supply secures cost stability for West African production lines. |
Research Methodology
Desk research of customs trade records, retail audit databases, and regulatory filing repositories preceded structured interviews with cereal bar brand managers, category buyers at Cairo and Lagos supermarket chains, Dubai-based food technologists, and East African agricultural procurement leads. Primary fieldwork with supply chain planners and packaging engineers validated secondary findings on moisture-controlled barrier film integration challenges. Bottom-up volume modeling triangulated against top-down macro consumption trend analysis.
Assumptions around AfCFTA regulatory harmonization progress and Gulf Cooperation Council standards alignment were held fixed across baseline scenarios while climate-driven agricultural yield volatility was stress-tested in sensitivity runs. Segmentation dimensions included product type, distribution channel, end user archetype, and packaging format across the projection horizon. CAGRs derived from fitted growth curves incorporating gym culture penetration rates and e-commerce adoption trajectories. Forecast inputs incorporated SFDA enforcement intensity and cold-press technology cost decline curves.
Sensitivities concentrate around AfCFTA timeline delays, SFDA labeling rule expansion to additional nutrients, and drought frequency escalation in East African oat-growing zones. Cross-checking against Nielsen retail audit data for comparable emerging market snack categories is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Low-Calorie Sweet Treats Market
Snacks
United Kingdom Snack Bar Market
Snacks
Low Calorie Granola Market
Snacks
Kale Chips Market
Snacks
Saudi Arabia French Fries Market
Snacks
South America Protein Bar Market
Snacks
Savory Snacks Market
Snacks
UAE Snack Bar Market
Snacks
Crackers Market
Snacks
Fried Potato Chips Market
Snacks
Organic Snack Food Market
Snacks
Asia-Pacific Cereal Bar Market
Snacks
Middle East and Africa Snack Food Market
Snacks
Oat-Based Snacks Market
Snacks
Italy Snack Bar Market
Snacks
Dairy Snacks Market