
 Asia-Pacific Smart Manufacturing Market | 2026-2036
Asia-Pacific Smart Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Smart Manufacturing Market Outlook
Industrial equipment distribution across Southeast Asia is fragmenting as local system integrators gain bargaining power against traditional distributors. ABB Ltd leverages its robotics service network to anchor premium positioning in Thailand and Vietnam. Siemens AG competes through its digital twin platform, while Mitsubishi Electric Corporation dominates motion control supply to Japanese automotive transplant factories in Indonesia.
Asia-Pacific smart manufacturing integrates cyber-physical systems, industrial IoT sensors, and AI-driven analytics to automate production workflows, optimize asset utilization, and enable real-time decision-making across factory floors. Machine Learning algorithms process vibration and thermal data from equipment to predict failures before unplanned downtime occurs. Automation Solutions capture the largest revenue pool among product types due to retrofit demand across legacy automotive and electronics facilities. Cloud Computing deployments are expanding fastest among technologies as manufacturers seek to reduce on-premise infrastructure capital.
China's MIIT enforces GB standards for industrial data security and interoperable equipment protocols, while Japan's METI promotes Society 5.0 manufacturing roadmaps through JIS certification requirements. South Korea's MFDS coordinates with METI-aligned frameworks for pharmaceutical and medical device smart factory compliance. Stakeholders must monitor which regulatory bloc achieves cross-border data flow agreements first, as this will determine where regional platform investments cluster.
Market Dynamics
China's MIIT dual carbon mandates and GB standard enforcement are compressing factory upgrade timelines across the region, forcing automotive and electronics manufacturers to accelerate energy-efficient automation retrofits or face operational penalties.
Growth Catalysts
- MIIT Dual Carbon Compliance:China's binding GB standards for industrial data security and equipment interoperability are mandating smart factory investments. Automotive OEMs face penalties for non-compliance, driving immediate automation procurement.
- Electronics Manufacturing Corridor Expansion:South Korea's semiconductor and display fabrication clusters around Seoul and Gyeonggi-do are deploying AI-driven predictive maintenance systems to minimize unplanned downtime in 24/7 production environments.
- Industrial IoT Sensor Proliferation:Vibration and thermal monitoring hardware costs have dropped sufficiently to enable retrofit deployment across legacy automotive stamping and assembly lines throughout Thailand and Vietnam.
Market Restraints
- Legacy Equipment Integration Friction:Proprietary protocols in 1990s-era Japanese and Korean machine tools create data extraction barriers. System integrators charge premium fees for protocol translation middleware.
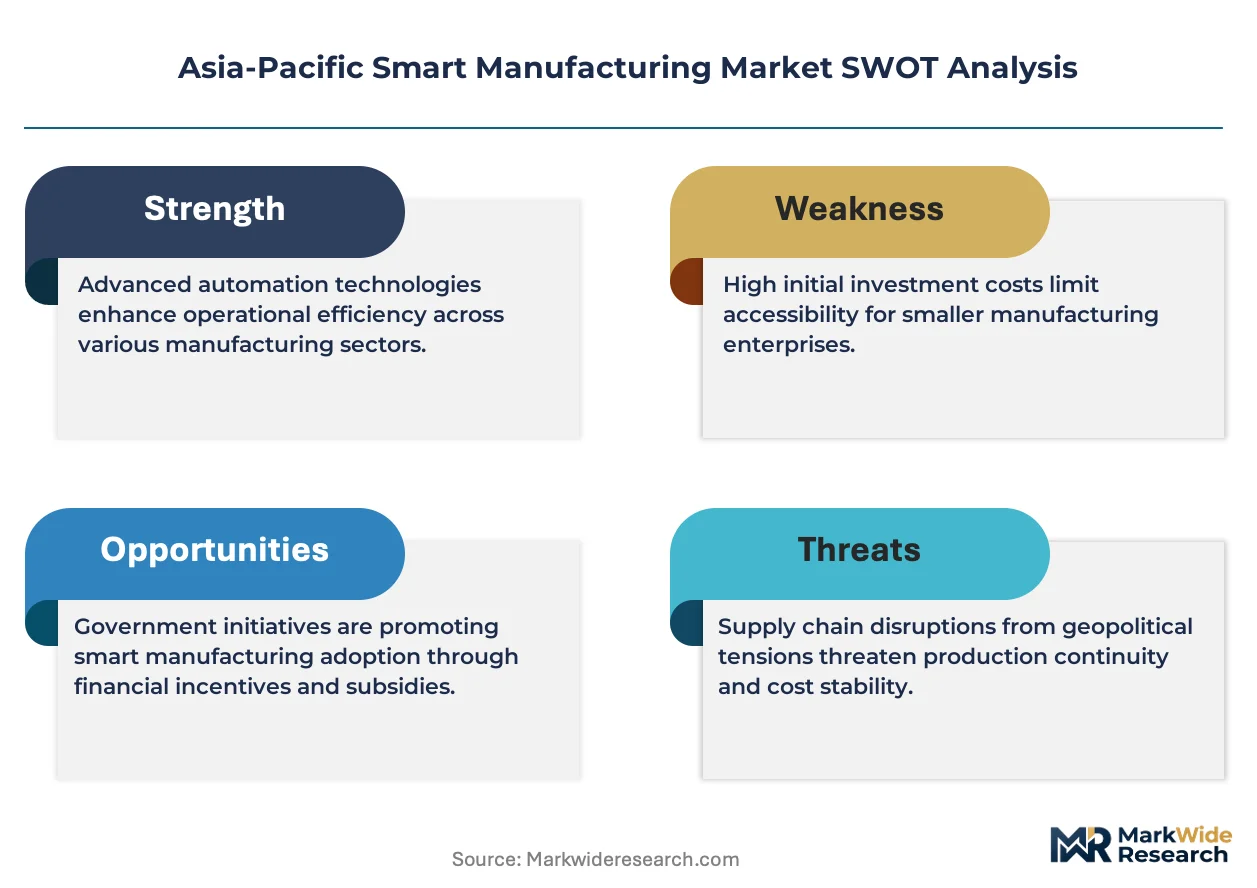
- Semiconductor Component Concentration:Industrial controller and sensor chip supply remains concentrated among Taiwanese and South Korean foundries. Geopolitical tensions threaten just-in-time delivery schedules for automation projects.
- Specialized Technician Scarcity:Cyber-physical system maintenance requires combined mechanical-electrical-software competencies. Vocational training pipelines in Indonesia and Vietnam lag deployment timelines by 18-24 months.
Strategic Opportunities
- Philippines Electronics Assembly Underpenetration:Contract manufacturers in Clark and Cebu industrial zones remain below 15% automation density. Cloud-based manufacturing execution systems offer low-capex entry paths for tier-two suppliers.
- Digital Twin Convergence:Physics simulation software merged with real-time IoT data streams enables virtual commissioning of production lines. Japanese automotive transplant factories in Indonesia are piloting reduced physical prototyping cycles.
- Thailand Board of Investment Incentives:Tax holidays and import duty exemptions for smart factory equipment are attracting Japanese and German automation vendors to establish regional service hubs in Eastern Economic Corridor zones.
Industry Challenges
- Cross-Border Data Flow Uncertainty:Divergent MIIT, METI, and South Korean MFDS data localization requirements complicate regional platform architectures. Manufacturers must maintain separate cloud instances per jurisdiction.
- Certification Timeline Compression:JIS, GB, and KCs mark harmonization remains incomplete. Equipment suppliers face 6-9 month approval delays when deploying identical hardware across Japan, China, and South Korea.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Smart Manufacturing Market |
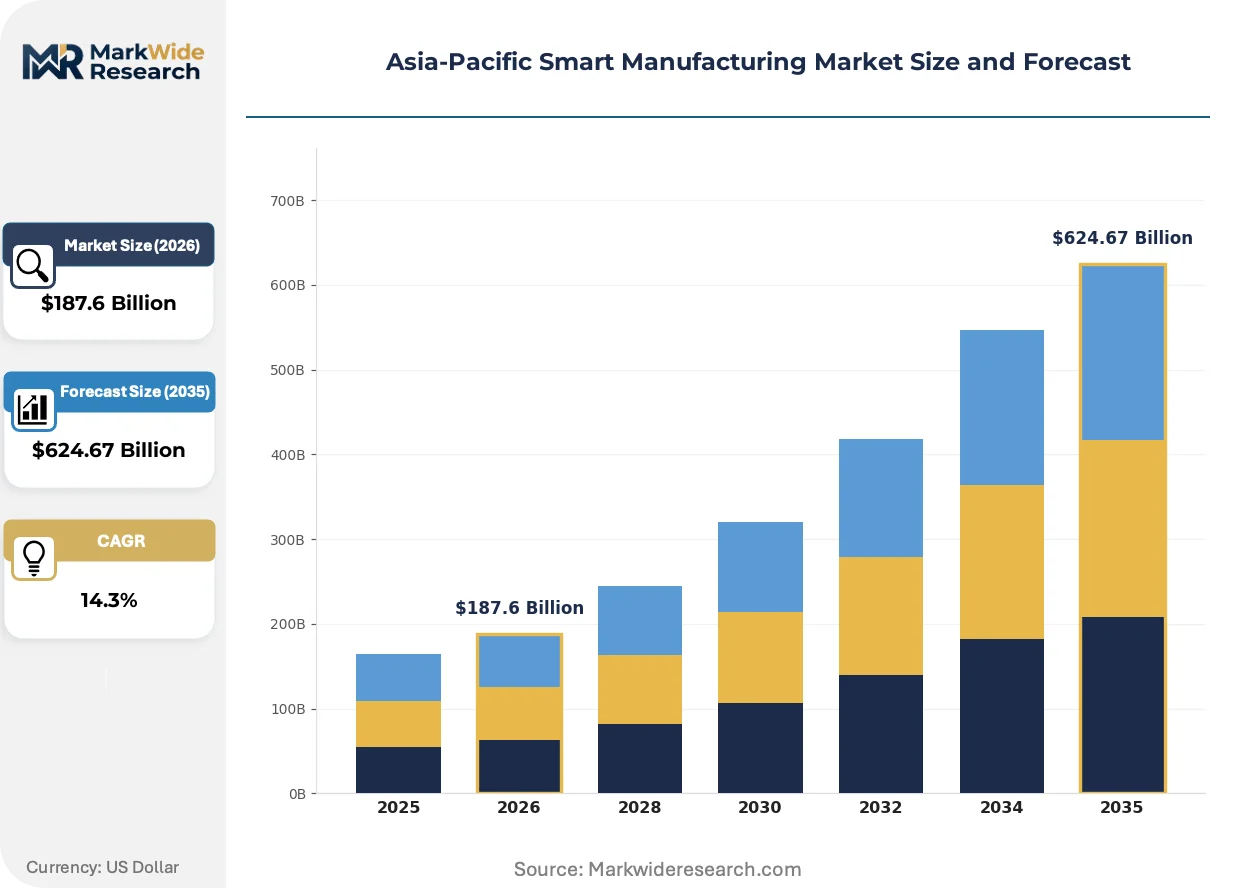
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $624.67 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Robots, IoT Devices, AI Software, Automation Solutions End User: Aerospace, Automotive OEMs, Electronics, Food & Beverage Technology: Machine Learning, Big Data Analytics, Cloud Computing, Cyber-Physical Systems Application: Predictive Maintenance, Quality Control, Supply Chain Optimization, Production Planning |
| Companies Covered | ABB Ltd, Honeywell International Inc., Schneider Electric SE, Rockwell Automation Inc., Siemens AG, FANUC Corporation, Mitsubishi Electric Corporation, Emerson Electric Co., General Electric Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Smart Manufacturing Market Strategic Shifts
Edge computing architectures are displacing centralized cloud processing for latency-sensitive quality inspection tasks, while regulatory blocs compete to establish interoperable data governance frameworks that will determine where regional platform investments concentrate.
Digital twin technology is collapsing the traditional separation between product design and production engineering phases. Automotive OEMs in South Korea and Japan are adopting unified simulation environments that synchronize CAD models with live factory floor data streams. This convergence compresses new model introduction timelines from 18 months to 9 months for powertrain assembly lines.
China's MIIT enforcement of GB/T 22239-2019 cybersecurity classification standards is mandating air-gapped network segments for critical manufacturing infrastructure. Semiconductor fabs in Shanghai and Hefei are deploying zero-trust architecture retrofits to maintain operating licenses. Equipment vendors must now pre-certify hardware against state encryption protocols before installation.
After-sales service unbundling is fragmenting traditional automation vendor revenue models. Thai and Vietnamese electronics contract manufacturers are purchasing hardware through independent distributors while sourcing predictive maintenance analytics from specialized software providers. This disintermediation pressures ABB and Siemens to defend attachment rates through proprietary sensor ecosystems rather than bundled service contracts.
Asia-Pacific Smart Manufacturing Market Segmentation
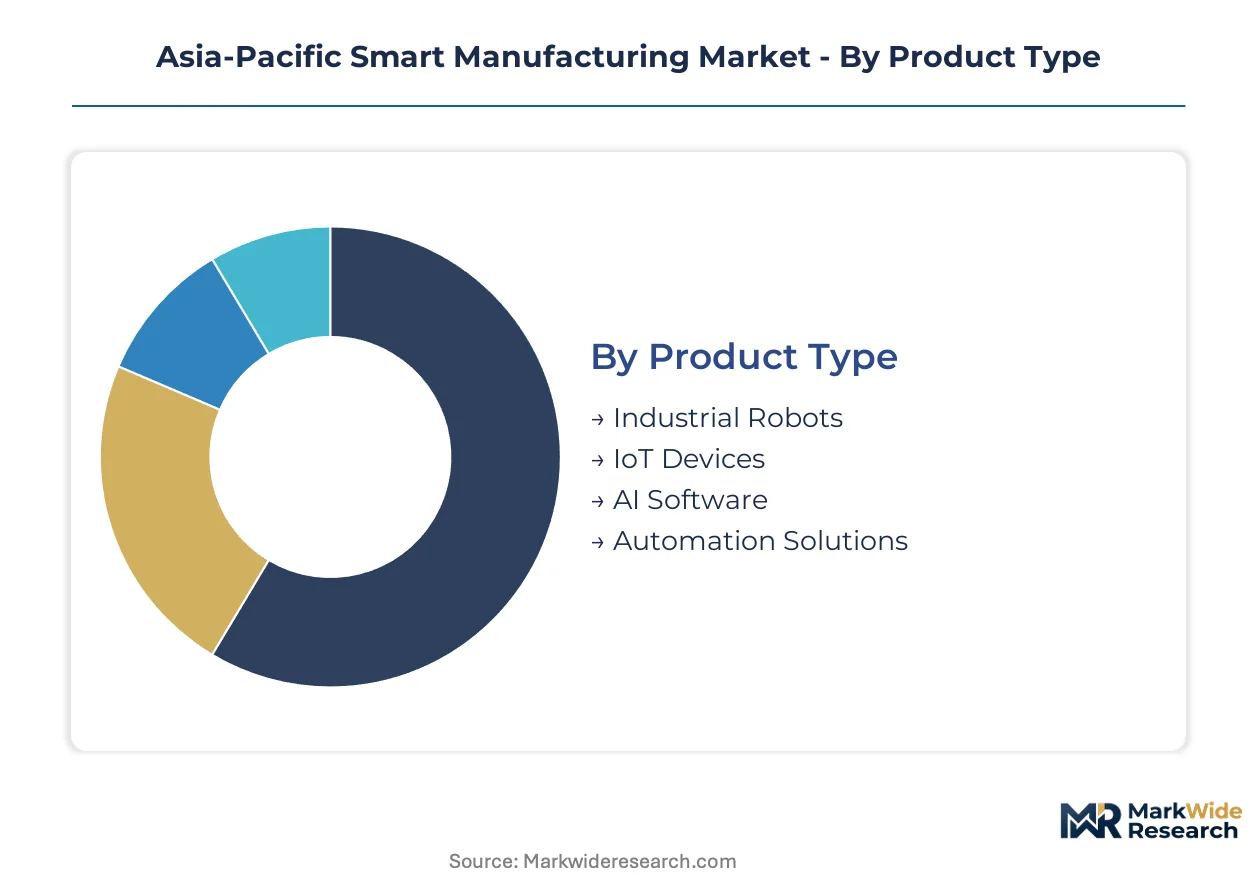
Asia-Pacific smart manufacturing deployment varies sharply by factory vintage, regulatory pressure, and capital intensity. Segmentation reveals where retrofit demand concentrates versus greenfield investment, and which technology stacks command premium pricing.
Product Type:
Industrial buyers select hardware-software bundles based on legacy equipment compatibility and energy efficiency mandates from China's MIIT.
- Industrial Robots:Six-axis articulated arms and collaborative cobots dominate automotive welding and electronics assembly. South Korean automotive OEMs in Gyeonggi-do are standardizing on unified robot fleets to reduce spare parts inventory.
- Automation Solutions:Programmable logic controllers, distributed control systems, and integrated safety networks form the core of factory retrofits. China's GB standards for equipment interoperability are forcing simultaneous controller and sensor upgrades across legacy automotive stamping lines.
- IoT Devices:Vibration, thermal, and current sensors with edge preprocessing capabilities.
- AI Software:Computer vision platforms and predictive analytics engines deployed atop existing automation infrastructure.
The dominant share belongs to Automation Solutions, while AI Software is closing the gap fastest.
End User:
Capital deployment intensity tracks regulatory enforcement pressure and export market access requirements.
- Automotive OEMs:Connected production lines with real-time quality feedback loops are becoming mandatory for MIIT dual carbon compliance. Japanese transplant factories in Thailand's Eastern Economic Corridor are piloting digital twin commissioning to accelerate model changeovers.
- Electronics:Semiconductor fabs and display panel manufacturers operate 24/7 environments where unplanned downtime costs exceed $2 million per hour. Seoul-based memory chip producers are deploying AI-driven predictive maintenance across etching and deposition equipment.
- Aerospace:Precision machining and composite layup automation for tier-one suppliers.
- Food & Beverage:Hygienic design robots and batch traceability systems for export certification.
Electronics captures the largest procurement volume, with Automotive OEMs expanding their automation budgets most aggressively.
Technology:
Architecture choices hinge on latency requirements, data sovereignty constraints, and integration complexity with 1990s-era machine tools.
- Cloud Computing:Manufacturing execution systems and enterprise resource planning extensions are migrating to hybrid deployments. Vietnamese electronics contract manufacturers favor cloud-based MES to avoid on-premise capital expenditure.
- Machine Learning:Supervised learning models trained on historical failure data enable predictive maintenance with 85-90% accuracy. Japanese automotive suppliers in Indonesia are deploying vibration-based bearing failure detection across CNC machining centers.
- Big Data Analytics:Time-series databases and visualization platforms for process optimization.
- Cyber-Physical Systems:Tightly coupled sensor-actuator loops with deterministic real-time control.
Machine Learning leads technology spending, though Cloud Computing is expanding most quickly among mid-tier suppliers.
Application:
Use case prioritization reflects the balance between immediate operational risk reduction and long-term efficiency gains.
- Predictive Maintenance:Vibration and thermal monitoring with ML-based anomaly detection prevents unplanned downtime. South Korean semiconductor fabs around Seoul are mandating predictive maintenance coverage for all critical equipment.
- Quality Control:Automated optical inspection and dimensional verification using computer vision. Thai automotive stamping plants are retrofitting in-line vision systems to reduce manual inspection headcount.
- Supply Chain Optimization:Demand forecasting and inventory positioning algorithms.
- Production Planning:Finite capacity scheduling and dynamic lot sizing systems.
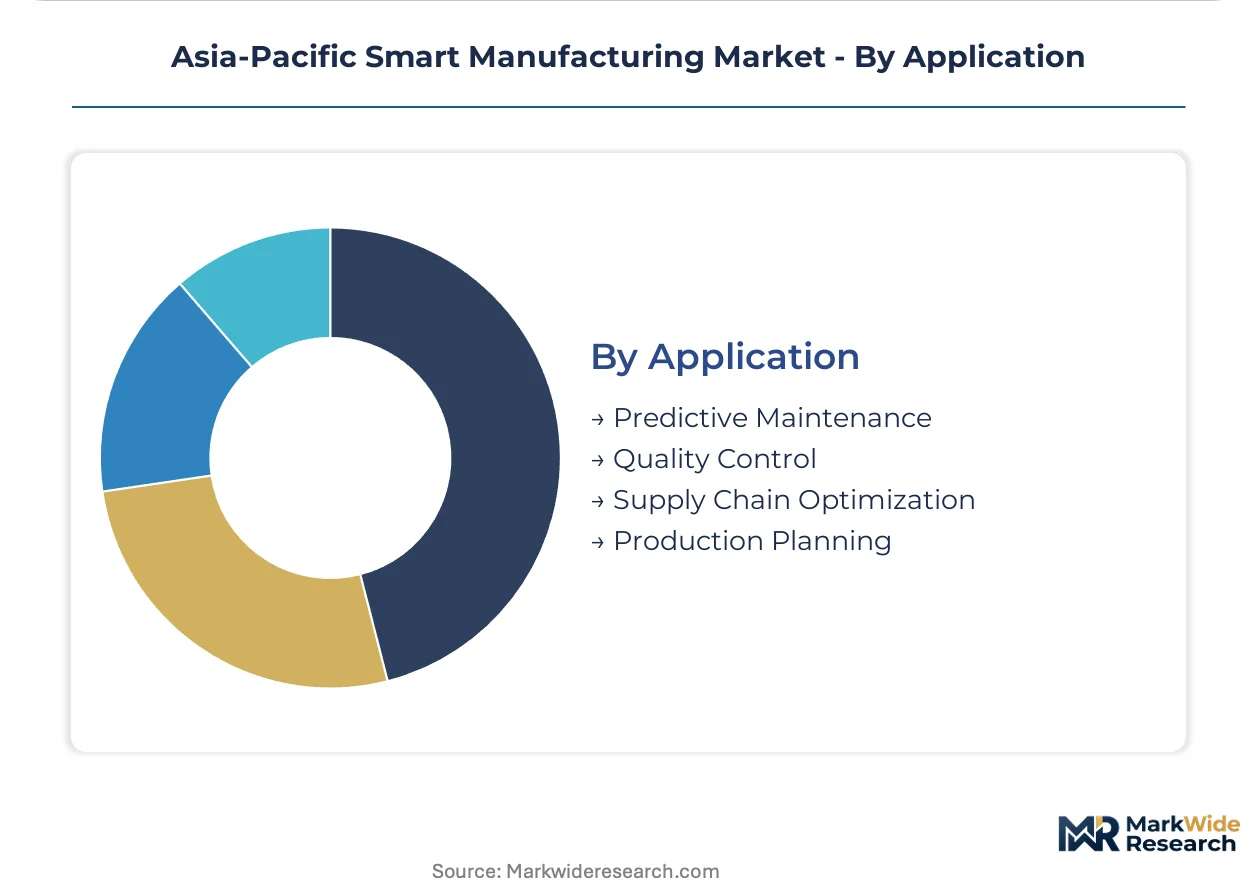
Predictive Maintenance holds the largest installed base, while Quality Control is gaining share fastest among contract manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT dual carbon mandates and GB standard enforcement in China are compressing factory upgrade timelines across Asia-Pacific, forcing automotive and electronics manufacturers to accelerate energy-efficient automation retrofits or face operational penalties.
China
Automotive OEMs in Shanghai and Hefei are retrofitting connected production lines to meet MIIT dual carbon compliance deadlines. GB standards for industrial data security and equipment interoperability mandate simultaneous controller and sensor upgrades. Semiconductor fabs in Yangtze River Delta clusters are deploying zero-trust architecture retrofits to maintain operating licenses under GB/T 22239-2019 cybersecurity classifications.
Japan
Automotive suppliers in Nagoya's Chubu region are deploying vibration-based bearing failure detection across CNC machining centers. METI promotes Society 5.0 manufacturing roadmaps through JIS certification requirements. Tokyo-based electronics manufacturers are piloting digital twin commissioning to compress new model introduction timelines for powertrain assembly lines.
South Korea
Memory chip producers in Seoul and Gyeonggi-do are mandating AI-driven predictive maintenance coverage for all critical etching and deposition equipment. MFDS coordinates with METI-aligned frameworks for pharmaceutical and medical device smart factory compliance. Display fabrication clusters around Suwon are deploying 24/7 monitoring systems to minimize unplanned downtime costs exceeding $2 million per hour.
Thailand
Japanese automotive transplant factories in the Eastern Economic Corridor are piloting digital twin commissioning to accelerate model changeovers. Board of Investment tax holidays and import duty exemptions for smart factory equipment are attracting German and Japanese automation vendors to establish regional service hubs. Electronics contract manufacturers in Bangkok industrial zones favor cloud-based manufacturing execution systems to avoid on-premise capital expenditure.
Vietnam
Electronics contract manufacturers in Ho Chi Minh City and Hanoi industrial parks remain below 15% automation density, creating entry paths for tier-two suppliers. Cloud computing deployments are expanding fastest among mid-tier suppliers seeking to reduce infrastructure capital. Vocational training pipelines lag deployment timelines by 18-24 months, constraining cyber-physical system maintenance capacity.
Asia-Pacific Smart Manufacturing Market Competitive Environment
On the supply side, the industry is consolidating around integrated automation platforms that bundle hardware, software, and service capabilities. European and Japanese industrial conglomerates anchor premium positioning through established robotics service networks and digital twin platforms. Three strategic archetypes dominate: full-stack automation vendors, specialized motion control suppliers, and predictive analytics software providers. Competitive moves center on proprietary sensor ecosystem development and regional service hub establishment to defend attachment rates against disintermediation.
Within the full-stack automation tier, ABB Ltd leverages its robotics service network to anchor premium positioning in Thailand and Vietnam. Siemens AG competes through its digital twin platform, while Mitsubishi Electric Corporation dominates motion control supply to Japanese automotive transplant factories in Indonesia. These three exemplify divergent approaches to defending market position against the unbundling of after-sales service revenue models.
| Leading Market Players |
|---|
| ABB Ltd |
| Honeywell International Inc. |
| Schneider Electric SE |
| Rockwell Automation Inc. |
| Siemens AG |
| FANUC Corporation |
| Mitsubishi Electric Corporation |
| Emerson Electric Co. |
| General Electric Company |
| Others |
Value Chain & Pricing Dynamics
Taiwanese foundry concentration for industrial controller chips creates a dual chokepoint that compresses mid-tier automation margins while amplifying premium-tier pricing power for vendors with captive semiconductor supply. This single-source dependency forces buyers into longer contract horizons and tiered service bundling that obscures true hardware costs.
Pricing Analysis
Certification level (GB/JIS/KCs-grade) creates the primary spread between premium and standard automation tiers. Project-based pricing with multi-year service attachments dominates, though SaaS-tiered predictive analytics subscriptions are gaining share. Price differentiation rests on after-sales service depth and proprietary sensor ecosystem lock-in. Cost compression in mid-tier PLCs is intensifying because Vietnamese electronics contract manufacturers are disintermediating bundled service contracts. Tier-two automotive suppliers in Thailand exhibit highest price sensitivity, while semiconductor fabs in South Korea prioritize uptime guarantees over unit cost.
Supply Chain Analysis
US export controls on advanced semiconductor manufacturing equipment limit flows of EUV-related technologies into Chinese fabs, reshaping regional equipment vendor hierarchies. Geographic supply concentration centers on Taiwan for industrial controller chips, Japan for precision motion components, and Germany for high-end PLC modules. Raw material dependencies include rare earth magnets for servo motors, silicon carbide substrates for power electronics, and high-purity aluminum for robotic arm castings. Single-source vulnerability runs through Taiwanese foundry capacity allocation for automotive-grade microcontrollers. Distribution runs through authorized system integrator networks rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
After-sales service unbundling is accelerating faster than hardware procurement across Thai and Vietnamese electronics corridors, creating attach-rate defense as the central competitive battleground.
For Market Incumbents: Harden proprietary sensor ecosystem lock-in to defend attachment rates against predictive analytics specialists disintermediating bundled contracts. Deepen backward integration into edge computing hardware to preserve margin on disaggregated software sales. Priority rests on regional service hub density in Thailand's Eastern Economic Corridor where Japanese transplant factories are consolidating vendor relationships. For New Entrants and Emerging Players: Establish a beachhead in cloud-based manufacturing execution systems for Philippines electronics assembly zones where automation density remains below 15%. Target tier-two Vietnamese contract manufacturers seeking capex-light deployment models. Lead with subscription pricing that converts capital expenditure to operational expenditure, bypassing incumbent hardware bundling. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors predictive analytics software providers with demonstrated ML model accuracy above 85%. Long-term viability hinges on cross-border data flow agreement resolution between MIIT, METI, and MFDS regulatory blocs. Acquisition target archetype: specialized vibration analytics firms with established training datasets from Korean semiconductor fabs. Signal to watch: first harmonized certification pathway enabling single-hardware approval across Japan, China, and South Korea.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Sensor Ecosystem Development | Defends service attachment rates against disintermediation by specialized analytics vendors in Thai electronics corridors. |
| Regional Service Hub Establishment | Captures maintenance revenue from Japanese automotive transplant factories in Indonesia's industrial zones. |
| Digital Twin Platform Integration | Compresses physical prototyping cycles for South Korean powertrain assembly line model changeovers. |
| Cloud-Based MES Deployment | Enables low-capex entry for Philippines tier-two suppliers avoiding on-premise infrastructure capital. |
| Predictive Maintenance Analytics Acquisition | Secures ML model training data from 24/7 semiconductor fab environments in Seoul and Gyeonggi-do. |
Study Parameters
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base. Primary interviews across these stakeholder roles combined with secondary validation from MIIT GB standard filings, METI Society 5.0 roadmap documents, SEC 10-K automation segment disclosures, and customs equipment import records. Bottom-up equipment deployment tallies triangulated against top-down factory automation spend estimates.
Scenario-bracketing around MIIT dual carbon compliance timelines and semiconductor supply disruption probabilities framed the analytical envelope. Segmentation dimensions modeled include product type, end-user industry, technology architecture, and application use case across the analysis window. CAGRs derived from installed base growth rates, replacement cycle compression, and greenfield automation intensity by regional industrial cluster. Forecast inputs incorporated GB standard enforcement velocity and vocational training pipeline lag times in Southeast Asian markets.
Stress conditions across Taiwanese foundry allocation constraints, cross-border data flow regulatory divergence, and legacy equipment protocol translation costs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding MIIT enforcement consistency and METI-MFDS framework alignment. Material shifts in US export control scope or GB standard cybersecurity classification thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Industrial Data Loggers Market
Industrial Automation
Conveyor Sorting Systems Market
Industrial Automation
Latin America HMI Market
Industrial Automation
Operational Predictive Maintenance Market
Industrial Automation
Motion Control Market
Industrial Automation
Refining Industry Automation and Software Market
Industrial Automation
Warehouse Automation Equipment Market
Industrial Automation
Asia Pacific Warehouse Automation Market
Industrial Automation
Rotary Actuators Market
Industrial Automation
Warehouse Automation Systems Market
Industrial Automation
Factory Automation Market
Industrial Automation
Global Industrial Automation and Control Systems Market
Industrial Automation
GMC Based Motion Controller Market
Industrial Automation
Human Machine Interface (HMI) Market
Industrial Automation
Brazil Factory Automation and Industrial Controls Market
Industrial Automation
Tilt Tray Sorter Market