
 Industrial Data Loggers Market | 2026-2036
Industrial Data Loggers Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Data Loggers Market Insights
Multi-source procurement for sensor components is recalibrating how original equipment manufacturers manage cost and supply continuity. ABB Ltd. leverages its automation ecosystem to bundle data loggers with distributed control systems, creating stickier plant-floor relationships. Yokogawa Electric Corp. anchors its position through deep calibration services and precision measurement heritage in process industries. National Instruments Corp. competes by extending software-defined instrumentation architectures into edge logging applications.
Industrial data loggers are electronic instruments that autonomously record environmental or electrical parameters—temperature, humidity, voltage, current—over time using internal memory and analog-to-digital converters, typically achieving measurement resolutions of 0.1°C or 0.1% relative humidity for regulatory-grade applications. These devices serve critical traceability functions in regulated industries where continuous, tamper-evident records validate product integrity, process compliance, and chain-of-custody documentation. Temperature loggers command the largest installed base due to pervasive cold-chain mandates, though wireless connectivity is the fastest-expanding technology dimension as facilities retire cabled installations in favor of mesh-networked Bluetooth and Wi-Fi nodes that reduce installation labor and enable real-time alerting. Voltage and current loggers occupy narrower but higher-margin niches tied to predictive maintenance programs in utilities and heavy manufacturing.
FDA 21 CFR Part 11 and EU Good Distribution Practice guidelines shape product design by mandating electronic records integrity, audit trails, and secure data transfer protocols for pharmaceutical deployments. EMA's tightened guidance on temperature excursions during transport directly elevates logger accuracy requirements and calibration frequency expectations across European distribution networks. Stakeholders must weigh the capital cost of wireless infrastructure against the operational savings from automated compliance documentation and reduced manual inspection labor.
Market Dynamics
Wireless mesh architectures are systematically displacing cabled sensor infrastructure across pharmaceutical cold chains and utility substations, compressing installation timelines and enabling real-time compliance telemetry that wired systems cannot match.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records integrity mandates in pharmaceutical manufacturing are accelerating replacement of paper-based temperature logs with tamper-evident digital systems.
- Bluetooth Low Energy:Battery-efficient wireless protocols are enabling decade-long deployments in remote cold-storage facilities without maintenance access.
- Food Safety Modernization Act:Preventive controls rules are forcing U.S. food processors to install continuous environmental monitoring across harvest-to-retail chains.
Market Restraints
- Semiconductor supply concentration:Analog-to-digital converter fabrication concentrates in East Asian foundries, exposing logger OEMs to geopolitical disruption risk.
- Calibration labor scarcity:Precision metrology technician shortages in North America and Europe are extending service turnaround times for regulatory-grade devices.
- Legacy system lock-in:Proprietary data formats from 1990s-era wired logger installations create switching costs that delay wireless upgrades.
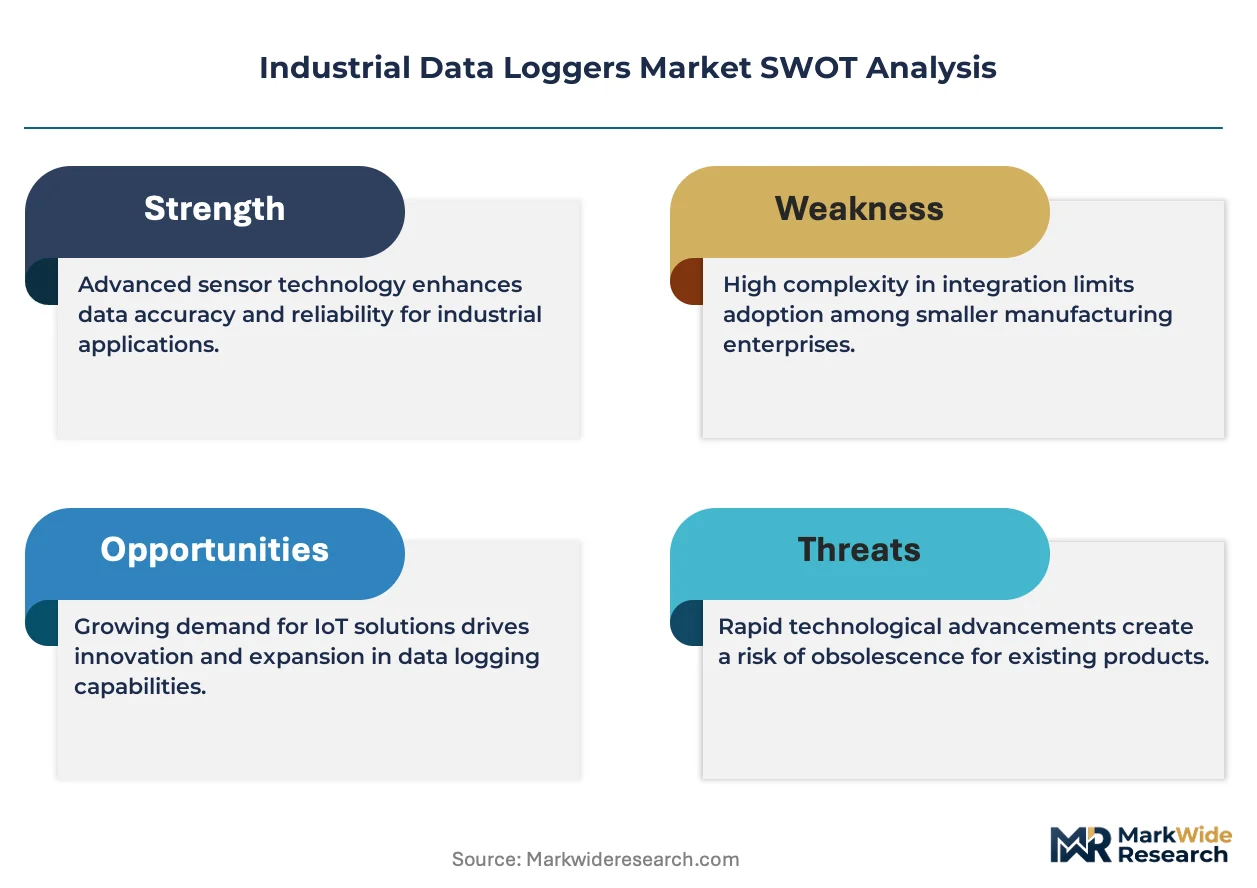
Strategic Opportunities
- EU Green Deal:Energy efficiency auditing mandates for industrial facilities are creating demand for combined temperature-electrical parameter loggers.
- Predictive maintenance convergence:Vibration-temperature-humidity multi-sensor fusion is opening margins in rotating equipment monitoring for steel and cement plants.
- India cold-chain expansion:FSSAI enforcement of temperature documentation for dairy and vaccine distribution is driving first-time logger adoption in warehousing.
Industry Challenges
- Cybersecurity certification timelines:IEC 62443 industrial control system security standards are adding 8-14 months to product release cycles for wireless-enabled devices.
- Legacy SCADA integration:Protocol translation between modern Bluetooth loggers and 1980s-era Modbus installations requires custom gateway development that erodes project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Data Loggers Market |
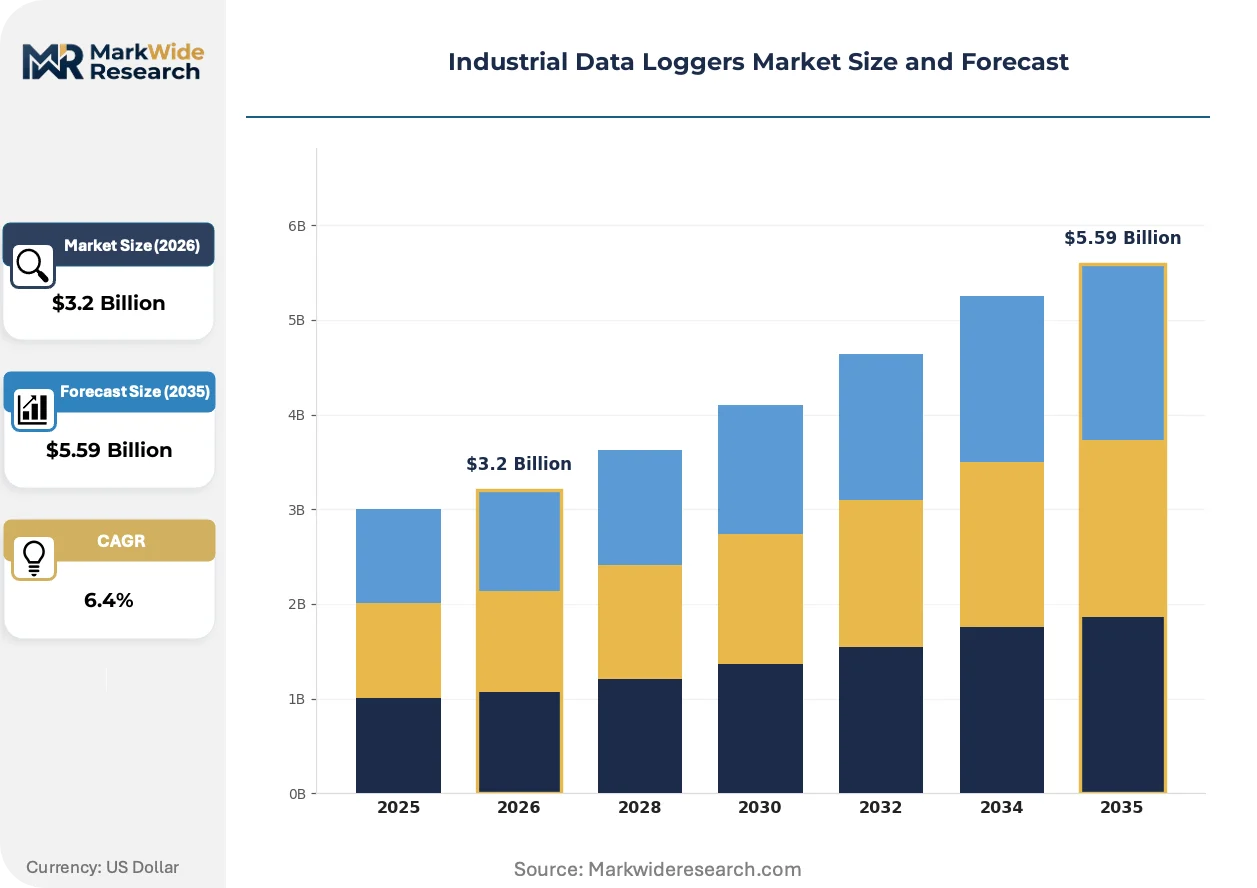
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Loggers, Humidity Loggers, Voltage Loggers, Current Loggers Technology: Wired, Wireless, Bluetooth, Wi-Fi End User: Manufacturing, Pharmaceuticals, Food Processing, Utilities Application: Environmental Monitoring, Supply Chain Management, Quality Control, Research |
| Companies Covered | ABB Ltd., Yokogawa Electric Corp., National Instruments Corp., Keysight Technologies Inc., Testo SE & Co. KGaA, Hioki E.E. Corporation, Robert Bosch GmbH, Thermo Fisher Scientific Inc., Fluke Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Data Loggers Market Trends and Innovations
Sensor miniaturization and edge computing integration are collapsing the distinction between data collection and real-time decision support, enabling autonomous anomaly detection without cloud dependency.
Multi-parameter fusion loggers are modularizing hardware architectures across pharmaceutical and food processing deployments. Facilities in Germany and the Netherlands are standardizing on swappable sensor cartridges that reduce spare parts inventory. This shift is modularizing procurement patterns, allowing plant engineers to reconfigure monitoring capabilities without replacing entire devices.
EMA's tightened guidance on temperature excursion documentation during cross-border distribution is forcing logistics providers to upgrade logger sampling frequencies from 15-minute to 1-minute intervals. Cold-chain operators are responding by deploying higher-resolution devices with expanded onboard memory buffers. Pharmaceutical 3PLs in Belgium and the Netherlands are absorbing these hardware costs to retain EMA audit readiness.
Service unbundling is fragmenting traditional logger vendor relationships. End-users in U.S. utilities are separating hardware procurement from calibration and data analytics subscriptions, treating loggers as commoditized sensors while purchasing compliance documentation as a distinct service. This pattern is most pronounced among municipal water treatment authorities facing constrained capital budgets.
Industrial Data Loggers Market Segmentation
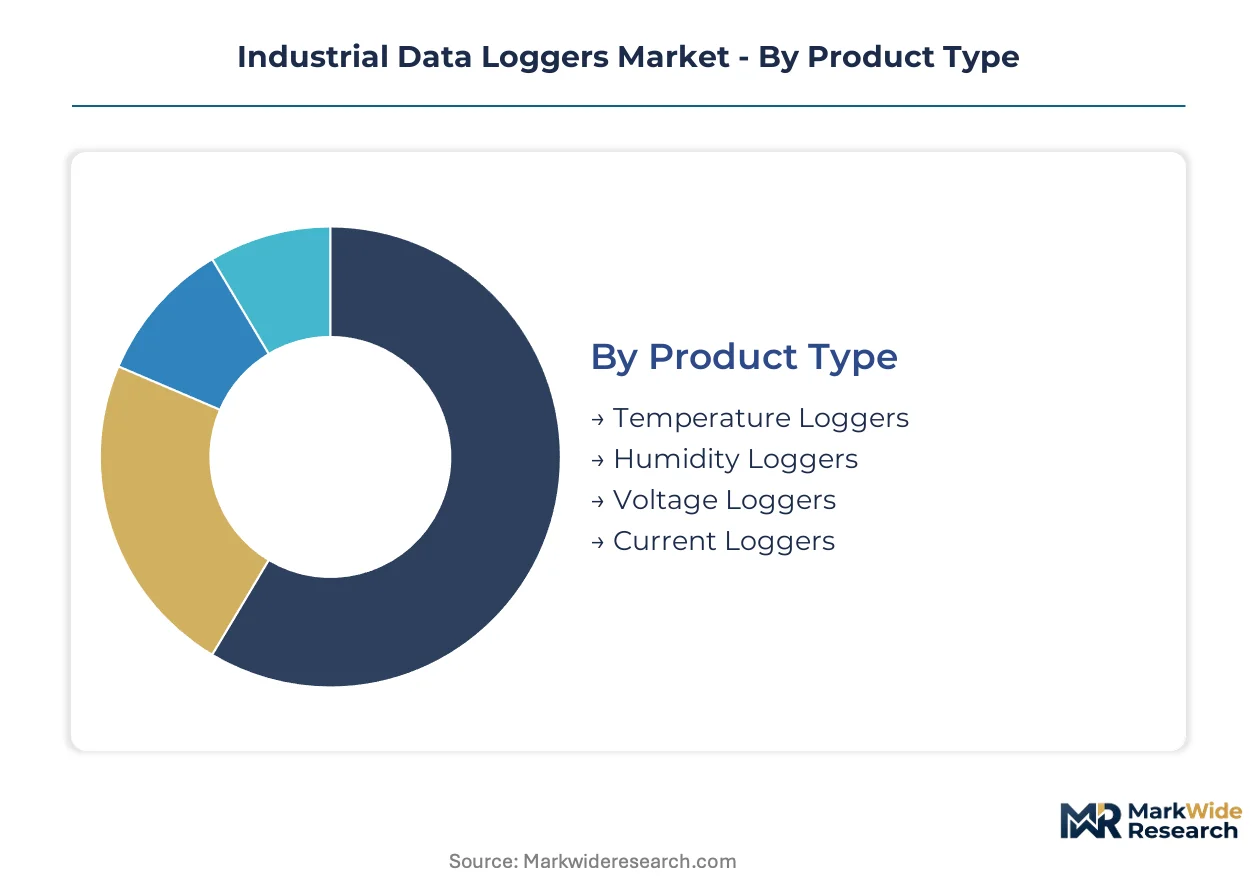
Industrial data logger procurement divides sharply between regulated and unregulated environments, with certification requirements dictating sensor accuracy, calibration protocols, and data integrity architectures. Understanding these segment boundaries clarifies where margin concentrates and where commoditization pressures dominate.
Product Type:
FDA 21 CFR Part 11 and EU GDP guidelines impose distinct validation burdens across logger categories, with pharmaceutical cold-chain applications demanding tamper-evident records and audit trails that general industrial monitoring escapes.
- Temperature Loggers:These devices measure thermal conditions using thermistors or RTD sensors achieving 0.1°C resolution for regulatory-grade deployments. Pharmaceutical manufacturers in Germany and the United States drive replacement cycles as EMA and FDA tighten excursion documentation requirements, forcing upgrades from 15-minute to 1-minute sampling intervals.
- Humidity Loggers:Capacitive polymer sensors track relative humidity with 0.1% precision in controlled atmosphere applications. Food processing facilities across the Netherlands deploy these for cheese aging and chocolate tempering operations where moisture control determines product safety and shelf stability.
- Voltage Loggers:These instruments capture electrical potential fluctuations across power distribution networks using high-impedance inputs. Utility substations in the United States integrate voltage loggers into grid modernization programs for fault detection and load balancing analytics.
- Current Loggers:Hall-effect or shunt-based sensors monitor amperage draw in industrial equipment for predictive maintenance. Steel and cement plants combine current logging with vibration analysis to forecast motor bearing failures before catastrophic downtime occurs.
Temperature loggers sit at the top of the volume ranking, with humidity loggers climbing the fastest as food safety regulations expand moisture documentation requirements.
Technology:
Installation cost structures and maintenance access determine technology selection, with battery life and mesh network reliability becoming decisive factors in remote or hazardous environments.
- Wired:Cabled installations using RS-485 or 4-20mA loops deliver uninterrupted power and signal integrity in electromagnetic-heavy factory floors. Legacy pharmaceutical plants in Belgium retain wired infrastructure where Bluetooth retrofit costs exceed replacement timelines.
- Wireless:Proprietary radio protocols enable kilometer-range transmission without cellular dependency. Mining operations in Australia deploy wireless loggers for tailings dam monitoring where terrain blocks cabled installation.
- Bluetooth:Low-energy protocols support decade-long battery life in cold-storage facilities lacking maintenance access. Pharmaceutical 3PLs in the Netherlands standardize on Bluetooth mesh for warehouse mapping with real-time mobile alerts.
- Wi-Fi:Existing enterprise infrastructure reduces deployment costs in IT-rich environments. Research laboratories at universities in the United States leverage Wi-Fi loggers for immediate cloud synchronization and collaborative data access.
Wired technology retains the largest installed base, though Bluetooth deployments are expanding most quickly as facilities retire cabled infrastructure.
End User:
Capital intensity and regulatory exposure create divergent purchasing behaviors, with validation documentation commanding premium pricing in life sciences while manufacturing prioritizes sensor density per dollar.
- Manufacturing:Discrete and process manufacturers deploy loggers for equipment condition monitoring and environmental compliance. Automotive paint shops in Germany track booth humidity to prevent solvent blistering and warranty claims.
- Pharmaceuticals:Vaccine and biologics producers require calibrated, traceable records for every shipment. Cold-chain operators absorb hardware cost premiums to maintain EMA audit readiness and FDA inspection compliance.
- Food Processing:Harvest-to-retail chains install continuous monitoring under FSMA preventive controls rules. Dairy cooperatives in India adopt first-time logger systems as FSSAI enforcement intensifies temperature documentation mandates.
- Utilities:Power generation and water treatment authorities balance capital constraints against reliability requirements. Municipal water districts in the United States unbundle hardware from calibration services to stretch constrained budgets.
Manufacturing represents the deepest penetration by unit volume, while pharmaceutical applications generate the steepest expansion trajectory as distribution networks globalize.
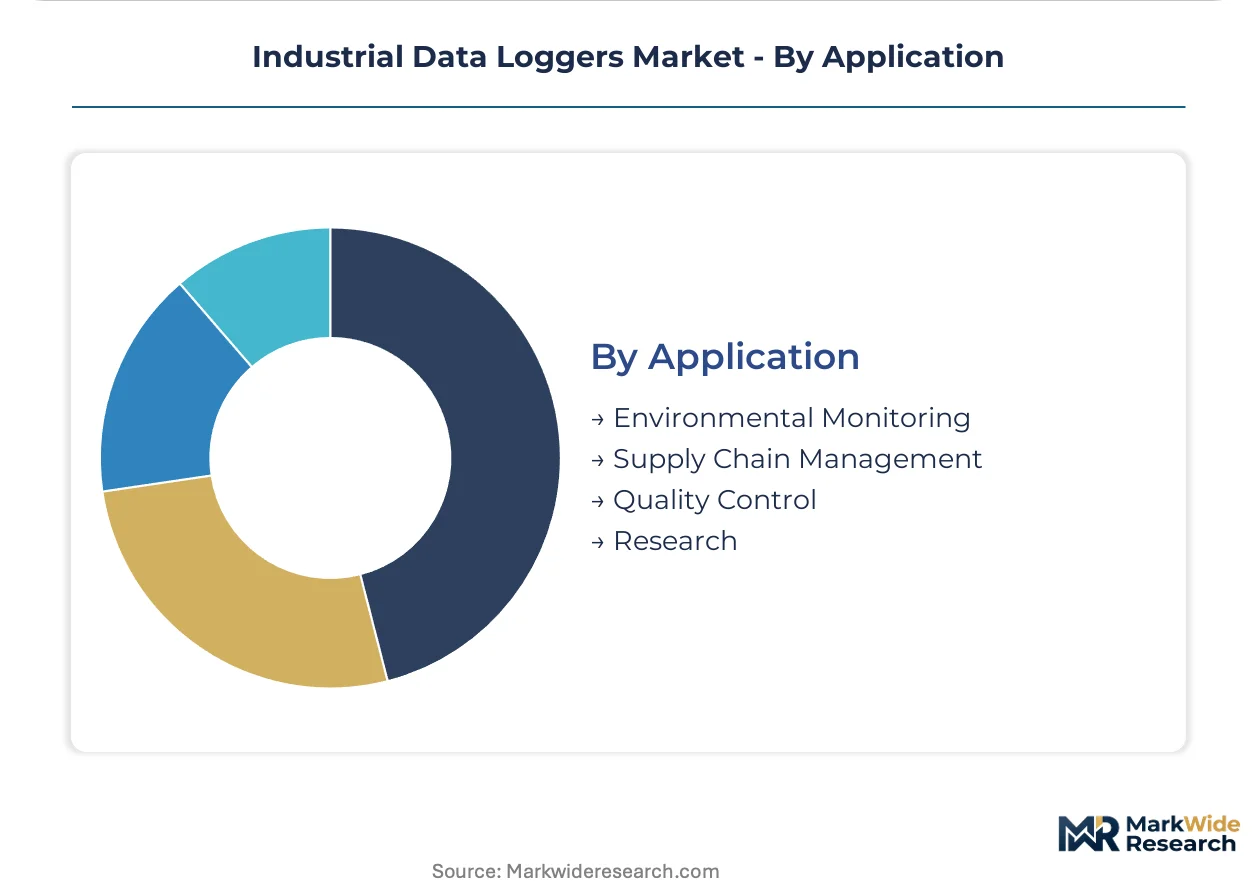
Application:
Use case complexity determines software integration depth, with supply chain applications requiring multi-party data handoffs that research applications typically avoid.
- Environmental Monitoring:Continuous tracking of temperature, humidity, and pressure in controlled spaces. Cleanroom facilities in Switzerland deploy redundant sensor arrays for semiconductor wafer production contamination prevention.
- Supply Chain Management:End-to-end custody documentation from manufacturing through last-mile delivery. Logistics providers crossing Benelux borders upgrade logger resolution to satisfy EMA cross-distribution guidance.
- Quality Control:Process validation and batch record integration for regulated production. Generic drug manufacturers in India implement logger-based evidence packages for CDSCO facility inspections.
- Research:Experimental reproducibility through precise environmental recording. Climate science field stations in Norway log permafrost thermal profiles for longitudinal ecosystem studies.
Environmental monitoring commands the broadest deployment footprint, with supply chain management gaining share fastest as pharmaceutical distribution networks digitize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between jurisdictions is reshaping where pharmaceutical and food manufacturers validate their cold-chain infrastructure, with compliance-cost gaps driving facility investment toward markets offering streamlined certification pathways.
United States
FDA enforcement of Food Safety Modernization Act preventive controls is compelling food processors across California's Central Valley to install continuous temperature monitoring from harvest through distribution. Utility modernization programs in Texas and the Midwest are accelerating voltage logger deployments for grid resilience analytics. Municipal water authorities in the Great Lakes region are unbundling hardware procurement from calibration services to navigate constrained capital budgets.
Germany
EMA's tightened guidance on temperature excursion documentation is forcing pharmaceutical 3PLs in Bavaria and North Rhine-Westphalia to upgrade logger sampling frequencies from 15-minute to 1-minute intervals. Automotive paint shops in Baden-Württemberg track booth humidity to prevent solvent blistering and warranty claims. The country's precision measurement heritage anchors deep calibration service capabilities for regulatory-grade deployments.
India
FSSAI enforcement of temperature documentation for dairy and vaccine distribution is driving first-time logger adoption in warehousing clusters around Mumbai and Delhi-NCR. Generic drug manufacturers in Gujarat and Telangana implement logger-based evidence packages for CDSCO facility inspections. Cold-chain infrastructure gaps in secondary cities are creating demand for battery-efficient wireless devices lacking maintenance access.
Netherlands
Pharmaceutical logistics providers crossing Benelux borders absorb hardware cost premiums to satisfy EMA cross-distribution guidance on excursion traceability. Cheese aging and chocolate tempering operations deploy humidity loggers with 0.1% precision for moisture-controlled atmosphere compliance. Bluetooth mesh standardization in Rotterdam and Eindhoven warehousing enables real-time mobile alerts without cabled infrastructure.
China
NMPA's alignment with international ICH guidelines is elevating data integrity requirements for domestic pharmaceutical exporters targeting EU and US markets. Industrial clusters in Jiangsu and Zhejiang provinces are retrofitting process manufacturing with multi-parameter fusion loggers for combined environmental and electrical monitoring. Semiconductor fabrication cleanrooms in the Yangtze River Delta deploy redundant sensor arrays for contamination prevention.
Industrial Data Loggers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue edge-computing integration and subscription-based service models. The vendor base stratifies across three maturity levels: diversified industrial automation conglomerates, precision measurement specialists with calibration heritage, and software-defined instrumentation architects. Consolidation pressure concentrates among mid-scale hardware fabricators facing component cost volatility and certification timeline extensions. Dominant competitive moves include bundling loggers with distributed control systems and unbundling hardware from compliance-documentation subscriptions.
Within the automation-integrated tier, ABB Ltd. and Yokogawa Electric Corp. exemplify platform-centric positioning that embeds data logging within broader plant-floor control architectures. National Instruments Corp. occupies a distinct vector extending software-defined instrumentation into edge applications. These three anchors represent divergent strategic bets: ecosystem lock-in through bundled infrastructure, precision metrology credibility through calibration services, and programmable flexibility through modular software stacks.
| Leading Market Players |
|---|
| ABB Ltd. |
| Yokogawa Electric Corp. |
| National Instruments Corp. |
| Keysight Technologies Inc. |
| Testo SE & Co. KGaA |
| Hioki E.E. Corporation |
| Robert Bosch GmbH |
| Thermo Fisher Scientific Inc. |
| Fluke Corporation |
| Others |
Pricing and Supply Chain Analysis
Analog-to-digital converter fabrication costs in East Asian foundries transmit directly through to regulatory-grade logger pricing tiers, with precision metrology labor scarcity in North America and Europe amplifying service premiums for pharmaceutical validation protocols.
Pricing Analysis
Input-cost pass-through from semiconductor foundries and calibration technician wages shapes a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on FDA 21 CFR Part 11 certification grade and volume procurement scale, with pharmaceutical cold-chain operators absorbing hardware premiums for audit-ready documentation. Cost compression in the economy tier intensifies because municipal utilities unbundle hardware from service subscriptions. Manufacturing plants prove most price-sensitive due to sensor density requirements, while pharmaceutical 3PLs exhibit least sensitivity given compliance failure costs.
Supply Chain Analysis
Dual-sourcing requirements for ADC components and battery cells compel logger OEMs to qualify suppliers across Taiwan, South Korea, and Japan. Raw material dependencies center on lithium-ion cells, precision resistors, and MEMS humidity sensors. Single-source vulnerability concentrates in BLE chipset fabrication, exposing production schedules to geopolitical disruption. Distribution runs through authorized calibration service networks for regulated deployments, with direct OEM sales dominating high-volume manufacturing accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Industrial Data Loggers Market compounds steadily as regulatory documentation mandates harden across pharmaceutical and food distribution networks, embedding replacement demand into compliance cycles.
For Market Incumbents: Deploy calibration service bundling to lock pharmaceutical 3PL relationships against emerging software-defined instrumentation entrants. Deepen sensor cartridge standardization to raise switching costs for facilities with modular hardware investments. Strengthen backward integration into ADC component sourcing to buffer East Asian foundry concentration risks.
For New Entrants and Emerging Players: FDA 21 CFR Part 11 enforcement in the United States opens a window for cloud-native compliance documentation platforms that unbundle hardware from subscription analytics. Target Indian cold-chain warehousing for first-time logger adoption as FSSAI documentation mandates expand. Pursue white-label partnerships with European pharmaceutical logistics providers seeking EMA audit readiness without capital-intensive hardware development.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale hardware fabricators face extended IEC 62443 certification timelines and component cost volatility simultaneously. Five-to-ten-year viability favors precision metrology specialists with captive calibration technician networks. Watch Bluetooth mesh adoption rates in Benelux pharmaceutical warehousing as inflection indicator for wireless technology displacement speed.
| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Bundling | Captures recurring revenue from pharmaceutical 3PLs facing EMA audit frequency requirements. |
| Sensor Cartridge Modularization | Reduces spare parts inventory for Dutch cheese aging and chocolate tempering operations. |
| Bluetooth Mesh Standardization | Enables decade-long battery deployments in Indian vaccine distribution warehousing. |
| Backward Integration into ADC Sourcing | Buffers OEM margins against Taiwan and South Korea foundry concentration risks. |
| Cloud-Native Compliance Platforms | Unbundles hardware from subscription documentation for U.S. municipal water authorities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pharmaceutical quality directors, utility maintenance engineers, food safety compliance officers, and calibration service technicians with secondary validation against FDA 21 CFR Part 11 guidance documents, EMA GDP inspection reports, FSSAI enforcement circulars, and customs trade data for sensor component flows. Bottom-up facility installation estimates and top-down OEM revenue analysis triangulated market sizing.
Comparable-period anchoring tied projection models to historical replacement cycles in pharmaceutical cold chains and utility grid modernization programs across the analysis window. Segmentation dimensions modeled include product type, connectivity technology, end-user industry, and regional regulatory cluster. CAGRs derived from logistic diffusion curves for wireless technology substitution and compliance-driven hardware refresh rates. Industry-specific inputs incorporated EMA temperature excursion documentation tightening and FSMA preventive controls enforcement intensity.
Revisions become necessary when semiconductor supply disruptions, calibration labor shortages, or cybersecurity certification timeline extensions materialize beyond baseline assumptions. Deviation in FDA or EMA enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Global Warehouse Automation Market
Industrial Automation
Latin America Laboratory Automation Market
Industrial Automation
Smart Manufacturing Devices Market
Industrial Automation
Asia Pacific Factory Automation and Industrial Controls Market
Industrial Automation
Conveyor Sorting Systems Market
Industrial Automation
Industrial Multiprotocol Gateways Market
Industrial Automation
Programmable Logic Controller Market
Industrial Automation
Industrial Automation Services Market
Industrial Automation
Europe Water Automation and Instrumentation Market
Industrial Automation
Europe Industrial Automation Software Market
Industrial Automation
US and Europe Warehouse Automation Market
Industrial Automation
Asia-Pacific Industrial Automation Market
Industrial Automation
North America Automated Rotary Indexing Table Market
Industrial Automation
Material Handling Robotics Market
Industrial Automation
South Korea Factory Automation and Industrial Controls Market
Industrial Automation
Europe SCADA Market