
 Asia-Pacific Digital Twin Market | 2026-2036
Asia-Pacific Digital Twin Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Digital Twin Market Analytics
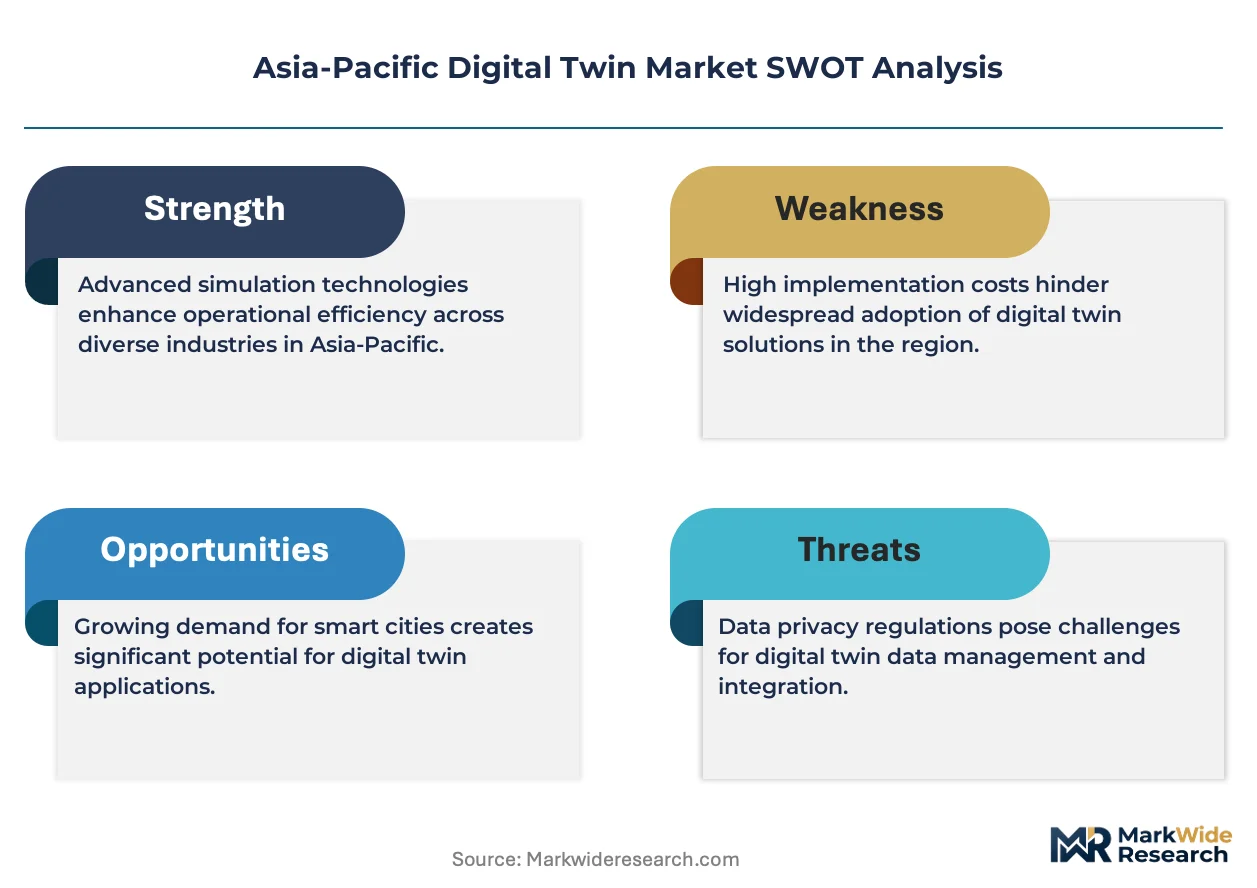
The Asia-Pacific digital twin landscape is repositioning around a sharp split between premium AI-integrated platforms and commoditized visualization software. ABB Group leverages its robotics heritage to dominate factory-floor digital twin deployments across Southeast Asia. Siemens sustains technology leadership through its Xcelerator platform architecture, while Dassault Systèmes specializes in aerospace-grade simulation fidelity for defense and aviation clients.
A digital twin constitutes a dynamic virtual replica of a physical asset, system, or process that ingests real-time sensor data through IoT connectivity and applies physics-based modeling to simulate operational behavior, predict failure modes, and optimize performance parameters across lifecycle stages. Software platforms command the deepest margin pools as enterprises prioritize subscription-based analytics over one-time modeling licenses, while cloud-based deployment is displacing on-premises infrastructure among mid-market manufacturers seeking scalable compute without capital intensity. Edge computing configurations are gaining traction in energy sector applications where latency constraints prevent centralized data processing.
China's MIIT enforces GB standards for industrial internet platforms that mandate interoperability protocols, while Japan's METI promotes digital twin adoption through its Society 5.0 framework for connected industries. South Korea's KOSHA safety regulations are embedding predictive digital twin requirements into heavy manufacturing compliance audits. Stakeholders must weigh sovereign data localization rules against cross-border platform architectures when selecting deployment strategies.
Market Dynamics
China's MIIT dual carbon mandates are compressing deployment timelines for industrial digital twins as energy-intensive sectors face compliance deadlines requiring real-time emissions monitoring and predictive optimization.
Growth Catalysts
- MIIT GB Standards Mandate:China's Ministry of Industry and Information Technology enforces interoperability protocols for industrial internet platforms, compelling state-owned steel and chemical enterprises to deploy certified digital twin architectures for regulatory compliance.
- Semiconductor Predictive Maintenance:South Korean memory and logic fabs are integrating equipment digital twins to reduce unplanned downtime in lithography and etch processes where single-hour outages cost millions in lost wafer output.
- Smart Manufacturing Acceleration:Japanese automotive OEMs are deploying factory-floor digital twins to synchronize robotics, AGVs, and quality systems across multi-supplier assembly networks.
Market Restraints
- Cloud Infrastructure Concentration:Hyperscaler concentration in Singapore and Tokyo data centers creates sovereign risk for Australian and Indonesian manufacturers subject to data localization requirements.
- Physics Engine Licensing Costs:High-fidelity simulation cores from specialized software vendors impose recurring royalty burdens that erode margins for mid-market system integrators serving discrete manufacturing.
- Interoperability Friction:Legacy OPC-UA and proprietary industrial protocols resist seamless integration with modern IoT data pipelines, forcing costly middleware development.
Strategic Opportunities
- Vietnamese Electronics Assembly:Contract manufacturers serving Apple and Samsung supply chains lack mature digital twin deployments, creating first-mover advantage for platform vendors offering turnkey cloud-edge hybrid architectures.
- AI-Physics Convergence:Neural network surrogates trained on high-fidelity simulations are enabling real-time optimization previously impossible with pure physics-based models, opening process industries to digital twin adoption.
- METI Society 5.0 Incentives:Japan's Ministry of Economy, Trade and Industry subsidizes connected industry demonstrations, reducing customer acquisition costs for vendors targeting SME manufacturing clusters in Aichi and Osaka prefectures.
Industry Challenges
- Mechatronics-AI Skill Gap:Deployment teams require rare hybrid expertise combining mechanical system modeling, industrial IoT architecture, and machine learning operations, constraining implementation velocity.
- Multi-Year Certification Cycles:Safety-critical applications in nuclear, aviation, and medical device manufacturing demand extensive validation against JIS and GB functional safety standards before operational deployment.
- Edge-Cloud Orchestration Complexity:Energy sector deployments require seamless failover between offshore platform edge nodes and onshore cloud analytics, demanding specialized distributed systems engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Digital Twin Market |
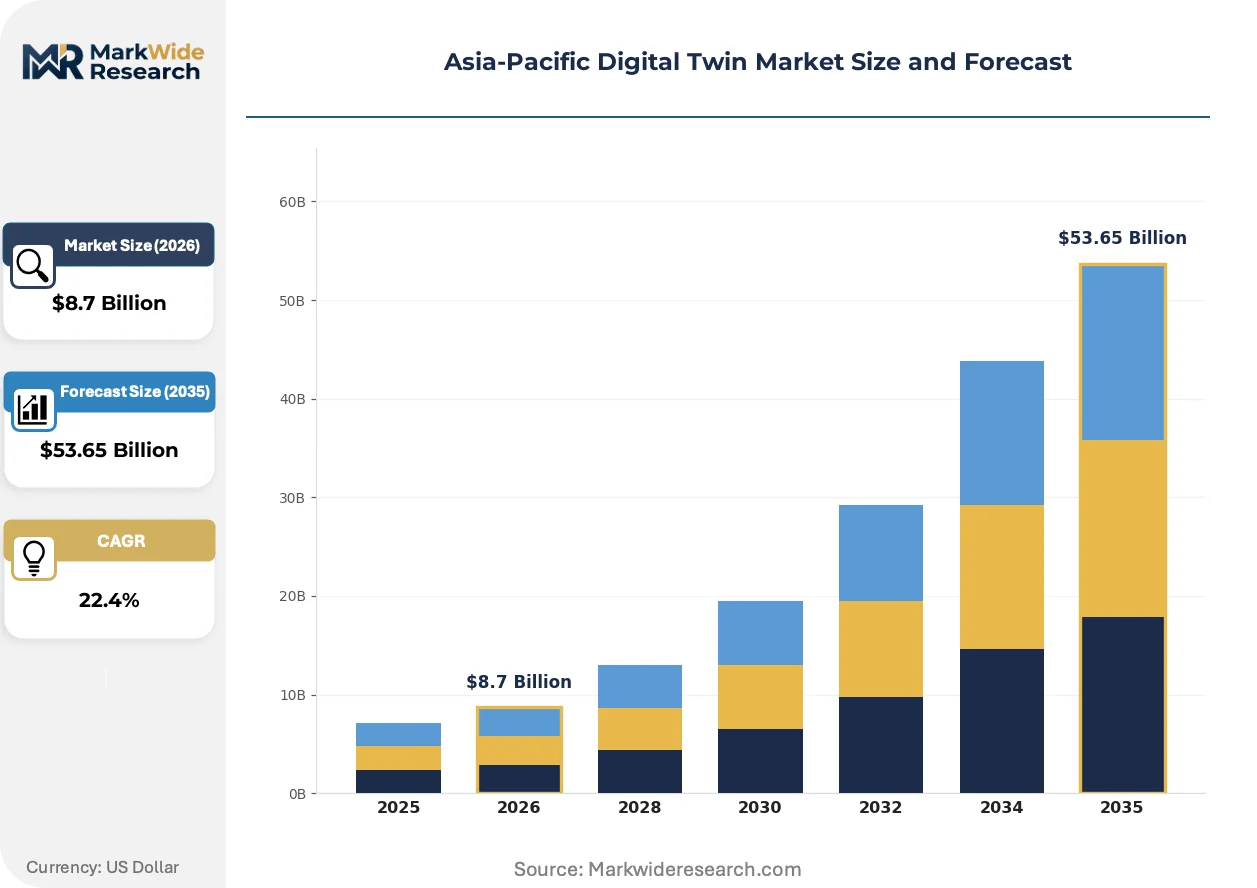
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $53.65 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Platform, Service, Application End User: Aerospace, Automotive OEMs, Manufacturing, Energy Technology: IoT, AI, Machine Learning, Cloud Computing Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | ABB Group, General Electric Company, Siemens, Robert Bosch GmbH, IBM Corporation, GE Vernova, Accenture, Microsoft Corporation, Dassault Systèmes, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Digital Twin Market Evolving Landscape
Generative AI is compressing model development cycles while physics-informed machine learning narrows the simulation-to-reality gap, fundamentally altering how industrial enterprises justify digital twin investments.
Physics-informed neural networks are rewriting the cost structure of high-fidelity asset modeling by replacing computationally expensive finite element solvers with surrogate models that train on sparse sensor data. Japanese shipbuilders and Australian mining operators are piloting these architectures for structural fatigue prediction. The technology is rewriting competitive positioning by enabling mid-market manufacturers to access simulation fidelity previously reserved to aerospace and automotive leaders.
METI's 2024 amendments to the Industrial Competitiveness Enhancement Act explicitly fund digital twin integration for supply chain resilience, channeling subsidies toward cross-enterprise data sharing platforms. The policy accelerates adoption among keiretsu manufacturing networks seeking synchronized production planning. Heavy machinery and robotics sectors in Nagoya and Kobe industrial corridors are restructuring procurement specifications to mandate interoperable twin architectures.
Asset-as-a-service contracting is displacing perpetual software licenses in Southeast Asian manufacturing, with Malaysian and Thai automotive suppliers preferring subscription models that bundle digital twin analytics with hardware maintenance. System integrators are responding by unbundling platform access from implementation services, creating tiered engagement models aligned to customer maturity. This shift is most visible in Indonesian palm oil processing and Thai automotive component clusters where capital constraints favor operational expenditure structures.
Asia-Pacific Digital Twin Market Segmentation
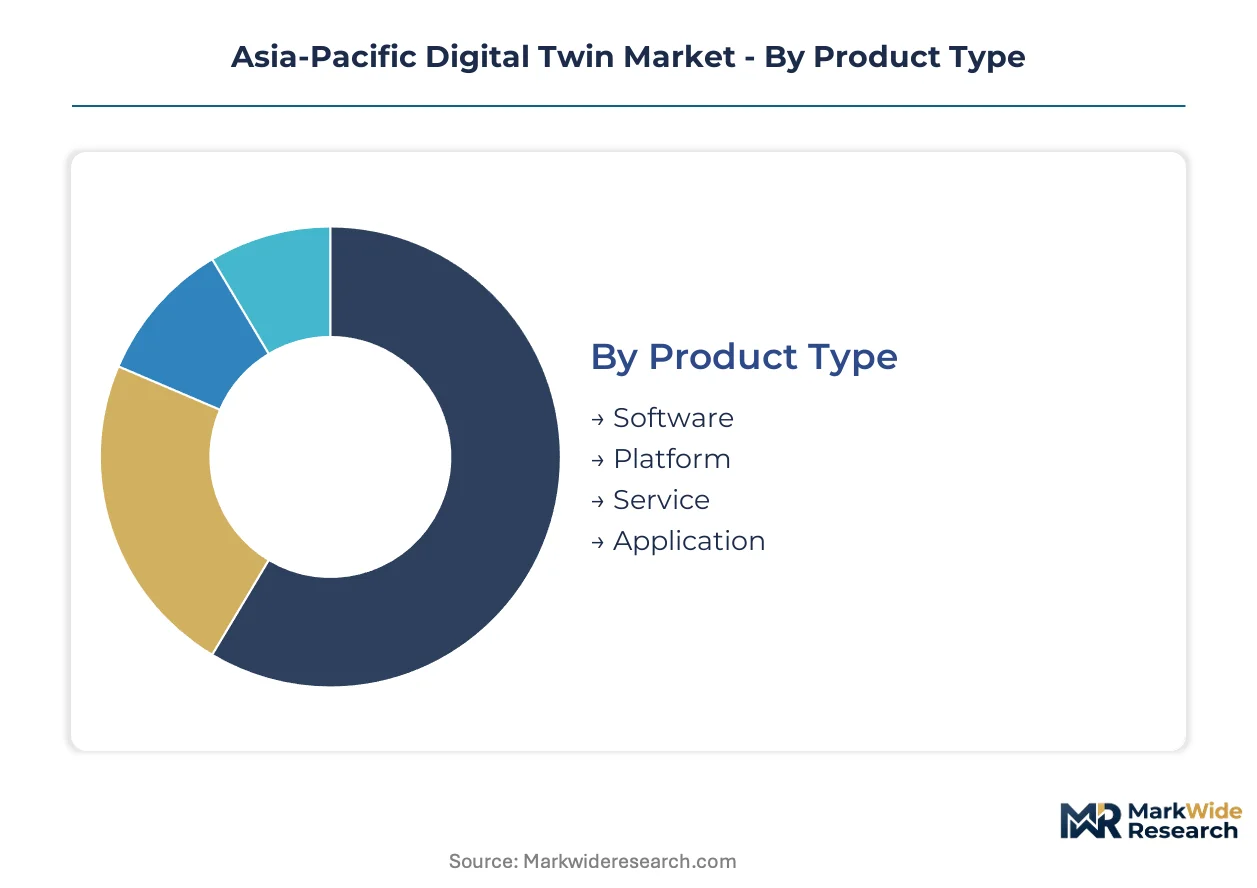
Digital twin architectures fragment across four intersecting dimensions that determine procurement priorities. Product type dictates margin capture for vendors, while deployment mode reflects sovereign data constraints and latency requirements specific to Asia-Pacific industrial infrastructure.
Product Type:
Software commands premium pricing through recurring analytics subscriptions, while platform and service revenues concentrate in turnkey integration contracts for state-owned enterprises.
- Software:Physics-based simulation engines and visualization tools ingest real-time sensor streams to model asset degradation. Chinese steel mills under MIIT dual carbon mandates deploy emissions-optimization software for compliance reporting, with procurement concentrated among state-owned enterprises facing regulatory deadlines.
- Platform:Integrated development environments combine modeling, data ingestion, and analytics in unified architectures. Japanese automotive OEMs in Aichi prefecture favor platform subscriptions that synchronize multi-supplier assembly networks through METI-subsidized Society 5.0 implementations.
- Service:Implementation consulting and managed operations support deployment for manufacturers lacking in-house IoT expertise. Vietnamese electronics contract manufacturers procure packaged services to bridge skill gaps in mechatronics-AI integration.
- Application:Pre-configured vertical solutions address specific use cases without customization overhead. South Korean semiconductor fabs deploy lithography-specific applications for predictive maintenance where unplanned downtime costs millions per hour.
Mature deployment sits with Software. Newer deployment is concentrated in Platform.
End User:
Automotive OEMs drive volume through synchronized supply chain requirements, while Energy procurement reflects offshore latency constraints and safety-critical certification cycles.
- Aerospace:Structural fatigue modeling and flight simulation demand aerospace-grade fidelity. Australian mining operators pilot physics-informed neural networks for equipment stress prediction, adapting aviation-derived simulation techniques to extractive industries.
- Automotive OEMs:Factory-floor twins coordinate robotics, AGVs, and quality systems across tiered supplier networks. Toyota and Honda deployment in Nagoya and Osaka industrial corridors accelerates through METI procurement subsidies for connected industry demonstrations.
- Manufacturing:Discrete and process manufacturing deploy twins for throughput optimization and predictive maintenance. Thai automotive component clusters favor subscription analytics bundled with hardware maintenance to preserve capital for equipment upgrades.
- Energy:Offshore platforms and renewable installations require edge-cloud orchestration for real-time optimization. Indonesian and Australian operators face sovereign data localization requirements that complicate hyperscaler cloud concentration in Singapore and Tokyo data centers.
Procurement maturity clusters in Automotive OEMs. Fastest expansion trajectory appears in Energy.
Technology:
Cloud Computing underpins scalable deployment for mid-market manufacturers, while AI and Machine Learning differentiate premium offerings through predictive capabilities.
- IoT:Sensor networks and connectivity protocols feed real-time operational data into twin architectures. South Korean semiconductor fabs embed thousands of sensors per lithography tool to capture vibration, temperature, and gas flow parameters.
- AI:Generative algorithms compress model development cycles and enable natural language interfaces for non-technical operators. Japanese shipbuilders deploy AI-augmented twins for hull inspection automation, reducing manual survey requirements.
- Machine Learning:Neural network surrogates trained on physics simulations enable real-time optimization previously impossible with finite element solvers. Australian mining operators apply ML surrogates to structural fatigue prediction, narrowing simulation-to-reality gaps.
- Cloud Computing:Elastic compute resources eliminate capital intensity for manufacturers lacking on-premises infrastructure. Malaysian and Thai automotive suppliers prefer cloud-based twins to avoid data center construction, though Indonesian palm oil processors face intermittent connectivity challenges.
Established integration sits with IoT. Emerging adoption clusters in Machine Learning.
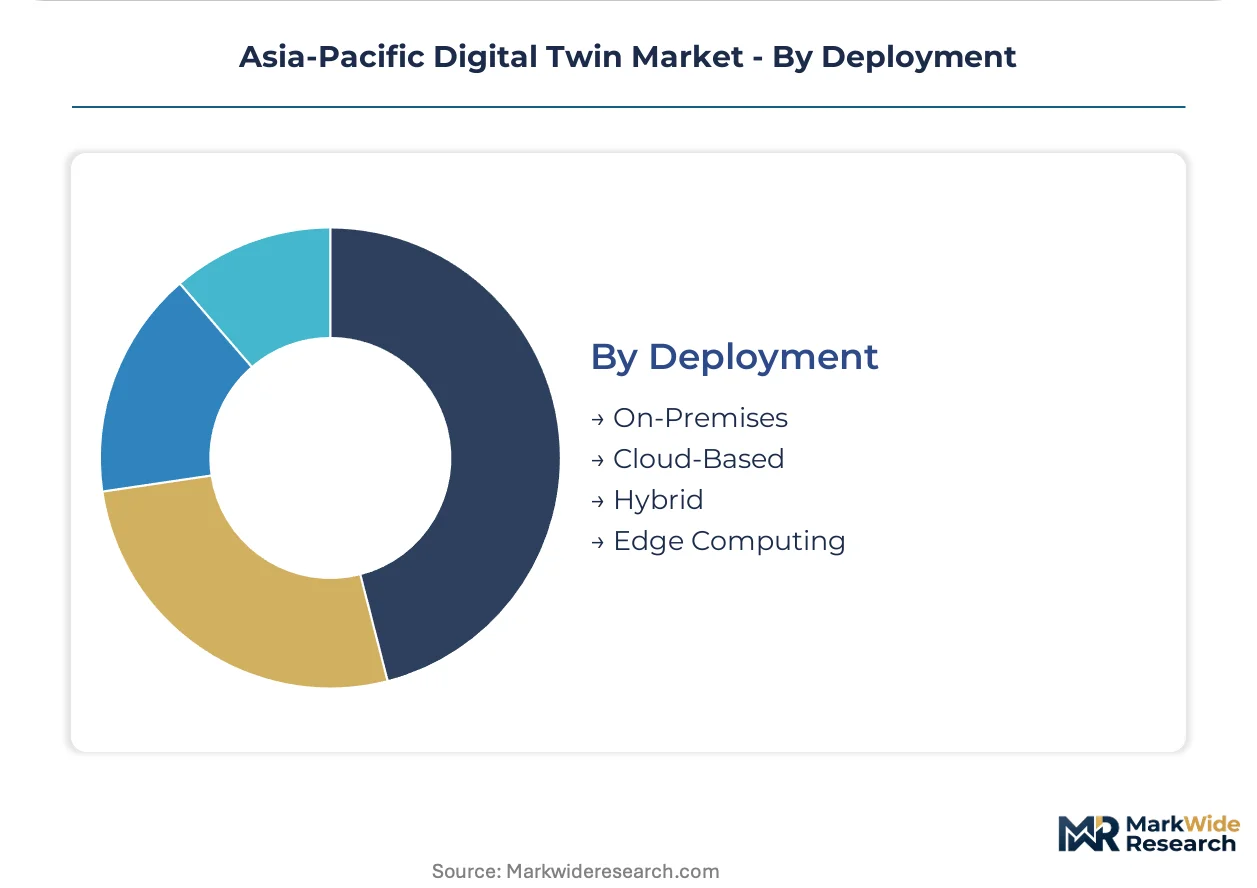
Deployment:
Cloud-Based deployment dominates mid-market manufacturing, while Edge Computing addresses latency-sensitive applications in energy and heavy industry.
- On-Premises:Dedicated infrastructure serves manufacturers with strict data sovereignty requirements or legacy system dependencies. Chinese state-owned enterprises under GB standards mandates often retain on-premises twins for industrial internet platform certification.
- Cloud-Based:Scalable subscription models reduce capital expenditure for contract manufacturers and SME clusters. Vietnamese electronics assembly serving Apple and Samsung supply chains favors cloud deployment to accelerate time-to-value without infrastructure investment.
- Hybrid:Architectures partition workloads between edge preprocessing and cloud analytics. Japanese automotive OEMs deploy hybrid configurations to synchronize real-time factory-floor control with enterprise-level supply chain optimization.
- Edge Computing:Localized processing eliminates latency for safety-critical and bandwidth-constrained applications. Offshore energy platforms in Australian and Indonesian waters require edge nodes for autonomous operation during connectivity interruptions.
Volume concentration rests with Cloud-Based. Technical differentiation is shifting toward Edge Computing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nagoya anchors the region's industrial digital twin deployment through Toyota's keiretsu network and METI-subsidized Society 5.0 implementations across Aichi prefecture's automotive corridor.
China
State-owned steel and chemical enterprises under MIIT dual carbon mandates deploy certified industrial internet platforms for real-time emissions monitoring. GB standards enforcement compels interoperability protocols across state-owned enterprises. Yangtze River Delta manufacturing clusters in Shanghai and Jiangsu province accelerate cloud-edge hybrid architectures for compliance deadlines.
Japan
Automotive OEMs in Aichi and Osaka prefectures synchronize multi-supplier assembly networks through factory-floor digital twins. METI's Industrial Competitiveness Enhancement Act amendments fund cross-enterprise data sharing for supply chain resilience. Nagoya and Kobe industrial corridors restructure procurement specifications to mandate interoperable twin architectures.
South Korea
Memory and logic fabs integrate equipment digital twins to reduce unplanned downtime in lithography and etch processes. KOSHA safety regulations embed predictive digital twin requirements into heavy manufacturing compliance audits. Seoul Capital Area semiconductor clusters deploy thousands of sensors per tool for vibration and temperature parameter capture.
Australia
Mining operators pilot physics-informed neural networks for structural fatigue prediction in extractive equipment. Sovereign data localization requirements complicate hyperscaler cloud concentration in Singapore and Tokyo data centers. Western Australian offshore energy platforms require edge nodes for autonomous operation during connectivity interruptions.
Vietnam
Electronics contract manufacturers serving Apple and Samsung supply chains lack mature digital twin deployments. Capital constraints favor operational expenditure structures over infrastructure investment. Northern industrial zones around Hanoi and Hai Phong create first-mover advantage for platform vendors offering turnkey cloud-edge hybrid architectures.
Asia-Pacific Digital Twin Market Competitive Landscape
Premium-margin players sit above commodity-margin players across simulation fidelity and integration depth. The vendor base organizes around three strategic archetypes: industrial automation incumbents leveraging robotics heritage, software specialists delivering aerospace-grade modeling engines, and cloud hyperscalers providing elastic compute infrastructure. Consolidation pressures intensify as platform vendors acquire niche physics engine developers and system integrators expand vertical service capabilities.
Within the industrial automation tier, ABB Group and Siemens occupy positions anchored by factory-floor deployment heritage across Southeast Asian manufacturing corridors. Dassault Systèmes exemplifies the simulation-specialist archetype through its focus on aerospace and defense-grade fidelity requirements. These three entities represent distinct competitive vectors: robotics-integrated deployment, unified platform architecture, and high-precision modeling engines respectively.
| Leading Market Players |
|---|
| ABB Group |
| General Electric Company |
| Siemens |
| Robert Bosch GmbH |
| IBM Corporation |
| GE Vernova |
| Accenture |
| Microsoft Corporation |
| Dassault Systèmes |
| Others |
Value Network & Pricing Analysis
Platform vendors rolled up through private-equity consolidation exercise pricing discipline through subscription bundling, while sovereign-backed Chinese system integrators undercut margin pools in state-owned enterprise procurement. This ownership bifurcation concentrates supply leverage among robotics-heritage incumbents and fragments pricing power for mid-market visualization software.
Pricing Analysis
Outcome-based pricing tied to uptime guarantees and yield improvement anchors premium platform contracts in South Korean semiconductor fabs and Japanese automotive corridors. Three-tier pricing structure across premium AI-integrated platforms, standard middleware subscriptions, and economy visualization licenses stratifies the vendor base. Pricing pressure stems from open-source physics engines eroding royalty-dependent simulation cores. Mid-market discrete manufacturers in Vietnam and Thailand exhibit acute price sensitivity, while energy sector buyers prioritize latency performance over cost.
Supply Chain Analysis
Freight costs for edge computing hardware shipments from Singapore and Tokyo data centers inflate deployment budgets for Australian offshore platforms and Indonesian palm oil processors. Component supply concentrates in China for industrial IoT sensors, Japan for precision robotics controllers, and South Korea for semiconductor-grade computing modules. Raw material dependencies span gallium nitride chips, rare-earth magnets, and fiber-optic cabling. Single-source vulnerability sits with hyperscaler cloud concentration in Singapore and Tokyo facilities. Distribution runs through system integrator partnerships rather than direct vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressures from MIIT certification mandates and METI subsidy qualification requirements are forcing sub-scale physics engine developers and regional system integrators toward acquisition or exit.
For Market Incumbents: Deploy AI-physics convergence capabilities to defend platform stickiness against neural network surrogate challengers. Acquire niche edge orchestration specialists to secure energy sector deployments where latency requirements prevent cloud migration. Fortify certification pipelines for GB standards compliance to lock out unqualified competitors in Chinese state-owned enterprise procurement. For New Entrants and Emerging Players: Capture Vietnamese electronics contract manufacturing through turnkey cloud-edge hybrid offerings that bypass capital expenditure barriers. Target Thai automotive component clusters with subscription analytics bundled to hardware maintenance contracts. Lead with rapid deployment guarantees measured in weeks rather than quarters to displace incumbent implementation timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor physics engine specialists with aerospace-grade fidelity and depleted cash reserves in Japanese industrial corridors. Long-term viability hinges on AI-augmented simulation differentiation rather than commoditized visualization. Watch for METI subsidy exhaustion as an inflection signal for keiretsu procurement specification tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies modeling, ingestion, and analytics to meet MIIT interoperability mandates for Chinese steel mills. |
| Acquisition of Specialist Firm | Captures physics engine IP to narrow simulation-to-reality gaps in Australian mining fatigue prediction. |
| Geographic Expansion | Establishes edge node presence in Hanoi industrial zones for Vietnamese electronics assembly first-mover positioning. |
| Strategic Partnership | Links robotics OEMs with hyperscalers to resolve sovereign data localization for Indonesian energy operators. |
| Product Launch | Introduces lithography-specific predictive maintenance applications for Seoul Capital Area semiconductor fabs. |
Research Methodology
Document review covered MIIT regulatory filings, METI subsidy program documentation, and KOSHA safety standard amendments, complemented by interviews with plant engineers at Japanese automotive OEMs, platform architects at Southeast Asian system integrators, and procurement leads at South Korean memory fabs. Secondary validation drew from customs records of industrial IoT sensor imports, hyperscaler capex disclosures for Asia-Pacific data center construction, and patent filings for physics-informed neural network architectures. Bottom-up deployment estimates triangulated against top-down market sizing across software, platform, service, and application revenue pools.
Segment-level outputs reflect modeling across product type, end user industry, technology layer, and deployment mode dimensions throughout the forecast period. CAGRs derived from regression analysis of historical adoption curves adjusted for regulatory mandate acceleration and AI-physics convergence technology maturation. Industry-specific inputs incorporated MIIT dual carbon compliance deadlines, METI Society 5.0 subsidy allocation trajectories, and semiconductor fab capital expenditure cycles for lithography equipment refresh.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to hyperscaler data center expansion delays, GB standards enforcement variability, and mechatronics-AI skill gap persistence. Forecasts reflect assumptions about regulatory continuity and technology cost curves that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Supply Chain Digital Twin Market
Digital Solutions
Product Life Cycle Management (PLM) Market
Digital Solutions
ICT Investment in Government Market
Digital Solutions
Mobile Tracking Solution Market
Digital Solutions
Service Mesh Market
Digital Solutions
Passenger Ticket Vending Machine Market
Digital Solutions
Ticketing Solution Market
Digital Solutions
Synthetic Monitoring Market
Digital Solutions
Agent-Oriented Enterprise Architecture Market
Digital Solutions
Global Unified Endpoint Management Market
Digital Solutions
Defense IT Spending Market
Digital Solutions
Product Design and Development Services Market
Digital Solutions
Cannabis POS System Market
Digital Solutions
Big Data and Data Engineering Services Market
Digital Solutions
Business Process Management As a Service Market
Digital Solutions
Global Smart Offices Market