
 Global Drone Sensor Market | 2026-2036
Global Drone Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Drone Sensor Market Analysis
Skilled photonics engineering talent is collapsing across North American and European defense subcontractors, forcing sensor manufacturers to relocate R&D closer to Asian optical foundries. DJI leverages captive inertial measurement unit production to dominate consumer and commercial tier pricing. FLIR Systems sustains thermal core differentiation through proprietary vanadium oxide microbolometer architectures. Teledyne FLIR anchors military-grade cooled infrared lines with ITAR-compliant supply chains.
Drone sensors are electromechanical transducers that convert physical stimuli—electromagnetic radiation, acoustic pressure, or inertial forces—into processable digital signals, typically operating across wavelength bands from ultraviolet through long-wave infrared and sampling frequencies exceeding 100 Hz for real-time flight control. Their primary purpose is to enable autonomous navigation, environmental perception, and mission-specific data acquisition for unmanned aerial platforms. LiDAR segments command premium pricing in infrastructure and mining mapping applications where centimetric elevation accuracy determines project viability. Thermal imagery competes aggressively in emergency services and surveillance, though margin pools concentrate in cooled detector arrays for defense end users. GPS technology underpins virtually all navigation stacks, while radar is displacing optical systems in low-visibility delivery corridors.
The FAA's Remote ID mandate and the EU's CE marking under MDR and F-Gas Regulation shape hardware compliance costs and airspace access rules for manufacturers selling across transatlantic markets. China's NMPA and MIIT enforce GB standards for radio frequency emissions and flight safety protocols that determine market entry for foreign sensor suppliers. India's DGFT and PLI scheme for drone components are redirecting procurement toward domestic assembly operations. Stakeholders must monitor evolving beyond-visual-line-of-sight waiver frameworks and sensor fusion certification requirements as regulators reconcile autonomous density with airspace safety.
Market Dynamics
Photonics engineering scarcity across North American and European defense subcontractors is forcing sensor manufacturers to relocate R&D closer to Asian optical foundries, compressing development cycles and redrawing competitive boundaries.
Growth Catalysts
- Brazilian precision agriculture:Fleet operators are expanding sensor payloads for crop health monitoring, pulling multispectral and thermal units into commercial service at accelerating rates.
- EU AI Act compliance pathways:Airworthiness certification frameworks for autonomous flight systems are creating structured demand for sensor fusion architectures that meet verified safety thresholds.
- Guangdong component clustering:Shenzhen's hardware supply base concentrates MEMS fabrication and optical assembly capacity, driving procurement efficiency for global tier suppliers.
Market Restraints
- ITAR-controlled cooled infrared supply:Defense-grade thermal cores face restricted cross-border transfer, fragmenting procurement options for non-US allied militaries.
- Vanadium oxide microbolometer feedstock volatility:Thermal sensor manufacturers face input cost instability tied to specialty material sourcing constraints.
- F-Gas Regulation refrigerant restrictions:EU rules on cooling system fluids complicate cooled detector array maintenance and lifecycle service economics.
Strategic Opportunities
- India's PLI scheme for drone components:Domestic assembly incentives are redirecting procurement toward local manufacturing operations, opening supplier entry points.
- Radar-optical sensor convergence:Low-visibility delivery corridors are driving fused perception stacks that combine millimeter-wave detection with electro-optical confirmation.
- Beyond-visual-line-of-sight waivers:FAA framework evolution is creating regulatory white space for autonomous density in controlled airspace corridors.
Industry Challenges
- Photonics engineering talent scarcity:North American and European defense subcontractors face collapsing skilled labor pools, forcing geographic R&D relocation.
- CE marking under MDR and F-Gas Regulation:Hardware compliance costs and airspace access rules create extended certification timelines for transatlantic market entry.
- Sensor fusion certification complexity:Regulators are still reconciling autonomous density requirements with validated safety protocols, delaying product approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Drone Sensor Market |
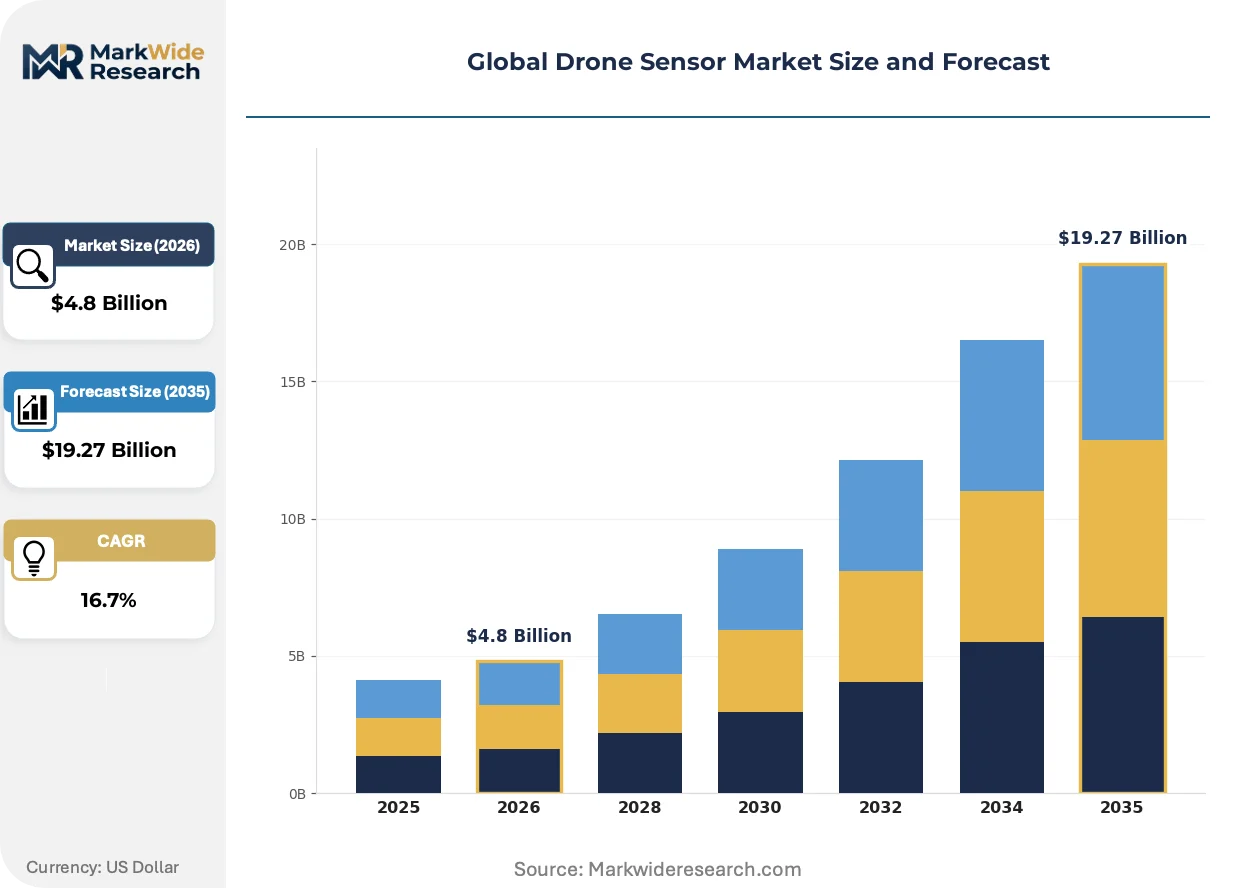
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
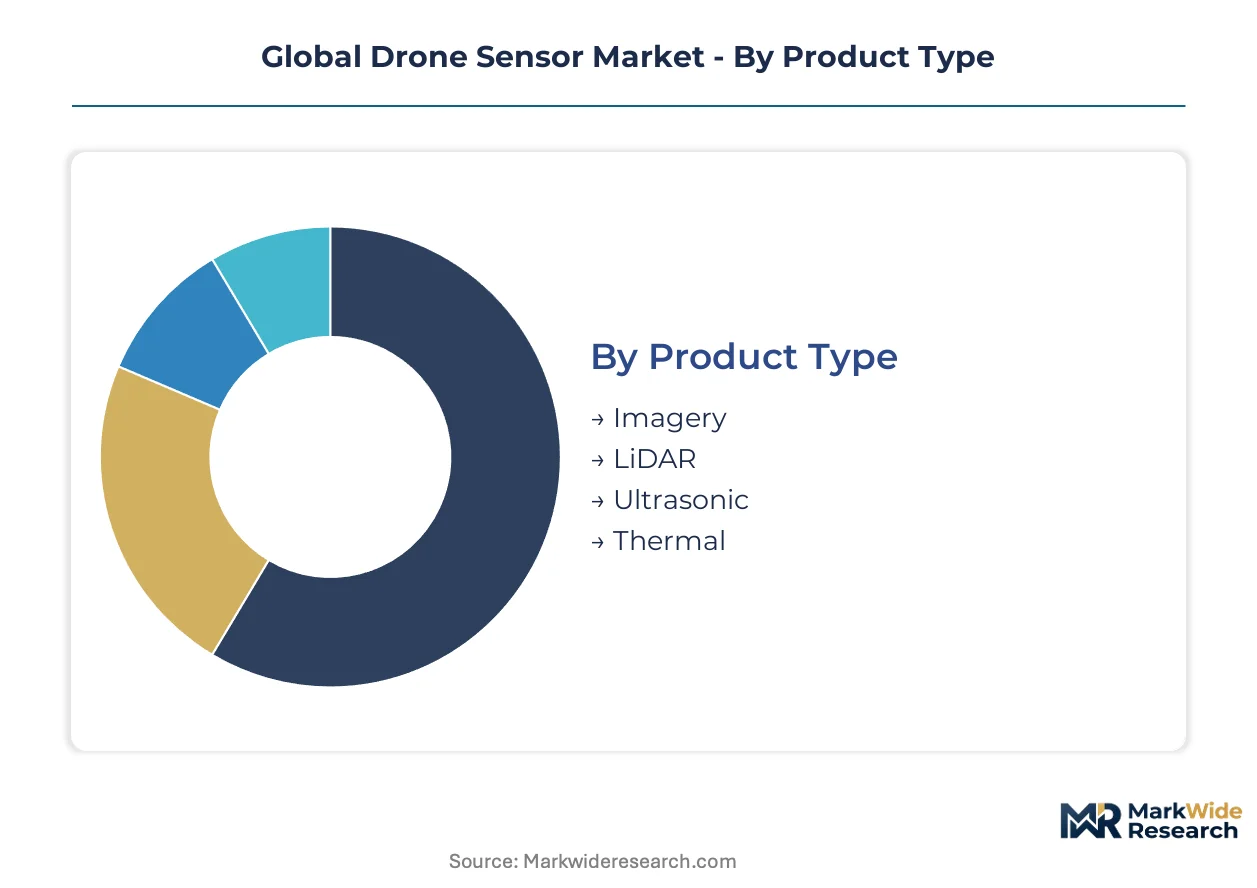
| Segmentation | Product Type: Imagery, LiDAR, Ultrasonic, Thermal End User: Agriculture, Mining, Emergency Services, Infrastructure Technology: GPS, Optical, Radar, RFID Application: Surveillance, Mapping, Inspection, Delivery |
| Companies Covered | XAG, Jouav, DJI, FLIR Systems, Parrot, Skydio, EHang, Teledyne FLIR, Yuneec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Drone Sensor Market Emerging Trajectories
Solid-state LiDAR architectures are compressing unit economics while thermal imaging cores penetrate emergency services workflows. Regulatory mandates across multiple jurisdictions are hardening compliance requirements faster than certification infrastructure can adapt.
Solid-state beam-steering LiDAR eliminates mechanical scanning assemblies through optical phased arrays and MEMS mirrors. Mining and infrastructure mapping operators are adopting these units for centimetric elevation accuracy at reduced maintenance burden. The technology is miniaturizing payload footprints, enabling integration onto sub-2kg commercial drones previously restricted to photogrammetry.
EU AI Act risk-classification frameworks now mandate verified safety thresholds for autonomous decision systems in aviation applications. Hardware manufacturers must demonstrate sensor fusion reliability through standardized test protocols before CE marking approval. Commercial tier suppliers targeting European markets are restructuring development roadmaps to accommodate third-party conformity assessment timelines.
Chinese NMPA and MIIT enforcement of GB standards for radio frequency emissions is filtering foreign sensor suppliers through localized type-approval requirements. Procurement departments at domestic drone assemblers are prioritizing in-market certification holders over established international brands. This preference shift is most visible in Guangdong manufacturing corridors where component sourcing decisions increasingly favor pre-cleared domestic alternatives.
Global Drone Sensor Market Segmentation
Drone sensor procurement channels diverge sharply by payload complexity and certification grade. Defense integrators source through ITAR-compliant supply chains, while commercial fleet operators purchase via Shenzhen-based component distributors or domestic assembly partners.
Product Type:
Channel mix varies by unit economics and replacement frequency. Thermal and LiDAR sensors flow through specialized photonics distributors with calibration service capabilities. Imagery and ultrasonic units move through high-volume electronics channels with minimal technical support.
- Thermal:Vanadium oxide microbolometer cores detect infrared radiation across 8-14 micron wavelengths, converting heat signatures into digital thermal maps. Mining operators in Australia and emergency services in Germany are pulling cooled detector arrays for personnel search and equipment monitoring, constrained by EU F-Gas Regulation refrigerant compliance costs.
- LiDAR:Solid-state beam-steering architectures eliminate mechanical scanning assemblies through optical phased arrays. Infrastructure mapping contractors in Brazil and open-pit mining operators in Canada are adopting these units for centimetric elevation accuracy, though payload weight limits integration on sub-2kg commercial platforms.
- Imagery:CMOS and CCD sensor arrays capture visible-spectrum data for photogrammetry and real-time video feeds.
- Ultrasonic:Piezoelectric transducers emit high-frequency acoustic pulses for close-range obstacle detection and altitude holding.
By volume, Imagery leads. By growth pace, Thermal is climbing the fastest.
End User:
Cost tier stratification separates defense-grade certification from commercial procurement. Agriculture and mining represent high-volume, price-sensitive demand. Emergency services and infrastructure command premium pricing for reliability guarantees.
- Agriculture:Multispectral and normalized difference vegetation index sensors enable variable-rate input application. Brazilian soybean operators in Mato Grosso and corn growers in Iowa are expanding fleet sensor payloads for crop health monitoring, pulling thermal and imagery units into commercial service.
- Mining:LiDAR and thermal cores support volumetric surveying and equipment thermal monitoring. Open-pit operators in Western Australia and Chilean copper districts are standardizing sensor fusion stacks for autonomous haul truck coordination.
- Emergency Services:Cooled infrared arrays and optical zoom modules support search-and-rescue and firefighting operations.
- Infrastructure:High-resolution imagery and LiDAR enable bridge inspection and transmission line monitoring.
Agriculture generates the highest unit volumes. Mining posts the steepest expansion trajectory as autonomous fleet deployment accelerates.
Technology:
Application context determines technology selection. GPS underpins virtually all navigation stacks. Optical and radar compete for environmental perception, with radar gaining share in low-visibility delivery corridors.
- Radar:Millimeter-wave and frequency-modulated continuous-wave systems penetrate fog, dust, and precipitation where optical sensors fail. Logistics operators in the Netherlands and pharmaceutical delivery services in Switzerland are deploying radar-optical fusion stacks for beyond-visual-line-of-sight corridor operations.
- Optical:Electro-optical and infrared cameras provide visual confirmation and target identification. Surveillance contractors in the United Kingdom and agricultural scouts in France rely on gimbal-stabilized optical payloads for detailed imagery acquisition.
- GPS:Multi-constellation receivers combine signals from GPS, GLONASS, Galileo, and BeiDou for positioning accuracy.
- RFID:Radio-frequency identification readers support inventory tracking and asset location in warehouse and yard management.
GPS maintains universal penetration. Radar is gaining share fastest as low-visibility delivery routes proliferate.
Application:
Customer type and mission criticality shape procurement patterns. Surveillance and mapping demand high-resolution, export-controlled components. Inspection and delivery prioritize cost efficiency and rapid replacement.
- Mapping:LiDAR and photogrammetry sensors generate topographic and volumetric data products. Surveying firms in Canada and geospatial service providers in South Africa are consolidating around solid-state LiDAR for centimetric accuracy at reduced maintenance burden.
- Surveillance:Thermal and optical gimbal systems provide persistent area monitoring and target tracking. Border security agencies in Poland and private security operators in the United Arab Emirates are sourcing cooled infrared lines through ITAR-compliant channels.
- Inspection:Ultrasonic and high-zoom optical sensors assess structural integrity of bridges, turbines, and pipelines.
- Delivery:Radar and ultrasonic arrays enable obstacle avoidance in urban and suburban distribution networks.
Mapping leads by revenue concentration. Delivery is expanding most quickly as regulatory frameworks for autonomous density mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian soybean operators deploy multispectral payloads for crop health monitoring, while German emergency services source cooled infrared arrays through ITAR-compliant channels. This consumption-mix differential separates agricultural volume demand from defense-grade thermal procurement.
United States
FAA Remote ID mandates and beyond-visual-line-of-sight waiver frameworks shape hardware compliance costs for commercial fleet operators. Logistics providers in the Netherlands and pharmaceutical delivery services in Switzerland deploy radar-optical fusion stacks for corridor operations. The FAA's evolving autonomous density rules create regulatory white space in controlled airspace corridors around Phoenix and Dallas-Fort Worth.
Germany
Emergency services in North Rhine-Westphalia and Bavaria pull cooled detector arrays for personnel search and firefighting operations. EU F-Gas Regulation refrigerant restrictions complicate maintenance economics for thermal sensor fleets. The Stuttgart manufacturing corridor concentrates automotive-tier sensor assembly operations serving European drone integrators.
China
NMPA and MIIT enforcement of GB standards for radio frequency emissions filters foreign suppliers through localized type-approval requirements. Guangdong manufacturing corridors cluster MEMS fabrication and optical assembly capacity around Shenzhen's hardware supply base. Domestic assemblers prioritize pre-cleared local alternatives over established international brands.
Brazil
Soybean operators in Mato Grosso and corn growers in Iowa expand fleet sensor payloads for normalized difference vegetation index monitoring. ANVISA and DECEA regulations govern commercial drone operations over agricultural zones. Precision agriculture fleets in the Cerrado biome drive accelerating adoption of multispectral and thermal units.
India
DGFT and PLI scheme incentives redirect procurement toward domestic drone component assembly operations. Karnataka and Telangana states host emerging sensor integration facilities serving agricultural and surveillance applications. The Delhi-NCR corridor concentrates defense procurement offices specifying ITAR-aligned thermal cores for border monitoring.
Global Drone Sensor Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive inertial measurement unit production and proprietary microbolometer architectures defining competitive moats. Defense-grade suppliers anchor ITAR-compliant supply chains for cooled infrared lines, while commercial-tier vendors compete through Shenzhen-sourced component economics. Three archetypes dominate: vertically integrated platform builders, thermal core specialists, and distributed optics fabricators. Consolidation pressure intensifies through strategic partnerships and geographic expansion into India's PLI-subsidized assembly zones.
Within the integrated platform tier, DJI and EHang occupy positions shaped by captive supply chain control and regulatory pre-certification in Asian markets. FLIR Systems exemplifies thermal core specialization, sitting within the vanadium oxide microbolometer segment that mining and emergency services operators specify for reliability-critical deployments. XAG represents the agricultural application anchor, with its positioning tied to precision farming fleet expansion in Brazil and China.
| Leading Market Players |
|---|
| XAG |
| Jouav |
| DJI |
| FLIR Systems |
| Parrot |
| Skydio |
| EHang |
| Teledyne FLIR |
| Yuneec |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between Brazilian agribusiness operators and Shenzhen-based component distributors lock in multispectral sensor supply while capping unit cost exposure against vanadium oxide microbolometer feedstock volatility. These contracts bundle hardware procurement with calibration service subscriptions, creating price visibility across the three-tier certification grade structure that separates ITAR-compliant defense lines from commercial-tier alternatives.
Pricing Analysis
Project-based pricing dominates infrastructure mapping contracts where solid-state LiDAR units command premiums tied to centimetric elevation accuracy guarantees. Certification grade and volume scale drive differentiation: defense integrators absorb ITAR-compliant thermal core costs while agricultural fleet operators in Mato Grosso squeeze margins on multispectral payloads. Cost compression in commercial-tier imagery sensors is intensifying because Guangdong MEMS foundries are expanding optical assembly capacity. Emergency services in Germany exhibit lowest price sensitivity due to mission-critical reliability requirements; Brazilian soybean cooperatives show highest sensitivity, driving procurement toward Shenzhen-sourced alternatives.
Supply Chain Analysis
Strait of Malacca transit underwrites critical rare earth element flows for vanadium oxide microbolometer production, creating chokepoint exposure for thermal sensor manufacturers. Component fabrication concentrates in China, South Korea, and Taiwan; optical foundries in these markets supply MEMS mirrors and optical phased arrays for solid-state LiDAR architectures. Raw material dependencies include indium antimonide for cooled infrared detectors, gallium arsenide for RF components, and specialized glass substrates for optical assemblies. Single-source vulnerability in ITAR-controlled cooled infrared supply fragments procurement options for non-US allied militaries. Distribution runs through Shenzhen hardware supply bases for commercial tiers and ITAR-compliant channels for defense integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
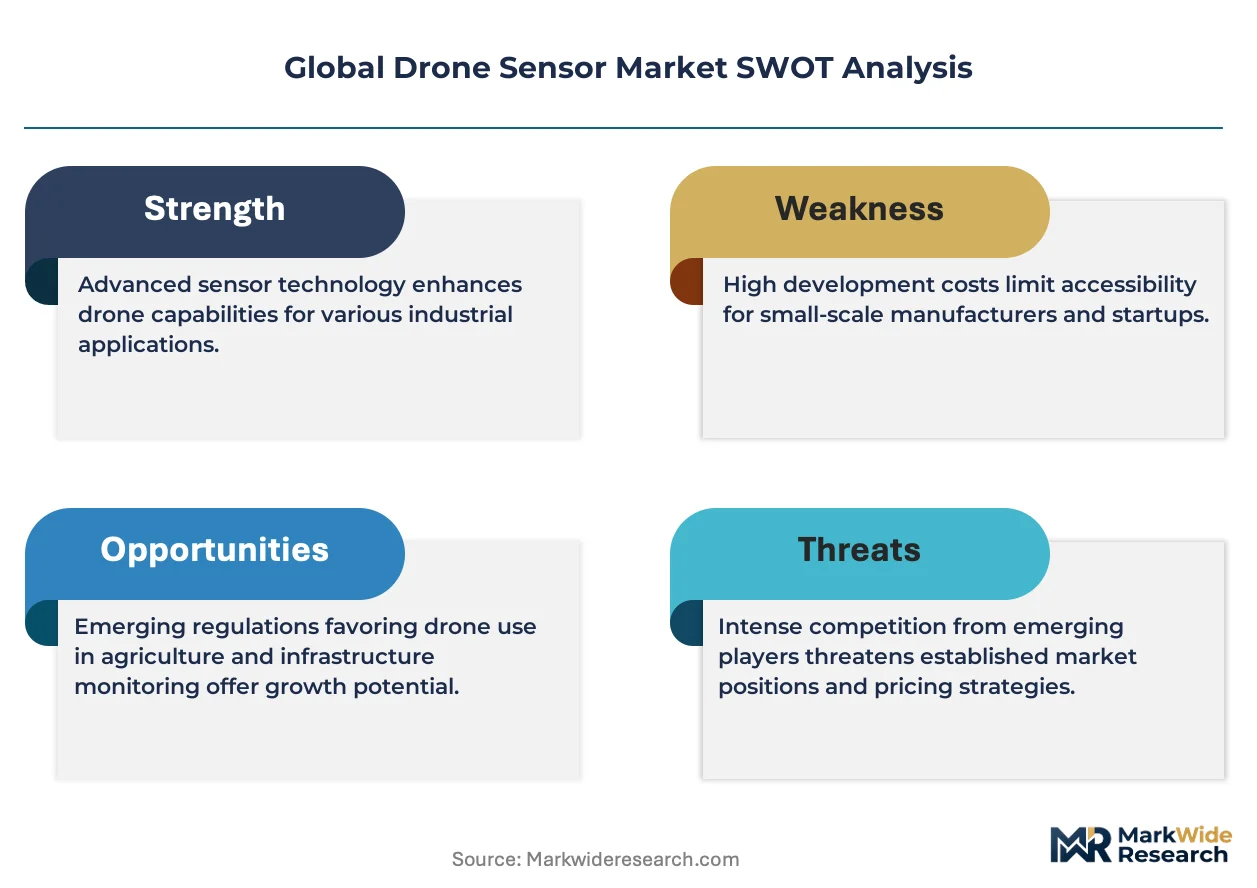
Photonics engineering talent scarcity across North American defense subcontractors is redrawing competitive boundaries, forcing R&D relocation toward Asian optical foundries and compressing development cycles for late entrants.
For Market Incumbents: Compound captive inertial measurement unit production advantages by deepening backward integration into MEMS fabrication capacity in Guangdong manufacturing corridors. Anchor ITAR-compliant supply chain relationships against emerging domestic assembly competitors in India's PLI-subsidized zones. Certification investment in EU AI Act conformity assessment protocols creates defensive moats as regulatory timelines extend for challengers. For New Entrants and Emerging Players: Anchor in India's Karnataka and Telangana sensor integration facilities to capture PLI scheme procurement redirection toward domestic assembly operations. Precision agriculture in Brazil's Cerrado biome offers the most penetrable volume segment, with multispectral payload demand accelerating faster than established supplier capacity expansion. Go-to-market through ANVISA-preferred domestic distributors bypasses international brand recognition gaps. For Investors and Strategic Acquirers: Capital is best deployed toward thermal core specialists with proprietary vanadium oxide microbolometer architectures and established emergency services channel relationships. Long-term viability hinges on defense-grade certification maintenance and radar-optical fusion stack development capability. Watch FAA beyond-visual-line-of-sight waiver density approvals as the inflection indicator for autonomous delivery corridor sensor demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Fabrication | Captive optical foundry capacity in Shenzhen compresses LiDAR unit economics for infrastructure mapping contracts. |
| EU AI Act Conformity Assessment Investment | Third-party verified safety thresholds accelerate CE marking timelines for sensor fusion architectures in German emergency services. |
| India PLI Scheme Domestic Assembly Partnership | Karnataka integration facilities redirect procurement from international brands toward pre-cleared local alternatives. |
| ITAR-Compliant Cooled Infrared Supply Chain Expansion | Restricted cross-border thermal core transfer creates procurement fragmentation that favors established defense-tier suppliers. |
| Radar-Optical Fusion Stack Development | Millimeter-wave and electro-optical convergence addresses low-visibility delivery corridor requirements in Netherlands logistics networks. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with photonics engineering directors, drone fleet procurement managers, defense subcontractor supply chain leads, and optical foundry operations heads; and secondary validation through FAA Remote ID regulatory filings, EU AI Act implementation guidance, NMPA GB standard type-approval records, and Indian DGFT PLI scheme beneficiary disclosures. Bottom-up sensor shipment estimates by application and certification tier were triangulated against top-down market value reconstruction from component bill-of-materials analysis.
Across the projection horizon, the analytical framework modeled demand by product type, end user vertical, technology architecture, and application mission criticality, with additional segmentation by regulatory compliance tier. CAGRs were derived from installed base expansion rates and replacement cycle compression in precision agriculture fleets. Industry-specific forecast inputs included Brazilian soybean acreage under multispectral monitoring and German emergency services thermal array procurement pipelines.
Material uncertainties — NMPA enforcement intensity against foreign suppliers, F-Gas Regulation refrigerant restriction scope expansion, and FAA autonomous density waiver approval velocity — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as regulatory reconciliation between autonomous flight density and airspace safety protocols evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
FPV Drone Goggles Market
UAV
North America Tactical UAV Market
UAV
GCC Drone Pilot Training Market
UAV
Global Drone Autopilots Market
UAV
Unmanned Aerial Vehicle Fuel Cell Market
UAV
Global Aerial Imaging Market
UAV
Home Security Drone Market
UAV
North America Small UAV Market
UAV
Nano Drones Market
UAV
Autonomous Underwater Gliders (AUG) Market
UAV
UAV GNSS Antenna Market
UAV
Drone Camera Market
UAV
Asia Pacific Small UAV Market
UAV
Europe Drone Light Shows Market
UAV
North America Drone Software Market
UAV
North America Drones Market